
 Brazil Automotive Composites Market | 2026-2036
Brazil Automotive Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive Composites Market Outlook
The gap between Tier-1 suppliers and vehicle assemblers is collapsing as OEMs consolidate direct composite procurement. Teijin Carbon Brazil leverages its local carbon fiber precursor capacity to anchor supply security for domestic automakers. Cogumelo Compósitos specializes in natural fiber hybrid formulations that navigate Brazil's bio-based material preferences. Stratus Compósitos dominates compression-molded structural parts for commercial vehicle platforms in the Southeast region.
Automotive composites in Brazil encompass engineered material systems combining reinforcement fibers with thermoset or thermoplastic matrices, typically achieving specific strength ratios exceeding 200 MPa/(g/cm³) through resin transfer molding or vacuum infusion processes. These materials primarily serve mass reduction mandates where every kilogram eliminated improves fuel efficiency in flex-fuel and ethanol-powered vehicle fleets. Glass fiber formulations occupy the volume leadership position across interior components and non-structural exterior panels, while carbon fiber segments capture concentrated margin pools in structural parts and electrical housing applications for premium vehicle lines. Natural fiber composites represent the fastest-growing product category as Rota 2030 local content incentives and sustainability procurement criteria reshape supplier selection at OEM level.
ANVISA governs chemical substance exposure limits in automotive interior applications, compelling reformulation of resin systems to meet migrated compound thresholds. INMETRO certification requirements for vehicle safety and energy efficiency create downstream pressure for composite material traceability and performance documentation. The Central Bank of Brazil's exchange rate volatility management indirectly conditions import dependency for epoxy resin and carbon fiber precursors. Stakeholders must monitor how Rota 2030 renewal negotiations restructure local content thresholds versus technology transfer requirements for foreign composite suppliers.
Market Dynamics
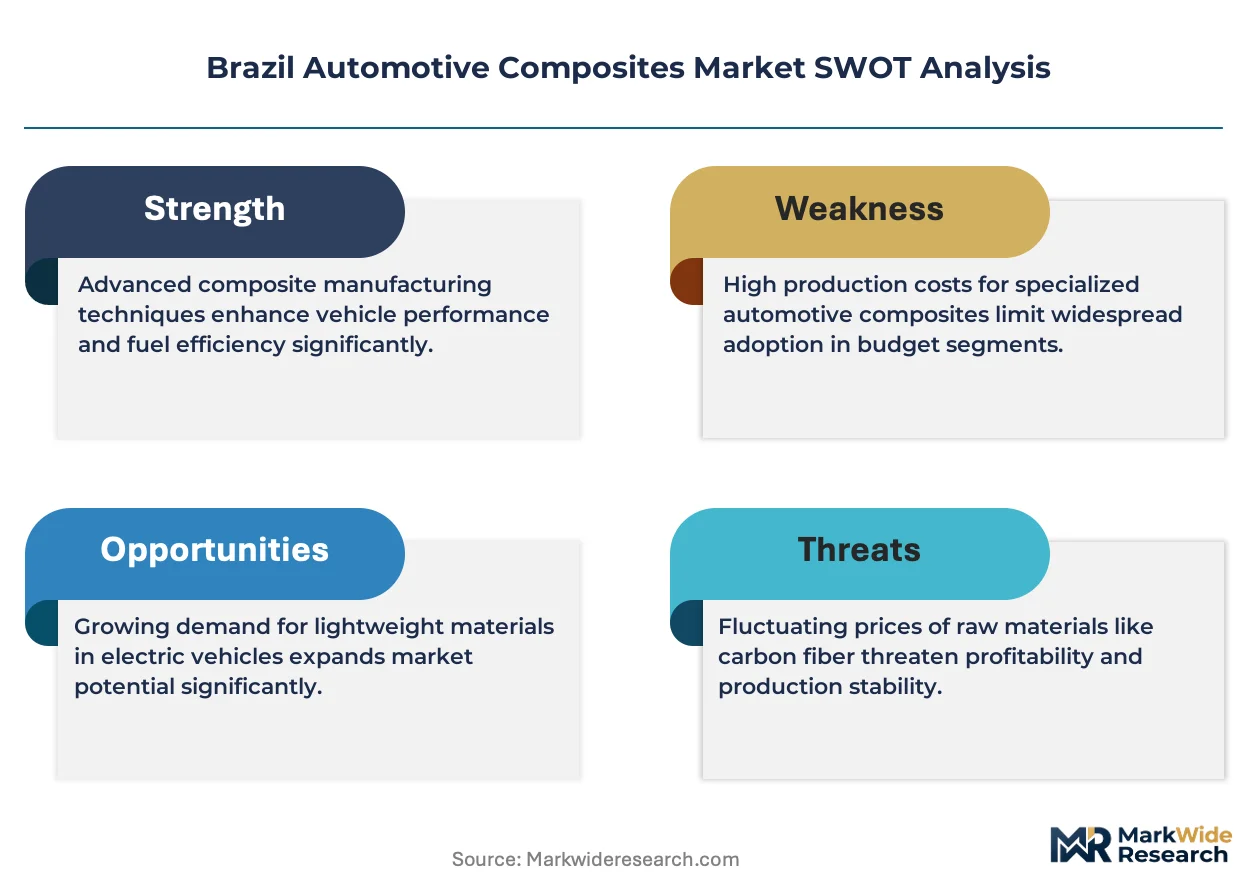
OEM consolidation of direct composite procurement is collapsing traditional Tier-1 supplier margins across Brazil's Southeast industrial corridor. This structural compression is redistributing value toward carbon fiber precursor capacity and bio-based formulation capabilities.
Growth Catalysts
- Rota 2030 local content thresholds:Brazil's automotive incentive framework mandates escalating domestic value-add, forcing foreign suppliers to establish precursor production or joint ventures with Brazilian compounders.
- Flex-fuel light-truck fleet expansion:Vehicle assemblers in Minas Gerais prioritize mass reduction technologies to offset ethanol fuel economy penalties in heavy-duty applications.
- ANVISA-aligned resin reformulation:Chemical exposure limits for interior applications accelerate adoption of low-emission thermoplastic matrices over conventional epoxy systems.
Market Restraints
- Epoxy resin import dependency:Central Bank exchange rate volatility inflates landed costs for specialty thermoset precursors, compressing gross margins for compression-molding specialists.
- Carbon fiber precursor concentration:Asian suppliers control acrylonitrile supply chains, exposing Brazilian converters to shipping delays and tariff uncertainty.
- Natural fiber supply seasonality:Sisal and jute harvest cycles in Northeast Brazil create input volume mismatches with just-in-time automotive assembly schedules.
Strategic Opportunities
- Paraná industrial corridor underpenetration:Vehicle assembly plants in the South region lack localized composite component suppliers, creating first-mover advantage for greenfield thermoplastic stamping operations.
- Electrical housing applications:Battery enclosure demand from emerging hybrid flex-fuel platforms opens margin pools beyond traditional structural body-in-white replacement.
- INMETRO certification pre-approval:Early traceability documentation investments position suppliers for accelerated qualification when Rota 2030 renewals tighten performance verification requirements.
Industry Challenges
- Resin transfer molding technician scarcity:Brazilian vocational programs emphasize metal stamping over composite processing, forcing manufacturers to import Portuguese-speaking specialists from Portugal.
- Multi-material joining certification:OEM weld-bond specifications for steel-composite hybrid structures require expensive adhesion testing protocols not covered by existing INMETRO automotive safety frameworks.
- Legacy ERP integration:Domestic compounders operate on disconnected inventory systems that cannot exchange real-time fiber orientation data with OEM digital twin platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive Composites Market |
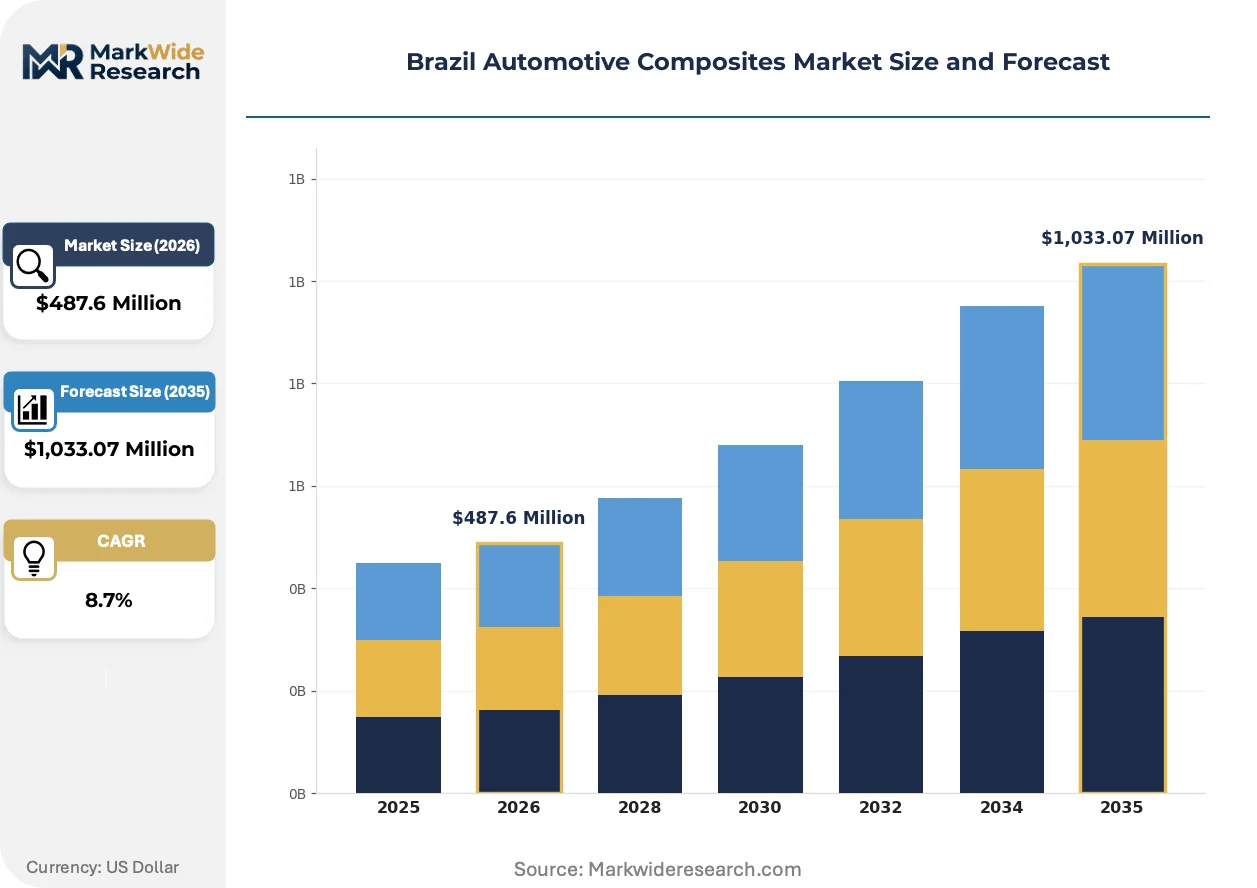
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Fiber, Carbon Fiber, Natural Fiber, Hybrid Composites Application: Interior Components, Exterior Panels, Structural Parts, Electrical Housing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Injection Molding, Compression Molding, Resin Transfer Molding, Vacuum Infusion |
| Companies Covered | Teijin Limited, BASF, Hexcel Corporation, Cogumelo Compósitos, Stratus Compósitos, Toray Industries, Inc., Owens Corning, Teijin Carbon Brazil, Solvay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive Composites Market Strategic Shifts
Material science advances and procurement restructuring are fragmenting established supply hierarchies across Brazilian automotive manufacturing. Three distinct vectors are compressing traditional value chain positions.
Hybrid natural-synthetic fiber composites are bifurcating the interior panel segment between cost-driven glass-reinforced formulations and sustainability-weighted bio-hybrid alternatives. São Paulo-based OEM engineering teams specify Cogumelo Compósitos' jute-glass hybrids for door trim applications where flexural modulus requirements sit below 15 GPa. This material divergence is compressing pure-glass commodity suppliers into price-driven aftermarket channels while elevating bio-compounders to platform co-development roles.
Rota 2030 renewal negotiations are tightening local content verification mechanisms beyond simple bill-of-materials accounting. INMETRO now requires polymer precursor traceability to Brazilian petrochemical feedstock or certified bio-origin documentation. Southeast region assemblers respond by qualifying domestic pre-preg suppliers who can certify carbon fiber tow conversion within Mercosur territory, displacing Asian direct-ship arrangements.
Direct OEM procurement of structural preforms is eliminating traditional Tier-1 stamping house intermediaries. Vehicle manufacturers in the ABC Paulista industrial belt now contract compression-molded pickup box components from Stratus Compósitos through long-term offtake agreements rather than annual supplier auctions. This channel compression concentrates volume risk with compounders while transferring design iteration costs from assemblers to material suppliers.
Brazil Automotive Composites Market Segmentation
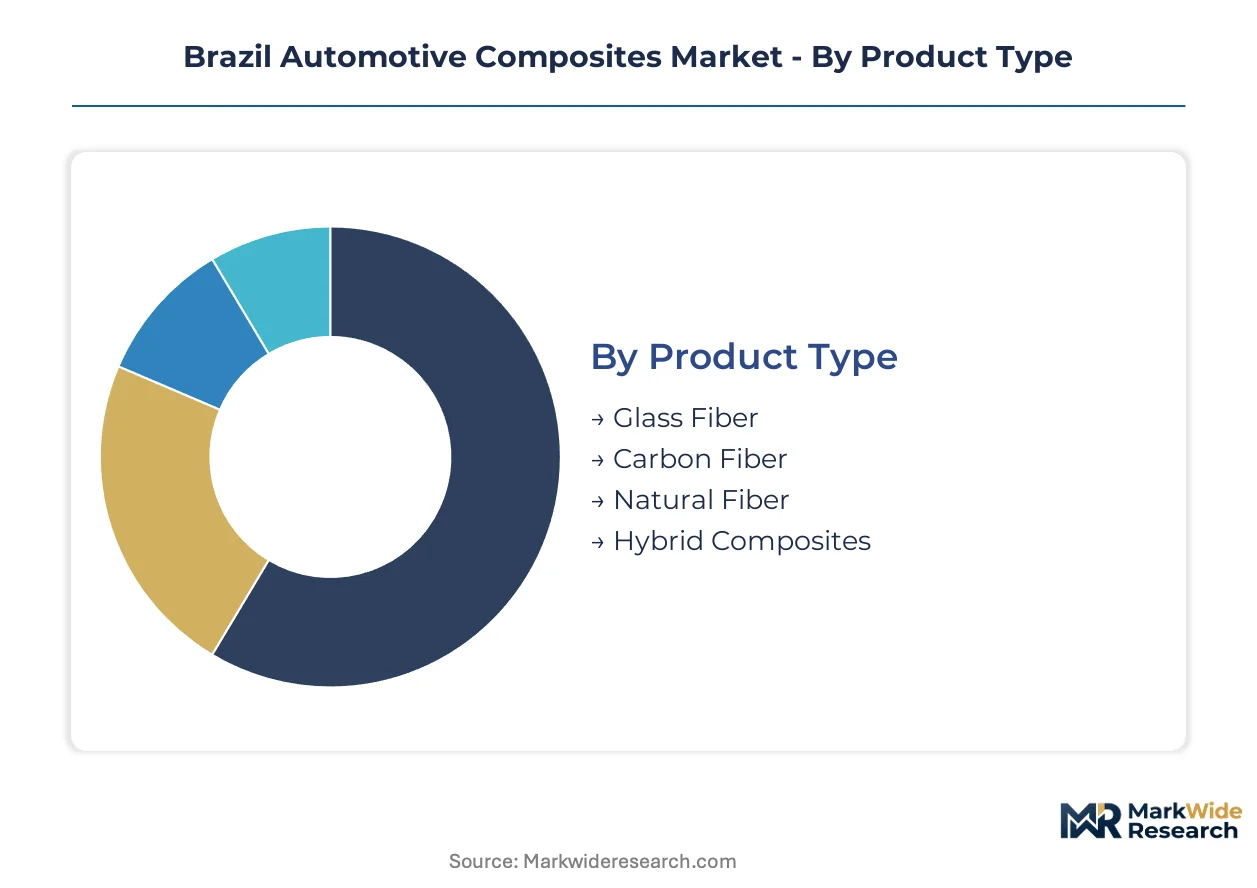
Segmentation in Brazil's automotive composites market reveals how Rota 2030 incentives and ANVISA compliance reshape procurement patterns across material grades and manufacturing tiers. Each dimension exposes distinct margin pools and qualification barriers that suppliers must navigate.
Product Type:
Domestic production concentrates in glass and natural fiber formulations serving flex-fuel platforms, while carbon fiber segments remain import-dependent with concentrated precursor supply chains.
- Glass Fiber:Reinforced thermoset and thermoplastic matrices dominate interior trim and non-structural exterior applications. São Paulo OEMs specify E-glass formulations for door panels and dashboard carriers where flexural modulus requirements sit below 20 GPa. Volume leadership stems from established compounding infrastructure in Minas Gerais industrial corridors.
- Carbon Fiber:PAN-based precursors achieve specific strength ratios exceeding 300 MPa/(g/cm³) in structural body-in-white replacements. Teijin Carbon Brazil's local precursor capacity anchors supply security for premium vehicle platforms, though epoxy resin import dependency inflates landed costs during exchange rate volatility.
- Natural Fiber:Sisal and jute hybrids from Northeast Brazil harvest cycles serve sustainability-weighted procurement criteria.
- Hybrid Composites:Cogumelo Compósitos' jute-glass formulations balance cost and bio-content thresholds for Rota 2030 compliance.
Glass fiber holds the largest share; momentum sits with natural fiber as local content verification tightens.
Application:
Cost tiers separate commodity interior panels from structural parts commanding premium qualification timelines and performance documentation.
- Interior Components:Door trim, seat backs, and headliners specify low-emission thermoplastic matrices to meet ANVISA chemical exposure limits. São Paulo engineering teams prioritize reformulated PP compounds over conventional epoxy systems for cabin air quality compliance.
- Structural Parts:Compression-molded pickup box components and load-bearing chassis elements require INMETRO safety certification with full material traceability. Stratus Compósitos dominates this segment through direct OEM offtake agreements in the ABC Paulista belt.
- Exterior Panels:Class-A surface quality demands limit adoption to non-visible fender and hood applications.
- Electrical Housing:Battery enclosures for emerging hybrid flex-fuel platforms open margin pools beyond traditional mechanical applications.
Interior components command volume leadership; electrical housing climbs fastest on electrification timelines.
End User:
Customer type determines contract structure, with direct OEM procurement collapsing traditional Tier-1 intermediaries across the Southeast region.
- OEMs:Vehicle manufacturers in Paraná and Minas Gerais now contract composite preforms directly, transferring design iteration costs from assemblers to material suppliers. Long-term offtake agreements replace annual supplier auctions.
- Tier-1 Suppliers:Stamping houses face margin compression as procurement consolidation eliminates intermediary positions; survivors pivot to multi-material joining and assembly integration.
- Vehicle Assemblers:Flex-fuel light-truck specialists in Minas Gerais prioritize mass reduction technologies.
- Aftermarket Providers:Price-driven channels absorb displaced pure-glass commodity suppliers.
OEMs hold procurement volume leadership; vehicle assemblers gain fastest on platform co-development roles.
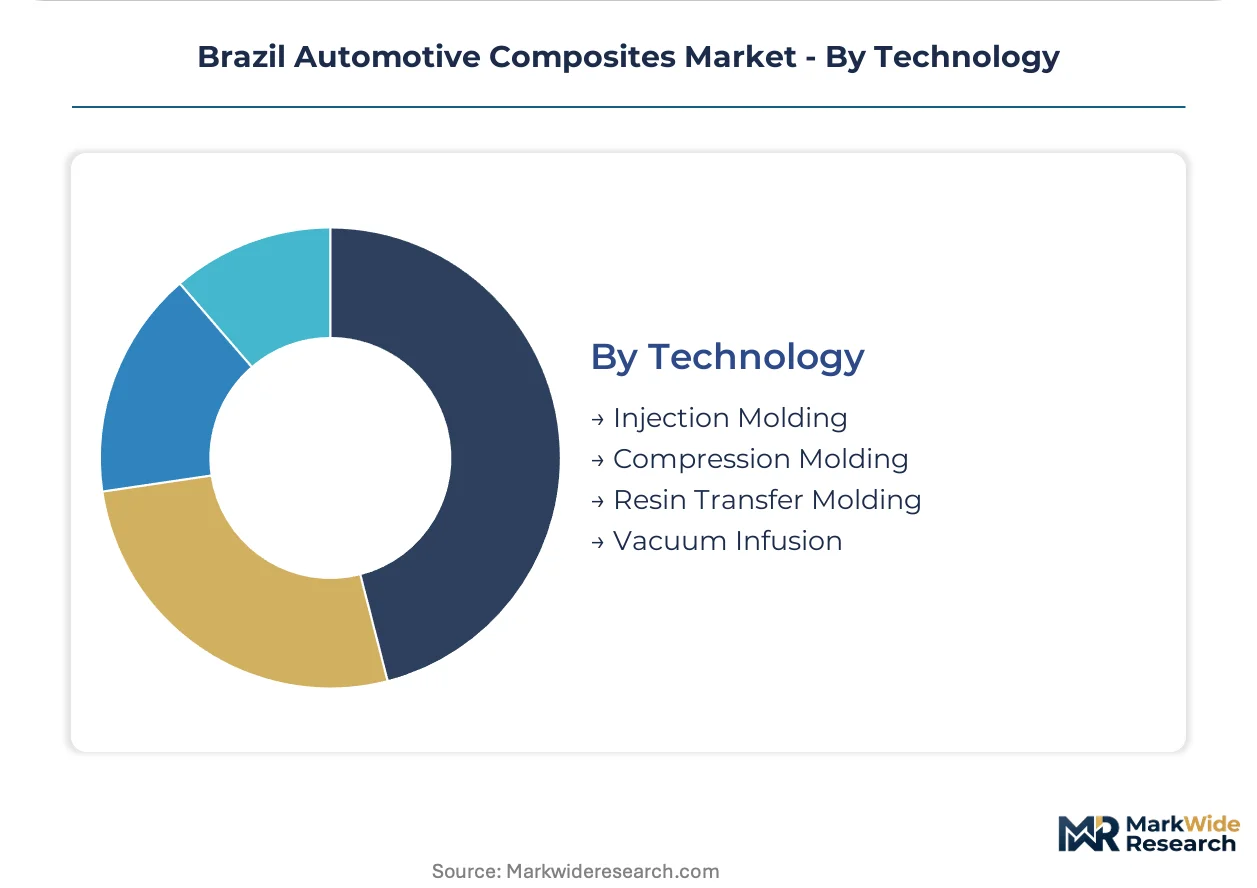
Technology:
Process maturity separates high-volume injection molding from specialized resin transfer molding requiring scarce technician expertise.
- Compression Molding:SMC and BMC formulations serve structural pickup components with cycle times compatible with automotive throughput requirements. Stratus Compósitos anchors Southeast regional capacity for commercial vehicle platforms.
- Resin Transfer Molding:Closed-mold processes achieve fiber volume fractions exceeding 50% in carbon fiber structural parts. Brazilian vocational program gaps force manufacturers to import Portuguese-speaking specialists from Portugal.
- Injection Molding:Thermoplastic compounds dominate interior commodity production.
- Vacuum Infusion:Lower tooling costs suit prototype and low-series exterior panel development.
Compression molding holds installed capacity leadership; resin transfer molding expands most quickly on structural carbon fiber demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber precursor conversion and natural fiber harvesting concentrate supply-side capacity across Brazil's Southeast industrial corridor. ANVISA chemical exposure protocols and Rota 2030 local content mandates reshape procurement patterns in distinct regional manufacturing clusters.
São Paulo
Teijin Carbon Brazil anchors acrylonitrile precursor production for domestic automakers in the ABC Paulista belt. ANVISA-aligned resin reformulation drives low-emission thermoplastic qualification for interior cabin applications. São Paulo-based OEM engineering teams specify jute-glass hybrid door trim from Cogumelo Compósitos for flex-fuel platforms.
Minas Gerais
Vehicle assemblers prioritize mass reduction technologies to offset ethanol fuel economy penalties in heavy-duty light-truck applications. INMETRO safety certification requirements compress qualification timelines for structural composite suppliers. The state's industrial corridor concentrates flex-fleet manufacturing capacity serving Southeast regional demand.
Paraná
Underpenetrated composite component supply creates first-mover opportunity for greenfield thermoplastic stamping operations. Rota 2030 local content thresholds force foreign suppliers to establish precursor production or joint ventures with Brazilian compounders. Vehicle assembly plants in the South region lack localized structural preform suppliers.
Rio Grande do Sul
Natural fiber supply seasonality from Northeast Brazil harvest cycles creates input volume mismatches with just-in-time automotive schedules. The Central Bank of Brazil's exchange rate volatility management indirectly conditions import dependency for epoxy resin precursors. Regional compounders face margin compression from Asian acrylonitrile supply chain concentration.
Brazil Automotive Composites Market Competitive Environment
Concentration sits with multinational chemical conglomerates controlling precursor supply chains and domestic compounders capturing Rota 2030 local content benefits. The market structure divides between import-dependent carbon fiber specialists and bio-based formulation innovators. Three archetypes dominate: Japanese-Korean conglomerates with integrated precursor capacity, European chemical majors with resin system portfolios, and Brazilian hybrid compounders leveraging natural fiber feedstocks. Competitive moves center on backward integration into acrylonitrile production and strategic partnerships with vehicle assemblers for direct procurement contracts.
Among Japanese conglomerates, Teijin Limited and Toray Industries, Inc. exemplify integrated precursor-to-composite supply chain control. European chemical majors including BASF and Solvay occupy positions in thermoplastic matrix formulation. Domestic specialists Cogumelo Compósitos and Stratus Compósitos represent the bio-hybrid and structural compression-molding archetypes respectively, anchoring local content compliance for Southeast region OEMs.
| Leading Market Players |
|---|
| Teijin Limited |
| BASF |
| Hexcel Corporation |
| Cogumelo Compósitos |
| Stratus Compósitos |
| Toray Industries, Inc. |
| Owens Corning |
| Teijin Carbon Brazil |
| Solvay |
| Others |
Value Chain & Pricing Dynamics
ANVISA chemical exposure protocols gate both supplier qualification timelines and price differentiation between thermoset and thermoplastic matrix tiers, compressing margins for epoxy-dependent converters while elevating low-emission compounders to premium contract structures. This regulatory anchor forces procurement teams to weight certification documentation costs against landed resin expenses when sourcing structural preforms for flex-fuel platforms.
Pricing Analysis
ANVISA dictates the pricing tier structure across interior and structural applications, separating reformulated thermoplastic compounds meeting migrated compound thresholds from conventional epoxy systems facing qualification rejection risk. Price differentiation separates INMETRO-certified structural preforms with full traceability documentation from commodity glass-reinforced interior panels. Cost compression in carbon fiber segments intensifies because Asian acrylonitrile supply concentration exposes Brazilian converters to exchange rate volatility. Vehicle assemblers in Minas Gerais demonstrate highest price sensitivity for commodity interior components, while OEM direct procurement of structural parts shows lowest sensitivity due to platform co-development lock-in.
Supply Chain Analysis
Just-in-time assembly schedules in São Paulo and Minas Gerais clash with strategic-stockpile preferences for epoxy resin precursors subject to Central Bank exchange rate volatility. Supply concentrates in Japan, South Korea, and China for PAN-based carbon fiber precursors, while natural fiber feedstocks draw from Northeast Brazil sisal and jute harvest cycles. Raw material dependencies rest on acrylonitrile monomer, specialty epoxy formulations, and seasonal lignocellulosic inputs. Single-source vulnerability in Asian precursor supply chains exposes domestic compounders to shipping delays and tariff uncertainty. Distribution runs through direct OEM offtake agreements that displace traditional Tier-1 stamping house intermediaries across the Southeast industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's automotive composites sector rewards operators who control scarce resin transfer molding technician pools and certified carbon fiber precursor conversion capacity within Mercosur territory. The capability gap between bio-hybrid compounders and import-dependent structural specialists is widening as Rota 2030 verification mechanisms tighten.
For Market Incumbents: Compound backward integration into acrylonitrile precursor production or joint ventures with Brazilian petrochemical feedstock suppliers to defend against Asian supply chain concentration. Prioritize INMETRO certification pre-approval investments before Rota 2030 renewal negotiations tighten performance verification requirements. Lock in long-term offtake agreements with Paraná vehicle assemblers to secure volume before greenfield thermoplastic stamping operations capture first-mover advantage. For New Entrants and Emerging Players: Anchor in the underpenetrated Paraná industrial corridor where vehicle assembly plants lack localized structural preform suppliers. Target electrical housing applications for emerging hybrid flex-fuel battery enclosures, the fastest-climbing margin pool beyond traditional mechanical parts. Qualify as domestic pre-preg suppliers with carbon fiber tow conversion traceability within Mercosur territory to displace Asian direct-ship arrangements. For Investors and Strategic Acquirers: Rota 2030 renewal negotiations reshape the acquisition landscape toward compounders with certified bio-origin documentation and local precursor conversion capability. Five-to-ten year viability favors domestic specialists over import-dependent carbon fiber traders facing persistent exchange rate headwinds. Target acquisition archetypes: Brazilian hybrid compounders with jute-glass formulation IP and established OEM platform co-development relationships. Monitor Central Bank exchange rate management interventions as the signal indicating when epoxy resin import dependency becomes structurally prohibitive for undifferentiated converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captures Rota 2030 local content benefits while reducing Asian acrylonitrile supply chain exposure. |
| INMETRO Certification Pre-Approval Investment | Accelerates supplier qualification timelines when Rota 2030 renewals tighten performance verification requirements. |
| Greenfield Thermoplastic Stamping Operations | Addresses Paraná industrial corridor underpenetration for vehicle assembly plants lacking localized composite suppliers. |
| Natural Fiber Hybrid Formulation Development | Aligns with ANVISA-aligned resin reformulation and bio-based material preferences reshaping OEM procurement criteria. |
| Direct OEM Offtake Agreement Structuring | Eliminates Tier-1 intermediary margin compression while transferring design iteration costs from assemblers to material suppliers. |
Study Parameters
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement leads, composite compounder plant managers, and ANVISA regulatory affairs specialists anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from INMETRO certification databases, Rota 2030 policy documentation, Central Bank exchange rate series, and automotive production registration data. Bottom-up volume builds across material grades and applications triangulated against top-down market sizing from petrochemical feedstock consumption patterns.
Sensitivity analysis tested forecast robustness across exchange rate volatility scenarios and Rota 2030 local content threshold variations over the projection horizon. Segmentation dimensions modeled include product type, application tier, end-user procurement structure, and manufacturing technology process maturity. CAGRs derived from regression analysis of historical capacity additions and OEM platform launch timelines, with specific inputs from flex-fuel light-truck fleet expansion schedules and electrical housing adoption curves for hybrid platforms.
Decision-makers should treat outputs as directional under stable regulatory enforcement and continued Rota 2030 incentive continuity; material deviation would warrant model refresh. Forecasts assume ANVISA chemical exposure limits remain binding and Central Bank volatility management prevents sustained currency depreciation beyond historical bands. Revision becomes warranted when carbon fiber precursor supply chain disruptions or Rota 2030 cancellation cross thresholds that invalidate local content compliance assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Automotive Exhaust Emission Control Device Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Plastic Components Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
Automotive Axle Market
Automotive Components
Global Automotive Structural Sheet Metal Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
India Automotive Stamping Market
Automotive Components
Italy Automotive Actuators Market
Automotive Components
Automotive Exhaust Manifolds Market