
 Automotive Distributor Market | 2026-2036
Automotive Distributor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Distributor Market Analysis
EPA emissions enforcement is recalibrating the cost-of-entry calculus for aftermarket distributors, forcing compliance investments in traceable supply chains and certified parts documentation. Genuine Parts Company leverages its NAPA network to sustain coast-to-coast coverage density. AutoZone anchors its position through proprietary private-label lines and same-day fulfillment infrastructure. O'Reilly Automotive differentiates via professional installer programs that lock in repair shop loyalty.
An automotive distributor procures, warehouses, and delivers vehicle components—ranging from brake assemblies with DOT friction ratings to CAN-bus-compatible sensors—through multi-tier logistics networks serving repair facilities and retail channels. The product-type split shows aftermarket parts commanding the broadest SKU breadth and highest inventory turns, while OEM parts concentrate margin in warranty-captive channels. Wholesale distribution retains structural dominance for collision and mechanical repair volumes, though online channels capture growing share among individual consumers seeking price transparency on maintenance items.
FCC regulations on connected-vehicle telematics modules intersect with NHTSA safety standards to shape which electronic components distributors may legally stock and sell. OSHA warehouse safety mandates and DOT hazmat shipping rules further constrain operational economics for multi-location distributors. Stakeholders must monitor how right-to-repair legislation evolves across state capitals, as expanded access mandates would force distributors to reconfigure parts-data systems and technical support staffing.
Market Dynamics
EPA emissions enforcement is compressing inventory cycles for catalytic converters and oxygen sensors, forcing distributors to restructure supplier verification protocols and documentation systems. Tier-1 distributors absorb compliance costs through scale, while regional players face margin compression from traceability investments.
Growth Catalysts
- Commercial fleet consolidation:Fleet operators are aggregating parts procurement under single-source national contracts, favoring distributors with coast-to-coast warehouse networks and consolidated billing platforms.
- Right-to-repair momentum:State-level repair access legislation in Massachusetts and expanding similar frameworks are mandating standardized parts data access, opening technical documentation revenue streams for distributors.
- Telematics module proliferation:Connected-vehicle sensor replacement cycles are accelerating aftermarket demand for CAN-bus-compatible components across passenger and commercial vehicle segments.
Market Restraints
- Semiconductor input volatility:Sensor and module distributors face margin pressure from fluctuating chip allocation priorities at upstream foundries, particularly for automotive-grade microcontrollers.
- Supplier concentration in rare earth processing:Catalytic converter substrate sourcing remains concentrated in Chinese refining operations, exposing inventory cost spikes from export quota adjustments.
- FCC certification friction:Connected-vehicle telematics components require device-specific authorization cycles that extend stockout recovery times beyond traditional mechanical parts.
Strategic Opportunities
- EV powertrain aftermarket emergence:Battery thermal management components and electric motor bearings represent greenfield SKU categories as first-wave EV fleets exit warranty coverage.
- Independent repair channel digitization:Mobile-first parts ordering platforms for small mechanical shops remain underpenetrated relative to collision repair electronic parts procurement systems.
- IRA clean vehicle incentives:Federal tax credits for commercial EV adoption are expanding fleet electrification timelines, creating demand for hybrid-compatible brake and suspension components.
Industry Challenges
- Automotive cybersecurity certification gaps:Distributors stocking telematics modules lack standardized technician training frameworks for secure installation protocols, slowing category expansion.
- Legacy warehouse management system integration:Real-time inventory visibility requirements for same-day fulfillment clash with mainframe-era ERP architectures at mid-scale distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Distributor Market |
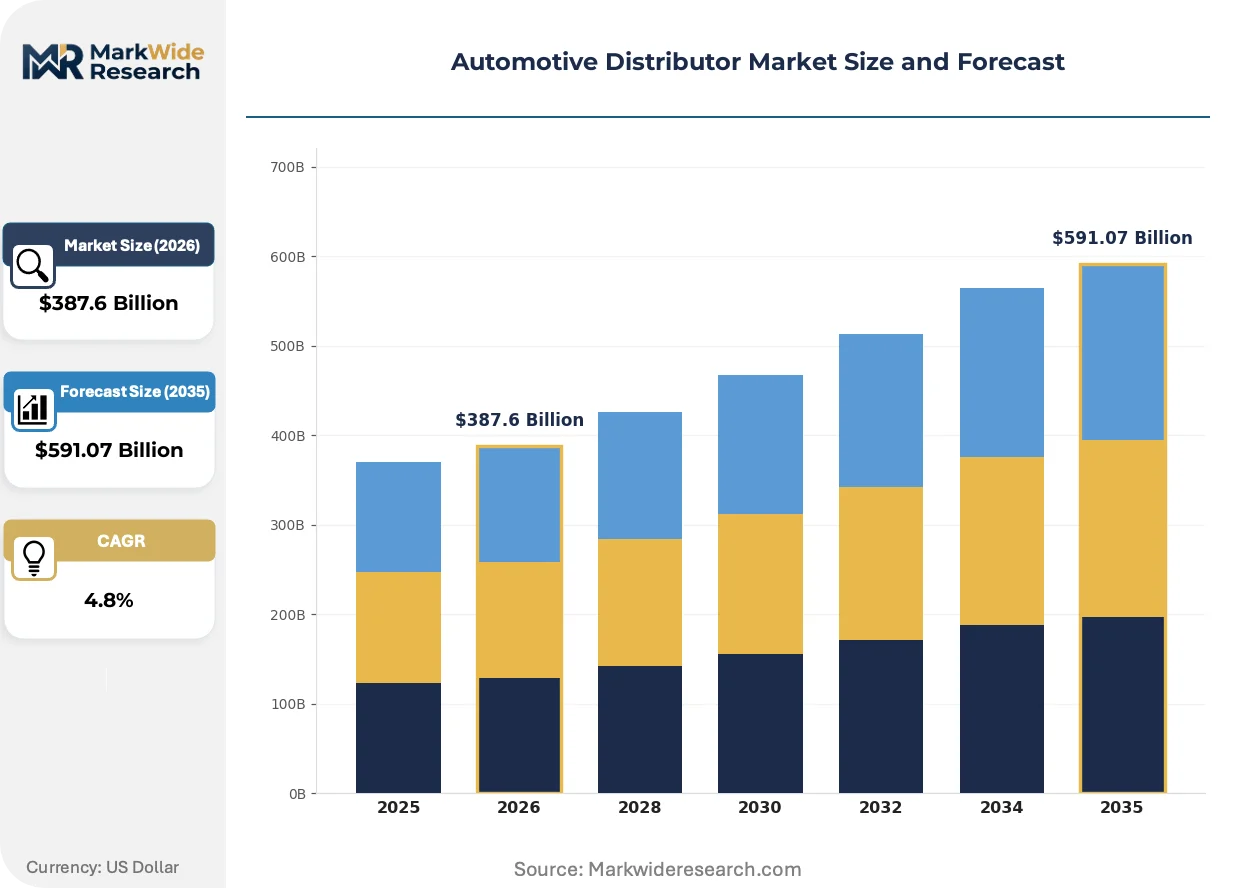
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Distribution Channel: Wholesale, Retail, Online, Direct Sales Product Type: OEM Parts, Aftermarket Parts, Accessories, Tools Customer Type: Dealerships, Repair Shops, Fleet Operators, Individual Consumers Service Type: Logistics, Inventory Management, Technical Support, Training |
| Companies Covered | Advance Auto Parts, Uni-Select, Genuine Parts Company, Asbury Automotive Group, Group 1 Automotive, AutoZone, CarParts.com, Lithia Motors, O'Reilly Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Distributor Market Emerging Trajectories
Digital procurement interfaces are compressing order-to-delivery windows while predictive inventory algorithms reshape stocking decisions. Three developments are restructuring competitive position.
Artificial intelligence-driven demand forecasting is overtaking historical sales-based replenishment models. Distributors deploying machine learning on telematics-derived failure data are reducing safety stock requirements by fifteen to twenty percent. Professional installer channels adopt these systems fastest, squeezing competitors reliant on manual category management.
The EPA's tightened enforcement on catalytic converter supply chain documentation is forcing distributors to deploy blockchain-based provenance tracking. Non-compliant suppliers face delisting from approved vendor rosters. Smaller distributors lacking IT infrastructure to support serialized part tracking are exiting the converter category entirely.
Repair shops are consolidating parts purchasing through integrated shop management system interfaces rather than standalone distributor portals. This behavior concentrates volume with distributors offering API-native inventory connectivity. The shift is most visible in the United States, where multi-location mechanical repair chains now mandate direct ERP-to-ERP procurement integration.
Automotive Distributor Market Segmentation
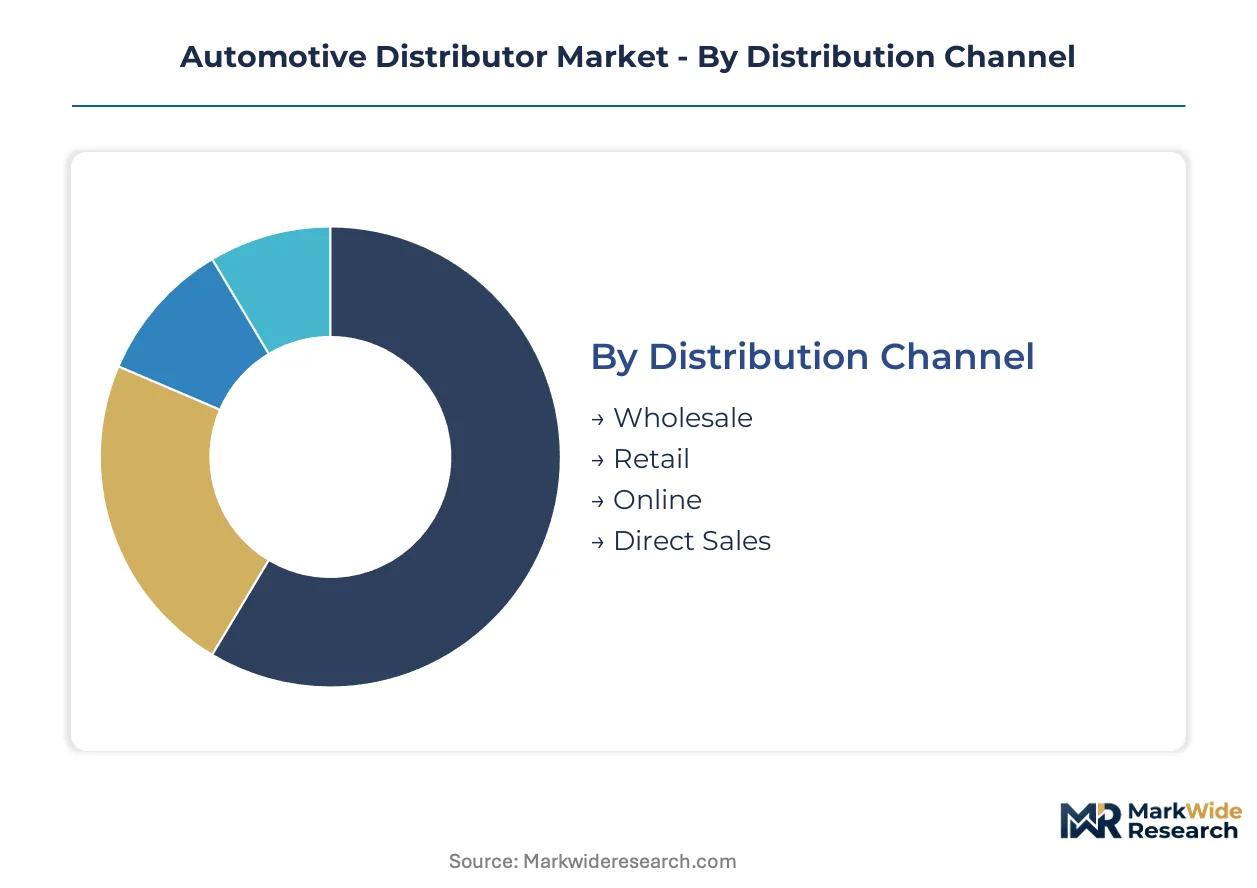
Automotive distributors configure capital deployment and operational footprint differently across channel structures and customer interfaces. Segment boundaries determine which players capture margin from complexity versus scale.
Distribution Channel:
Capital intensity peaks in segments requiring physical infrastructure density and last-mile fleet investment.
- Wholesale:Multi-location warehouse networks with dedicated delivery fleets serve collision repair chains and mechanical shops. Fleet operators in the United States concentrate procurement through these channels, demanding consolidated billing and coast-to-coast coverage density.
- Retail:Counter-based operations with high-turn inventory positioning serve walk-in professional installers and consumers. Same-day fulfillment infrastructure requires real-time inventory systems that compress working capital cycles.
- Online:Digital-first platforms with drop-ship or centralized fulfillment models reduce fixed asset requirements.
- Direct Sales:Manufacturer-captive distribution bypasses independent intermediaries for warranty parts and proprietary components.
Most installed capacity flows through wholesale networks. Expansion is steepest in online channels.
Product Type:
Margin profiles diverge sharply between warranty-captive supply and competitive aftermarket replacement cycles.
- OEM Parts:Factory-authorized components with proprietary fitment data and warranty documentation. Dealership service departments in the United States anchor demand, though EPA emissions enforcement is recalibrating inventory requirements for certified catalytic converters and sensors.
- Aftermarket Parts:Third-party brake assemblies, filtration systems, and electrical components with broad SKU breadth. Repair shops seeking price transparency on maintenance items drive highest inventory turns in this category.
- Accessories:Non-essential cabin and exterior enhancement products with seasonal demand patterns.
- Tools:Diagnostic equipment and service hardware with extended replacement cycles.
Aftermarket parts generate the broadest revenue base. OEM parts retain the highest per-unit margin contribution.
Customer Type:
Account complexity scales with transaction volume and technical support requirements.
- Dealerships:Franchise service operations requiring just-in-time OEM parts delivery and manufacturer-compliant documentation systems. NHTSA safety standards and FCC regulations on connected-vehicle modules shape which electronic components distributors may legally stock for this channel.
- Repair Shops:Independent mechanical and collision facilities consolidating procurement through integrated shop management systems. Professional installer programs that lock in loyalty represent the primary competitive battleground here.
- Fleet Operators:Commercial vehicle managers aggregating parts procurement under single-source national contracts.
- Individual Consumers:Price-sensitive end-users capturing growing share through online channels seeking transparency on maintenance items.
Fleet operators command the largest average order values. Repair shops represent the deepest penetration opportunity.
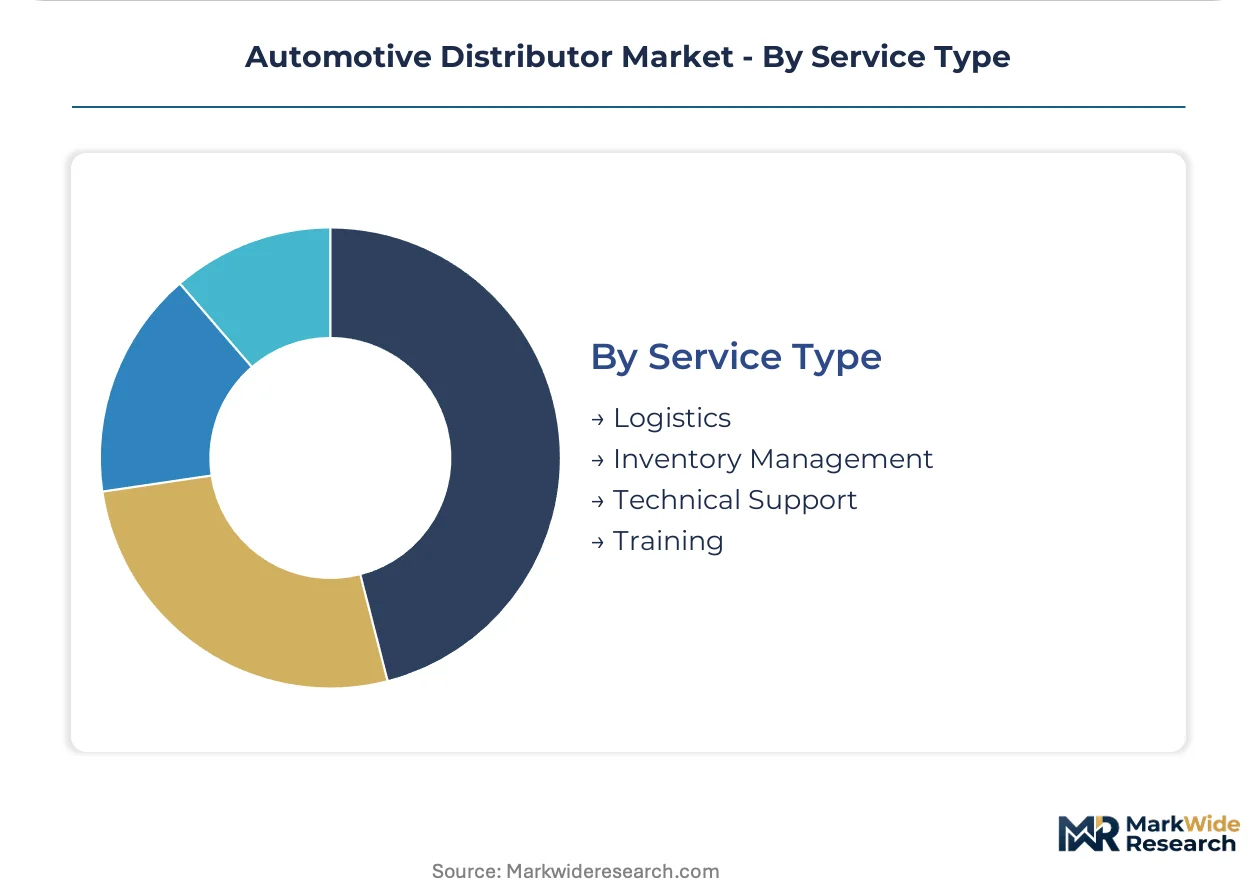
Service Type:
Value-added capabilities separate full-service distributors from pure logistics intermediaries.
- Logistics:Core warehousing, inventory positioning, and last-mile delivery execution. Predictive algorithms on telematics-derived failure data are reducing safety stock requirements by fifteen to twenty percent for distributors deploying machine learning.
- Inventory Management:Vendor-managed stock programs and consignment arrangements at customer locations. Blockchain-based provenance tracking is becoming mandatory for EPA-compliant catalytic converter documentation.
- Technical Support:Helpline and field engineering assistance for complex installations.
- Training:Certification programs for repair technicians on new vehicle technologies.
Logistics absorbs the majority of operational investment. Inventory management services are gaining share fastest as compliance requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive distribution industry traces its modern scale to post-war United States industrial expansion, when highway infrastructure and suburban vehicle ownership created the first national parts networks. This legacy shapes today's geographic concentration patterns.
United States
Large-format distributors command disproportionate aftermarket share through coast-to-coast warehouse density. EPA emissions enforcement recalibrates inventory requirements for catalytic converters and oxygen sensors, forcing traceable supply chain investments. The Detroit-to-Chicago corridor anchors collision parts distribution, while Texas and Florida hubs serve expanding fleet operator procurement consolidation.
Germany
Precision engineering heritage sustains premium OEM parts distribution through manufacturer-captive channels. REACH and RoHS compliance frameworks shape which electronic components distributors may legally stock for connected vehicles. The Stuttgart-Munich industrial belt concentrates specialist distributors serving independent repair shops with German-brand vehicle expertise.
China
Rare earth processing concentration for catalytic converter substrates exposes inventory cost volatility from export quota adjustments. MIIT standards on vehicle telematics modules intersect with GB certification requirements for aftermarket electronic components. Yangtze River Delta logistics clusters enable same-day fulfillment to the world's largest vehicle parc.
Japan
Just-in-time distribution philosophy permeates keiretsu-linked parts networks serving domestic OEM service channels. METI regulations on connected-vehicle data security constrain which telematics modules aftermarket distributors may legally supply. Nagoya-centered industrial zones maintain specialized thermal management component distribution for hybrid powertrains.
India
Fragmented independent repair shop density creates underpenetrated opportunity for mobile-first parts ordering platforms. BIS certification requirements for automotive components extend stockout recovery times versus unregulated mechanical parts. Tamil Nadu and Maharashtra manufacturing corridors generate growing aftermarket demand as first-wave vehicle fleets age beyond warranty coverage.
Automotive Distributor Market Vendor Landscape
The competitive structure tilts toward national-scale warehouse networks with professional installer program lock-in. Three tiers separate coast-to-coverage leaders from regional specialists and digital-first entrants. Consolidation pressure intensifies as compliance investments in traceable supply chains favor scale. Dominant competitive moves include M&A for geographic density and API-native inventory connectivity for repair shop ERP integration.
Among North American parts networks, Genuine Parts Company, AutoZone, and O'Reilly Automotive represent the scale-driven archetype with coast-to-coast infrastructure. These entities exemplify how professional installer loyalty programs and same-day fulfillment capabilities anchor market position against digital entrants. Their structural advantage resides in decades of warehouse network accumulation that regional competitors cannot replicate without capital intensity beyond mid-scale balance sheet capacity.
| Leading Market Players |
|---|
| Advance Auto Parts |
| Uni-Select |
| Genuine Parts Company |
| Asbury Automotive Group |
| Group 1 Automotive |
| AutoZone |
| CarParts.com |
| Lithia Motors |
| O'Reilly Automotive |
| Others |
Supply Flow & Price Mechanics
Fleet operator procurement consolidation in the United States anchors contract-based long-term offtake agreements, compressing margin negotiation leverage for regional distributors lacking coast-to-coast warehouse density. EPA emissions enforcement on catalytic converters and oxygen sensors forces traceability investments that Tier-1 players absorb through scale while smaller competitors exit the category entirely.
Pricing Analysis
Three-tier pricing structure across premium certified, standard aftermarket, and economy private-label levels stratifies the market. Price differentiation rests on EPA certification grade and volume scale, with genuine OEM components commanding substantial premiums over non-certified alternatives. Pricing pressure stems from semiconductor input volatility squeezing sensor and module margins. Individual consumers exhibit highest price sensitivity, while fleet operators prioritize consolidated billing and coverage density over per-unit cost.
Supply Chain Analysis
Freight cost escalation from diesel price volatility and driver shortage pressures multi-location warehouse networks serving mechanical repair chains. Geographic supply concentration centers on China for rare earth catalytic converter substrates, Germany for precision OEM components, and Mexico for nearshored brake and suspension assemblies. Raw material dependencies include automotive-grade microcontrollers, platinum-group metals, and specialized steel alloys. Single-source vulnerability in Chinese rare earth refining exposes inventory cost spikes from export quota adjustments. Distribution runs through wholesale networks with dedicated delivery fleets, though online channels capture growing individual consumer share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive distributor market functions as a regulatory compounder, with EPA emissions enforcement recalibrating inventory requirements and compliance investments that scale-favored incumbents leverage to consolidate share.
For Market Incumbents: Deepen vertical integration into certified catalytic converter supply chains to capture traceability premiums and delist non-compliant competitors. Expand API-native inventory connectivity for repair shop ERP integration, locking in professional installer loyalty against digital entrants. EPA documentation mandates represent the primary consolidation lever. For New Entrants and Emerging Players: Launch via mobile-first parts ordering platforms targeting India's fragmented independent repair shop density, where digital penetration lags collision repair electronic procurement systems. White-space opportunity concentrates in battery thermal management components for first-wave EV fleets exiting warranty coverage. Direct shop management system integration offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Private equity firms with automotive services portfolios are the most active acquirer in this space, seeking regional distributors with repair shop concentration but lacking IT infrastructure for serialized part tracking. Long-term viability favors platforms with coast-to-coast density and professional installer program lock-in. Monitor right-to-repair legislation expansion across state capitals as the signal for technical documentation revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Tracking Deployment | EPA emissions enforcement mandates serialized catalytic converter documentation, forcing IT infrastructure investments that favor scale. |
| API-Native ERP Integration | Repair shop consolidation through integrated shop management systems concentrates volume with distributors offering direct connectivity. |
| EV Powertrain SKU Expansion | Battery thermal management components and electric motor bearings represent greenfield categories as hybrid fleets age beyond warranty. |
| Professional Installer Program Lock-In | Same-day fulfillment capabilities and technical support staffing anchor loyalty against price-transparent online channels. |
| Coast-to-Coast Warehouse Network M&A | Consolidated fleet procurement under single-source national contracts demands coverage density regional players cannot replicate. |
Methodological Framework
Bottom-up repair shop and fleet operator demand modeling reconciled against top-down distributor shipment tracking forms the analytical core. Primary interviews with aftermarket distributor procurement directors, OEM platform engineers, Tier 1 supplier logistics managers, and independent repair shop owners combined with secondary validation from EPA enforcement disclosures, NHTSA safety standard filings, and vehicle registration databases. Trade data on catalytic converter substrate flows and semiconductor allocation reports provided upstream supply-side triangulation.
Input-output matrices mapped parts demand across vehicle class, propulsion architecture, distribution channel, and customer type segments. CAGRs derived from regression analysis on historical shipment patterns and elasticity-adjusted demand projections. Forecast inputs incorporated telematics module replacement cycle acceleration, EV fleet electrification timelines under IRA incentives, and right-to-repair legislative adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor allocation disruption or rare earth export quota shocks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Argentina Automotive Electric Actuators Market
Automotive Components
Automotive Silencer Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Drive System Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market
Automotive Components
Automotive Carbon Ceramic Brakes Market
Automotive Components
Automotive Metal Timing Chain Market
Automotive Components
Global Automotive Water Separation Systems Market
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
Automotive Differential Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Global Cylinder Deactivation System Market