
 Automotive Fuel Injection Pump Market | 2026-2036
Automotive Fuel Injection Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Injection Pump Market Intelligence
The trend towards modular fuel system integration, bundling pumps with injectors and rails, is shifting procurement patterns away from individual components. Bosch leverages its extensive R&D in high-pressure systems to anchor the common rail segment. Denso Corporation specializes in highly efficient piezoelectric technologies integrated with its pump designs. Meanwhile, Continental AG competes through its comprehensive powertrain solutions for both passenger cars and commercial vehicles, positioning itself as a system supplier to major OEMs.
An automotive fuel injection pump is a high-precision device that pressurizes fuel and delivers it to the engine's injectors at precise intervals. These systems operate at pressures exceeding 2,000 bar in modern common rail designs to ensure fine atomization and efficient combustion. Common rail pump technology leads the market, displacing older mechanical and distributor pump designs due to superior efficiency. While passenger cars form a large volume base, the commercial vehicles application provides higher-margin opportunities for advanced pump systems.
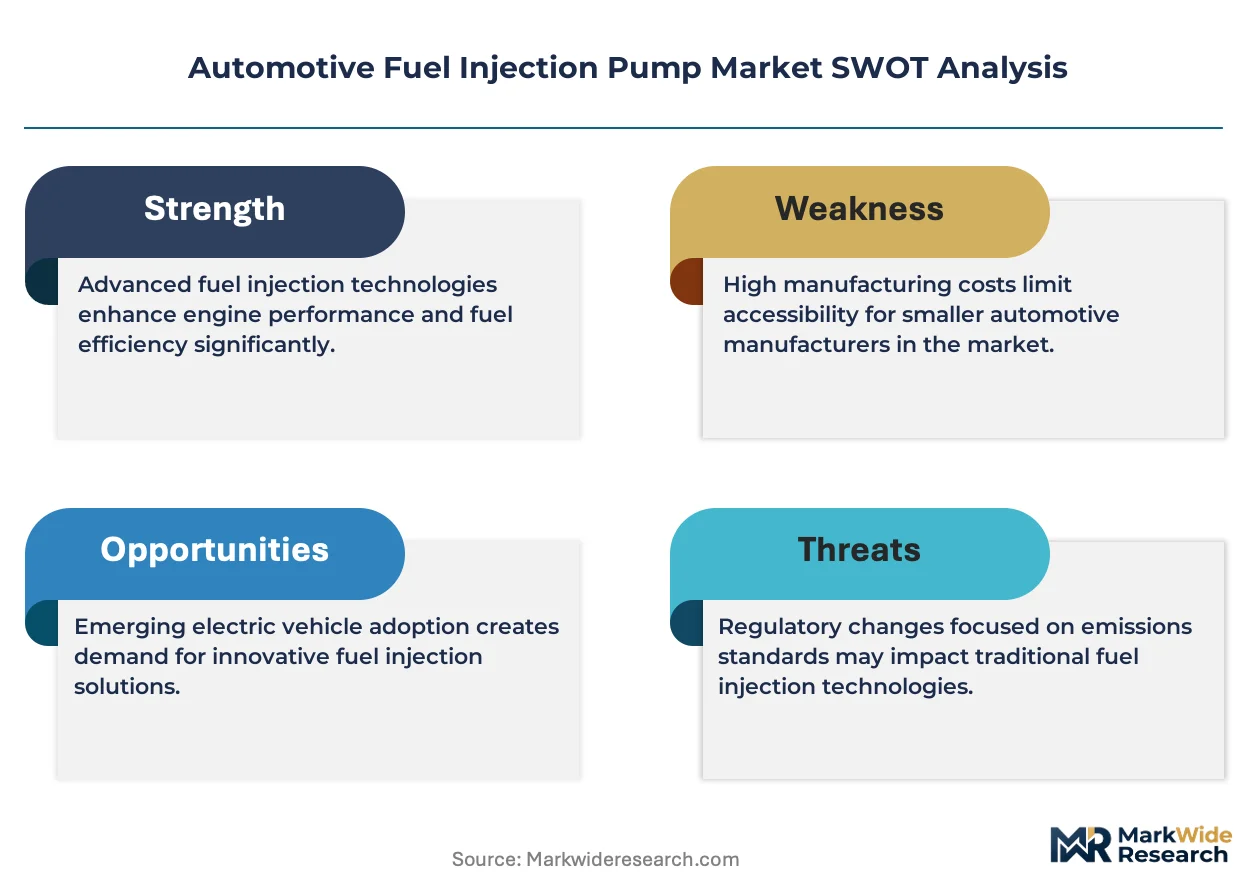
Stringent emissions mandates, including the EPA's standards in the United States, Euro 7 regulations in Europe, and China's GB standards, are the primary market shapers. These regulations compel original equipment manufacturers to adopt higher-pressure and more precise fuel injection technologies to meet pollution targets. Component suppliers must now decide between specializing in advanced diesel systems or diversifying into solutions for alternative fuels and hybrid powertrains to remain competitive.
Market Dynamics
The primary force defining the fuel injection pump market is the global regulatory mandate for reduced emissions. This pressure compels a technological race toward higher operating pressures and greater precision in fuel delivery.
Growth Catalysts
- Global Emissions Standards:Mandates such as Euro 7 in Europe and stringent GB standards in China necessitate the adoption of advanced, high-pressure pump technologies to meet pollution reduction targets.
- Commercial Vehicle Sector Growth:Expansion in logistics and freight, particularly in Asian markets, creates sustained demand for efficient and durable diesel fuel injection systems offering higher margins.
- Technology Transition:The ongoing shift from legacy mechanical pumps to superior common rail systems provides a continuous replacement and upgrade cycle, driven by performance and fuel economy benefits.
Market Restraints
- Powertrain Electrification:The strategic pivot by automakers toward battery electric vehicles (BEVs) directly shrinks the long-term addressable market for all internal combustion engine components, including fuel pumps.
- High Capital Investment:Manufacturing pumps that meet extreme pressure and tolerance specifications requires significant capital outlay for precision machinery, limiting new market entrants and pressuring margins.
- Substitution by GDI:In passenger cars, the rise of gasoline direct injection (GDI) systems creates a competing technology track, diverting R&D resources away from diesel-focused pump development.
Strategic Opportunities
- Alternative Fuel Systems:Engineering injection pumps compatible with hydrogen, ammonia, or advanced biofuels creates new revenue streams and aligns with long-term decarbonization goals in heavy-duty transport.
- Aftermarket Remanufacturing:Establishing certified remanufacturing programs for complex common rail pumps addresses a cost-sensitive segment and builds a circular economy model, especially in developing regions.
- Hybrid Vehicle Optimization:Developing specialized, compact pump modules for gasoline direct injection in hybrid powertrains caters to a growing vehicle segment that requires high efficiency.
Industry Challenges
- System Integration Complexity:Ensuring flawless communication between the fuel pump, engine control unit (ECU), and injectors, often from multiple vendors, remains a primary technical hurdle for vehicle integrators.
- Counterfeit Component Risk:The proliferation of unauthorized, low-quality copies in the global aftermarket poses significant safety risks and erodes brand value for established manufacturers.
- Specialized Talent Gap:A persistent shortage of engineers with expertise in high-pressure fluid dynamics and mechatronic control systems constrains innovation and production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Injection Pump Market |
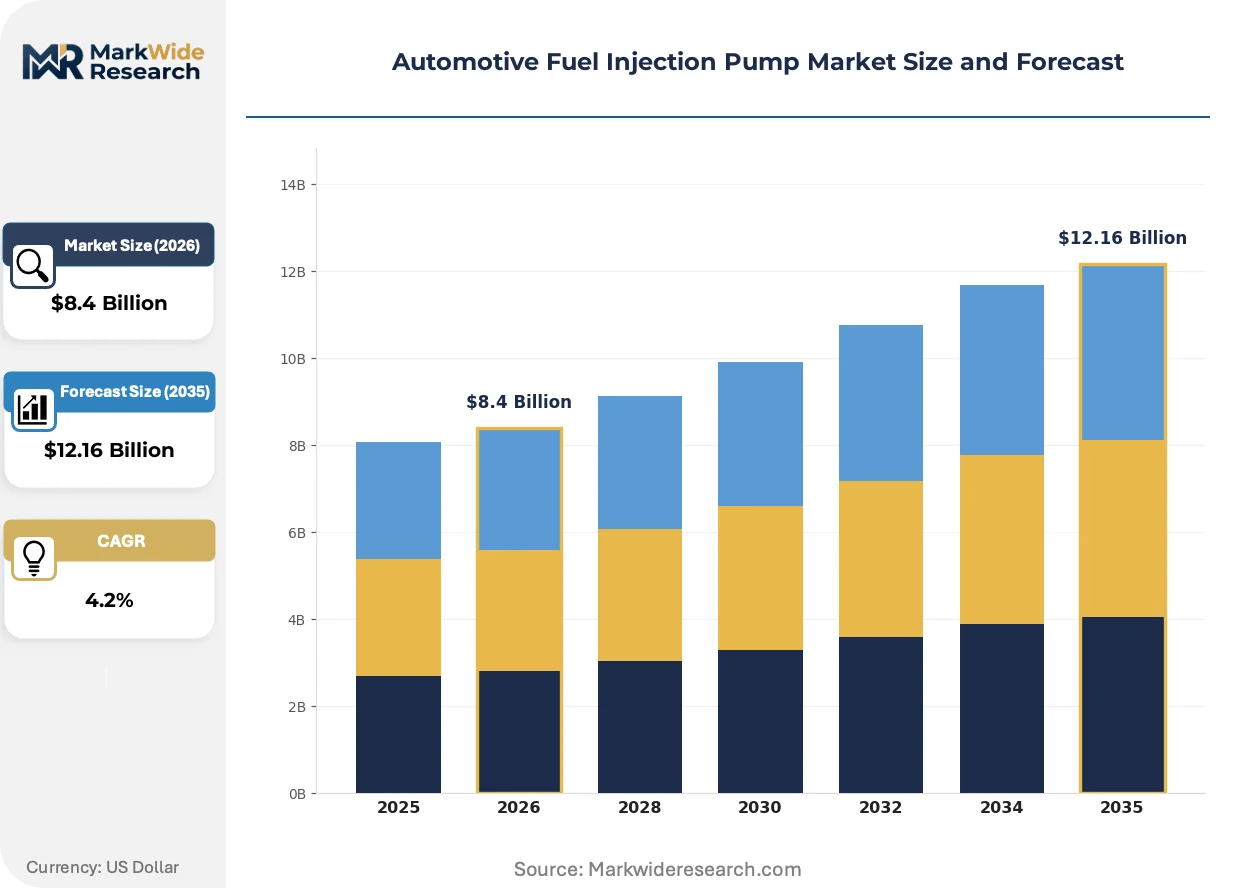
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Pump, Electronic Pump, Common Rail Pump, Distributor Pump Technology: Piezoelectric, Electromagnetic, Hydraulic, Solenoid Application: Passenger Cars, Commercial Vehicles, Construction Machinery, Agricultural Machinery End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Service Providers |
| Companies Covered | Bosch, Denso Corporation, Continental AG, Delphi Technologies, Cummins Inc., BorgWarner Inc., Hitachi Astemo Ltd., Marelli Holdings Co., Ltd., Stanadyne LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Injection Pump Market Strategic Shifts & Innovations
Innovation in the fuel injection pump sector is driven by a dual mandate. Suppliers must engineer components with unprecedented efficiency for internal combustion engines while positioning for a future with alternative powertrains.
Electronically controlled pump actuators with embedded sensors provide dynamic fuel pressure modulation. Commercial vehicle OEMs rapidly adopt this technology to meet emissions test cycles. This integration is automating fuel delivery calibration, allowing the system to self-adjust to engine conditions.
Europe's Euro 7 regulation imposes stricter pollutant limits under real-world driving conditions. This impacts diesel engine design, compelling investment in injection systems capable of higher pressures and multiple injection events. The commercial vehicle segment is most affected, driving innovation in pump and after-treatment synergy.
A shift in purchasing behavior involves OEMs sourcing pre-integrated fuel delivery modules instead of discrete components. This trend favors system suppliers providing a validated pump, rail, and injector package, simplifying OEM assembly. The practice is most visible in China's automotive sector, where speed-to-market is critical.
Automotive Fuel Injection Pump Market Segmentation
The automotive fuel injection pump market segments reflect varied technological capabilities and diverse application demands across the vehicle industry. Understanding these distinctions helps manufacturers align product development with specific performance requirements and regulatory pressures. Market segmentation provides clarity on where investment in advanced systems generates the most significant returns for suppliers.
Product Type:
Buyer decisions for fuel injection pumps increasingly prioritize precision and efficiency, directly influencing the adoption of advanced product types. Emissions regulations and fuel economy targets heavily shape these procurement choices across vehicle platforms.
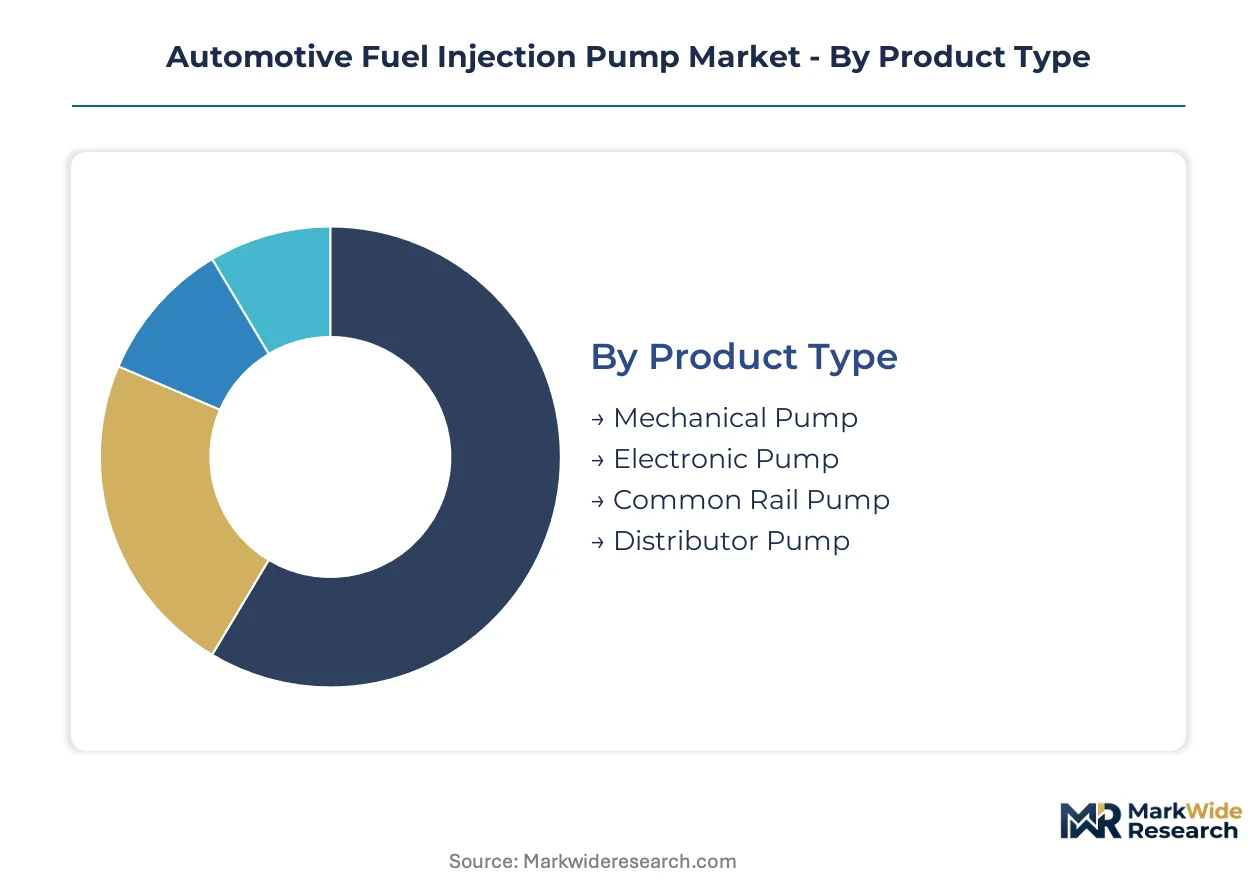
- Common Rail Pump:This product type delivers fuel at extremely high pressures through a shared rail to individual injectors, ensuring precise timing and atomization. Demand concentrates in commercial vehicles and modern diesel passenger cars due to stringent Euro 7 and GB emissions standards.
- Electronic Pump:Electronically controlled pumps integrate sensors and actuators for dynamic fuel pressure modulation, allowing for adaptive delivery based on engine conditions. Commercial vehicle OEMs rapidly adopt this technology to optimize combustion and meet evolving emissions test cycles.
- Mechanical Pump:These older designs utilize mechanical linkages to deliver fuel, offering robust simplicity but lacking the precision of modern systems. Legacy vehicles and certain off-highway machinery still utilize mechanical pumps.
- Distributor Pump:Distributor pumps use a single pumping element to distribute fuel to all cylinders, representing a step up from mechanical but still less advanced than common rail systems. These pumps see declining use as modern designs prevail.
Common Rail Pump leads on scale; Electronic Pump leads on momentum.
Technology:
Application focus guides technology selection within the fuel injection pump market, with specific vehicle performance and efficiency needs driving material and actuation choices. Different technologies offer distinct advantages in terms of response time, pressure capability, and cost efficiency.
- Piezoelectric:Piezoelectric technology utilizes ceramic materials that change shape when an electric current is applied, enabling extremely fast and precise injector actuation. Denso Corporation leverages this technology for highly efficient systems in high-performance diesel engines.
- Electromagnetic:Electromagnetic systems employ solenoids to control fuel flow and pressure, offering a balance of responsiveness and cost-effectiveness for various injection applications. This technology finds widespread use in both gasoline and diesel direct injection systems.
- Hydraulic:Hydraulic systems use fluid pressure to operate components within the pump, providing high force capabilities for certain heavy-duty applications. These systems are common in older, larger diesel engines requiring robust operation.
- Solenoid:Solenoid-based technology controls fuel delivery through electrically activated valves, offering reliable and cost-effective solutions for various fuel injection pump designs. Solenoid systems are prevalent across diverse engine types.
Technology choices differentiate pump performance, with Piezoelectric systems offering superior precision and Electromagnetic solutions balancing cost and efficiency.
Application:
Vehicle type significantly influences the required pump specifications, with each application demanding specific durability, pressure, and efficiency characteristics from fuel injection systems. The operational environment and duty cycle of the vehicle dictate the design priorities for these components.
- Commercial Vehicles:This segment includes heavy-duty trucks, buses, and vans, which require robust, high-pressure fuel injection pumps for sustained operation and strict emissions compliance. Growth in logistics and freight, particularly in Asian markets, drives demand for advanced diesel systems.
- Passenger Cars:Passenger cars represent a large volume base for fuel injection pumps, with a focus on fuel economy, reduced noise, and lower emissions for gasoline and diesel engines. The shift towards GDI systems and hybrid powertrains shapes pump development in this segment.
- Construction Machinery:Excavators, loaders, and other heavy equipment in construction demand durable fuel injection systems capable of operating under harsh conditions and varying loads. These machines prioritize reliability and power delivery.
- Agricultural Machinery:Tractors, harvesters, and other farm equipment require resilient fuel injection pumps designed for continuous operation and efficiency in demanding agricultural environments. Emissions standards for off-road engines also influence this application.
Commercial Vehicles contribute higher-margin opportunities, while Passenger Cars account for the largest unit volumes in the market.
End User:
The purchasing entity determines procurement channels and service requirements for fuel injection pumps, ranging from new vehicle integration to replacement parts and maintenance. Each end-user type has distinct needs regarding product specifications, volume, and supply chain logistics.
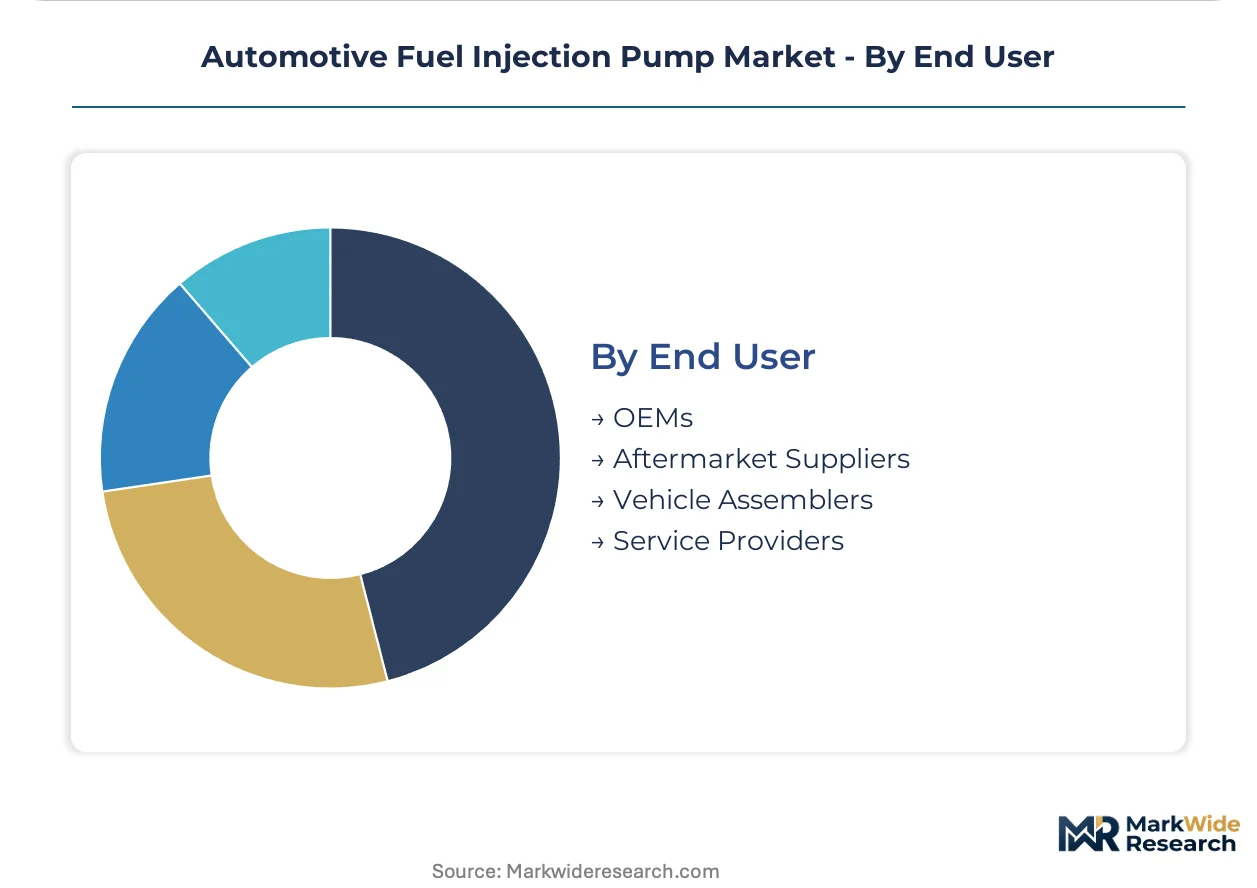
- OEMs:Original Equipment Manufacturers integrate fuel injection pumps directly into new vehicle production lines, often sourcing pre-integrated fuel delivery modules from system suppliers like Bosch and Continental AG. These manufacturers demand high-volume supply and strict quality control.
- Aftermarket Suppliers:These entities provide replacement parts and components for vehicles already in operation, catering to repair and maintenance needs. Establishing certified remanufacturing programs addresses a cost-sensitive segment within the aftermarket.
- Vehicle Assemblers:Vehicle assemblers, distinct from full OEMs, often purchase pre-fabricated engine sub-assemblies including fuel injection systems for final vehicle construction. Their focus lies on efficient integration and component compatibility.
- Service Providers:Independent garages and authorized service centers procure fuel injection pumps for vehicle repair and maintenance, requiring reliable parts and comprehensive technical support. This segment values availability and diagnostic tools.
OEMs drive initial demand for new systems, while Aftermarket Suppliers ensure continued vehicle operation and component longevity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive fuel injection pump industry scaled significantly in regions with established automotive manufacturing hubs, particularly in Western Europe and North America, before expanding to Asian powerhouses. The necessity for precise fuel delivery systems drives regional development, influenced by local emissions mandates and vehicle production volumes.
China
China's vast automotive manufacturing sector drives substantial demand for fuel injection pumps. The country's stringent GB standards compel local manufacturers to adopt advanced high-pressure systems. Production clusters in the Yangtze River Delta, including cities like Shanghai, focus on integrating these sophisticated components into new vehicle platforms.
Germany
Germany, a hub for premium automotive engineering, demands high-precision fuel injection pumps for both passenger cars and commercial vehicles. Euro 7 regulations push for continuous innovation in diesel and gasoline direct injection systems. Bavaria, home to major automotive OEMs, leads in developing and integrating next-generation fuel delivery technologies.
United States
The United States commercial vehicle segment provides a strong market for durable, high-performance fuel injection pumps. EPA emissions standards dictate the need for efficient fuel atomization across engine types. Detroit, Michigan, remains a critical center for powertrain development and component integration for North American vehicle production.
Japan
Japan's focus on advanced engine technology and fuel efficiency sustains demand for innovative fuel injection pump designs. Policies from the Ministry of Economy, Trade and Industry (METI) encourage R&D in hybrid and alternative fuel powertrains. The Aichi Prefecture, a core automotive region, concentrates on manufacturing high-tech components for global markets.
India
India's expanding automotive market, particularly in the commercial vehicle and tractor segments, creates a growing need for robust fuel injection pumps. The government's Production Linked Incentive (PLI) scheme supports domestic manufacturing of advanced automotive components. Chennai, a major automotive manufacturing hub, sees increasing investment in fuel system production.
Automotive Fuel Injection Pump Market Key Industry Players
The competitive structure tilts toward established, large-scale system integrators with extensive R&D capabilities. These dominant players often provide complete fuel delivery modules rather than individual components. Strategic archetypes include global powertrain technology providers, specialized high-pressure system manufacturers, and diversified industrial component suppliers. Dominant competitive moves involve significant capital investment in precision manufacturing and strategic partnerships with major vehicle OEMs.
Global powertrain technology providers like Bosch and Continental AG exemplify the market's trajectory towards integrated solutions, leveraging their broad portfolios. Denso Corporation, a Japanese entity, occupies a position as a leading specialized component manufacturer, anchoring the segment for highly efficient piezoelectric technologies. These firms collectively demonstrate the industry's drive for technological leadership and system-level integration.
| Leading Market Players |
|---|
| Bosch |
| Denso Corporation |
| Continental AG |
| Delphi Technologies |
| Cummins Inc. |
| BorgWarner Inc. |
| Hitachi Astemo Ltd. |
| Marelli Holdings Co., Ltd. |
| Stanadyne LLC |
| Others |
Cost & Logistics Intelligence
Performance-based tiering in fuel injection pumps, driven by precision requirements and emissions compliance, directly influences both pricing power and the configuration of highly specialized supply chains.
Pricing Analysis
Value-based pricing governs the advanced fuel injection pump market, reflecting the high R&D investment and precision manufacturing required for common rail systems. Price differentiation stems from the technology implemented, such as piezoelectric actuation, and the specific certification levels needed for Euro 7 compliance. Pricing softness reflects intense competition for OEM contracts, particularly in the passenger car segment. Commercial vehicle OEMs, prioritizing long-term durability and emissions performance, exhibit lower price sensitivity for high-margin systems.
Supply Chain Analysis
Skilled workforce availability for precision machining and mechatronics engineering significantly shapes manufacturing concentrations in Germany and Japan. The supply chain draws from specialized inputs like high-pressure steel alloys and advanced electronic control units. Single-source vulnerability for certain proprietary components poses a structural risk. Distribution runs through direct OEM supply channels for new vehicle production, complemented by a multi-tier aftermarket network for replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive fuel injection pump market operates as a stable compounder, underpinned by persistent global emissions regulations that mandate continuous technological upgrades.
For Market Incumbents: Extend R&D leadership in high-pressure common rail systems to maintain a competitive edge against new entrants offering alternative powertrain components. Deepen vertical integration into precision component manufacturing to control quality and mitigate supply chain risks. Focus on developing compact, efficient pump modules for hybrid powertrains, addressing the strategic pivot by automakers. This strategy counters the long-term threat of powertrain electrification by diversifying product offerings.
For New Entrants and Emerging Players: Online aftermarket platforms present a viable entry point for specialized component providers, particularly for remanufactured common rail pumps in cost-sensitive markets. Target the commercial vehicle aftermarket in developing regions, where demand for durable and repairable systems remains robust. Focus on developing alternative fuel systems compatible with hydrogen or ammonia, aligning with long-term decarbonization goals. A go-to-market angle emphasizing cost-effectiveness and localized service can capture market share.
For Investors and Strategic Acquirers: Consolidation pressure builds where scale and R&D capabilities are paramount for meeting stringent emissions standards. Investors should seek out mid-cap specialists with proprietary high-pressure technology or strong regional manufacturing footprints. These targets offer long-term viability within the heavy-duty commercial vehicle segment, which provides higher-margin opportunities. The signal to watch is the pace of adoption for alternative fuel powertrains in heavy transport, indicating future market shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Piezoelectric Technology | Denso Corporation leverages this for highly efficient systems, enabling superior precision in fuel delivery. |
| Develop Modular Fuel Delivery Systems | Bosch provides pre-integrated pump, rail, and injector packages, simplifying OEM assembly and procurement. |
| Expand Alternative Fuel Pump R&D | Engineering pumps for hydrogen or ammonia creates new revenue streams for heavy-duty transport decarbonization. |
| Establish Certified Remanufacturing Programs | Addressing cost-sensitive aftermarket segments builds a circular economy model and extends product lifecycle. |
| Form Strategic OEM Partnerships | Continental AG positions itself as a system supplier, ensuring integration for major vehicle manufacturers. |
Research Approach
Direct dialogue with OEM platform engineers, Tier 1 procurement leads, aftermarket distributors, and regulatory affairs specialists informed primary data collection. This primary research complemented a robust secondary validation process, drawing from vehicle production databases, emissions standards documentation, and corporate financial filings. A combination of bottom-up data aggregation and top-down market sizing ensured comprehensive market understanding.
A bottom-up analytical lens, validated against top-down market estimations, formed the core of the forecast framework across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and regional production clusters. Compound Annual Growth Rates (CAGRs) were derived through regression analysis of historical trends and projected market dynamics. Commercial vehicle production forecasts and emissions regulation timelines served as key industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for powertrain electrification would alter the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement and economic stability. Rapid shifts in global trade policies or raw material availability represent significant risk factors. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Crate Engines Market
Powertrain
Engine Flush Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Automotive Engine Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Automotive Timing Chain and Belt Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
Carburetor Market
Powertrain
Automotive Fuel Injector Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Natural Gas Engines Market
Powertrain
Spark Plugs Market