
 Global Industrial Brakes and Clutches Market | 2026-2036
Global Industrial Brakes and Clutches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Brakes and Clutches Market Outlook
The EU Green Deal is repositioning industrial brake and clutch procurement across European manufacturing hubs, compelling suppliers to redesign for energy recovery and reduced friction losses. Eaton Corp. plc leverages its integrated electromechanical portfolio to capture retrofit demand from automotive OEMs transitioning assembly lines. Altra Industrial Motion Corp. anchors North American aftermarket channels through specialized service networks for heavy-duty clutches. Siemens AG differentiates via intelligent control systems that embed predictive wear algorithms into brake management architectures.
Industrial brakes and clutches are torque transmission and deceleration devices engineered with friction-lined plates, sintered metal composites, or electromagnetic actuation, typically rated for operating temperatures between 150°C and 350°C depending on duty cycle and application load. Their primary purpose is to control rotational motion in heavy machinery, ensuring precise stopping, holding, and speed modulation across automated production environments. Electromechanical technology leads product type demand as factories phase out pneumatic infrastructure for precision motion control, while intelligent control systems represent the fastest-expanding technology segment as AI-driven condition monitoring reduces unplanned downtime. The OEM end user channel commands the dominant margin pool due to long-term supply agreements and co-development contracts, though aftermarket providers sustain higher per-unit profitability on legacy equipment retrofits.
OSHA mandates in the United States enforce fail-safe brake performance standards for overhead cranes and material handling systems, directly shaping product certification requirements for exporters. REACH and RoHS frameworks in Europe restrict hazardous substances in friction materials, forcing reformulation of brake pad compositions and clutch facing chemistries. China's GB standards and MIIT directives on equipment energy efficiency create parallel compliance obligations for multinational suppliers operating across jurisdictions. Stakeholders must monitor regulatory divergence between these frameworks to avoid fragmented certification costs that erode cross-border manufacturing economics.
Market Dynamics
Electromechanical brake systems are compressing the installed base of pneumatic alternatives as precision motion control becomes non-negotiable in automated production lines. Heavy machinery OEMs in Germany and Japan are accelerating procurement of intelligent braking architectures that embed predictive algorithms directly into control systems.
Growth Catalysts
- EU Green Deal:REACH and RoHS frameworks compel reformulation of friction materials toward reduced hazardous substance content. Suppliers redesign clutch facings and brake pad chemistries to maintain European market access.
- China's eastern manufacturing corridor:Domestic automation upgrades in Jiangsu and Zhejiang provinces outpace regional peers, concentrating demand for high-duty-cycle brake systems in metalworking and robotics applications.
- Predictive wear monitoring:AI-driven condition monitoring algorithms embedded in brake management architectures reduce unplanned downtime. Automotive OEMs retrofit assembly lines with intelligent control systems to capture this operational efficiency.
Market Restraints
- Copper and rare-earth magnet cost volatility:Electromechanical brake architectures depend on copper windings and neodymium-based magnetic actuators. Input price swings compress margin stability for manufacturers without captive raw material sourcing.
- Supply concentration in sintered metal composites:Specialized friction material production clusters in Germany and Japan create geographic dependency. Disruption at these nodes propagates through global OEM supply chains.
- Thermal degradation ceiling:Organic friction materials face hard temperature limits around 350°C in continuous duty cycles. This technical boundary restricts deployment in steel mill and forging applications without liquid cooling augmentation.
Strategic Opportunities
- India's industrial automation buildout:PLI scheme incentives for machinery manufacturing create entry points for brake and clutch suppliers. Domestic automotive and textile equipment producers seek localized sourcing partnerships.
- Energy recovery integration:Regenerative braking architectures that capture deceleration energy align with MIIT efficiency directives in China and EPA industrial energy standards in the United States. Dual-technology clutch-brake units capture this white space.
- Aftermarket service unbundling:Specialized service networks for legacy heavy-duty clutch refurbishment outearn per-unit OEM margins. Independent distributors in North American mining and construction verticals exploit this channel innovation.
Industry Challenges
- Cross-jurisdiction certification complexity:OSHA crane brake mandates, REACH substance restrictions, and GB standards create parallel compliance obligations. Multinational suppliers fragment engineering resources to avoid exclusion from any major market.
- Legacy pneumatic infrastructure integration:Electromechanical brake retrofits demand control system re-architecture and operator retraining. Food processing and packaging OEMs delay upgrades due to production line disruption risk.
- Electromagnetic compatibility testing:Intelligent brake systems with embedded sensors must satisfy IEC and FCC emission standards. Extended validation timelines delay product launches in medical device and semiconductor handling equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Brakes and Clutches Market |
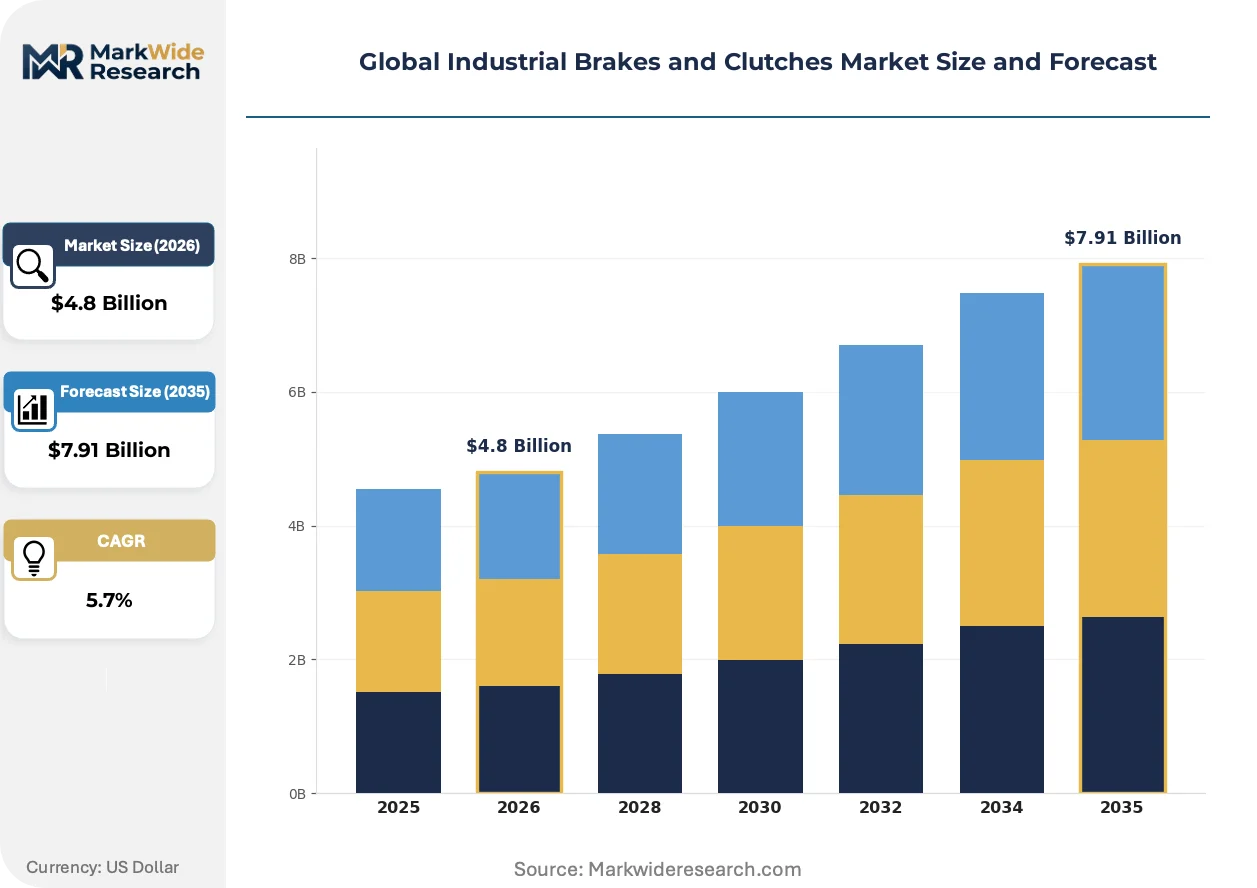
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Brakes, Hydraulic Brakes, Electric Clutches, Pneumatic Clutches Industry Vertical: Manufacturing, Aerospace, Automotive, Marine End User: OEMs, Aftermarket Providers, Service Centers, Maintenance Operators Technology: Electromechanical, Hydraulic, Pneumatic, Intelligent Control Systems |
| Companies Covered | Eaton Corp. plc, Altra Industrial Motion Corp., Siemens AG, Regal Rexnord Corporation, KEB Automation, Hilliard Corp., Dellner Bubenzer, Lenze SE, Kendrion N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Brakes and Clutches Market Strategic Shifts
Friction material science and control system architecture are converging to redefine performance benchmarks in torque transmission equipment. Three distinct vectors are compressing legacy technology lifecycles and rewiring competitive advantage.
Permanent magnet synchronous brake technology is overtaking wound-field electromagnetic alternatives in precision positioning applications. Semiconductor wafer handling equipment manufacturers in South Korea and Taiwan specify compact PM brake modules for sub-micron repeatability. This displacement is compressing supplier R&D cycles toward magnet array optimization and thermal management miniaturization.
REACH authorization procedures for chromium(VI) compounds in friction linings are forcing reformulation of high-temperature brake pad compositions. European clutch manufacturers accelerate ceramic matrix composite development to maintain temperature performance without restricted substances. Heavy machinery OEMs in Germany and Poland now require full material disclosure documentation as a procurement gate.
Buyer consolidation among automotive Tier-1 suppliers is compressing supplier qualification timelines and unbundling after-sales service contracts. Brake and clutch vendors face compressed pricing negotiation windows and must maintain regional spare parts inventories without guaranteed volume commitments. This pattern is most visible in Michigan and Stuttgart manufacturing corridors where assembly line uptime penalties have shifted risk allocation downstream.
Global Industrial Brakes and Clutches Market Segmentation
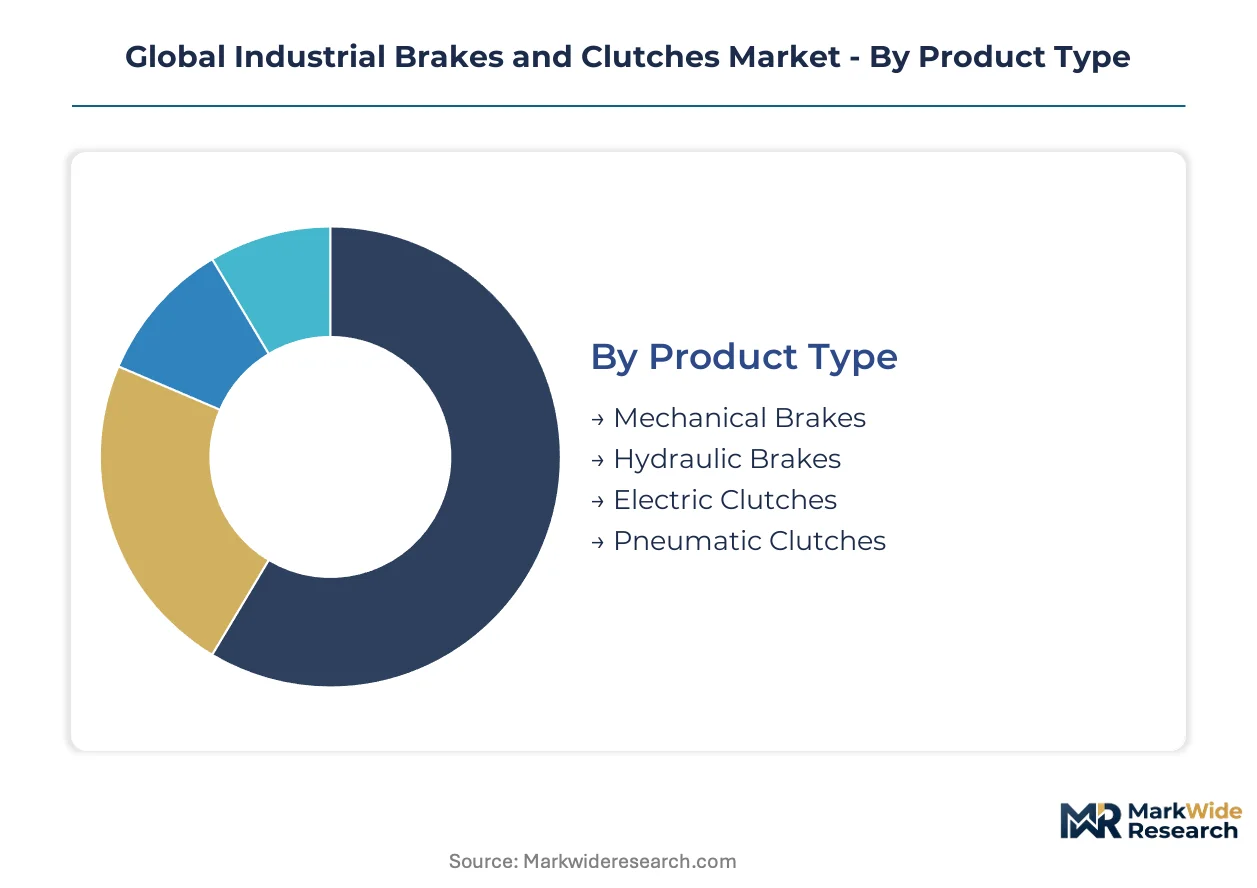
Industrial brake and clutch procurement patterns diverge sharply across product architectures and end-user channels. Capital allocation decisions, regulatory exposure, and technology refresh cycles create distinct margin profiles within each segment cluster.
Product Type:
Capital intensity varies dramatically across actuation technologies, with electromechanical architectures demanding the highest upfront tooling investment for precision magnet arrays and thermal management systems.
- Mechanical Brakes:Friction-lined plate assemblies using spring-applied, electrically released mechanisms dominate legacy infrastructure in steel mills and mining conveyors. German heavy machinery OEMs retain substantial installed bases despite accelerating replacement timelines.
- Hydraulic Brakes:Oil-pressurized piston systems deliver sustained torque across continuous duty cycles in port cranes and offshore winches. China's eastern manufacturing corridor concentrates procurement for new port automation projects along the Yangtze River Delta.
- Electric Clutches:Electromagnetic coil-and-friction-plate configurations enable rapid cycling in packaging machinery and textile looms. Japanese automation equipment manufacturers specify compact units for cleanroom semiconductor handling.
- Pneumatic Clutches:Compressed-air actuated systems persist in food processing environments where explosion-proof ratings exceed electromechanical alternatives. Midwest US meatpacking facilities delay replacement due to pneumatic infrastructure lock-in.
Mechanical brakes absorb the bulk of installed capacity; electric clutches are expanding most quickly as precision motion control becomes non-negotiable in automated production lines.
Industry Vertical:
Application severity and duty cycle requirements segment demand across torque transmission specifications, with aerospace and marine verticals imposing the most stringent certification burdens.
- Manufacturing:Metal stamping presses, robotic assembly arms, and conveyor systems constitute the volume anchor. Automotive OEMs in Michigan and Stuttgart manufacturing corridors specify intelligent brake architectures for predictive maintenance integration.
- Aerospace:Aircraft landing gear and thrust reverser systems demand fail-safe redundancy with sub-millisecond response times. FAA certification timelines extend product development cycles and compress supplier qualification windows.
- Automotive:Transmission clutch packs and electric vehicle regenerative braking systems are displacing traditional friction architectures. South Korean battery manufacturers specify compact electromechanical units for assembly line AGVs.
- Marine:Mooring winches and propulsion shaft brakes face salt corrosion and shock load requirements. Singapore shipyard retrofits concentrate demand for sealed hydraulic systems in container vessel upgrades.
Manufacturing commands the dominant revenue pool; aerospace maintains the steepest expansion trajectory as next-generation aircraft programs accelerate qualification cycles.
End User:
Customer type determines pricing power and contract structure, with OEMs extracting volume discounts through co-development agreements while aftermarket channels capture premium margins on legacy equipment.
- OEMs:Original equipment manufacturers lock in multi-year supply agreements with embedded engineering collaboration clauses. German automotive Tier-1 suppliers now require full material disclosure documentation as a procurement gate.
- Aftermarket Providers:Independent distributors stock refurbished clutch packs and brake pad inventories for mining and construction verticals. North American channel partners sustain higher per-unit profitability without guaranteed volume commitments.
- Service Centers:Authorized repair facilities perform warranty-backed installations with manufacturer technical support. Japanese industrial equipment makers restrict spare parts distribution to certified network members.
- Maintenance Operators:In-house plant engineering teams execute emergency replacements during scheduled downtime windows. Chinese state-owned steel enterprises maintain captive brake refurbishment shops to minimize procurement lead times.
OEMs anchor the volume base; aftermarket providers are gaining share fastest as equipment aging extends replacement demand beyond original design lifecycles.
Technology:
Control system sophistication segments supplier capabilities, with intelligent architectures requiring embedded software development resources that mechanical specialists cannot readily replicate.
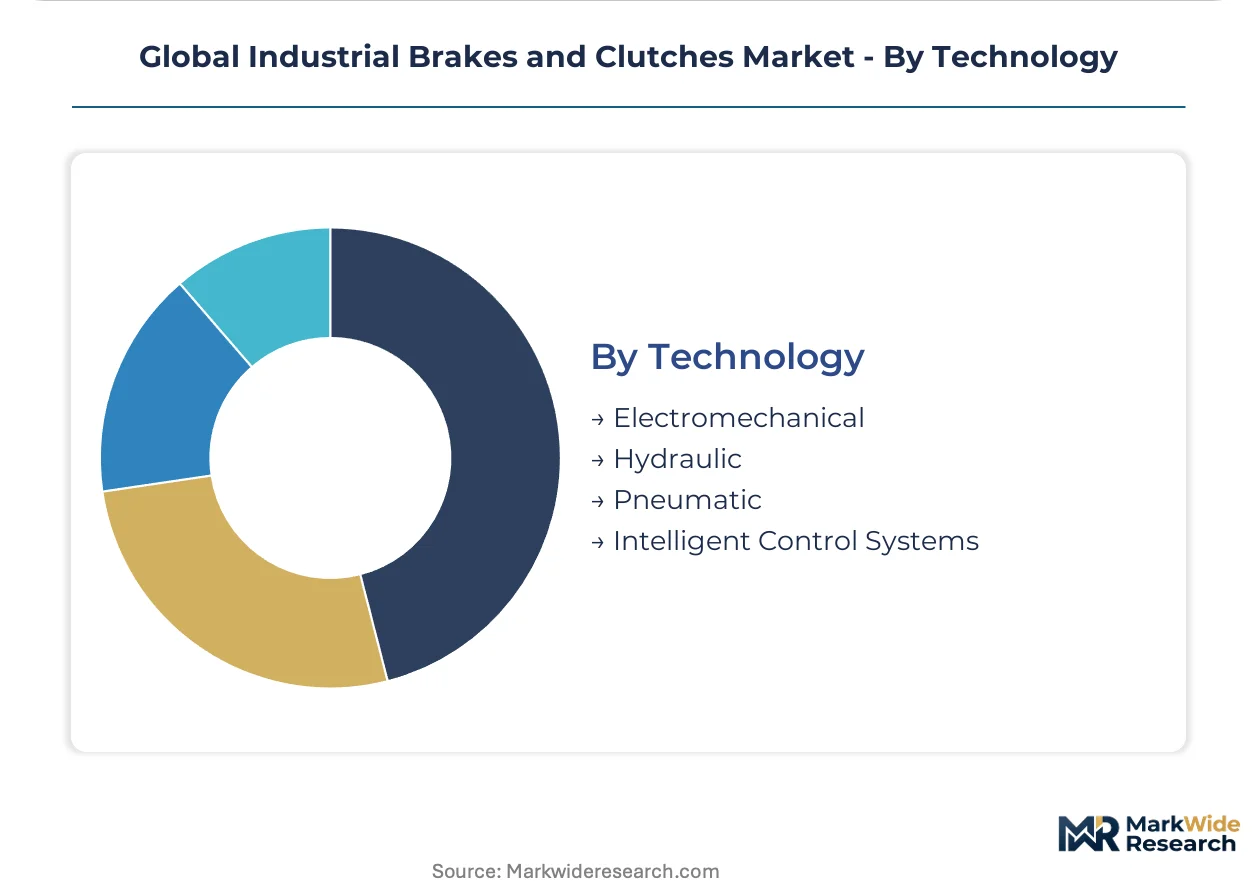
- Electromechanical:Servo-driven brake actuation eliminates pneumatic infrastructure dependencies while enabling programmable torque profiles. Taiwan semiconductor wafer handling equipment manufacturers specify compact modules for sub-micron repeatability.
- Hydraulic:Pressurized fluid systems maintain thermal stability in continuous high-load applications. REACH substance restrictions are forcing reformulation of hydraulic fluid compatibility with seal materials.
- Pneumatic:Compressed-air infrastructure persists where explosion-proof ratings or washdown requirements exceed electromechanical alternatives. OSHA crane brake mandates enforce fail-safe performance standards that pneumatic systems satisfy through mechanical spring defaults.
- Intelligent Control Systems:AI-driven condition monitoring algorithms embedded in brake management architectures reduce unplanned downtime. Automotive OEMs retrofit assembly lines with predictive wear monitoring to capture operational efficiency gains.
Electromechanical technology holds the dominant installed position; intelligent control systems are climbing the fastest as factories phase out pneumatic infrastructure for precision motion control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor procurement intensity as China's eastern manufacturing corridor outpaces regional peers in automation upgrades. Heavy machinery OEMs in Germany and Japan expand electromechanical brake procurement while the EU Green Deal repositions supplier priorities toward energy-efficient clutch designs.
China
MIIT directives on equipment energy efficiency drive demand for regenerative braking architectures in Jiangsu and Zhejiang provinces. GB standards create parallel compliance obligations for multinational suppliers operating in the Yangtze River Delta. Domestic automation upgrades concentrate procurement for high-duty-cycle brake systems in metalworking and robotics applications.
Germany
Heavy machinery OEMs in Baden-Württemberg and Bavaria accelerate procurement of intelligent braking architectures with embedded predictive algorithms. REACH authorization procedures for chromium(VI) compounds force reformulation of high-temperature brake pad compositions. German automotive Tier-1 suppliers now require full material disclosure documentation as a procurement gate.
United States
OSHA mandates enforce fail-safe brake performance standards for overhead cranes and material handling systems in Michigan manufacturing corridors. EPA industrial energy standards create demand for regenerative braking architectures that capture deceleration energy. Automotive OEMs in Detroit retrofit assembly lines with intelligent control systems to reduce unplanned downtime.
Japan
METI industrial efficiency programs accelerate replacement timelines for legacy pneumatic infrastructure in Kansai and Chubu manufacturing zones. JIS standards govern electromagnetic compatibility testing for intelligent brake systems with embedded sensors. Semiconductor wafer handling equipment manufacturers in Osaka specify compact permanent magnet brake modules for sub-micron repeatability.
India
PLI scheme incentives for machinery manufacturing create entry points for brake and clutch suppliers in Maharashtra and Gujarat. Domestic automotive and textile equipment producers seek localized sourcing partnerships to reduce procurement lead times. State-owned steel enterprises in Haryana maintain captive brake refurbishment shops to minimize supply chain disruption.
Global Industrial Brakes and Clutches Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with integrated electromechanical portfolios. Tier-1 automotive suppliers compress supplier qualification timelines and unbundle after-sales service contracts. Three archetypes dominate: integrated motion control specialists, friction material compounders, and regional aftermarket distributors. Consolidation through strategic partnerships and technology licensing reshapes supplier relationships as buyers demand embedded predictive maintenance capabilities.
Among diversified industrial conglomerates, Eaton Corp. plc and Siemens AG occupy positions as integrated motion control specialists with global aftermarket reach. Altra Industrial Motion Corp. exemplifies the North American aftermarket channel anchor, sustaining service networks for heavy-duty clutch refurbishment. KEB Automation and Kendrion N.V. represent European mid-cap specialists with concentrated expertise in electromagnetic actuation architectures. These players collectively illustrate how geographic origin and corporate structure map to competitive positioning across OEM supply agreements and independent distribution channels.
| Leading Market Players |
|---|
| Eaton Corp. plc |
| Altra Industrial Motion Corp. |
| Siemens AG |
| Regal Rexnord Corporation |
| KEB Automation |
| Hilliard Corp. |
| Dellner Bubenzer |
| Lenze SE |
| Kendrion N.V. |
| Others |
Value Chain & Pricing Dynamics
Performance-certification divergence between REACH-compliant electromechanical architectures and legacy pneumatic systems manifests in both margin structures and supplier qualification timelines. OEM procurement gates in Germany and Michigan now mandate full material disclosure documentation, compressing pricing power for non-compliant friction material compounders while elevating premium tiers for ceramic matrix composite suppliers.
Pricing Analysis
Value-based pricing anchored to assembly line uptime guarantees dominates automotive OEM contracts, with predictive wear algorithms commanding per-unit premiums over standard electromechanical alternatives. Price differentiation stems from certification grade (REACH/RoHS compliance tier) and volume scale (multi-year co-development agreements versus spot aftermarket purchases). Cost compression in standard mechanical brake tiers is intensifying because copper and rare-earth magnet input volatility erodes margin stability for manufacturers without captive raw material sourcing. Aftermarket providers exhibit lowest price sensitivity due to emergency replacement demand during unplanned downtime windows.
Supply Chain Analysis
Copper winding and neodymium magnet supply rests on Chinese rare-earth processing clusters and Chilean copper concentrate exports. Specialized friction material production draws from German sintered metal composite facilities and Japanese ceramic matrix development centers. Single-source vulnerability concentrates in neodymium magnet refining, where geographic concentration propagates disruption through global OEM supply chains. Distribution runs through authorized service networks for OEM channel fulfillment and independent distributors for aftermarket refurbishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical brake architectures are displacing pneumatic infrastructure across automated production lines, compressing technology lifecycles and rewiring supplier competitive positions. This transition phase demands distinct strategic postures from incumbents, new entrants, and capital allocators.
For Market Incumbents: Extend predictive maintenance software capabilities through embedded AI-driven condition monitoring to defend against intelligent control system specialists entering from adjacent automation sectors. Deepen backward integration into copper winding production and rare-earth magnet sourcing to insulate margin stability from input price volatility. Prioritize REACH certification investment for ceramic matrix composite formulations to maintain European market access as authorization procedures tighten. For New Entrants and Emerging Players: Intelligent control system modules represent the most penetrable white space, as legacy mechanical specialists lack embedded software development resources to replicate predictive wear algorithms. Target India's PLI scheme machinery manufacturing incentives in Maharashtra and Gujarat for localized sourcing partnerships with domestic automotive and textile equipment producers. Pursue joint development agreements with semiconductor wafer handling equipment manufacturers in Taiwan and South Korea seeking sub-micron repeatability specifications. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial conglomerates seeking integrated electromechanical portfolios. Long-term viability favors suppliers with captive friction material formulation capabilities and embedded software architectures rather than pure mechanical component manufacturers. Watch for MIIT energy efficiency directive enforcement intensity in China's eastern manufacturing corridor as inflection indicator for regenerative braking architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Sourcing | Captive neodymium supply insulates margin stability from Chinese export quota volatility. |
| Ceramic Matrix Composite Formulation Investment | REACH-compliant high-temperature friction materials maintain European automotive OEM access. |
| Predictive Maintenance Software Development | Embedded AI algorithms reduce unplanned downtime for Michigan automotive assembly lines. |
| India PLI Scheme Localization Partnership | Maharashtra machinery manufacturing incentives create entry points for brake system suppliers. |
| Regenerative Braking Architecture Integration | Energy recovery systems align with MIIT efficiency directives in Jiangsu and Zhejiang provinces. |
Study Parameters
Document review covered customs and trade data, SEC 10-K filings from diversified industrial conglomerates, and MIIT equipment efficiency directive publications, complemented by interviews with maintenance directors at German heavy machinery OEMs, plant engineers in China's eastern manufacturing corridor, aftermarket service heads at North American mining distributors, and OEM procurement teams in Michigan automotive corridors. Bottom-up demand modeling triangulated against top-down industrial automation capex forecasts validated secondary projections.
Cross-reference between historical electromechanical adoption curves and panel input from brake system engineering directors shaped the analytical framework across the analysis window. Segmentation dimensions modeled include actuation technology, industry vertical severity tier, end-user channel structure, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and automation upgrade intensity indices, with specific inputs from semiconductor wafer handling equipment specification trends and port crane modernization timelines.
Several conditions sit outside the modeled scope, including abrupt rare-earth export restrictions, sudden REACH substance list expansion, and unanticipated pneumatic infrastructure lifespan extension in food processing verticals. Forecasts reflect documented assumptions regarding copper price stability and OEM co-development contract renewal rates. A small set of named triggers warrants ongoing watch: MIIT enforcement patterns, German automotive Tier-1 supplier consolidation velocity, and JIS electromagnetic compatibility standard revision timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Transmission Mounting Brackets Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Gasoline Turbochargers Market
Powertrain
Gear Oil Market
Powertrain
Turbocharger Market
Powertrain
Truck Auxiliary Power Units Market
Powertrain
Brazil Automotive Actuators Market
Powertrain
Mechanical Reciprocating Engine Market
Powertrain
EV Drivetrain Systems Market
Powertrain
Automotive Oil Sump Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Power Steering Filter Market
Powertrain
Turbocharger Actuators Market
Powertrain
Axle Shaft Market