
 Carburetor Market | 2026-2036
Carburetor Market Size, Share, and Industry Trends Forecast 2026-2036
Carburetor Market Analysis
Asset-light leasing models for precision machining equipment is fragmenting competitive barriers across the carburetor supply base. Holley leverages its brand strength in performance aftermarket channels to sustain premium positioning. Keihin Group anchors production scale across motorcycle OEM supply chains in Asia. Mikuni specializes in small-engine carburetion for powersports and marine applications.
A carburetor is a mechanical device that blends air and fuel in precise stoichiometric ratios for internal combustion engines, typically operating at venturi pressures between 0.3 and 0.7 bar to draw fuel through calibrated jets. Its primary commercial purpose is to deliver metered combustible mixtures without electronic control systems, serving engines where cost simplicity or legacy compatibility outweighs fuel-injection precision. Multiple barrel configurations lead the product type landscape by volume, reflecting V-twin and multi-cylinder engine architectures in automotive and marine end uses. Ethanol-compatible fuel type segments represent the fastest-growing configuration category, as flex-fuel standards proliferate across Brazil and North American small-engine markets. Direct fit installation types command margin concentration due to OEM certification requirements and warranty alignment.
The US EPA sets evaporative emission limits that constrain carburetor design through permeability standards and diurnal breathing loss thresholds, while California's Air Resources Board imposes additional small-engine criteria that manufacturers must navigate for coastal state market access. India's BIS enforces Bharat Stage emission norms that progressively restrict carbureted two-wheeler sales in urban corridors. Brazil's PROCONVE framework maintains distinct flex-fuel carburetion standards that preserve ethanol-blend compatibility requirements. Stakeholders must monitor regulatory divergence between emerging market phase-out timelines and developed market classic-vehicle exemptions that sustain aftermarket demand pools.
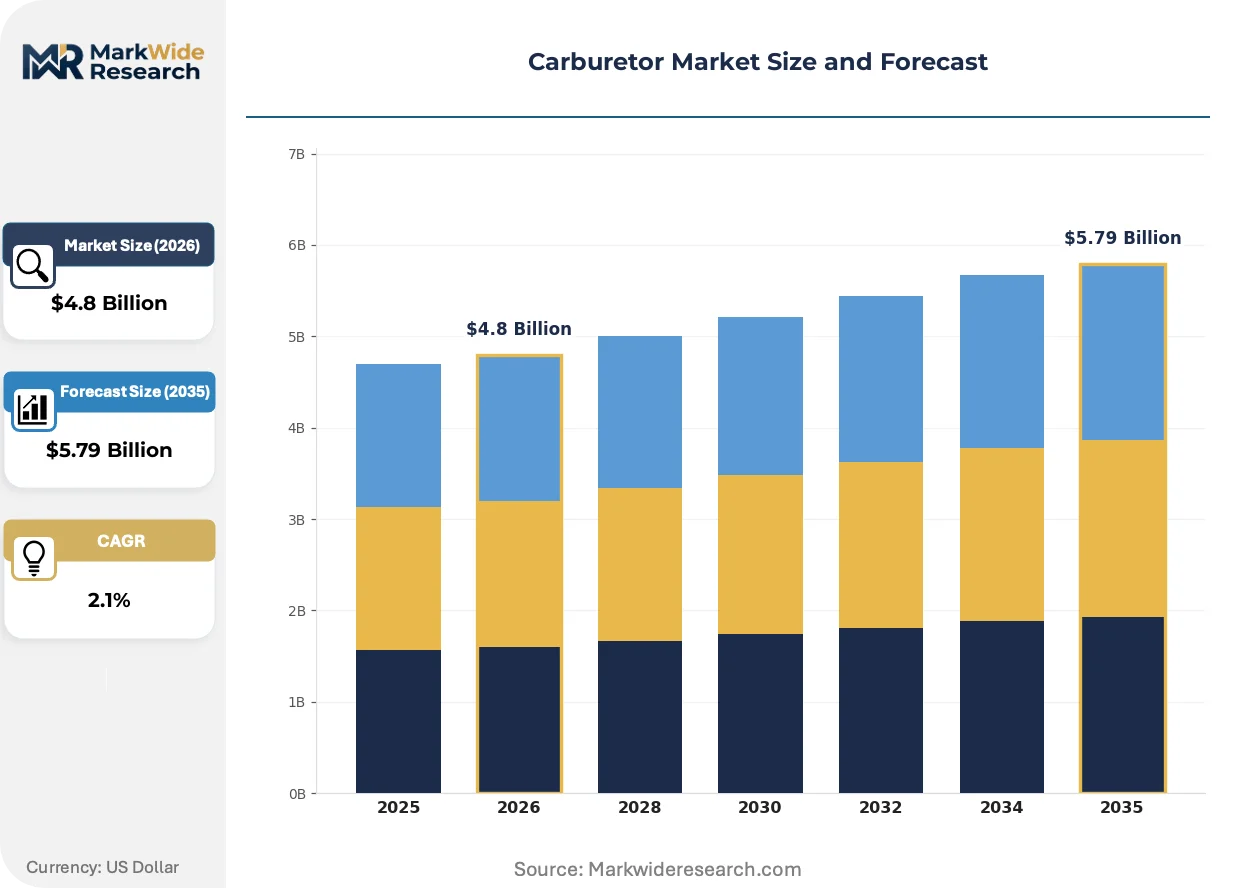
Market Dynamics
Emission phase-out timelines in India and Brazil are compressing carburetor demand into aftermarket channels while flex-fuel compatibility requirements reshape product specifications across Latin American small-engine supply chains.
Growth Catalysts
- Brazil PROCONVE Flex-Fuel Mandates:Ethanol-blend compatibility requirements preserve carburetor relevance in small-engine and motorcycle applications where electronic fuel injection remains cost-prohibitive.
- Southeast Asia Motorcycle Aftermarket:India's BIS Bharat Stage norms tighten urban sales restrictions, diverting carburetor demand toward rural replacement cycles and cross-border secondary markets.
- Marine and Powersports Persistence:Carbureted outboard motors and recreational vehicles sustain production volumes where salt-water corrosion resistance favors mechanical fuel systems over electronic alternatives.
Market Restraints
- Aluminum Alloy Price Volatility:Die-cast carburetor body production faces margin compression from fluctuating secondary aluminum ingot costs across Asian foundry clusters.
- Electronic Fuel Injection Substitution:Low-cost EFI modules from Chinese suppliers undercut carburetor price positioning in sub-150cc motorcycle segments.
- India BIS Urban Sales Bans:Progressive Bharat Stage VI restrictions eliminate original-equipment carburetor placements in metropolitan two-wheeler registrations.
Strategic Opportunities
- Vietnam and Indonesia Rural Motorization:Unregulated secondary markets in Mekong Delta and Sumatran provinces absorb Indian surplus carburetor inventory through informal distribution networks.
- Ethanol-Resistant Elastomer Retrofit Kits:Replacement seal and diaphragm packages address compatibility gaps in legacy small-engine installations across Brazilian agricultural equipment.
- Asset-Light Precision Machining Leasing:Contract manufacturing models lower entry barriers for regional suppliers serving fragmented powersports aftermarket channels.
Industry Challenges
- Venturi Calibration Technician Scarcity:Specialized airflow bench operation and jetting expertise retires faster than vocational programs replenish qualified labor pools.
- Homologation Timeline Compression:Multi-jurisdiction emission certification cycles for ethanol-tolerant configurations strain product development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carburetor Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Barrel, Dual Barrel, Multiple Barrel, Adjustable Installation Type: Direct Fit, Universal Fit, Custom Fit, OEM End User: Automotive, Motorcycles, Small Engines, Marine Fuel Type: Gasoline, Ethanol, Methanol, LPG |
| Companies Covered | Zama, Holley, Keihin Group, Fuding Huayi, Edelbrock, Mikuni, Dell'Orto, Ruixing, Walbro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carburetor Market Emerging Trajectories
Mechanical fuel-metering architectures face systematic replacement pressure from electronic alternatives, yet material science advances and regulatory grandfathering provisions create sustained niche demand pockets.
Variable-venturi carburetor designs incorporating polymer composite throttle bodies are rendering obsolete traditional zinc-alloy castings in marine salt-water environments. Outboard motor manufacturers in Florida and Queensland specify these configurations for corrosion resistance. The shift compresses foundry order books while elevating precision injection-molding capacity requirements across Southeast Asian tier-two suppliers.
California's Air Resources Board small-engine evaporative emission standards impose permeability thresholds that force diaphragm material transitions from nitrile rubber to fluorocarbon elastomers. Landscape equipment OEMs serving coastal US states must redesign fuel circuits or forfeit market access. Compliance investments concentrate among carburetor specialists with captive polymer compounding capabilities.
Aftermarket distributors in India's Tier-2 and Tier-3 cities unbundle carburetor sales from authorized service networks, establishing direct procurement relationships with Indonesian and Thai component manufacturers. Independent motorcycle repair shops in Lucknow and Indore now source jets and needle valves through cross-border B2B platforms. Channel disintermediation erodes traditional OEM parts margins while expanding addressable volume for unbranded precision-machined alternatives.
Carburetor Market Segmentation
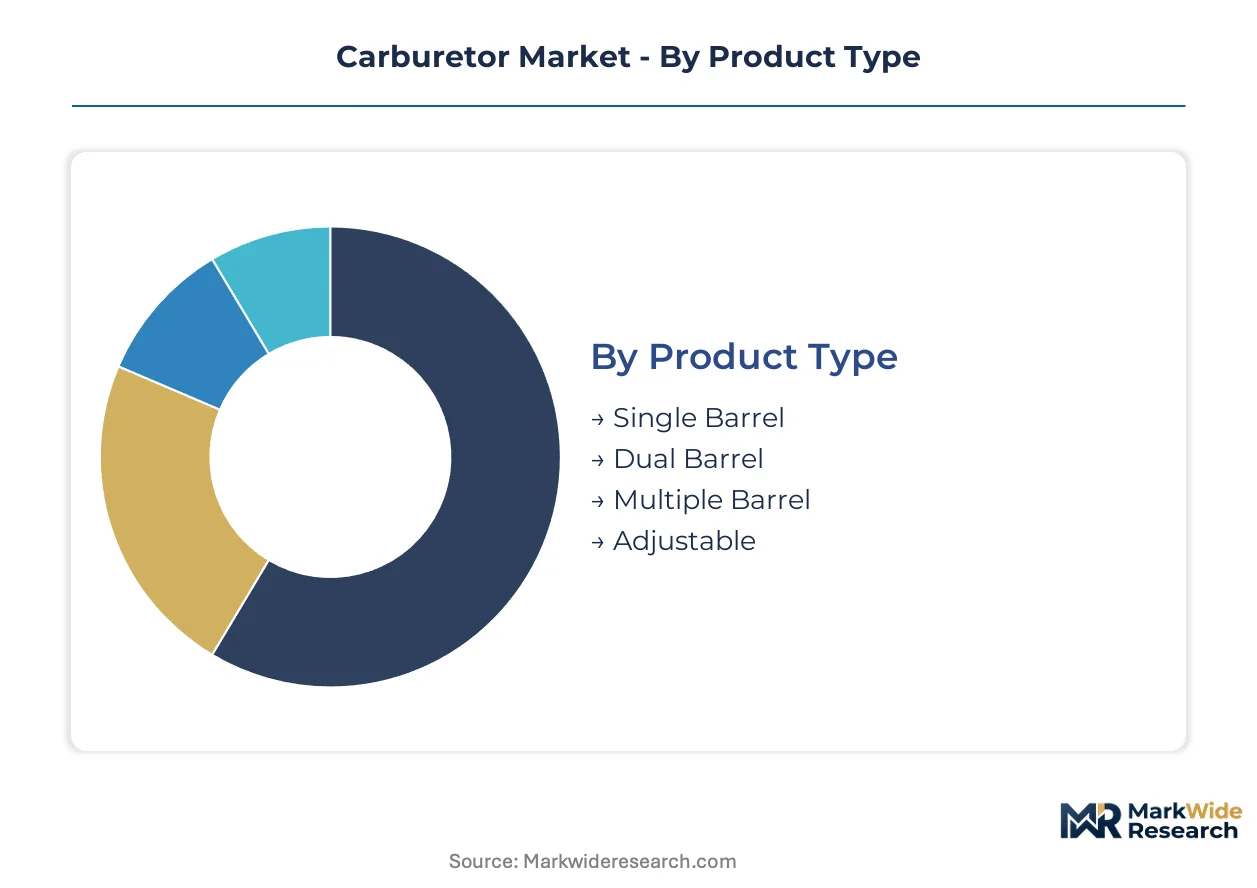
Carburetor market segmentation reveals divergent replacement cycles across product architectures, with precision-tuned OEM installations lasting years while universal aftermarket units turn over rapidly. Installation protocols and fuel compatibility requirements further stratify margin structures and technical barriers to entry.
Product Type:
Replacement velocity varies dramatically across barrel configurations, with single-barrel units cycling fastest in small-engine fleets while multi-barrel systems endure across marine and performance automotive applications.
- Single Barrel:Simple venturi architecture with one fuel discharge point serves sub-200cc engines and basic landscaping equipment. Demand concentrates in Brazilian agricultural machinery where cost minimization outweighs fuel efficiency optimization.
- Dual Barrel:Staged primary-secondary venturi arrangement enables part-throttle economy and full-power enrichment. Powersports manufacturers in Japan specify these configurations for mid-displacement motorcycles balancing urban commuting with highway capability.
- Multiple Barrel:Multi-venturi assemblies meter fuel through independent barrels synchronized to engine load ranges. V-twin motorcycle OEMs and marine outboard producers leverage this architecture for torque-band flexibility across RPM ranges.
- Adjustable:Variable-jet mechanisms permit field calibration without component replacement. Aftermarket distributors in Southeast Asia stock these for unregulated secondary markets where service infrastructure remains sparse.
Multiple barrel configurations anchor the volume base while adjustable units gain share at the steepest rate.
Installation Type:
Margin concentration tracks certification burden, with factory-authorized placements commanding premium pricing against price-compressed universal alternatives.
- Direct Fit:Application-specific castings align with OEM intake manifolds and emission control hardware. India's BIS-certified two-wheeler manufacturers require these configurations for warranty compliance in Bharat Stage regulated corridors.
- Universal Fit:Adaptable mounting interfaces accommodate multiple engine families through interchangeable linkage kits. Independent repair shops in Indonesia favor these for cost-sensitive rural motorization where formal dealer networks do not reach.
- Custom Fit:Bespoke venturi profiling and throttle bore machining address racing and restoration applications. California's Air Resources Board exempts these from evaporative emission standards when installed on pre-regulation vehicle chassis.
- OEM:Original equipment placements integrate with engine management calibration and durability testing protocols. Marine engine builders in Florida specify OEM carburetors for salt-water corrosion resistance validation.
OEM installations anchor the volume base while custom fit configurations climb the fastest on restoration and racing demand.
End User:
Application durability requirements shape material selection and replacement frequency, with salt-water marine environments demanding corrosion-resistant alloys against dry-climate automotive tolerances.
- Automotive:Classic vehicle restoration and developing-market legacy fleets sustain demand where electronic fuel injection retrofit costs prove prohibitive. Brazil's PROCONVE flex-fuel standards preserve carbureted configurations in entry-level passenger vehicles.
- Motorcycles:Two-wheeler OEM supply chains in India and Southeast Asia represent the largest volume concentration. BIS Bharat Stage VI urban sales restrictions divert carburetor placements toward rural replacement cycles and export markets.
- Small Engines:Landscaping, agriculture, and portable power equipment rely on mechanical fuel metering for field-service simplicity. Ethanol-blend compatibility requirements across Brazilian agricultural equipment accelerate seal and diaphragm retrofit demand.
- Marine:Outboard motors and inboard auxiliary engines favor carbureted fuel systems for salt-water corrosion resistance. Queensland and Florida boatbuilders specify polymer-composite throttle bodies over zinc-alloy castings for extended service intervals.
Motorcycle applications anchor the volume base while marine end uses expand most quickly on corrosion-resistant material transitions.
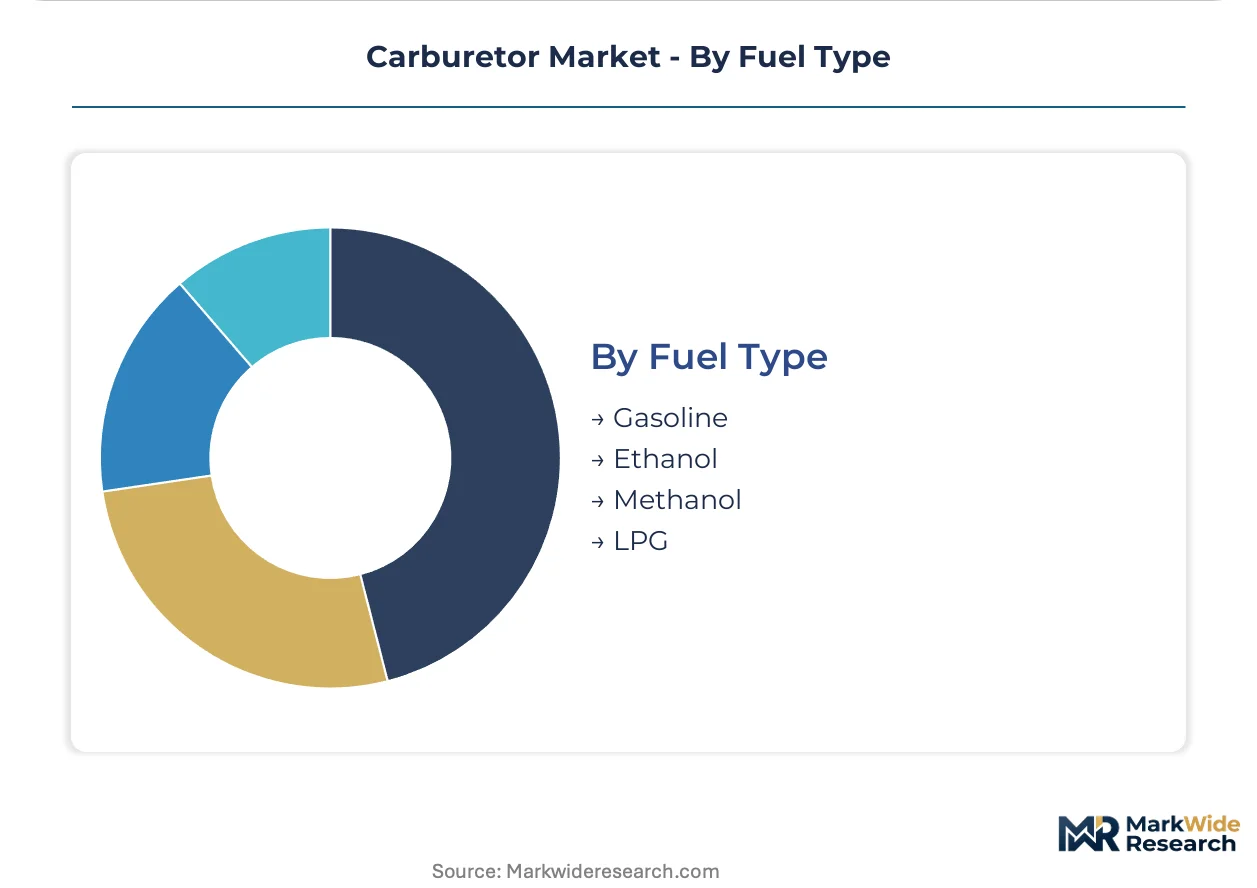
Fuel Type:
Compatibility specifications diverge across regional energy policies, with ethanol-tolerant configurations gaining regulatory preference in biofuel-mandated jurisdictions against gasoline-optimized legacy stock.
- Gasoline:Conventional hydrocarbon formulations remain standard for classic vehicle preservation and regions without biofuel mandates. Restoration specialists in North America and Europe specify these for period-correct engine calibration.
- Ethanol:Flex-fuel carburetors accommodate variable ethanol-gasoline blends through corrosion-resistant fuel circuits and recalibrated air-fuel ratios. Brazil's PROCONVE framework mandates these configurations for domestic small-engine and motorcycle production.
- Methanol:High-octane racing formulations require enlarged fuel jets and alcohol-compatible elastomers. Drag racing and oval track sanctioning bodies in the United States specify these for forced-induction engine applications.
- LPG:Liquefied petroleum gas conversions utilize pressure-regulated vaporizer-mixer assemblies adapted from gasoline carburetor architectures. Fleet operators in India and Turkey deploy these for fuel cost arbitrage against pump gasoline pricing.
Gasoline configurations anchor the volume base while ethanol-compatible segments gain share at the steepest rate on flex-fuel mandate proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across carburetor supply chains, with surplus production in Asian manufacturing clusters offsetting deficit regions in North America and Europe where legacy demand outpaces domestic fabrication capacity.
United States
Classic vehicle restoration and marine outboard replacement cycles sustain import dependence for multi-barrel and corrosion-resistant configurations. The EPA's evaporative emission standards constrain permissible designs for small-engine applications, while California's Air Resources Board imposes additional permeability thresholds. Florida boatbuilders concentrate demand for polymer-composite throttle bodies specified for salt-water service intervals.
Brazil
Domestic flex-fuel mandate compliance preserves carburetor relevance in agricultural machinery and entry-level motorcycles where electronic fuel injection costs remain prohibitive. The PROCONVE framework mandates ethanol-blend compatibility across small-engine production, creating specification divergence from gasoline-optimized export markets. São Paulo state foundries and precision-machining clusters anchor ethanol-tolerant configuration fabrication for Latin American supply chains.
India
BIS Bharat Stage VI urban sales restrictions eliminate original-equipment placements in metropolitan two-wheeler registrations, diverting carburetor demand toward rural replacement cycles and informal export channels. The BIS emission norms tighten progressively across urban corridors. Gujarat and Tamil Nadu manufacturing belts absorb displaced production capacity through cross-border secondary market shipments to Southeast Asia.
Japan
Mid-displacement motorcycle OEM supply chains sustain precision-tuned dual-barrel fabrication for domestic and export assembly. METI industrial standards govern component durability testing protocols. Chubu region carburetor specialists maintain technical heritage in venturi calibration expertise increasingly scarce across global supplier bases.
Indonesia
Unregulated rural motorization in Sumatran provinces and Eastern islands absorbs surplus inventory from Indian and Thai manufacturing through informal distribution networks. The country's national emission regulator has not implemented equivalent urban sales restrictions to India's BIS framework. Jababeka industrial estate outside Jakarta hosts assembly operations serving replacement demand across the archipelago's fragmented service infrastructure.
Carburetor Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical heritage. The vendor base distributes across consolidated OEM supply relationships and fragmented aftermarket channels with divergent margin structures. Three archetypes dominate: heritage brands with performance aftermarket positioning, scale-oriented motorcycle OEM suppliers, and precision-machining contract manufacturers serving unbranded replacement demand. Competitive moves concentrate on geographic expansion into regulatory arbitrage corridors and portfolio diversification toward ethanol-compatible material specifications.
Among heritage-positioned specialists, Holley and Edelbrock occupy positions in North American performance and restoration channels where brand equity sustains premium pricing. Keihin Group and Mikuni anchor the OEM-integrated tier with established supply relationships across Asian motorcycle and powersports production. Zama represents the precision-component archetype with manufacturing heritage in small-engine carburetion for global landscaping equipment brands.
| Leading Market Players |
|---|
| Zama |
| Holley |
| Keihin Group |
| Fuding Huayi |
| Edelbrock |
| Mikuni |
| Dell'Orto |
| Ruixing |
| Walbro |
| Others |
Supply Flow & Price Mechanics
Gujarat and Tamil Nadu manufacturing belts concentrate carburetor fabrication capacity, and their export-oriented production dynamics translate into pricing leverage over Southeast Asian aftermarket distributors. Die-cast aluminum body costs and precision-machining labor rates in these clusters set floor pricing for global small-engine supply chains.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across motorcycle and marine engine supply chains. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified direct-fit configurations from universal aftermarket alternatives. Cost compression in economy-tier universal units is intensifying because Chinese EFI module suppliers undercut mechanical fuel-metering price points. Rural independent repair shops in Indonesia and Vietnam exhibit highest price sensitivity; Florida marine OEMs demonstrate lowest sensitivity due to corrosion-resistance certification requirements.
Supply Chain Analysis
Tariff exposure between India and Indonesia dominates supply chain risk calculations for carburetor distributors serving unregulated Southeast Asian secondary markets. Fabrication concentrates in India, Thailand, and Brazil, with secondary aluminum ingot, fluorocarbon elastomer diaphragms, and polymer composite throttle bodies as critical input dependencies. Single-source vulnerability in venturi calibration technician pools threatens production continuity. Distribution runs through authorized OEM parts networks and informal cross-border B2B platforms serving independent repair channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated powersports OEMs and fragmented rural repair networks, with the latter's disintermediation of authorized service channels eroding traditional margin structures.
For Market Incumbents: Entrench ethanol-compatible material capabilities to defend against PROCONVE regulatory displacement in Brazil. Deepen backward integration into fluorocarbon elastomer compounding to capture California Air Resources Board compliance premiums. Channel control through captive distribution in Indian Tier-2 cities counters informal cross-border procurement erosion.
For New Entrants and Emerging Players: Establish a beachhead in Indonesian rural motorization corridors where national emission regulators have not implemented urban sales restrictions. Target ethanol-resistant retrofit kit segments for Brazilian agricultural equipment where legacy fleet maintenance outpaces OEM replacement cycles. Go-to-market leverage rests on direct B2B platform relationships with Sumatran and Mekong Delta repair shops.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because emission phase-out timelines diverge sharply between Indian urban corridors and Southeast Asian unregulated zones. Acquisition targets should display precision-machining heritage with captive polymer compounding capabilities. The signal to watch is Bharat Stage VI enforcement intensity across Indian Tier-3 cities.
| Strategic Initiative | Industry Significance |
|---|---|
| Ethanol-Compatible Material Transition | PROCONVE flex-fuel mandates in Brazil preserve relevance against EFI substitution. |
| Precision Machining Leasing Models | Asset-light fabrication lowers entry barriers for regional powersports aftermarket suppliers. |
| Direct B2B Platform Expansion | Cross-border procurement relationships with Indonesian repair shops disintermediate OEM parts networks. |
| Fluorocarbon Elastomer Investment | California Air Resources Board permeability thresholds force diaphragm material upgrades. |
| Rural Distribution Network Control | Lucknow and Indore independent shops source through informal channels eroding authorized margins. |
Methodological Framework
Desk research of customs trade databases, BIS emission filings, and PROCONVE regulatory archives preceded structured interviews with carburetor procurement managers at powersports OEMs, precision-machining plant engineers, aftermarket distributors in Gujarat and Tamil Nadu, and venturi calibration technicians. Secondary validation drew from EPA evaporative emission standards documentation and California Air Resources Board small-engine criteria. Bottom-up volume builds across barrel configurations and fuel compatibility segments were triangulated against top-down market sizing.
Assumptions held fixed include current BIS Bharat Stage VI urban enforcement boundaries and PROCONVE ethanol-blend mandate continuity; variables tested included EFI cost curve acceleration and aluminum alloy price volatility. The analytical framework modeled product type, installation protocol, end-use application, fuel compatibility, and regional regulatory cluster across the projection horizon. CAGRs were derived from segment-level replacement cycle analysis and export-import flow trajectories. Industry-specific inputs incorporated marine salt-water corrosion resistance specifications and small-engine field-service simplicity requirements.
Stress conditions across aluminum ingot pricing bands, Bharat Stage enforcement intensity, and Chinese EFI module penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory grandfathering provisions and classic-vehicle exemption durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Automotive Driveshaft Couplings Market
Powertrain
Automotive Fuel Pulsation Damper Market
Powertrain
Automotive Tuner Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Gear Oil Market
Powertrain
Crankshaft Position Sensor Market
Powertrain
Mexico Electrically Powered Hydraulic Steering Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Global Automotive Tappet Market
Powertrain
Automotive Drivetrain Market
Powertrain
South America Automotive Market
Powertrain
Japan Electrically Powered Hydraulic Steering Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Gear Reduction Starter Market