
 Electric AC Motors Market | 2026-2036
Electric AC Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Electric AC Motors Market Analysis
Permanent magnet synchronous motor integration is reconfiguring how OEMs design high-efficiency drivetrains for industrial equipment. ABB leverages its European manufacturing footprint to anchor premium servo motor supply for precision automation. Siemens competes through digital twin integration that extends hardware value into predictive maintenance services. WEG dominates Latin American infrastructure projects with localized three-phase induction motor production.
Electric AC motors convert alternating current electrical energy into mechanical rotation through electromagnetic induction, typically operating at speeds governed by supply frequency and pole count with efficiency ratings spanning IE1 through IE4 under IEC 60034 standards. Three-phase induction motors occupy the largest installed base across heavy manufacturing due to rugged construction and minimal maintenance requirements, while variable frequency drive pairings represent the fastest-growing technology segment as facilities retrofit existing fixed-speed pump and fan systems for energy recovery. Synchronous motors with integrated permanent magnet rotors concentrate margin pools in precision positioning applications where servo control delivers sub-arcminute accuracy.
The US Department of Energy enforces minimum efficiency standards under 10 CFR 431 that phase out IE2-equivalent motors above one horsepower, while the EU Ecodesign Directive and F-Gas Regulation indirectly accelerate motor upgrades by linking compressor and HVAC system efficiency to climate targets. China's GB 18613 standard mandates IE3 minimum efficiency for industrial motors, tightening market access for non-compliant imports. Stakeholders must monitor how regional efficiency tier convergence affects sourcing strategies and inventory segmentation across multinational manufacturing networks.
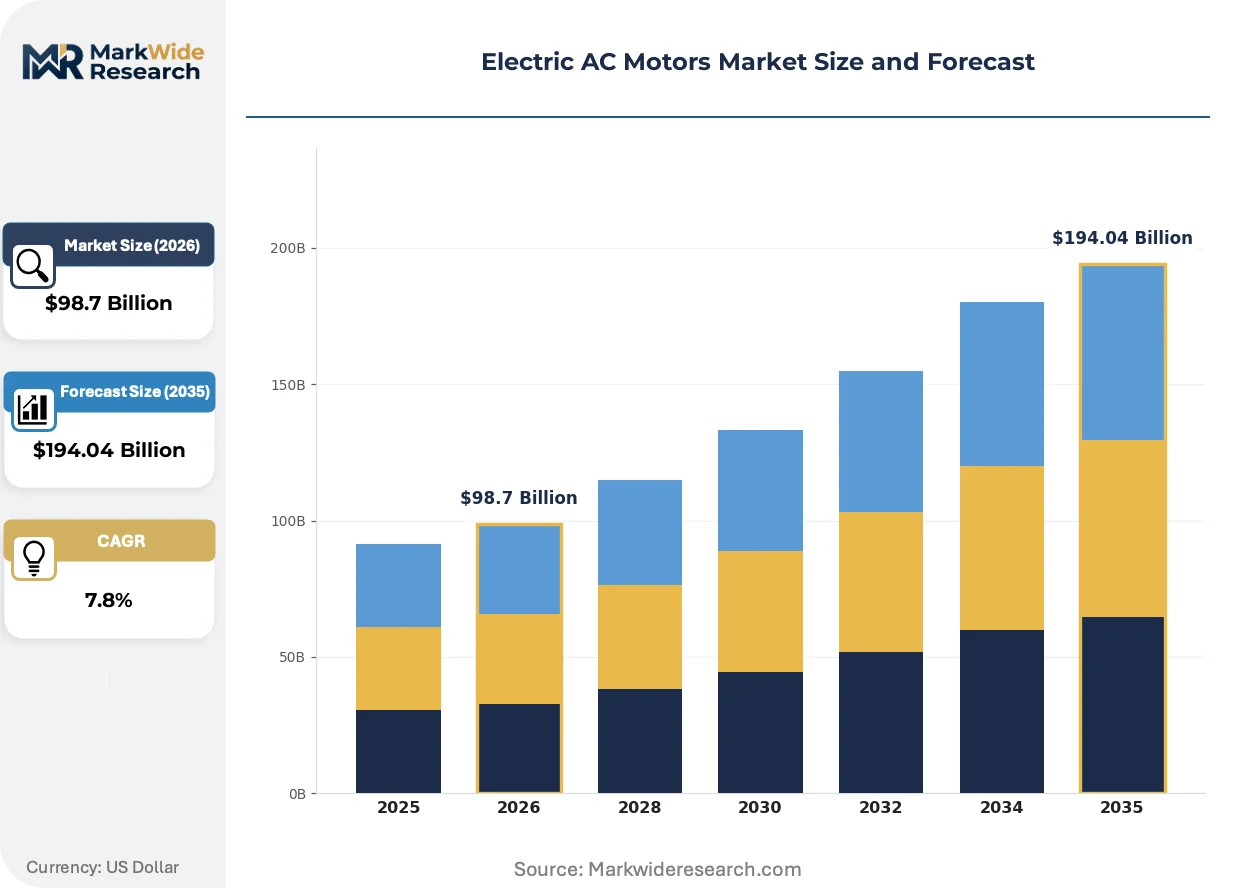
Market Dynamics
IE3 and IE4 efficiency mandates are compressing the addressable market for legacy induction motor architectures while permanent magnet synchronous designs capture margin in precision positioning applications.
Growth Catalysts
- US DOE 10 CFR 431 Phase-Out:Federal efficiency standards are removing IE2-equivalent motors above one horsepower from commercial circulation, forcing replacement demand across industrial facilities.
- Automotive Manufacturing Automation:Battery assembly lines and EV powertrain production are absorbing high-torque servo motors for robotic welding and precision component placement.
- Variable Frequency Drive Retrofits:Fixed-speed pump and fan systems are pairing with VFDs to recover energy, extending motor lifecycle value in process industries.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium refining concentrates in China's Inner Mongolia processing corridor, creating geopolitical exposure for permanent magnet rotor production.
- Copper Price Volatility:Stator winding costs fluctuate with London Metal Exchange copper futures, compressing margins on standard induction motor lines.
- Technical Limitation in High-Temperature Environments:Permanent magnet demagnetization above 150°C restricts synchronous motor deployment in steel mill and glass furnace applications.
Strategic Opportunities
- India PLI Scheme for Manufacturing:Production-linked incentives for industrial automation equipment are attracting motor assembly investments in Gujarat and Tamil Nadu corridors.
- Hydrogen Compressor Integration:Electrolyzer systems require explosion-proof motors for high-pressure gas handling, opening specialized product lines.
- Digital Twin Convergence:Physics-based motor modeling combined with edge computing enables predictive bearing failure detection as a service layer.
Industry Challenges
- IE4 Certification Timeline Compression:Third-party testing backlogs at IEC-accredited laboratories are extending product launch cycles for premium efficiency tiers.
- Legacy System Integration Friction:Retrofitting servo motors into mechanical cam-driven assembly lines requires custom mechanical adapters and control architecture overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric AC Motors Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $194.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-phase Motors, Three-phase Motors, Synchronous Motors, Induction Motors End User: Manufacturing, HVAC, Automotive, Agriculture Application: Pumps, Fans, Compressors, Conveyors Technology: Variable Frequency Drive, Direct Online, Soft Starter, Servo Control |
| Companies Covered | ABB, Siemens, Nidec Corporation, Rockwell Automation, Emerson Electric Co., Johnson Electric Holdings Limited, Toshiba Corporation, WEG, AMETEK, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric AC Motors Market Emerging Trajectories
Magnet material science and embedded sensor architectures are redefining how motor performance is validated, monetized, and maintained across industrial asset bases.
Axial flux motor topologies are migrating from aerospace auxiliary power units into commercial EV traction applications. Commercial vehicle OEMs in Germany and the Netherlands are piloting compact wheel-hub integrations that eliminate transmission losses. This topology compression enables direct-drive architectures that remove gearbox maintenance burden from fleet operators.
The EU F-Gas Regulation is tightening refrigerant containment standards for HVAC compressors, indirectly mandating higher-efficiency motor pairings to offset system power draw. Compressor manufacturers are redesigning scroll and reciprocating platforms around IE4 minimums. Cold chain logistics operators in France and Poland face accelerated replacement schedules for warehouse refrigeration assets.
Buyer preference is consolidating around total cost of ownership metrics rather than upfront equipment pricing. Industrial procurement teams in Japan and South Korea are unbundling motor supply from maintenance contracts, selecting vendors on kWh-per-year performance guarantees. This service model rotation favors suppliers with localized technical service networks over pure manufacturing scale.
Electric AC Motors Market Segmentation
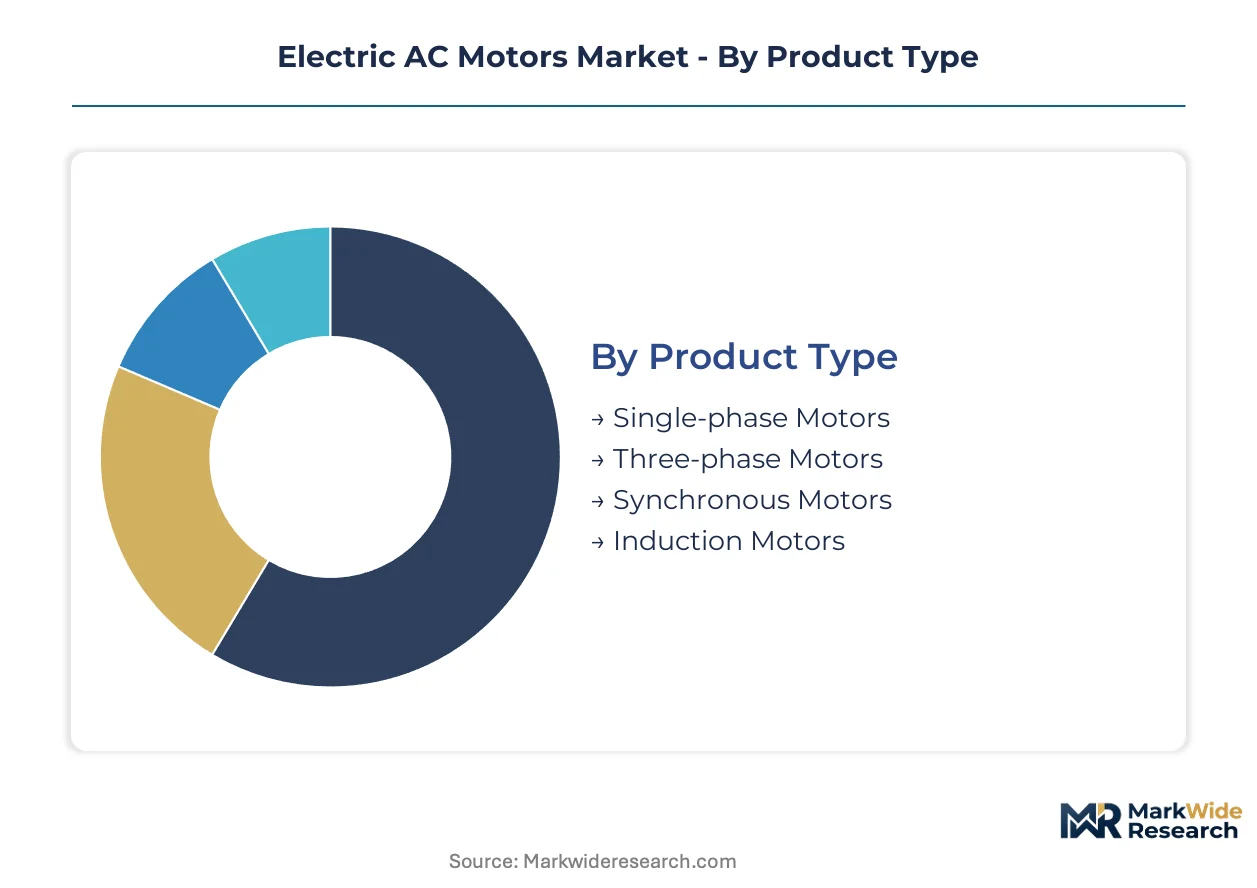
Segmentation in the Electric AC Motors Market reveals how efficiency mandates and automation intensity reshape procurement patterns across industrial verticals. Buyers prioritize IE3 and IE4 ratings in high-duty-cycle applications while tolerating lower tiers for intermittent use.
Product Type:
Mature induction architectures dominate installed base volumes while emerging synchronous designs capture precision positioning growth.
- Three-phase Motors:Rugged squirrel-cage construction withstands continuous operation in heavy manufacturing environments. Demand concentrates across automotive stamping lines in Germany, Japan, and the US Midwest where 24/7 duty cycles justify premium efficiency investments.
- Synchronous Motors:Permanent magnet rotors deliver synchronous speed lock without slip losses, enabling sub-arcminute positioning accuracy. Battery gigafactories in Nevada, Hungary, and South Korea absorb high-torque servo variants for robotic welding and cell stacking operations.
- Induction Motors:Standardized NEMA and IEC frame sizes support universal replacement across legacy pump and fan infrastructure.
- Single-phase Motors:Fractional horsepower units serve residential HVAC and agricultural irrigation where three-phase distribution remains unavailable.
Three-phase motors retain volume leadership; synchronous motors hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive automation buyers from price-sensitive seasonal operators.
- Manufacturing:Discrete automation and process industries demand IE4-rated motors paired with integrated condition monitoring. Automotive OEMs in Stuttgart, Detroit, and Toyota City specify predictive maintenance-ready architectures to minimize unplanned downtime.
- HVAC:Commercial building codes in California, New York, and the EU mandate minimum efficiency for air handling units. Chiller manufacturers specify electronically commutated and premium induction motors to meet ASHRAE 90.1 and EU Ecodesign thresholds.
- Automotive:EV powertrain production lines require explosion-proof and washdown-rated motors for battery electrolyte handling.
- Agriculture:Seasonal irrigation pumps and grain handling equipment favor repairable induction designs over premium efficiency tiers.
Manufacturing commands the highest specification density; automotive exhibits the most rapid technology refresh cycles.
Application:
Volume concentration in fluid handling systems contrasts with precision requirements in material transport.
- Pumps:Centrifugal and positive displacement configurations absorb the largest motor population across water treatment, oil and gas, and chemical processing. Municipal utilities in Texas, Florida, and Australia's Murray-Darling basin prioritize VFD-compatible motors for demand-responsive flow control.
- Fans:Axial and centrifugal blower applications in power generation and steelmaking require high-inertia starting capability. Cooling tower operators in India's National Capital Region and Saudi Arabia's Jubail Industrial City specify tropicalized insulation systems for 50°C ambient operation.
- Compressors:Refrigeration and air compression duty cycles demand robust bearing systems for frequent start-stop operation.
- Conveyors:Bulk material handling and parcel sorting systems require precise speed regulation and regenerative braking.
Pump applications anchor installed base volume; compressor pairings with HVAC systems climb the fastest.
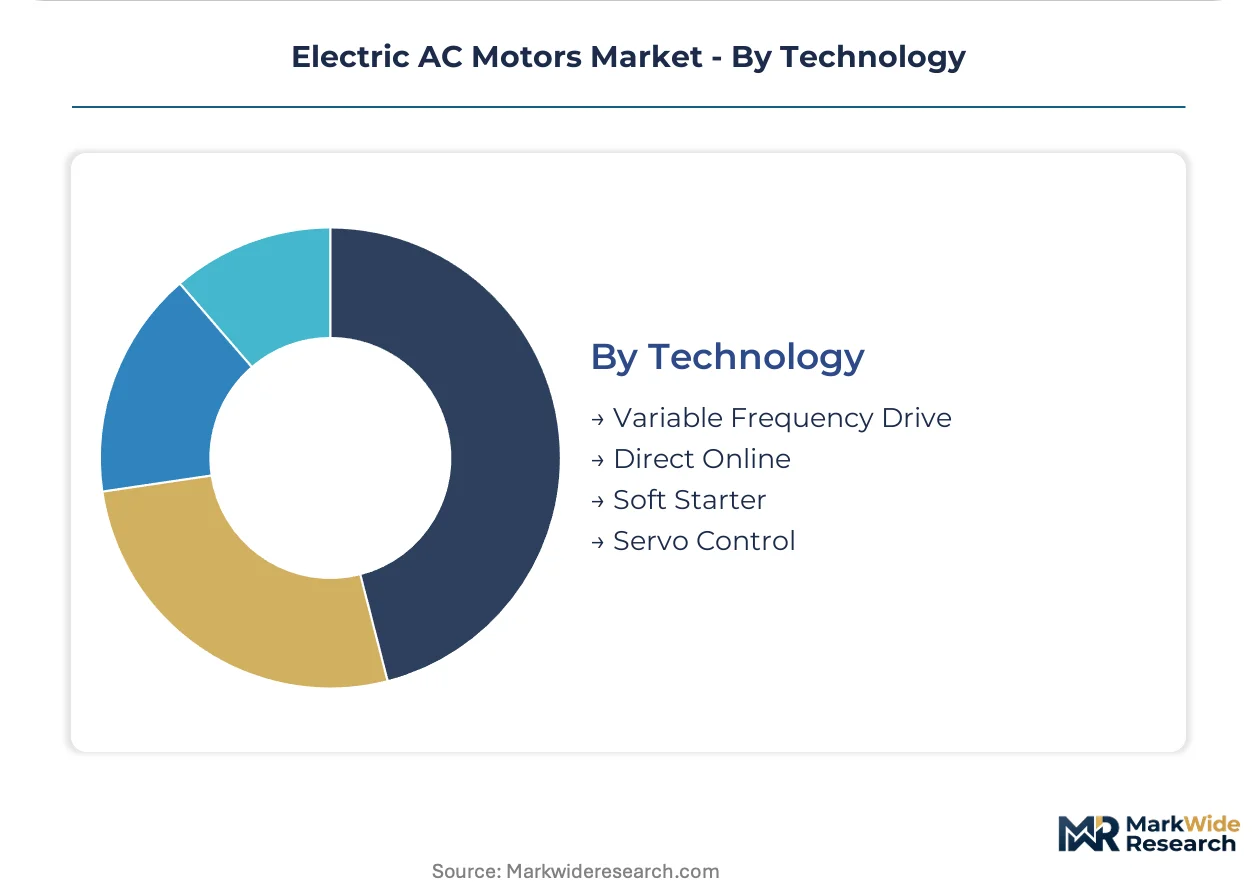
Technology:
Control architecture selection determines energy recovery potential and maintenance complexity across retrofit and greenfield installations.
- Variable Frequency Drive:VFD pairings enable 20-50% energy recovery in variable-torque pump and fan applications. Industrial facilities in Ontario, the Netherlands, and Singapore retrofit fixed-speed assets to meet corporate sustainability targets and utility rebate programs.
- Servo Control:Closed-loop positioning systems with resolver or encoder feedback deliver multi-axis synchronization for robotics. Semiconductor fabrication plants in Hsinchu, Dresden, and Hillsboro specify ultra-precise direct-drive motors for wafer handling.
- Direct Online:Across-the-line starting remains standard for low-inertia, constant-speed applications with minimal duty cycle variation.
- Soft Starter:Reduced-voltage starting limits mechanical and electrical stress on high-inertia loads such as large fans and compressors.
VFD integration captures the broadest retrofit opportunity; servo control commands the highest value-per-kilowatt premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German motor exports flow into automotive assembly plants across Hungary, Poland, and the Czech Republic, while Chinese manufacturers supply cost-optimized induction units to Southeast Asian infrastructure projects.
United States
Industrial facilities in Michigan and Ohio retrofit fixed-speed pump systems with VFD-compatible motors to capture utility rebate programs. The US Department of Energy enforces 10 CFR 431 efficiency mandates that phase out IE2-equivalent motors above one horsepower. Battery gigafactories in Nevada and Texas absorb high-torque servo motors for robotic welding and cell stacking operations.
Germany
Automotive OEMs in Stuttgart specify IE4-rated motors with integrated condition monitoring to minimize unplanned downtime. The EU Ecodesign Directive and F-Gas Regulation indirectly accelerate motor upgrades by linking compressor efficiency to climate targets. Precision automation suppliers in Baden-Württemberg anchor premium servo motor production for European manufacturing corridors.
China
GB 18613 standards mandate IE3 minimum efficiency for industrial motors, tightening market access for non-compliant imports. Rare earth magnet refining concentrates in Inner Mongolia, creating supply chain exposure for permanent magnet rotor production. Yangtze River Delta manufacturing clusters absorb the largest share of new three-phase motor installations across Asia-Pacific.
India
Production-linked incentives for industrial automation equipment attract motor assembly investments in Gujarat and Tamil Nadu corridors. The Bureau of Indian Standards enforces efficiency certification for industrial equipment under CEA guidelines. Municipal utilities in Maharashtra prioritize VFD-compatible motors for demand-responsive water treatment infrastructure.
Japan
Semiconductor fabrication plants in Hsinchu and Hillsboro source ultra-precise direct-drive motors from Japanese suppliers for wafer handling applications. METI efficiency guidelines push industrial facilities toward IE4 minimums. Kanto-region automotive suppliers specify predictive maintenance-ready motor architectures to support just-in-time production systems.
Electric AC Motors Market Vendor Landscape
On the supply side, the industry is consolidating around three structural tiers: integrated conglomerates with full automation portfolios, specialized motor fabricators with regional manufacturing footprints, and emerging Asian producers competing on cost-optimized induction designs. European and Japanese conglomerates anchor premium efficiency segments through captive R&D and certification expertise. Competitive moves concentrate on strategic partnerships for rare earth magnet supply security and geographic expansion into India and Southeast Asia via local assembly joint ventures.
Among diversified industrial conglomerates, ABB and Siemens exemplify the integrated automation archetype, combining hardware manufacturing with digital service layers. WEG represents the regional-specialist model with concentrated Latin American infrastructure presence. Nidec Corporation occupies a position bridging precision motor technology with scaled production capacity for automotive and industrial applications.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Nidec Corporation |
| Rockwell Automation |
| Emerson Electric Co. |
| Johnson Electric Holdings Limited |
| Toshiba Corporation |
| WEG |
| AMETEK, Inc. |
| Others |
Supply Flow & Price Mechanics
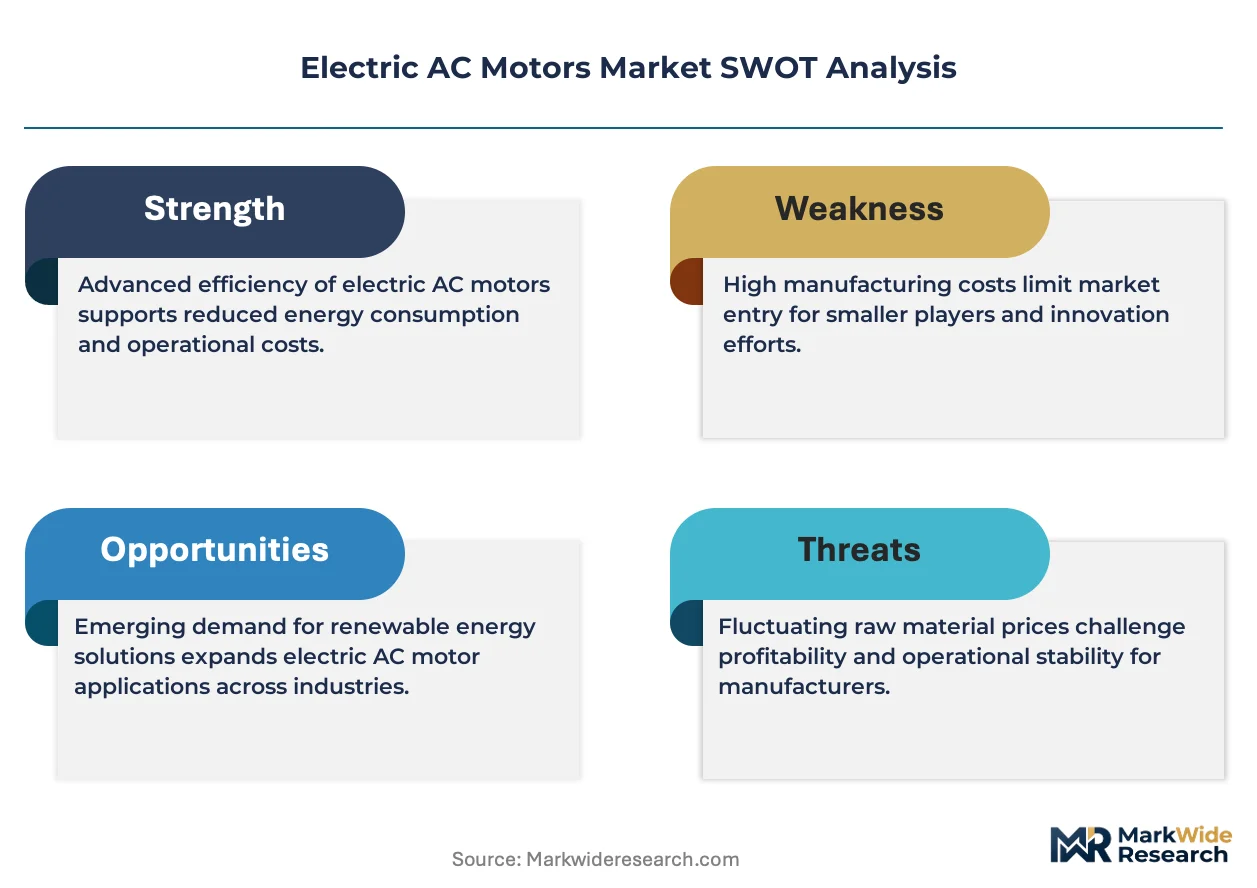
Inner Mongolia's rare earth magnet refining corridor governs permanent magnet rotor economics, concentrating pricing power among integrated producers while forcing induction motor fabricators to absorb copper volatility through frame-size standardization.
Pricing Analysis
IE4-to-IE3-to-IE2 efficiency-tier spreads define transaction structures, with three-tier pricing stratification across premium synchronous, standard induction, and economy fractional-horsepower lines. Certification grade under IEC 60034 and GB 18613 standards anchors price differentiation alongside volume scale and after-sales service bundling. Pricing pressure stems from copper futures volatility on the London Metal Exchange, compressing margins on high-volume induction units. Agricultural irrigation buyers exhibit highest price sensitivity, while automotive automation procurement teams prioritize kWh-per-year performance guarantees over unit cost.
Supply Chain Analysis
Copper cathode and electrical steel feed from Chile, China, and Japan anchor stator and rotor fabrication costs. Neodymium and dysprosium draws from China's Inner Mongolia corridor, with electrical steel sourcing concentrated in Japanese and South Korean mill complexes. Single-source vulnerability around rare earth magnet refining creates geopolitical exposure for permanent magnet synchronous production. Distribution runs through OEM direct contracts for large industrial orders, with authorized distributor networks handling MRO replacement volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric AC motors sit in early-cycle expansion as IE3 and IE4 efficiency mandates force replacement demand across installed bases that predate 2020 regulatory thresholds.
For Market Incumbents: Build certification moats around IEC-accredited laboratory relationships to compress IE4 launch timelines against testing backlogs. Defend servo motor margins by deepening captive rare earth magnet supply agreements with Inner Mongolia processors. Anchor channel control through localized technical service networks in Gujarat and Tamil Nadu corridors where PLI incentives attract new assembly investment. For New Entrants and Emerging Players: India's underpenetrated VFD retrofit market offers white-space entry through demand-responsive water treatment infrastructure in Maharashtra and Gujarat. Target hydrogen electrolyzer compressor integration as a specialized explosion-proof motor segment with limited incumbent specialization. Pursue joint venture assembly structures with established electrical steel distributors to bypass capital-intensive greenfield fabrication. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among servo motor suppliers bundling predictive maintenance services with hardware. Long-term viability favors targets with digital twin integration capabilities and edge-computing sensor architectures. Monitor IEC testing laboratory capacity expansion as an inflection signal for premium efficiency tier supply elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing from Inner Mongolia processors insulates permanent magnet rotor production against export restriction risk. |
| IE4 Certification Laboratory Partnership | Preferred IEC-accredited testing slots compress product launch cycles against third-party backlog constraints. |
| Digital Twin Platform Integration | Physics-based motor modeling with edge computing enables predictive bearing failure detection as recurring service revenue. |
| India PLI Scheme Manufacturing Footprint | Gujarat and Tamil Nadu assembly investments capture production-linked incentives for industrial automation equipment. |
| Hydrogen Compressor Motor Specialization | Explosion-proof designs for high-pressure electrolyzer gas handling open specialized product lines with limited competition. |
Methodological Framework
A standing panel of plant engineers, OEM procurement managers, aftermarket service heads, and maintenance directors provided ongoing calibration across primary interview cycles. Secondary validation drew from IEC 60034 certification databases, US DOE 10 CFR 431 filings, China's GB 18613 enforcement records, and copper futures exchange data. Bottom-up unit economics triangulated against top-down manufacturing capacity assessments across Yangtze River Delta and European industrial corridors.
Scenario-bracketing anchored volume and value outputs across the projection horizon, modeling efficiency tier adoption curves, VFD retrofit penetration rates, and regional regulatory phase-in schedules. Segmentation dimensions spanned motor topology, control architecture, end-use vertical, and geographic manufacturing cluster. CAGRs derived from installed base replacement cycles, greenfield automation intensity, and efficiency mandate compliance deadlines. Industry-specific inputs included rare earth magnet price indices, electrical steel mill capacity utilization, and utility rebate program enrollment data.
Practitioners should monitor IEC laboratory testing backlogs, copper futures volatility spikes, and rare earth export policy shifts for early signals requiring forecast revision. Cross-checking against US DOE enforcement action rates and EU Ecodesign implementation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Frameless Motor Market
Electric Motor
Electric Drives Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
Automotive ABS Motor Market
Electric Motor
Trolling Motor Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
North America Electric Motor Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Air Motor Market
Electric Motor
UAE Electric Motor Market
Electric Motor
Automotive Sunroof Motor Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
United States AC Motor Market
Electric Motor
Europe Automotive Torque Actuator Motor Market