
 Automotive Timing Chain and Belt Market | 2026-2036
Automotive Timing Chain and Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Timing Chain and Belt Market Analysis
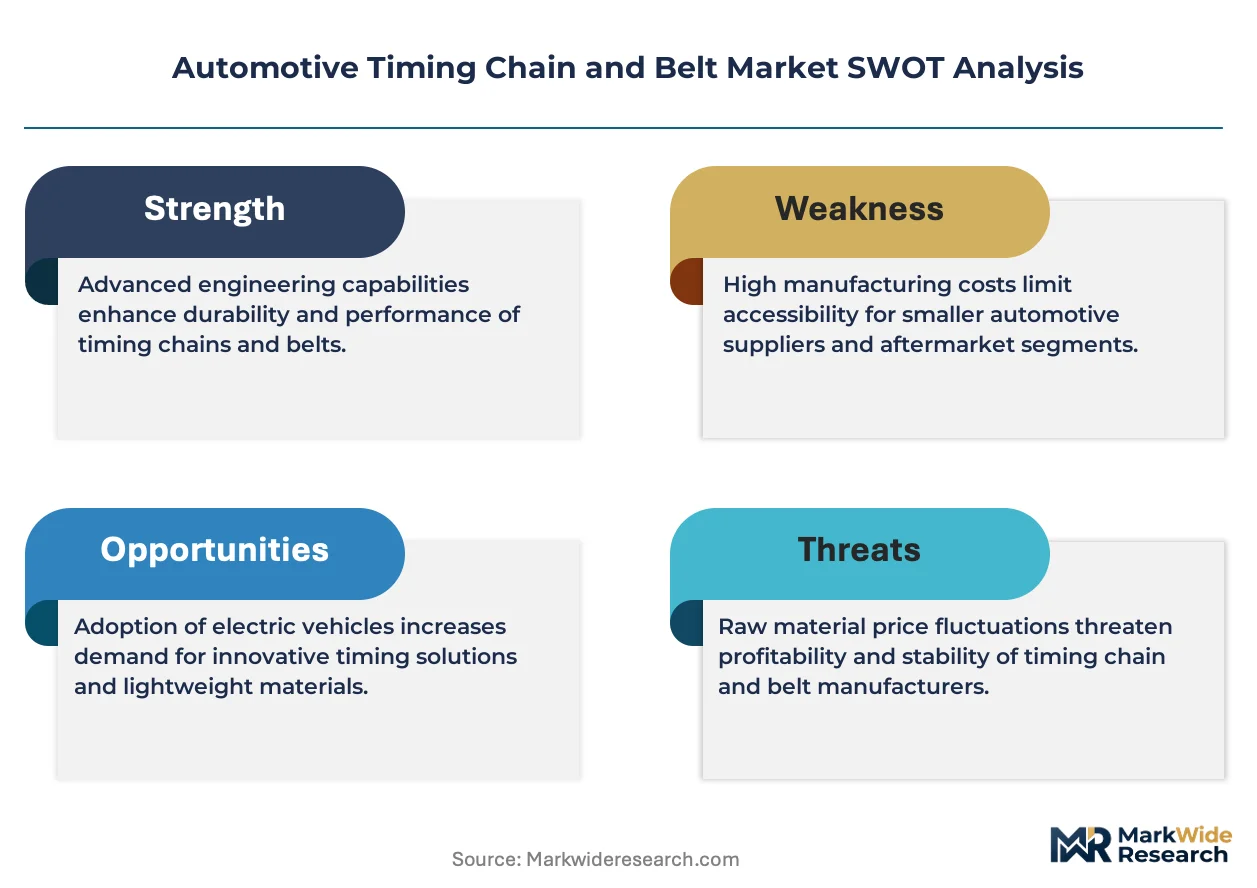
Aftermarket maintenance contracts and software-defined predictive replacement scheduling is consolidating how timing component value gets captured across vehicle lifecycles. BorgWarner Inc. leverages its powertrain integration depth to bundle chain systems with cam phasing hardware. Schaeffler AG anchors European supply through precision forging capabilities for high-load timing chains. Gates Corporation competes on elastomer compound expertise that extends belt durability in hybrid thermal cycling.
Automotive timing chains and belts are engineered powertrain components that synchronize crankshaft and camshaft rotation to maintain valve timing within 1-2 degrees of precision, using heat-treated alloy steel chains or fiber-reinforced rubber belts operating at 100-150°C continuous temperatures. Timing chains dominate OEM fitment in gasoline and diesel engines due to their 150,000-mile service life, while timing belts retain cost advantages in compact passenger cars and certain hybrid architectures where packaging space is constrained. The tensioner segment captures disproportionate margin as electromechanical actuation replaces passive spring designs in modern variable valve timing systems. Electric vehicle timing gear applications represent an emerging structural pocket as motor-transmission integration creates new synchronization requirements.
NHTSA crashworthiness standards and EPA emission certification protocols shape material selection and durability testing regimes for US-market timing components. EU REACH chemical restrictions and ECHA substance evaluations limit certain rubber plasticizers and coating chemistries in belt manufacturing, pushing suppliers toward bio-based elastomer formulations. Stakeholders must monitor how powertrain electrification trajectories redefine addressable component volumes and whether hybrid engine architectures sustain timing system demand longer than pure internal combustion forecasts assume.
Market Dynamics
Hybrid engine architectures are compressing timing component specifications as thermal cycling demands intensify, forcing suppliers to recalibrate material formulations for 100-150°C operating windows while maintaining 150,000-mile durability benchmarks.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Passenger vehicle OEMs in the United States are expanding lightweight timing belt adoption to meet tightening fleet efficiency mandates, creating specification pull-through for fiber-reinforced elastomer compounds.
- China hybrid engine production:Domestic automakers are scaling localized component sourcing for dual-motor hybrid architectures, concentrating demand for precision-forged timing chains in Shanghai and Guangzhou manufacturing clusters.
- Electromechanical tensioner actuation:Variable valve timing integration is displacing passive spring designs with sensor-enabled tensioner systems, opening margin capture opportunities in the tensioner subsegment.
Market Restraints
- Steel alloy input volatility:Heat-treated alloy steel chain production faces cost pressure from nickel and chromium price fluctuations, compressing margin stability for forged component manufacturers.
- EU REACH chemical restrictions:ECHA substance evaluations are limiting rubber plasticizers and coating chemistries in belt manufacturing, forcing reformulation investments before bio-based elastomer alternatives mature.
- Electric motor synchronization:Pure battery electric vehicles eliminate traditional crankshaft-camshaft timing systems entirely, threatening long-term addressable volume in passenger car segments.
Strategic Opportunities
- Electric vehicle timing gear applications:Motor-transmission integration in EVs creates novel synchronization requirements for multi-speed reduction gearboxes, opening a structural pocket for adapted timing component suppliers.
- Software-defined predictive replacement:Aftermarket maintenance contracts are consolidating lifecycle value capture through telematics-enabled wear monitoring, shifting revenue from part sales to service subscriptions.
- India hybrid localization:PLI scheme incentives for advanced automotive components are attracting timing system suppliers to establish forging and elastomer compounding capacity in Tamil Nadu and Maharashtra.
Industry Challenges
- Precision forging talent scarcity:High-load timing chain production requires specialized metallurgical expertise in heat treatment and dimensional control, with skill gaps concentrated in European and Japanese supplier bases.
- Dual certification timelines:Simultaneous NHTSA crashworthiness validation and EPA emission certification for US-market timing components extends product launch cycles by 8-14 months.
- Legacy ICE-EV portfolio balancing:Suppliers must maintain internal combustion timing system capacity while building EV-adjacent capabilities, straining capital allocation and engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Timing Chain and Belt Market |
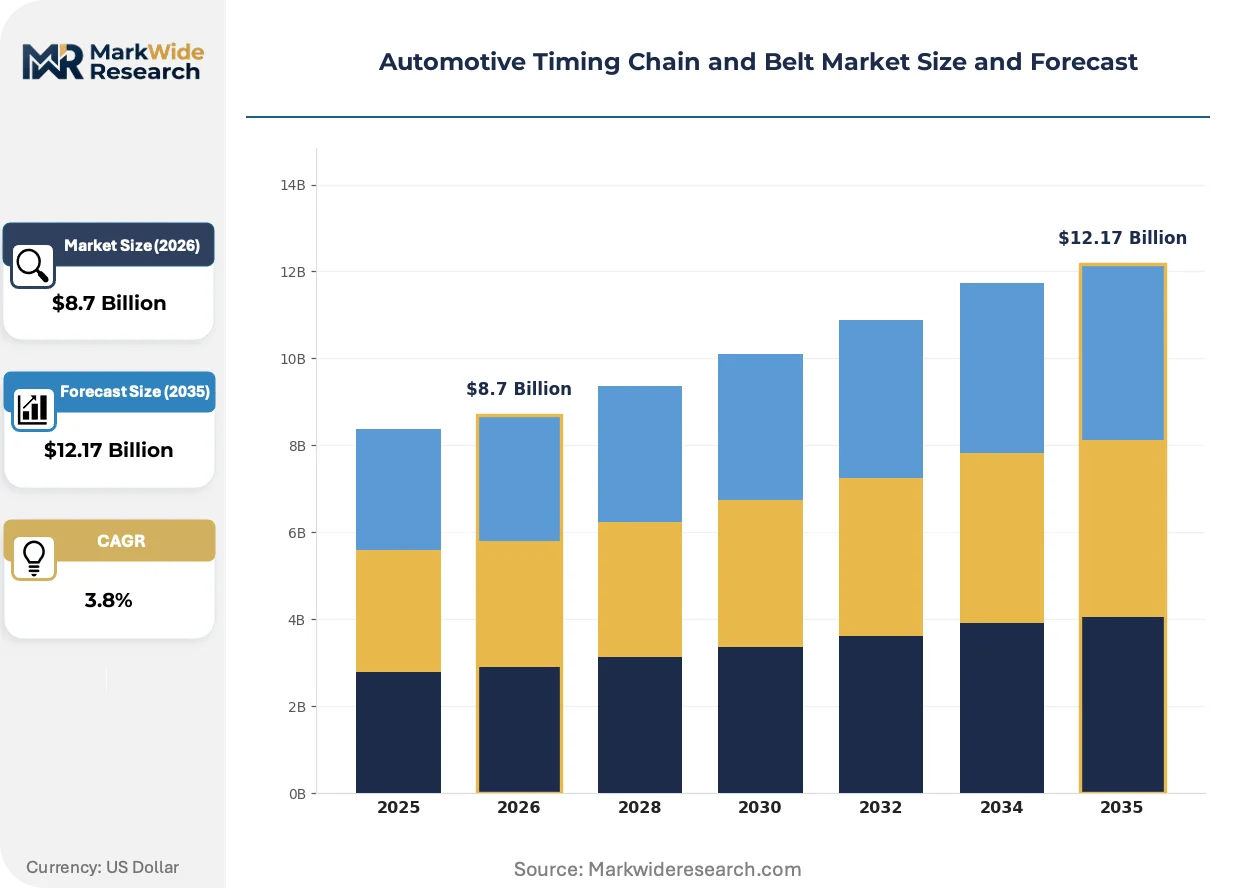
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Timing Chain, Timing Belt, Timing Gear, Tensioner Engine Type: Gasoline, Diesel, Hybrid, Electric Vehicle Type: Passenger Car, Commercial Vehicle, SUV, Motorcycle Distribution Channel: OEM, Aftermarket, Retailer, Wholesaler |
| Companies Covered | BorgWarner Inc., Schaeffler AG, Continental AG, Gates Corporation, Dayco Products LLC, SKF, NTN Group, Aisin Corporation, Tsubakimoto Chain Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Timing Chain and Belt Market Emerging Trajectories
Active material science breakthroughs and regulatory chemistry restrictions are simultaneously forcing formulation pivots and opening premium positioning for compliant suppliers who solve thermal durability under constrained additive palettes.
Electromechanical tensioner systems with integrated position sensors are electrifying valve train control precision. Tier 1 powertrain integrators are adopting these actuators at accelerated pace for 48V mild-hybrid architectures. This electrification is compressing the addressable market for mechanical spring-and-pawl tensioners to cost-optimized compact car segments.
EU REACH Annex XVII restrictions on phthalate plasticizers are compelling belt manufacturers to accelerate bio-based elastomer validation. The industrial consequence is a 24-36 month reformulation window before 2026 enforcement deadlines. Asian compounders with established natural rubber supply chains are capturing specification leadership for next-generation hybrid belt platforms.
Fleet operators and leasing companies are unbundling timing component replacement from bundled maintenance packages, creating direct procurement relationships with OES suppliers. This channel disintermediation is most visible in German and US commercial vehicle segments where total cost of ownership transparency drives component-level sourcing decisions.
Automotive Timing Chain and Belt Market Segmentation
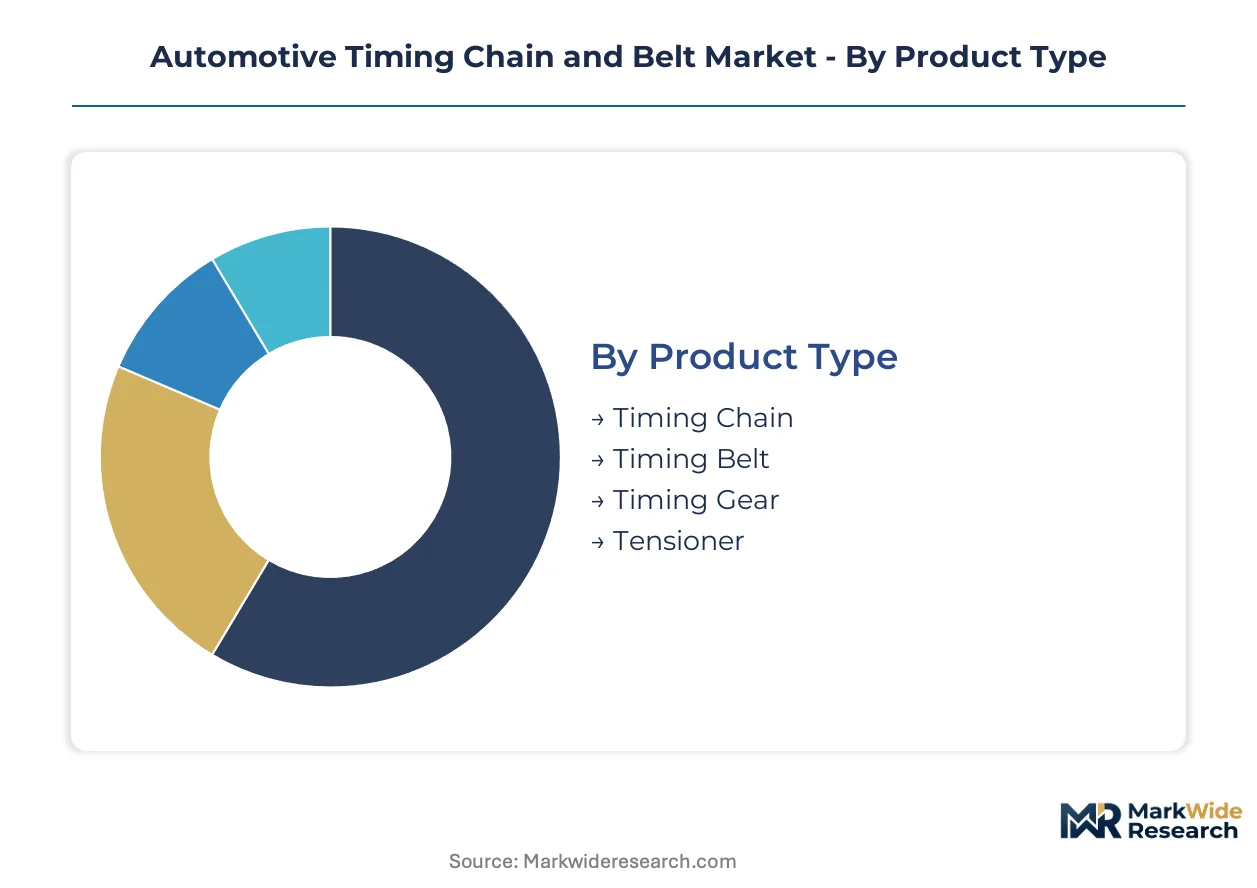
Timing component buyers face divergent specification requirements across powertrain architectures, with hybrid thermal cycling and EV motor synchronization creating entirely new segmentation logic. Understanding where value concentrates within each dimension reveals which supplier capabilities command premium positioning.
Product Type:
Standardization dominates at the commodity end while precision-forged and sensor-integrated variants capture customization premiums.
- Timing Chain:Heat-treated alloy steel link plates and bushings engineered for 150,000-mile service intervals in gasoline and diesel crankshaft-camshaft synchronization. Demand concentrates in Shanghai and Guangzhou manufacturing clusters where domestic automakers scale hybrid engine production under China's dual carbon goals.
- Tensioner:Electromechanical actuation systems with integrated position sensors replacing passive spring designs in variable valve timing integration. The subsegment captures disproportionate margin as 48V mild-hybrid architectures accelerate adoption across European and Japanese OEM lineups.
- Timing Belt:Fiber-reinforced elastomer compounds operating at 100-150°C continuous temperatures, retaining cost advantages in compact passenger cars where packaging space is constrained.
- Timing Gear:Precision-machined sprockets and pulleys for direct drive applications, emerging as structural components in motor-transmission integration for multi-speed EV reduction gearboxes.
Leading the category by volume: Timing Chain. Growing fastest: Tensioner.
Engine Type:
Volume distribution tracks powertrain electrification trajectories, with hybrid architectures sustaining component demand longer than pure ICE forecasts assume.
- Hybrid:Dual-motor architectures intensify thermal cycling demands, forcing material reformulation for 100-150°C operating windows while maintaining durability benchmarks. Chinese domestic automakers anchor global demand concentration through localized component sourcing mandates.
- Gasoline:Conventional port and direct injection engines represent the installed base volume, though share compression accelerates as EPA CAFE standards tighten fleet efficiency requirements.
- Diesel:Compression ignition timing systems face regulatory pressure from EU emission targets and urban access restrictions, constraining growth in European passenger car applications.
- Electric:Pure battery electric vehicles eliminate traditional crankshaft-camshaft timing entirely, though motor-transmission synchronization creates adjacent component opportunities.
Hybrid applications command the steepest expansion trajectory as electrification transitions prolong ICE component relevance.
Vehicle Type:
Specification tiers separate mass-market passenger applications from commercial durability requirements and motorcycle packaging constraints.
- Passenger Car:Lightweight timing belt preference dominates compact and mid-size segments where fuel efficiency mandates drive material selection, with OEM specification pull-through for fiber-reinforced elastomer compounds.
- Commercial Vehicle:Fleet operators in German and US markets unbundle timing component replacement from bundled maintenance packages, creating direct procurement relationships with OES suppliers based on total cost of ownership transparency.
- SUV:Larger displacement engines and all-wheel-drive architectures favor timing chain fitment for load-bearing durability in higher-torque applications.
- Motorcycle:Compact packaging and high-revving engine characteristics drive specialized tensioner and small-displacement belt requirements with distinct aftermarket service patterns.
Passenger Car generates the largest absolute volume. Commercial Vehicle procurement patterns are shifting fastest toward component-level sourcing.
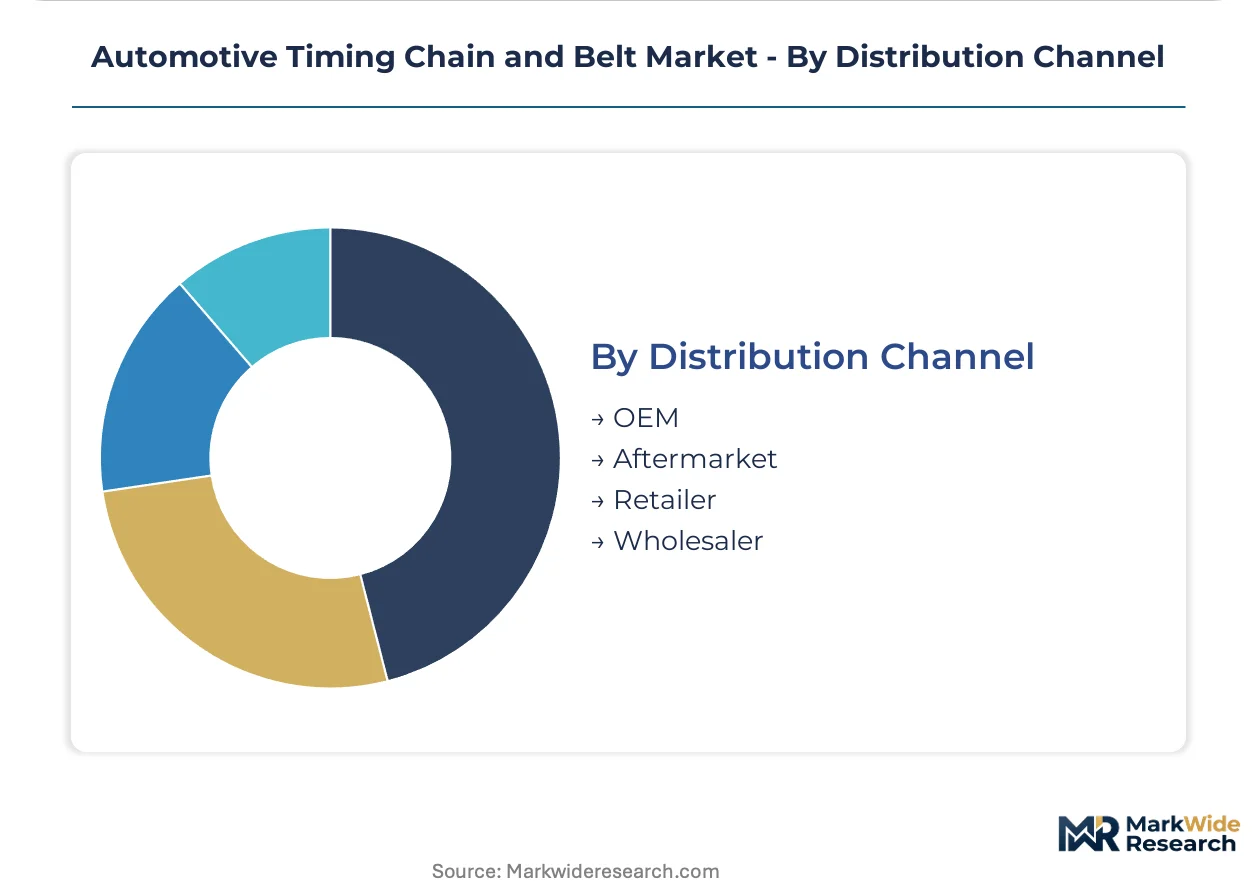
Distribution Channel:
Channel power consolidates around lifecycle value capture models, with telematics-enabled service subscriptions displacing transactional part sales.
- OEM:Original equipment fitment for new vehicle production, where powertrain integration depth determines supplier selection and BorgWarner bundles chain systems with cam phasing hardware.
- Aftermarket:Maintenance contracts and software-defined predictive replacement scheduling consolidate lifecycle value capture, shifting revenue from part sales to service subscriptions.
- Retailer:Consumer-facing parts counters and e-commerce platforms serving DIY maintenance segments with standardized replacement intervals.
- Wholesaler:Bulk distribution to independent repair facilities and regional jobbers, intermediating inventory risk for slower-moving specialty applications.
OEM retains volume leadership. Aftermarket revenue models are transforming most rapidly through predictive maintenance integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of precision-forged timing chains while the United States and Germany drive specification standards through EPA CAFE and EU emission mandates. This production-consumption divide shapes supplier location decisions and certification investments across major automotive clusters.
China
Domestic automakers in Shanghai and Guangzhou manufacturing clusters scale hybrid engine production under the country's dual carbon goals. MIIT fuel consumption regulations tighten material specifications for 100-150°C thermal cycling durability. Precision forging capacity concentrates in Yangtze River Delta supplier parks serving BYD and Geely hybrid platforms.
United States
EPA Corporate Average Fuel Economy standards pull lightweight timing belt adoption across Detroit Three lineups. NHTSA crashworthiness validation extends product launch cycles for US-market components. Michigan and Ohio supplier corridors anchor forging and elastomer compounding investments for North American OEM fitment.
Germany
ECHA REACH Annex XVII restrictions on phthalate plasticizers force belt reformulation investments before enforcement deadlines. KBA type-approval protocols shape durability testing regimes for European passenger car applications. Bavaria and Baden-Württemberg precision engineering clusters sustain high-load timing chain metallurgical expertise.
Japan
METI carbon neutrality roadmaps accelerate 48V mild-hybrid architecture adoption across Toyota and Honda lineups. JIS standards govern heat-treated alloy steel dimensional control for 150,000-mile service life benchmarks. Aichi and Kanagawa manufacturing belts retain specialized tensioner electromechanical actuation capabilities.
India
PLI scheme incentives for advanced automotive components attract timing system suppliers to establish forging capacity. BIS certification requirements align with tightening emission norms for domestic hybrid production. Tamil Nadu and Maharashtra industrial corridors localize component sourcing for Maruti Suzuki and Tata Motors hybrid platforms.
Automotive Timing Chain and Belt Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across forged chain and molded belt segments. The supplier base consolidates around powertrain integrators with cam phasing bundling capabilities and standalone component specialists with compound formulation depth. Three archetypes dominate: integrated powertrain system houses, precision forging metallurgists, and elastomer compound innovators. Competitive moves concentrate on backward integration into heat treatment capacity and strategic partnerships for electromechanical actuator development.
Within the integrated powertrain tier, BorgWarner Inc. and Schaeffler AG exemplify system-level bundling strategies that capture valve train specification authority. Among elastomer-focused compounders, Gates Corporation occupies a position representing bio-based formulation leadership under constrained additive palettes. Continental AG anchors European supply relationships through precision engineering scale. These three company structures illustrate how geographic origin and corporate form shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Schaeffler AG |
| Continental AG |
| Gates Corporation |
| Dayco Products LLC |
| SKF |
| NTN Group |
| Aisin Corporation |
| Tsubakimoto Chain Co. |
| Others |
Supply Flow & Price Mechanics
Nickel and chromium alloy feedstock moves from Australian and Indonesian mining operations through Yangtze River Delta forging clusters, then stratifies into three distinct pricing tiers based on heat-treatment certification and electromechanical integration depth before reaching Detroit Three and Shanghai-based OEM procurement desks.
Pricing Analysis
Margin tightening in precision-forged timing chains reflects nickel price volatility and EU REACH compliance costs. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated electromechanical tensioners from passive spring designs and commodity link plates. Chinese domestic automakers exhibit highest price sensitivity due to localization mandates, while German luxury OEMs prioritize certification tier over unit cost. Cost-down pressure accelerates as hybrid thermal cycling requirements force material reformulation investments.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta precision forging capacity for heat-treated alloy steel chains. Production concentrates in China, Germany, and Japan, drawing from nickel mines in Australia and Indonesia, chromium from South Africa, and synthetic rubber feedstocks from South Korea. Tariff exposure on steel alloy imports threatens margin stability for North American suppliers. Distribution runs through Tier 1 powertrain integrators who bundle chain systems with cam phasing hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical tensioner systems are displacing passive mechanical designs across 48V mild-hybrid architectures, compressing the addressable market for legacy spring-and-pawl components while opening premium positioning for sensor-integrated suppliers.
For Market Incumbents: Hedge against pure battery electric vehicle volume erosion by deepening backward integration into heat treatment capacity and securing electromechanical actuator partnerships. Maintain internal combustion timing system capacity while building EV-adjacent motor-transmission synchronization capabilities. Channel control through software-defined predictive maintenance subscriptions offers defensive revenue stabilization against part sales decline. For New Entrants and Emerging Players: Begin with bio-based elastomer formulation for EU REACH-compliant timing belts, targeting Asian compounders with established natural rubber supply chains. The most penetrable white space sits in India's Tamil Nadu and Maharashtra corridors under PLI scheme incentives. A direct procurement relationship with German and US fleet operators unbundling maintenance packages offers channel access without OEM incumbent barriers. For Investors and Strategic Acquirers: Schaeffler AG's precision forging metallurgy capabilities are the leading indicator that high-load timing chain expertise retains scarcity value through the electrification transition. Five-to-ten year viability favors suppliers with dual ICE-EV portfolio balance and electromechanical integration depth. Watch for EPA CAFE standard tightening velocity as the signal for lightweight timing belt specification pull-through acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captures margin from nickel volatility while securing 150,000-mile durability certification for Shanghai-based OEM programs. |
| Electromechanical Actuator Partnership | Positions suppliers for 48V mild-hybrid tensioner demand across Toyota and Honda lineups under METI carbon neutrality roadmaps. |
| Bio-Based Elastomer Validation | Opens EU market access before ECHA REACH Annex XVII enforcement deadlines constrain phthalate-based compounders. |
| Software-Defined Predictive Maintenance Platform | Shifts revenue from transactional part sales to subscription-based lifecycle value capture with fleet operators. |
| India Manufacturing Footprint Expansion | Localizes component sourcing for Maruti Suzuki and Tata Motors hybrid platforms under PLI scheme incentives. |
Methodological Framework
Multi-period observation of EPA CAFE standard implementation velocity, EU REACH enforcement timelines, and China MIIT fuel consumption regulation trajectories anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and precision forging metallurgists. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of publicly traded component suppliers, and ECHA substance evaluation notifications. Bottom-up volume modeling triangulated against top-down powertrain electrification scenario analysis.
Segment-weighting across product type, engine architecture, vehicle class, and regional production cluster shaped the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted volume projections and value-per-vehicle content assumptions. Industry-specific inputs included hybrid engine production forecasts from Shanghai and Guangzhou manufacturing clusters, and 48V mild-hybrid adoption curves from European and Japanese OEM lineups.
Powertrain electrification trajectory revisions, nickel and chromium commodity price shocks, and ECHA substance evaluation outcomes are the dominant revision risks that could alter forecast outputs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Automotive Brake Booster Market
Powertrain
Turbocharger Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Automotive Torque Vectoring System Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
EV Powertrain Market
Powertrain
Global Automotive Dyno Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Automotive Tuner Market
Powertrain
Automotive Coil Spring Market
Powertrain
Automotive Engine Market
Powertrain
North America Automotive Engine Oils Market