
 Automotive Engine Market | 2026-2036
Automotive Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Market Intelligence
Aftermarket service revenue for engine rebuilds and component refurbishment is narrowing as original equipment manufacturers extend powertrain warranties and push certified pre-owned programs. Toyota leverages its hybrid synergy drive expertise to sustain dominance in electrified powertrain shipments. BMW anchors its profit pool in high-performance inline-six and V8 architectures for premium segments. Honda competes through advanced variable valve timing integration across its mass-market four-cylinder portfolio.
An automotive engine is a machine designed to convert chemical energy from fuel combustion into mechanical rotational force, typically measured in displacement liters, cylinder count, brake horsepower, and torque output, serving as the primary propulsion system for road vehicles, marine vessels, and off-highway equipment. Internal combustion engines still occupy the largest installed base, though hybrid configurations are capturing the fastest expansion in new vehicle registrations as emissions thresholds tighten. Turbocharged technology leads margin retention for petrol applications, while direct injection systems dominate diesel architecture due to thermal efficiency mandates.
EPA tailpipe standards, Euro 7 emission frameworks, and China's MIIT fuel consumption regulations collectively dictate combustion architecture choices, certification costs, and production feasibility across major supply bases. California Air Resources Board waivers and EU CO2 fleet-average penalties further compress the viable window for pure internal combustion launches in developed markets. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded tooling investments and misaligned product pipelines.
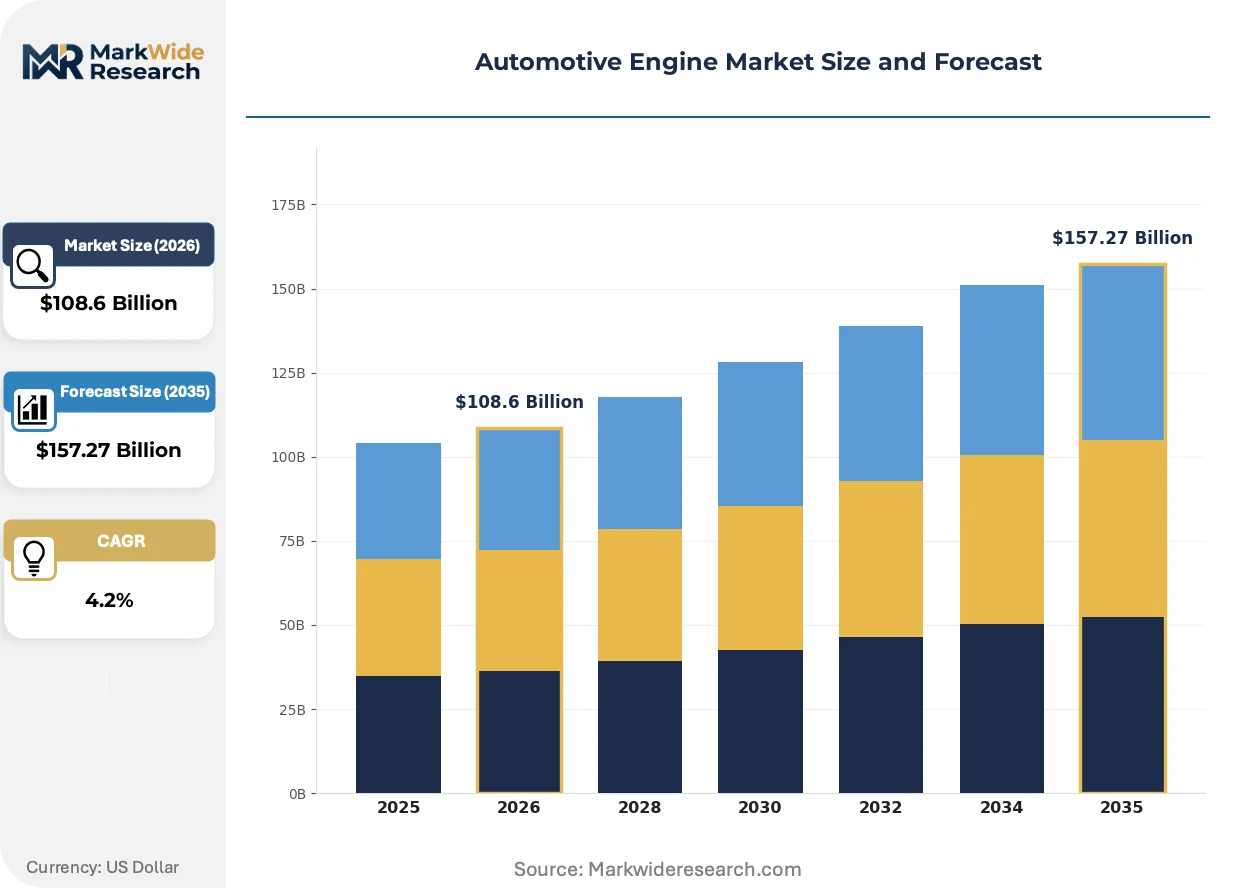
Market Dynamics
The automotive engine sector is experiencing a fundamental recomposition as hybrid powertrain architectures displace pure internal combustion in new vehicle procurement, forcing capital reallocation across manufacturing footprints and supplier tiers.
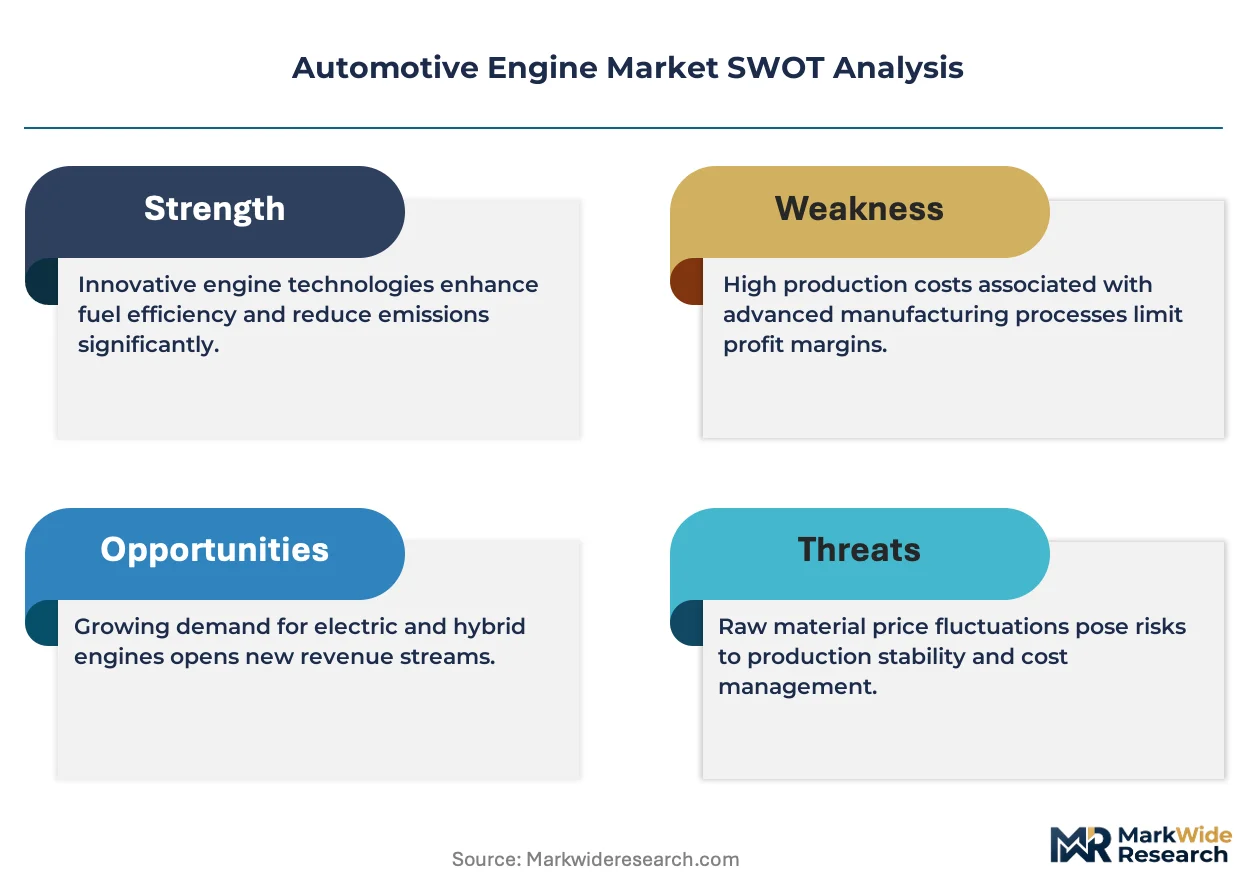
Growth Catalysts
- EPA Tier 4 and Euro 7 mandates:These frameworks compel fleet operators to accelerate hybrid powertrain procurement, expanding the addressable market for electrified engine systems in commercial vehicle segments.
- China's MIIT fuel consumption regulations:Domestic manufacturers must achieve progressively stricter corporate average fuel economy targets, driving R&D investment in turbocharged downsized engines and integrated starter-generator architectures.
- Commercial vehicle electrification:Urban delivery and logistics operators face municipal zero-emission zone restrictions, creating pull-through demand for range-extended hybrid engines that preserve operational flexibility.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet materials for hybrid motor integration concentrate in Chinese processing facilities, exposing powertrain manufacturers to input cost volatility and geopolitical supply interruptions.
- Platinum group metal cost escalation:Catalytic converter loadings for NOx aftertreatment systems face rhodium and palladium price spikes that compress margin structures on compliant diesel architectures.
- Battery-electric substitution threat:Pure battery platforms are capturing share in light-duty passenger segments where daily range requirements fall within single-charge capability, narrowing the viable window for hybrid intermediate solutions.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced automotive technology manufacturing create localized assembly opportunities for hybrid powertrain modules serving South Asian export markets.
- Marine and off-highway hybridization:Harbor craft, construction equipment, and agricultural machinery face emerging emissions regulations with limited battery-electric viability, opening specialized engine system demand.
- Software-defined engine calibration:Over-the-air update capability enables subscription-based performance tiering and emissions compliance management, transforming hardware-centric business models toward recurring revenue architectures.
Industry Challenges
- Power electronics integration complexity:Combining high-voltage inverter assemblies with thermal engine management requires cross-functional engineering competencies scarce in traditional mechanical engineering workforces.
- Homologation timeline compression:Euro 7 certification protocols demand extended real-driving emissions testing cycles that extend development schedules and delay revenue recognition for new engine launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Market |
| Market Size in 2026 | $108.6 Billion |
| Market Size in 2035 | $157.27 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Combustion Engine, Electric Engine, Hybrid Engine, Gas Turbine Engine Fuel Type: Petrol, Diesel, Ethanol, Compressed Natural Gas Application: Passenger Vehicles, Commercial Vehicles, Agricultural Equipment, Marine Applications Technology: Turbocharged, Supercharged, Direct Injection, Variable Valve Timing |
| Companies Covered | Mercedes-Benz, Audi, Toyota, Subaru, Mazda, Honda, BMW, Renault, Ferrari, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Market Strategic Shifts & Innovations
Digital twin architectures and model-based systems engineering are compressing development cycles while enabling predictive maintenance integration, fundamentally altering how engine performance is validated and monetized across the vehicle lifecycle.
Digital twin simulation platforms are digitizing the engine calibration process by creating virtual replicas of combustion behavior, thermal management, and emissions formation. Tier-1 suppliers and OEM powertrain divisions deploy these tools to reduce physical prototype iterations by half. The technology is digitizing validation workflows, compressing homologation timelines while enabling real-time parameter optimization across diverse operating conditions and fuel qualities.
REACH substance restrictions and the EU Green Deal's embedded carbon reporting requirements are reshaping material selection for engine castings and coatings. Manufacturers must document supply chain emissions intensity and eliminate certain heavy-metal surface treatments. High-performance passenger car segments face the steepest compliance cost escalation, prompting accelerated adoption of recycled aluminum alloys and water-based coating chemistries.
Fleet operators are consolidating procurement decisions at the corporate level rather than delegating to regional maintenance managers, centralizing powertrain specification authority. This concentration shifts negotiation leverage toward volume buyers and squeezes aftermarket service margins previously captured by independent rebuilders. North American commercial vehicle leasing companies exhibit the most pronounced centralization, bundling powertrain warranties into full-service lease arrangements that displace component-level purchasing.
Automotive Engine Market Segmentation
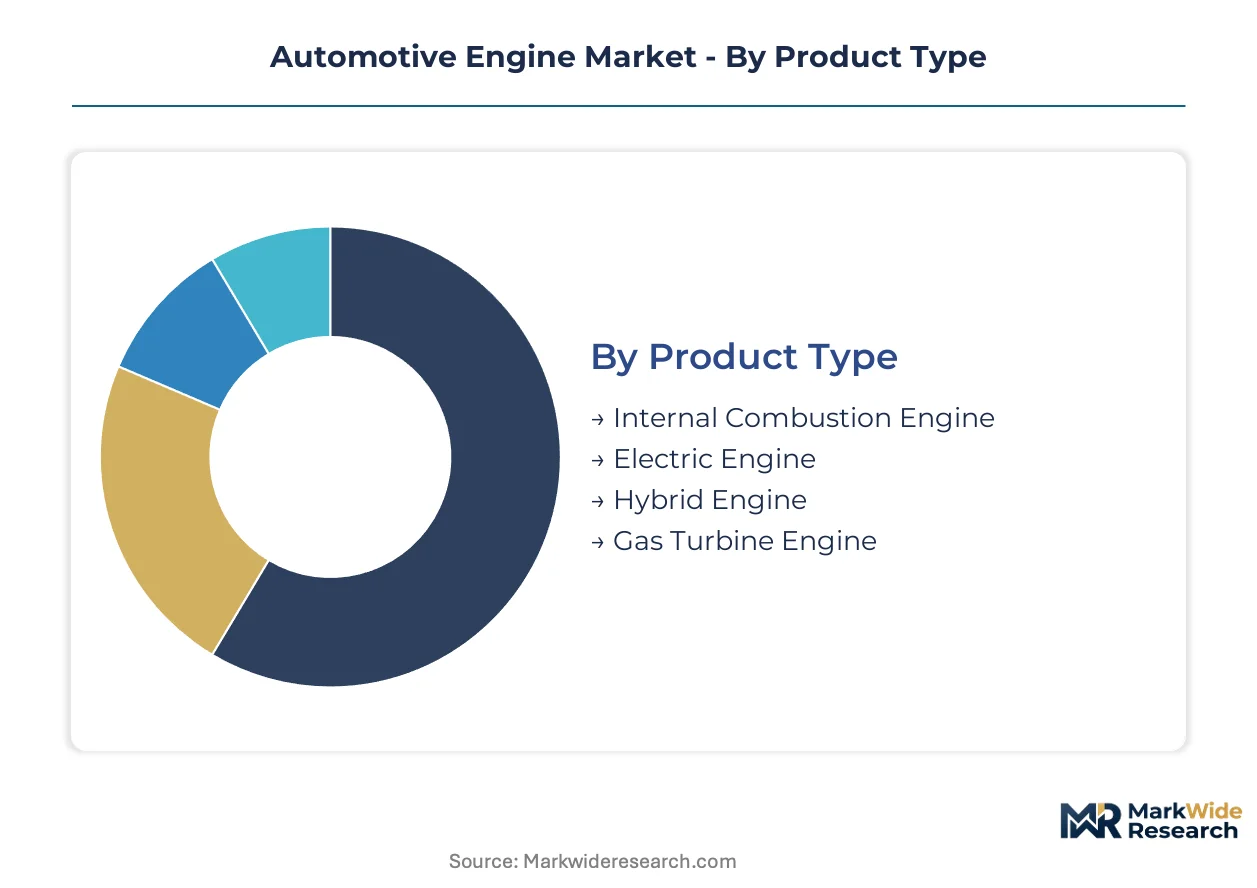
Engine architecture choices in this market trace directly to regulatory compliance costs, fuel infrastructure availability, and duty-cycle requirements across vehicle categories. Procurement patterns diverge sharply between developed markets prioritizing emissions reduction and emerging economies optimizing capital efficiency.
Product Type:
Cost tier stratification separates mass-market powertrain investments from specialized high-performance or zero-emission alternatives.
- Internal Combustion Engine:These architectures remain the dominant installed base across global vehicle fleets, utilizing spark-ignition or compression-ignition cycles with displacements ranging from sub-liter three-cylinder designs to large-bore V8 configurations. Fleet operators in India, Brazil, and Southeast Asia continue procurement of pure combustion units where fuel subsidies and lower acquisition costs outweigh emissions compliance penalties.
- Hybrid Engine:Integrated motor-generator architectures combine thermal engines with electric traction motors, enabling regenerative braking and torque-fill during transient load conditions. Toyota, Honda, and Hyundai-Kia manufacturing clusters in Japan, Thailand, and the United States ship these systems to markets with stringent corporate average fuel economy mandates.
- Electric Engine:Permanent magnet synchronous and induction motor designs eliminate tailpipe emissions entirely, requiring high-voltage inverter integration and thermal management systems.
- Gas Turbine Engine:Brayton-cycle turbines serve specialized military and heavy-duty applications where power-to-weight ratios exceed reciprocating engine capabilities.
Internal Combustion Engine holds installed capacity. Hybrid Engine is rotating up the share rankings.
Fuel Type:
Application context dictates fuel selection, with infrastructure density and energy density requirements filtering viable options across geographic markets.
- Petrol:Spark-ignited gasoline formulations dominate light-duty passenger segments, with turbocharged downsizing replacing naturally aspirated larger-displacement architectures. OEM engineering centers in Germany and Japan optimize port and direct injection strategies for China's MIIT fuel consumption certification cycles.
- Diesel:Compression-ignition systems with high-pressure common-rail injection deliver thermal efficiency advantages in high-mileage commercial applications. Euro 7 NOx aftertreatment requirements have escalated catalyst costs, compressing margins and accelerating fleet migration to hybrid alternatives in European Union markets.
- Ethanol:Biofuel-compatible flex-fuel engines with corrosion-resistant fuel system materials serve Brazilian and Midwestern United States agricultural supply chains.
- Compressed Natural Gas:Spark-ignited methane combustion reduces particulate emissions and fuel costs for urban bus and taxi fleets with accessible pipeline infrastructure.
Diesel retains commercial vehicle penetration. Petrol is climbing the fastest among passenger powertrain investments.
Application:
Customer type segmentation reveals divergent procurement authority structures and lifecycle cost optimization horizons.
- Passenger Vehicles:Light-duty automobiles and SUVs prioritize NVH refinement, packaging efficiency, and transient response characteristics over absolute thermal efficiency. Chinese domestic brands and joint ventures concentrate four-cylinder turbocharged production for this segment, with electrified variants capturing regulatory compliance advantages in coastal megacity license plate restriction zones.
- Commercial Vehicles:Heavy-duty trucks and delivery vans emphasize brake-specific fuel consumption, durability intervals, and residual value retention. Fleet leasing companies in the United States negotiate powertrain specifications at corporate headquarters, bundling extended warranties and telematics-based maintenance into per-mile pricing contracts.
- Agricultural Equipment:Tractor and harvester engines face seasonal load profiles and biofuel compatibility requirements in Brazilian and Midwestern United States farming corridors.
- Marine Applications:Harbor craft and inland waterway vessels confront emerging emissions regulations with limited battery-electric range viability, sustaining demand for compliant diesel and hybrid architectures.
Passenger Vehicles holds installed capacity. Commercial Vehicles is rotating up the share rankings.
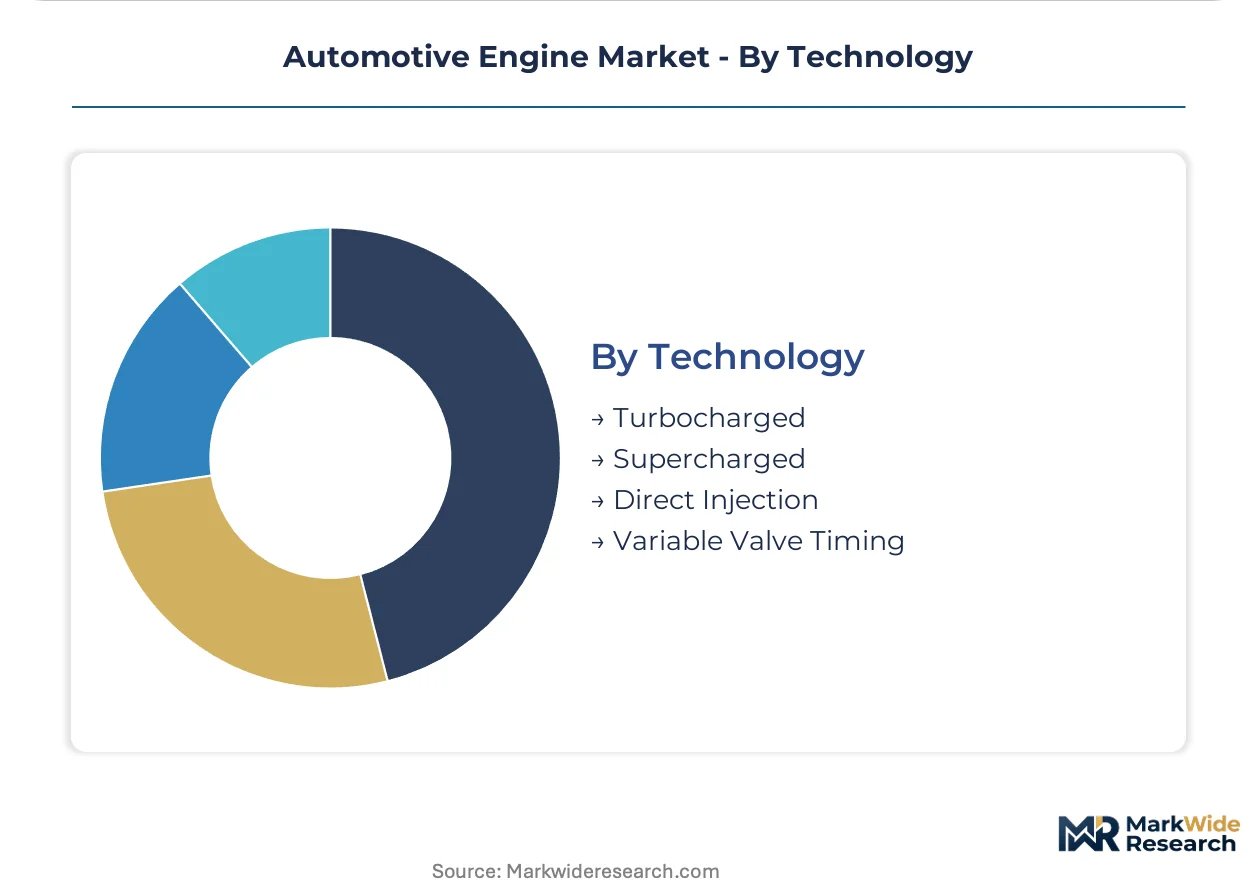
Technology:
Maturity curves separate proven production technologies from emerging calibration-dependent architectures requiring software integration competencies.
- Turbocharged:Exhaust-driven compressor wheels force additional air mass into combustion chambers, enabling downsized engine displacement without power density sacrifice. BorgWarner and Honeywell manufacturing facilities in Mexico and China supply variable-geometry turbochargers for European and North American OEM assembly plants.
- Direct Injection:High-pressure fuel rail systems deliver precise stratified charge formation, improving thermal efficiency and particulate control compared to port injection. Bosch and Denso pump and injector production serves gasoline and diesel architectures across German, Japanese, and South Korean vehicle platforms.
- Supercharged:Belt-driven compressors eliminate turbo lag at the cost of parasitic losses, preserving linear throttle response in performance segments.
- Variable Valve Timing:Cam phasing and lift modulation systems optimize volumetric efficiency across engine speed ranges, with Honda VTEC and BMW Valvetronic architectures representing distinct implementation philosophies.
Direct Injection holds installed capacity. Turbocharged is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys hybrid architectures at manufacturing scale unmatched elsewhere, while Germany and the United States concentrate combustion engineering expertise for premium and commercial segments respectively.
China
Domestic manufacturers accelerate turbocharged downsizing to satisfy MIIT corporate average fuel economy mandates. The Ministry of Industry and Information Technology tightens certification cycles annually. Shanghai and Guangzhou manufacturing clusters integrate starter-generator architectures at volume scale for both domestic consumption and Southeast Asian export markets.
Germany
Premium OEM engineering centers optimize high-performance inline-six and V8 architectures for residual value retention in leasing channels. KBA homologation protocols enforce extended real-driving emissions testing under Euro 7 frameworks. Stuttgart and Munich R&D campuses concentrate powertrain calibration talent for global platform deployment.
United States
Commercial vehicle fleet operators centralize procurement authority at corporate headquarters, bundling extended powertrain warranties into per-mile pricing contracts. EPA Tier 4 standards compel NOx aftertreatment redesign cycles. Detroit and Tennessee assembly corridors sustain heavy-duty diesel and hybrid production for North American logistics networks.
Japan
Hybrid synergy drive expertise anchors electrified powertrain shipments across Asian and North American markets. METI coordinates domestic supplier consolidation to secure rare earth magnet supply chains. Toyota City and Nagoya manufacturing basins export integrated motor-generator systems to Thailand and United States transplant facilities.
India
Mass-market four-cylinder portfolios dominate passenger vehicle procurement where capital efficiency outweighs emissions compliance penalties. PLI scheme production-linked incentives attract localized assembly of hybrid powertrain modules. Chennai and Pune industrial corridors expand engine manufacturing capacity for South Asian and Middle Eastern export destinations.
Automotive Engine Market Key Industry Players
Capability concentration sits with full-line OEMs commanding integrated powertrain architectures; scale advantage sits with diversified manufacturers spanning multiple vehicle categories. The vendor base organizes around three strategic archetypes: vertically integrated premium specialists, mass-market hybrid system integrators, and commercial vehicle durability engineers. Competitive moves center on backward integration into power electronics and geographic expansion into PLI-subsidized manufacturing jurisdictions.
Among German-based premium manufacturers, Mercedes-Benz AG and Bayerische Motoren Werke AG occupy positions defined by high-performance combustion expertise and electrified architecture development. Toyota Motor Corporation represents the mass-market hybrid archetype with manufacturing scale spanning multiple continents. These three entities exemplify distinct competitive postures: Stuttgart-based engineering depth, Munich-centered performance segmentation, and Toyota City-derived integrated production systems.
| Leading Market Players |
|---|
| Mercedes-Benz |
| Audi |
| Toyota |
| Subaru |
| Mazda |
| Honda |
| BMW |
| Renault |
| Ferrari |
| Others |
Cost & Logistics Intelligence
Rare earth magnet supply concentration in Chinese processing facilities determines both the premium tier spreads for hybrid powertrains and the geographic shape of component sourcing networks. Platinum group metal cost escalation for NOx aftertreatment systems simultaneously compresses diesel engine margins and accelerates fleet migration toward electrified architectures.
Pricing Analysis
Long-term offtake contracts dominate procurement between OEM powertrain divisions and Tier 1 suppliers, with spot market exposure limited to platinum group metals and rare earth inputs. Price differentiation rests on certification grade attainment and volume scale, with Euro 7-compliant architectures commanding substantial premiums over baseline configurations. Pricing pressure stems from rhodium and palladium cost spikes that erode margin structures on compliant diesel systems. Commercial vehicle fleet operators exhibit the highest price sensitivity due to per-mile cost optimization mandates, while premium passenger segments absorb cost pass-through with minimal volume elasticity.
Supply Chain Analysis
Upstream feedstock dependencies for permanent magnet materials concentrate in Chinese rare earth processing facilities, with secondary concentration in Japanese magnet alloy production. The supply chain draws from neodymium-iron-boron magnets, high-pressure common-rail injection components, and variable-geometry turbocharger castings as critical inputs. Single-source vulnerability in rare earth magnet supply exposes powertrain manufacturers to geopolitical interruption risk. Distribution runs through consolidated Tier 1 supplier networks serving OEM assembly corridors in Germany, China, and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 and Euro 7 regulatory convergence is accelerating hybrid powertrain disruption, compressing the viable window for pure internal combustion launches and reallocating capital toward electrified architectures.
For Market Incumbents: Insulate core profit pools by securing captive supply of rare earth magnets through METI-coordinated supplier consolidation in Japan. Deepen backward integration into power electronics manufacturing to preserve margin structures as high-voltage inverter assemblies become standard content. Prioritize certification investment for Euro 7 homologation protocols to maintain market access in European Union jurisdictions. For New Entrants and Emerging Players: Marine and off-highway hybridization segments in harbor craft and construction equipment represent the most penetrable entry points, given limited battery-electric viability and emerging emissions regulations. India's PLI-subsidized manufacturing corridors offer localized assembly opportunities for hybrid powertrain modules serving South Asian export markets. Pursue software-defined engine calibration capabilities as a differentiated go-to-market angle enabling subscription-based revenue architectures. For Investors and Strategic Acquirers: Power electronics integration specialists with cross-functional engineering competencies command premium valuation multiples as traditional mechanical engineering workforces face capability gaps. Long-term viability assessment should frame the 5-10 year transition window for hybrid intermediate solutions before battery-electric substitution captures light-duty passenger segments. Monitor municipal zero-emission zone expansion timelines as the critical inflection signal for range-extended hybrid engine demand trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering overhead across hybrid and combustion architectures for OEM powertrain divisions. |
| Battery Supply Agreement | Secures lithium-ion cell allocation for integrated starter-generator systems amid raw material competition. |
| Software-Defined Vehicle Investment | Enables over-the-air engine calibration updates transforming hardware sales toward recurring revenue models. |
| Geographic Manufacturing Footprint | Positions assembly capacity within PLI-subsidized jurisdictions to capture localized procurement incentives. |
| Charging Infrastructure Partnership | Extends hybrid system viability through range-extended architectures serving commercial fleet operators. |
Research Approach
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations converged on the working assumptions underlying demand estimates. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, EPA certification filings, and Euro 7 regulatory drafts. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators to establish volume and value baselines.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from modeled adoption curves for hybrid configurations against regulatory compliance deadlines. Forecast inputs incorporated MIIT fuel consumption certification cycles, KBA homologation protocol changes, and fleet operator procurement centralization trends.
Practitioners should monitor rare earth export quota adjustments, platinum group metal price volatility, and municipal zero-emission zone designations for early signals of forecast revision. Quarterly review of OEM powertrain warranty extension announcements and PLI scheme beneficiary lists is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Active Purge Pump Market
Powertrain
Brazil Automotive Market
Powertrain
Torque Limiter Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Automotive Half Shaft Market
Powertrain
Global Automotive GD Injector Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
High Speed Engine Market
Powertrain
South America Internal Combustion Engines Market
Powertrain
Automotive Hydraulic Lash Adjuster Market
Powertrain
Transmission Shift Actuator Market
Powertrain
Global Automotive Tappet Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Automotive Power Steering Pump Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Automotive Conversion Kit Market