
 Crate Engines Market | 2026-2036
Crate Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Crate Engines Market Intelligence
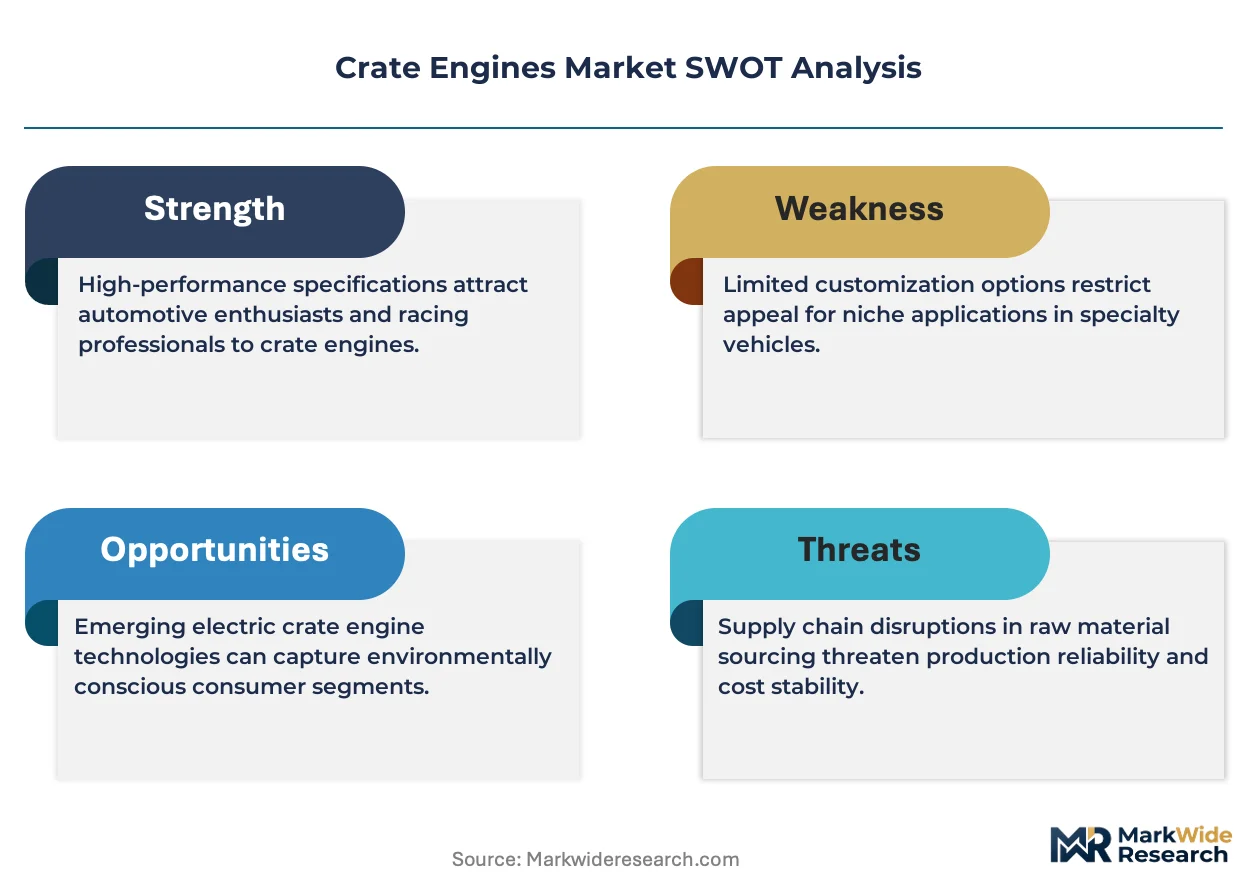
Aluminum block construction is realigning cost structures across the crate engine supply base as foundries convert capacity from traditional cast iron. General Motors (Chevrolet Performance) leverages its captive aluminum casting network to control billet supply for LS-series crate assemblies. Ford Motor Company sustains volume leadership through its Coyote and Godzilla modular platforms sold via dealer and direct channels. Edelbrock, LLC differentiates through specialized small-block and big-block offerings targeting the restoration segment.
A crate engine is a fully assembled, ready-to-install internal combustion engine delivered in a shipping crate, typically featuring pre-machined cylinder bores, fitted crankshafts, and calibrated fuel or ignition systems rated by horsepower and torque output for vehicle replacement or enhancement. Carbureted configurations retain share among period-correct restoration builds where originality commands price premiums, while fuel-injected and supercharged variants capture expansion in custom builds and performance upgrades seeking drivability and emissions compliance. V8 architectures dominate value pools given their install base in muscle car restoration and light truck applications, though inline-6 assemblies gain traction in restomod projects balancing torque delivery with packaging efficiency.
The EPA enforces emissions certification for crate engines sold as complete assemblies, while California Air Resources Board executive orders create a bifurcated compliance landscape separating 50-state-legal products from race-only configurations. NHTSA safety standards and FMVSS provisions further constrain how crate engines integrate into vehicle modification workflows. Stakeholders must monitor regulatory divergence between federal and state-level certification pathways when allocating product development resources.
Market Dynamics
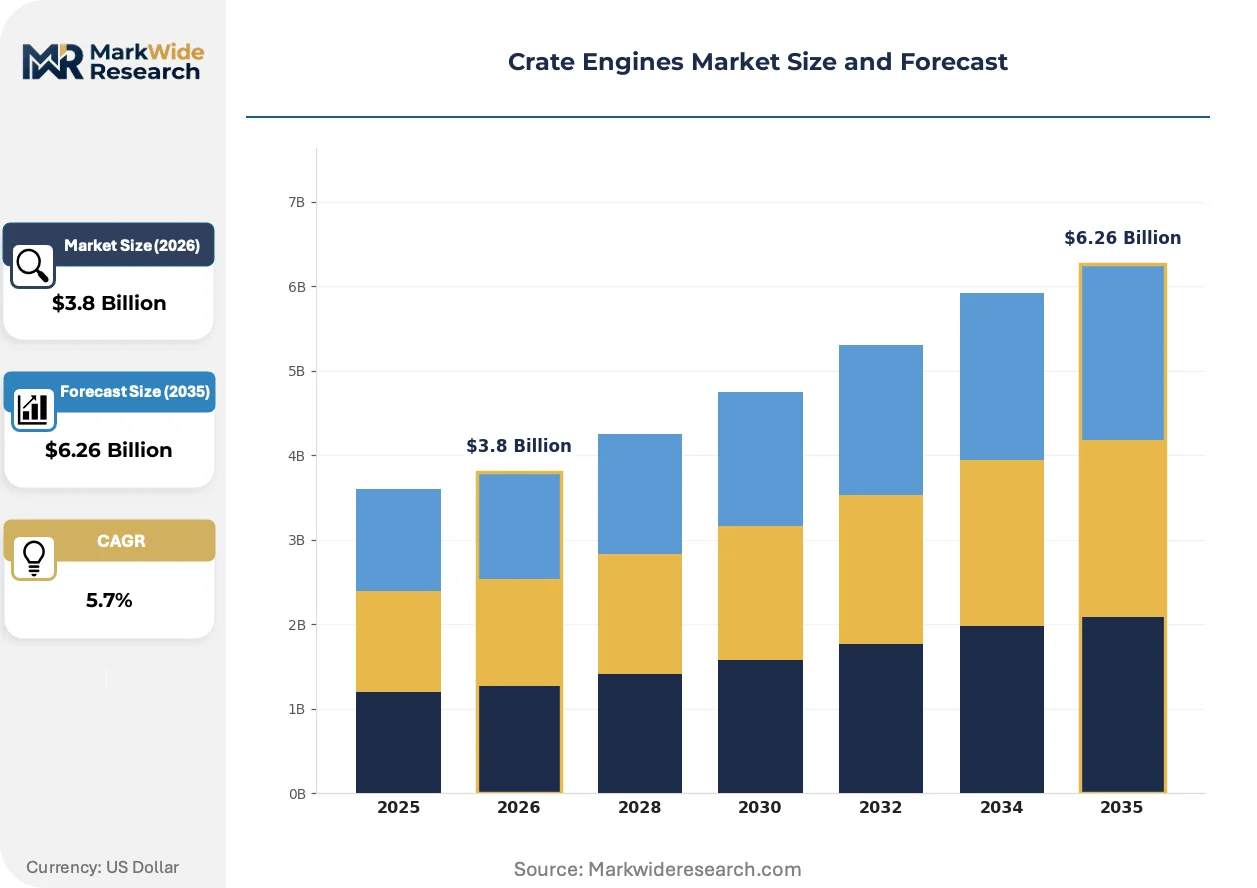
Aluminum block foundry conversions are compressing traditional cast iron supply chains while EPA and CARB certification bifurcation forces dual-track product development strategies across the crate engine supply base.
Growth Catalysts
- CARB Executive Order pathway:California Air Resources Board rulings create a premium tier for 50-state-legal crate assemblies, commanding price premiums from builders seeking registration compliance.
- Fuel injection retrofit demand:Restoration shops in Texas and California are specifying EFI conversions for drivability improvements in classic truck and muscle car rebuilds.
- Light truck V8 install base:The persistent fleet of GMT800 and Ford F-Series platforms sustains replacement engine demand through independent repair channels and enthusiast builders.
Market Restraints
- Aluminum billet supply concentration:Domestic foundry capacity constraints limit block casting availability, forcing lead time extensions for high-performance assemblies.
- EPA certification cost burden:Complete assembly emissions testing requirements impose fixed compliance costs that disadvantage low-volume specialty builders.
- Electric powertrain substitution:EV conversion kits for classic platforms, while nascent, capture regulatory attention and builder mindshare in coastal metropolitan markets.
Strategic Opportunities
- Restomod inline-6 expansion:Packaging-efficient torque delivery from modern inline-6 architectures opens build opportunities in compact sport coupe and vintage 4x4 segments underserved by V8 dimensions.
- Direct-to-builder digital channels:Bypassing traditional speed shop distribution, manufacturers can capture margin and configuration data through online spec-build portals.
- IRA clean vehicle credit spillover:Federal electric vehicle incentives indirectly stimulate ICE crate demand by preserving older vehicles as hobby assets rather than daily drivers.
Industry Challenges
- Calibration engineering scarcity:EFI tuning expertise for non-OEM engine management systems concentrates among a shrinking cohort of specialists, constraining fuel-injected product rollout.
- Dual certification timeline compression:Parallel EPA and CARB approval processes extend product launch windows, freezing development capital for 18-24 month cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crate Engines Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
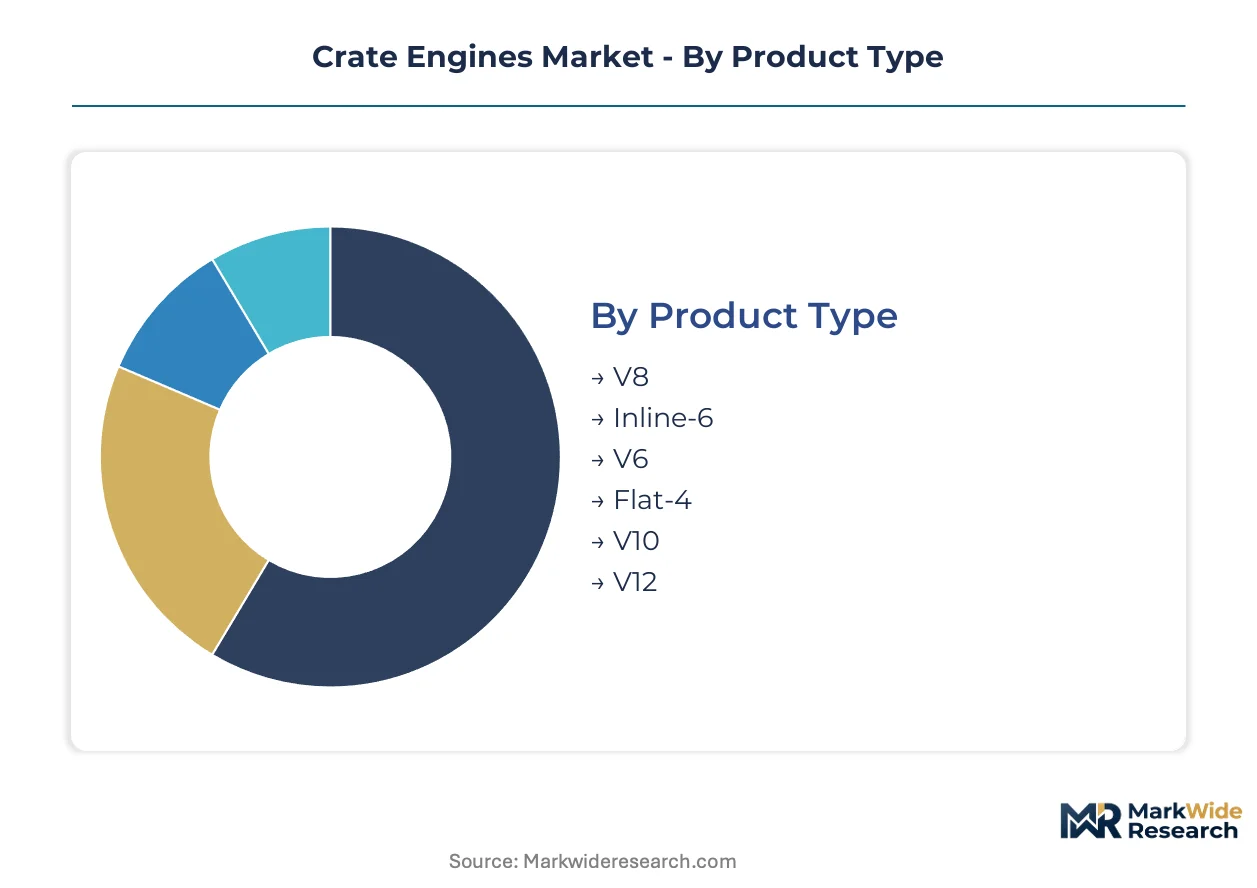
| Segmentation | Product Type: V8, Inline-6, V6, Flat-4, V10, V12 Application: Restoration Projects, Custom Builds, Performance Upgrades, Marine Craft, Agricultural Machinery, Motorcycles End User: Dealerships, Vehicle Assemblers, Aftermarket Providers, Tier-1 Suppliers Technology: Carbureted, Fuel Injected, Supercharged, Turbocharged, Hybrid, Electric Assist |
| Companies Covered | Ford Motor Company, General Motors (Chevrolet Performance), Stellantis (Mopar), Edelbrock, LLC, Roush Performance, Blueprint Engines, ATK High Performance Engines, Jasper Engines & Transmissions, JEGS High Performance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crate Engines Market Strategic Shifts & Innovations
Digital configuration tools and modular engine architectures are dissolving traditional boundaries between OEM parts divisions and aftermarket specialists, reshaping how builders specify and source powertrain assemblies.
Sealed, long-block crate configurations with integrated engine management are decentralizing the traditional machine shop role in engine builds. Restoration specialists in Michigan and Texas are specifying these turn-key assemblies to compress project timelines from months to weeks. The shift compresses value capture toward foundries and electronics suppliers while marginalizing independent engine builders.
EPA enforcement of emissions certification for complete assemblies is tightening product categorization between street-legal and competition-only offerings. Manufacturers now face binary compliance pathways that force portfolio segmentation rather than gradient positioning. California builders bear the highest compliance burden, driving concentration of 50-state-legal product development resources toward CARB-precedent designs.
Builder preference for documented provenance and dyno-verified output is shifting specification authority from retail counter staff to online research and peer forum validation. Traditional speed shop channels lose influence as YouTube build documentation and direct manufacturer technical support replace counter expertise. This pattern concentrates most visibly in the 25-45 age demographic entering the restoration hobby through digitally-native research behaviors.
Crate Engines Market Segmentation
Crate engine buyers segment sharply between period-correct restoration purists and performance-focused builders, creating divergent specification requirements across product architectures. Understanding these fault lines reveals where aluminum casting investments and calibration engineering resources generate returns.
Product Type:
V8 architectures command premium positioning through install base dominance, while inline-6 variants exploit packaging efficiency gaps.
- V8:Dual-plane and single-plane intake configurations anchor muscle car restoration and light truck replacement demand. Texas and California build clusters sustain volume for LS-series, Coyote, and Godzilla platforms where CARB certification commands price premiums.
- Inline-6:Longitudinal packaging efficiency suits restomod sport coupes and vintage 4x4 conversions where hood length constraints exclude V8 dimensions. Michigan specialists specify these for torque-rich drivability in Jeep and Toyota Land Cruiser builds.
- V6:Compact transverse and longitudinal applications serve import restoration and space-constrained engine bays.
- Flat-4:Air-cooled and water-cooled variants target Porsche and Subaru enthusiast communities with specific mounting geometries.
- V10:Limited production runs serve exotic and motorsport-homologation builds with extreme power density requirements.
- V12:Ultra-premium tier for luxury marque restoration and bespoke coachwork projects with minimal volume scale.
Today's leader: V8. Tomorrow's challenger: Inline-6.
Application:
Project type determines certification burden and margin structure across the builder base.
- Restoration Projects:Period-correct specifications prioritize carbureted configurations where originality validates price premiums. EPA and CARB bifurcation forces builders to choose between 50-state legality and competition-only categorization.
- Custom Builds:Fuel-injected and supercharged variants dominate this segment where drivability and emissions compliance enable registration in California and other restricted jurisdictions.
- Performance Upgrades:Dyno-verified output documentation shifts specification authority to online research and peer validation rather than retail counter expertise.
- Marine Craft:Salt-water corrosion resistance and continuous-duty cooling requirements differentiate marine-spec assemblies from automotive counterparts.
- Agricultural Machinery:Torque-biased cam profiles and extended service intervals suit farm equipment replacement cycles.
- Motorcycles:Ultra-compact V-twin and inline-4 architectures serve custom bike builders with severe weight and space constraints.
Restoration Projects currently generate the highest margin per unit. Custom Builds are expanding most quickly as EFI retrofit demand accelerates.
End User:
Channel structure determines configuration authority and technical support expectations.
- Dealerships:OEM-backed warranty coverage and factory calibration support justify price premiums for risk-averse builders seeking installation confidence.
- Vehicle Assemblers:Low-volume manufacturers and kit car producers require 50-state certification to maintain registration pathway clarity across distribution territories.
- Aftermarket Providers:Speed shops and restoration specialists compress project timelines through sealed long-block specifications with integrated engine management.
- Tier-1 Suppliers:Captive foundry relationships and volume purchasing power shape cost structures for high-performance aluminum block sourcing.
Aftermarket Providers currently capture the highest configuration velocity. Dealerships are gaining share fastest through direct-to-builder digital channels.
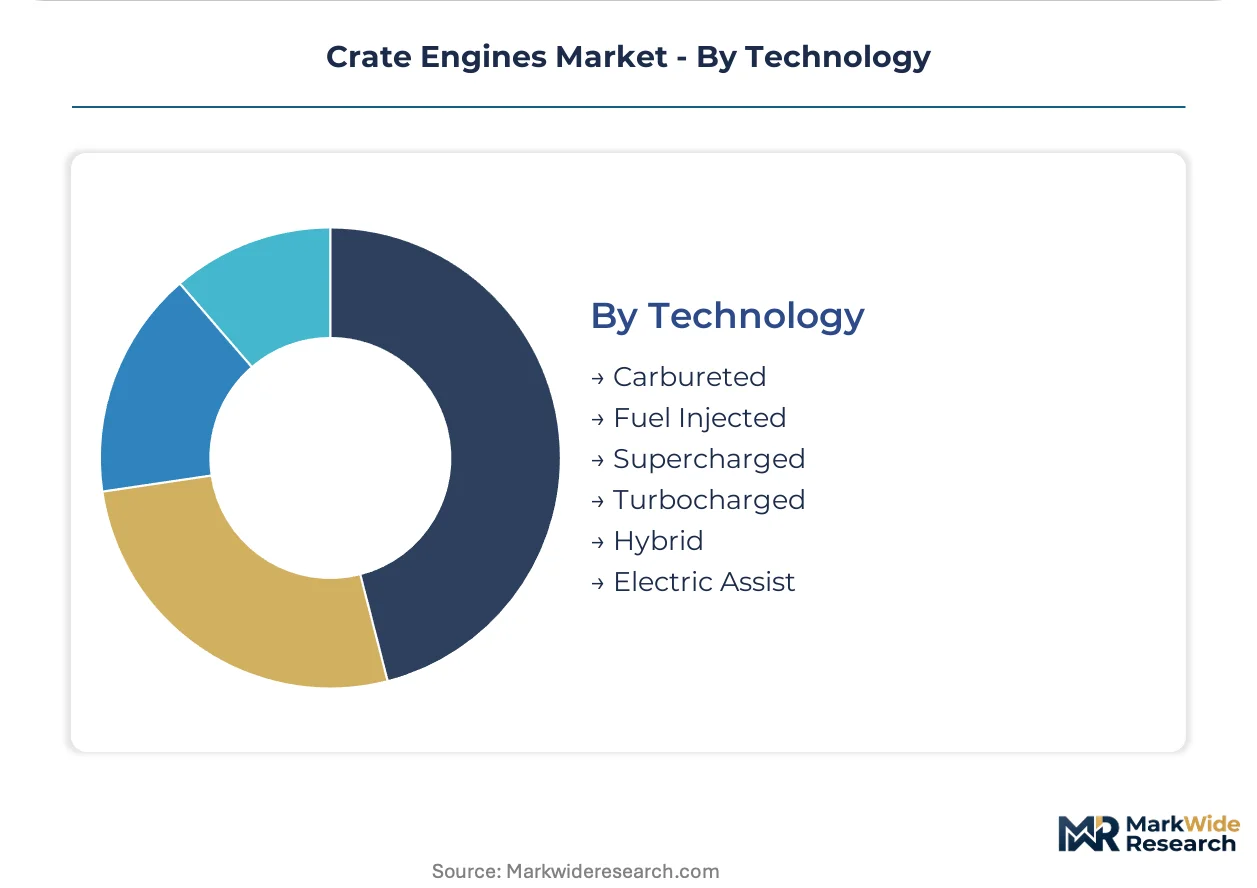
Technology:
Fuel delivery architecture separates street-legal from competition-only product tiers.
- Carbureted:Mechanical simplicity and period authenticity retain share among restoration purists where originality commands price premiums and regulatory scrutiny is minimized.
- Fuel Injected:Sequential port and direct injection configurations enable CARB Executive Order compliance for California registration while improving cold-start drivability and altitude compensation.
- Supercharged:Positive displacement and centrifugal blower integrations require specialized calibration engineering that concentrates among a shrinking cohort of EFI tuning specialists.
- Turbocharged:Boost-controlled architectures offer packaging efficiency advantages over supercharged alternatives in space-constrained engine bays.
- Hybrid:Mild-hybrid assist systems explore torque-fill applications for large-displacement builds facing emissions pressure.
- Electric Assist:Belt-driven starter-generator integrations represent nascent technology for classic platform electrification without full powertrain substitution.
Fuel Injected dominates current volume. Supercharged offers the steepest expansion trajectory as forced-induction drivability improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas build clusters anchor demand concentration for V8 crate assemblies serving light truck restoration and muscle car projects. EPA emissions certification and CARB Executive Order pathways create divergent compliance requirements across state lines. Foundry capacity constraints in domestic aluminum supply chains extend lead times for high-performance blocks.
United States
Texas, California, and Michigan build clusters sustain the highest configuration velocity for LS-series, Coyote, and Godzilla platforms. EPA enforcement of complete assembly emissions testing imposes fixed compliance costs that disadvantage low-volume specialty builders. Restoration specialists in Dallas-Fort Worth specify sealed long-block assemblies with integrated engine management to compress project timelines.
Germany
Porsche and BMW enthusiast communities drive demand for air-cooled flat-6 and inline-6 crate configurations in restomod applications. KBA type-approval requirements for engine replacements create regulatory friction for non-EU origin assemblies. Stuttgart-area specialists concentrate on documented provenance and dyno-verified output for classic 911 builds.
Japan
Compact sport coupe restoration projects favor inline-6 architectures from Toyota and Nissan heritage platforms. METI fuel economy standards and exhaust emissions regulations constrain aftermarket engine certification pathways. Osaka-based builders specify packaging-efficient torque delivery for vintage 4x4 conversions where hood length excludes V8 dimensions.
United Kingdom
Classic Ford and Vauxhall restoration communities sustain demand for small-block and inline-4 crate configurations. DVLA registration compliance for engine-swapped vehicles requires documented emissions conformity or competition-only categorization. Midlands-based speed shops source carbureted assemblies for period-correct builds where originality validates price premiums.
Australia
Holden Commodore and Ford Falcon restoration projects drive V8 crate engine demand through independent repair channels. TGA does not regulate automotive powertrain assemblies, though state-level vehicle modification codes constrain installation workflows. Melbourne and Sydney build clusters concentrate EFI retrofit demand for drivability improvements in classic ute rebuilds.
Crate Engines Market Key Industry Players
Global majors compete with regional champions across certification pathways and foundry access. OEM-backed divisions leverage captive aluminum casting networks and factory calibration support to justify price premiums, while independent specialists compress timelines through sealed long-block specifications. Three archetypes dominate: integrated automaker performance divisions, dedicated engine builders with foundry relationships, and speed shop distributors curating multi-brand portfolios. Competitive moves concentrate on dual-track EPA and CARB certification investments, plus direct-to-builder digital channel expansion bypassing traditional retail counter distribution.
Within the OEM performance division tier, General Motors (Chevrolet Performance) and Ford Motor Company exemplify scale-driven positioning through modular platform standardization and dealer network reach. Edelbrock, LLC occupies a specialist position representing the independent builder archetype focused on heritage small-block and big-block architectures. These three entities anchor the competitive structure, with automaker divisions controlling billet supply chains and certification resources while independents capture restoration purist segments through period-authentic specifications.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors (Chevrolet Performance) |
| Stellantis (Mopar) |
| Edelbrock, LLC |
| Roush Performance |
| Blueprint Engines |
| ATK High Performance Engines |
| Jasper Engines & Transmissions |
| JEGS High Performance |
| Others |
Cost & Logistics Intelligence
Captive aluminum casting networks at General Motors and Ford anchor both supply security and pricing power for high-performance crate assemblies. These foundry investments insulate OEM divisions from billet supply shocks while forcing independent builders to absorb spot-market volatility in block sourcing.
Pricing Analysis
Aluminum billet cost pass-through dominates pricing dynamics across the crate engine supply base. Three-tier pricing structure across 50-state CARB-certified, EPA-compliant, and competition-only configurations separates street-legal premiums from race-use discounting. Cost compression in cast iron long-blocks is intensifying because foundry capacity is migrating to aluminum. Independent restoration specialists exhibit highest price sensitivity, while OEM-backed dealer channels absorb premiums for warranty coverage.
Supply Chain Analysis
Domestic-content mandates under EPA assembly certification requirements reshape sourcing toward US-based foundry operations. Raw material flows draw from domestic aluminum smelters, Mexican machining facilities, and Canadian billet suppliers. Single-source vulnerability concentrates in high-performance aluminum block casting where capacity conversion lags demand. Distribution runs through direct-to-builder digital portals, dealer networks, and traditional speed shop channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in crate engines rests on aluminum casting cost-down curves and CARB-certified premium tier capture. Foundry automation and EFI calibration standardization compress production costs while 50-state legality commands price premiums.
For Market Incumbents: Hedge against EV conversion kit substitution by accelerating sealed long-block rollout with integrated engine management. Deepen captive foundry control over aluminum billet supply to compress lead times. Prioritize dual-track EPA and CARB certification investment to lock in 50-state registration pathways before regulatory divergence widens. For New Entrants and Emerging Players: Launch via direct-to-builder digital spec-build portals bypassing traditional speed shop distribution. Target restomod inline-6 segments in Michigan and Texas where V8 packaging constraints create white space. Exploit calibration engineering scarcity by partnering with EFI tuning specialists for fuel-injected product rollout. For Investors and Strategic Acquirers: Roll-up economics work for regional foundry-dependent engine builders because EPA certification fixed costs disadvantage sub-scale operators. Five-to-ten year viability hinges on aluminum casting capacity access and CARB Executive Order portfolio depth. Watch EPA enforcement intensity on complete assembly emissions testing as inflection indicator for compliance cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Parallel EPA and CARB approval processes secure 50-state market access for LS-series and Coyote platforms. |
| Foundry Capacity Expansion | Captive aluminum casting investments at Chevrolet Performance insulate billet supply from spot-market volatility. |
| Direct-to-Builder Digital Launch | Online spec-build portals capture margin and configuration data from digitally-native 25-45 demographic entrants. |
| EFI Calibration Partnership | Collaboration with shrinking EFI tuning specialist cohort accelerates fuel-injected product rollout timelines. |
| Inline-6 Architecture Development | Packaging-efficient torque delivery opens restomod opportunities in Jeep and vintage 4x4 segments. |
Research Approach
Bottom-up restoration project modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with crate engine product managers, EPA compliance officers, speed shop owners, and EFI calibration specialists combined with secondary validation from EPA certification databases, CARB Executive Order filings, and aluminum trade association production statistics. Triangulation across stakeholder inputs and documentary sources anchors volume and value estimates.
Historical trendline analysis of build cluster activity in Texas, California, and Michigan established baseline demand patterns across the projection horizon. The forecast framework segments by engine architecture, fuel delivery technology, certification pathway, and end-user channel. CAGRs derive from build rate projections, foundry capacity expansion schedules, and regulatory compliance cost trajectories. Aluminum billet price curves and CARB certification timeline data feed directly into margin modeling.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA enforcement escalation or accelerated EV conversion kit adoption. Projections reflect assumptions regarding regulatory stability, foundry conversion rates, and builder demographic continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
United States Electro Hydraulic Power Steering Market
Powertrain
Automotive Power Steering Pump Market
Powertrain
Axle Shaft Market
Powertrain
Automotive Variable Discharge Oil Pump Market
Powertrain
Automotive Chain Tensioners Market
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
Automotive Camless Engine Market
Powertrain
Power Transmission Gearbox Market
Powertrain
Crankshaft Oil Market
Powertrain
Japan Automotive Engine Oils Market
Powertrain
EV Powertrain Market
Powertrain
Modular Belt Drive Market
Powertrain
Engine Tuner Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Japan Electrically Powered Hydraulic Steering Market