
 Drivetrain Vibration and Condition Monitoring Sensor Systems Market | 2026-2036
Drivetrain Vibration and Condition Monitoring Sensor Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Drivetrain Vibration and Condition Monitoring Sensor Systems Market Insights
Sensor-as-a-service and predictive analytics subscription models is shifting how condition monitoring value gets captured in industrial contracts. Bosch leverages its automotive sensor heritage to compete in high-channel-count drivetrain diagnostics. SKF anchors its position through integrated bearing-sensor systems that combine hardware with cloud-based vibration analysis. ABB extends its electrification portfolio into marine and wind applications with specialized monitoring packages.
Drivetrain vibration and condition monitoring sensor systems comprise electromechanical transducers that convert mechanical oscillation into electrical signals, typically operating across frequency ranges from sub-Hertz gearbox modulation to ultrasonic bearing defect detection, with piezoelectric and MEMS technologies dominating cost-sensitive deployments. These systems enable predictive maintenance by detecting incipient faults in rotating machinery before catastrophic failure occurs. Acceleration sensors and eddy current proximity probes together occupy the largest share of installed base revenue, while fiber optic sensing is gaining traction in high-electromagnetic-interference environments such as rail and aerospace. The wind turbine application segment leads absolute unit demand, though marine propulsion monitoring commands premium pricing due to classification society certification requirements.
The EU Machinery Directive and ISO 13374 condition monitoring standards shape product design and market access requirements across European manufacturing and energy sectors. In the US, OSHA machinery safety regulations and FAA airworthiness directives for rotorcraft drivetrains create compliance-driven replacement cycles. China's GB standards and dual carbon goals are pushing domestic turbine manufacturers toward integrated condition monitoring. Stakeholders must evaluate whether to build predictive analytics capabilities in-house or partner with specialized software providers as hardware commoditization pressures intensify.
Market Dynamics
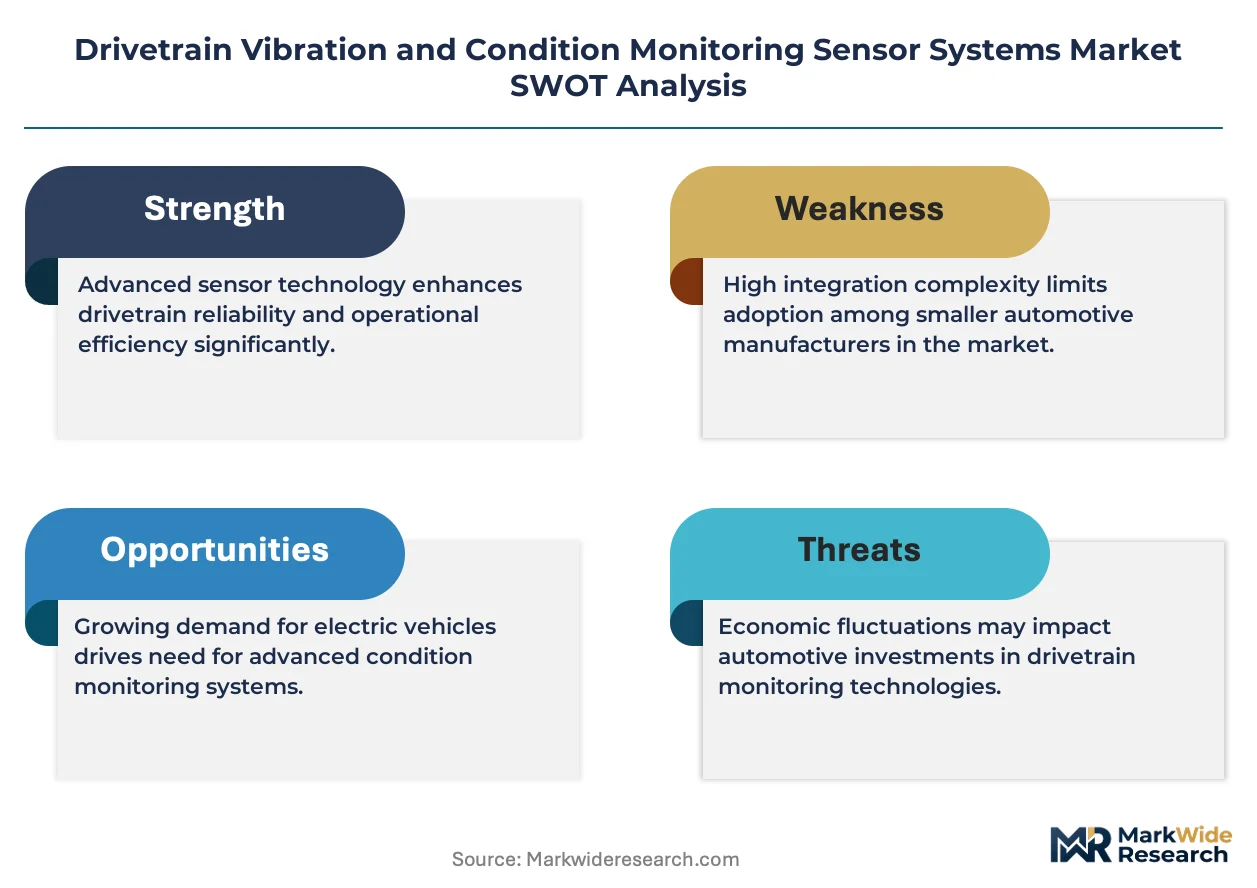
The EU F-Gas Regulation and ISO 13374 standards are forcing hardware suppliers to bundle predictive analytics or cede margin to software specialists. This regulatory-technical squeeze is redistributing value capture from sensor manufacturers to integrated platform providers.
Growth Catalysts
- Wind turbine fleet expansion:Blade and gearbox failures drive unplanned maintenance costs exceeding $300,000 per incident. Operators in Germany and Denmark now mandate continuous drivetrain monitoring for offshore installations.
- REACH compliance deadlines:Phased restrictions on hazardous substances in industrial electronics accelerate replacement of legacy sensor systems with RoHS-compliant alternatives across European manufacturing.
- MEMS cost curves:Silicon microfabrication yields now support sub-$50 vibration sensors with sufficient bandwidth for gearbox defect detection, opening mid-market wind and rail applications previously served by piezoelectric alternatives.
Market Restraints
- Piezoelectric ceramic supply concentration:High-sensitivity accelerometer manufacturing depends on PZT ceramic suppliers concentrated in China and Japan, exposing procurement to export control volatility.
- Marine certification timelines:Lloyd's Register and DNV classification society approvals for propulsion monitoring systems extend 18-24 months, freezing product iteration cycles.
- Optical encoder substitution:Magnetic and capacitive position sensing is displacing eddy current proximity probes in cost-sensitive industrial motor applications.
Strategic Opportunities
- India wind repowering:The country's CEA mandates turbine upgrades at aging wind farms, creating retrofit demand for integrated condition monitoring where penetration currently lags below 15%.
- Sensor-as-a-service models:Subscription-based vibration analytics with guaranteed uptime SLAs is capturing multi-year contracts from capital-constrained fleet operators.
- Fiber optic convergence:Interferometric sensing combined with silicon photonics enables immunity to electromagnetic interference in electrified rail and aerospace nacelles.
Industry Challenges
- Vibration analyst talent scarcity:ISO 18436-2 certified personnel for interpreting spectral data remain concentrated in Germany and the US, constraining service scaling in emerging markets.
- Legacy SCADA integration:Proprietary protocols in installed wind turbine fleets require custom gateway development, inflating deployment costs and extending project timelines.
- Patent thickets around MEMS resonant structures:Broad university-held IP in piezoelectric-on-silicon architectures complicates freedom-to-operate assessments for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drivetrain Vibration and Condition Monitoring Sensor Systems Market |
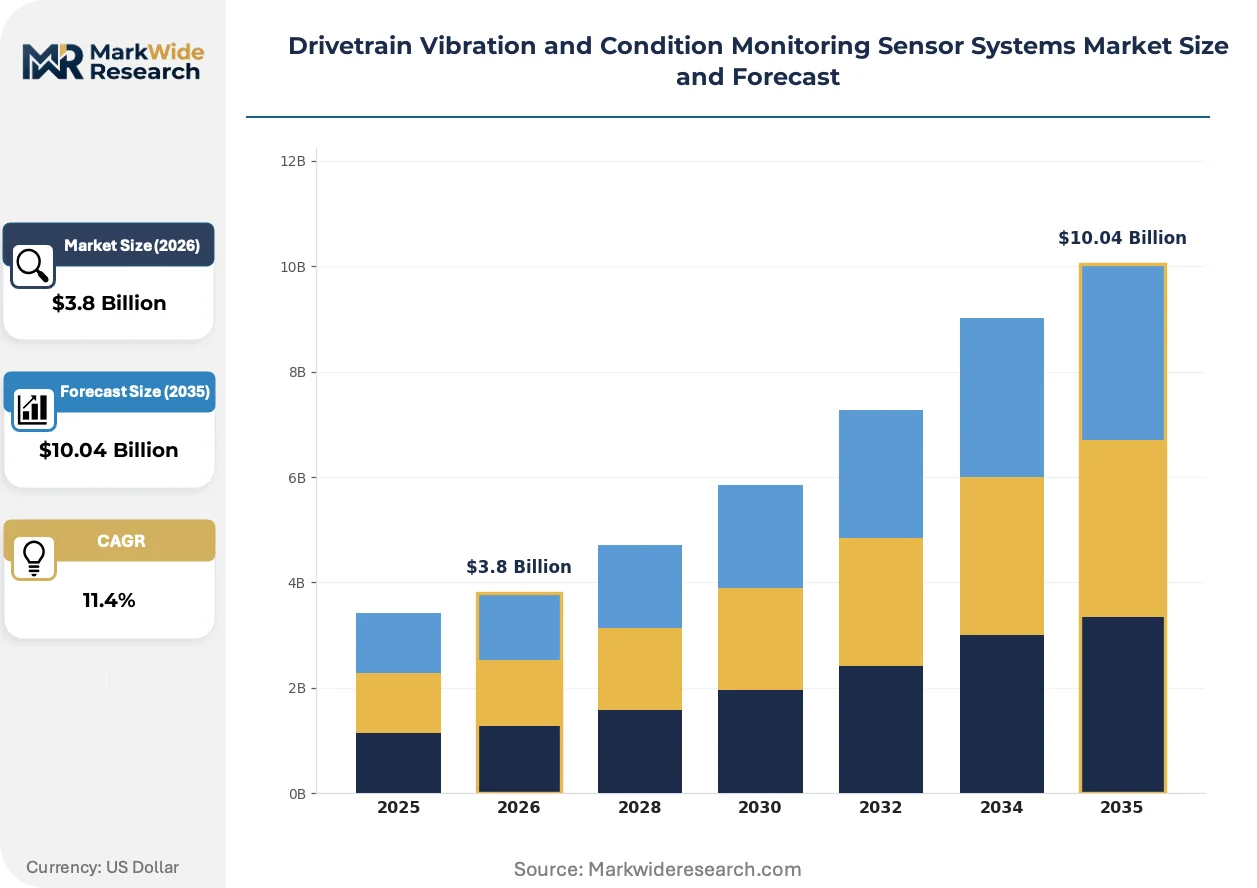
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acceleration Sensors, Velocity Sensors, Displacement Sensors, Proximity Probes, Ultrasonic Sensors Technology: Piezoelectric, Capacitive, Fiber Optic, MEMS, Eddy Current Application: Wind Turbines, Marine Propulsion, Aerospace Drivetrains, Rail Locomotives, Industrial Machinery End User: Energy Producers, Shipbuilders, Aircraft Manufacturers, Railway Operators, Manufacturing Plants |
| Companies Covered | Bosch, Continental, AVL List, Denso, ABB, Regal Rexnord, Baker Hughes, Caterpillar, SKF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drivetrain Vibration and Condition Monitoring Sensor Systems Market Trends and Innovations
Digital twin architectures are absorbing condition monitoring data streams into real-time drivetrain models. This convergence of physics-based simulation with operational sensor feeds is compressing fault detection windows and reshaping competitive differentiation.
Silicon carbide MEMS accelerometers are absorbing market share in high-temperature gearbox applications previously reserved for bulk piezoelectric devices. Wind turbine OEMs in Germany and Spain now specify SiC-based sensors for main bearing monitoring above 150°C. The technology is absorbing price premiums by eliminating charge amplifiers and simplifying cable routing.
Europe's F-Gas Regulation is accelerating refrigerant leak detection integration into drivetrain thermal management systems. The policy mandates sensor redundancy for systems above 50kW cooling capacity, effective 2027. Marine propulsion manufacturers are responding by specifying combined vibration-temperature-gas monitoring packages to streamline certification.
Buyers are unbundling hardware procurement from analytics subscriptions, forcing sensor suppliers to interoperate with third-party cloud platforms. Wind farm operators in Texas and Iowa now require open API access to raw vibration data. This pattern is most visible in North American independent power producer segments where in-house data science teams demand portability.
Drivetrain Vibration and Condition Monitoring Sensor Systems Market Segmentation
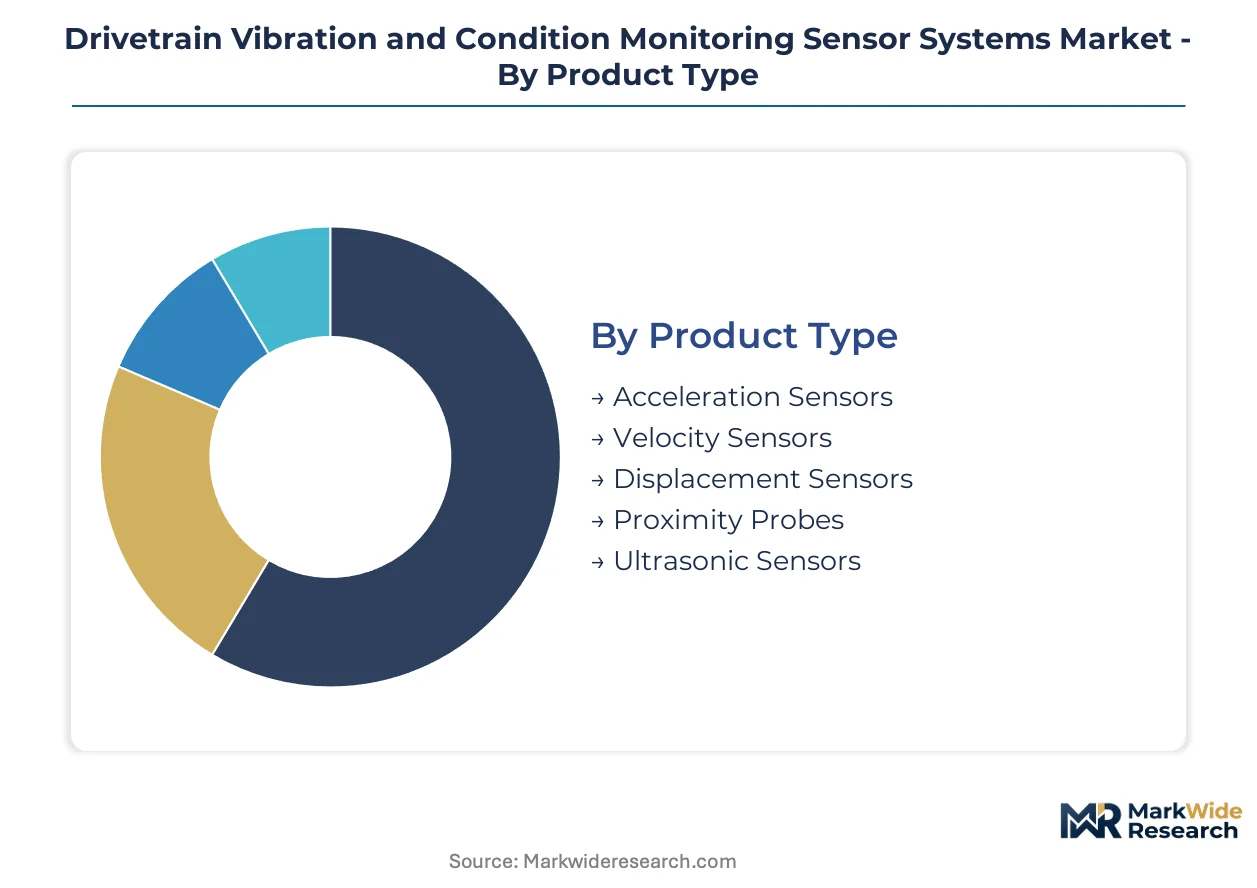
Drivetrain monitoring architectures demand sensor configurations matched to failure modes: bearing defect frequencies require accelerometers, shaft misalignment demands proximity probes, and thermal runaway necessitates integrated temperature sensing. Segmentation discipline separates commodity hardware from premium integrated systems where predictive analytics capture recurring revenue.
Product Type:
Supply concentration in piezoelectric ceramic manufacturing elevates acceleration sensor procurement risk, while MEMS foundry capacity expansion is redistributing bargaining power toward silicon-based alternatives.
- Acceleration Sensors:Piezoelectric and MEMS transducers dominate, converting mechanical vibration into charge or voltage signals across 0.5 Hz to 10 kHz bandwidth. Wind turbine main bearing monitoring in Germany and Denmark absorbs the highest channel densities, with offshore installations mandating redundant triaxial configurations per nacelle.
- Proximity Probes:Eddy current displacement sensors measure shaft radial position and eccentricity with sub-micron precision. Marine propulsion manufacturers in Norway and Japan specify these for crankshaft alignment verification, though magnetic encoder substitution is eroding share in cost-sensitive industrial motor applications.
- Velocity Sensors:Moving-coil and piezoelectric velocity transducers integrate acceleration signals for low-frequency gearbox modulation analysis. Seismic-grade units serve hydroelectric turbine monitoring.
- Displacement Sensors:Laser triangulation and capacitive technologies capture rotor-stator gap variations in large turbomachinery. Hydroelectric generators in Canada deploy these for wicket gate positioning.
- Ultrasonic Sensors:High-frequency acoustic emission detection identifies incipient bearing raceway cracking before vibration amplitude rises. Aerospace MRO facilities in France and the US deploy these for helicopter gearbox health assessment.
Today's leader: Acceleration Sensors. Tomorrow's challenger: Ultrasonic Sensors.
Technology:
Cost tier stratification separates mature piezoelectric installations from emerging MEMS penetration in mid-market wind and rail applications.
- Piezoelectric:Lead zirconate titanate (PZT) ceramics deliver the highest sensitivity and temperature tolerance for demanding environments. Supply concentration among Japanese and Chinese ceramic manufacturers exposes procurement to export control volatility, constraining European sensor OEMs.
- MEMS:Silicon microfabrication yields now support sub-$50 vibration sensors with sufficient bandwidth for gearbox defect detection. India's CEA-mandated wind repowering program is absorbing volume as domestic turbine manufacturers retrofit aging fleets with cost-optimized monitoring.
- Fiber Optic:Interferometric sensing provides immunity to electromagnetic interference in electrified rail and aerospace nacelles. Silicon photonics integration is compressing package sizes.
- Eddy Current:Non-contact position sensing for rotating shafts remains essential for marine classification society certification, though Lloyd's Register approval timelines extend 18-24 months.
- Capacitive:Microelectromechanical displacement sensing competes in clean industrial environments where contamination exclusion is manageable.
Piezoelectric anchors current revenue. MEMS is climbing the fastest.
Application:
Volume concentration in wind turbine installations contrasts with premium pricing commanded by marine propulsion certification requirements.
- Wind Turbines:Onshore and offshore installations generate absolute unit demand leadership, with blade and gearbox failures driving unplanned maintenance costs exceeding $300,000 per incident. German and Danish operators now mandate continuous drivetrain monitoring for offshore arrays.
- Marine Propulsion:Classification society certification from DNV and Lloyd's Register creates compliance-driven replacement cycles and pricing premiums. Dual-fuel engine proliferation is expanding sensor channel counts for combustion monitoring integration.
- Aerospace Drivetrains:FAA airworthiness directives for rotorcraft gearboxes mandate specific inspection intervals, with health monitoring systems qualifying for extended maintenance credits.
- Rail Locomotives:Traction motor and gearbox monitoring for predictive maintenance is expanding with electrified fleet deployments across European corridors.
- Industrial Machinery:Pulp and paper, cement, and steel processing equipment monitoring follows ISO 13374 implementation for insurance premium reduction.
Wind Turbines command volume. Marine Propulsion captures margin.
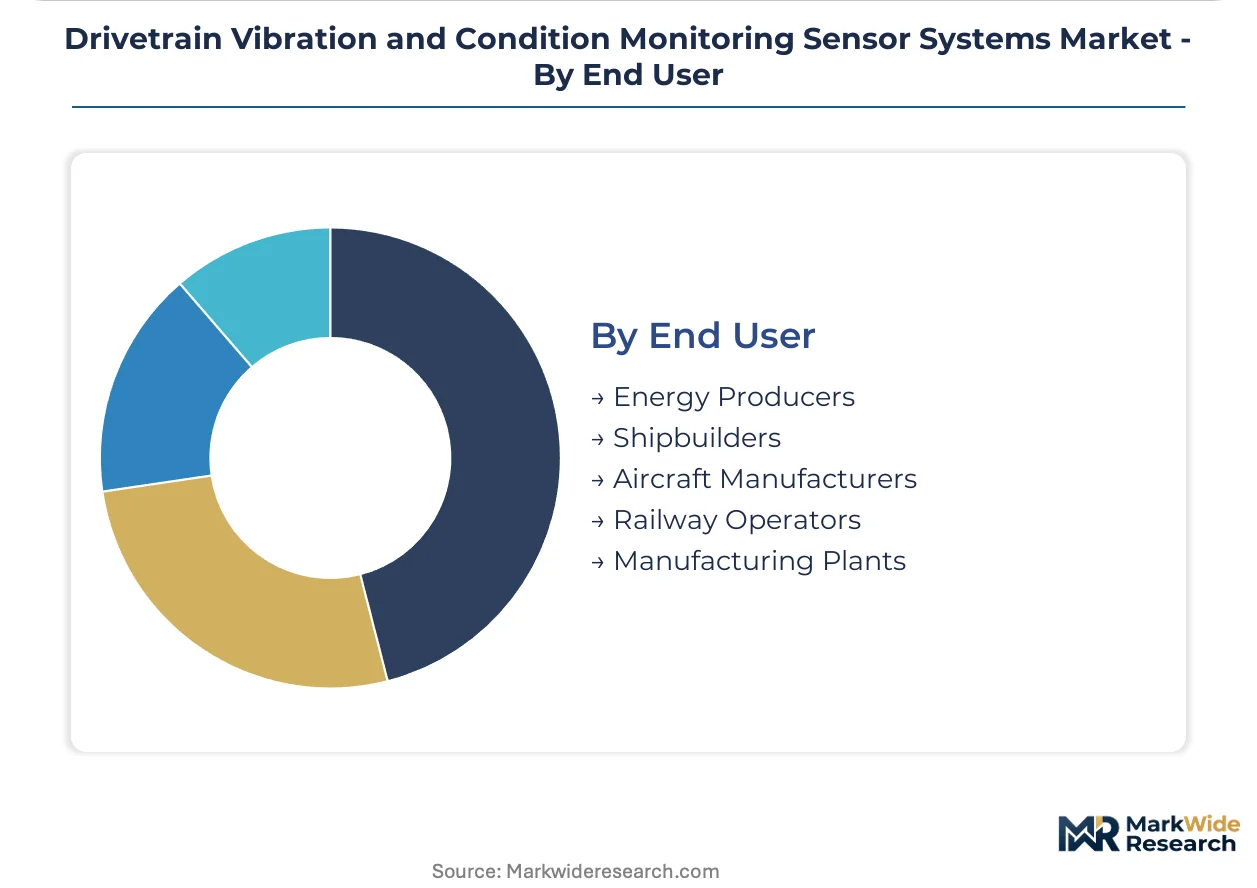
End User:
Customer type determines procurement modality: energy producers favor sensor-as-a-service subscriptions, while shipbuilders demand integrated platform packages.
- Energy Producers:Independent power producers in Texas and Iowa are unbundling hardware from analytics, requiring open API access to raw vibration data for in-house data science teams.
- Shipbuilders:Korean and Chinese yards specify combined vibration-temperature-gas monitoring packages to streamline EU F-Gas Regulation compliance for thermal management systems.
- Aircraft Manufacturers:OEM airframers integrate health monitoring into original equipment specifications, with MRO operators absorbing aftermarket retrofit demand.
- Railway Operators:State-owned European incumbents and Asian high-speed operators deploy wayside and onboard monitoring for fleet availability optimization.
- Manufacturing Plants:Automotive and semiconductor fabs implement condition monitoring for warranty cost containment and unplanned downtime elimination.
Energy Producers drive platform openness. Shipbuilders demand bundled compliance solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's turbine manufacturing density contrasts with India's retrofit-driven expansion, while the United States and China pursue divergent regulatory paths toward condition monitoring deployment.
United States
Independent power producers in Texas and Iowa now mandate open API access to raw vibration data for in-house analytics teams. OSHA machinery safety regulations and FAA airworthiness directives for rotorcraft drivetrains create compliance-driven replacement cycles. The Pacific Northwest hosts aerospace MRO facilities deploying ultrasonic sensors for helicopter gearbox health assessment.
Germany
Siemens Gamesa and Nordex anchor a dense cluster of turbine manufacturers and service providers mandating continuous drivetrain monitoring for offshore installations. The EU F-Gas Regulation and ISO 13374 standards force hardware suppliers to bundle predictive analytics or cede margin to software specialists. Bavaria's industrial sensor OEMs face procurement exposure from PZT ceramic supply concentration in Asia.
China
GB standards and dual carbon goals push domestic turbine manufacturers toward integrated condition monitoring systems. The country's PZT ceramic suppliers concentrate high-sensitivity accelerometer feedstock, exposing European sensor OEMs to export control volatility. Yangtze River Delta wind farm operators absorb MEMS cost-optimized retrofit volumes.
India
The CEA mandates turbine upgrades at aging wind farms, creating retrofit demand for integrated condition monitoring where penetration currently lags below 15 percent. Domestic turbine manufacturers absorb volume from silicon microfabrication yields supporting sub-dollar vibration sensors. Gujarat and Tamil Nadu wind clusters drive channel density expansion.
Japan
METI industrial efficiency programs accelerate predictive maintenance adoption in precision manufacturing and rail electrification corridors. JIS standards shape product certification requirements for domestic and export markets. Kansai-based ceramic manufacturers supply PZT materials to global accelerometer producers.
Drivetrain Vibration and Condition Monitoring Sensor Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers capturing recurring revenue from hardware commoditization pressures. The vendor base concentrates around three strategic archetypes: automotive heritage players leveraging sensor scale, bearing-integrated specialists combining hardware with cloud analytics, and electrification portfolio extenders targeting marine and wind applications. Dominant competitive moves include strategic partnerships with software analytics providers and backward integration into MEMS foundry capacity.
Among diversified industrial conglomerates, Bosch and ABB exemplify archetype expansion from adjacent sectors into drivetrain diagnostics. SKF occupies a position within the bearing-integrated specialist tier. These three anchors demonstrate how heritage competencies in automotive sensors, electrification systems, and rotating machinery translate into condition monitoring market presence.
| Leading Market Players |
|---|
| Bosch |
| Continental |
| AVL List |
| Denso |
| ABB |
| Regal Rexnord |
| Baker Hughes |
| Caterpillar |
| SKF |
| Others |
Pricing and Supply Chain Analysis
Silicon microfabrication yield improvements are compressing MEMS sensor costs below piezoelectric alternatives while simultaneously redistributing bargaining power toward foundry-dependent suppliers in Taiwan and South Korea. This production-method transition enables sub-$50 vibration sensors for mid-market wind applications but exposes buyers to wafer capacity allocation volatility.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for MEMS accelerometers while piezoelectric ceramic supply concentration in China and Japan sustains premium tiers. Three-tier pricing structure across marine-certified, industrial-grade, and cost-optimized levels reflects Lloyd's Register certification requirements and ISO 13374 compliance tiers. Cost compression in the mid-market tier is intensifying because Indian wind repowering mandates absorb volume at aggressive price points. Independent power producers in Texas and Iowa exhibit highest price sensitivity through unbundled hardware procurement, while Korean shipbuilders demonstrate lowest sensitivity via bundled compliance packages.
Supply Chain Analysis
Specialized vibration analyst certification programs in Germany and the US constrain manufacturing workforce availability for high-precision sensor assembly. Geographic supply concentration centers on China and Japan for PZT ceramic feedstock, Taiwan for MEMS foundry capacity, and Germany for precision assembly of marine-certified systems. Raw material dependencies draw from rare earth elements for magnetic components, high-purity silicon wafers, and specialized epoxy encapsulants. Single-source vulnerability in PZT ceramic supply exposes European sensor OEMs to export control volatility. Distribution runs through OEM direct channels for wind turbine manufacturers and authorized service networks for marine propulsion retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drivetrain sensor market functions as a geographic-arbitrage play where MEMS cost curves in Asian foundries enable margin capture in European compliance-driven replacement cycles.
For Market Incumbents: Lock in backward integration into MEMS foundry partnerships or captive capacity to defend against silicon microfabrication commoditization. Secure Lloyd's Register and DNV certification pipelines early to freeze out competitors in marine propulsion where approval timelines extend eighteen to twenty-four months. Prioritize open API development to retain independent power producer accounts demanding raw data portability. For New Entrants and Emerging Players: Launch via sensor-as-a-service subscription models targeting capital-constrained Indian wind farm operators where condition monitoring penetration lags below fifteen percent. Target fiber optic sensing white space in electrified rail and aerospace nacelles where electromagnetic interference immunity commands premium positioning. Pursue silicon photonics integration partnerships to compress package sizes and accelerate qualification timelines. For Investors and Strategic Acquirers: Roll-up economics work for predictive analytics platform specialists because hardware commoditization pressures intensify value capture toward software layers. Long-term viability hinges on recurring revenue attachment rates exceeding hardware replacement cycles. Monitor Lloyd's Register and DNV certification backlog volumes as inflection indicators for marine propulsion monitoring demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Secures wafer allocation priority as Taiwanese capacity tightens across automotive and industrial sensor demand. |
| Classification Society Pre-Certification | Compresses eighteen-month Lloyd's Register approval timelines for marine propulsion monitoring systems. |
| Open API Platform Development | Retains Texas and Iowa independent power producer accounts demanding raw vibration data portability. |
| Sensor-as-a-Service Launch | Captures multi-year contracts from capital-constrained Indian wind farm operators under CEA repowering mandates. |
| Fiber Optic Silicon Photonics Integration | Enables electromagnetic interference immunity for electrified rail and aerospace nacelle applications. |
Research Methodology
Coverage spans Germany, the United States, China, India, and Japan, with primary inputs from each market cluster obtained through structured interviews with wind farm maintenance directors, marine propulsion system engineers, OEM procurement teams, and aftermarket service heads. Secondary validation drew from customs and trade data, SEC filings of listed industrial conglomerates, IEA renewable energy deployment statistics, and Lloyd's Register certification registries. Bottom-up channel density estimates triangulated against top-down market size calculations.
Granularity-level modeling applied product type, technology, application, and end user dimensions across the projection horizon, with additional regional regulatory cluster segmentation for EU F-Gas compliance timelines. CAGRs were derived from installed base expansion rates, replacement cycle frequencies, and technology substitution curves. Forecast inputs incorporated silicon wafer cost trajectories, PZT ceramic supply availability indices, and classification society certification throughput rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control disruptions to PZT ceramic supply or accelerated MEMS substitution in wind turbine main bearing applications. Forecasts reflect documented assumptions regarding foundry capacity expansion schedules and regulatory enforcement timelines for EU F-Gas and REACH compliance. Material deviation in Lloyd's Register certification timelines or Indian CEA repowering execution rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Racing Clutches Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Truck Auxiliary Power Units Market
Powertrain
South America Automotive Market
Powertrain
Iridium Spark Plug Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
EGR and Emissions Control Actuator Systems Market
Powertrain
Power Liftgate for Automotive Market
Powertrain
Small Gas Engine Market
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Fuel Injection Systems Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Fuel Cell Powertrain Market