
 Natural Gas Engines Market | 2026-2036
Natural Gas Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Gas Engines Market Outlook
Power-hungry data center operators is collapsing into the traditional buyer base of municipal utilities and independent power producers. Cummins leverages its dual-fuel technology leadership to anchor utility-scale installations across North American grids. Wärtsilä competes through deep specialization in marine and energy sector applications, sustaining project finance relationships that span decades. INNIO differentiates via its Jenbacher and Waukesha engine platforms, dominating distributed generation niches where fuel flexibility commands premium positioning.
Natural gas engines are internal combustion power units optimized for methane-based fuels, typically operating with compression ratios between 10:1 and 14:1 and thermal efficiencies reaching 48% in modern four-stroke configurations. These engines convert chemical energy into mechanical work for electricity generation, marine propulsion, and heavy-duty transport applications where emissions regulations restrict diesel alternatives. Four-stroke architectures now lead product mix due to superior fuel efficiency and lower methane slip compared to two-stroke designs, though hybrid configurations are gaining fastest in grid-balancing roles. Spark-ignited technology occupies mature positions in stationary power, while dual-fuel systems capture expanding margin pools from operators seeking operational hedge against gas price volatility.
EPA New Source Performance Standards and the EU Methane Regulation impose stringent limits on engine emissions and upstream methane leakage, forcing manufacturers to redesign combustion chambers and integrate real-time monitoring systems. China's MIIT enforces GB standards on natural gas vehicle engines that restrict market access for non-compliant imports, creating localized certification barriers. Japan's METI coordinates hydrogen-methane blending pilots that will reshape fuel specification requirements across Asian supply chains. Stakeholders must monitor evolving fuel quality standards and carbon accounting methodologies to preserve asset valuations and avoid stranded technology investments.
Market Dynamics
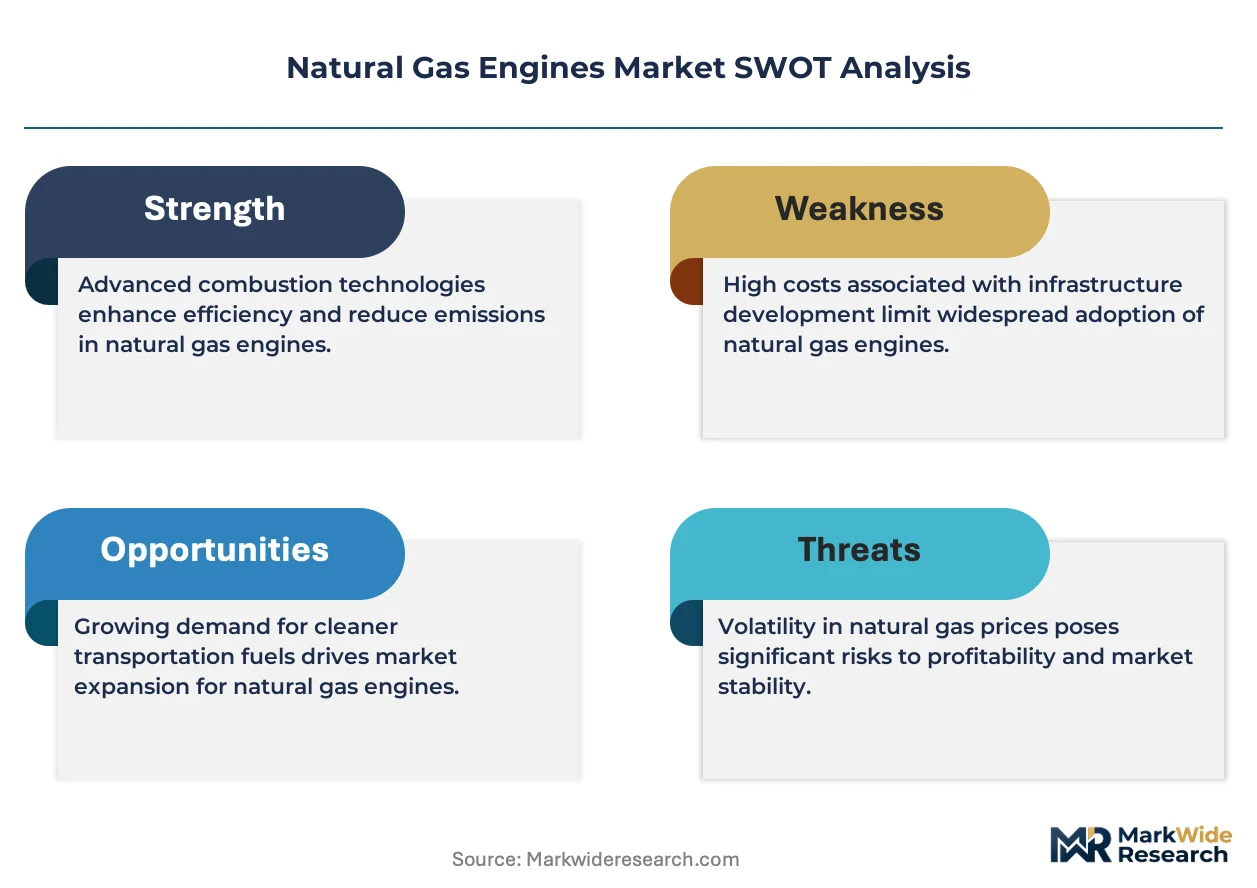
Dual-fuel combustion architecture is forcing a wholesale redesign of stationary power procurement as utilities hedge against methane price volatility through operational fuel flexibility.
Growth Catalysts
- EPA New Source Performance Standards:Stationary power operators in the United States face tightening NOx and methane limits, accelerating fleet replacement cycles toward certified low-emission configurations.
- Data center load growth:Hyperscale facility operators require dispatchable baseload power for grid-isolated campuses, creating captive demand for modular gas engine blocks.
- Marine fuel transition:IMO 2023 carbon intensity regulations push containership operators toward LNG propulsion, expanding addressable market for medium-speed engine variants.
Market Restraints
- Platinum group metal costs:Catalytic aftertreatment systems for Tier 4 Final compliance concentrate input cost exposure in South African and Russian supply corridors.
- Electrolyzer competition:Green hydrogen production economics are improving faster than projected, threatening gas-to-power investments in markets with abundant renewable curtailment.
- GB certification barriers:China's MIIT enforces localized engine testing protocols that extend time-to-market for European and North American manufacturers by 18-24 months.
Strategic Opportunities
- India industrial clusters:The country's PLI scheme for manufacturing and tightening particulate mandates in Gujarat and Maharashtra create first-mover positioning for distributed generation specialists.
- Hydrogen-methane blending:Japan's METI pilot programs are validating 30% hydrogen co-firing specifications that will unlock retrofit markets across existing Jenbacher and Waukesha installed bases.
- Virtual power plant aggregation:Grid operators in Germany and Texas now procure frequency response from aggregated engine fleets, creating new revenue stacks beyond energy arbitrage.
Industry Challenges
- Combustion modeling talent scarcity:Computational fluid dynamics expertise for high-pressure direct injection systems concentrates in a handful of university programs and incumbent engineering departments.
- Real-time methane monitoring integration:EU Methane Regulation leak detection mandates require retrofitting continuous emissions monitoring hardware onto legacy engine platforms without extended outage windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Gas Engines Market |
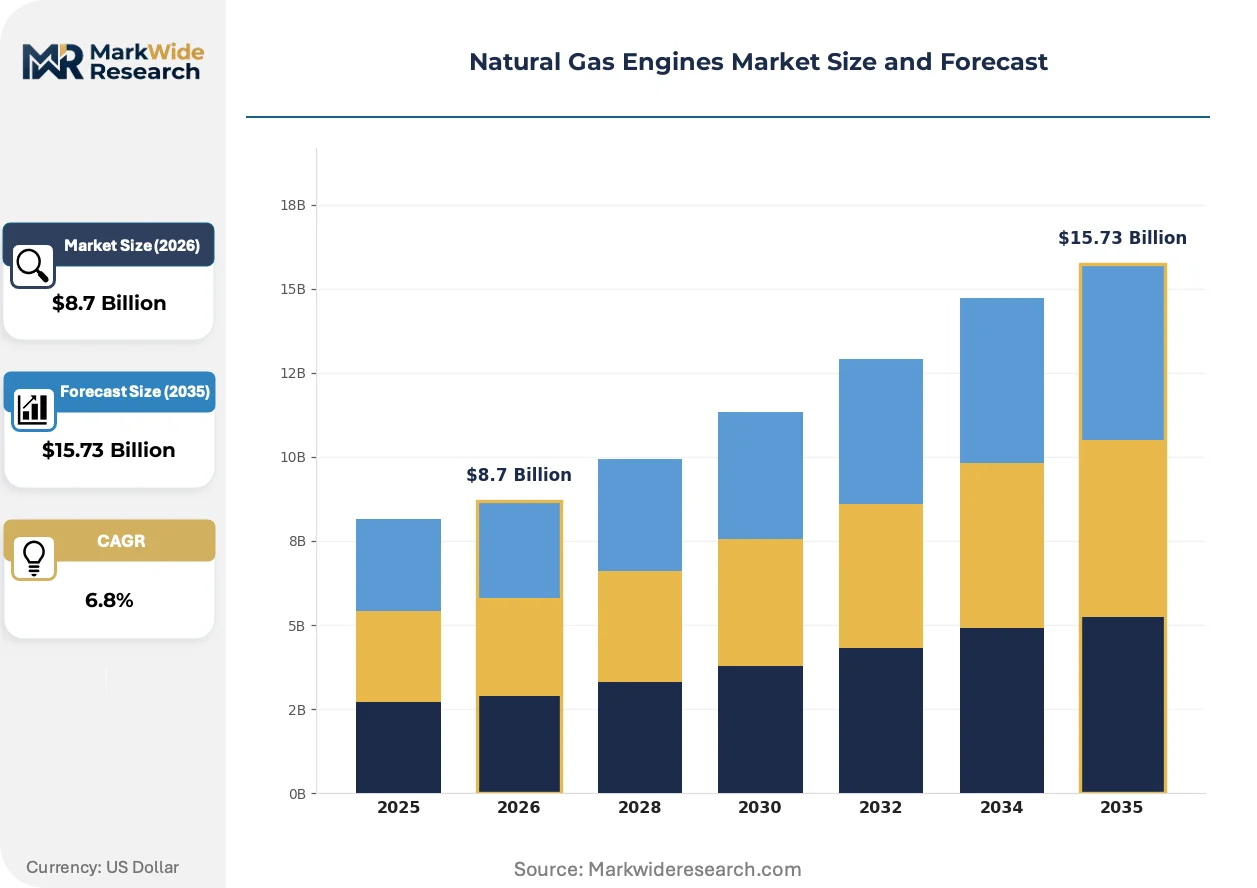
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Stroke, Four-Stroke, Hybrid, Compressed Gas End User: Marine, Automotive, Industrial, Power Generation Technology: Dual Fuel, Spark Ignited, Diesel Cycle, Constant Pressure Application: Power Supply, Transportation, Drill Rigs, Residential Heating |
| Companies Covered | Caterpillar, Cummins, Wärtsilä, INNIO, Rolls-Royce, GE Vernova, Siemens Energy, Mitsubishi Heavy Industries, Kawasaki Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Gas Engines Market Strategic Shifts
Engine architecture is splitting along operational duty cycles as baseload, peaking, and balancing applications demand divergent performance optimization. This fragmentation is accelerating specialization among manufacturers and reshaping R&D allocation.
High-pressure direct injection technology is bifurcating the dual-fuel segment. The system permits diesel-ignited methane combustion without spark plugs, extending fuel flexibility to remote mining and drilling sites lacking gas infrastructure. Off-grid operators in Australia and the Permian Basin are adopting these configurations fastest. The technology is bifurcating service contract structures, separating fuel-agnostic engine blocks from captive gas handling skids and compressing margins for integrated system suppliers.
The EU Methane Regulation mandates upstream leak detection and repair protocols that extend to engine exhaust and crankcase venting. Equipment suppliers must now certify component-level methane slip performance across full load ranges. Marine and distributed generation segments face the steepest compliance redesign, with Wärtsilä and MAN Energy Solutions accelerating closed-crankcase ventilation development for harbor and coastal operations.
Power purchase agreement structures are unbundling engine hardware from long-term service obligations. Independent power producers in Texas and Alberta now procure equipment through lease-to-own vehicles while contracting maintenance to third-party specialists. This disintermediation compresses OEM aftermarket capture and forces manufacturers to defend position through proprietary diagnostics and remote monitoring platforms rather than captive parts distribution.
Natural Gas Engines Market Segmentation
Natural gas engine procurement splits sharply between stationary power and mobile applications, with divergent duty cycles forcing distinct combustion architectures and emissions control strategies. Understanding these segment boundaries clarifies where technology investments concentrate and which regulatory frameworks govern equipment certification.
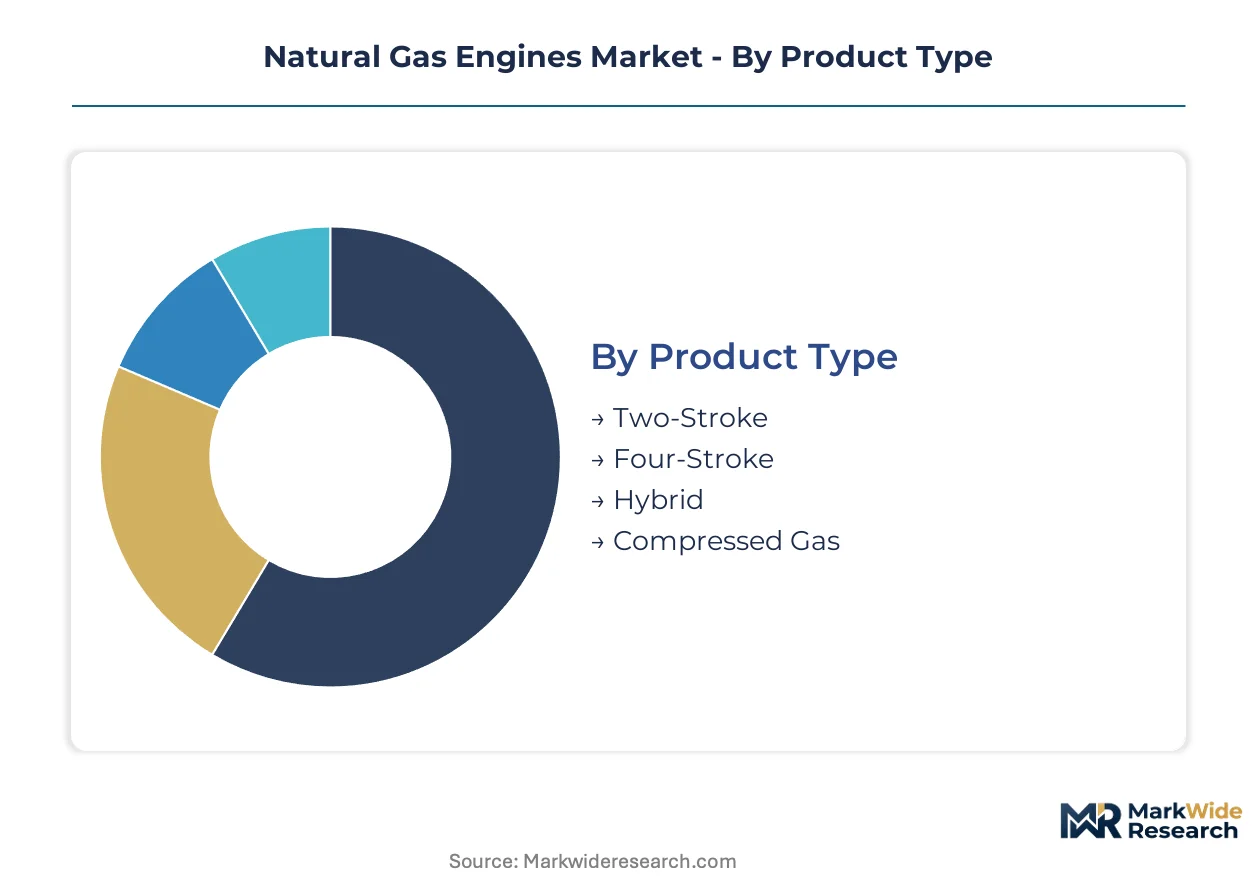
Product Type:
EPA New Source Performance Standards and EU methane regulations apply differential compliance burdens across combustion architectures, with thermal efficiency and methane slip performance determining market access.
- Four-Stroke:Modern configurations achieve thermal efficiencies approaching 48% through optimized compression ratios between 10:1 and 14:1. Power generation utilities in the United States and Germany specify these for baseload and peaking applications where fuel efficiency determines lifecycle economics.
- Two-Stroke:Simpler valve trains and higher power density per displacement suit marine propulsion and remote drilling operations. IMO 2023 carbon intensity regulations constrain their adoption in coastal shipping routes where methane slip monitoring is mandatory.
- Hybrid:Grid-balancing configurations pair gas engines with battery storage to capture frequency response revenue stacks in Texas and German electricity markets.
- Compressed Gas:Dedicated spark-ignited variants serve light-duty automotive and residential cogeneration niches where fuel delivery infrastructure limits liquid fuel alternatives.
Established volume favors four-stroke architectures; emerging adoption favors hybrid configurations.
End User:
Customer procurement patterns concentrate investment in equipment scale and service contract structures, with project finance relationships spanning decades in marine and utility segments.
- Power Generation:Independent power producers and municipal utilities deploy modular engine blocks for dispatchable capacity. Data center operators in Northern Virginia and Frankfurt now represent the fastest-expanding customer cohort for captive baseload installations.
- Marine:Containership operators facing IMO 2023 carbon intensity regulations convert medium-speed engine fleets to LNG propulsion. Wärtsilä and MAN Energy Solutions dominate this segment through deep specialization in vessel integration.
- Industrial:Manufacturing clusters in Gujarat and Maharashtra drive distributed generation demand where grid reliability constraints force captive power investment.
- Automotive:Heavy-duty trucking and bus fleets in China face GB certification requirements that extend time-to-market for non-compliant engine imports.
Power generation commands the largest equipment scale; marine applications carry the steepest compliance redesign burden.
Technology:
Fuel flexibility premiums reshape competitive positioning as operators hedge against methane price volatility through operational switching capability.
- Dual Fuel:High-pressure direct injection permits diesel-ignited methane combustion without spark plugs, extending fuel flexibility to remote mining sites in Australia and the Permian Basin.
- Spark Ignited:Mature stationary power configurations dominate where consistent gas supply quality supports simplified combustion control.
- Diesel Cycle:Compression-ignited architectures persist in heavy transport applications requiring maximum thermal efficiency under variable load.
- Constant Pressure:Specialized combustion modes optimize for specific industrial process heat requirements in chemical and refining operations.
Dual fuel systems capture expanding margin pools; spark ignited technology defends mature installed bases.
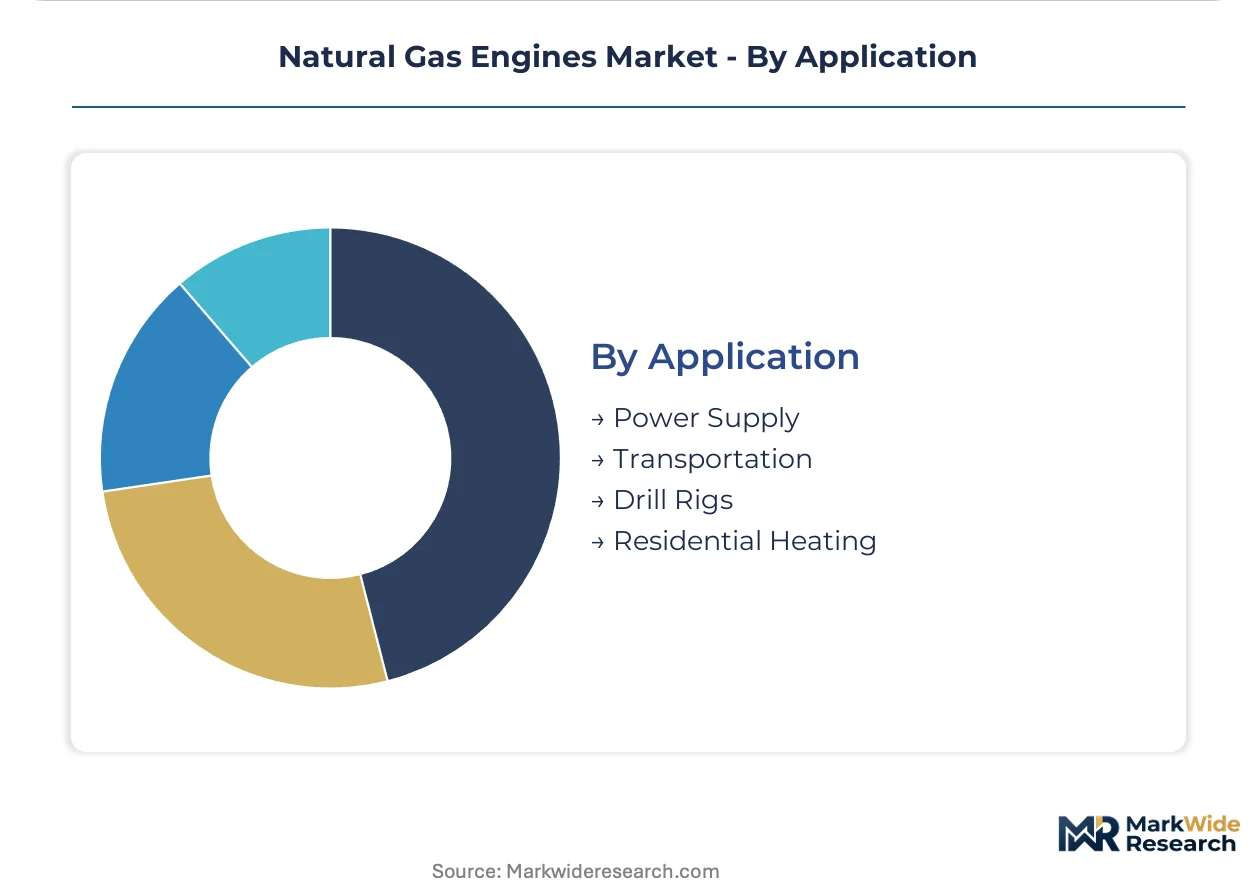
Application:
Operational duty cycles fragment engine architecture specialization between continuous baseload, intermittent peaking, and emergency standby roles.
- Power Supply:Grid-isolated campuses and industrial parks require dispatchable capacity where renewable intermittency creates reliability gaps. Virtual power plant aggregation in Germany and Texas now procures frequency response from distributed engine fleets.
- Transportation:Heavy-duty trucking corridors and marine shipping lanes face divergent fuel infrastructure availability, compressing addressable market definitions.
- Drill Rigs:Remote oilfield operations in West Texas and Western Australia adopt high-pressure direct injection for fuel flexibility where pipeline connectivity is absent.
- Residential Heating:Cogeneration micro-units serve European district heating networks and individual building installations where thermal load coincides with electricity demand.
Power supply applications concentrate technology investment; drill rig configurations test fuel-agnostic engineering limits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network underwrites United States market dominance, while China's West-East Gas Pipeline anchors Asia-Pacific infrastructure investment. Grid modernization programs and industrial decarbonization mandates concentrate equipment procurement across five national markets.
United States
Data center load growth in Northern Virginia and Texas drives captive baseload installations. EPA New Source Performance Standards tighten NOx and methane limits, accelerating fleet replacement cycles. The Permian Basin hosts remote drilling operations adopting high-pressure direct injection configurations for fuel flexibility.
Germany
Virtual power plant aggregation creates frequency response revenue stacks for distributed engine fleets. EU Methane Regulation mandates continuous emissions monitoring hardware retrofits. Industrial clusters in North Rhine-Westphalia deploy modular gas engine blocks for grid-balancing services.
China
West-East Gas Pipeline expansion enables power generation investments in coastal manufacturing zones. MIIT enforces GB certification standards that extend time-to-market for non-compliant imports. Gujarat and Maharashtra industrial corridors drive distributed generation demand where grid reliability constraints force captive power investment.
Japan
METI coordinates hydrogen-methane blending pilots validating 30% hydrogen co-firing specifications. National hydrogen strategy unlocks retrofit markets across existing engine installed bases. Kanto region utilities test grid-balancing configurations pairing gas engines with battery storage.
Australia
Mining operations in Western Australia adopt high-pressure direct injection for diesel-ignited methane combustion at remote sites. National greenhouse gas reporting frameworks tighten methane leak detection requirements. Pilbara iron ore camps deploy fuel-agnostic engine blocks where pipeline connectivity remains absent.
Natural Gas Engines Market Competitive Environment
Listed leaders compete with private specialists across technology licensing and project finance relationships. The vendor base concentrates around three tiers: diversified industrial conglomerates with captive energy divisions, pure-play engine manufacturers with deep application specialization, and regional fabricators serving localized certification markets. Strategic moves center on dual-fuel technology licensing and aftermarket service contract disintermediation.
Within the diversified industrial tier, Caterpillar and Cummins exemplify scale-driven positioning across utility-scale installations. Wärtsilä occupies a specialist position in marine and energy sector applications. These three anchors represent divergent competitive vectors: equipment leasing vehicles, proprietary diagnostics platforms, and decades-spanning project finance relationships.
| Leading Market Players |
|---|
| Caterpillar |
| Cummins |
| Wärtsilä |
| INNIO |
| Rolls-Royce |
| GE Vernova |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| Kawasaki Heavy Industries |
| Others |
Value Chain & Pricing Dynamics
Platinum group metal substitution in catalytic aftertreatment systems is simultaneously relocating supply geography toward South African and Russian corridors while compressing margin structures for Tier 4 Final compliant configurations. This input shift forces engine manufacturers to renegotiate long-term offtake terms or absorb volatile precious metal exposure into project economics.
Pricing Analysis
Volume-discount tiering structures separate utility-scale independent power producers from distributed generation operators and emergency standby purchasers. Pricing stratifies across premium, standard, and economy tiers based on thermal efficiency certification and methane slip performance grades. Cost compression in the economy tier is intensifying because Chinese manufacturers are expanding GB-certified export capacity. Municipal utilities exhibit the highest price sensitivity due to ratepayer oversight constraints, while hyperscale data center operators prioritize reliability premiums over unit economics.
Supply Chain Analysis
Strait of Hormuz transit vulnerability concentrates platinum group metal feedstock exposure for manufacturers dependent on South African concentrate and Russian refined output. Component sourcing draws from Germany for precision fuel injection hardware, China for electronic control modules, and the United States for emissions monitoring sensors. Single-source vulnerability in high-pressure direct injection nozzle manufacturing creates bottleneck risk for dual-fuel system assemblers. Distribution runs through original equipment manufacturer captive parts networks and third-party aftermarket specialists serving remote mining and marine installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural gas engine procurement is approaching a platform-economics inflection as virtual power plant aggregation protocols standardize interoperability between distributed engine fleets and grid operator dispatch systems.
For Market Incumbents: Shield installed base revenue streams by accelerating proprietary remote monitoring platform deployment before third-party diagnostics specialists capture aftermarket service contracts. Deepen backward integration into high-pressure direct injection nozzle manufacturing to reduce single-source supplier dependency. Prioritize EPA and EU Methane Regulation certification investment to maintain market access against emerging Chinese competitors.
For New Entrants and Emerging Players: Lead with hydrogen-methane blending retrofit kits targeting Japan's METI pilot specifications and Germany's existing Jenbacher and Waukesha installed bases. India's Gujarat and Maharashtra industrial corridors offer the most penetrable geography given PLI scheme incentives and tightening particulate mandates. Pursue lease-to-own equipment financing partnerships with independent power producers seeking to unbundle hardware from long-term service obligations.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized dual-fuel technology licensors with captive computational fluid dynamics expertise. Long-term viability hinges on fuel flexibility asset positioning across the hydrogen transition horizon. Acquisition targets should demonstrate project finance relationships spanning decades in marine or utility segments. Monitor Japan's hydrogen-methane blending pilot results as the critical inflection signal for retrofit market sizing.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Technology Licensing | Cummins and Wärtsilä anchor utility-scale installations through proprietary high-pressure direct injection architectures. |
| Virtual Power Plant Integration | Grid operators in Germany and Texas now procure frequency response from aggregated engine fleets beyond energy arbitrage. |
| Backward Integration into Aftertreatment | Catalytic system captive production reduces platinum group metal cost exposure from South African and Russian supply corridors. |
| Hydrogen-Methane Blending Retrofit | METI pilot programs validating 30% hydrogen co-firing specifications unlock existing Jenbacher and Waukesha installed base revenue. |
| Remote Monitoring Platform Deployment | Proprietary diagnostics defend OEM aftermarket position against third-party service contract disintermediation. |
Study Parameters
Initial hypotheses were tested against primary input from utility planning officers, independent power producer project developers, EPC contractors, and marine fleet technical managers and refined through secondary validation across EIA power generation databases, IEA energy technology reports, FERC interconnection filings, and EPA emissions compliance records. Bottom-up equipment deployment tracking was triangulated with top-down fuel consumption modeling across the analysis window.
Variance-decomposition framing separated volume drivers by combustion architecture, end-use application, and technology type while isolating regulatory compliance cost impacts. Segmentation dimensions modeled include engine stroke configuration, operational duty cycle, fuel flexibility tier, and regional grid modernization intensity. CAGRs were derived through iterative convergence of historical deployment patterns and forward-looking project pipeline assessments, with specific weighting applied to data center load growth trajectories and IMO marine fuel transition timelines.
The analysis sits within stated boundaries; outcomes outside sustained EPA and EU methane regulatory enforcement or accelerated green hydrogen cost reduction would require recalibration. Forecasts reflect documented assumptions regarding fuel price volatility, certification timeline adherence, and infrastructure buildout pacing. Practitioners should keep alternative scenarios live as hydrogen blending specifications and virtual power plant aggregation protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Exhaust System Muffler Market
Powertrain
Powertrain Domain Control Unit Platforms Market
Powertrain
Automotive Drivetrain Market
Powertrain
Automotive Torque Vectoring System Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Automotive Variable Discharge Oil Pump Market
Powertrain
Automotive Power Steering Pump Market
Powertrain
Automotive Oil Sump Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Automotive Crank Trigger Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Automotive Turbocharger Market
Powertrain
Automotive TCU Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Automotive Crankshaft Market