
 Gasoline Direct Injection (GDI) System Market | 2026-2036
Gasoline Direct Injection (GDI) System Market Size, Share, and Industry Trends Forecast 2026-2036
Gasoline Direct Injection (GDI) System Market Analysis
The light-duty passenger vehicle segment is restructuring its fuel system architecture as turbocharged downsized engines displace larger naturally aspirated powertrains across mass-market nameplates. Robert Bosch GmbH leverages its injector manufacturing scale to anchor supply contracts with European and Asian OEMs. Continental AG differentiates through integrated fuel rail and pump modules that reduce assembly complexity for vehicle assemblers. Marelli Holdings Co. Ltd. competes on cost-optimized dual-injection systems targeting high-volume compact car platforms.
A gasoline direct injection system pressurizes fuel to 15-35 MPa and sprays it directly into the combustion chamber rather than the intake port, enabling precise charge control and higher compression ratios for improved thermal efficiency. Dual injection and direct fuel injection configurations now dominate product type demand as OEMs balance particulate emissions with power density requirements. Turbocharged technology leads the technology dimension, while naturally aspirated applications retreat to entry-price vehicle segments where cost sensitivity overrides efficiency gains.
EPA tailpipe standards, Euro 7 emission frameworks, and China's MIIT fuel consumption regulations collectively mandate particulate number limits that GDI hardware must satisfy through revised injector spray patterns and gasoline particulate filters. NHTSA corporate average fuel economy rules in the United States reinforce this trajectory by penalizing fleet-wide consumption shortfalls. Stakeholders must monitor how California Air Resources Board waivers and EU Green Deal implementation timelines alter the cost-benefit calculus of GDI versus hybrid powertrain investments.
Market Dynamics
Turbocharged downsizing is compressing engine displacement across passenger car lineups, forcing fuel system suppliers to recalibrate injector spray patterns and rail pressure architectures for smaller-bore combustion chambers. This powertrain transition concentrates procurement decisions at fewer OEM powertrain engineering centers.
Growth Catalysts
- EPA Tier 3 particulate standards:The regulation mandates gasoline particulate filters on most GDI-equipped vehicles, expanding the addressable hardware market beyond injectors and pumps to include filter substrates and sensors.
- China MIIT corporate average fuel consumption rules:The 2025 target of 4 liters per 100 kilometers pushes domestic automakers toward turbo-GDI architectures as a lower-cost compliance path versus full hybridization.
- Turbocharger penetration:Mass-market compact and midsize nameplates now specify boosted engines as standard equipment, creating baseline demand for high-pressure fuel systems capable of supporting lean-burn combustion modes.
Market Restraints
- Stainless steel alloy costs:Injector bodies and fuel rails require corrosion-resistant grades whose prices track nickel and chromium volatility, compressing supplier margins when raw material markets spike.
- Supplier concentration in Baden-Württemberg:A cluster of precision machining and electromagnetic component suppliers sits within a 150-kilometer radius of Stuttgart, exposing the value chain to single-region disruption risk from energy or logistics shocks.
- Hybrid powertrain substitution:Plug-in hybrid architectures with extended electric-only ranges reduce annual GDI operating hours per vehicle, degrading the lifetime revenue per unit for fuel system suppliers.
Strategic Opportunities
- India's BS6 Phase II implementation:The country's tightened particulate matter limits for gasoline vehicles create first-mover advantage for suppliers offering GDI-GPF integrated systems to Maruti Suzuki and Hyundai Motor India.
- Dual-injection system convergence:Combining port and direct injection in a single architecture addresses cold-start particulate emissions while preserving power density, opening premium compact segments previously reserved for pure GDI.
- Remanufactured injector channels:Independent aftermarket distributors in the United States are building testing and reconditioning capabilities for high-mileage GDI components, creating a secondary revenue stream outside OEM replacement cycles.
Industry Challenges
- Combustion calibration expertise scarcity:The intersection of spray-guided injection, turbocharger transient response, and particulate filter regeneration requires engineers fluent in three-domain optimization, a profile rare outside established powertrain centers.
- Euro 7 certification timeline compression:The shortened validation windows for real-driving emissions testing force parallel rather than sequential hardware-software development, straining supplier program management capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gasoline Direct Injection (GDI) System Market |
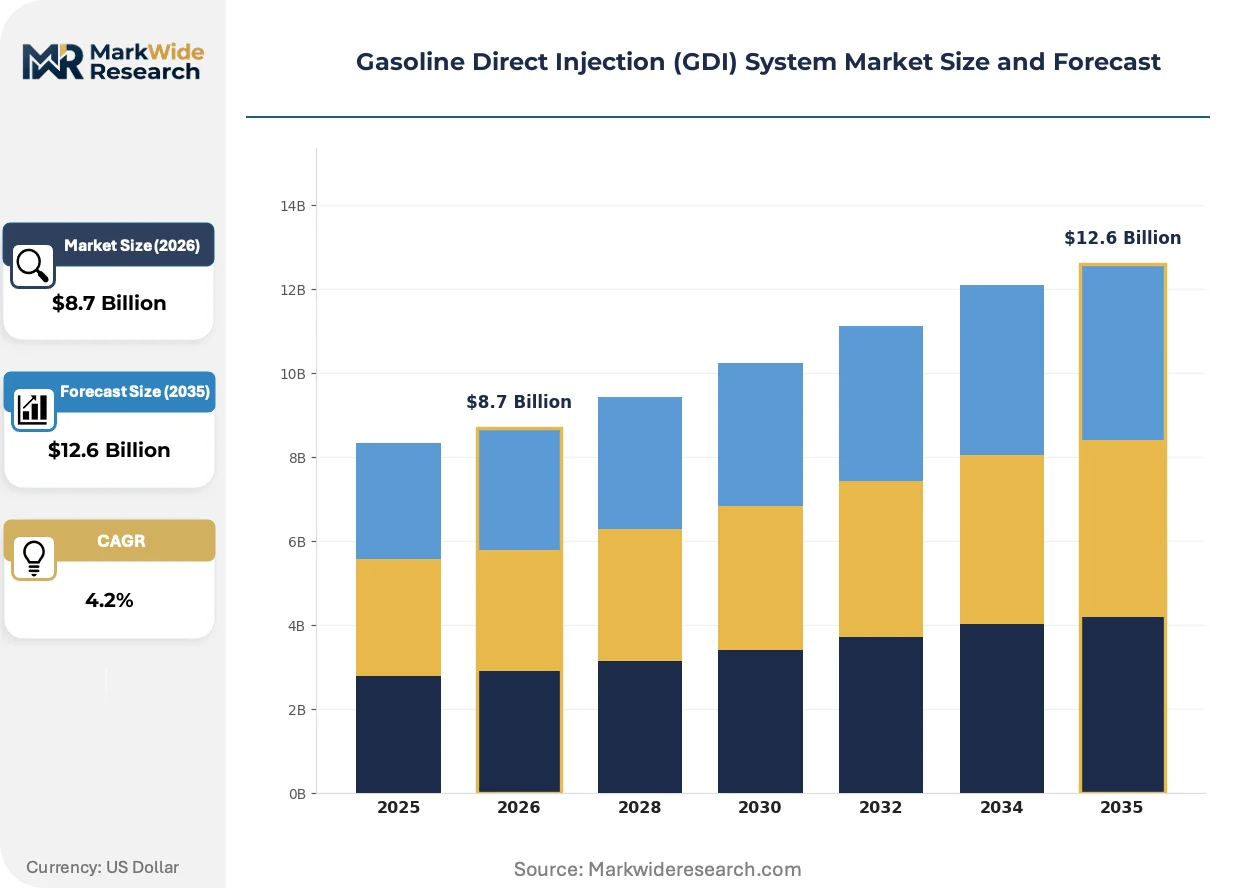
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Port Injection, Dual Injection, Multi-Port Injection, Direct Fuel Injection Technology: Turbocharged, Naturally Aspirated, Supercharged, Hybrid GDI End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, High-Performance Vehicles |
| Companies Covered | Marelli Holdings Co. Ltd., Hitachi Ltd., Robert Bosch GmbH, Delphi Technologies, Stanadyne LLC, Continental AG, BorgWarner Inc., Keihin, DENSO Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gasoline Direct Injection (GDI) System Market Emerging Trajectories
Electrification pressure is fragmenting the fuel system supplier base into three tiers: full-powertrain integrators, component specialists, and aftermarket service providers. Technology roadmaps now diverge based on bets on hybridization depth versus full battery electric displacement.
Solenoid-actuated injectors with piezoelectric response characteristics are integrating into next-generation fuel systems, enabling multiple injection events per combustion cycle with sub-millisecond precision. European and Korean OEMs specify these for 48V mild-hybrid architectures where stop-start frequency demands extreme durability. The technology is integrating spray pattern control with cylinder pressure feedback loops, compressing the calibration cycle from months to weeks.
REACH restrictions on hexavalent chromium plating are forcing suppliers to transition injector needle coatings to physical vapor deposition alternatives. The industrial consequence is a qualification bottleneck at tier-two surface treatment providers, delaying hardware releases for 2026 model-year programs. Powertrain divisions at volume OEMs are responding by pre-purchasing coating capacity and embedding process engineers at supplier facilities.
Fleet procurement of light-duty vehicles is shortening powertrain validation cycles as commercial buyers prioritize total cost of ownership over brand loyalty. Leasing companies and rental fleets now specify fuel economy guarantees that transfer calibration risk to OEMs, who in turn demand fuel system suppliers assume warranty liability for consumption shortfalls. This pattern is most visible in Germany's corporate fleet market, where taxation rules weight CO2 emissions heavily in lease rate calculations.
Gasoline Direct Injection (GDI) System Market Segmentation
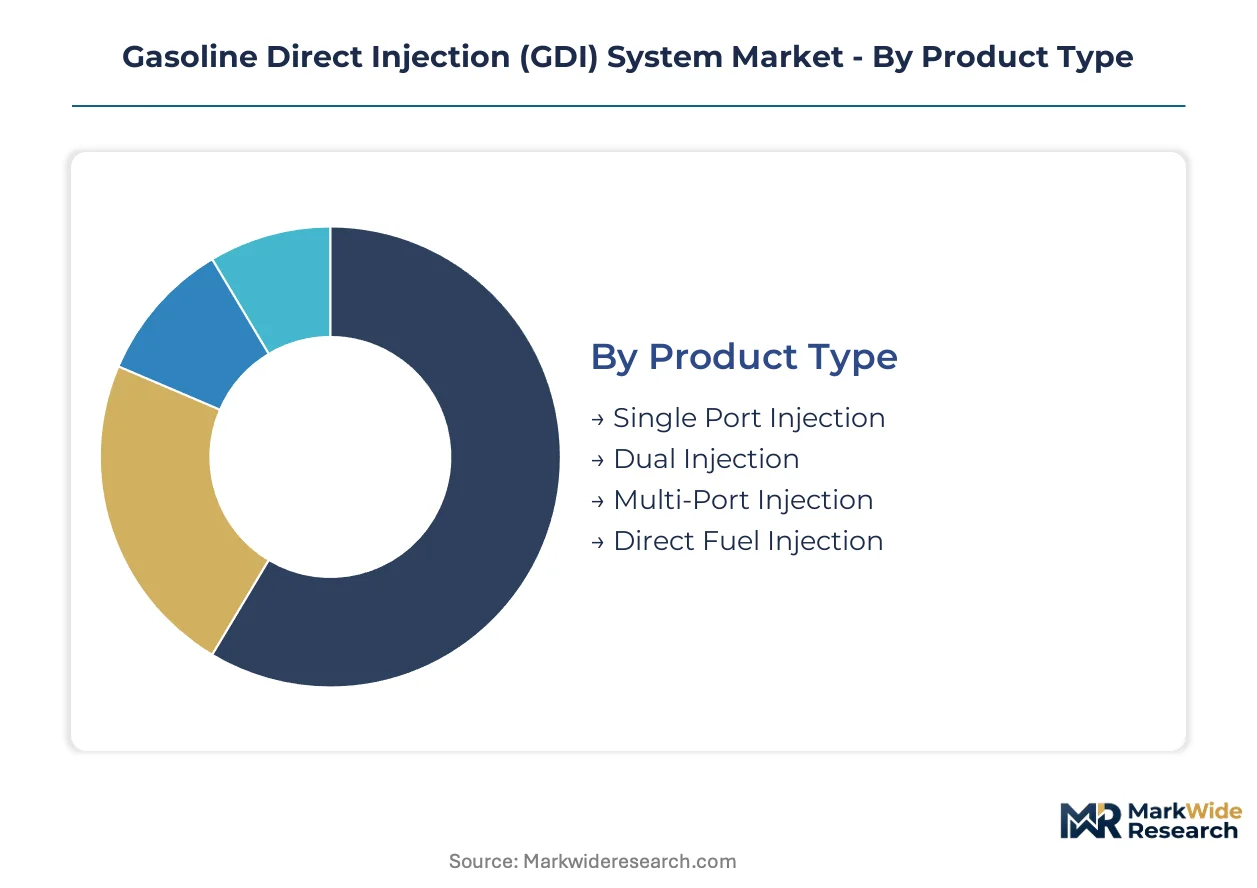
GDI system procurement diverges sharply between high-volume compact platforms and premium performance architectures. Suppliers must calibrate spray patterns, rail pressures, and filter integration for four distinct product configurations, each with unique particulate emission profiles and thermal efficiency targets.
Product Type:
Volume concentration sits with dual-injection architectures, while premium positioning favors pure direct injection for maximum power density.
- Dual Injection:Combines port and direct injection in a single fuel system, enabling cold-start particulate control without sacrificing full-load performance. Demand concentrates in European and Chinese compact car lineups where Euro 7 and MIIT regulations enforce strict particulate number limits. OEMs specify this configuration as a lower-cost compliance path versus gasoline particulate filter retrofit.
- Direct Fuel Injection:Delivers fuel at 15-35 MPa directly into the combustion chamber, supporting higher compression ratios and lean-burn modes for thermal efficiency gains. High-performance vehicle assemblers in Germany and the United States specify pure GDI for turbocharged downsized engines where power density overrides particulate concerns.
- Single Port Injection:Legacy architecture retained in entry-price vehicle segments where cost sensitivity exceeds efficiency mandates.
- Multi-Port Injection:Intermediate configuration serving naturally aspirated powertrains in emerging market compact cars.
Today's leader: Dual Injection. Tomorrow's challenger: Direct Fuel Injection.
Technology:
Cost tier separation drives supplier R&D allocation, with turbocharged systems commanding premium pricing and naturally aspirated configurations retreating to price-sensitive segments.
- Turbocharged:Dominant technology across mass-market and premium nameplates, compressing engine displacement while maintaining output through forced induction. Fuel system suppliers calibrate injector spray patterns for transient boost response and knock-limited combustion. China, Germany, and the United States concentrate procurement for turbo-GDI powertrains as fleet fuel economy penalties tighten.
- Hybrid GDI:Integrates high-pressure fuel systems with 48V mild-hybrid architectures, demanding extreme injector durability for stop-start cycling. Korean and European OEMs specify this technology for segments bridging conventional and plug-in hybrid powertrains.
- Naturally Aspirated:Retained in entry-price segments where manufacturing cost outweighs efficiency gains.
- Supercharged:Niche application in high-performance vehicles requiring instant throttle response without turbo lag.
Turbocharged technology anchors current revenue. Hybrid GDI is gaining share fastest as electrification deepens.
End User:
Customer type determines contract structure, with OEMs demanding system integration and aftermarket providers seeking component interchangeability.
- OEMs:Volume purchasers specifying complete fuel system modules with warranty-backed fuel economy guarantees. Powertrain engineering centers in Stuttgart, Wolfsburg, and Shanghai consolidate procurement decisions for global vehicle platforms.
- Aftermarket Providers:Independent distributors building remanufacturing capabilities for high-mileage injector replacement. United States channels lead development of testing and reconditioning protocols.
- Tier-1 Suppliers:Intermediate integrators sourcing injectors, pumps, and rails for assembly into complete modules.
- Vehicle Assemblers:Contract manufacturers requiring just-in-sequence delivery for flexible production lines.
OEMs dominate contract value. Aftermarket Providers are expanding fastest as GDI vehicle populations age.
Application:
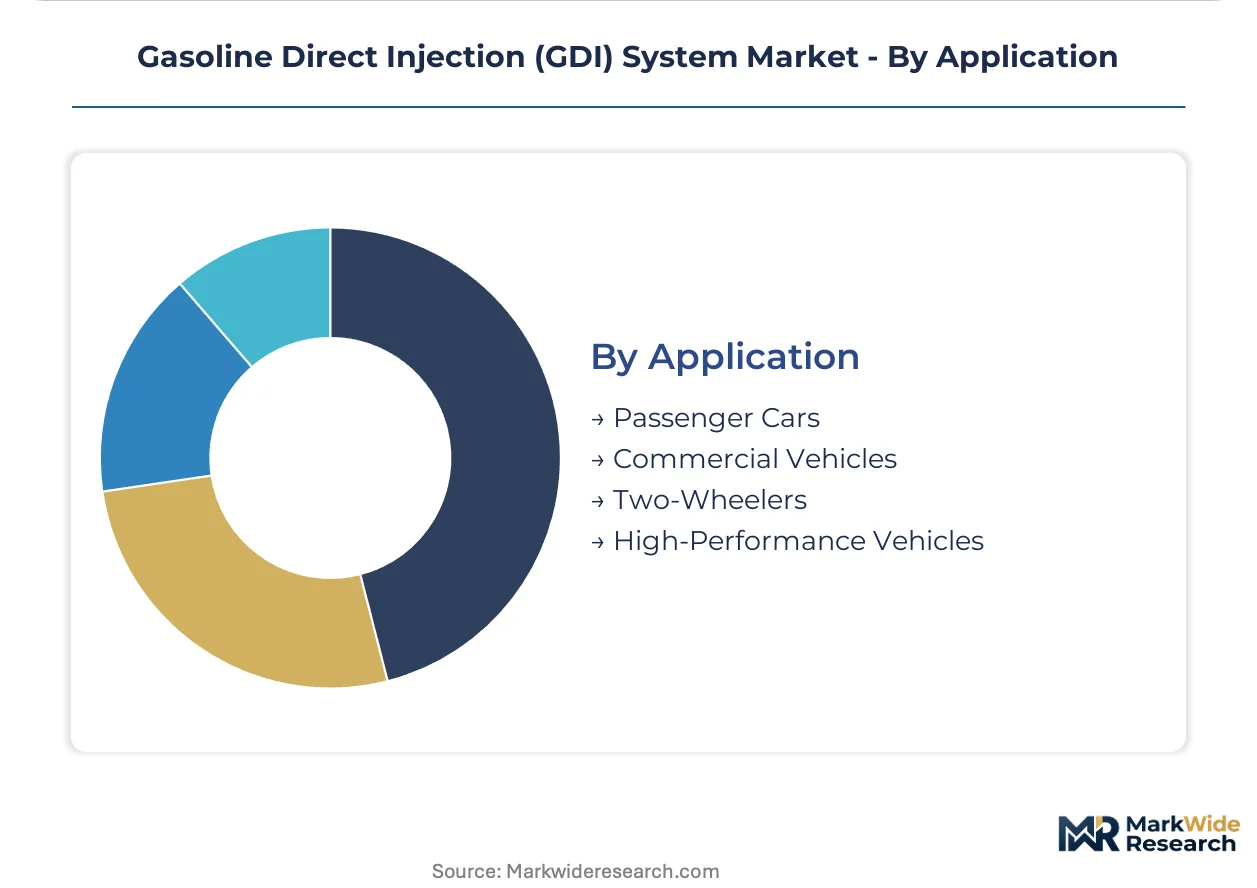
Application maturity varies by thermal load and duty cycle, with passenger cars driving standardization and commercial vehicles demanding heavy-duty filtration.
- Passenger Cars:Largest application segment spanning compact through luxury nameplates. Turbocharged downsizing across mass-market lineups creates baseline demand for high-pressure fuel systems. Regulatory pressure from EPA Tier 3 and Euro 7 mandates gasoline particulate filter integration.
- Commercial Vehicles:Light-duty vans and pickups adopting GDI for fleet fuel economy compliance. Leasing companies specify consumption guarantees that transfer calibration risk to suppliers.
- High-Performance Vehicles:Low-volume segment prioritizing spray-guided injection precision and multiple injection events per cycle.
- Two-Wheelers:Emerging application in premium motorcycles where power density requirements mirror automotive downsizing trends.
Passenger Cars define the technology baseline. Commercial Vehicles are climbing the fastest as fleet procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg anchors global GDI manufacturing density, hosting precision machining clusters that supply injector bodies and electromagnetic components to powertrain engineering centers across three continents. Procurement decisions from Stuttgart-based OEMs cascade through tier-one supplier networks, shaping capacity allocation from Shanghai to Detroit.
United States
EPA Tier 3 particulate standards and NHTSA corporate average fuel economy rules drive turbo-GDI adoption across Detroit Three lineups. The Southeast manufacturing corridor—Tennessee, Alabama, and South Carolina—hosts engine plants retooling for downsized boosted architectures. Tier-one suppliers cluster near these facilities to support just-in-sequence delivery.
Germany
KBA certification timelines and Euro 7 real-driving emissions testing compress hardware validation cycles for domestic OEMs. The Stuttgart-Wolfsburg axis concentrates powertrain engineering decisions, with supplier parks in Lower Saxony and Bavaria feeding module assembly lines. REACH restrictions on hexavalent chromium plating force coating process migrations to physical vapor deposition alternatives.
China
MIIT corporate average fuel consumption regulations targeting 4 liters per 100 kilometers by 2025 push domestic automakers toward turbo-GDI as a lower-cost compliance path versus full hybridization. The Yangtze River Delta and Pearl River Delta host joint-venture engine plants scaling high-pressure fuel system output. Shanghai-based procurement centers coordinate global platform sourcing.
Japan
METI energy efficiency benchmarks and domestic OEM hybrid strategies create specialized demand for 48V mild-hybrid GDI configurations. The Aichi Prefecture cluster around Nagoya anchors injector and pump manufacturing for Toyota and Honda powertrain divisions. Tier-two suppliers in the Chubu region specialize in electromagnetic actuator components.
South Korea
MFDS automotive component standards and domestic OEM export requirements to EPA-regulated markets drive dual-injection system adoption. The Busan-Ulsan industrial complex hosts engine and transmission plants supplying Hyundai Motor and Kia Corporation. Gyeonggi-do supplier parks feed module assembly with precision-machined fuel rail components.
Gasoline Direct Injection (GDI) System Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers position for Euro 7 and China Phase VI implementation deadlines. The vendor base separates into three tiers: full-system integrators commanding OEM module contracts, component specialists capturing injector or pump niches, and regional fabricators serving aftermarket channels. Two strategic archetypes anchor positioning—scale-driven manufacturers leveraging procurement volume and technology specialists monetizing calibration expertise. Geographic expansion and portfolio diversification represent the dominant competitive moves, with suppliers adding gasoline particulate filter integration capabilities to core fuel system offerings.
Within the full-system integrator tier, Robert Bosch GmbH and Continental AG exemplify scale-driven positioning, while Marelli Holdings Co. Ltd. occupies a specialist niche. Stuttgart-based Robert Bosch GmbH anchors European and Asian OEM supply relationships through manufacturing scale. Continental AG represents integrated module architecture, reducing assembly complexity for vehicle assemblers. Marelli Holdings Co. Ltd. exemplifies cost-optimized dual-injection targeting high-volume compact platforms.
| Leading Market Players |
|---|
| Marelli Holdings Co. Ltd. |
| Hitachi Ltd. |
| Robert Bosch GmbH |
| Delphi Technologies |
| Stanadyne LLC |
| Continental AG |
| BorgWarner Inc. |
| Keihin |
| DENSO Corp. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between Euro 7-validated systems and legacy hardware creates parallel pricing tracks and supply chain tiers, with validated components commanding premium positioning while uncertified inventory clears through aftermarket channels at compressed margins. This bifurcation concentrates procurement leverage at OEM powertrain centers in Stuttgart and Shanghai, which extract volume guarantees from tier-one suppliers in exchange for platform access.
Pricing Analysis
Input-cost pass-through from stainless steel alloy volatility shapes contract structures, with nickel and chromium price spikes compressing supplier margins on fixed-price OEM agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, with Euro 7-validated hardware commanding substantial premiums over legacy stock. Pricing pressure stems from hybrid powertrain substitution reducing per-vehicle lifetime revenue. Fleet procurement teams exhibit highest price sensitivity, while performance vehicle assemblers prioritize spray precision over unit cost.
Supply Chain Analysis
Certification and qualification gating for physical vapor deposition coatings creates supply chain bottlenecks, with REACH-compliant surface treatment capacity pre-purchased by volume OEMs ahead of 2026 model-year programs. Manufacturing concentrates in Germany, China, and South Korea, with precision machining clusters in Baden-Württemberg and Aichi Prefecture feeding global module assembly. The chain draws from specialty steel mills, electromagnetic actuator foundries, and gasoline particulate filter substrate suppliers. Single-region concentration around Stuttgart exposes the network to energy or logistics disruption. Distribution runs through just-in-sequence supplier parks adjacent to engine plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Euro 7 certification costs in Germany exceed MIIT compliance investments in China by a substantial margin, rewarding suppliers with dual-qualification capabilities.
For Market Incumbents: Deepen backward integration into physical vapor deposition coating capacity to circumvent tier-two qualification bottlenecks. Anchor procurement relationships at Shanghai-based powertrain centers by offering localized MIIT compliance expertise. Hybrid powertrain substitution threatens lifetime revenue per unit; defend through extended service bundling and calibration IP licensing. For New Entrants and Emerging Players: A mid-tier price-point gap between Bosch-scale premium systems and commodity port-injection hardware opens white-space opportunity in India's BS6 Phase II transition. Target Maruti Suzuki and Hyundai Motor India procurement teams with cost-optimized dual-injection architectures. Aftermarket remanufacturing channels in the United States offer second-mover entry with lower capital requirements than OEM qualification. For Investors and Strategic Acquirers: Consolidation pressure builds where coating qualification bottlenecks strand tier-two suppliers without OEM pre-purchase agreements. Long-term viability hinges on gasoline particulate filter integration capabilities and 48V mild-hybrid durability expertise. Acquisition targets include electromagnetic actuator specialists in Japan's Chubu region and surface treatment providers with REACH-compliant capacity. Watch for California Air Resources Board waiver decisions as inflection signals for hybrid versus GDI investment allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Gasoline Particulate Filter Integration | Expands addressable hardware beyond injectors to capture EPA Tier 3 compliance spending. |
| Physical Vapor Deposition Coating Scale-Up | Secures REACH-compliant needle surface treatment capacity ahead of Euro 7 deadlines. |
| 48V Mild-Hybrid Durability Programs | Positions injectors for extreme stop-start cycling in Korean and European OEM architectures. |
| India BS6 Phase II Localization | Captures first-mover advantage in Maruti Suzuki and Hyundai Motor India supply chains. |
| Aftermarket Remanufacturing Capability | Creates secondary revenue stream outside OEM replacement cycles in aging US vehicle fleet. |
Methodological Framework
Multiple input streams — OEM powertrain procurement data, tier-one supplier production schedules, and regulatory filing documentation — were reconciled through bottom-up and top-down triangulation. Primary interviews engaged Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads across Germany, China, Japan, and the United States. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA certification filings, and KBA type-approval records.
Data-stream reconciliation applied analytical frameworks across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs were derived from segmented volume projections reconciled against macroeconomic drivers. Forecast inputs incorporated turbocharger penetration curves, MIIT corporate average fuel consumption trajectory, and gasoline particulate filter adoption rates by regulatory jurisdiction.
The model assumes a particular technology adoption path; alternative pathways for hybrid powertrain substitution would alter the outlook for GDI hardware demand. Forecasts reflect assumptions regarding Euro 7 implementation timing and China Phase VI enforcement consistency. A model refresh is warranted upon material change in California Air Resources Board waiver status or EU Green Deal acceleration timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Torque Vectoring System Market
Powertrain
Global Automotive Powertrain Management System Market
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Global Automotive Fuel Delivery and Injection Systems Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Automotive Oil Sump Market
Powertrain
Torque Limiter Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Automotive Performance Tuning Market
Powertrain
South America Automotive Market
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Automotive Driveshaft Couplings Market
Powertrain
South Korea Electro Hydraulic Power Steering Market
Powertrain
Timing Belt Market
Powertrain
Automotive Crankshaft Sensor Market