
 Apron Bus Market | 2026-2036
Apron Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Apron Bus Market Analysis
The EU Green Deal is pivoting the apron bus competitive landscape by mandating progressive decarbonization of airport ground fleets and raising compliance costs for conventional diesel platforms. COBUS Industries GmbH leverages its specialized manufacturing footprint in German airport infrastructure to sustain premium positioning in the European market. Zhengzhou Yutong Bus Co., Ltd. anchors its expansion strategy on electric drivetrain scale from its domestic bus operations, while BYD Company Limited differentiates through integrated battery-electric platforms that compete on total cost of ownership metrics.
An apron bus is a low-floor, high-capacity ground support vehicle engineered for passenger movement between airport terminals and aircraft, typically featuring a chassis height of 300-400 mm to align with commercial jet bridges and a capacity of 70-120 passengers. These vehicles operate under severe duty cycles with frequent stop-start patterns on restricted tarmac surfaces, requiring reinforced suspension and corrosion-resistant aluminum or composite body construction. Electric drive technology is capturing the fastest growth trajectory as airports phase out diesel fleets, while hydraulic systems retain dominance in legacy baggage transport applications where retrofit economics lag. The passenger transport application generates the deepest margin pools due to higher reliability specifications and brand-sensitive airline procurement standards.
The European Union Aviation Safety Agency coordinates with ECHA under REACH and RoHS frameworks to restrict hazardous substances in vehicle electronics and batteries, while the EPA in the United States enforces Tier 4 Final emission standards that compress diesel product lifecycles. These regulatory layers force manufacturers to maintain parallel certification streams and accelerate R&D allocation toward zero-emission architectures. Stakeholders must monitor how emerging automated control standards reshape operator procurement criteria and whether connectivity mandates create new compliance barriers for smaller fleet suppliers.
Market Dynamics
Airport fleet electrification mandates are compressing diesel product lifecycles and forcing manufacturers to reallocate R&D toward zero-emission architectures with integrated battery management systems.
Growth Catalysts
- EU Green Deal decarbonization timelines:The F-Gas Regulation and associated ground support equipment standards are mandating progressive fleet replacement across European hubs, creating procurement pull for electric apron buses.
- High-frequency stop-start duty cycles:Electric drivetrains with regenerative braking capture operational advantages in severe tarmac conditions where thermal engines suffer accelerated wear.
- Frankfurt and Munich airport clusters:These German hubs are accelerating sustainable aviation ground operations procurement, concentrating demand for low-floor electric passenger transport vehicles.
Market Restraints
- Lithium-ion battery supply concentration:Cell production and critical mineral processing concentrate in East Asian supply chains, exposing European and North American manufacturers to input cost volatility and geopolitical disruption risk.
- Tier 4 Final compliance costs:EPA emission standards in the United States compress residual values for diesel platforms and force parallel certification streams that inflate engineering overhead.
- Airport infrastructure retrofit requirements:High-voltage charging infrastructure and grid capacity upgrades at aging terminals create capital barriers that slow fleet conversion timelines.
Strategic Opportunities
- Automated vehicle guidance systems:Convergence of lidar-based navigation with electric platforms enables precision docking at aircraft stands, reducing ground damage incidents and labor costs.
- India airport privatization wave:Greenfield terminals at Delhi, Mumbai, and Bangalore are specifying electric ground support equipment from commissioning, bypassing legacy fleet inertia.
- Connectivity mandate gaps:Smaller fleet suppliers without telematics integration capabilities face compliance barriers that create white space for technology-forward entrants to capture mid-tier airport contracts.
Industry Challenges
- Battery thermal management certification:EASA and FAA standards for fire suppression and thermal runaway containment in airport environments extend validation timelines and inflate testing costs.
- Legacy hydraulic system integration:Electric platforms must interface with existing baggage conveyor and cargo loader fleets, creating software and powertrain compatibility friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apron Bus Market |
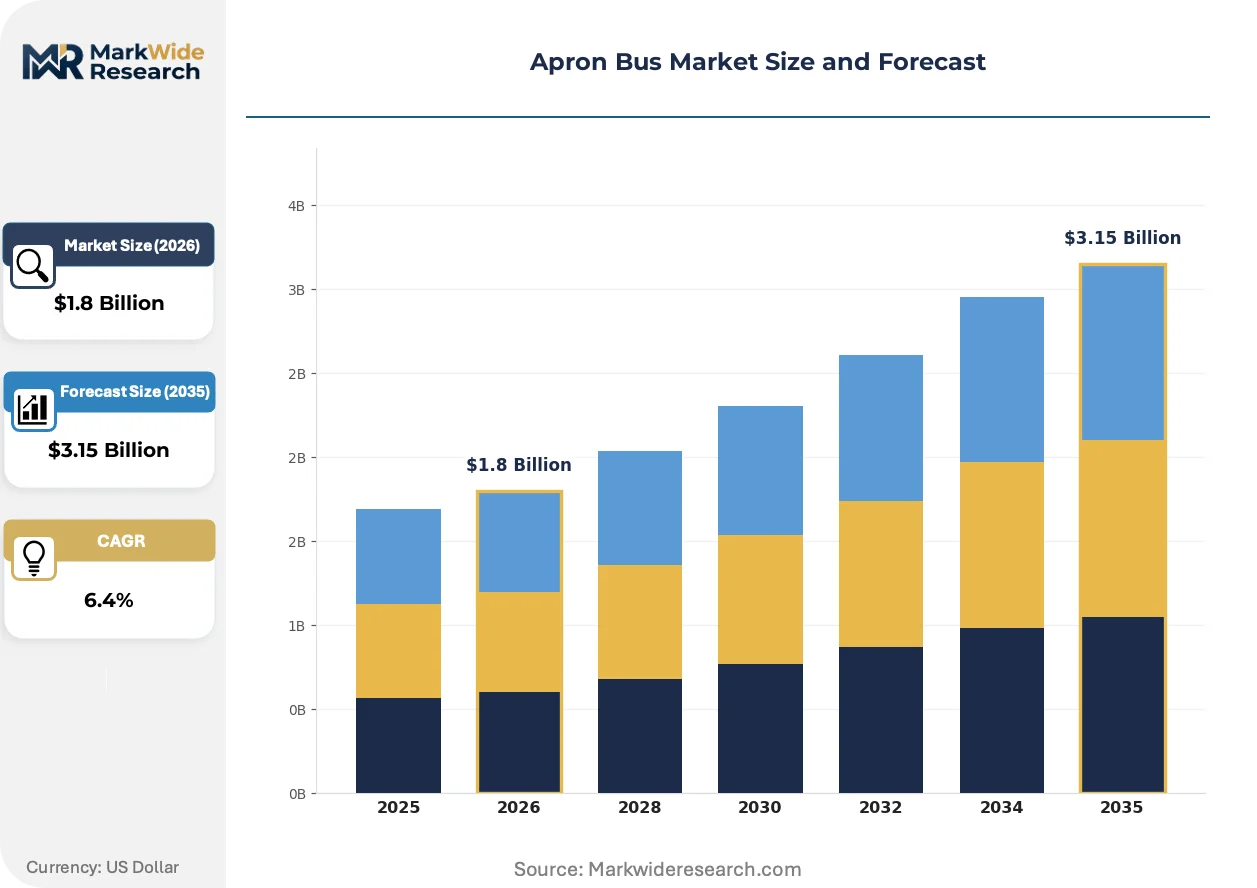
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-deck, Double-deck, Electric, Diesel End User: Airlines, Airports, Ground Handling, Private Operators Application: Passenger Transport, Baggage Transport, Maintenance Support, Cargo Transport Technology: Hydraulic Systems, Electric Drive, Automated Control, Connectivity |
| Companies Covered | Volvo Group, TAM-Europe d.o.o., Zhengzhou Yutong Bus Co., Ltd., MAN Truck & Bus, Daimler AG, COBUS Industries GmbH, Mallaghan Engineering Ltd., Xiamen King Long United Automotive Industry Co., Ltd., BYD Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apron Bus Market Emerging Trajectories
Electrification is restructuring competitive positioning by elevating battery-electric drivetrains from niche alternatives to default specifications at major hub airports, while connectivity requirements reshape procurement evaluation criteria.
High-capacity lithium iron phosphate battery packs with active liquid cooling are overtaking nickel-manganese-cobalt chemistries in apron bus applications. Frankfurt Airport and Amsterdam Schiphol specify these systems for their extended cycle life and thermal stability in high-ambient tarmac conditions. The technology is overtaking conventional battery architectures by enabling 18-hour continuous operation without mid-shift charging interruptions.
The EU F-Gas Regulation tightens emission standards for ground support equipment refrigerants and propulsion systems through 2030. Manufacturers must redesign thermal management systems and accelerate phase-out of diesel-hybrid platforms. German and French airport operators are responding with binding fleet electrification clauses in ground handling concession agreements.
Airline procurement teams now bundle apron bus contracts with comprehensive service-level agreements covering uptime guarantees and predictive maintenance. Traditional equipment-only sales models are losing share to performance-based contracts at major European and Middle Eastern hubs. This shift is most visible at Dubai International and Heathrow, where ground handlers face penalties for passenger boarding bridge delays.
Apron Bus Market Segmentation
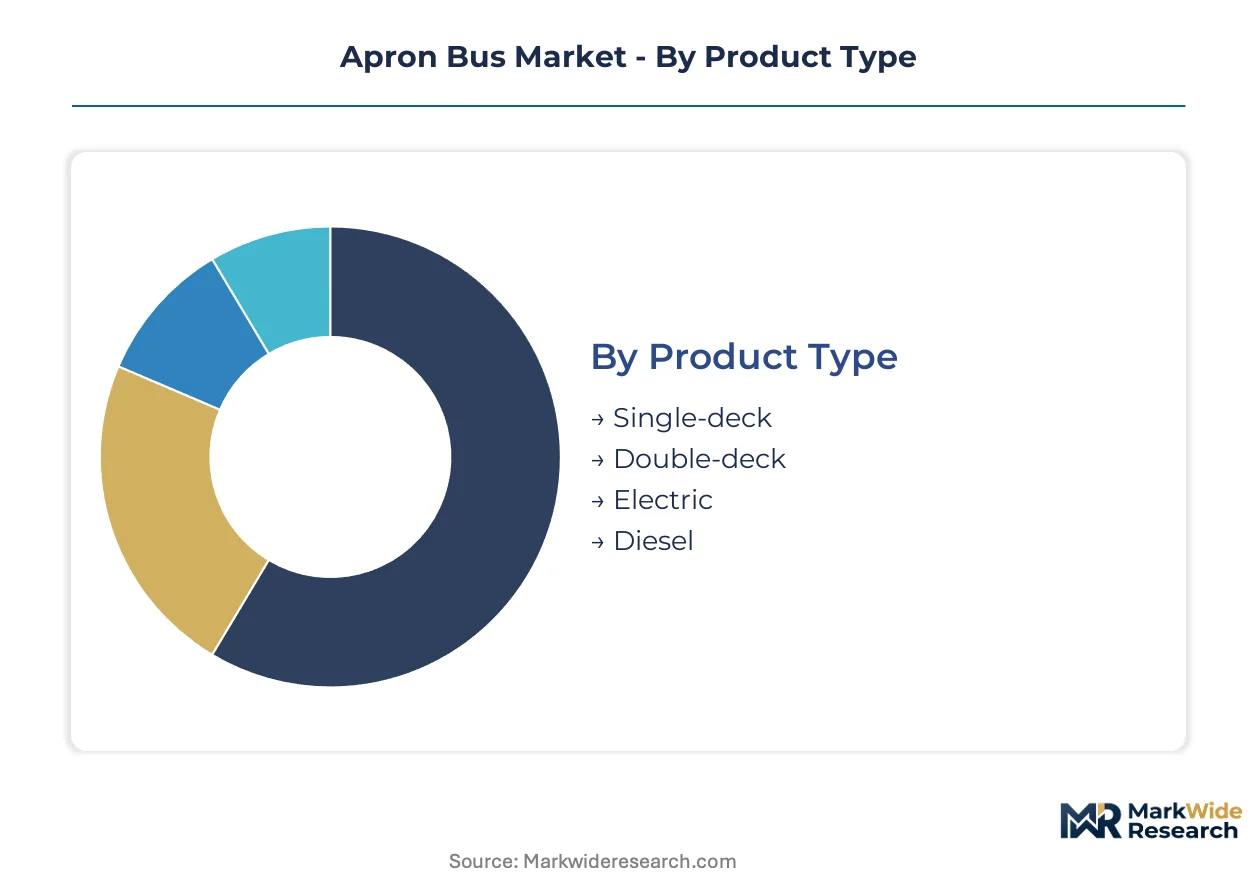
Apron bus procurement patterns diverge sharply across operational contexts. Fleet managers weight duty cycle severity, regulatory exposure, and infrastructure retrofit costs differently depending on airport scale and ground handling contract structures.
Product Type:
Manufacturing capacity clusters around low-floor electric platforms as European and Asian airports accelerate diesel phase-out programs.
- Single-deck:These vehicles dominate narrow-body aircraft operations with chassis heights of 300-350 mm and 70-90 passenger capacity. Frankfurt and Munich airports specify single-deck electric variants for their high-frequency shuttle routes, where regenerative braking captures energy from stop-start tarmac cycles.
- Double-deck:Upper-deck configurations accommodate 110-120 passengers for wide-body aircraft servicing at high-volume hubs. Dubai International and Heathrow procure these units for A380 and 747-8 operations, though vertical clearance restrictions limit deployment at older terminals with constrained gate infrastructure.
- Electric:Battery-electric drivetrains with lithium iron phosphate cells are overtaking diesel alternatives at greenfield airports.
- Diesel:Tier 4 Final compliant engines retain residual demand in regions with limited charging infrastructure.
Single-deck platforms absorb the bulk of installed capacity; electric drivetrains are expanding most quickly.
End User:
Procurement authority fragmentation across airport ecosystems creates divergent specification requirements and contract tenures.
- Airlines:Legacy carriers at Frankfurt and Lufthansa Group hubs specify branded liveries and premium interior finishes. Their fleet decisions prioritize passenger experience metrics and on-time performance guarantees over capital expenditure minimization.
- Airports:Hub operators like Amsterdam Schiphol and Munich Airport direct sustainable aviation ground operations procurement through binding electrification clauses in concession agreements. Their centralized purchasing captures economies of scale across multiple ground handlers.
- Ground Handling:Swissport and Menzies Aviation operate mixed fleets across contracted airport portfolios.
- Private Operators:Independent shuttle providers serve regional airports with lower utilization rates.
Airport authorities command the largest procurement volumes; ground handling contractors are gaining purchasing influence fastest.
Application:
Margin structures diverge dramatically between passenger-facing and cargo-supporting operations.
- Passenger Transport:Low-floor configurations with climate control and accessibility features generate premium pricing. Reliability specifications are stringent due to airline delay penalties at Dubai International and Heathrow.
- Baggage Transport:High-capacity trailers with hydraulic lift systems interface with existing conveyor infrastructure. Retrofit economics lag electric conversion here due to lower utilization intensity.
- Maintenance Support:Specialized vehicles transport technicians and equipment to remote stands.
- Cargo Transport:Reinforced suspension variants handle palletized freight on dedicated cargo aprons.
Passenger transport commands the deepest margin pools; baggage handling electrification is climbing the fastest.
Technology:
Technology integration requirements are reshaping supplier qualification criteria beyond mechanical performance.
- Electric Drive:Integrated battery management systems with active liquid cooling enable 18-hour continuous operation. Frankfurt Airport and Amsterdam Schiphol specify these for thermal stability in high-ambient tarmac conditions.
- Automated Control:Lidar-based precision docking systems reduce ground damage incidents and labor costs at aircraft stands.
- Hydraulic Systems:Legacy powertrains retain installed base in baggage conveyor integration.
- Connectivity:Telematics platforms enable predictive maintenance and uptime guarantees.
Electric drive platforms capture the steepest expansion trajectory; connectivity mandates are creating compliance barriers for smaller fleet suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the UAE and special economic corridors in China concentrate apron bus manufacturing capacity and fleet deployment capital. These zones attract ground support equipment producers through tariff exemptions and streamlined customs protocols. Airport privatization waves in India and Southeast Asia redirect procurement flows toward these supply hubs.
Germany
Frankfurt and Munich airports anchor European demand for electric apron buses through binding fleet electrification clauses in ground handling concessions. The EU Green Deal and F-Gas Regulation mandate progressive decarbonization timelines that compress diesel product lifecycles. Bavaria's manufacturing corridor hosts specialized producers serving these hub requirements with low-floor electric platforms.
United States
Major hub airports in Atlanta, Dallas-Fort Worth, and Los Angeles face EPA Tier 4 Final compliance costs that accelerate fleet turnover toward zero-emission alternatives. The FAA coordinates with airport authorities on automated vehicle guidance standards for tarmac operations. The Southwest corridor concentrates ground handling contractor procurement for narrow-body shuttle routes.
China
Dual carbon goals and MIIT electric vehicle mandates drive domestic airport fleet conversion in Beijing, Shanghai, and Guangzhou. The Yangtze River Delta and Pearl River Delta special economic zones host integrated battery-electric bus manufacturing clusters. Zhengzhou and Xiamen anchor export capacity for lithium iron phosphate drivetrain platforms serving Asian and Middle Eastern hubs.
India
Greenfield terminal developments at Delhi, Mumbai, and Bangalore specify electric ground support equipment from commissioning under airport privatization frameworks. The Bureau of Indian Standards and CEA regulate high-voltage charging infrastructure standards for aging grid connections. Maharashtra and Karnataka states concentrate fleet operator headquarters and maintenance facilities.
United Arab Emirates
Dubai International and Abu Dhabi International airports procure premium-specification double-deck units for A380 operations under performance-based service contracts. The country's aviation regulator enforces connectivity mandates that favor telematics-integrated fleet suppliers. Jebel Ali free zone concentrates regional distribution and aftermarket service operations for Gulf Cooperation Council airports.
Apron Bus Market Vendor Landscape
German producers anchor the premium tier through specialized airport infrastructure manufacturing footprints; Chinese fabricators hold scale advantages in integrated battery-electric platforms. The market structures around three strategic archetypes: dedicated ground support equipment specialists, diversified commercial bus manufacturers with apron variants, and integrated battery-electric platform providers. Competitive moves concentrate on automated docking technology licensing and strategic partnerships with airport authorities for fleet-as-a-service contracts.
Among diversified commercial bus manufacturers, Zhengzhou Yutong Bus Co., Ltd. and Xiamen King Long United Automotive Industry Co., Ltd. occupy positions leveraging domestic electric drivetrain scale. COBUS Industries GmbH exemplifies the dedicated specialist archetype with concentrated European airport infrastructure presence. BYD Company Limited represents the integrated battery-electric platform approach competing on total cost of ownership metrics.
| Leading Market Players |
|---|
| Volvo Group |
| TAM-Europe d.o.o. |
| Zhengzhou Yutong Bus Co., Ltd. |
| MAN Truck & Bus |
| Daimler AG |
| COBUS Industries GmbH |
| Mallaghan Engineering Ltd. |
| Xiamen King Long United Automotive Industry Co., Ltd. |
| BYD Company Limited |
| Others |
Supply Flow & Price Mechanics
Ground handling contractors at Frankfurt and Munich airports command concentrated procurement volumes that anchor contract-based long-term offtake pricing with embedded electrification clauses. Their fleet-scale purchasing power compresses margins for diesel platform suppliers while elevating premium capture for integrated battery-electric providers with certified thermal management systems.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply for electric apron bus deliveries needed within compressed airport concession renewal windows. Three-tier pricing structure across premium, standard, and economy levels separates telematics-integrated fleet-as-a-service contracts from equipment-only transactions and spot procurement for emergency replacements. Cost compression in standard-tier diesel platforms is intensifying because EPA Tier 4 Final compliance inflates engineering overhead without differentiation leverage. Regional airports and private shuttle operators exhibit highest price sensitivity due to constrained capital budgets and lower utilization intensity.
Supply Chain Analysis
Lithium iron phosphate cell supply rests on Chinese cathode material processing and South Korean electrolyte formulation specialists, with German thermal management component suppliers providing active liquid cooling systems. Aluminum body construction draws from Norwegian smelter output and Chinese extrusion capacity, while semiconductor content for battery management systems sources from Taiwanese foundry operations. Single-source vulnerability concentrates in East Asian cell production, exposing European and North American assemblers to input cost volatility. Distribution runs through Jebel Ali free zone hubs for Middle Eastern and African airport deployments, with direct manufacturer-airport authority relationships dominating European procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The apron bus market sits in a technology-transition phase where lithium iron phosphate electric drivetrains are displacing Tier 4 Final diesel platforms as default specifications at major hub airports.
For Market Incumbents: Cement defensive positioning through backward integration into battery thermal management certification capabilities and captive supply of active liquid cooling components. COBUS Industries GmbH and comparable specialists must accelerate EASA validation timelines to offset emerging competition from integrated Chinese battery-electric platforms. Channel control through fleet-as-a-service contract structures protects against price erosion from diversified commercial bus manufacturers. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for mid-tier airport contracts where telematics integration mandates create compliance barriers for smaller legacy suppliers. India's greenfield terminal privatization wave at Delhi, Mumbai, and Bangalore offers the most penetrable geography, bypassing legacy fleet inertia through electric ground support equipment specifications from commissioning. A precision docking technology licensing partnership with established ground handlers provides viable go-to-market acceleration without full manufacturing footprint investment. For Investors and Strategic Acquirers: The window for entry favors vertically integrated battery-electric platform providers with certified airport thermal management systems and existing ground handling service relationships. Over a five-to-ten year horizon, acquisition targets must demonstrate sustainable aviation ground operations procurement traction at Frankfurt-scale hubs. The signal to watch is binding electrification clause penetration into ground handling concession renewals at secondary European airports.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet-as-a-Service Contract Structure | Performance-based agreements with uptime guarantees capture premium pricing at Dubai International and Heathrow. |
| Automated Vehicle Guidance Licensing | Lidar-based precision docking partnerships reduce ground damage liability and labor costs for ground handlers. |
| Battery Thermal Management Certification | EASA and FAA validation for fire suppression systems accelerates electric platform adoption at European hubs. |
| Greenfield Airport Electrification Partnership | Early engagement with Delhi and Mumbai privatization frameworks locks in fleet specifications from commissioning. |
| Telematics Platform Integration | Predictive maintenance capabilities satisfy connectivity mandates at UAE aviation regulator-enforced airports. |
Methodological Framework
Independent corroboration across ground handling fleet managers, airport procurement officers, and ground support equipment engineering directors underwrites the qualitative findings in this study. Primary interviews with maintenance directors at Frankfurt and Munich airports, aftermarket service heads at Jebel Ali free zone operations, and OEM procurement teams at diversified commercial bus manufacturers combined with secondary validation from EASA certification databases, EU Green Deal implementation reports, and airport authority concession agreement disclosures. Bottom-up installed base estimates and top-down procurement flow analysis triangulate volume and value outputs.
Across the analysis window, the forecast framework anchored projections to historical fleet replacement cycles at major hub airports and greenfield terminal commissioning schedules. Segmentation dimensions modeled include product type architecture, end-user procurement authority structure, application duty cycle intensity, and drivetrain technology platform. CAGRs were derived from regression analysis against regulatory compliance timelines and infrastructure retrofit capital deployment patterns. Battery chemistry transition curves and automated docking technology adoption rates provided industry-specific forecast inputs.
Caveats apply where lithium-ion mineral supply disruptions, grid capacity upgrade delays at aging terminals, or automated vehicle guidance standard revisions could materially shift the outlook. Forecasts reflect assumptions around EU F-Gas Regulation enforcement consistency and airport electrification mandate penetration rates. A small set of named triggers warrants ongoing watch: East Asian cell production concentration, EASA thermal runaway containment standard updates, and India airport privatization framework implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Europe Ball Bearings Market
Automotive Parts
Smart Adaptive Headlights Market
Automotive Parts
Car Refrigerator Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Asia Pacific Automotive Parts Die Casting Market
Automotive Parts
Hydraulic Lash Adjuster Market
Automotive Parts
Timing Gear Market
Automotive Parts
Saudi Arabia Vehicle Exhaust Hose Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
Japan Ceramic Ball Bearings Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
Automotive Thermostat Market
Automotive Parts
Automotive AC Compressor Market