
 Whiplash Protection System Market | 2026-2036
Whiplash Protection System Market Size, Share, and Industry Trends Forecast 2026-2036
Whiplash Protection System Market Intelligence
The rising integration of advanced safety features by automakers is rebalancing the market away from standalone aftermarket solutions. This shift favors large, established tier-one suppliers capable of delivering integrated systems. Autoliv Inc. leads in specialized safety component manufacturing, including pyrotechnic and mechanical activators. Continental AG leverages its deep expertise in automotive electronics and sensor technology to develop sophisticated active systems. Meanwhile, Lear Corporation specializes in integrating whiplash protection directly into its advanced seating platforms for major OEMs.
A whiplash protection system is an automotive safety device engineered to mitigate neck injuries during a rear-end collision. These systems function by controlling the occupant's head and torso movement, often by moving the head restraint forward and upward to meet the head early in the impact sequence. While passive systems rely on the occupant's inertia, active systems use sensors to detect a rear impact and preemptively position the headrest. Sensor-Based technologies are displacing purely mechanical systems, especially in the premium and mid-range vehicle segments.
Regulatory mandates and consumer safety ratings are the primary market accelerators. Safety standards set by the United States' NHTSA and testing protocols from Europe's Euro NCAP create direct incentives for manufacturers to equip vehicles with effective whiplash protection. These frameworks define minimum performance criteria and influence consumer purchasing decisions through safety scores. The next phase of innovation will involve integrating these systems with vehicle-to-everything (V2X) communication for pre-crash activation.
Market Dynamics
The market's primary structural force is the escalating stringency of automotive safety testing protocols. Mandates and rating systems from bodies like the NHTSA and Euro NCAP are compelling automakers to move beyond basic passive systems, creating a definitive pull for integrated, active technologies.
Growth Catalysts
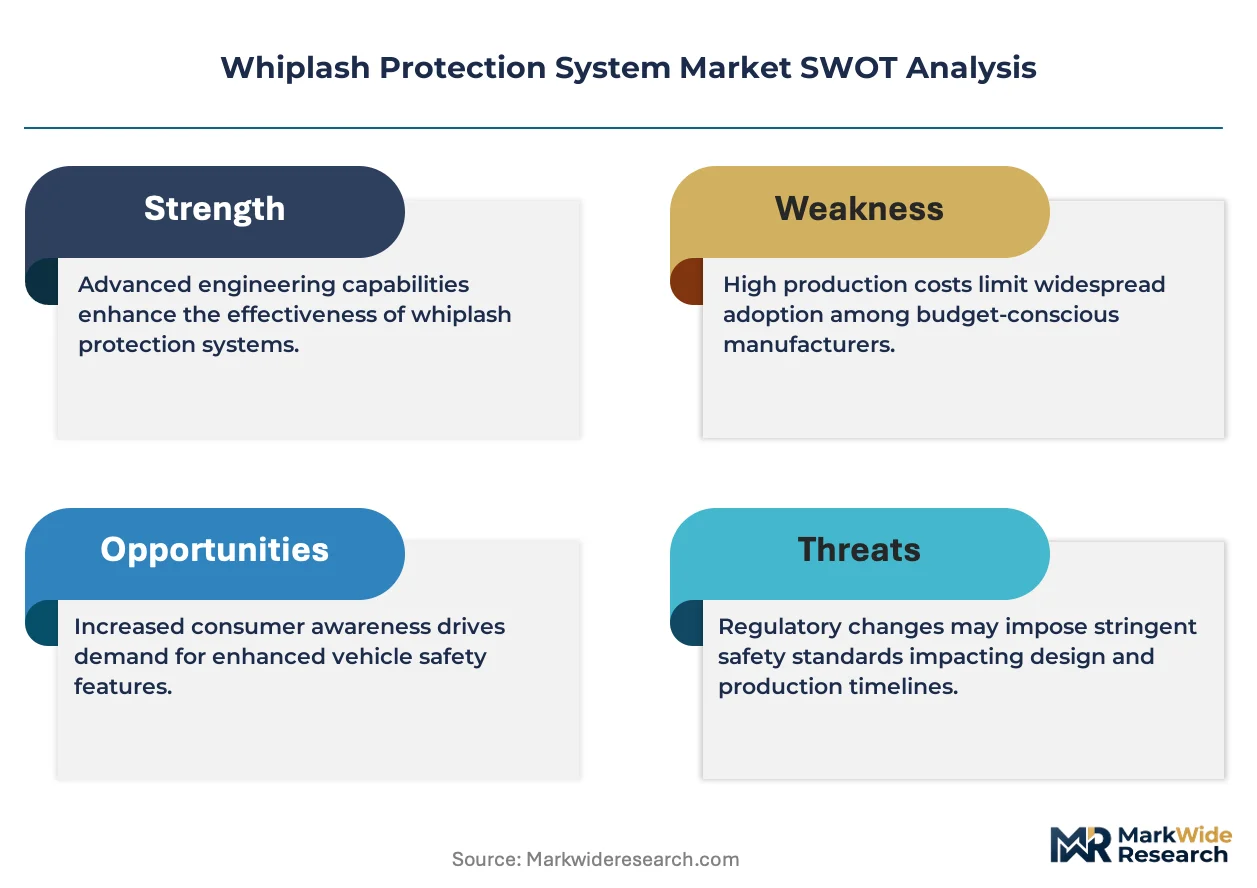
- Stringent Safety Protocols:The Euro NCAP's comprehensive testing, which includes detailed rear-impact sled tests and whiplash assessments, creates a direct incentive for manufacturers to incorporate advanced, high-performing protection systems to achieve top safety ratings.
- Technology Proliferation:The falling cost and miniaturization of sensors and micro-actuators are enabling the spread of active whiplash systems from the luxury segment into mid-range vehicles, expanding the addressable market for sophisticated solutions.
- Consumer Safety Awareness:In mature automotive markets like Germany and Japan, high consumer awareness of vehicle safety ratings directly influences purchasing decisions, pressuring OEMs to standardize effective whiplash protection as a key feature.
Market Restraints
- High System Cost:The significant cost differential between basic mechanical systems and advanced sensor-based active systems remains a major barrier to adoption in the price-sensitive economy and compact vehicle segments.
- Technical Integration Complexity:Integrating active whiplash systems requires complex calibration with a vehicle's central electronics, sensor arrays, and seat structures, posing a significant engineering and validation hurdle for automakers.
- Aftermarket Competition:The availability of low-cost, non-OEM headrest and seat cover solutions, while offering minimal protection, creates a perception of choice that can divert consumer spending from factory-installed, certified systems in older vehicles.
Strategic Opportunities
- V2X Integration:The convergence of whiplash protection with vehicle-to-everything (V2X) communication technology presents an opportunity for pre-crash activation, allowing the system to prepare for an imminent impact before it occurs.
- Mid-Range Segment Penetration:Developing cost-effective, semi-active systems can unlock significant volume growth in the global mid-range sedan and SUV markets, which are currently underserved by advanced whiplash protection.
- Regulatory Expansion:Anticipated updates to vehicle safety standards in large emerging automotive markets, such as those governed by India's BIS, offer a future growth avenue for suppliers who can provide compliant and localized solutions.
Industry Challenges
- Software Validation Burden:Verifying and validating the software for active systems across countless potential impact scenarios is a time-consuming and costly challenge, delaying product development cycles and increasing liability exposure.
- Supply Chain Constraints:The reliance on a concentrated number of specialized suppliers for key components like pyrotechnic gas generators and advanced sensors creates potential bottlenecks and pricing pressures for vehicle manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whiplash Protection System Market |
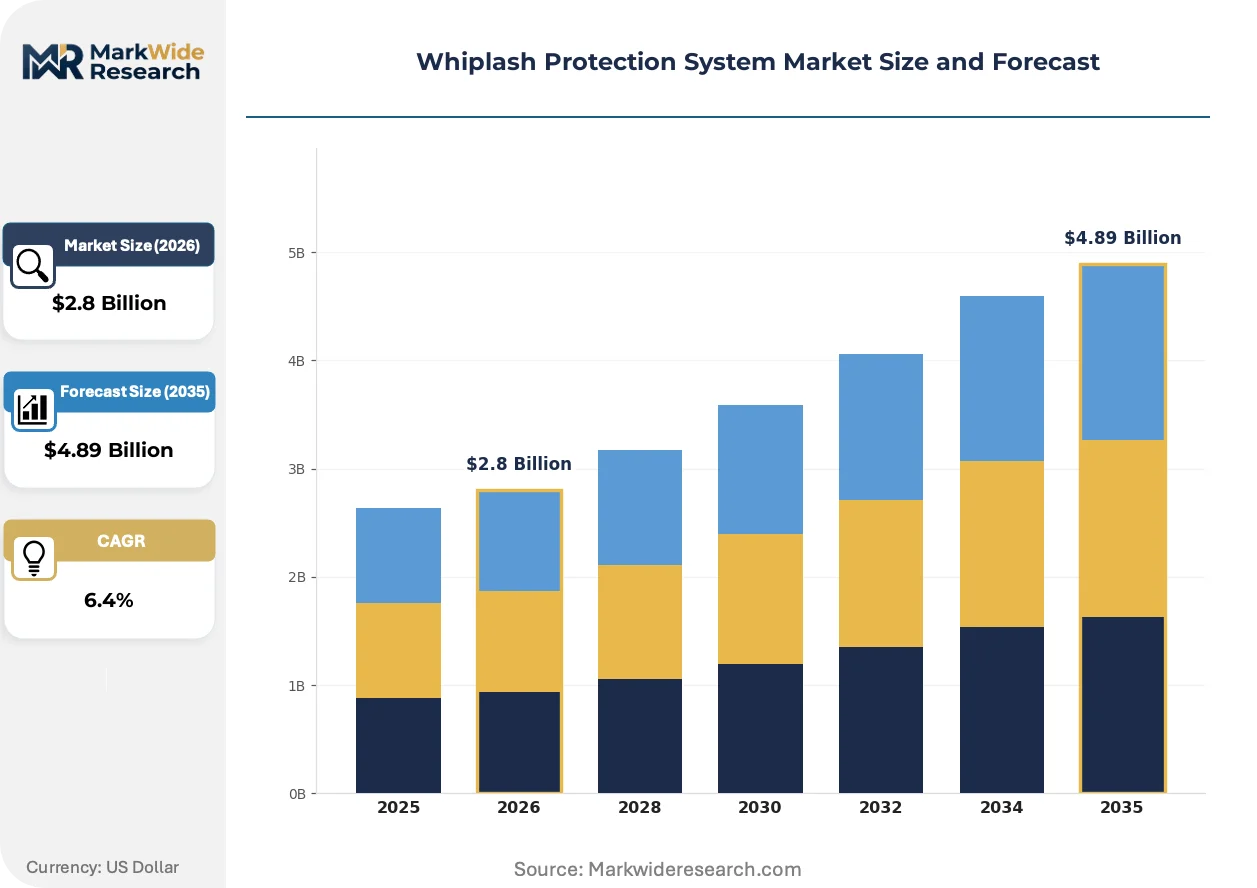
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Systems, Passive Systems, Integrated Solutions, Standalone Devices End User: Automakers, Aftermarket Providers, Fleet Management, OEMs Technology: Sensor-Based, Mechanical Systems, Software Solutions, Hybrid Systems Installation Type: Pre-Installed, Retrofitted, DIY Kits, Professional Installations |
| Companies Covered | Denso Corporation, Hyundai Mobis, Robert Bosch GmbH, Grammer AG, Delphi Automotive, Continental AG, Lear Corporation, Takata Corporation, Autoliv Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whiplash Protection System Market Strategic Shifts & Innovations
The evolution from passive, inertia-driven mechanisms to intelligent, electronically controlled safety interventions is the market's defining technological arc. This transition places a premium on software development and sensor-fusion capabilities, fundamentally changing supplier requirements and competitive dynamics.
Sensor-Fusion for Preemptive Activation
Advanced sensor-fusion technology combines inputs from rear-facing radar, ultrasonic sensors, and in-cabin accelerometers to accurately profile an impending rear-end collision. Automakers in the premium and electric vehicle segments are adopting this approach to enable preemptive headrest positioning. This shift is consolidating the supply base around Tier-1 providers who can deliver a complete hardware and software package, diminishing the role of standalone mechanical component makers.
Stricter Global Testing Standards
New testing protocols, such as those being implemented under Japan's automotive safety framework, are placing greater emphasis on the dynamic performance of head restraints during low-to-moderate speed rear impacts. This regulatory action compels manufacturers to re-evaluate and often redesign their seating and headrest systems to meet more demanding neck injury criteria. The passenger car segment, particularly vehicles intended for export, is most directly impacted, accelerating the move away from static headrests.
Bundled System Procurement
Automakers are increasingly sourcing complete seating systems with pre-integrated and certified whiplash protection features. This disrupts the traditional component-level procurement model, favoring large, vertically integrated seating manufacturers over smaller, specialized headrest or activator suppliers. The trend is most prominent in North America and Europe, where OEMs leverage the scale of global vehicle platforms to streamline their supply chains and reduce integration complexity.
Whiplash Protection System Market Segmentation
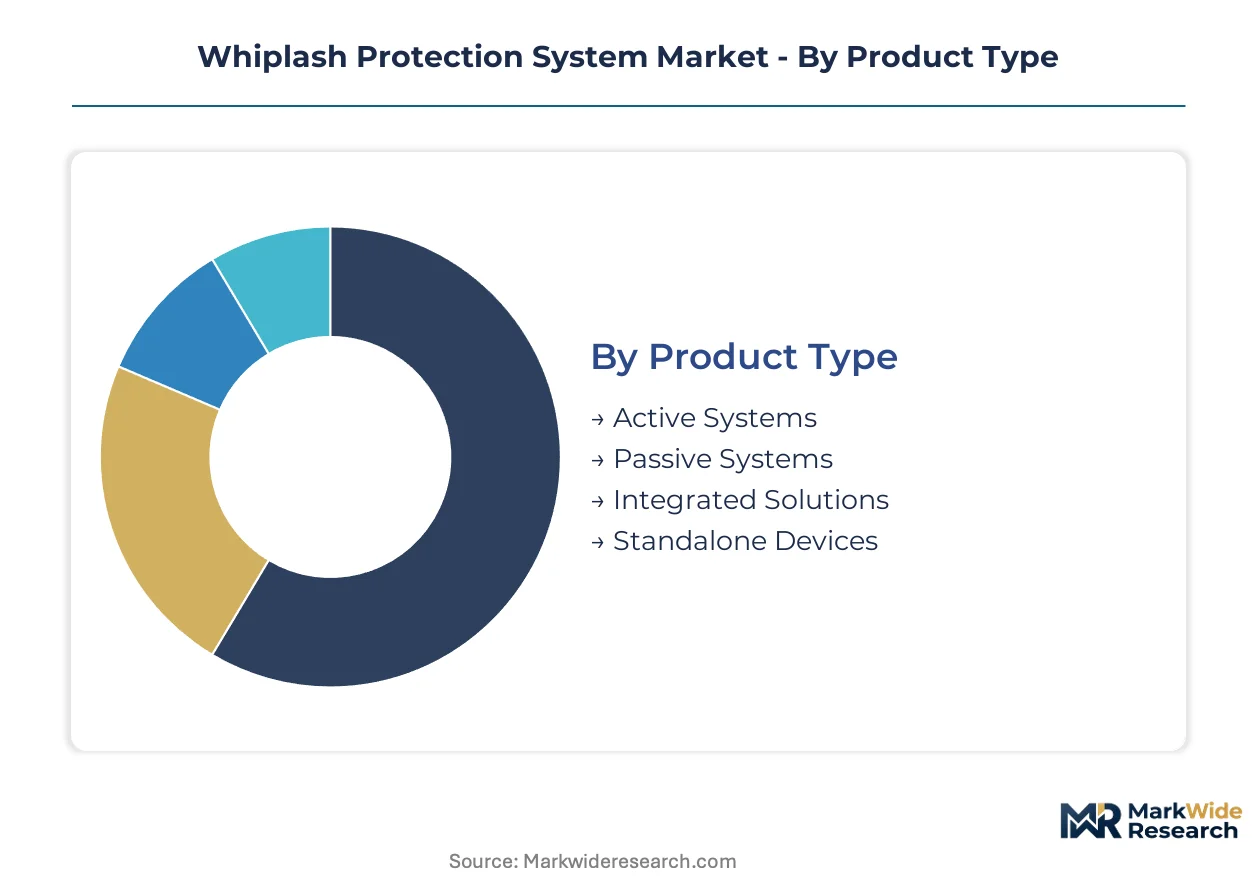
The Whiplash Protection System market segments by product type, end user, technology, and installation type, reflecting the diverse approaches to occupant safety. Understanding these segments helps clarify where innovation is concentrating and how regulatory mandates influence adoption across different vehicle categories. This granular view reveals the distinct value propositions and market dynamics for each system configuration.
Product Type:
The customization-vs-standardization spectrum significantly influences the product type offerings within whiplash protection systems. Automakers balance the need for highly integrated, custom solutions with the efficiency of standardized modular components.
- Active Systems:These electronically controlled systems use sensors to detect an impending rear impact, moving the headrest forward and upward preemptively. Demand for active systems is concentrating in premium and mid-range passenger vehicles, driven by Euro NCAP's rigorous safety assessments.
- Integrated Solutions:These systems combine whiplash protection directly into advanced seating platforms, often supplied as a complete module to vehicle manufacturers. European and North American OEMs increasingly procure these comprehensive solutions to streamline vehicle assembly and certification processes.
- Passive Systems:These mechanical systems rely on the occupant's inertia during a collision to activate the headrest movement.
- Standalone Devices:These are individual components or aftermarket add-ons, offering basic protection without deep vehicle integration.
Most installed capacity flows through Passive Systems. Expansion is steepest in Active Systems.
End User:
Customer type significantly shapes the procurement and deployment strategies for whiplash protection systems, with distinct requirements for volume, integration, and certification. Each end-user segment prioritizes different aspects of system performance and cost-effectiveness.
- Automakers:Major vehicle manufacturers integrate whiplash protection systems directly into new car designs, prioritizing compliance with global safety standards like NHTSA and Euro NCAP. This segment demands highly engineered, certified solutions for mass production.
- OEMs:Original Equipment Manufacturers, often Tier-1 suppliers, develop and produce complete seating systems or specialized modules containing whiplash protection for direct supply to automakers. Their focus is on scalable production and seamless integration into vehicle platforms.
- Aftermarket Providers:These companies supply replacement parts or upgrade components for existing vehicles, often focusing on repair and enhancement.
- Fleet Management:Operators of large vehicle fleets procure systems for their vehicles, balancing safety requirements with long-term maintenance costs and durability.
The primary customer base for advanced systems consists of Automakers, while Fleet Management represents a growing segment for standardized solutions.
Technology:
The market's technological maturity dictates the sophistication and performance capabilities of whiplash protection systems, with a clear evolution towards more proactive and data-driven solutions. Innovation drives differentiation in system responsiveness and injury mitigation.
- Sensor-Based:These technologies utilize radar, ultrasonic sensors, and accelerometers to detect impact severity and direction, enabling preemptive headrest deployment. Premium vehicle segments in Japan and Germany are concentrating demand for these advanced, rapid-response systems.
- Hybrid Systems:These combine mechanical components with electronic sensors, offering a balance between cost-effectiveness and enhanced performance over purely passive designs. The mid-range vehicle segment is increasingly adopting these balanced protection solutions.
- Mechanical Systems:These purely physical mechanisms react to crash forces, moving the headrest based on occupant inertia.
- Software Solutions:These primarily involve the algorithms and control logic that govern active and hybrid whiplash protection systems.
Sensor-Based technologies exhibit the highest growth trajectory, while Mechanical Systems still account for a substantial installed base.
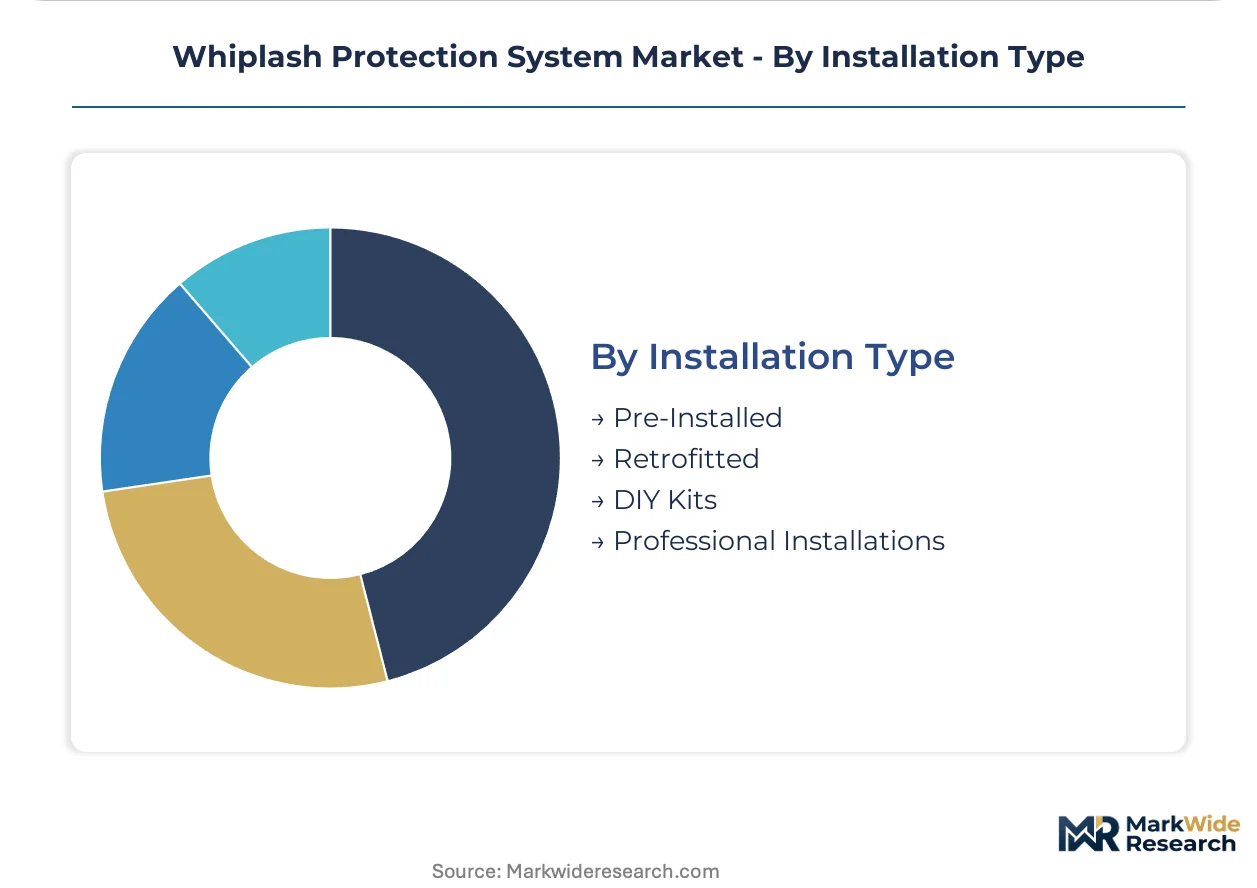
Installation Type:
Volume considerations significantly influence the prevalence of different installation types for whiplash protection systems, with factory integration dominating new vehicle production. The ease of implementation and certification requirements shape market penetration.
- Pre-Installed:These systems are integrated into the vehicle during the manufacturing process, ensuring optimal performance and compliance with safety regulations. New vehicle sales in North America and Europe primarily drive demand for factory-installed systems.
- Professional Installations:Certified technicians install these systems post-manufacture, often in specialized aftermarket or fleet service centers. This segment serves older vehicles or specific fleet upgrade requirements.
- Retrofitted:These involve modifying existing vehicle components to incorporate whiplash protection, typically for older models.
- DIY Kits:Consumers purchase and install these kits themselves, usually offering basic, non-certified headrest enhancements.
The largest volume of whiplash protection systems is Pre-Installed in new vehicles. Professional Installations are gaining traction for fleet upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage influences the global distribution of automotive safety component manufacturing, with some production migrating to regions offering a more favorable cost-of-compliance gap. Automakers seek to balance stringent safety standards in mature markets with cost efficiencies in emerging production hubs. This dynamic shapes investment in advanced whiplash protection systems across key automotive manufacturing nations.
Germany
Demand for active whiplash protection systems stems from the country's premium automotive segment and high consumer safety awareness. Euro NCAP's rigorous testing protocols directly compel manufacturers to integrate sophisticated systems. Major automotive clusters in Bavaria and Baden-Württemberg drive innovation in sensor-based technologies and integrated seating solutions.
Japan
The emphasis on dynamic performance in new automotive safety frameworks, such as those from METI, fuels the adoption of advanced whiplash protection. Consumers actively seek vehicles with superior safety ratings, influencing purchasing decisions across all segments. Automotive research and development centers in Aichi Prefecture and Kanagawa are pioneering next-generation pre-crash activation systems.
United States
NHTSA safety mandates and consumer demand for advanced driver assistance systems drive the integration of whiplash protection into new vehicles. The Insurance Institute for Highway Safety (IIHS) ratings also influence manufacturer design choices. Detroit's automotive manufacturing base and Silicon Valley's tech companies collaborate on V2X communication and sensor fusion for enhanced safety features.
China
Rapid expansion of the domestic automotive market and evolving safety standards, including GB standards, are accelerating the adoption of integrated whiplash protection. Local OEMs are increasingly focusing on safety features to compete with international brands. Major production centers in the Yangtze River Delta and Pearl River Delta are becoming significant hubs for automotive safety system manufacturing.
India
Anticipated updates to vehicle safety regulations by BIS will create a significant future growth avenue for whiplash protection systems, particularly in the mid-range vehicle segment. Cost-effective, hybrid solutions are gaining traction among domestic manufacturers. Automotive component suppliers in Pune and Chennai are developing localized solutions to meet future compliance requirements.
Whiplash Protection System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure for whiplash protection systems. The competitive landscape features a mix of large, diversified automotive suppliers and niche component manufacturers. Strategic archetypes include integrated system providers, specialized component innovators, and cost-focused mechanical suppliers. Dominant competitive moves involve strategic partnerships for technology co-development and portfolio diversification into software-defined safety solutions.
Integrated system providers such as Continental AG exemplify the trend towards comprehensive hardware and software packages. Autoliv Inc. represents a specialized component innovator, focusing on pyrotechnic and mechanical activators for safety systems. Lear Corporation occupies a position as a seating platform specialist, integrating whiplash protection directly into its advanced seating modules for major OEMs.
| Leading Market Players |
|---|
| Denso Corporation |
| Hyundai Mobis |
| Robert Bosch GmbH |
| Grammer AG |
| Delphi Automotive |
| Continental AG |
| Lear Corporation |
| Takata Corporation |
| Autoliv Inc. |
| Others |
Cost & Logistics Intelligence
Automaker procurement concentration drives a contract-based pricing model for whiplash protection systems, favoring suppliers capable of large-scale, integrated solutions. This structure incentivizes long-term agreements over spot market transactions, particularly for advanced active systems.
Pricing Analysis
Direct-to-OEM discount structures dominate pricing for whiplash protection systems, reflecting the high volume and integration requirements of vehicle manufacturers. Pricing stratifies across premium, standard, and economy tiers based on technology sophistication and certification level like Euro NCAP performance. Pricing pressure stems from the significant cost differential between basic mechanical systems and advanced sensor-based active systems, particularly in price-sensitive economy segments. Premium vehicle segments exhibit lower price sensitivity due to consumer demand for advanced safety features.
Supply Chain Analysis
Domestic-content mandates, such as those anticipated in India, are reshaping sourcing strategies for whiplash protection systems. Supply concentration for advanced components centers on Germany and Japan for sensor technology, while China is a significant manufacturing hub for mechanical parts. The supply chain draws from specialized inputs like pyrotechnic gas generators and advanced sensors. Single-source vulnerability for these specialized components presents a structural risk. Distribution runs through Tier-1 suppliers providing complete seating systems directly to automakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Whiplash Protection System market functions as a regulatory compounder, with anticipated updates to vehicle safety standards by India's BIS creating a significant future growth avenue.
For Market Incumbents:Lock in long-term supply agreements with major OEMs to secure volume and defend market share against emerging competitors. Deepen vertical integration into software development and sensor fusion to mitigate technical integration complexity and software validation burdens. Invest in advanced testing and certification for next-generation systems to maintain a lead in Euro NCAP and NHTSA ratings, countering aftermarket competition.
For New Entrants and Emerging Players:Launch via strategic partnerships with mid-range vehicle manufacturers in emerging markets like India, focusing on cost-effective hybrid solutions. Target the underserved mid-range sedan and SUV markets with semi-active systems, offering a balance of performance and affordability. Localized manufacturing and supply chains can provide a significant go-to-market advantage by meeting regional compliance requirements and reducing costs.
For Investors and Strategic Acquirers:Automotive electronics and safety system integrators are the most active acquirers in this space, seeking to bolster software and sensor capabilities. The market offers long-term viability, driven by persistent regulatory pressure for enhanced vehicle safety. Acquisition targets should include specialized sensor manufacturers, software validation firms, and providers of cost-effective semi-active systems. The signal to watch is the widespread adoption of V2X communication for pre-crash activation.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Safety Investment | This enhances system intelligence and responsiveness, aligning with regulatory demands for preemptive protection. |
| Mid-Range Segment Product Development | This unlocks significant volume growth by addressing a currently underserved and price-sensitive market. |
| Regional Manufacturing Expansion | This facilitates compliance with local content rules and reduces logistics costs in emerging automotive hubs. |
| V2X Communication Partnership | This enables pre-crash activation capabilities, setting a new standard for advanced whiplash protection. |
| Certification and Testing Center Expansion | This accelerates product validation and ensures compliance with evolving global safety protocols like Euro NCAP. |
Research Approach
Multiple input streams — primary interviews, secondary research, and proprietary databases — were reconciled to construct a comprehensive market view. Industry stakeholders, including OEM platform engineers, Tier 1 supplier procurement leads, automotive safety regulators, and specialized component R&D leads, provided qualitative and quantitative insights. Secondary validation drew from Euro NCAP crash test reports, NHTSA safety mandates, vehicle production databases, and academic research on whiplash injury mechanics. This approach enabled robust bottom-up and top-down triangulation.
Historical data and expert panel input were cross-referenced to project market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including product type, end user, technology, installation type, and vehicle segment. Compound annual growth rates were derived through regression analysis of historical trends and validated against anticipated regulatory update schedules. New vehicle sales projections and evolving safety standards served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen supply chain disruptions or slower-than-anticipated regulatory enforcement. Forecasts reflect assumptions regarding technological advancements and consumer safety awareness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Park Assist System Market
Automotive Safety and Security Systems
Automotive Active Safety System Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Anti-Fog Lights Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
Global Highway Driving Assist Market
Automotive Safety and Security Systems
Wearable Motorcycle Airbags Market
Automotive Safety and Security Systems
Start Stop System Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
Global Automotive Parking Sensors Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Global Automotive Radar Sensors Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market