
 Australia Automotive Airfilters Market | 2026-2036
Australia Automotive Airfilters Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Automotive Airfilters Market Outlook
Buyer concentration among national fleet operators is realigning procurement volumes toward consolidated long-term service contracts. MANN+HUMMEL leverages its European engineering heritage to dominate premium cabin filter supply chains. Robert Bosch (Australia) Pty Ltd. anchors its position through dense distribution networks spanning metropolitan service centers. Sakura Filters Australia competes aggressively on aftermarket pricing for engine filtration.
Automotive airfilters are engineered media assemblies designed to remove particulate matter, pollen, and contaminants from air streams entering vehicle cabins and engine combustion chambers, typically constructed from pleated cellulose, synthetic non-woven layers, or activated carbon composites with filtration efficiencies calibrated to micron-scale thresholds. Their primary purpose spans occupant health protection, engine wear reduction, and emissions compliance across passenger and commercial vehicle platforms. Engine filters occupy the largest volume share given mandatory replacement intervals tied to manufacturer service schedules, while cabin filters integrating HEPA and activated carbon layers represent the fastest-growing material configuration as consumer sensitivity to interior air quality intensifies. Aftermarket providers capture significant margin pools through branded premium tiers, though OEM captive channels sustain pricing power on warranty-linked replacements.
TGA-aligned automotive component safety frameworks and Australian Design Rules administered by the Department of Infrastructure influence filter performance certifications and market access requirements for both domestic manufacturers and importers. State-level environmental agencies in Victoria and New South Wales enforce escalating particulate emissions benchmarks that directly expand demand for higher-efficiency engine intake media. Stakeholders must monitor pending revisions to Australian Design Rule emissions thresholds and assess material substitution strategies before compliance deadlines crystallize.
Market Dynamics
Fleet procurement consolidation across Western Australia and Victoria is compressing distributor margins while elevating contract scale requirements for aftermarket suppliers serving national service networks.
Growth Catalysts
- Australian Design Rule emissions thresholds:Tightening particulate limits for commercial vehicles are expanding replacement frequency for high-efficiency engine intake media across heavy-duty fleets.
- HEPA-activated carbon composites:Cabin filter material upgrades are capturing premium positioning as operator sensitivity to interior air quality intensifies in urban service corridors.
- Perth and Melbourne:Concentrated demand along these metropolitan service corridors is anchoring distribution network expansion and localized inventory positioning strategies.
Market Restraints
- Synthetic non-woven supply concentration:Import dependency for specialized filtration media creates exposure to freight cost volatility and currency fluctuation.
- Cellulose price cycles:Raw material input costs for conventional pleated engine filters compress margin pools for economy-tier aftermarket providers.
- Extended service intervals:Manufacturer-recommended replacement schedules are lengthening, directly reducing per-vehicle filter consumption rates.
Strategic Opportunities
- Western Australia fleet operators:Expanded cabin filter replacement schedules among mining and logistics fleets create volume anchors for preventive maintenance contracts.
- TGA-equivalent certification pathways:Alignment with therapeutic goods administration standards for automotive components opens premium positioning for health-conscious cabin filtration.
- Direct-to-fleet digital procurement:Bypassing traditional parts distributors through integrated fleet management platforms reduces channel friction for national operators.
Industry Challenges
- Multi-grade inventory complexity:Stocking requirements across pleated cellulose, synthetic non-woven, and activated carbon configurations strain working capital for regional distributors.
- Micron-scale calibration certification:Demonstrating filtration efficiency to Australian Design Rule benchmarks requires capital-intensive testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Automotive Airfilters Market |
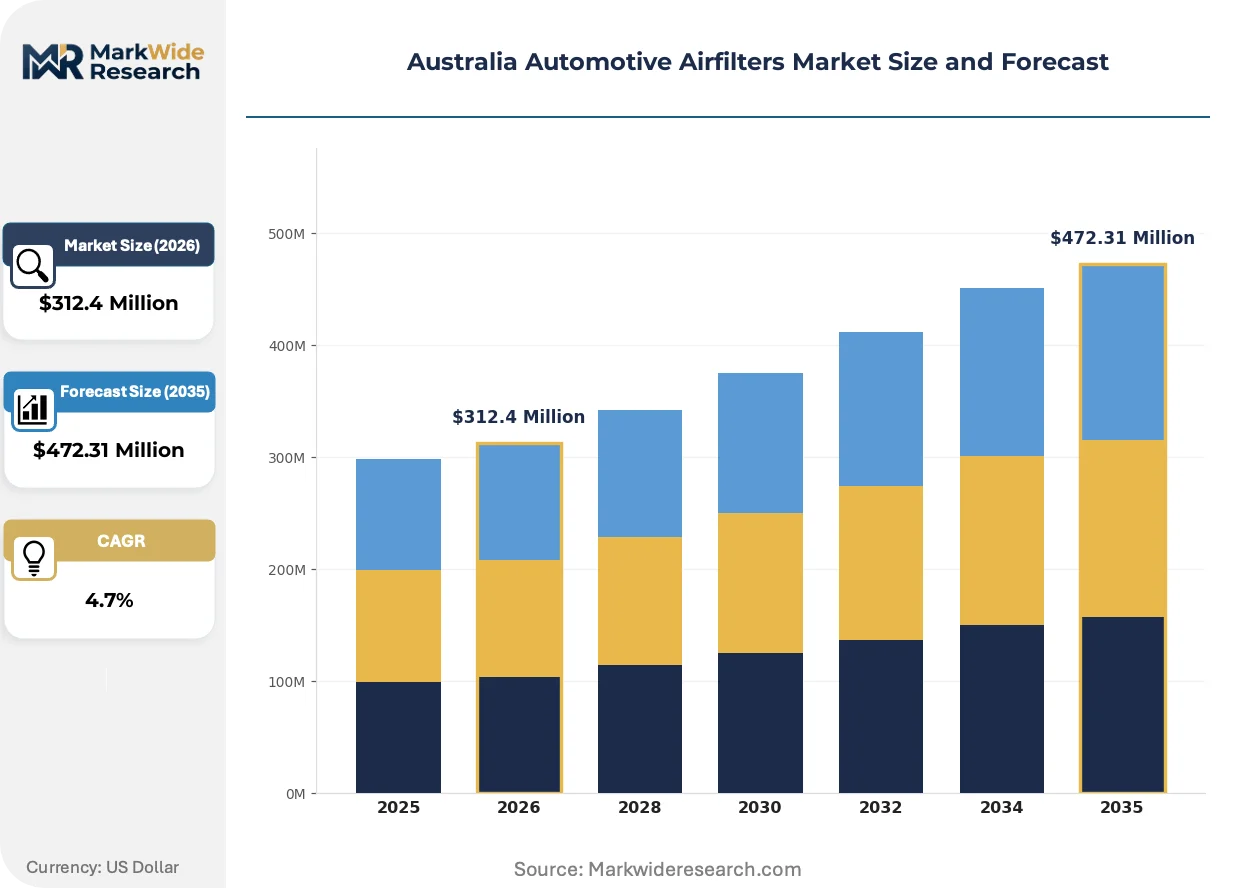
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabin Filters, Engine Filters, Intake Filters, Fuel Filters End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Service Centers Material: HEPA, Activated Carbon, Foam, Paper Technology: Electrostatic, Synthetic Media, Pleated, Non-Woven |
| Companies Covered | MANN+HUMMEL, Robert Bosch (Australia) Pty Ltd., Denso Corporation, Sakura Filters Australia, Cabin Air Filters Australia, K&N Engineering, Purolator Filters LLC, Camfil Australia Pty Ltd., Sy-Klone International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Automotive Airfilters Market Strategic Shifts
Material science advances and procurement digitization are restructuring how filtration media flows from manufacturers to end-users across Australian automotive service networks.
Synthetic non-woven layers incorporating electrostatic charging are overtaking conventional pleated cellulose in engine intake applications. Heavy-duty fleet operators in Queensland and New South Wales are adopting these media at accelerated replacement cycles. The technology is overtaking legacy materials by enabling extended service intervals without sacrificing particulate capture efficiency, compressing total cost of ownership calculations for high-mileage vehicles.
Australian Design Rule revisions administered by the Department of Infrastructure are mandating stricter verification protocols for aftermarket filter performance claims. Component suppliers must now document filtration efficiency against standardized test aerosols before market authorization. Engine filtration categories face the steepest compliance burden, with Victorian environmental agency enforcement driving accelerated certification timelines among import-dependent distributors.
Long-term service contracts bundling filter replacement with preventive maintenance are displacing transactional parts purchasing among national fleet operators. Traditional wholesale distributors serving independent repair shops face volume erosion as direct manufacturer-fleet agreements capture scheduled maintenance spend. This pattern concentrates most visibly along Perth's mining logistics corridors and Melbourne's interstate freight terminals.
Australia Automotive Airfilters Market Segmentation
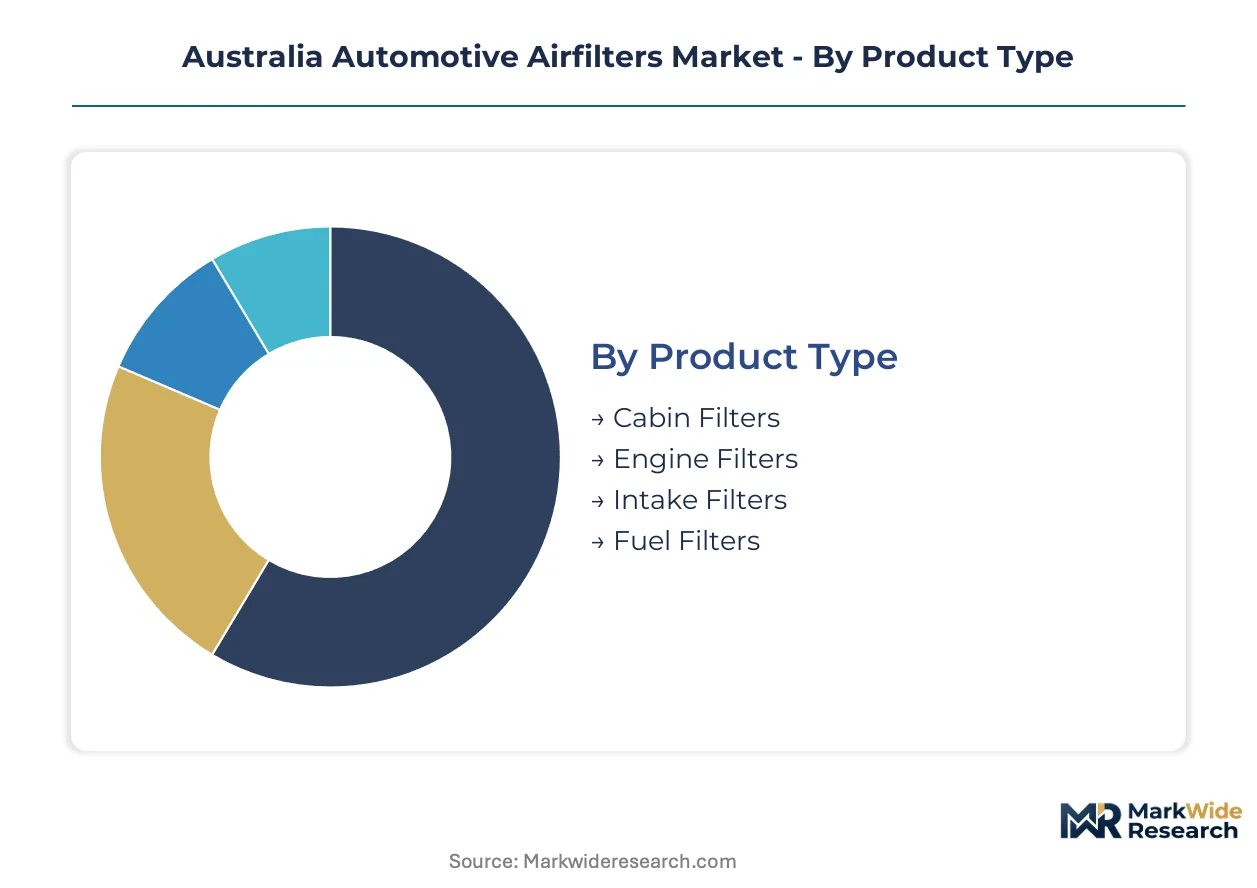
Segmentation across product type, material composition, and procurement channel determines margin structure and competitive positioning within Australia's automotive filtration landscape. Fleet procurement consolidation and emissions compliance timelines create divergent growth trajectories across these dimensions.
Product Type:
Performance specifications and replacement intervals vary sharply across intake locations, with combustion chamber protection commanding fundamentally different engineering priorities than occupant health applications.
- Engine Filters:Pleated cellulose and synthetic non-woven media assemblies protect combustion chambers from abrasive particulate ingress. Mandatory replacement intervals tied to manufacturer service schedules sustain predictable demand volumes across Western Australia mining fleets and Melbourne freight corridors. Australian Design Rule emissions thresholds are compressing replacement cycles for heavy-duty commercial applications.
- Cabin Filters:Multi-layer configurations integrating HEPA and activated carbon composites remove pollen, particulate matter, and volatile organic compounds from occupant air streams. Perth and Melbourne service corridors are anchoring demand concentration as operator sensitivity to interior air quality intensifies. Fleet operators in Western Australia are expanding replacement schedules beyond manufacturer minimums.
- Intake Filters:Engine intake media positioned upstream of air metering systems require precise flow calibration.
- Fuel Filters:Contaminant removal from diesel and gasoline delivery systems protects injector systems from abrasive wear.
Engine filters lead on scale; cabin filters lead on momentum.
End User:
Channel structure determines pricing power and contract duration, with captive OEM relationships sustaining premium positioning against fragmented aftermarket competition.
- OEMs:Original equipment manufacturers specify filtration media during vehicle platform development, locking in multi-year supply agreements with performance guarantees. Warranty-linked replacement schedules sustain pricing power through authorized dealer networks across Australian metropolitan centers.
- Aftermarket Providers:Independent distributors and branded component suppliers capture margin pools through premium tier positioning and economy alternatives. National fleet procurement consolidation is compressing traditional wholesale margins while elevating contract scale requirements.
- Vehicle Assemblers:Local manufacturing operations source filtration components for domestic production lines.
- Service Centers:Independent repair workshops and franchise operations execute replacement services on transactional demand.
Aftermarket providers dominate transaction volume; OEMs dominate value capture per unit.
Material:
Substrate selection governs filtration efficiency, service interval duration, and total cost of ownership calculations across passenger and commercial vehicle applications.
- HEPA:High-efficiency particulate air media capture sub-micron particles with calibrated pressure drop characteristics. Urban service corridors in Melbourne and Perth are driving specification upgrades as emissions compliance tightens.
- Activated Carbon:Adsorptive layers neutralize volatile organic compounds and odor molecules through porous surface chemistry. Mining fleet operators in Western Australia are specifying carbon-integrated cabin configurations for extended cabin air quality protection.
- Foam:Open-cell polyurethane structures provide coarse pre-filtration with washable service characteristics.
- Paper:Pleated cellulose remains the cost-optimized standard for conventional engine intake applications.
Paper dominates unit economics; HEPA dominates specification upgrades.
Technology:
Manufacturing process and media architecture determine particulate capture efficiency against pressure drop trade-offs and service interval optimization.
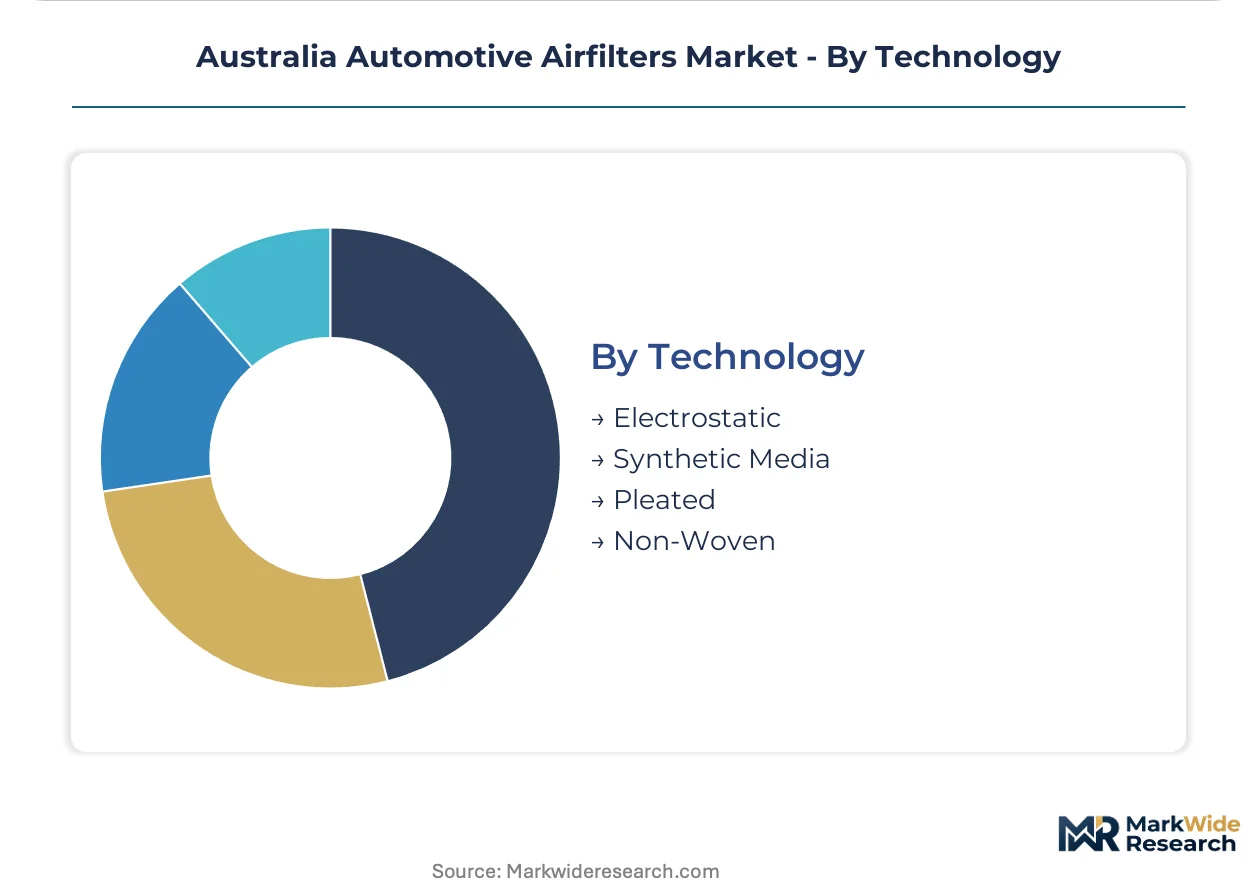
- Synthetic Media:Melt-blown and spun-bond non-woven layers with electrostatic charging enable extended service intervals without sacrificing capture efficiency. Queensland and New South Wales heavy-duty fleets are adopting these configurations at accelerated replacement cycles.
- Electrostatic:Charged fiber matrices enhance sub-micron particle attraction without dense media packing. TGA-equivalent certification pathways are opening premium positioning for health-conscious cabin filtration specifications.
- Pleated:Folded cellulose or synthetic configurations maximize surface area within compact housing dimensions.
- Non-Woven:Random fiber orientation produces tortuous flow paths for mechanical particle entrapment.
Pleated configurations anchor installed base; synthetic media is climbing the fastest on replacement specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's automotive airfilter demand diverges sharply from New Zealand's smaller fleet base, with state-level mining logistics and urban freight corridors driving replacement volume concentration. Western Australia's heavy-duty commercial fleets operate under distinct particulate exposure profiles compared to eastern seaboard passenger vehicle patterns.
Western Australia
Mining fleet operators in the Pilbara and Goldfields regions are accelerating cabin filter replacement cycles beyond manufacturer minimums. TGA-equivalent automotive component standards administered at the federal level influence certification requirements for components entering these remote service networks. Perth anchors distribution infrastructure for preventive maintenance contracts spanning the state's resource extraction corridors.
Victoria
Melbourne's interstate freight terminals generate concentrated engine filter demand from commercial vehicle operators facing tightening Australian Design Rule emissions thresholds. The state's environmental protection agency enforces particulate benchmarks that expand replacement frequency for heavy-duty intake media. Geelong and Melbourne's western industrial zones host service center clusters executing fleet maintenance at scale.
New South Wales
Sydney's metropolitan density drives cabin filter specification upgrades toward HEPA-activated carbon configurations. The state's environmental regulator applies pressure on commercial vehicle emissions compliance that filters into aftermarket procurement patterns. Newcastle and Wollongong industrial corridors sustain engine filter volume from port logistics and steel manufacturing fleet operations.
Queensland
Heavy-duty fleets in the Bowen Basin mining region and Brisbane's freight networks are adopting synthetic non-woven engine media at accelerated replacement cycles. Australian Design Rule verification protocols administered by the Department of Infrastructure shape aftermarket authorization requirements. Townsville and Cairns service hubs support remote mining and agricultural equipment filtration needs.
Australia Automotive Airfilters Market Competitive Environment
European engineering heritage anchors one competitive tier; Asia-Pacific manufacturing specialists hold cost-optimized positioning. The market exhibits moderate concentration with three to five entities capturing disproportionate share in premium cabin filtration. Strategic archetypes include: OEM-captive suppliers with warranty-linked distribution, independent aftermarket brands competing on replacement pricing, and direct-to-fleet service integrators. Competitive moves center on long-term service contract aggregation and material science differentiation for emissions compliance.
Within the premium-tier vector, MANN+HUMMEL occupies a position exemplifying European engineering-led cabin filter supply. Robert Bosch (Australia) Pty Ltd. represents the OEM-captive archetype with metropolitan distribution density. Sakura Filters Australia anchors the aftermarket pricing tier competing on engine filtration replacement cost.
| Leading Market Players |
|---|
| MANN+HUMMEL |
| Robert Bosch (Australia) Pty Ltd. |
| Denso Corporation |
| Sakura Filters Australia |
| Cabin Air Filters Australia |
| K&N Engineering |
| Purolator Filters LLC |
| Camfil Australia Pty Ltd. |
| Sy-Klone International |
| Others |
Value Chain & Pricing Dynamics
Fleet procurement consolidation across Western Australia and Victoria is compressing distributor margins while forcing supply base rationalization toward manufacturers capable of long-term contract scale. This buyer-side concentration elevates pricing power for tier-one suppliers with TGA-equivalent certification and synthetic media production capabilities, while economy-tier providers face accelerated margin erosion.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for pleated cellulose engine media, intensifying cost competition among import-dependent Australian distributors. Pricing stratifies across premium, standard, and economy tiers, with HEPA-activated carbon cabin configurations commanding substantial premiums over conventional paper-based alternatives. Cost compression in the economy tier is intensifying because national fleet operators are consolidating procurement volumes into preventive maintenance contracts. Mining fleet operators in Western Australia exhibit the lowest price sensitivity due to total cost of ownership calculations, while independent service centers in metropolitan corridors face acute margin pressure.
Supply Chain Analysis
Australian Design Rule compliance requirements and therapeutic goods administration standards for automotive components are reshaping sourcing criteria toward certified manufacturers with documented testing infrastructure. Filtration media supply draws from Germany, China, and Japan, with specialized synthetic non-woven layers exhibiting concentrated sourcing from East Asian producers. Raw material dependencies span melt-blown polypropylene, activated carbon substrates, and electrostatic charging agents. Single-source vulnerability for electrostatically charged synthetic media creates exposure to freight cost volatility and currency fluctuation. Distribution runs through national parts distributors, direct-to-fleet digital platforms, and OEM-captive dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia Automotive Airfilters Market reads as a late-cycle quality story, with operator sensitivity to cabin air quality and emissions compliance tightening specification thresholds toward premium HEPA-activated carbon configurations.
For Market Incumbents: Anchor market position through backward integration into synthetic non-woven media production, reducing exposure to import cost volatility while capturing margin pools from specification upgrades. Deepen certification investment against Australian Design Rule verification protocols to create barriers for import-dependent challengers. Lock in multi-year preventive maintenance contracts with Western Australia mining fleets before direct-to-fleet digital procurement platforms erode traditional distributor relationships. For New Entrants and Emerging Players: The price-point gap between MANN+HUMMEL-tier premium cabin filtration and Sakura-tier economy engine media creates white-space opportunity for mid-market synthetic media specialists. Target Queensland and New South Wales heavy-duty fleet operators adopting electrostatically charged configurations at accelerated replacement cycles. Penetrate through direct digital procurement integration with fleet management platforms, bypassing established wholesale distributor networks. For Investors and Strategic Acquirers: Asymmetric upside sits with synthetic media specialists possessing TGA-equivalent certification pathways and existing relationships with Australian Design Rule testing infrastructure. Long-term viability over a five-to-ten year window favors manufacturers with demonstrated filtration efficiency documentation and capacity to serve national fleet contract scale. Watch for inflection when Victorian and New South Wales environmental agencies announce pending particulate emissions benchmark revisions.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Media Manufacturing Scale-Up | Captures margin from specification upgrades as HEPA-activated carbon demand accelerates in Perth and Melbourne corridors. |
| TGA-Equivalent Certification Investment | Creates regulatory moat against uncertified imports while opening premium positioning for health-conscious cabin filtration. |
| Direct-to-Fleet Digital Platform Launch | Bypasses traditional wholesale distributors serving independent repair shops facing volume erosion from national contract consolidation. |
| Long-Term Preventive Maintenance Contracts | Locks in scheduled replacement revenue from Western Australia mining and logistics fleets expanding cabin filter service intervals. |
| Backward Integration into Raw Material Supply | Reduces exposure to cellulose price cycles and synthetic non-woven import dependency affecting economy-tier margin pools. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured conversations with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distribution heads, and national fleet maintenance managers with secondary validation. Primary fieldwork drew from vehicle production databases, Australian Design Rule filings with the Department of Infrastructure, customs import records for filtration media, and IHS Markit registration data. Bottom-up demand modeling across replacement intervals and fleet composition triangulated against top-down market sizing from trade flow analysis.
Historical reference periods anchored the projection horizon to observed replacement cycle compression and specification upgrade trajectories across the analysis window. The analytical framework modeled segmentation across product type, material composition, procurement channel, and end-user archetype, with CAGRs derived from trend extrapolation of fleet procurement consolidation and emissions compliance timelines. Synthetic media adoption rates and TGA-equivalent certification penetration served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for electrostatically charged synthetic media would alter the outlook if breakthroughs in extended service interval performance emerge. Forecasts reflect assumptions regarding Australian Design Rule enforcement consistency and fleet operator procurement centralization. Supply disruption from raw material concentration or regulatory delay in pending emissions benchmark revisions could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
South Africa Passenger Vehicles Lubricants Market
Automotive Parts
Electric Parking Brake Actuator Components Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Rear Spoiler Market
Automotive Parts
Speed Bump Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Sintered Silencer Market
Automotive Parts
Automotive Thermal Systems Market