
 Russia Commercial Vehicle Market | 2026-2036
Russia Commercial Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Commercial Vehicle Market Analysis
A chronic shortage of certified diesel engine technicians is unwinding maintenance capacity across Russia's commercial vehicle service network. KAMAZ leverages its in-house vocational training centers to sustain a captive technician pipeline in Tatarstan. GAZ Group anchors light-duty production through its Nizhny Novgorod assembly complex, while SINOTRUK competes aggressively on cost in the heavy-duty import segment.
Russia commercial vehicles encompass chassis-cab platforms, complete trucks, and bus configurations engineered for gross vehicle weights exceeding 3.5 tonnes, with diesel compression-ignition engines dominating propulsion architecture for long-haul torque requirements. These assets serve primary commercial purposes spanning freight haulage, passenger transit, and specialized road-building operations across Russia's vast road network. Heavy duty trucks command the dominant share of value given their centrality to extractive industry logistics and transcontinental freight corridors. Electric powertrains within the fuel-type taxonomy attract policy support but remain nascent outside urban bus deployments in Moscow and Saint Petersburg. Vans and light duty trucks capture disproportionate volume in last-mile delivery services as e-commerce fulfillment networks expand beyond the Central Federal District.
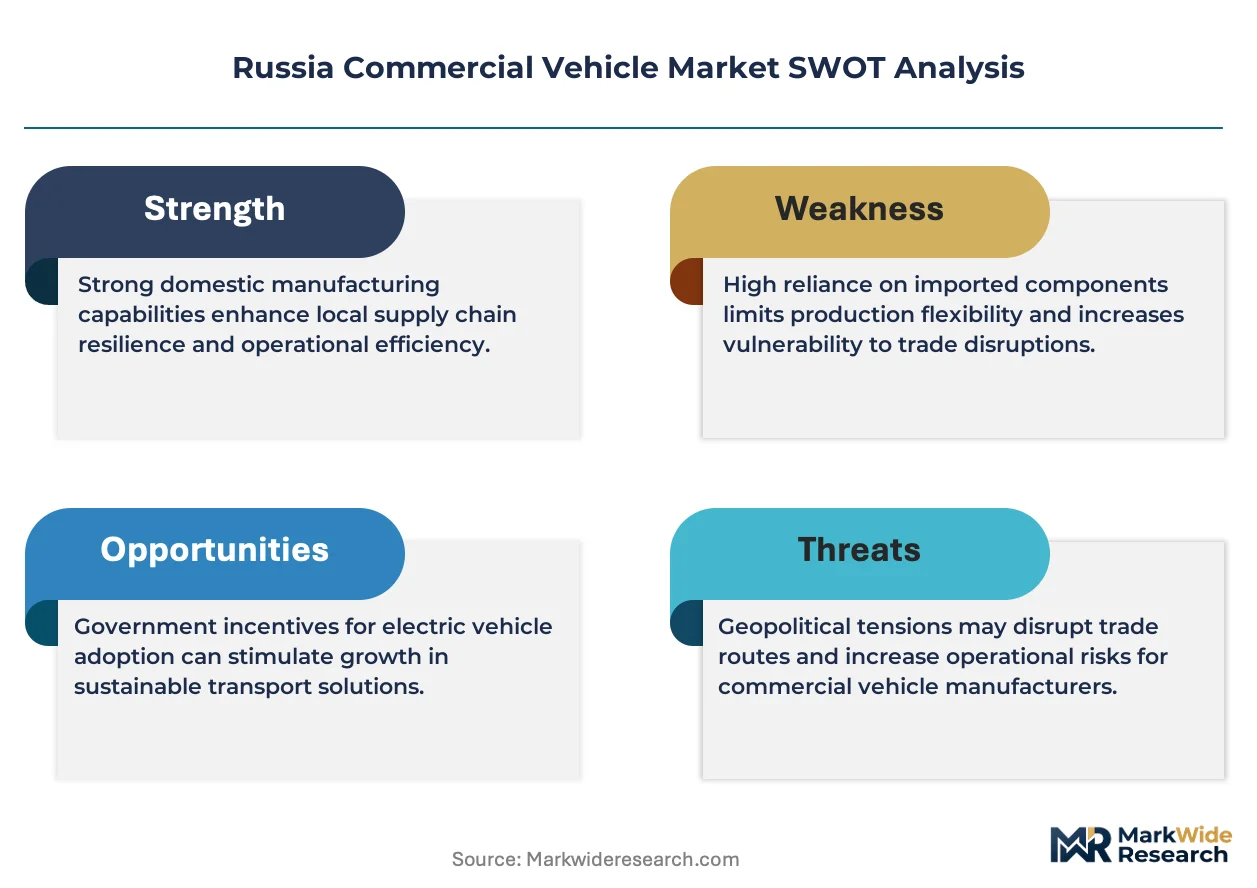
Russia's Federal Technical Regulation on Safety of Wheeled Vehicles, administered by Rosstandart, mandates periodic emissions compliance updates that shape manufacturer product cycles and import eligibility. The Eurasian Economic Union's unified technical regulations, enforced by national certification bodies, create cross-border standardization that eases component sourcing from Belarus and Kazakhstan but restricts non-union suppliers. Russia's national carbon intensity targets, monitored by the Ministry of Economic Development, are redirecting state procurement preferences toward CNG and domestically manufactured platforms. Stakeholders must monitor how sanctions-driven supply chain restructuring affects spare parts availability and whether domestic engine production can scale to replace displaced European component imports.
Market Dynamics
Russia's phased emissions tightening under Federal Technical Regulation on Safety of Wheeled Vehicles is redirecting procurement toward cleaner diesel and CNG platforms while squeezing service capacity through technician shortages.
Growth Catalysts
- E-commerce Fulfillment Networks:Logistics providers across the Russian Far East are accelerating fleet renewals as last-mile delivery corridors deepen beyond the Central Federal District.
- CNG Infrastructure Expansion:State procurement preferences under national carbon intensity targets are redirecting municipal and state-owned fleet orders toward compressed natural gas platforms.
- Ural Industrial Belt Freight Corridors:Extractive industry logistics linking Moscow to the Ural region sustain heavy-duty truck demand through minerals transport and transcontinental haulage contracts.
Market Restraints
- Certified Technician Scarcity:A chronic shortage of diesel engine specialists is unwinding maintenance capacity across Russia's commercial vehicle service network, extending downtime for fleet operators.
- European Component Displacement:Sanctions-driven supply chain restructuring restricts spare parts availability from traditional Western suppliers, forcing reliance on Belarusian and Kazakh sourcing channels.
- Electric Powertrain Limitations:Battery-electric platforms remain technically constrained outside urban bus deployments due to cold-climate range degradation and charging infrastructure gaps in intercity corridors.
Strategic Opportunities
- Siberian Logistics Corridors:Underpenetrated freight routes connecting Novosibirsk to Pacific port facilities offer fleet expansion potential as Asia-Russia trade volumes stabilize.
- Domestic Engine Manufacturing Scale-Up:Import substitution policies create white space for localized powertrain production to replace displaced European diesel and transmission assemblies.
- Telematics-Enabled Fleet Management:Convergence of GPS tracking platforms with predictive maintenance algorithms is opening subscription revenue streams for service providers targeting mid-size haulage operators.
Industry Challenges
- Vocational Training Pipeline Gaps:The shortage of certified diesel technicians forces fleet operators to internalize training costs or accept extended vehicle downtime, compressing operating margins.
- Eurasian Economic Union Certification Timelines:Cross-border type-approval harmonization creates bureaucratic friction for component sourcing from Belarus and Kazakhstan, delaying vehicle homologation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Commercial Vehicle Market |
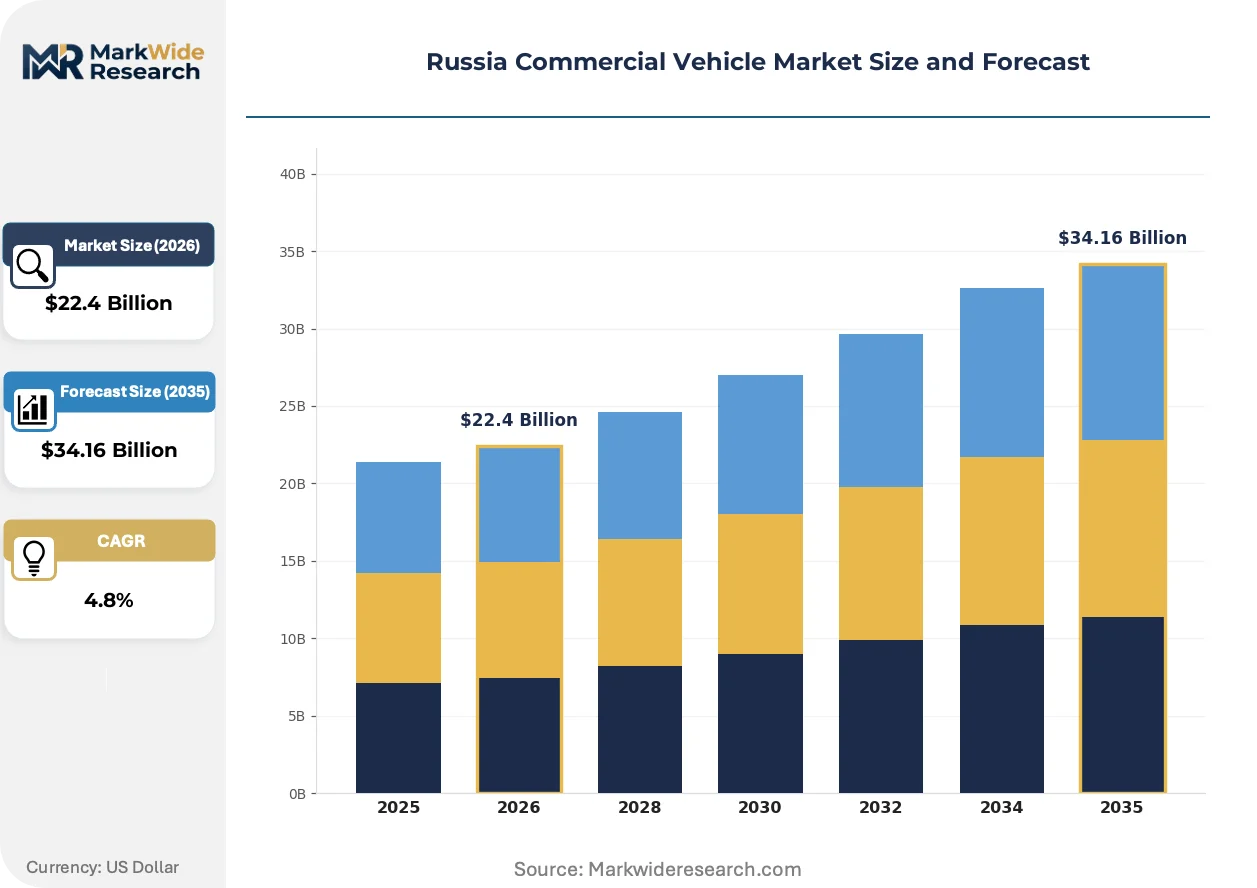
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $34.16 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty Trucks, Heavy Duty Trucks, Buses, Vans Fuel Type: Diesel, Petrol, CNG, Electric End User: Logistics Providers, Construction Companies, Public Transportation, Delivery Services Application: Freight Transportation, Passenger Transport, Urban Delivery, Road Construction |
| Companies Covered | UAZ, SHACMAN, KAMAZ, BAZ, FAW Trucks Co., Ltd., GAZ Group, SINOTRUK, Volvo AB, URAL Automotive Plant, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Commercial Vehicle Market Emerging Trajectories
Propulsion architecture and fleet management systems are diverging across multiple fronts as regulatory pressure, supply chain restructuring, and buyer behavior reshape competitive requirements.
Compressed natural gas powertrains are bifurcating the heavy-duty segment between long-haul diesel retainers and urban-regional CNG adopters. Municipal procurement offices in Moscow and Saint Petersburg are mandating CNG compliance for new bus contracts, while private freight operators in the Ural corridor maintain diesel dominance for torque-demanding routes. This technology split is compressing single-fuel fleet strategies and forcing multi-platform maintenance investments.
Rosstandart's phased emissions compliance updates are compressing product development cycles for domestic manufacturers. The Federal Technical Regulation on Safety of Wheeled Vehicles mandates periodic particulate matter and nitrogen oxide threshold reductions that shape engine calibration and after-treatment system investments. Heavy-duty chassis-cab platforms face the steepest redesign burden as they must satisfy both long-haul efficiency requirements and tightening urban access restrictions.
Service contract unbundling is fragmenting traditional dealer-captive maintenance relationships. Large logistics operators in the Central Federal District are negotiating component-level service agreements with independent workshops, bypassing authorized service networks for routine powertrain work. This behavioral shift concentrates in freight corridors where technician mobility between employers has eroded brand-loyal service capture rates.
Russia Commercial Vehicle Market Segmentation
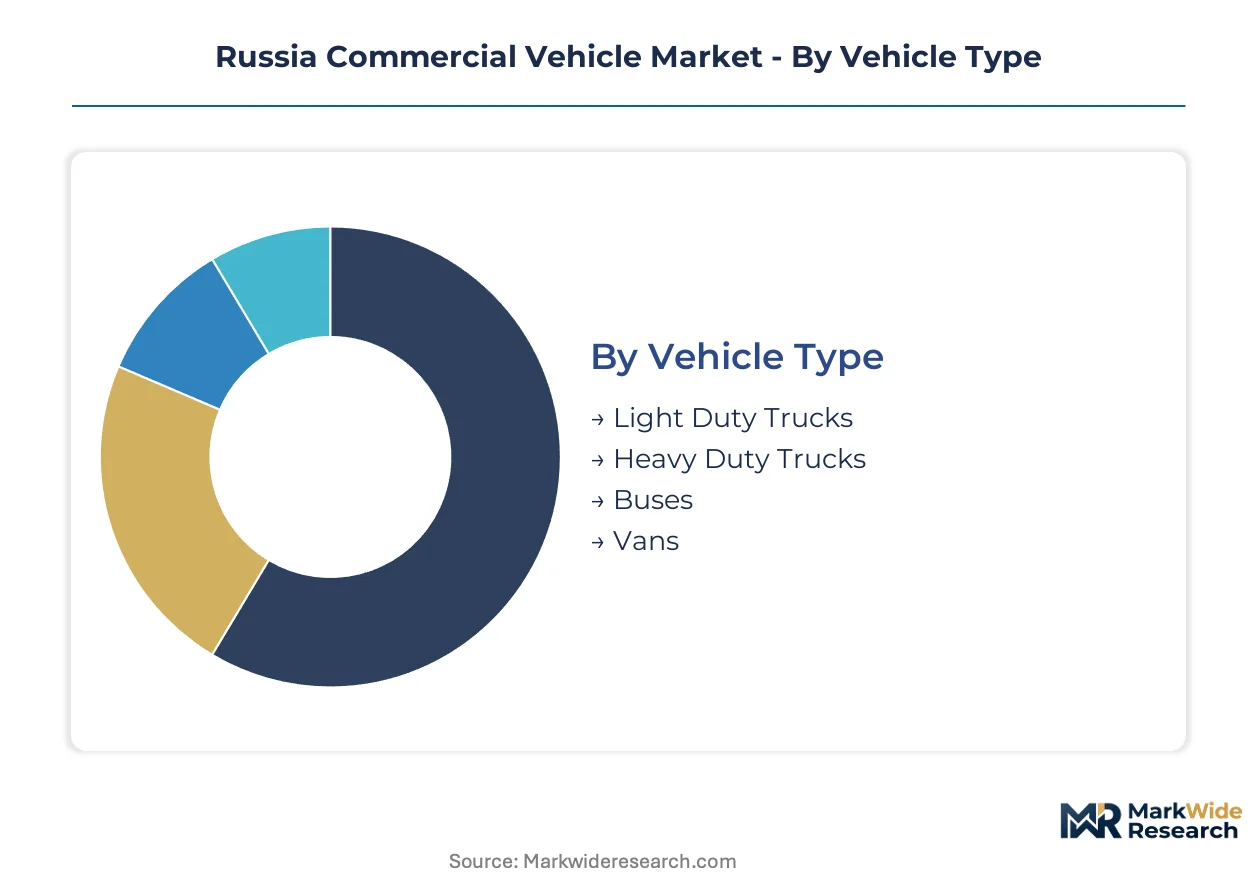
Segmentation reveals how procurement patterns diverge across Russia's commercial vehicle fleet operators. Each dimension exposes distinct pressure points from regulatory tightening, infrastructure gaps, and shifting logistics requirements.
Vehicle Type:
Substitution pressure concentrates most intensely in the light-duty bracket, where Chinese van imports and domestic GAZ platforms compete for last-mile contracts.
- Heavy Duty Trucks:Chassis-cab platforms engineered for gross vehicle weights exceeding 12 tonnes dominate extractive industry logistics. Demand concentrates along the Moscow-Ural freight corridor where minerals transport and transcontinental haulage contracts sustain fleet investment despite technician shortages.
- Light Duty Trucks:Compact commercial platforms between 3.5 and 7.5 tonnes GVW serve regional distribution networks. Procurement accelerates in the Russian Far East as e-commerce fulfillment networks extend beyond the Central Federal District.
- Buses:Urban and intercity passenger configurations face CNG conversion mandates in Moscow and Saint Petersburg municipal procurement.
- Vans:Panel and cargo van derivatives under 3.5 tonnes capture disproportionate volume in last-mile delivery services.
Heavy duty trucks anchor the volume base while vans gain share at the steepest rate.
Fuel Type:
Cost tier stratification separates long-haul diesel retainers from urban CNG adopters facing Rosstandart emissions deadlines.
- Diesel:Compression-ignition engines retain dominance across long-haul freight corridors for cold-start reliability and torque density. Procurement persists in the Ural industrial belt where charging infrastructure gaps and range degradation exclude battery alternatives.
- CNG:Compressed natural gas powertrains satisfy municipal procurement preferences under national carbon intensity targets. Adoption clusters in urban bus contracts and state-owned fleet renewals where refueling infrastructure has achieved critical density.
- Electric:Battery-electric platforms remain technically constrained outside Moscow and Saint Petersburg urban bus deployments.
- Petrol:Spark-ignition engines occupy niche applications in light commercial segments where upfront cost sensitivity outweighs fuel efficiency considerations.
Diesel anchors the volume base while CNG climbs the fastest on policy tailwinds.
End User:
Application maturity diverges sharply between established extractive logistics and emerging e-commerce fulfillment networks.
- Logistics Providers:Third-party freight operators and dedicated fleet managers drive heavy-duty procurement along transcontinental corridors. Investment concentrates in telematics-enabled fleet management systems as predictive maintenance algorithms compress downtime costs.
- Delivery Services:Last-mile operators accelerate van and light-duty renewals across Siberian and Far Eastern regions. Demand responds to e-commerce penetration beyond Moscow's central distribution hubs.
- Construction Companies:Road-building and extractive sector operators maintain specialized chassis requirements for off-highway applications.
- Public Transportation:Municipal authorities in Moscow and Saint Petersburg mandate CNG compliance for new bus contracts under Rosstandart emissions schedules.
Logistics providers anchor the volume base while delivery services expand most quickly.
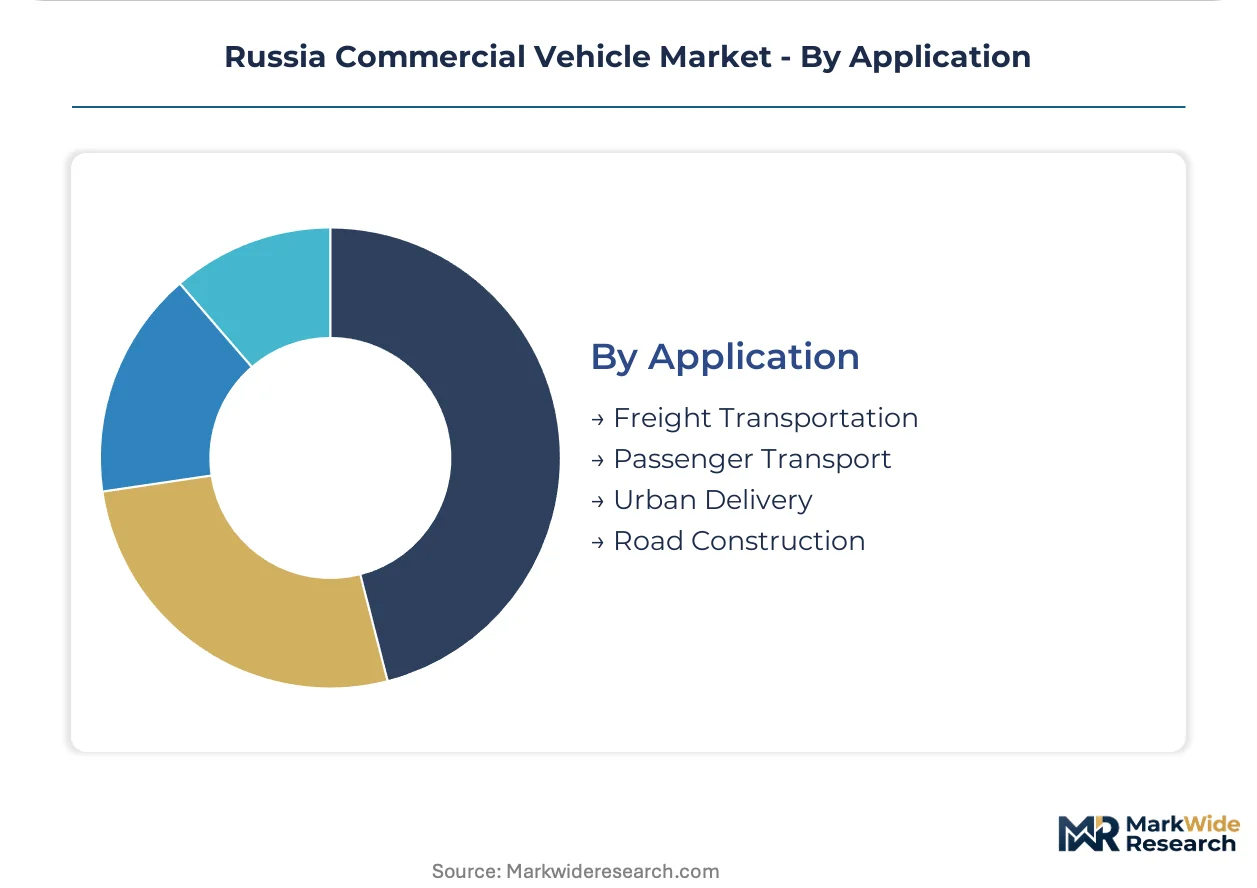
Application:
Geographic concentration shapes procurement priorities, with freight corridors commanding capital intensity against dispersed urban delivery networks.
- Freight Transportation:Long-haul and regional cargo movement dominates value capture across the commercial vehicle fleet. Corridor density peaks along the Moscow-Ural axis where minerals transport and containerized trade sustain heavy-duty utilization rates.
- Urban Delivery:Last-mile distribution networks require maneuverable platforms with frequent stop-start cycles. Fleet operators prioritize total cost of ownership metrics over upfront acquisition price.
- Passenger Transport:Intercity and municipal bus services face CNG conversion timelines under Federal Technical Regulation mandates.
- Road Construction:Specialized chassis configurations serve off-highway earthmoving and paving operations.
Freight transportation anchors the volume base while urban delivery gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial vehicle deployment patterns diverge sharply across Russia's federal districts, with freight corridors demanding heavy-duty torque density while urban centers prioritize CNG compliance for municipal fleets.
Central Federal District
Moscow anchors procurement volume through state fleet renewals and logistics hub concentration. Rosstandart's emissions compliance deadlines drive municipal bus operators toward CNG platforms. The Moscow-Tver freight corridor sustains heavy-duty utilization for containerized trade and minerals transport.
Ural Federal District
Extractive industry logistics dominate demand through minerals haulage contracts linking Perm to Chelyabinsk. The region's cold climate reinforces diesel retention for cold-start reliability. Yekaterinburg-based fleet operators maintain specialized chassis requirements for off-highway mining applications.
Far Eastern Federal District
E-commerce fulfillment networks accelerate van and light-duty renewals across Vladivostok and Khabarovsk. Pacific port facilities generate container drayage demand for chassis-cab platforms. The region's underpenetrated corridors offer expansion potential as Asia-Russia trade volumes stabilize.
Volga Federal District
Nizhny Novgorod anchors light-duty production through GAZ Group's assembly complex. Tatarstan's KAMAZ vocational training centers sustain captive technician pipelines. Kazan-based operators benefit from proximity to domestic manufacturing for reduced spare parts lead times.
Siberian Federal District
Novosibirsk serves as a transshipment node for transcontinental freight corridors. The region's vast distances reinforce diesel dominance due to charging infrastructure gaps. Krasnoyarsk-based construction companies drive demand for specialized road-building chassis configurations.
Russia Commercial Vehicle Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with domestic manufacturers controlling vocational training pipelines while import brands compete on acquisition cost. The structure bifurcates between captive-service networks and price-driven procurement channels. Three archetypes dominate: vertically integrated domestic producers with in-house technician training, Chinese cost competitors in heavy-duty imports, and European heritage brands with constrained parts availability. Competitive moves concentrate on multi-platform maintenance investments and telematics-enabled fleet management subscriptions.
Among domestic integrated producers, KAMAZ and GAZ Group exemplify the vocational-training archetype through captive pipeline development. SINOTRUK occupies the cost-competitive import position, representing Chinese manufacturers aggressive on heavy-duty pricing. These three anchors illustrate how procurement splits between state-preferred domestic platforms and private-operator cost optimization.
| Leading Market Players |
|---|
| UAZ |
| SHACMAN |
| KAMAZ |
| BAZ |
| FAW Trucks Co., Ltd. |
| GAZ Group |
| SINOTRUK |
| Volvo AB |
| URAL Automotive Plant |
| Others |
Supply Flow & Price Mechanics
Ninety-day lead times for European diesel engine components now govern procurement calendars across Russian commercial vehicle fleets, compressing pricing power for domestic assemblers while elevating premiums on Belarusian and Kazakh substitute sourcing. This inventory bandwidth simultaneously anchors contract structures and exposes operators to spot-market volatility when sanctions disrupt established channels.
Pricing Analysis
Long-term offtake agreements dominate heavy-duty chassis procurement along the Moscow-Ural corridor, with state-owned extractive operators locking multi-year contracts to secure KAMAZ and Ural Automotive Plant allocations. Price differentiation rests on after-sales service bundling and Rosstandart certification tiers, with premium tiers capturing fleet telematics integration. Cost compression in the light-duty van segment intensifies as Chinese imports from SINOTRUK and FAW Trucks undercut GAZ Group on acquisition price. Municipal procurement offices demonstrate lowest price sensitivity due to carbon-intensity mandate compliance budgets, while independent logistics operators in Siberia exhibit acute sensitivity to total cost of ownership.
Supply Chain Analysis
Belarusian component transit through the Eurasian Economic Union customs corridor underwrites spare parts availability for Tatarstan-based KAMAZ assembly, though single-source vulnerability persists for high-pressure common-rail injection systems previously sourced from German suppliers. Domestic manufacturing draws from Russian steel mills and in-house engine foundries, yet remains tethered to Chinese electronics for telematics control modules. Distribution runs through authorized dealer networks in the Central Federal District, with independent workshops capturing increasing share in regional freight corridors where technician mobility erodes brand-loyal service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's commercial vehicle market sits in cyclical recovery as extractive industry logistics rebound from sanctions-driven fleet deferrals, with minerals transport contracts along the Ural belt serving as the primary cyclical driver.
For Market Incumbents: Consolidate captive technician pipelines through vocational training center expansion in Tatarstan and Nizhny Novgorod, insulating maintenance revenue from independent workshop encroachment. Deepen backward integration into domestic engine production to displace European component dependencies, while securing Rosstandart pre-certification for CNG platforms ahead of municipal procurement deadlines. Vertical control over after-treatment system manufacturing represents the critical defensive lever against Chinese cost competitors. For New Entrants and Emerging Players: Telematics-enabled predictive maintenance services present the most penetrable white space, as mid-size haulage operators in Novosibirsk and Krasnoyarsk remain underserved by OEM-locked subscription platforms. Target the Siberian Federal District's dispersed construction fleet segment, where GPS tracking adoption lags Central Federal District benchmarks. A channel partnership model with independent workshops bypasses established dealer networks and accelerates customer acquisition. For Investors and Strategic Acquirers: Long-term, this sits as a domestic manufacturing reshoring play because import substitution policies create structural tailwinds for localized powertrain production. Acquisition targets should emphasize vocational training infrastructure and Eurasian Economic Union certification capabilities. The signal to watch is Rosstandart's enforcement velocity on particulate matter thresholds, which would accelerate fleet replacement cycles and expand addressable market for compliant platforms.| Strategic Initiative | Industry Significance |
|---|---|
| CNG Platform Pre-Certification | Rosstandart compliance deadlines in Moscow and Saint Petersburg municipal procurement create first-mover advantage. |
| Technician Vocational Pipeline Expansion | KAMAZ-style captive training centers reduce fleet downtime and lock in aftermarket service revenue. |
| Telematics Subscription Launch | Predictive maintenance algorithms compress operating costs for mid-size haulage operators in underpenetrated corridors. |
| Domestic Engine Manufacturing Scale-Up | Import substitution policies favor localized production of diesel and CNG powertrains to replace European assemblies. |
| Independent Workshop Channel Partnership | Service contract unbundling in regional freight corridors erodes dealer-captive relationships and opens distribution access. |
Methodological Framework
Desk research of customs trade databases, Rosstandart certification registries, and Eurasian Economic Union technical regulation filings preceded structured interviews with fleet operations managers, aftermarket service directors, and municipal procurement officers across the Central and Ural Federal Districts. Primary fieldwork with KAMAZ and GAZ Group supply chain executives was cross-validated against secondary sources including Ministry of Economic Development carbon intensity reports and commercial vehicle production statistics. Bottom-up triangulation of fleet renewal intentions with top-down macroeconomic indicators anchored volume and value estimates.
Variance decomposition across vehicle type, fuel architecture, and federal district segmentation shaped the analytical framework, with propulsion technology splits and regional infrastructure maturity serving as key demand drivers throughout the projection horizon. CAGRs were derived from replacement cycle analysis and procurement pipeline visibility, incorporating technician shortage constraints and sanctions-driven supply chain restructuring as industry-specific forecast inputs.
Forecasts assume regulatory continuity in Rosstandart emissions schedules and Eurasian Economic Union type-approval harmonization; material policy shifts would require re-modeling. Sanctions escalation affecting Belarusian component transit or domestic engine production scaling failures represent specific risk factors that could revise trajectory. Revision becomes warranted when CNG refueling infrastructure deployment in the Far Eastern Federal District crosses critical density thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Mini Truck Market
Commercial Vehicles
Service Truck Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Heavy Haulage Trucks Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
France Light Commercial Vehicles Market