
 Motorcycles, Scooters and Mopeds Market | 2026-2036
Motorcycles, Scooters and Mopeds Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycles, Scooters and Mopeds Market Intelligence
The availability of technicians skilled in battery management systems and electric motor repair is bifurcating the after-sales service network. Established OEMs like Honda Motor leverage their vast legacy service infrastructure for retraining initiatives. In contrast, electric-native firms such as Yadea build new service partnerships focused on EV technology, while Bajaj Auto specializes in developing modular repair kits to simplify maintenance in developing economies.
Motorcycles, scooters, and mopeds are two- or three-wheeled motorized vehicles designed for personal transport and light commercial use. These vehicles are characterized by engine capacities typically ranging from 50cc up to and beyond 650cc, or by specific kilowatt-hour ratings for electric variants. While the 50cc-125cc engine capacity segment commands the highest unit sales in congested urban centers, the electric fuel type category is the most dynamic, driven by regulatory pressures and falling battery costs.
Product design and market access are shaped by a complex web of regional mandates. Compliance with Euro 5 standards is mandatory for market entry in Europe, while manufacturers in India must adhere to Bharat Stage VI norms. In the United States, the EPA sets federal limits on exhaust and noise emissions, forcing model-specific modifications. Consequently, producers must balance the need for global platform standardization against the requirement for regional powertrain adaptations.
Market Dynamics
The global push for decarbonization, enforced through stringent emissions standards, is the central force shaping the market. This pressure compels a fundamental shift from internal combustion engines to electric powertrains, reconfiguring supply chains and after-sales service networks.
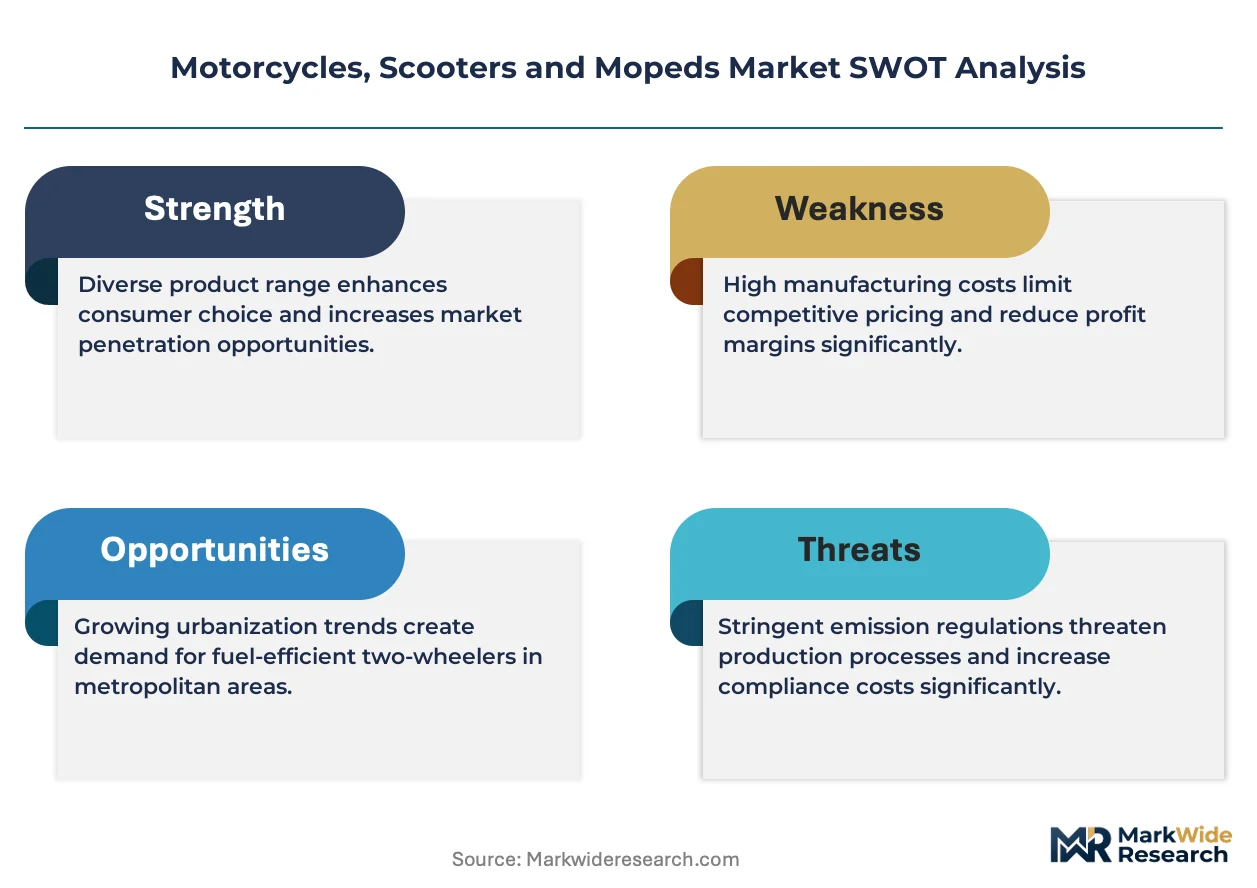
Growth Catalysts
- Urban Logistics Expansion:Growth in the urban last-mile delivery sector, especially in dense Asian cities, creates sustained demand for efficient, low-cost scooters.
- Electrification Mandates:Regulatory frameworks like the EU Green Deal accelerate the transition to electric models by penalizing high-emission vehicles and incentivizing EV adoption.
- Falling Battery Costs:Reductions in lithium-ion battery manufacturing costs make electric variants more price-competitive against internal combustion engine models.
Market Restraints
- High Initial EV Cost:The upfront purchase price of electric models remains a barrier for consumers in price-sensitive developing economies compared to ICE alternatives.
- Charging Infrastructure Deficit:A lack of public charging stations, particularly in residential areas of emerging markets, limits the practical appeal of electric two-wheelers.
- Battery Material Concentration:Supply chains for battery materials like cobalt are concentrated geographically, creating price volatility and geopolitical risk for manufacturers.
Strategic Opportunities
- Battery Swapping Networks:Battery-as-a-Service (BaaS) models and swapping stations overcome charging time and range anxiety, accelerating EV adoption in dense urban centers.
- Modular Repair Solutions:Creating modular repair kits simplifies maintenance in regions with few skilled technicians, improving serviceability in developing economies.
- Sub-Saharan Africa Expansion:Underpenetrated markets in Sub-Saharan Africa offer a significant opportunity for low-cost, durable motorcycles as personal mobility needs increase.
Industry Challenges
- Technician Skill Gaps:A shortage of technicians trained in electric motor repair and battery management systems creates a bottleneck for after-sales service and maintenance networks.
- Regulatory Fragmentation:Manufacturers face high compliance costs and design complexity managing divergent emissions standards like Europe's Euro 5 and India's Bharat Stage VI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycles, Scooters and Mopeds Market |
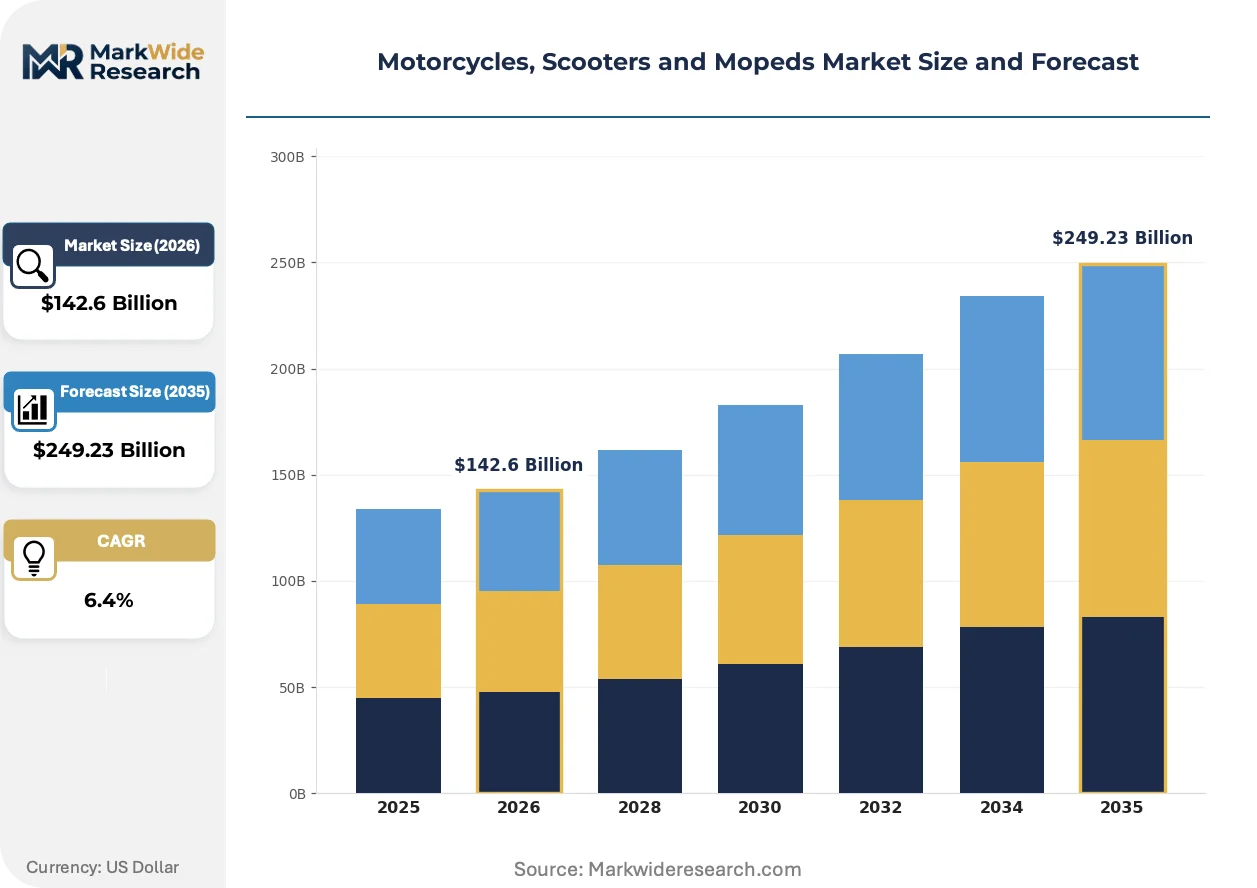
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $249.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Standard Bikes, Cruiser Bikes, Sport Bikes, Touring Bikes, Off-road Bikes Engine Capacity: 50cc-125cc, 126cc-250cc, 251cc-400cc, 401cc-650cc, Above 650cc Fuel Type: Petrol, Electric, Diesel, Hybrid, Compressed Natural Gas Sales Channel: Dealerships, Online Platforms, Independent Retailers, Rental Services |
| Companies Covered | Hero MotoCorp, Piaggio, Honda Motor, BMW Motorrad, Kymco, Yamaha Motor, Suzuki Motor, Yadea, Bajaj Auto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycles, Scooters and Mopeds Market Strategic Shifts & Innovations
The industry's pivot to electrification is creating ripple effects beyond the powertrain. This transition is reshaping vehicle intelligence, after-sales service models, and the very definition of vehicle ownership for consumers and commercial fleet operators alike.
Onboard telematics control units (TCUs) provide vehicle connectivity for remote diagnostics, tracking, and over-the-air updates. Commercial fleet operators are the primary adopters for logistics management, with premium consumer models now integrating these systems. This embedded technology is miniaturizing the after-sales service footprint by enabling predictive maintenance, thus reducing the frequency of physical workshop visits.
Right-to-repair legislative movements in the United States and parts of Europe are gaining momentum. These initiatives compel manufacturers to make diagnostic tools, software, and OEM parts available to independent repair shops. The after-sales service segment is most affected, as it opens up competition and potentially erodes the captive service revenue of established OEMs.
A clear behavioral shift from outright vehicle ownership toward subscription and leasing models is underway. This disrupts traditional dealer-based sales channels, which are being supplemented by direct-to-fleet and online platforms. The trend is most visible within European urban delivery fleets, where operators prioritize total cost of ownership over initial capital outlay.
Motorcycles, Scooters and Mopeds Market Segmentation
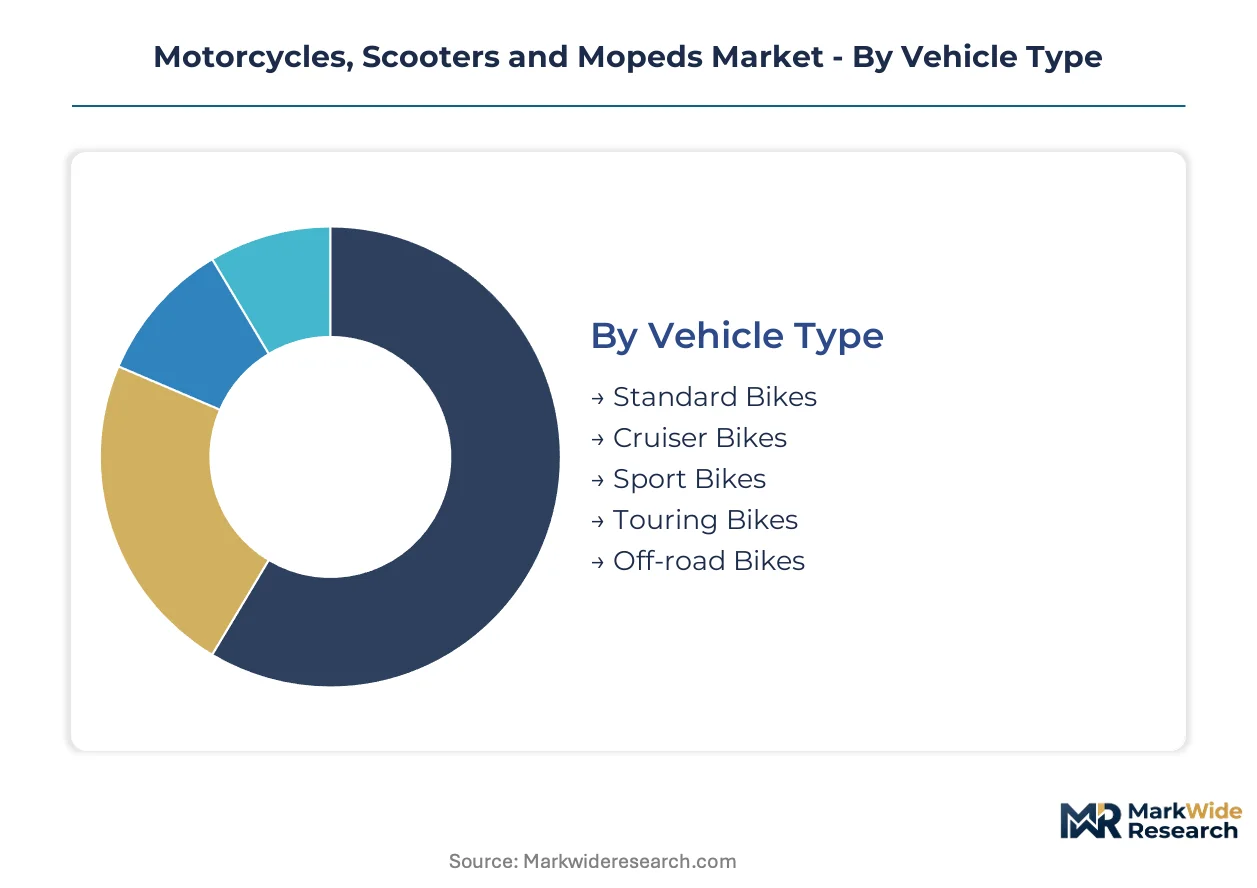
The Motorcycles, Scooters and Mopeds market segments based on vehicle type, engine capacity, fuel type, and sales channel. This granular segmentation provides a detailed view of consumer preferences, technological adoption rates, and regulatory impacts across diverse global markets.
Vehicle Type:
The Vehicle Type category faces significant substitution pressure from alternative urban mobility solutions and evolving consumer preferences.
- Standard Bikes:These versatile motorcycles offer a balanced performance profile, suitable for daily commuting and general-purpose riding. Demand is concentrated in developing economies like India and Vietnam, where they serve as primary personal transport due to their affordability and durability.
- Sport Bikes:Characterized by high-performance engines, aerodynamic fairings, and aggressive riding positions for speed and agility. Premium models find strong demand in developed markets such as Germany and Japan, driven by enthusiast riders seeking advanced technology and dynamic performance.
- Cruiser Bikes:These motorcycles feature a low-slung riding position, often with V-twin engines, designed for comfort on long-distance rides.
- Touring Bikes:Equipped for extended journeys with large fuel tanks, comfortable seating, and luggage capacity, appealing to long-distance travelers.
- Off-road Bikes:Built for challenging terrain with robust suspension and knobby tires, popular in recreational and adventure sports segments.
Standard Bikes retain volume leadership; Sport Bikes hold the steepest expansion curve.
Engine Capacity:
The market's volume dynamics are heavily influenced by specific engine capacities, reflecting diverse utility and regulatory frameworks.
- 50cc-125cc:These low-displacement vehicles are ideal for congested urban centers and last-mile delivery, particularly in Asian megacities. Regulatory incentives for smaller engines and the EU Green Deal's focus on low emissions boost demand in these segments.
- Above 650cc:Representing the premium and high-performance segment, these motorcycles cater to experienced riders and touring enthusiasts. Markets in North America and Western Europe drive demand for these larger engines, often for leisure and long-distance travel.
- 126cc-250cc:This segment offers a balance of power and efficiency, popular for daily commuting and light touring in many Asian and European countries.
- 251cc-400cc:These mid-range engines provide enhanced performance for varied riding conditions, appealing to a growing segment of urban and suburban riders.
- 401cc-650cc:This capacity range serves the mid-to-heavyweight market, often chosen for a blend of highway capability and manageable city riding.
The 50cc-125cc segment dominates urban mobility; higher capacities cater to enthusiast and touring markets.
Fuel Type:
Regulatory pressures and technological advancements significantly differentiate fuel type segments, driving a fundamental market transition.
- Petrol:Internal combustion engine models remain the market's largest segment by volume, benefiting from established infrastructure and lower upfront costs. Demand is sustained in regions with less stringent emission standards or limited EV charging infrastructure, such as parts of Sub-Saharan Africa.
- Electric:These zero-emission vehicles are gaining rapid traction due to falling battery costs and electrification mandates like the EU Green Deal. Urban last-mile delivery fleets in Europe and India are accelerating their adoption of electric two-wheelers.
- Diesel:This fuel type holds a niche market, primarily for heavy-duty commercial applications or specific utility vehicles with specialized requirements.
- Hybrid:Combining internal combustion with electric power, hybrid models offer improved fuel efficiency and lower emissions, though their market presence is currently limited.
- Compressed Natural Gas:CNG-powered two-wheelers are emerging in specific markets like India, driven by lower fuel costs and government initiatives to reduce pollution.
Electric powertrains are displacing traditional internal combustion engine models, particularly in dense urban centers.
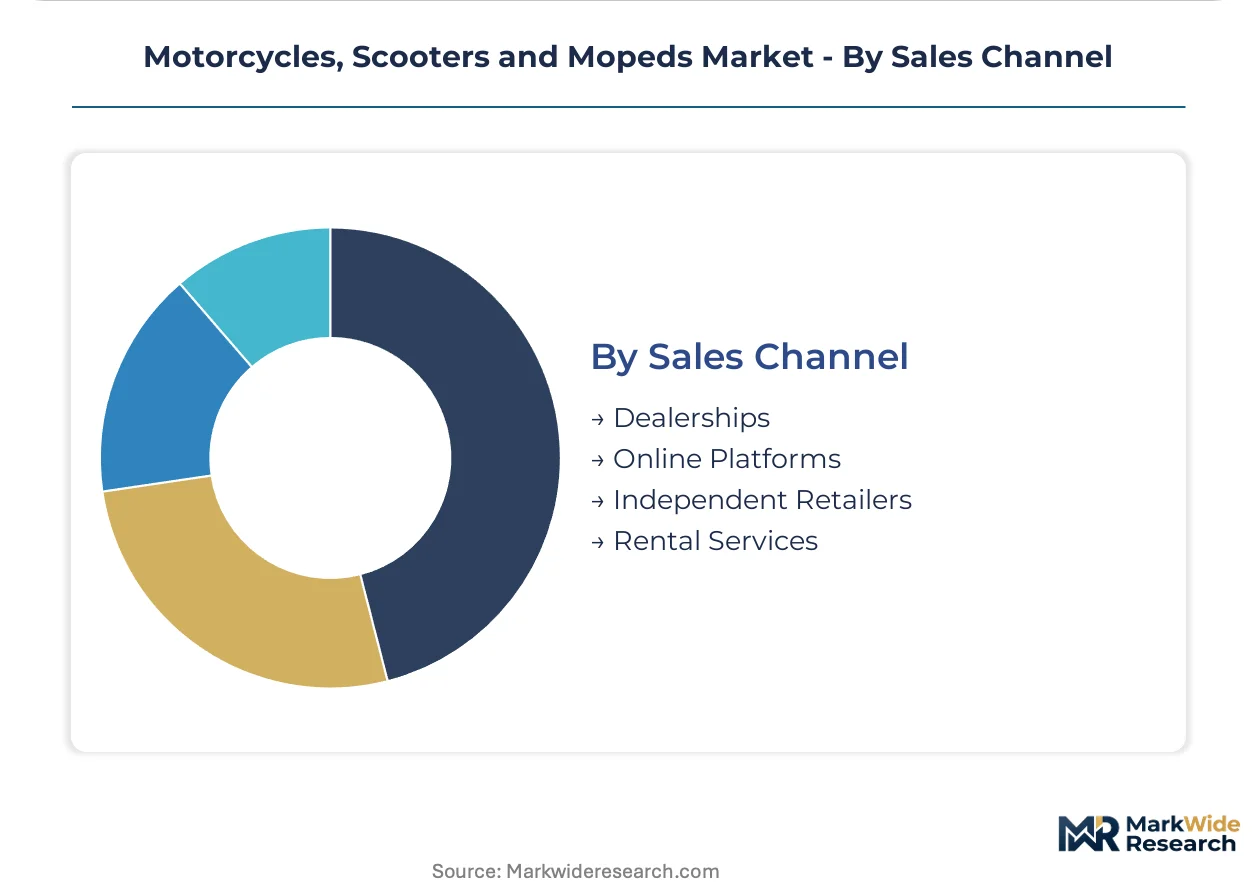
Sales Channel:
Customer purchasing behaviors and evolving service models shape the sales channel landscape, influencing market access and product distribution.
- Dealerships:Traditional dealerships offer comprehensive sales, financing, and after-sales service, maintaining a strong presence in established markets. Honda Motor and Bajaj Auto leverage extensive dealership networks for sales and maintenance, particularly in India.
- Online Platforms:E-commerce channels provide convenience and direct-to-consumer sales, appealing to tech-savvy buyers and fleet operators. This channel is expanding rapidly for electric-native firms like Yadea, offering broader market reach without physical showrooms.
- Independent Retailers:Smaller, often specialized outlets provide localized sales and repair services, catering to specific communities or niche market segments.
- Rental Services:These services offer short-term access to two-wheelers, particularly popular in tourist destinations and urban areas for flexible mobility solutions.
While traditional dealerships maintain strong customer relationships, online platforms offer expanding reach and efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Bharat Stage VI norms anchor the market's regulatory landscape, reflecting a strong governmental push for cleaner emissions in a high-volume two-wheeler market. This regulatory environment shapes product development and market access across diverse global regions. Manufacturers must navigate these varied standards to compete effectively in major demand centers.
India
Demand for 50cc-125cc motorcycles and scooters in India stems from their affordability and utility for daily commuting. The Bharat Stage VI emission standards mandate cleaner engine technologies, influencing local production and supply chains. Dense metropolitan areas like Delhi-NCR and Mumbai are experiencing sustained demand for efficient, low-cost personal transport.
Vietnam
Vietnam's market for two-wheelers is driven by personal transport needs and urban last-mile delivery services. Local government initiatives promote the adoption of more fuel-efficient and lower-emission vehicles. Major cities such as Ho Chi Minh City and Hanoi exhibit high concentrations of scooter usage, supporting vehicle sales and service networks.
Germany
Germany represents a key European market where Euro 5 standards dictate vehicle compliance for market entry. The EU Green Deal further accelerates the transition to electric models, particularly in urban delivery fleets. Advanced technology and dynamic performance for sport bikes find strong demand among enthusiast riders in cities like Munich and Stuttgart.
United States
The United States market focuses on leisure and long-distance touring, particularly for motorcycles above 650cc. The EPA sets federal limits on exhaust and noise emissions, requiring specific model modifications for compliance. Californian cities and other urban centers are seeing increasing interest in electric two-wheelers, driven by environmental consciousness.
Japan
Japanese consumers prioritize advanced technology and dynamic performance, especially within the sport bike segment. METI guidelines encourage innovation in powertrain efficiency and safety features for local manufacturers. Tokyo and Osaka remain critical hubs for both premium motorcycle sales and cutting-edge research and development.
Motorcycles, Scooters and Mopeds Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure. Established OEMs, electric-native firms, and regional specialists constitute the primary strategic archetypes. Dominant competitive moves include strategic partnerships to expand service networks and portfolio diversification to address evolving fuel type preferences.
Electric-native firms like Yadea exemplify the rapid expansion of new service partnerships focused on EV technology. Honda Motor, an established OEM, occupies a position leveraging its vast legacy service infrastructure for retraining initiatives. Bajaj Auto, a regional specialist, anchors the development of modular repair kits to simplify maintenance in developing economies.
| Leading Market Players |
|---|
| Hero MotoCorp |
| Piaggio |
| Honda Motor |
| BMW Motorrad |
| Kymco |
| Yamaha Motor |
| Suzuki Motor |
| Yadea |
| Bajaj Auto |
| Others |
Cost & Logistics Intelligence
Economies of scale in vehicle manufacturing drive supply concentration among established OEMs, influencing price floors across various segments. This scale allows for cost-effective production, shaping market competitiveness and material sourcing strategies.
Pricing Analysis
Geographic price spreads reflect regional regulatory compliance costs and local market demand elasticity. The dominant pricing structure remains per-unit transactional, though subscription models are emerging for fleet operators. Price differentiation stems from brand premium and the inclusion of advanced telematics features. Cost compression in the 50cc-125cc segment intensifies due to fierce competition in Asian markets. Consumers in developing economies exhibit the highest price sensitivity, while premium sport bike enthusiasts are less affected by price fluctuations.
Supply Chain Analysis
Strategic stockpiling of critical battery components mitigates supply disruptions, balancing just-in-time manufacturing for vehicle assembly. Geographic supply concentration centers on China, India, and Vietnam for component manufacturing and assembly. The industry depends on raw materials like lithium, cobalt, and rare earth elements for electric powertrains. Geopolitical risk affecting battery material access creates a structural supply chain vulnerability. Distribution runs through established dealership networks for traditional models and increasingly via online platforms for electric variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A cyclical recovery, spurred by sustained urban mobility demand, shapes strategic imperatives across the Motorcycles, Scooters and Mopeds market.
For Market Incumbents: Compound existing service infrastructure by retraining technicians for electric powertrains, addressing the emerging skill gap threat. Diversify product portfolios to include a wider range of electric models, leveraging established brand recognition. Form strategic partnerships with battery swapping network providers to enhance customer convenience. Control over the after-sales service channel remains a critical lever against new entrants.
For New Entrants and Emerging Players: Anchor in underserved rural markets of Sub-Saharan Africa, offering low-cost, durable models optimized for local conditions. Target the urban last-mile delivery segment with purpose-built electric scooters and modular repair solutions. The entry-level electric two-wheeler segment in dense urban centers presents the most penetrable market. A direct-to-consumer online sales model, supported by localized service hubs, offers an effective go-to-market angle.
For Investors and Strategic Acquirers: Electric-native firms demonstrating scalable battery technology represent attractive acquisition targets for established OEMs seeking rapid electrification capabilities. Long-term viability is driven by decarbonization mandates and expanding urban logistics needs. The successful deployment of battery-as-a-service models in new geographies serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization for Electric Models | Reduces manufacturing costs and accelerates time-to-market across diverse regional mandates. |
| Battery Swapping Network Partnerships | Addresses range anxiety and charging infrastructure deficits, accelerating EV adoption in urban areas. |
| Modular Repair Kit Development | Simplifies maintenance in developing economies with limited skilled technician availability. |
| Direct-to-Fleet Sales Channel Expansion | Captures commercial demand from urban logistics operators prioritizing total cost of ownership. |
| Investment in Telematics and Remote Diagnostics | Enables predictive maintenance and reduces physical workshop visits, optimizing after-sales service. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence reports anchors the qualitative findings. This involved discussions with OEM executives, battery technology developers, urban logistics fleet managers, and national transport regulators. Secondary research drew from automotive trade publications, government emissions reports, financial filings of public companies, and academic research on battery technology. Both bottom-up and top-down triangulation methodologies were employed to ensure data consistency.
Sensitivity analysis on key market drivers informs the forecast framework, assessing potential impacts of varying input conditions over the projection horizon. The quantitative model delineates market segments by vehicle type, fuel type, engine capacity, sales channel, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth trends and projected market shifts. Key forecast inputs include lithium-ion battery price curves and urban population density projections.
Material uncertainties — including unforeseen geopolitical events affecting material supply chains and rapid technological breakthroughs — sit outside the modeled envelope of this study. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. Revision becomes warranted when shifts in global trade policies or significant advancements in battery chemistry cross defined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Brazil E-Bike Market
Bikes and Motorcycles
Motorcycle Cooling Helmets Market
Bikes and Motorcycles
Bike Hub Market
Bikes and Motorcycles
Smart Bicycle Accessories Market
Bikes and Motorcycles
Motorcycles Fuel Tank Market
Bikes and Motorcycles
Europe Motorcycle ADAS Market
Bikes and Motorcycles
Used Bike Market
Bikes and Motorcycles
South America Two-Wheeler Market
Bikes and Motorcycles
On-Road Motorcycles Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
Two-Wheeler Services Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Motorcycle Horns Market