
 France Electric Vehicle Market | 2026-2036
France Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
France Electric Vehicle Market Intelligence
The European Union's ban on new internal combustion engine car sales from 2035 is realigning the cost-of-entry calculus for all automotive manufacturers operating in France. Domestic champion Renault leverages its early leadership in models like the Zoe to defend its market share. Tesla competes on battery technology and its proprietary Supercharger network. Legacy automakers like Peugeot and Citroën are rapidly expanding their Battery Electric Vehicle and Plug-in Hybrid Electric Vehicle portfolios to meet the mandate.
An electric vehicle, for this analysis, is a road-legal passenger or light commercial vehicle propelled by one or more electric motors using energy from rechargeable battery packs, typically with Lithium-Ion chemistries like NMC or LFP. Its primary function is providing personal or commercial transport with zero tailpipe emissions, aligning with France's decarbonization goals. Within vehicle types, Battery Electric Vehicles (BEVs) represent the fastest-growing category, while Plug-in Hybrid Electric Vehicles (PHEVs) serve as a transitional technology. Adoption is strongest among Urban Professionals and Fleet Operators, who are key consumer demographics influenced by incentives and operational cost savings.
France's implementation of Low Emission Zones (Zones à Faibles Émissions mobilité or ZFE-m) in major cities directly stimulates EV sales. Concurrently, adherence to EU-wide CE marking and charging connector standards ensures interoperability and safety for all vehicles and infrastructure. The critical decision for public and private stakeholders now centers on the pace and geographic equity of public fast-charging infrastructure deployment to support mass adoption.
Market Dynamics
The French government's dual-policy approach, combining national incentives like the bonus-malus écologique with city-level restrictions such as ZFE-m, is the primary structural force shaping EV adoption patterns and OEM product strategy across the country.
Growth Catalysts
- National Incentives:France's bonus-malus écologique system provides direct financial subsidies for purchasing low-emission vehicles, significantly lowering the total cost of ownership for both private consumers and commercial fleet operators.
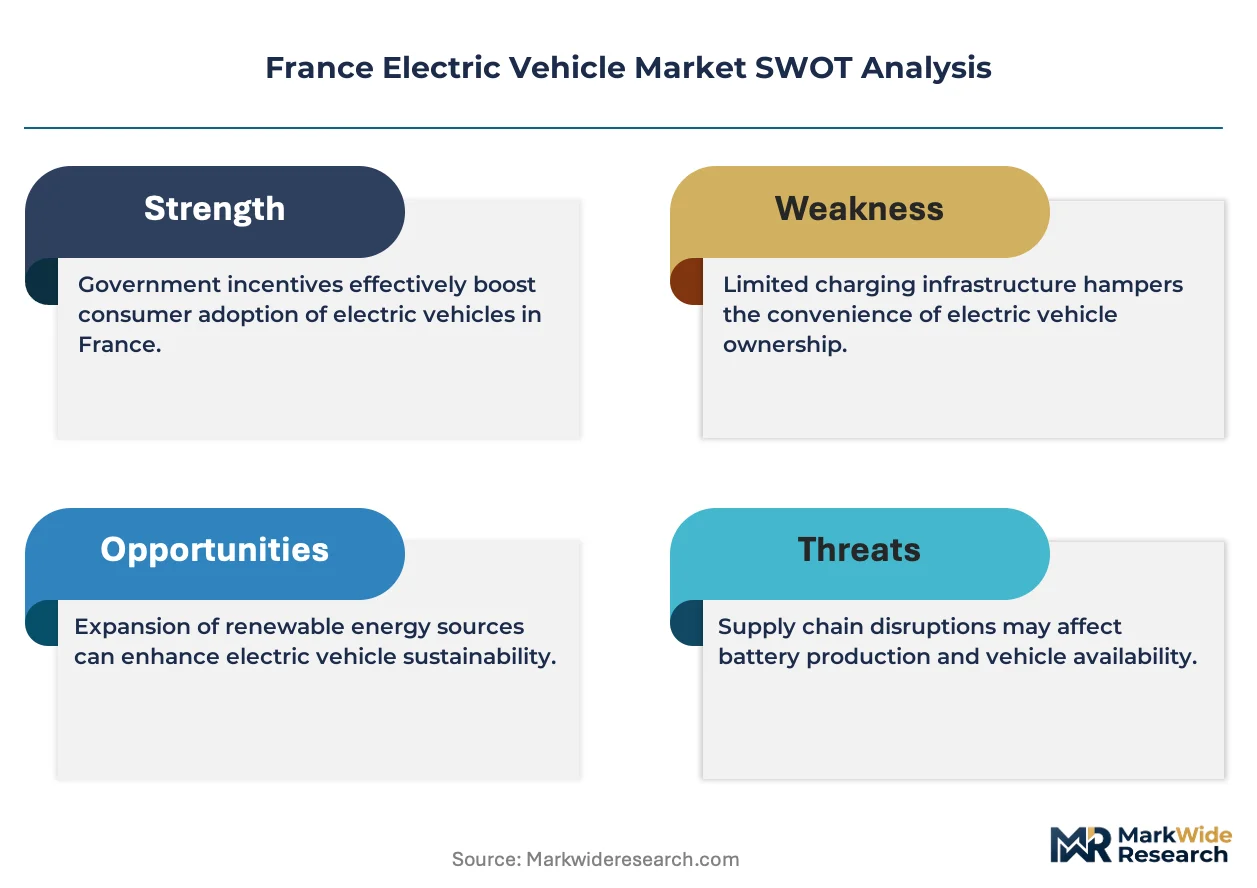
- Urban Access Restrictions:The expansion of Low Emission Zones (ZFE-m) in major metropolitan areas like Paris and Lyon effectively mandates the use of electric vehicles for unrestricted access, compelling adoption among urban residents and businesses.
- Corporate Sustainability Goals:Corporate fleet operators are transitioning vehicle pools to electric models to meet internal ESG mandates and leverage operational cost savings, creating a consistent source of B2B demand.
Market Restraints
- Charging Infrastructure Gaps:The uneven geographic distribution of public fast-charging stations, particularly in rural areas and within multi-unit residential buildings, poses a barrier to mass-market adoption outside of major cities.
- High Upfront Vehicle Cost:Despite subsidies, the initial purchase price of BEVs remains higher than comparable internal combustion engine models, acting as a primary deterrent for budget-conscious households and small businesses in France.
- Battery Supply Dependency:The French automotive industry's reliance on Asian-sourced battery cells and critical raw materials introduces supply chain vulnerabilities and exposure to geopolitical price volatility, constraining production capacity.
Strategic Opportunities
- Light Commercial Vehicle Electrification:The LCV segment, particularly for last-mile urban logistics, presents a significant opportunity for electrification, driven by ZFE-m regulations and the total cost of ownership benefits for high-utilization delivery fleets.
- Second-Life Battery Systems:Developing a domestic circular economy for used EV batteries, repurposing them for stationary energy storage, creates a new value stream and addresses end-of-life environmental concerns for Lithium-Ion packs.
- Subscription and Leasing Models:Flexible vehicle-as-a-service offerings can lower the barrier to entry for consumers hesitant about battery degradation and technology obsolescence, expanding the addressable market beyond outright purchasers.
Industry Challenges
- Technician Skill Gaps:A shortage of mechanics trained in high-voltage battery systems and EV-specific diagnostics creates a bottleneck in the after-sales service network, impacting vehicle uptime and owner satisfaction.
- Grid Integration and Capacity:Managing the increased electricity demand from widespread EV charging requires substantial investment in local grid upgrades and smart charging solutions to prevent instability during peak hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Electric Vehicle Market |
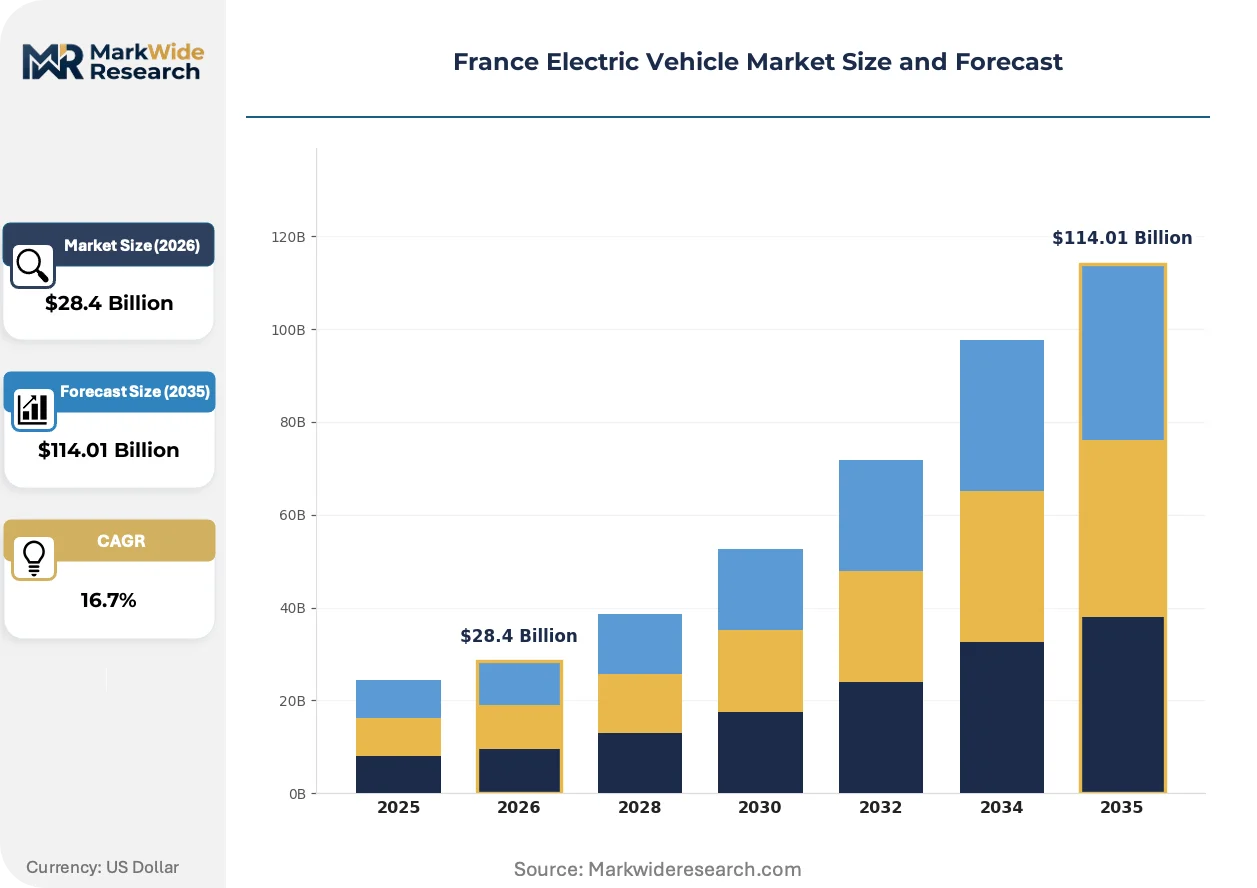
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $114.01 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles, Fuel Cell Electric Vehicles, Extended Range Electric Vehicles Charging Infrastructure: Home Charging, Public Charging, Fast Charging Stations, Workplace Charging, Destination Charging Consumer Demographic: Urban Professionals, Fleet Operators, Eco-conscious Individuals, Tech Enthusiasts Sales Channel: Authorized Dealerships, Online Platforms, Direct Manufacturer Sales, Specialty Electric Vehicle Retailers |
| Companies Covered | Peugeot, BMW, Renault, Skoda, Dacia, Tesla, Citroën, Mercedes-Benz, Volkswagen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Electric Vehicle Market Strategic Shifts & Innovations
Technology and consumer behavior are converging to redefine vehicle ownership and utility in France. Innovations in battery chemistry and a shift toward service-based models are transforming the EV from a simple product into an integrated mobility platform.
Lithium Iron Phosphate (LFP) battery chemistry provides enhanced safety, longer cycle life, and lower cost by eliminating cobalt. Automakers targeting mass-market segments in France are rapidly adopting LFP for standard-range models to reduce bill-of-materials expense. This technology shift is absorbing significant cost pressures from nickel and cobalt volatility, making entry-level EVs more financially accessible to French consumers.
The French "Loi d'orientation des mobilités" (LOM) imposes binding quotas for public and corporate fleets, mandating a progressively higher share of low-emission vehicles. This legislative requirement creates a predictable, large-scale demand channel for BEVs and PHEVs, de-risking OEM production planning for the French market. Corporate fleet operators are most affected, accelerating their procurement cycles for electric models to ensure compliance.
A user preference shift from perpetual vehicle ownership toward all-inclusive subscription services is gaining traction among French urban professionals. These models, offered by OEMs and specialized providers, bundle insurance, maintenance, and charging, challenging the traditional dealership sales process. This behavioral change is most visible in metropolitan hubs like Paris, where flexible access is often valued over long-term ownership.
France Electric Vehicle Market Segmentation
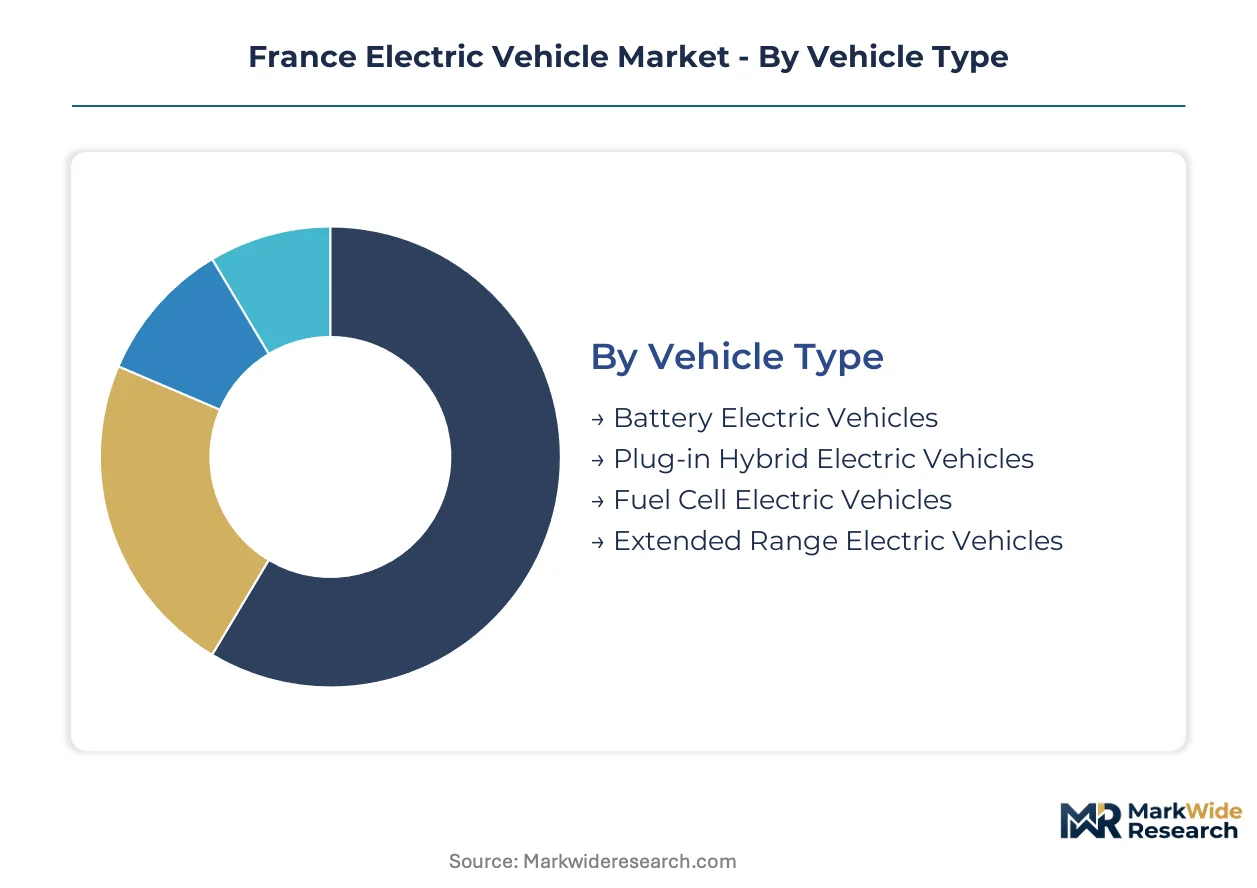
The France electric vehicle market exhibits distinct segmentation across key dimensions, reflecting varied consumer needs and operational requirements. Understanding these segments is crucial for automotive manufacturers, charging infrastructure providers, and policy makers. This granular analysis reveals where investment and strategic focus yield the highest returns within the French EV ecosystem.
Vehicle Type:
The upgrade and replacement cycles within the French automotive sector are increasingly driven by the distinct advantages offered by various electric vehicle types.
- Battery Electric Vehicles (BEVs):Zero-emission vehicles powered solely by rechargeable battery packs, offering the purest form of electric mobility. Demand concentrates in French metropolitan areas due to ZFE-m regulations and corporate sustainability mandates.
- Plug-in Hybrid Electric Vehicles (PHEVs):Combine an internal combustion engine with an electric motor and battery, allowing for short-range electric-only driving. These serve as a transitional technology for French consumers seeking reduced emissions without range anxiety, particularly in semi-urban settings.
- Fuel Cell Electric Vehicles (FCEVs):Generate electricity onboard from hydrogen, emitting only water vapor. Adoption remains niche in France, primarily limited by the nascent hydrogen refueling infrastructure.
- Extended Range Electric Vehicles (EREVs):Feature a small gasoline generator to extend the range of a battery-electric powertrain. These offer range flexibility for French drivers, mitigating concerns over charging availability on longer journeys.
Volume placements concentrate in Plug-in Hybrid Electric Vehicles; the faster expansion belongs to Battery Electric Vehicles.
Charging Infrastructure:
The application of charging infrastructure solutions in France varies significantly based on user behavior and vehicle deployment scenarios.
- Public Charging:Networks of charging points accessible to the general public, often found in urban centers and along major roadways. Its expansion is critical for widespread EV adoption across France, particularly in areas lacking private charging options.
- Fast Charging Stations:High-power charging points capable of rapidly replenishing EV batteries, essential for long-distance travel and commercial fleet operations. Deployment of these stations is a strategic priority for French public and private stakeholders.
- Home Charging:Private charging solutions installed at residences, typically overnight, forming the primary charging method for most French EV owners.
- Workplace Charging:Charging facilities provided by employers for their employees, encouraging EV adoption and supporting daily commutes in French cities.
- Destination Charging:Charging points located at hotels, shopping centers, and recreational sites, enabling convenient top-ups while vehicles are parked for extended periods in France.
The market for Home Charging is mature; Fast Charging Stations are experiencing rapid development.
Consumer Demographic:
Customer types within the French EV market exhibit distinct purchasing motivations and usage patterns, influencing vehicle and service demand.
- Urban Professionals:Individuals residing and working in French metropolitan areas, often influenced by ZFE-m regulations and seeking convenient, low-emission transport. This demographic prioritizes range, compact size, and access to urban charging infrastructure.
- Fleet Operators:Commercial entities managing vehicle pools for logistics, taxis, or company cars, driven by operational cost savings and corporate sustainability goals in France. Their demand accelerates the adoption of light commercial EVs and efficient charging solutions.
- Eco-conscious Individuals:Consumers prioritizing environmental impact, often willing to pay a premium for zero-emission vehicles and sustainable mobility solutions in France.
- Tech Enthusiasts:Early adopters keen on advanced automotive technology, valuing performance, connectivity, and innovative features in their electric vehicles in France.
Demand from Fleet Operators drives significant volume, while Tech Enthusiasts represent a high-value niche.
Sales Channel:
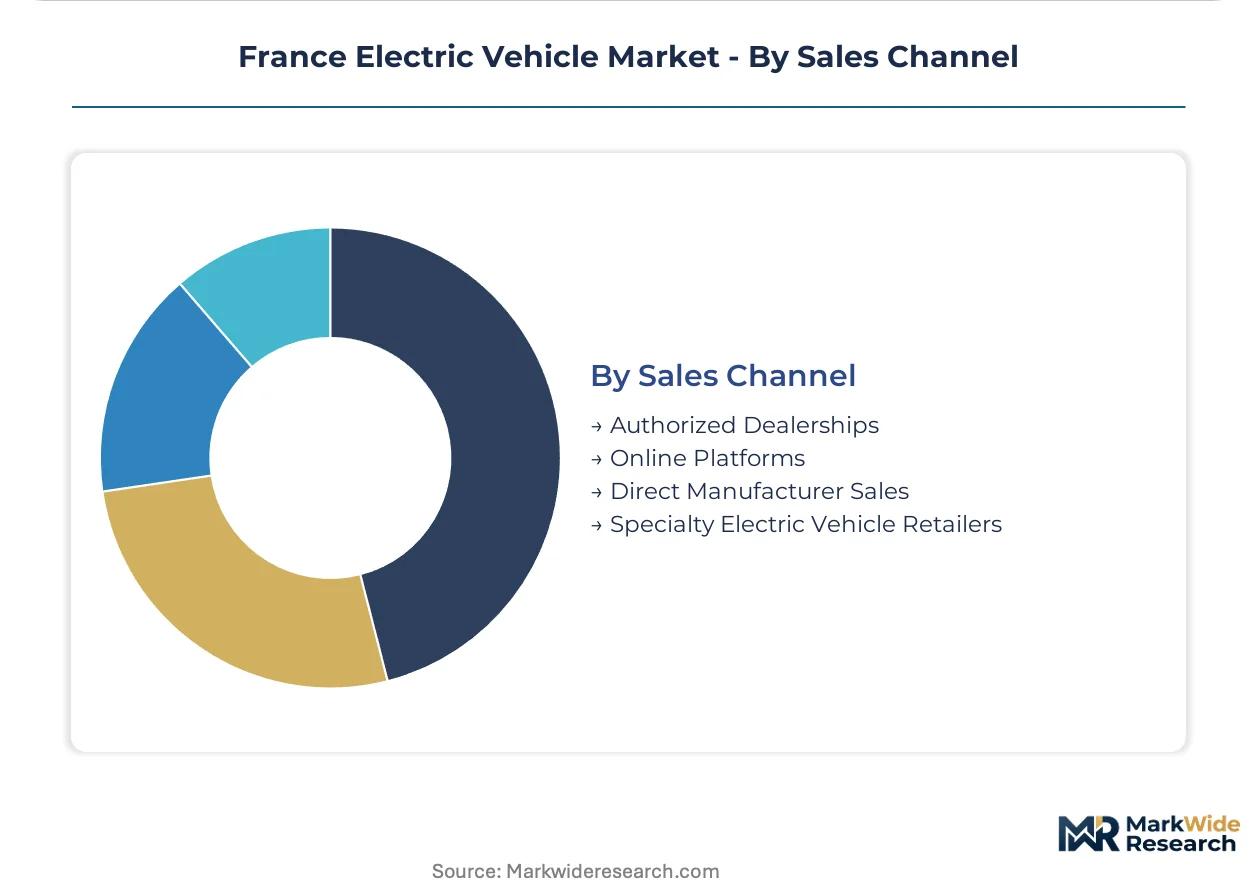
Supply concentration across sales channels for electric vehicles in France reflects evolving consumer purchasing preferences and manufacturer strategies.
- Authorized Dealerships:Traditional automotive showrooms and service centers offering a full range of EV models, sales support, and after-sales services. These remain the primary point of contact for French consumers seeking test drives and financing options.
- Online Platforms:Digital marketplaces and manufacturer websites facilitating vehicle configuration, purchase, and delivery, appealing to tech-savvy French buyers. This channel reduces overheads and offers convenience, particularly for younger demographics.
- Direct Manufacturer Sales:Automakers selling vehicles directly to consumers, bypassing traditional dealerships, often seen with newer EV brands entering the French market.
- Specialty Electric Vehicle Retailers:Independent stores focusing exclusively on electric vehicles, providing expert advice and a curated selection of brands to French customers.
The traditional channel of Authorized Dealerships maintains market dominance, but Online Platforms are gaining traction rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's bonus-malus écologique system, combined with Low Emission Zones (ZFE-m) in major cities, significantly shapes electric vehicle adoption across its regions. These national incentives and urban restrictions create distinct demand patterns for zero-emission mobility solutions. Regional disparities in charging infrastructure and local policy support also influence EV market penetration.
Île-de-France
Urban professionals and fleet operators drive substantial EV demand in Île-de-France, particularly within the Paris metropolitan area. The stringent ZFE-m regulations in Paris compel rapid transitions to electric vehicles for unrestricted city access. This region sees concentrated EV registrations and public charging infrastructure deployment to support its dense population.
Auvergne-Rhône-Alpes
Strong corporate sustainability goals from regional businesses and local government initiatives spur EV adoption in Auvergne-Rhône-Alpes. Lyon's ZFE-m program specifically encourages electric vehicle use for logistics and passenger transport within the city. This area benefits from a growing network of public charging stations and a focus on green mobility solutions.
Provence-Alpes-Côte d'Azur
Tourism and a strong environmental consciousness among residents boost electric vehicle sales across the Provence-Alpes-Côte d'Azur region. Local municipalities implement incentives beyond national schemes, such as free parking for EVs in cities like Nice. Coastal areas and major cities like Marseille are prioritizing charging infrastructure expansion to cater to both residents and visitors.
Nouvelle-Aquitaine
Fleet electrification for agricultural businesses and logistics companies represents a key demand segment in Nouvelle-Aquitaine. The French government's bonus-malus écologique system provides significant purchase incentives for low-emission vehicles, benefiting rural and semi-urban buyers. Bordeaux and its surrounding areas are witnessing increased investment in fast-charging hubs to support longer-distance EV travel.
France Electric Vehicle Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the French electric vehicle market, creating a dynamic competitive structure. This landscape features established automotive manufacturers alongside newer entrants challenging traditional business models and consumer expectations. Key strategic archetypes include legacy automakers adapting their extensive portfolios and technology-driven disruptors emphasizing proprietary ecosystems and direct sales. Competitive moves involve significant investment in battery technology development, expanding public and private charging network partnerships, and advanced software integration.
Among the long-standing automotive brands, Renault S.A. and Peugeot S.A. exemplify the strategic shift towards electrification, leveraging their established dealership networks. Tesla, Inc., a prominent US-based manufacturer, represents the technology-centric approach, emphasizing battery innovation and its proprietary Supercharger infrastructure. These companies anchor different segments of the French EV market, from mass-market offerings to premium and performance-oriented vehicles, shaping consumer choices through varied market positioning.
| Leading Market Players |
|---|
| Peugeot |
| BMW |
| Renault |
| Skoda |
| Dacia |
| Tesla |
| Citroën |
| Mercedes-Benz |
| Volkswagen |
| Others |
Cost & Logistics Intelligence
France's stringent ZFE-m regulations, combined with corporate sustainability mandates, are forcing automotive manufacturers to prioritize EV production. This shift is creating supply-side pricing power for critical battery components and specialized EV platforms.
Pricing Analysis
Short lead times for advanced EV battery chemistries command a premium in the French market, while standard-range models may see discounts for existing inventory. Per-unit transactional pricing dominates for vehicle sales, though subscription models gain traction for urban professionals. Price differentiation stems from battery capacity and after-sales service bundles. Pricing softness reflects competition from established players and new entrants. Fleet operators are most price-sensitive, while tech enthusiasts prioritize features over initial cost.
Supply Chain Analysis
CE marking and EU-wide charging connector standards gate entry for EV components into the French market, ensuring product safety and interoperability. The EV supply chain draws heavily from Asian sources for battery cells, particularly China and South Korea, and critical raw materials from Australia and the DRC. Single-source vulnerability for specific battery chemistries poses a structural risk. Distribution runs through authorized dealerships for vehicle sales, with online platforms gaining traction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France electric vehicle market is currently supply-constrained, with battery cell manufacturing capacity acting as a primary bottleneck. This constraint is propping up pricing for high-performance EV models.
For Market Incumbents: Anchor existing market share by expanding domestic battery production partnerships and securing long-term raw material contracts. Defend against new entrants by accelerating software-defined vehicle development and enhancing charging infrastructure access. Renault and Peugeot must leverage their established dealership networks to offer comprehensive after-sales service, mitigating technician skill gaps. Investment in LFP battery R&D can reduce reliance on volatile nickel and cobalt.
For New Entrants and Emerging Players: Online platforms and direct-to-consumer sales provide a cost-effective go-to-market strategy for new EV brands in France. Target the light commercial vehicle segment, particularly for last-mile logistics, where ZFE-m regulations compel adoption. Offer flexible subscription and leasing models to lower upfront costs for budget-conscious small businesses. Focus on seamless digital integration and customer experience to differentiate from legacy automakers.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term growth in the French EV ecosystem. Target specialized battery recycling and second-life battery system developers for their circular economy potential. Acquire companies with advanced charging technology or smart grid integration solutions to address infrastructure gaps. A signal to watch is the consistent deployment pace of public fast-charging stations outside metropolitan areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures critical components, de-risking production for French automotive OEMs. |
| Charging Infrastructure Partnership | Expands public charging access, supporting mass EV adoption across France. |
| Software-Defined Vehicle Investment | Enhances vehicle features and connectivity, attracting tech-savvy French buyers. |
| LCV Electrification Focus | Addresses specific demand from fleet operators and ZFE-m regulations in France. |
| Second-Life Battery Development | Creates new value streams and addresses environmental concerns for used EV batteries. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, validated through primary interviews. We engaged with automotive OEM executives, fleet managers, charging infrastructure providers, and policy advisors. This approach combined bottom-up market sizing with top-down validation against macroeconomic indicators.
Volume and value outputs were modeled at a granular level across vehicle type, charging infrastructure, consumer demographic, and sales channel. CAGRs were derived from historical growth trends and projected adoption rates over the analysis window. Key forecast inputs included national incentive budgets, ZFE-m expansion schedules, and battery cost reduction trajectories.
The model holds under current regulatory frameworks and expected technological advancements; deviation in geopolitical stability or raw material supply would shift projections. Forecasts reflect assumptions documented through extensive primary and secondary research. A model refresh is warranted upon material change in EU decarbonization targets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
Electric Bike Kit Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
Global Electric All Wheel Drive (AWD) Market
Electric Vehicles
Solar Golf Cart Market
Electric Vehicles
North America Electric Bus Market
Electric Vehicles
Electric Vehicle Battery on Demand Market
Electric Vehicles
Automotive Battery Pack Compression Pad Market
Electric Vehicles
New Energy Vehicle (NEV) Taxi Market
Electric Vehicles
Asia-Pacific Electric Bus Market