
 HCV Brake Components Market | 2026-2036
HCV Brake Components Market Size, Share, and Industry Trends Forecast 2026-2036
HCV Brake Components Market Outlook
Indian friction material producers is repositioning capacity toward disc brake pad lines as domestic OEMs phase out drum configurations. Continental AG leverages captive foundry networks across Central Europe to sustain cast iron disc supply. Knorr-Bremse AG anchors pneumatic actuator output through dedicated plants in Germany and China. ZF Friedrichshafen AG competes on integrated brake control architectures that merge pneumatic modulation with electronic sensing.
HCV brake components encompass friction elements, actuation hardware, and control modules engineered to dissipate kinetic energy from commercial vehicles exceeding 3.5 tonnes gross vehicle weight; sintered metallic pads operate at continuous temperatures above 350°C while carbon-ceramic rotors reduce unsprung mass by 40-60% versus cast iron equivalents. Brake pad formulations dominate replacement volume due to wear-rate sensitivity under high-frequency urban braking cycles. Electronic systems within the component layer capture margin concentration as air-disc brake penetration rises and fleet operators specify telematics-linked wear monitoring. Carbon composite rotors remain confined to premium coach and racing-derived applications where thermal shock resistance justifies unit cost premiums.
The US NHTSA Federal Motor Vehicle Safety Standard 121 mandates stopping distance thresholds for air-braked trucks, directly shaping friction material R&D priorities. Europe's ECE R90 homologation and REACH chemical restrictions constrain aftermarket pad composition, while India's BIS IS 11852 certification creates non-tariff barriers for unapproved imports. Stakeholders must calibrate regional compliance investments against the divergent pace of electronic braking mandates across North America, Europe, and Asia-Pacific manufacturing hubs.
Market Dynamics
Air-disc brake electrification is compressing replacement cycles and forcing tier-1 suppliers to restructure actuator foundry networks around integrated electronic control modules rather than standalone pneumatic hardware.
Growth Catalysts
- ECE R90 homologation expansion:European aftermarket pad certification requirements are filtering substandard imports and elevating certified supplier margins in Germany and Poland.
- Sintered metallic formulation advances:Continuous operating temperature thresholds above 400°C now enable extended service intervals for mining haulers in Western Australia and Chile.
- Shandong province production clustering:Heavy truck OEM concentration in China's eastern manufacturing corridor generates captive demand for brake disc and drum casting capacity.
Market Restraints
- Cast iron input volatility:Scrap metal pricing fluctuations and energy-intensive foundry operations compress margin stability for disc rotor manufacturers.
- Carbon-ceramic unit economics:Premium rotor production remains confined to low-volume coach and motorsport applications due to thermal shock manufacturing yields.
- REACH chemical restrictions:Copper and heavy metal limitations in friction formulations force R&D redirection toward alternative binding agents with unproven wear characteristics.
Strategic Opportunities
- Brazil fleet renewal acceleration:Long-haul freight operator consolidation programs are displacing aged drum-brake configurations with air-disc systems.
- Telematics-integrated wear monitoring:Sensor-enabled brake pad thickness reporting creates recurring revenue attachment for component suppliers serving fleet management platforms.
- India BIS IS 11852 certification:Domestic friction material standards generate protected market access for local producers against unapproved imports.
Industry Challenges
- Mechatronics talent scarcity:Pneumatic-to-electronic brake control migration outpaces technician training pipeline capacity in Central European manufacturing hubs.
- Dual certification timelines:Simultaneous FMVSS 121 and ECE R90 homologation requirements extend product launch cycles for multi-region brake system suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HCV Brake Components Market |
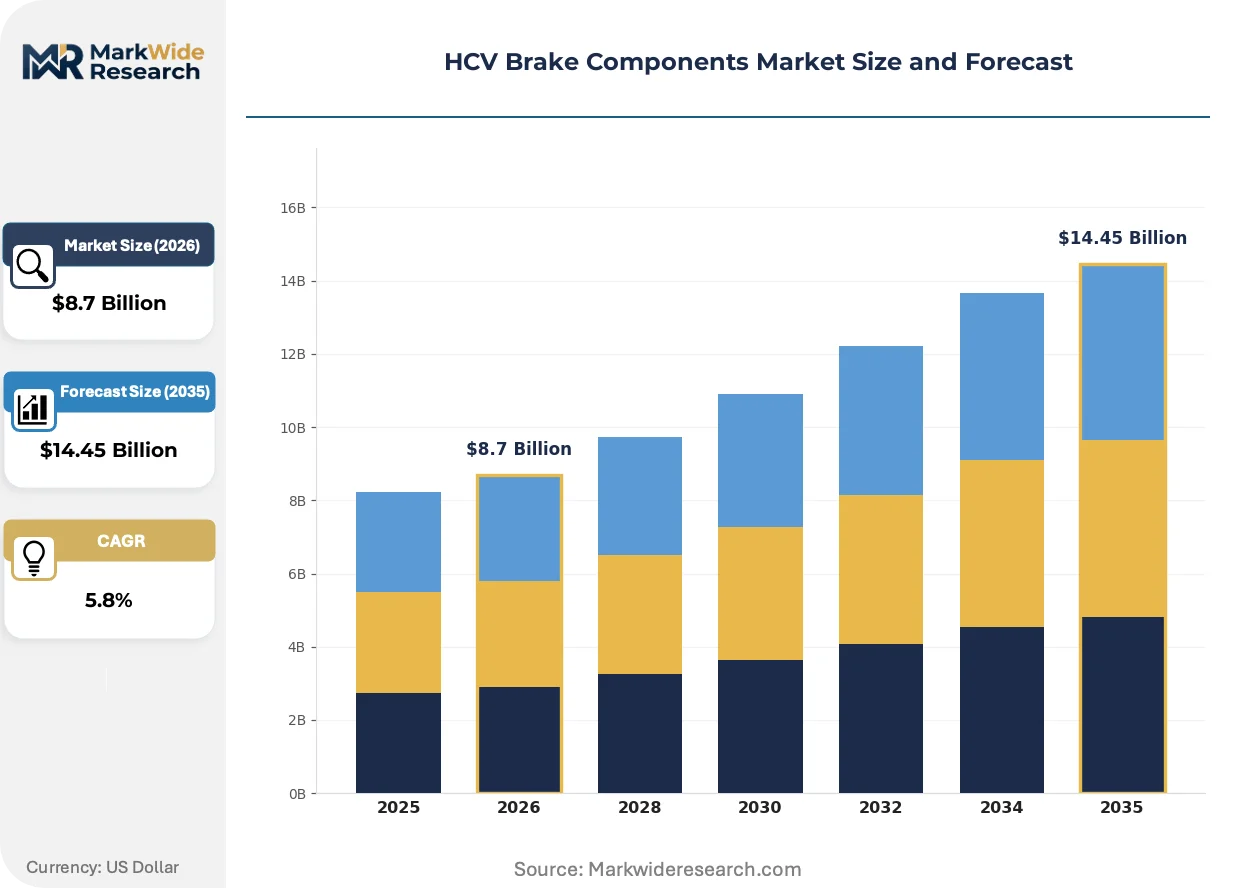
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brake Pads, Brake Discs, Brake Shoes, Brake Calipers Component: Hydraulic Systems, Pneumatic Systems, Electronic Systems, Actuators Material: Cast Iron, Carbon Composite, Ceramic, Steel End User: OEMs, Aftermarket Providers, Fleet Managers, Vehicle Assemblers |
| Companies Covered | Continental AG, ZF Friedrichshafen AG, Robert Bosch GmbH, Knorr-Bremse AG, Brembo S.p.A., Akebono Brake Industry Co Ltd, Valeo S.A, Nissin Kogyo Co. Ltd., Mando Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HCV Brake Components Market Strategic Shifts
Electronic braking architectures are displacing standalone pneumatic systems across heavy commercial vehicle segments, compressing hardware margins while expanding software and sensor content per axle.
Electro-pneumatic brake control is unifying pneumatic actuation with electronic modulation in integrated valve modules. European long-haul fleets are specifying these systems at accelerating rates for trailer applications. This convergence is unifying supplier tiers previously separated between mechanical hardware and electronic control specialists.
India's BIS certification mandates for brake friction materials are tightening chemical composition and performance testing protocols. Domestic OEM procurement departments are restricting vendor pools to certified suppliers exclusively. Aftermarket distributors in Maharashtra and Tamil Nadu are restructuring inventory toward approved pad lines.
Fleet operator buying committees are consolidating brake component procurement under total cost of ownership frameworks rather than unit price minimization. Large transport operators in Germany and the Netherlands are negotiating direct supply agreements with tier-1 manufacturers. This concentration is visible most acutely in refrigerated logistics segments where downtime costs dominate specification decisions.
HCV Brake Components Market Segmentation
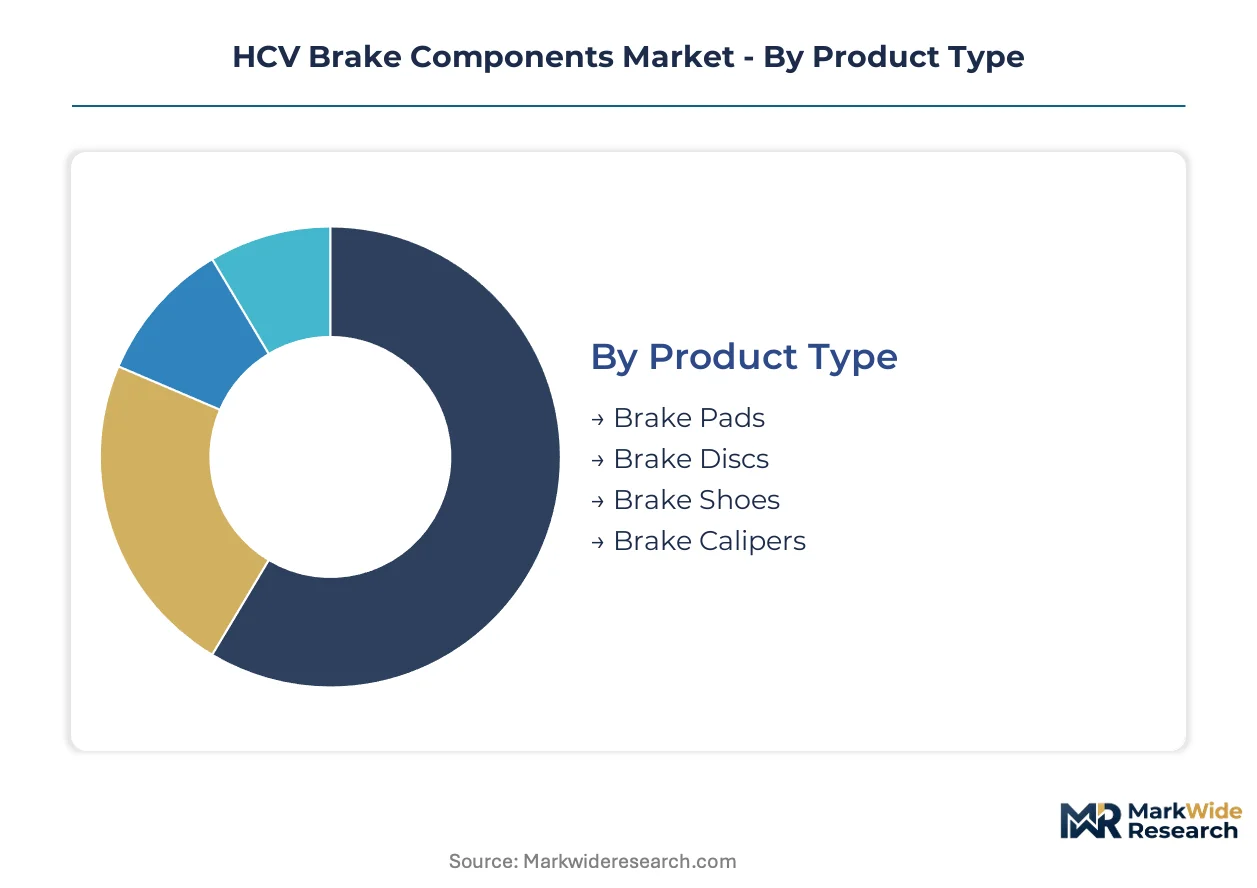
HCV brake component procurement splits sharply between high-volume wear items and premium integrated systems. Fleet operators prioritize total cost of ownership calculations that favor certified friction materials over lowest-unit-price alternatives. Component suppliers must align portfolio depth across both replacement velocity tiers and specification complexity tiers.
Product Type:
Volume leaders command replacement frequency while premium disc configurations capture specification upgrades in fleet renewal programs.
- Brake Pads:Sintered metallic and organic formulations dominate replacement demand due to wear-rate sensitivity under urban braking cycles. India's BIS-certified producers are capturing procurement share as domestic OEMs restrict vendor pools to approved suppliers exclusively.
- Brake Discs:Cast iron rotors sustain foundry network utilization across Central European supplier footprints. Shandong province heavy truck clusters generate captive demand for ventilated disc castings serving air-disc brake conversions.
- Brake Shoes:Drum brake configurations retain residual share in emerging market cost-sensitive segments and certain trailer applications. Brazil's long-haul fleet consolidation is accelerating displacement toward disc alternatives.
- Brake Calipers:Integrated electronic actuation modules merge pneumatic modulation with sensor feedback in next-generation architectures. These assemblies concentrate margin capture as electro-pneumatic penetration rises.
Today's leader: Brake Pads. Tomorrow's challenger: Brake Calipers.
Component:
System architecture determines margin capture, with electronic layers expanding software content per axle while pneumatic hardware faces compression.
- Hydraulic Systems:Medium-duty commercial vehicles and certain regional truck configurations retain hydraulic actuation for cost optimization. These systems concentrate in price-sensitive procurement segments across Latin American and Southeast Asian markets.
- Pneumatic Systems:Air-brake infrastructure remains standard for heavy commercial vehicles exceeding 12 tonnes gross vehicle weight. US NHTSA FMVSS 121 stopping distance mandates directly shape friction material R&D priorities for these configurations.
- Electronic Systems:Brake control modules integrating modulation algorithms with telematics interfaces capture expanding value per vehicle. European long-haul fleets specify these systems at accelerating rates for trailer compatibility.
- Actuators:Electro-pneumatic valve modules unify previously separated mechanical and electronic supplier tiers. Knorr-Bremse and Continental are restructuring foundry networks around integrated control module output rather than standalone hardware.
Electronic Systems are climbing the fastest as air-disc electrification compresses replacement cycles and elevates sensor content specifications.
Material:
Thermal performance thresholds and unsprung mass requirements segment material selection across duty cycle intensity tiers.
- Cast Iron:Gray iron and ductile iron formulations sustain rotor production at scale through energy-intensive foundry operations. Scrap metal pricing volatility compresses margin stability for manufacturers dependent on secondary metal inputs.
- Carbon Composite:Carbon-ceramic matrices reduce unsprung mass by 40-60% versus cast iron equivalents. Premium coach and motorsport applications justify unit cost premiums where thermal shock resistance dominates specification decisions.
- Ceramic:Advanced ceramic formulations operate at continuous temperatures above 400°C, enabling extended service intervals for mining haulers in Western Australia and Chilean copper extraction corridors.
- Steel:Steel-backed plates and structural hardware provide foundational support for friction material assemblies. REACH chemical restrictions on copper and heavy metals are forcing binding agent redirection toward alternative formulations.
Cast Iron anchors current volume. Carbon Composite represents the steepest expansion trajectory in premium thermal management segments.
End User:
Procurement concentration and specification authority vary sharply across direct OEM supply versus fragmented aftermarket channels.
- OEMs:First-fit specifications lock in multi-year supply agreements with tier-1 system integrators. ZF Friedrichshafen and Continental compete on integrated brake control architectures merging pneumatic modulation with electronic sensing.
- Aftermarket Providers:ECE R90 homologation requirements in Europe are filtering substandard imports and elevating certified supplier margins in Germany and Poland. India's BIS IS 11852 certification creates protected market access for domestic producers.
- Fleet Managers:Large transport operators in Germany and the Netherlands negotiate direct supply agreements under total cost of ownership frameworks. Refrigerated logistics segments exhibit acute concentration where downtime costs dominate specification decisions.
- Vehicle Assemblers:Shandong province production clustering generates captive demand for brake disc and drum casting capacity aligned with heavy truck OEM procurement schedules.
Fleet Managers are consolidating buying power fastest as telematics-integrated wear monitoring creates recurring revenue attachment opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting brake component sourcing as compliance cost differentials widen between mature certification regimes and emerging standard-setters. Manufacturers are relocating foundry and friction material capacity toward jurisdictions where domestic certification creates protected procurement channels.
China
Heavy truck OEM concentration in Shandong province generates captive demand for brake disc and drum casting capacity aligned with local production schedules. MIIT emission and safety standards for commercial vehicles tighten friction material specifications progressively. Qingdao and Jinan manufacturing corridors host integrated supplier parks serving air-disc brake conversion programs.
Germany
KBA type-approval requirements and ECE R90 homologation filter aftermarket pad imports and elevate certified supplier margins. REACH chemical restrictions on copper and heavy metals force binding agent reformulation toward alternative compounds. Continental AG and Knorr-Bremse AG anchor production networks across North Rhine-Westphalia and Bavaria serving European long-haul fleet specifications.
India
Domestic OEM procurement departments restrict vendor pools to BIS IS 11852 certified friction material suppliers exclusively. Long-haul freight operators in Maharashtra and Tamil Nadu expand fleet renewal programs displacing aged drum configurations. Chennai and Pune automotive corridors concentrate brake pad manufacturing capacity repositioning toward disc brake lines.
United States
NHTSA FMVSS 121 stopping distance mandates directly shape friction material R&D priorities for air-braked heavy commercial vehicles. Scrap metal pricing volatility compresses margin stability for cast iron rotor manufacturers dependent on secondary inputs. Michigan and Ohio supplier networks sustain foundry operations serving Detroit-based truck OEM procurement schedules.
Brazil
Long-haul freight operator consolidation programs accelerate displacement of drum-brake configurations toward air-disc systems. ANVISA and national automotive safety regulators align commercial vehicle braking standards with Mercosur technical harmonization. São Paulo state manufacturing clusters host assembly operations generating component demand from regional truck production.
HCV Brake Components Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electronic integration and telematics-linked architectures. The supplier base stratifies between integrated system architects and specialized friction material fabricators. Three archetypes dominate: captive foundry operators controlling cast iron supply, electro-pneumatic module specialists unifying mechanical and electronic tiers, and certified friction formulators serving protected aftermarket channels. Capacity restructuring and certification-driven vendor consolidation represent the dominant competitive vectors.
Among German-based integrated suppliers, Continental AG and ZF Friedrichshafen AG exemplify the system-architect archetype merging pneumatic modulation with electronic sensing. Knorr-Bremse AG anchors the electro-pneumatic tier through dedicated production footprints. These three entities represent contrasting strategic postures within a supplier base restructuring around electronic content expansion rather than standalone hardware volume.
| Leading Market Players |
|---|
| Continental AG |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Knorr-Bremse AG |
| Brembo S.p.A. |
| Akebono Brake Industry Co Ltd |
| Valeo S.A |
| Nissin Kogyo Co. Ltd. |
| Mando Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive foundry networks across Central Europe anchor both supply security and pricing power for cast iron disc manufacturers serving OEM procurement schedules. Continental AG's in-house casting capacity insulates margin stability against scrap metal volatility while compressing competitor pricing headroom in long-term supply agreements.
Pricing Analysis
Distributor margin layers in the European aftermarket compress as ECE R90 homologation filters substandard imports and elevates certified supplier pricing power. Three-tier pricing structure across premium, standard, and economy levels separates OE-certified pads from uncertified alternatives, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from cast iron input volatility as energy-intensive foundry operations face margin tightening. Fleet operators exhibit lowest price sensitivity where downtime costs dominate, while independent repair channels in emerging markets retain acute unit-price focus.
Supply Chain Analysis
Dual-sourcing requirements from European long-haul fleets mandate multi-supplier qualification for brake control modules, forcing tier-1 restructuring around integrated electronic architectures. Geographic supply concentration centers on Germany, China, and India, with Shandong province heavy truck clusters generating captive demand for disc castings. Raw material dependencies rest on scrap steel inputs, copper-binding agents, and rare earth elements for sensor modules. Single-source vulnerability in electro-pneumatic valve production elevates supply risk as mechatronics talent scarcity constrains capacity expansion. Distribution runs through OEM direct supply agreements and certified aftermarket channels with telematics-linked inventory management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HCV brake components represent a late-cycle quality story as fleet operators consolidate procurement under total cost of ownership frameworks favoring certified friction materials over lowest-unit-price alternatives. This demand-shift toward premium specifications elevates margin capture for suppliers with proven air-disc brake integration capabilities.
For Market Incumbents: Anticipate margin compression in standalone pneumatic hardware as electro-pneumatic penetration rises, and defend position through backward integration into sensor module production and captive foundry capacity expansion in Shandong province. Certification investment in India's BIS IS 11852 and Europe's ECE R90 homologation creates channel control against emerging entrant price competition. For New Entrants and Emerging Players: BIS IS 11852 certification in India opens a window for domestic friction material producers to capture protected market access as OEM procurement departments restrict vendor pools exclusively. Target Brazil's fleet renewal acceleration where long-haul operator consolidation displaces aged drum configurations, and pursue telematics-integrated wear monitoring partnerships as the primary go-to-market angle for recurring revenue attachment. For Investors and Strategic Acquirers: Roll-up economics work for certified friction material fabricators because regulatory barriers create protected aftermarket channels with elevated margin stability. The 5-10 year viability window favors suppliers with demonstrated electro-pneumatic integration capabilities and captive foundry networks. Watch air-disc brake penetration rates in European trailer applications as the primary inflection indicator for electronic content expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Electro-Pneumatic Module Integration | Unifies pneumatic actuation with electronic sensing in valve architectures specified by Knorr-Bremse and Continental. |
| Backward Integration into Sensor Production | Captures margin concentration as telematics-linked wear monitoring elevates software content per axle. |
| BIS IS 11852 Certification Investment | Creates protected procurement access as Indian OEMs restrict vendor pools to certified suppliers exclusively. |
| Foundry Network Restructuring | Aligns cast iron disc capacity with Shandong province heavy truck production clusters dominating procurement volumes. |
| Fleet Direct Supply Agreements | Bypasses distributor margin layers as German and Dutch transport operators consolidate procurement under total cost of ownership frameworks. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with tier-1 supplier procurement teams, OEM platform engineers, aftermarket distributors, and fleet maintenance directors with secondary validation. Secondary sources include NHTSA FMVSS 121 regulatory filings, ECE R90 homologation databases, BIS certification records, vehicle production data from IHS Markit, and SEC 10-K disclosures from listed automotive suppliers. Bottom-up unit volume estimates triangulate against top-down market value reconstructions.
Granularity-level modeling operates at product type, component architecture, material grade, and end-user channel dimensions, with additional segmentation by regional regulatory cluster and OEM production hub. Value projections across the analysis window derive from pricing trajectories in certified versus uncertified product tiers, replacement cycle compression from air-disc electrification, and content-per-vehicle expansion in electronic control modules. CAGRs reflect compound annual progression assumptions calibrated to fleet renewal program announcements and regulatory mandate timelines.
Revisions become necessary when scrap metal pricing volatility exceeds historical bands, electro-pneumatic adoption rates deviate from fleet specification trends, or REACH chemical restrictions force binding agent reformulation with unproven wear characteristics. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Automotive Air Lift Jack Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
Automotive Parking Heater Market
Automotive Parts
Automotive Engine Cooling Fan Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
Mexico Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Fuel Injection Cleaning Machine Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Global All Wheel Drive Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Adaptive Engine Mounts Market