
 India Automotive Lubricants Market | 2026-2036
India Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Lubricants Market Outlook
Workshop-to-retail distribution in tier-two and tier-three towns is tilting toward direct distributor models with digital inventory tracking. Castrol India Limited leverages its franchised service network to sustain brand visibility in semi-urban markets. Gulf Oil Lubricants India Ltd anchors its position through motorsport sponsorships that reinforce performance credentials among fleet buyers. Indian Oil Corporation Limited dominates institutional supply through its PS-1 and SERVO brands at state transport depots.
Automotive lubricants are formulated base oil blends with viscosity modifiers, detergents, and anti-wear additives engineered to reduce friction, dissipate heat, and prevent corrosion in powertrain assemblies. Engine oil commands the largest volume share due to mandatory drain intervals in both petrol and diesel powertrains, while synthetic technology leads value growth as OEMs specify longer service life for turbocharged engines. The aftermarket provider channel generates the highest margin pools through branded packaged goods sold via independent mechanics rather than bulk OEM fill.
BIS lubricant standards and the Automotive Research Association of India's emission testing protocols shape product specifications for the domestic market. India's PLI scheme for advanced chemistry cell batteries is indirectly redirecting lubricant R&D toward thermal management fluids for hybrid architectures. Stakeholders must monitor how state-level EV adoption targets in Delhi and Karnataka redefine fluid demand beyond traditional internal combustion formulations.
Market Dynamics
Fleet operators in Maharashtra and Gujarat are consolidating procurement around synthetic formulations as BIS certification mandates tighten quality thresholds across the domestic supply base. This concentration of demand among institutional buyers is compressing margin structures for mid-tier blenders while elevating specification barriers to entry.
Growth Catalysts
- PLI scheme for advanced chemistry cell batteries:The incentive framework is redirecting lubricant R&D toward thermal management fluids for hybrid powertrain architectures, opening adjacent formulation categories beyond conventional engine oils.
- Logistics corridor expansion:Dedicated freight corridors connecting Delhi-Mumbai and Chennai-Bengaluru are extending vehicle utilization rates, shortening drain intervals and accelerating consumption velocity in the commercial segment.
- BIS lubricant standards tightening:Mandatory quality certification is eliminating substandard imports and informal blending operations, formalizing market share for compliant domestic manufacturers.
Market Restraints
- Group II/III base oil import dependency:Domestic refiners lack hydrocracking capacity for high-viscosity-index feedstocks, exposing blenders to freight and currency volatility from Middle Eastern suppliers.
- EV adoption timelines in Delhi and Karnataka:State-level electrification targets are creating demand uncertainty for traditional internal combustion formulations in the two largest metropolitan clusters.
- Additive package concentration:Four global chemical houses control 70% of dispersant and anti-wear chemistry supply, constraining formulation differentiation for domestic blenders.
Strategic Opportunities
- Tier-three town direct distribution:Digital inventory tracking platforms are enabling bypass of multi-layer wholesale networks in Uttar Pradesh and Madhya Pradesh, capturing margin pools previously lost to intermediary markups.
- Hybrid thermal management fluids:Dual-clutch and mild-hybrid architectures require dedicated coolants and transmission fluids with dielectric properties, representing uncaptured white space in current product portfolios.
- Automotive Research Association of India protocol alignment:Early certification to ARAI emission testing standards positions suppliers for OEM fill contracts as domestic vehicle manufacturers upgrade powertrain efficiency.
Industry Challenges
- Formulation chemist scarcity:Indian Institutes of Technology and regional engineering colleges produce fewer than 200 lubricant-specialized graduates annually, constraining R&D pipeline velocity for indigenous additive development.
- Used oil collection infrastructure:Extended Producer Responsibility regulations under the Hazardous Waste Management Rules lack enforcement mechanisms, leaving re-refining capacity underutilized despite 1.3 million tonnes of annual waste oil generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Lubricants Market |
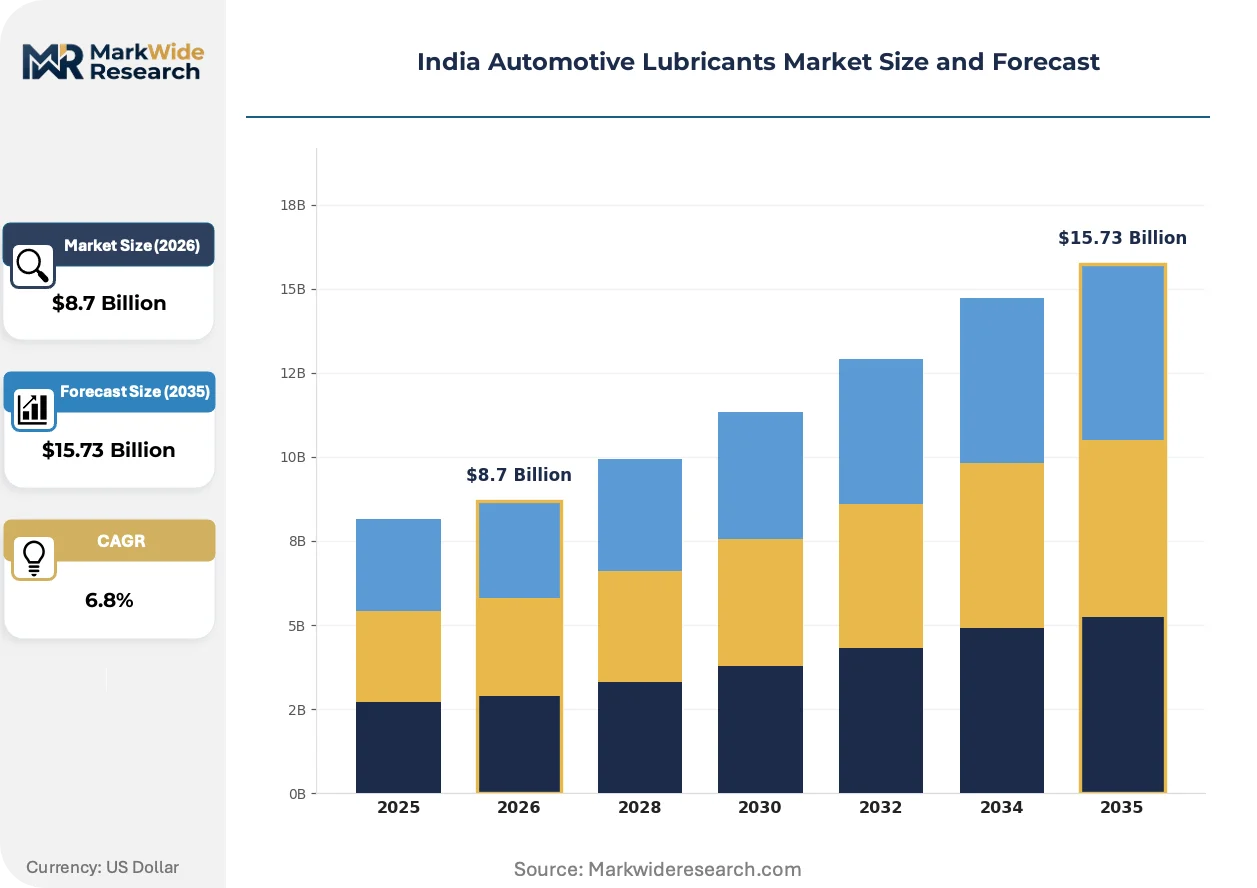
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
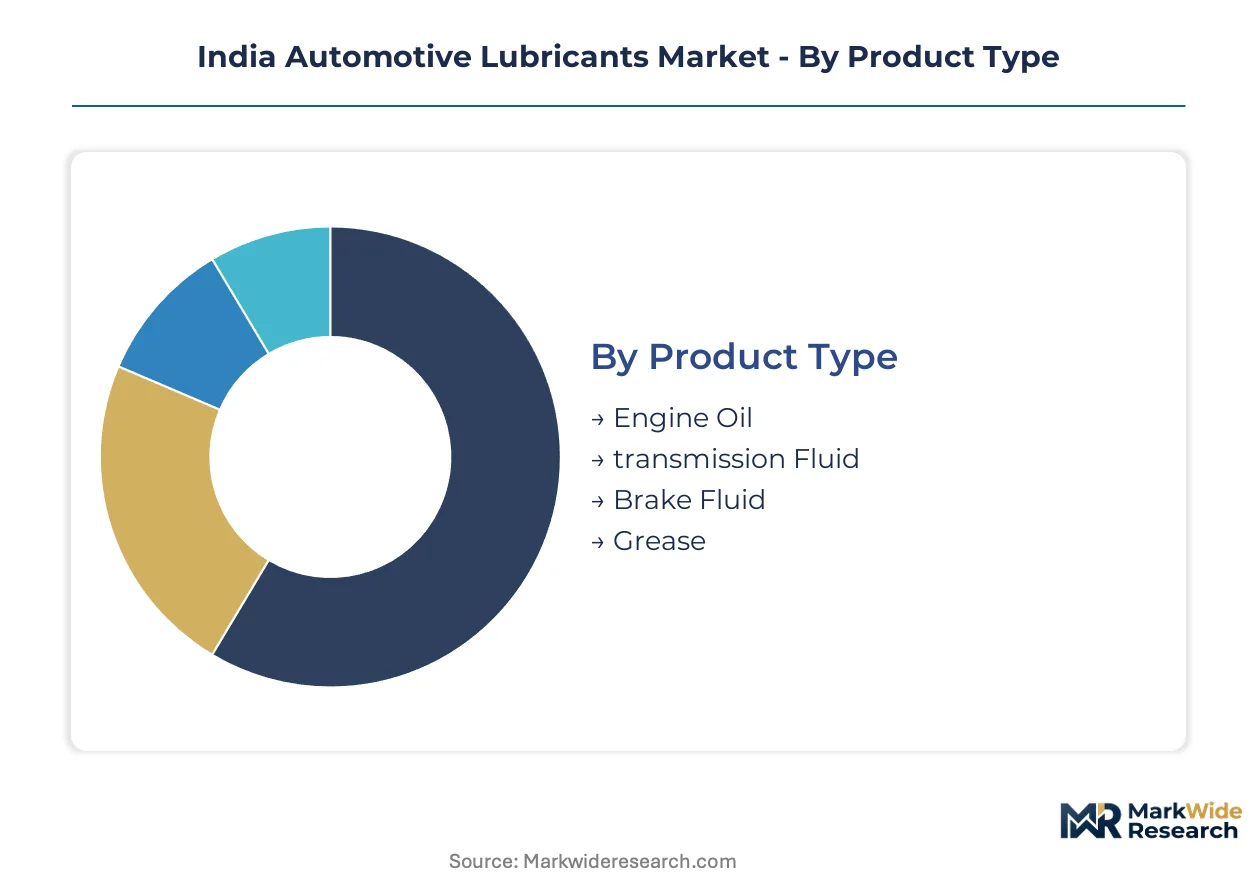
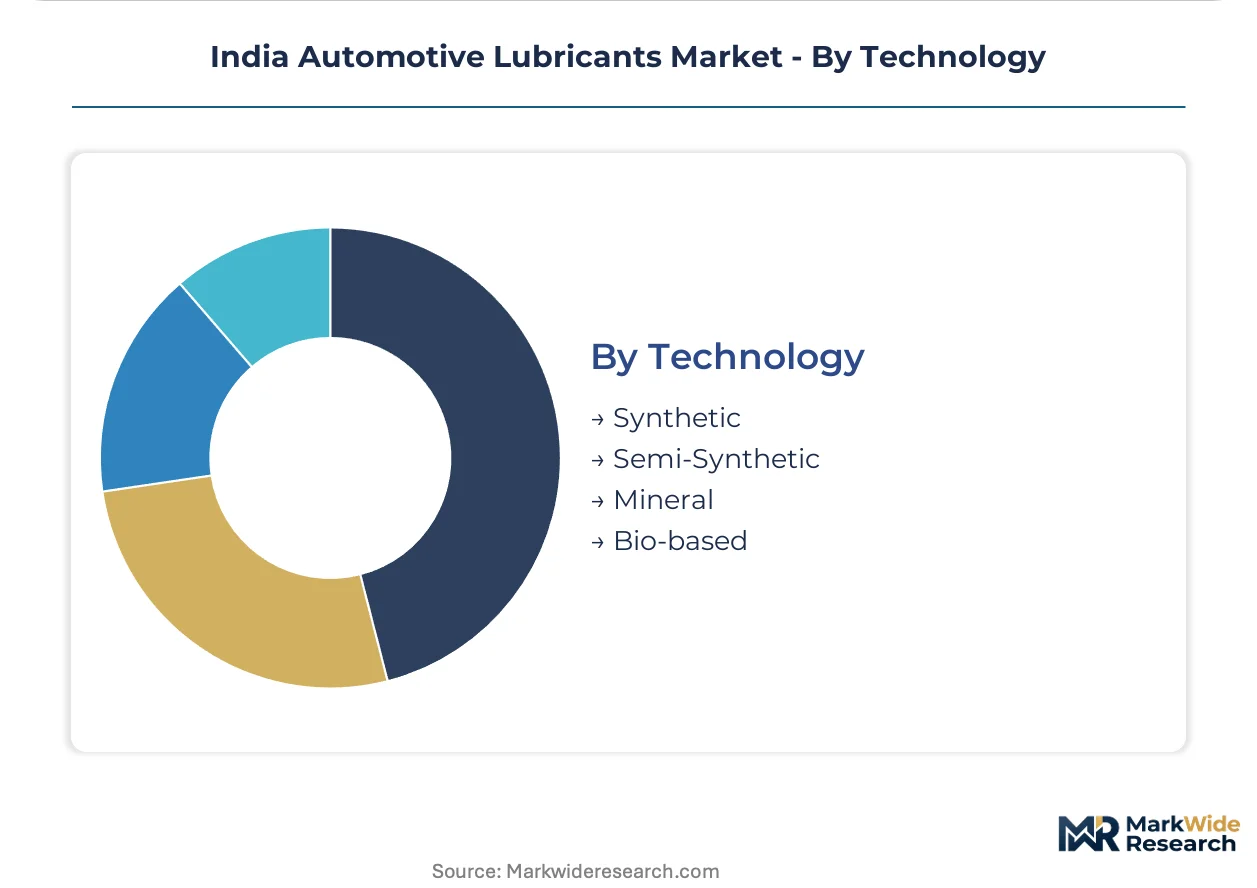
| Segmentation | Product Type: Engine Oil, transmission Fluid, Brake Fluid, Grease End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Heavy Equipment, Motorcycles Technology: Synthetic, Semi-Synthetic, Mineral, Bio-based |
| Companies Covered | Castrol India Limited, Gulf Oil Lubricants India Ltd, Indian Oil Corporation Limited, Valvoline Cummins Private Limited, Tide Water Oil Co. (India) Ltd, Bharat Petroleum Corporation Limited, Shell India Markets Private Limited, TotalEnergies Marketing India Private Ltd, Hindustan Petroleum Corporation Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Lubricants Market Strategic Shifts
Synthetic technology is collapsing the traditional service interval architecture that has governed aftermarket revenue models for decades. Three interconnected developments are compressing competitive timelines and reallocating value capture across the formulation chain.
Polyalphaolefin and ester-based synthetics are collapsing the viscosity degradation curves that previously constrained drain intervals to 5,000 kilometers. Fleet operators operating Bharat Stage VI powertrains are adopting 15,000-kilometer service schedules, compressing lubricant volume per vehicle-year while elevating per-liter specification requirements. This trade-off is collapsing aftermarket transaction frequency and forcing service networks to unbundle oil changes from complementary maintenance revenue.
BIS certification mandates for lubricant quality are tightening product standards nationwide, eliminating the specification gap between OEM fill and aftermarket formulations. The Automotive Research Association of India is integrating lubricant performance into vehicle type-approval testing, forcing blenders to pre-certify formulations against engine durability protocols. Maharashtra-based automotive manufacturing clusters are responding fastest, with supplier qualification timelines compressing from 18 months to 9 months for certified products.
Fleet procurement is consolidating around annual volume contracts with direct manufacturer relationships, bypassing the traditional distributor-workshop hierarchy. Large transport operators in Gujarat are mandating digital service records with RFID-tagged consumption tracking, displacing cash-based spot purchases at independent mechanics. This behavioral shift is most visible along the Delhi-Mumbai logistics corridor, where telematics-integrated maintenance is collapsing information asymmetry between buyers and suppliers.
India Automotive Lubricants Market Segmentation
After-sales service intensity varies sharply across lubricant categories in India's automotive value chain. Workshop labor economics and drain interval frequency determine where margin pools concentrate and which distribution channels dominate procurement flows.
Product Type:
Service bay throughput and technician labor allocation diverge dramatically by fluid category, with some requiring specialized equipment and others enabling rapid turnover.
- Engine Oil:Formulated base oil blends with viscosity modifiers, detergents, and anti-wear additives protect powertrain assemblies from friction and thermal degradation. Maharashtra and Gujarat absorb the dominant share as fleet operators consolidate procurement around synthetic formulations for Bharat Stage VI powertrains with extended drain intervals.
- Transmission Fluid:Specialized lubricants for gearboxes and differentials incorporate extreme-pressure additives and friction modifiers to manage shear stress across temperature ranges. Commercial vehicle workshops in the Delhi-Mumbai logistics corridor report rising specification complexity as automated manual transmissions proliferate in heavy-duty fleets.
- Brake Fluid:Hygroscopic glycol-ether formulations maintain hydraulic integrity across braking system temperature extremes.
- Grease:Thickened oil suspensions with soap or complex thickener systems seal chassis components and wheel bearings against contamination.
By volume, Engine Oil leads. By growth pace, Transmission Fluid is ahead.
End User:
Procurement scale and price sensitivity separate institutional buyers from fragmented retail channels, with each tier demanding distinct service architectures.
- OEMs:Vehicle manufacturers specify factory-fill formulations during assembly, requiring pre-certification to ARAI durability protocols and BIS quality mandates. First-fill contracts concentrate among domestic passenger car plants in Tamil Nadu and Haryana, where specification barriers compress supplier lists to blenders with integrated additive packages.
- Aftermarket Providers:Independent workshops and retail distributors generate the highest margin pools through branded packaged goods sold via mechanic networks. Uttar Pradesh and Madhya Pradesh exhibit the fastest channel expansion as digital inventory tracking platforms bypass traditional wholesale hierarchies.
- Dealerships:Authorized service networks combine lubricant sales with scheduled maintenance packages.
- Vehicle Assemblers:Commercial vehicle and two-wheeler factories source bulk formulations for initial fill.
Aftermarket Providers command the widest footprint. OEMs capture the most stable contract tenure.
Application:
Vehicle utilization rates and operating duty cycles determine fluid consumption velocity and specification severity across transport modes.
- Passenger Vehicles:Synthetic engine oils dominate as turbocharged petrol and diesel powertrains proliferate in urban markets. Karnataka and Delhi state-level electrification targets are compressing long-term demand visibility for conventional formulations despite current volume concentration.
- Commercial Vehicles:Fleet operators along dedicated freight corridors are adopting telematics-integrated maintenance with RFID-tagged consumption tracking. Gujarat-based transport companies mandate annual volume contracts with direct manufacturer relationships, collapsing the distributor-workshop hierarchy.
- Heavy Equipment:Construction and mining machinery operates in high-contamination environments requiring frequent service.
- Motorcycles:High-revving small-displacement engines stress thermal stability in clutch-integrated sump designs.
Commercial Vehicles generate the highest per-vehicle consumption intensity. Passenger Vehicles offer the broadest addressable base.
Technology:
Base oil group chemistry and additive sophistication stratify pricing architecture and performance claims across the formulation spectrum.
- Synthetic:Polyalphaolefin and ester-based formulations deliver extended drain intervals up to 15,000 kilometers by resisting viscosity degradation. Fleet procurement in Maharashtra is consolidating around synthetic technology as BIS certification mandates eliminate substandard alternatives and OEM service specifications tighten.
- Semi-Synthetic:Blended base oil combinations balance cost and performance for mid-market vehicle owners. Tier-two and tier-three towns in Rajasthan and Punjab exhibit expanding penetration as workshop technicians recommend upgraded formulations for aging powertrains.
- Mineral:Group I base oil formulations serve price-sensitive segments with conventional drain intervals.
- Bio-based:Vegetable-derived base stocks address sustainability preferences in niche fleet segments.
Synthetic technology leads value expansion. Semi-Synthetic formats bridge the widest customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands premium pricing power through its automotive manufacturing density, while Uttar Pradesh and Madhya Pradesh trade at thinner margins due to fragmented distributor networks. This geographic asymmetry shapes procurement consolidation patterns across the domestic market.
Maharashtra
Pune and Mumbai anchor the country's densest automotive manufacturing corridor, with fleet operators consolidating synthetic lubricant procurement around BIS-certified formulations. The state's industrial policy incentivizes advanced chemistry R&D through dedicated chemical parks near Taloja. OEM service networks in the Chakan belt are compressing supplier qualification timelines from 18 months to 9 months for certified products.
Gujarat
Sanand and Vadodara host expanding commercial vehicle assembly operations that drive institutional bulk demand for transmission fluids and engine oils. The state's logistics corridor investments along the Delhi-Mumbai freight route extend vehicle utilization rates and accelerate consumption velocity. Large transport operators in Ahmedabad mandate telematics-integrated maintenance with RFID-tagged consumption tracking.
Karnataka
Bengaluru's technology-driven passenger vehicle market shows early specification shifts toward hybrid thermal management fluids. State-level EV adoption targets are compressing long-term demand visibility for conventional internal combustion formulations despite current volume concentration. The Electronics City manufacturing cluster is piloting dielectric coolant requirements for mild-hybrid powertrains.
Tamil Nadu
Chennai's OEM first-fill contracts concentrate among domestic passenger car plants where ARAI durability protocols govern supplier selection. The Sriperumbudur automotive belt maintains strict BIS quality mandates that eliminate substandard blending operations. Component manufacturers in the Oragadam industrial corridor are extending drain interval specifications for export-bound vehicles.
Haryana
Gurugram and Manesar house premium passenger vehicle assembly operations that specify synthetic formulations for turbocharged powertrains. The state's proximity to Delhi-NCR logistics hubs creates overlapping demand from commercial fleet operators seeking extended service intervals. Industrial lubricant distributors in Faridabad are digitizing inventory tracking to bypass traditional wholesale hierarchies.
India Automotive Lubricants Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream of formulation chemistry. The India automotive lubricants market structures around three distinct player tiers: integrated oil majors with captive refining and additive capabilities, mid-scale blenders dependent on imported base stocks, and niche specialists targeting fleet-specific service contracts. Competitive moves concentrate on backward integration into additive package sourcing and digital platform deployment for direct distributor relationships.
Within the integrated oil major tier, Castrol India Limited and Indian Oil Corporation Limited exemplify divergent route-to-market strategies. Castrol anchors brand visibility through franchised service networks in semi-urban markets, while Indian Oil dominates institutional supply chains at state transport depots. Gulf Oil Lubricants India Ltd occupies a position emphasizing performance credentials through motorsport-linked positioning among fleet buyers.
| Leading Market Players |
|---|
| Castrol India Limited |
| Gulf Oil Lubricants India Ltd |
| Indian Oil Corporation Limited |
| Valvoline Cummins Private Limited |
| Tide Water Oil Co. (India) Ltd |
| Bharat Petroleum Corporation Limited |
| Shell India Markets Private Limited |
| TotalEnergies Marketing India Private Ltd |
| Hindustan Petroleum Corporation Limited |
| Others |
Value Chain & Pricing Dynamics
The Delhi-Mumbai logistics corridor's freight economics compress transport margins while amplifying price differentiation between bulk synthetic formulations and spot-market mineral oils. BIS certification mandates tighten specification barriers that concentrate pricing power among integrated blenders with captive additive sourcing, leaving mid-tier distributors exposed to cost pass-through volatility.
Pricing Analysis
The customization-premium spread separates fleet annual volume contracts from retail spot purchases, with synthetic formulations commanding substantial uplifts over mineral base stocks. Price differentiation hinges on BIS certification tier and after-sales service bundling through telematics-integrated maintenance platforms. Pricing pressure stems from fleet procurement consolidation around direct manufacturer relationships, compressing intermediary markups. Tier-three town workshops exhibit highest price sensitivity, while Gujarat-based transport operators with RFID-tagged consumption tracking show lowest sensitivity due to total cost of ownership optimization.
Supply Chain Analysis
Contract manufacturing concentration sits with domestic refiners lacking hydrocracking capacity for Group II/III base stocks, forcing reliance on Middle Eastern suppliers. Geographic supply concentration centers on Saudi Arabia, Kuwait, and the UAE for high-viscosity-index feedstocks, while additive packages draw from four global chemical houses controlling dispersant and anti-wear chemistry. Single-source vulnerability runs through hydrocracked base oil import channels exposed to currency and freight volatility. Distribution runs through franchised service networks in semi-urban markets and direct distributor models with digital inventory tracking in tier-two and tier-three towns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India automotive lubricants market represents high-growth disruption as BIS certification mandates and PLI scheme incentives for hybrid architectures simultaneously elevate specification barriers and redirect R&D investment.
For Market Incumbents: Pre-empt formulation chemist scarcity by anchoring captive R&D pipelines through Indian Institutes of Technology partnerships and in-house additive development programs. Defend against fleet procurement consolidation by deepening direct distributor relationships with digital inventory tracking platforms in Uttar Pradesh and Madhya Pradesh. Prioritize backward integration into base oil sourcing to mitigate Middle Eastern import dependency.
For New Entrants and Emerging Players: Build out hybrid thermal management fluid portfolios targeting mild-hybrid dielectric coolant requirements in Karnataka's Electronics City manufacturing cluster. The most penetrable segment lies in tier-three town direct distribution bypassing multi-layer wholesale networks. A go-to-market angle through motorsport-linked performance credentialing can accelerate fleet buyer acceptance.
For Investors and Strategic Acquirers: Mid-scale blenders with ARAI pre-certification and established OEM fill relationships represent the most attractive acquisition target archetype. Long-term viability over the next decade hinges on positioning for thermal management fluid categories beyond conventional engine oils. Monitor state-level EV adoption targets in Delhi and Karnataka as the critical inflection signal for demand trajectory revision.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Development | In-house dispersant chemistry reduces dependency on four global chemical houses controlling formulation inputs. |
| Direct Distributor Platform Deployment | Digital inventory tracking in tier-three towns captures margin pools previously lost to wholesale intermediaries. |
| Hybrid Thermal Management Fluid Certification | ARAI alignment for dielectric coolants positions suppliers for mild-hybrid OEM fill contracts in Karnataka. |
| Fleet Telematics Integration | RFID-tagged consumption tracking collapses information asymmetry between Gujarat transport operators and blenders. |
| Re-refining Capacity Utilization | Extended Producer Responsibility enforcement under Hazardous Waste Management Rules unlocks circular feedstock supply. |
Study Parameters
A spread of perspectives from lubricant formulation chemists, fleet procurement managers, aftermarket distributors, and BIS certification auditors converged on the working assumptions underlying demand projections. Primary interviews with OEM platform engineers and state transport depot supply officers were cross-validated against secondary sources including ARAI emission testing protocols, BIS quality mandate documentation, and vehicle production databases. Bottom-up segmentation modeling triangulated with top-down macroeconomic drivers anchored volume and value estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning product type, end user category, vehicle application, and base oil technology tier. CAGRs were derived from elasticity-adjusted consumption velocity models incorporating fleet utilization rates along dedicated freight corridors and drain interval extension trends for Bharat Stage VI powertrains. Hybrid architecture penetration curves and state-level electrification policy trajectories informed scenario-weighted outputs.
Sensitivities concentrate around EV adoption timeline acceleration in Delhi and Karnataka, Group II/III base oil import cost volatility, and enforcement rigor under Extended Producer Responsibility regulations. Forecasts reflect documented assumptions regarding BIS certification mandate implementation pace and PLI scheme incentive continuity. Quarterly review of fleet telematics adoption rates, re-refining capacity utilization, and additive package pricing indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Motorcycle Top Box Market
Automotive Parts
India Brake Pads Market
Automotive Parts
China Ceramic Ball Bearing Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Electric Fuel Pumps Market
Automotive Parts
Automotive Canister Purge Valve Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Automatic Gearbox Valves Market