
 Automotive Crankcase Additives Market | 2026-2036
Automotive Crankcase Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Crankcase Additives Market Analysis
Chemist and tribology specialist shortages across the lubricant additive industry are redrawing competitive boundaries in the Automotive Crankcase Additives Market. The Lubrizol Corporation leverages its captive R&D infrastructure and backward integration into key raw materials to sustain formulation leadership. Afton Chemical Corporation anchors its position through deep OEM relationships and just-in-time supply contracts with major automakers. Infineum International Limited differentiates via joint venture structures that combine Shell's base oil access with ExxonMobil's chemical process technology.
Automotive crankcase additives comprise detergent-dispersant packages, anti-wear agents, friction modifiers, and viscosity index improvers blended into lubricating oils to control deposits, neutralize acids, and reduce engine wear under high-temperature, high-shear operating conditions. Engine Oil Additives dominate value capture due to mandatory drain-interval extensions and OEM fill-for-life specifications, while Bio-Based technology represents the fastest-growing chemistry platform as fleet operators face Scope 3 emissions disclosure requirements. Synthetic technology leads margin pools because of premium pricing tied to ACEA C-class and API SP performance certifications.
EPA emissions standards and the EU F-Gas Regulation constrain volatile organic compound content in crankcase ventilation systems, while REACH chemical authorization rules govern zinc dialkyldithiophosphate and molybdenum compound usage in European formulations. These frameworks push additive suppliers toward ashless anti-wear chemistries and polymeric dispersant architectures that maintain performance at reduced treat rates. Stakeholders must monitor how OEM electrification timelines alter crankcase lubricant demand curves and whether aftermarket service intervals compress as hybrid powertrains impose novel thermal cycling stresses on engine oils.
Market Dynamics
Engine downsizing and turbocharger penetration are forcing additive suppliers to reformulate detergent-dispersant packages for higher thermal loads and extended drain intervals mandated by OEM fill-for-life specifications.
Growth Catalysts
- ACEA C-class and API SP certifications:Passenger vehicle OEMs in Germany and the United States now mandate these performance tiers for factory fills, creating mandatory upgrade cycles across service networks.
- EPA emissions standards:Tightening limits on particulate matter and nitrogen oxides compel lubricant formulators to optimize ash content and sulfur levels in crankcase ventilation systems.
- Turbocharger penetration:China-based automakers are fitting forced induction on sub-1.5L engines at unprecedented rates, multiplying demand for high-temperature stable viscosity index improvers.
Market Restraints
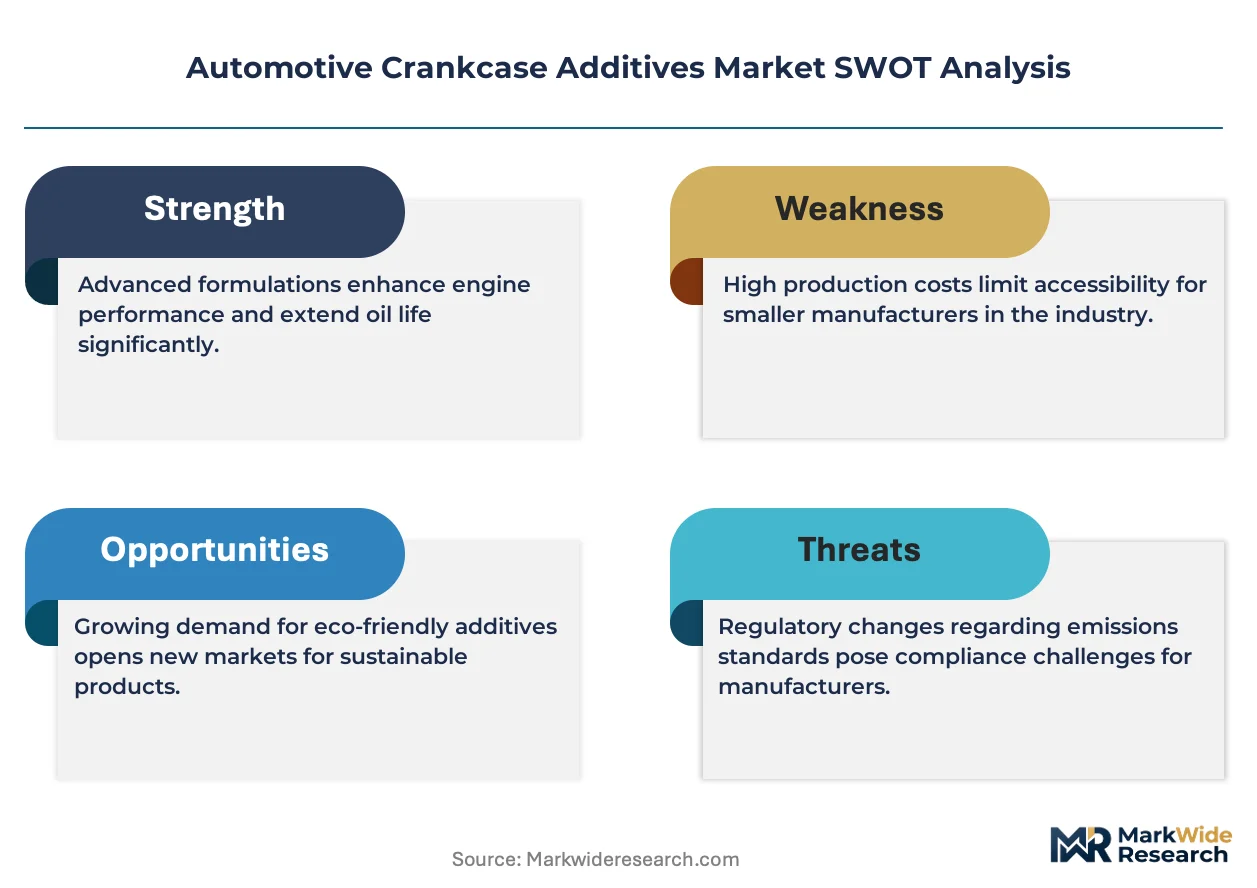
- Zinc dialkyldithiophosphate supply concentration:REACH authorization constraints on ZDDP precursors in Europe force additive blenders to qualify alternative anti-wear chemistries at elevated R&D cost.
- Base oil grade fragmentation:The shift from Group I to Group III and PAO stocks in Germany and the United States requires reformulation of polar dispersant architectures, extending qualification timelines.
- Hybrid powertrain lubricant incompatibility:Novel thermal cycling stresses in PHEV crankcases degrade conventional additive packages faster, threatening warranty claims and brand liability.
Strategic Opportunities
- India commercial vehicle aftermarket:BS-VI compliance deadlines and extended drain interval marketing by fleet operators create first-mover advantage for SAPS-light formulations.
- Carbon disclosure mandates:EU CSRD Scope 3 reporting requirements push logistics and ride-hail fleets toward bio-based crankcase additives with certified lifecycle emissions data.
- AI-driven oil condition monitoring:Integration of sensor data with predictive maintenance platforms enables just-in-time additive replenishment services for industrial engine operators.
Industry Challenges
- Tribology specialist scarcity:The lubricant additive industry faces critical shortages of chemists capable of balancing friction modification with deposit control in low-viscosity formulations.
- OEM qualification timelines:Fill-for-life specifications require 150,000+ kilometer field trials, compressing development windows and straining capital allocation for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Crankcase Additives Market |
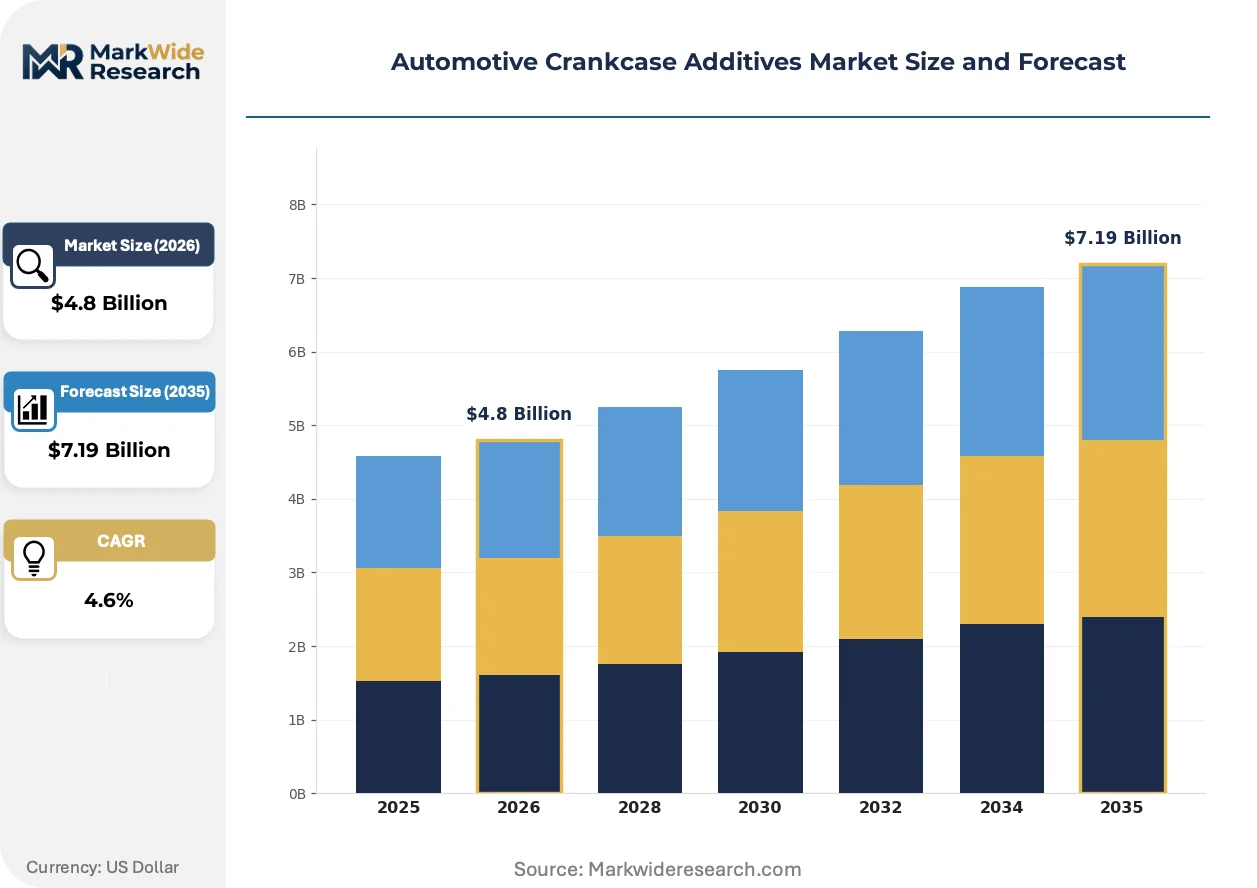
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil Additives, Fuel System Additives, Performance Enhancers, Detergents Technology: Synthetic, Mineral, Semi-Synthetic, Bio-Based End User: OEMs, Aftermarket Providers, Fleet Operators, Distributors Packaging Type: Bottles, Pails, Drum, Bulk |
| Companies Covered | The Lubrizol Corporation, Afton Chemical Corporation, Chevron Corporation, Evonik Industries, Royal Dutch Shell, Croda International, ABRO Industries, ENI SpA, Infineum International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Crankcase Additives Market Emerging Trajectories
Additive chemistry is fragmenting along performance-certification lines as synthetic base stocks and bio-derived feedstocks compete for formulation share in diverging OEM specifications.
Polymeric dispersant architectures are decomposing traditional succinimide chemistry's dominance in deposit control. European OEMs are adopting these high-molecular-weight alternatives for ACEA C6 factory fills. The technology is decomposing margin structures for conventional additive packages as treat rates drop while unit costs rise.
REACH chemical authorization rules are constraining molybdenum dithiocarbamate and ZDDP usage in European crankcase formulations. Blenders are accelerating ashless anti-wear trials to maintain EP performance at reduced sulfur levels. Germany-based formulators face the steepest compliance cost escalation as KBA type-approval documentation requirements expand.
Fleet procurement departments are consolidating lubricant supplier rosters around certified carbon intensity scores. Third-party fluid analysis laboratories in the United States are capturing additive specification influence previously held by OEM technical service bulletins. This concentration is most visible among Class 8 truck operators in California facing CARB fleet reporting mandates.
Automotive Crankcase Additives Market Segmentation
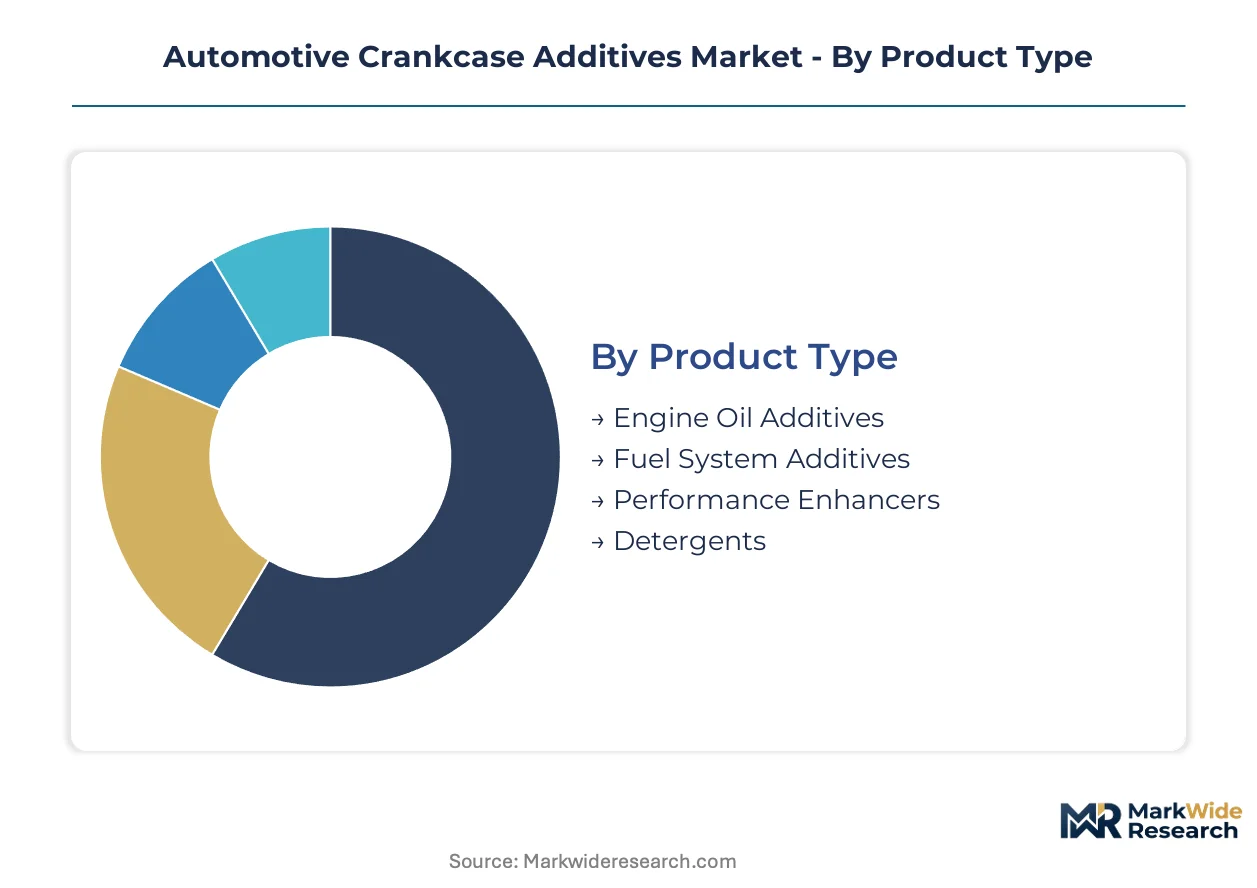
Crankcase additive purchasing decisions fragment across certification tiers, thermal stress profiles, and supply chain integration levels. Understanding these splits reveals where formulation premiums concentrate and which customer types drive specification upgrades.
Product Type:
REACH and EPA sulfur limits differentiate treat rate requirements across additive categories, with ACEA C-class and API SP certifications forcing divergent chemistry investments.
- Engine Oil Additives:Detergent-dispersant packages, anti-wear agents, and viscosity index improvers blended for high-temperature, high-shear protection. Factory fill specifications in Germany and the United States mandate extended drain intervals, locking in premium treat rates for OEM supply contracts.
- Performance Enhancers:Friction modifiers and extreme-pressure additives targeting fuel economy gains. Fleet operators in California facing CARB reporting mandates prioritize these chemistries for Scope 3 emissions reductions.
- Fuel System Additives:Deposit control agents and combustion improvers for intake valve cleanliness.
- Detergents:Alkaline reserve components neutralizing acidic byproducts in turbocharged crankcases.
Established volume favors Engine Oil Additives; emerging adoption favors Performance Enhancers.
Technology:
Cost tiers separate laboratory qualification timelines and backward integration requirements among chemistry platforms.
- Synthetic:PAO and Group III base stocks with polymeric dispersant architectures. ACEA C6 and API SP certifications in Germany command premium pricing tied to fill-for-life warranties.
- Bio-Based:Plant-derived feedstocks with certified lifecycle emissions data. EU CSRD Scope 3 disclosure rules accelerate fleet procurement of these formulations.
- Mineral:Group I and II base oils with conventional succinimide chemistry.
- Semi-Synthetic:Blended base stocks bridging performance and cost for service network volumes.
Margin concentration favors Synthetic; regulatory tailwinds favor Bio-Based.
End User:
Customer type determines specification authority and contract structure across the value chain.
- OEMs:Factory fill purchasers mandating 150,000+ kilometer field trials and KBA type-approval documentation. Just-in-time supply contracts with major automakers lock in multi-year formulation commitments.
- Fleet Operators:Consolidated procurement departments consolidating supplier rosters around certified carbon intensity scores. Class 8 truck operators in California drive fluid analysis laboratory influence over additive specifications.
- Aftermarket Providers:Service network distributors managing inventory complexity across certification tiers.
- Distributors:Regional logistics intermediaries balancing bulk procurement against SKU fragmentation.
Specification authority favors OEMs; procurement consolidation favors Fleet Operators.
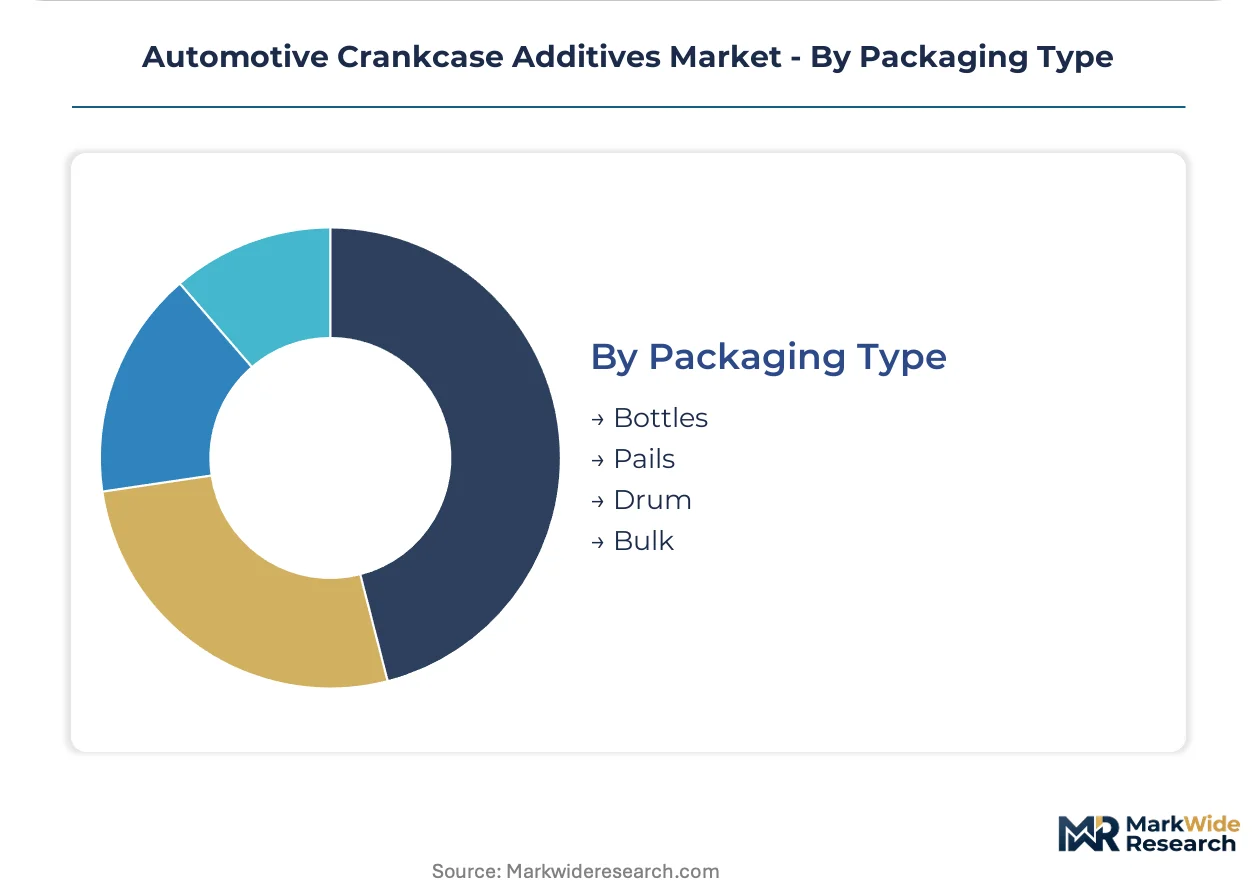
Packaging Type:
Volume scale and handling economics segment delivery formats from retail service bays to manufacturing plants.
- Bulk:Tanker and tote deliveries for OEM fill plants and large fleet depots. Direct pipeline integration at manufacturing facilities in the United States eliminates packaging cost.
- Drum:55-gallon steel containers for mid-volume service operations and regional distributors.
- Pails:5-gallon plastic containers for independent repair shops.
- Bottles:Quart and liter retail formats for consumer DIY applications.
Cost efficiency favors Bulk; channel reach favors Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards in the United States anchor the dominant geography, with Germany's REACH framework and China's MIIT regulations creating parallel compliance corridors that reshape additive chemistry investments across three continents.
United States
ACEA C-class certification adoption by domestic OEMs drives specialized lubricant demand for turbocharged engines. EPA sulfur limits and CARB fleet reporting mandates in California force reformulation toward lower SAPS architectures. Detroit-area manufacturing clusters concentrate factory fill contracts with just-in-time supply integration.
Germany
KBA type-approval documentation requirements extend qualification timelines for fill-for-life specifications. REACH chemical authorization rules constrain zinc dialkyldithiophosphate and molybdenum compound usage in crankcase formulations. Stuttgart and Munich industrial corridors host additive R&D facilities serving premium OEM supply chains.
China
MIIT engine downsizing policies accelerate turbocharger penetration on sub-1.5L passenger vehicle platforms. Dual carbon goals and GB standards push fleet operators toward certified low-emission lubricant procurement. Yangtze River Delta manufacturing bases concentrate domestic additive blending capacity for regional OEMs.
India
BS-VI compliance deadlines create aftermarket upgrade cycles for commercial vehicle lubricants. Extended drain interval marketing by logistics fleets drives SAPS-light formulation adoption. Maharashtra and Gujarat industrial zones concentrate refining and blending infrastructure serving domestic demand.
Japan
METI fuel economy standards compel friction modifier integration in factory fill specifications. JIS certification requirements maintain premium positioning for synthetic base stock formulations. Nagoya and Tokyo metropolitan areas anchor OEM technical partnerships with additive suppliers.
Automotive Crankcase Additives Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around captive R&D infrastructure and backward integration into key raw materials. The upper tier commands multi-year OEM supply contracts through fill-for-life warranty alignment, while mid-tier players compete on regional qualification speed and aftermarket service network coverage. Strategic archetypes include integrated formulators with base oil access, specialty chemical houses with dispersant technology, and regional blenders with logistics optimization. Competitive moves concentrate on joint venture structures combining upstream chemical process technology with downstream OEM relationships, plus portfolio diversification into bio-derived feedstock platforms.
Within the integrated formulator tier, The Lubrizol Corporation, Afton Chemical Corporation, and Infineum International Limited exemplify archetypes combining captive R&D infrastructure with deep OEM technical partnerships. These entities occupy positions where backward integration into raw materials and forward integration into factory fill specifications create defensive moats against qualification timeline compression. The Lubrizol Corporation represents the standalone specialty chemical house model, Afton Chemical Corporation anchors the deep OEM relationship archetype, and Infineum International Limited sits within the joint venture structure combining Shell's base oil access with ExxonMobil's process technology.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| Afton Chemical Corporation |
| Chevron Corporation |
| Evonik Industries |
| Royal Dutch Shell |
| Croda International |
| ABRO Industries |
| ENI SpA |
| Infineum International Limited |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between additive suppliers and OEM fill plants lock in multi-year supply access while anchoring price visibility for both parties. These contracts concentrate volume commitments around ACEA C-class and API SP certification tiers, insulating premium synthetic formulations from spot-market volatility while exposing mineral-based packages to raw material cost swings.
Pricing Analysis
Contract-based long-term offtake structures dominate OEM supply relationships, with three-tier pricing stratification across premium synthetic, standard semi-synthetic, and economy mineral grades. Price differentiation rests on certification level and volume scale, with ACEA C6 and API SP factory fills commanding substantial premiums tied to fill-for-life warranties. Cost compression in mineral-tier packages is intensifying because of Group I base oil phase-outs and succinimide chemistry margin erosion. Fleet operators consolidating supplier rosters around carbon intensity scores exhibit the highest price sensitivity, while OEM technical partnerships show the least.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for ZDDP precursors and polymeric dispersant feedstocks sourced from Chinese chemical parks. Supply concentrates in Germany, the United States, and China, with backward integration into key raw materials varying sharply across these hubs. The additive value chain draws from specialized chemical intermediates including succinic anhydride, polyisobutylene, and molybdenum compounds. Single-source vulnerability around REACH-authorized ZDDP alternatives in Europe presents structural risk. Distribution runs through direct pipeline integration at OEM manufacturing facilities, supplemented by bulk tanker deliveries to fleet depots and drum shipments to regional service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as electrification timelines splinter lubricant demand across hybrid thermal cycling profiles, PHEV intermittent operation, and residual ICE extended-drain specifications. This demand-side shift creates niches for specialized formulations that incumbent broad-line suppliers under-serve.
For Market Incumbents: Secure captive supply of ashless anti-wear chemistries and polymeric dispersant architectures before REACH authorization constraints tighten further. Deepen backward integration into bio-derived feedstock platforms to defend margin position against Scope 3 disclosure mandates. The threat of hybrid powertrain lubricant incompatibility demands accelerated R&D in thermal cycling-resistant additive packages. For New Entrants and Emerging Players: Predictive maintenance integration services represent a service-layer gap where incumbents under-serve industrial engine operators lacking sensor-data analytics capabilities. Target India commercial vehicle aftermarket for SAPS-light formulations ahead of BS-VI compliance maturation. White-space exists in certified carbon-intensity scoring services for fleet procurement departments. A go-to-market angle partnering with third-party fluid analysis laboratories in California bypasses entrenched OEM technical bulletin influence. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among additive suppliers with embedded factory fill contracts and KBA type-approval documentation depth. Long-term viability across the analysis window favors entities combining captive R&D infrastructure with backward integration into raw materials. Acquisition targets should display joint venture structures or deep OEM technical partnerships. The signal to watch is OEM electrification timeline acceleration compressing ICE crankcase additive demand curves faster than modeled.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Key Raw Materials | Captive supply of ZDDP alternatives and polymeric dispersant feedstocks insulates margin from REACH authorization volatility. |
| Joint Venture Structure Formation | Combining base oil access with chemical process technology accelerates qualification timelines for ACEA C6 factory fills. |
| Bio-Derived Feedstock Platform Investment | Certified lifecycle emissions data unlocks fleet procurement consolidation around Scope 3 disclosure compliance. |
| AI-Driven Oil Condition Monitoring Service Launch | Sensor integration with predictive maintenance platforms enables just-in-time additive replenishment for industrial operators. |
| Regional Blending Capacity Expansion | Yangtze River Delta and Maharashtra industrial zone presence captures turbocharger-driven demand from China and India OEMs. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and tribology R&D directors converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation from EPA emissions filings, REACH authorization databases, ACEA oil sequences documentation, and customs trade data. Bottom-up volume modeling across product type, technology platform, and end-user segments triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled encompass product category, chemistry platform, base stock technology, end-user archetype, and regional regulatory cluster. Value projections across the analysis window derived from treat rate evolution, certification tier pricing spreads, and OEM fill-for-life penetration curves. CAGRs were computed from annualized growth rates across these segmented demand drivers. Forecast inputs included turbocharger penetration rates by engine displacement, electrification timeline scenarios, and fleet carbon disclosure adoption curves.
Forecasts assume regulatory continuity in EPA sulfur limits, REACH chemical authorization frameworks, and EU CSRD Scope 3 reporting mandates; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Power Steering Oil Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Air Suspension Systems Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Automotive Battery Frames Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Automotive Brake Actuator Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
Drum Brake Market
Automotive Parts
Wind Shield Washer Market