
 RV Gear Reducer Market | 2026-2036
RV Gear Reducer Market Size, Share, and Industry Trends Forecast 2026-2036
RV Gear Reducer Market Insights
Capital-intensity divergence between in-house machining capability and outsourced gear grinding is reorganizing competitive tiers in the RV gear reducer landscape. Nabtesco sustains dominance through captive control over needle bearing and cycloid disc production. Harmonic Drive Systems differentiates via specialized strain wave expertise in semiconductor and medical robot segments. Zhejiang Shuanghuan Driveline leverages domestic Chinese supply chain density to compete on planetary reducer variants for industrial machinery.
An RV gear reducer employs a cycloidal disc mechanism meshing with needle bearings to achieve single-stage reduction ratios exceeding 100:1 with backlash below one arc-minute, serving primarily as the joint actuator in six-axis industrial robots and precision rotary tables. Planetary gear reducers occupy the broadest volume tier across material handling and construction equipment applications where cost sensitivity outweighs absolute precision. Compact installation configurations for collaborative robots and mobile robot arms represent the fastest-growing structural segment as OEMs prioritize torque density in confined joint envelopes.
Japan's METI enforces JIS standards for industrial robot safety and reliability that directly specify reducer fatigue life testing protocols, while China's MIIT administers GB standards and dual carbon goals pressuring domestic manufacturers toward higher-efficiency transmission designs. The EU Machinery Directive and CE marking requirements govern RV reducer integration into automated systems exported to European automotive assembly lines. Stakeholders must monitor how ISO 9283 robot performance testing revisions incorporate reducer-specific durability metrics that could reshape supplier qualification criteria.
Market Dynamics
China's MIIT dual carbon goals and GB standards for industrial equipment energy efficiency are tightening product certification requirements, forcing manufacturers to redesign transmission architectures for higher torque density and lower frictional losses. This regulatory compression is accelerating R&D allocation toward compact, high-efficiency cycloidal mechanisms while raising barriers for legacy planetary reducer suppliers lacking in-house precision grinding capability.
Growth Catalysts
- Automotive assembly automation:Six-axis industrial robot deployments on electric vehicle production lines are accelerating procurement of precision cycloidal reducers capable of sub-arc-minute positioning repeatability.
- Japan METI JIS standards:Fatigue life testing protocols for industrial robot safety and reliability directly specify reducer durability metrics, creating qualified demand pull from certified system integrators.
- Collaborative robot joint miniaturization:Torque density requirements in confined envelopes are driving specification shifts toward compact RV architectures with integrated hollow-shaft designs.
Market Restraints
- Needle bearing supply concentration:Captive production of precision needle rollers by dominant Japanese suppliers limits second-tier manufacturers' access to critical subcomponents.
- Specialized gear grinding equipment capex:Multi-million dollar investments in CNC profile grinding machines create capital barriers for new entrants seeking sub-micron tooth profile accuracy.
- Harmonic drive substitution in sub-100Nm applications:Strain wave reducers are capturing precision rotary table and semiconductor robot segments where absolute zero-backlash outweighs torque capacity.
Strategic Opportunities
- China domestic supply chain localization:GB standards compliance and MIIT dual carbon incentives are creating procurement preference windows for locally certified reducer manufacturers.
- Mobile robot arm integration:Autonomous mobile manipulators for warehouse logistics represent an emerging application requiring compact, lightweight joint actuators with integrated motor-reducer units.
- EU Machinery Directive CE marking:Automated system exports to European automotive assembly lines require documented reducer reliability testing, creating certification service revenue streams.
Industry Challenges
- Cycloid disc profile grinding expertise scarcity:Mastering the curved tooth geometry of cycloidal discs requires specialized machinist training programs that OEMs must develop internally.
- ISO 9283 robot performance testing alignment:Pending revisions to reducer-specific durability metrics within international robot testing standards are forcing premature qualification protocol investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RV Gear Reducer Market |
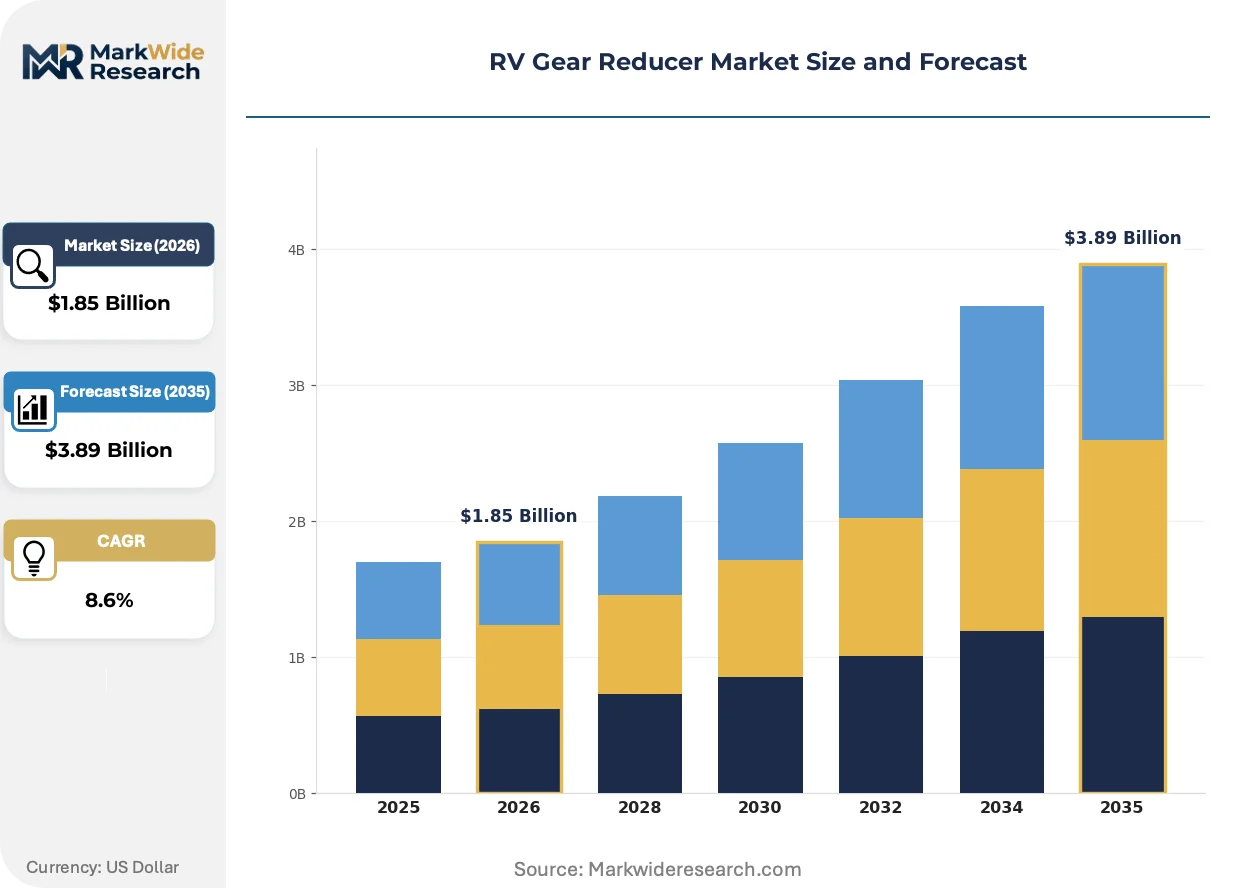
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
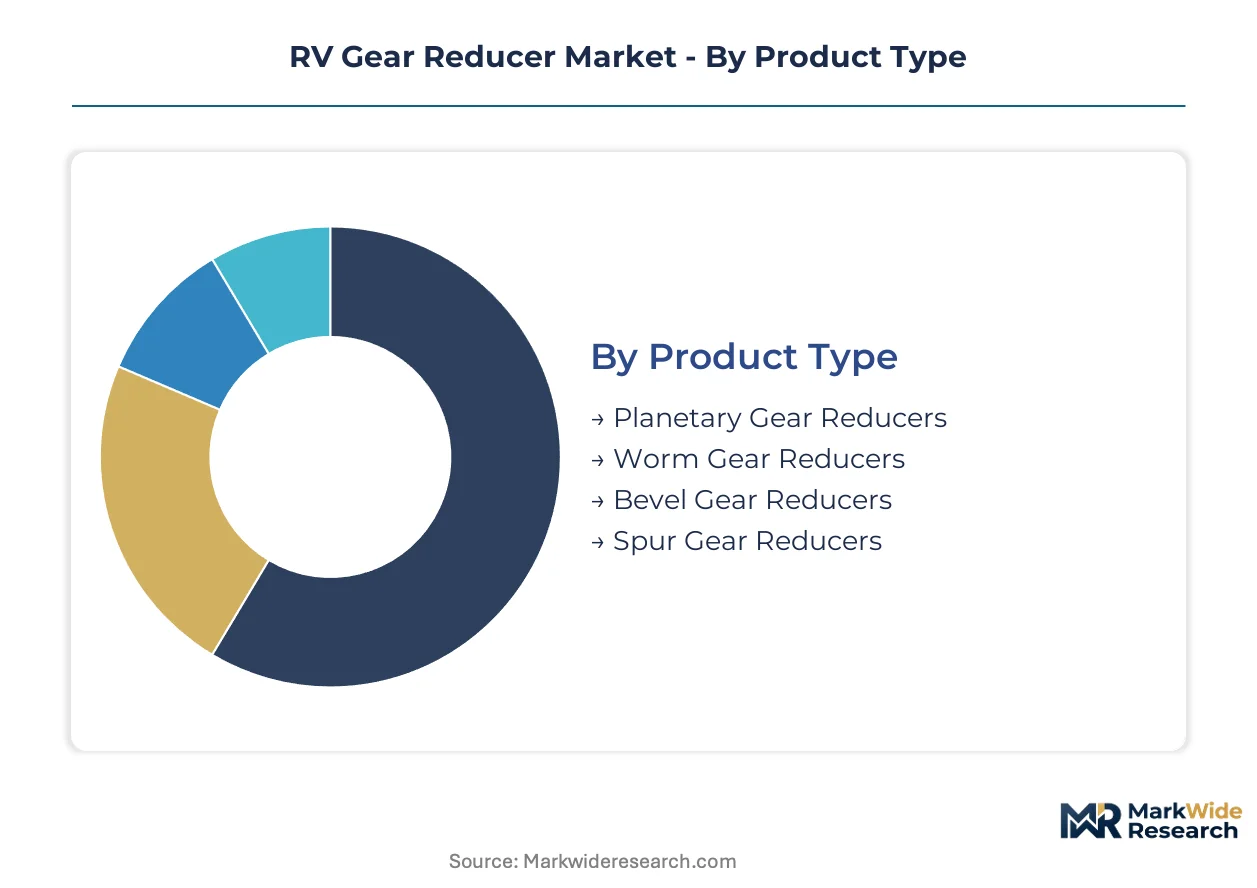
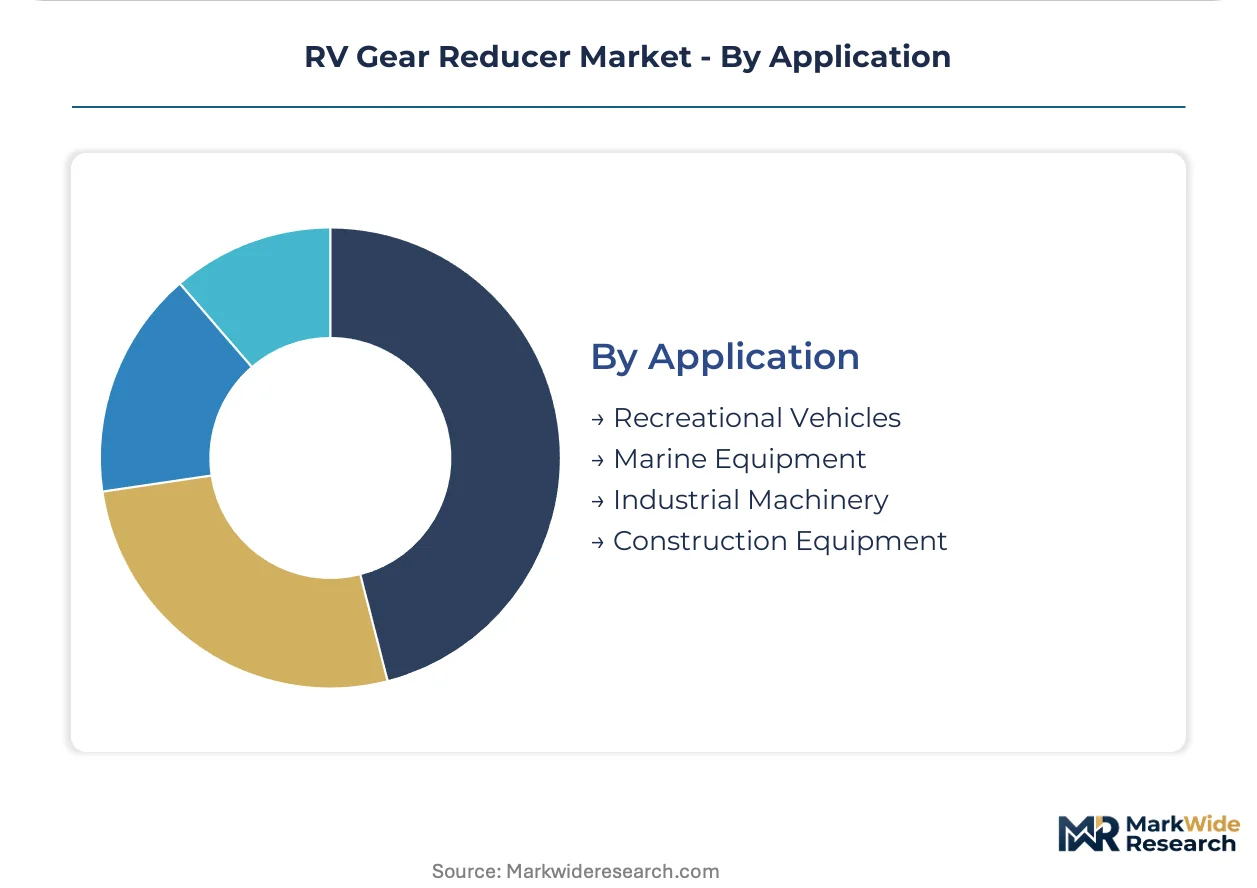
| Segmentation | Product Type: Planetary Gear Reducers, Worm Gear Reducers, Bevel Gear Reducers, Spur Gear Reducers End User: Manufacturers, OEMs, Aftermarket Providers, Retailers Installation: Direct Drive, Compact, Integrated, Standalone Application: Recreational Vehicles, Marine Equipment, Industrial Machinery, Construction Equipment |
| Companies Covered | Nabtesco, Harmonic Drive Systems, Sumitomo Drive Technologies, SPINEA, Zhejiang Shuanghuan Driveline, Ningbo Zhongda Leader, Hengfengtai, Nantong Zhenkang, Leaderdrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RV Gear Reducer Market Trends and Innovations
Precision transmission architecture is undergoing fundamental redesign as torque density requirements collide with energy efficiency mandates. Three interconnected developments are reshaping how manufacturers specify, source, and integrate rotary motion control.
Integrated motor-reducer units with hollow-shaft configurations are displacing conventional separate-component assemblies in collaborative robot joints. Medical device and electronics assembly OEMs are specifying these compact actuators for seven-axis redundant manipulators. This integration trend is compressing supplier tiers as motor manufacturers develop captive gear reduction capability.
China's MIIT GB standards for industrial equipment energy efficiency are mandating documented transmission efficiency testing above 90% rated load. Domestic manufacturers must submit third-party certification to qualify for state procurement programs. This regulatory pressure is most acute in precision rotary table applications serving semiconductor fabrication equipment.
Automotive tier-one suppliers are consolidating reducer vendor bases from multi-source to dual-source qualification models. Long-term framework agreements with volume commitments are replacing spot purchasing for six-axis robot joint actuators. This concentration pattern is most visible in Japan's Nagoya-Tokyo manufacturing corridor serving FANUC and Yaskawa supply chains.
RV Gear Reducer Market Segmentation
RV gear reducer specification pathways diverge sharply between precision industrial robotics and heavy-duty mobile equipment. Segment boundaries are hardening as Japanese, Chinese, and German certification regimes impose distinct performance testing protocols on each product category.
Product Type:
Planetary reducers dominate Chinese domestic production for construction and material handling, while Japanese and German manufacturers concentrate cycloidal and harmonic exports for precision robotics.
- Planetary Gear Reducers:Concentric sun-gear planet-carrier architecture delivers 3:1 to 100:1 reduction ratios through modular stacked stages. Chinese manufacturers in Jiangsu and Zhejiang provinces supply these units for excavator swing drives and automated guided vehicle wheel modules under MIIT GB energy efficiency certification requirements.
- Worm Gear Reducers:Right-angle worm-wheel meshing achieves high reduction in single-stage compact envelopes with inherent self-locking capability. Italian and German suppliers export these configurations for European conveyor systems and lifting equipment requiring CE-marked Machinery Directive compliance.
- Bevel Gear Reducers:Orthogonal shaft arrangements transmit power through spiral or straight bevel gear meshing for confined installation footprints.
- Spur Gear Reducers:Parallel shaft cylindrical gears provide cost-efficient speed reduction for general industrial power transmission with minimal axial load capacity.
Planetary configurations command the established base. The steepest expansion runs through precision cycloidal variants displacing worm architectures in collaborative robot joints.
End User:
Procurement authority concentrates with system integrators holding long-term framework agreements, while aftermarket channels fragment across regional distributor networks.
- Manufacturers:Captive production lines at Nabtesco, Harmonic Drive Systems, and Sumitomo Heavy Industries supply internal robot joint assembly operations with zero-backlash precision units. These integrated manufacturers control needle bearing sourcing and cycloid disc grinding expertise that external suppliers cannot replicate.
- OEMs:FANUC, Yaskawa, and KUKA source qualified reducer batches through dual-source vendor consolidation strategies. Automotive assembly line robot specifications now mandate documented fatigue life testing under revised ISO 9283 protocols.
- Aftermarket Providers:Regional distributors stock replacement units for aging industrial robot installations and construction equipment rebuild programs.
- Retailers:Industrial component distributors serve small-batch maintenance procurement for mid-tier manufacturing facilities without direct OEM relationships.
Manufacturer captive supply dominates precision tier volumes. Aftermarket channels are climbing the fastest as installed base aging accelerates replacement demand.
Installation:
Joint envelope constraints in seven-axis collaborative robots are collapsing traditional separations between motor and reducer housing designs.
- Direct Drive:Elimination of intermediate gearing through high-torque brushless motors serves semiconductor wafer handling and medical device assembly where absolute zero-backlash outweighs torque density requirements.
- Compact:Shortened axial length RV units with hollow-shaft configurations enable cable routing through robot joint centers. These designs are displacing conventional planetary stacks in mobile manipulator arms for warehouse logistics.
- Integrated:Motor-reducer monoblock assemblies with shared thermal management and sealed lubrication systems reduce assembly steps for OEMs.
- Standalone:Conventional foot-mounted or flange-mounted reducers persist in retrofit applications and heavy machinery where existing motor inventories must be preserved.
Standalone architectures retain the installed base. Integrated motor-reducer formats are expanding most quickly through collaborative robot joint specifications.
Application:
Electric vehicle production line automation is repositioning industrial robotics as the primary demand anchor, displacing traditional construction equipment volumes.
- Recreational Vehicles:Slide-out mechanisms and leveling systems utilize compact worm and planetary reducers with weather-sealed enclosures. North American suppliers dominate this specification tier with cost-optimized aluminum housing designs.
- Marine Equipment:Winch and windlass applications require corrosion-resistant coatings and IP67 sealing for salt spray environments. Norwegian and Dutch manufacturers specialize in these heavy-duty configurations for offshore vessel operations.
- Industrial Machinery:Six-axis robot joints, precision rotary tables, and CNC machine tool axes specify sub-arc-minute backlash cycloidal reducers. Japanese Nagoya-Tokyo manufacturing corridor clusters supply FANUC and Yaskawa assembly lines with METI JIS-certified units.
- Construction Equipment:Excavator swing drives and crane hoist mechanisms utilize high-torque planetary stacks where operational durability outweighs positioning precision.
Construction equipment retains volume leadership. Industrial machinery applications are gaining share fastest through automotive EV line automation procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese buyers accept premium pricing for METI-certified precision units, while Chinese manufacturers compete aggressively on planetary reducer variants for cost-sensitive construction applications. This elasticity gap shapes how suppliers allocate grinding capacity and certification investments across manufacturing footprints.
Japan
FANUC and Yaskawa maintain dual-source framework agreements with Nagoya-Tokyo corridor suppliers for six-axis robot joint actuators. METI enforces JIS standards specifying fatigue life testing protocols that filter qualified vendors. The Aichi Prefecture cluster concentrates captive needle bearing production and cycloid disc grinding expertise unavailable elsewhere.
China
MIIT dual carbon goals and GB energy efficiency standards are accelerating procurement preference windows for locally certified manufacturers. State-backed semiconductor fabrication equipment programs specify documented transmission efficiency testing above 90% rated load. Jiangsu and Zhejiang province suppliers dominate planetary reducer output for excavator swing drives and automated guided vehicle modules.
Germany
Automotive tier-one suppliers consolidate reducer vendor bases to dual-source qualification models for European EV production line automation. CE marking under the EU Machinery Directive mandates documented reliability testing for system exports. Baden-Württemberg engineering clusters specialize in precision rotary table integration for machine tool OEMs.
South Korea
Hyundai Robotics and Doosan Robotics are expanding domestic sourcing of compact RV architectures for collaborative robot joints. MFDS medical device regulations indirectly specify actuator precision requirements for surgical robot imports. The Gyeonggi-Seoul corridor hosts system integrators qualifying reducer batches under revised ISO 9283 durability protocols.
United States
Tesla and Rivian are accelerating six-axis robot deployments on battery pack assembly lines requiring sub-arc-minute positioning repeatability. OSHA industrial robot safety guidelines reference reducer backlash specifications in system integration standards. Michigan and Texas automotive manufacturing corridors concentrate demand for qualified joint actuators serving EV production ramp schedules.
RV Gear Reducer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the RV gear reducer landscape. Captive control over needle bearing supply and cycloid disc grinding capability separates the upper tier from assemblers dependent on outsourced precision components. Three archetypes dominate: Japanese precision specialists with backward-integrated bearing production, Chinese scale players leveraging domestic supply chain density, and European engineering-focused suppliers serving machine tool OEMs. Competitive moves concentrate on capacity expansion in high-torque compact architectures and strategic partnerships for integrated motor-reducer units.
Among Japanese precision manufacturers, Nabtesco and Harmonic Drive Systems exemplify the integrated archetype through in-house production of critical subcomponents. Zhejiang Shuanghuan Driveline occupies a position within the Chinese scale-driven tier, representing how domestic supply chain proximity enables cost positioning in planetary reducer variants. These three anchors illustrate how geographic clustering around distinct regulatory regimes—METI JIS certification, MIIT GB standards, and EU Machinery Directive CE marking—shapes viable competitive strategies without permitting cross-tier mobility.
| Leading Market Players |
|---|
| Nabtesco |
| Harmonic Drive Systems |
| Sumitomo Drive Technologies |
| SPINEA |
| Zhejiang Shuanghuan Driveline |
| Ningbo Zhongda Leader |
| Hengfengtai |
| Nantong Zhenkang |
| Leaderdrive |
| Others |
Pricing and Supply Chain Analysis
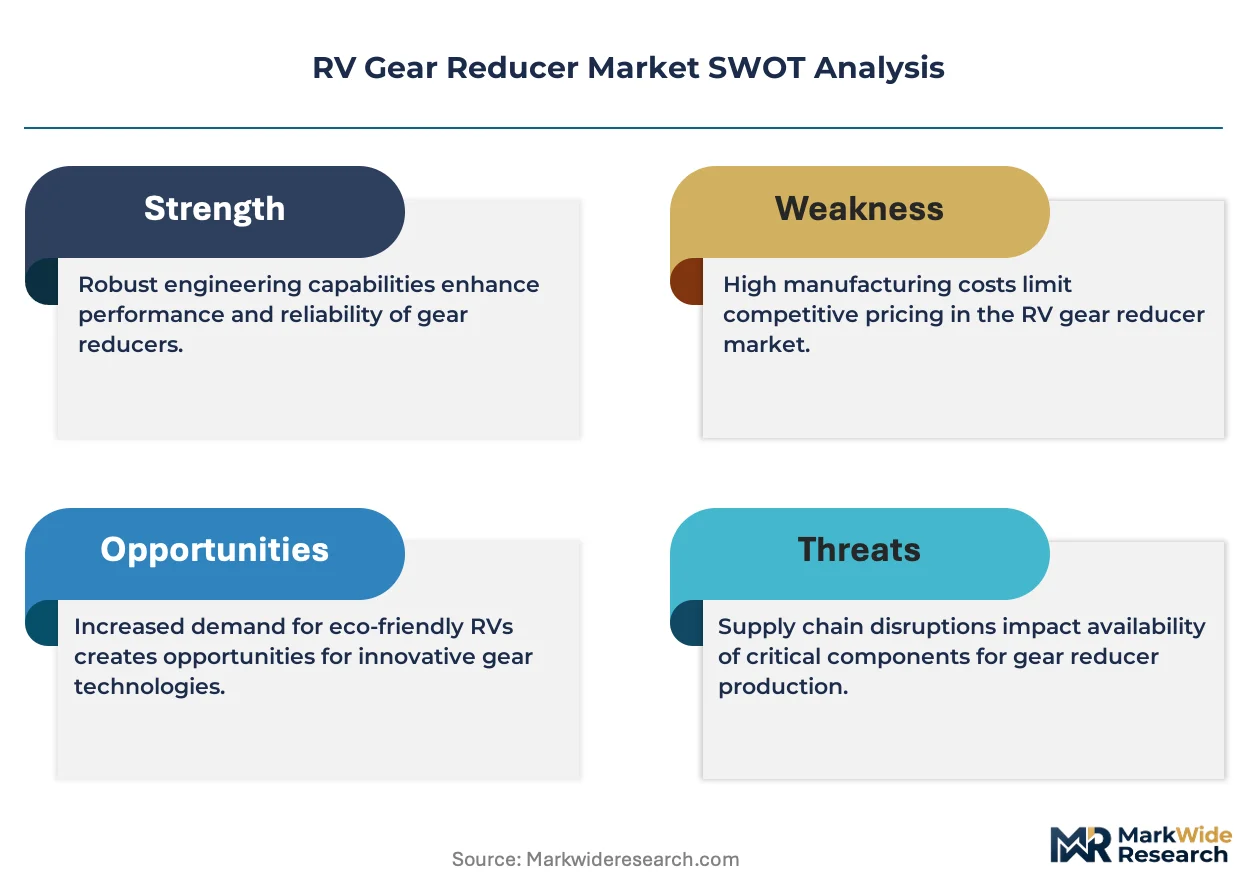
Needle bearing substitution by ceramic rolling elements is fragmenting supplier geography while compressing premium pricing tiers as Japanese captive producers face Chinese ceramic sintering scale. This materials transition simultaneously erodes traditional margin strongholds and opens procurement windows for MIIT-certified domestic manufacturers.
Pricing Analysis
Aftermarket parts and service contracts generate lifetime value multiples exceeding original equipment sales for precision cycloidal units. Pricing stratifies across METI JIS-certified premium tiers, GB-compliant domestic standard tiers, and uncertified economy planetary variants for construction equipment. Cost compression in standard tiers intensifies as Zhejiang manufacturers exploit localized heat treatment capacity. Automotive OEMs exhibit lowest price sensitivity due to qualification switching costs, while aftermarket distributors face margin erosion from gray-market imports.
Supply Chain Analysis
Aichi Prefecture needle roller grinding capacity anchors global precision reducer output, with supply risk concentrated in single-source Japanese bearing specialists. Raw material flows draw from Swedish specialty steel, Chinese rare-earth magnet feedstock for integrated motor units, and German CNC grinding machine tool providers. Tariff exposure on precision ground components threatens margin structures for European automotive tier-one suppliers. Distribution runs through captive OEM supply agreements for precision tiers and regional distributor networks for construction equipment aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated motor-reducer platform economics are displacing component sourcing as FANUC and Yaskawa consolidate vendor bases around interoperability-certified suppliers.
For Market Incumbents: Shield cycloid disc grinding expertise through captive machinist training pipelines against Chinese planetary scale entrants. Deepen backward integration into ceramic bearing supply as substitution accelerates. Prioritize METI JIS certification maintenance against pending ISO 9283 durability metric revisions. For New Entrants and Emerging Players: Differentiate on hollow-shaft compact architectures for mobile manipulator arms where torque density requirements outpace incumbent product roadmaps. Target warehouse logistics OEMs in China's Yangtze River Delta with GB-certified integrated units. Pursue joint development agreements with autonomous mobile robot platform developers. For Investors and Strategic Acquirers: The market sits at a vendor consolidation phase that favors precision grinding capability holders over assembly-only operators. Five-to-ten year viability hinges on cycloid disc profile expertise scarcity. Monitor MIIT dual carbon procurement preference window closures as inflection signals for Chinese domestic supplier valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Cycloid Disc Grinding Capacity Expansion | Aichi Prefecture clusters secure needle bearing supply chains for FANUC joint actuator demand. |
| Integrated Motor-Reducer Joint Development | Hollow-shaft designs capture collaborative robot specifications from Yaskawa and KUKA. |
| GB Standards Certification Investment | MIIT dual carbon compliance unlocks state-backed semiconductor equipment procurement. |
| Ceramic Bearing Backward Integration | Chinese ceramic sintering scale threatens Japanese steel roller premium positioning. |
| Automotive Tier-One Dual-Source Qualification | Long-term framework agreements with Tesla and Rivian reduce spot purchasing volatility. |
Research Methodology
Cross-validation between OEM procurement director interviews and customs trade data anchors the qualitative findings on supply chain concentration. Primary fieldwork engaged robot joint design engineers, aftermarket service heads at industrial distributors, METI standards committee participants, and MIIT certification auditors. Secondary sources include JIS fatigue life testing protocols, GB energy efficiency filings, SEC 10-K disclosures from precision component suppliers, and EU Machinery Directive CE marking databases. Bottom-up unit shipment estimates triangulate against top-down automotive robot deployment projections.
Sensitivity analysis around MIIT procurement preference duration and ISO 9283 revision timing frames projection uncertainty. The analytical framework segments by product architecture, installation configuration, end-user procurement authority, and application torque precision requirements across the modeling period. CAGRs derive from regression against automotive EV line automation capital expenditure trajectories and collaborative robot joint shipment curves. Forecast inputs incorporate needle bearing supply elasticity and cycloid disc grinding capacity utilization by geography.
The analysis sits within stated boundaries; outcomes outside sustained automotive electrification investment and dual carbon regulatory enforcement would require recalibration. Forecasts reflect assumptions on Japanese captive supply continuity and Chinese domestic certification pathway stability. Revision becomes warranted when ceramic bearing substitution rates cross 15% threshold in precision applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Suspension System Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Composite Leaf Springs Market
Automotive Parts
Tire Mold Market
Automotive Parts
Air Filter for Automotive Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
France Automotive Lubricants Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Electric Brake Booster Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
Hydraulic Lash Adjuster Market