
 North America Multi Camera Vision Inspection Systems Market | 2026-2036
North America Multi Camera Vision Inspection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Multi Camera Vision Inspection Systems Market Insights
The direct-to-factory distribution channel is reconfiguring as OEMs bypass traditional integrators for embedded vision partnerships. Cognex Corporation leverages its North American manufacturing footprint to sustain same-week delivery commitments for automotive clients. Keyence Corporation anchors its position through intensive application engineering support at major electronics clusters. Teledyne Technologies competes via specialized high-resolution arrays for pharmaceutical packaging lines.
Multi camera vision inspection systems deploy synchronized image sensors with sub-pixel calibration to capture multiple angles of moving parts at production-line speeds, primarily enabling automated defect detection and dimensional verification in continuous manufacturing environments. 3D systems command premium positioning where depth-critical assemblies such as EV battery modules require volumetric tolerance checks, while smart cameras occupy cost-sensitive tiers in food and beverage packaging halls. Machine learning integration is displacing rule-based algorithms in electronics quality assurance, creating fresh R&D investment cycles among semiconductor fabricators.
FDA quality system regulations and NHTSA traceability requirements shape product roadmaps by mandating auditable inspection records and deterministic failure thresholds across automotive and pharmaceutical output. The EPA's industrial emissions frameworks indirectly influence system design by pressuring manufacturers to reduce rework waste through tighter first-pass inspection accuracy. Stakeholders must weigh the capital trade-offs between retrofitting legacy 2D lines against greenfield 3D deployments as contract specifications tighten across regulated end markets.
Market Dynamics
The transition from rule-based inspection algorithms to machine learning architectures is compressing system refresh cycles across automotive and pharmaceutical production lines. Equipment buyers now face capital allocation decisions between retrofitting existing 2D arrays and deploying greenfield 3D volumetric stations.
Growth Catalysts
- NHTSA Traceability Mandates:Automotive component serialization requirements are forcing tier-one suppliers to upgrade inspection infrastructure for complete production genealogy capture.
- EV Battery Assembly Complexity:Lithium-ion module stacking tolerances below 50 microns demand synchronized multi-camera arrays for real-time volumetric verification.
- FDA Quality System Regulation Updates:Pharmaceutical manufacturers must maintain auditable inspection records with deterministic failure thresholds, accelerating system replacement timelines.
Market Restraints
- Specialized Optics Supply Concentration:High-resolution sensor arrays depend on concentrated Japanese and German component suppliers, creating input vulnerability.
- Technical Integration Complexity:Sub-pixel calibration across six-plus camera arrays requires proprietary software stacks that lock buyers into single-vendor ecosystems.
- Capital Intensity Barriers:Full 3D deployment costs exceed 2D retrofits by factors of three to four, freezing mid-tier contract manufacturers at legacy capability levels.
Strategic Opportunities
- Canadian Pharmaceutical Corridor:Ontario's expanding generic drug manufacturing base remains underpenetrated by 3D inspection relative to Michigan and Ohio automotive clusters.
- Machine Learning Edge Deployment:On-camera inference chips from semiconductor fabricators enable real-time defect classification without centralized server dependency.
- Direct OEM Partnership Channels:Embedded vision collaborations with automotive and electronics manufacturers bypass traditional systems integrator markups.
Industry Challenges
- Multi-Disciplinary Talent Scarcity:Deployment teams require simultaneous expertise in optical physics, industrial networking, and Python-based model training pipelines.
- Legacy Line Integration Friction:Brownfield automotive plants in Michigan and Ohio operate 1990s-era PLCs that lack deterministic timing protocols for camera synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Multi Camera Vision Inspection Systems Market |
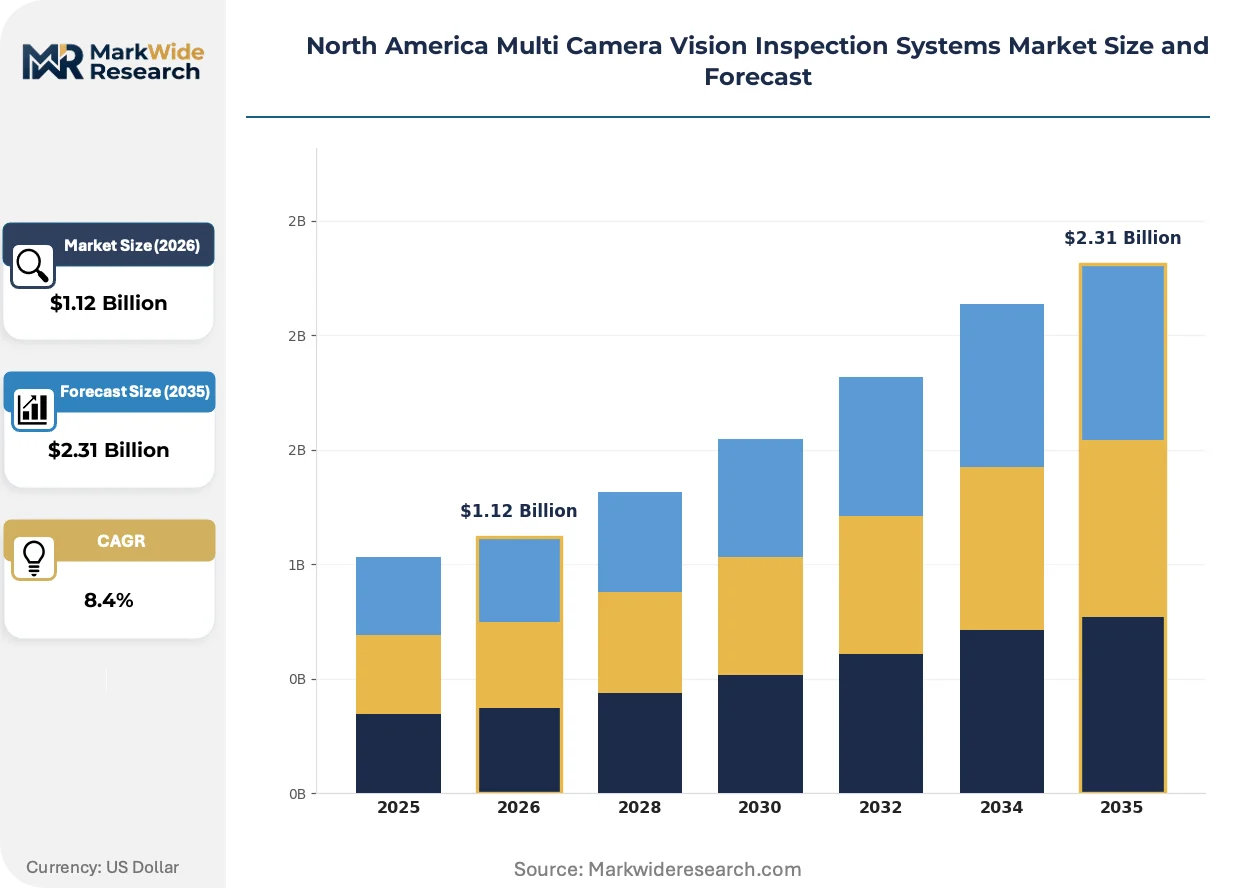
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Cameras, 2D Systems, 3D Systems, Modular Systems Industry Vertical: Automotive Manufacturing, Pharmaceuticals, Electronics, Food & Beverage Technology: Machine Learning, Image Processing, Optical Character Recognition, Image Acquisition Application: Quality Assurance, Defect Detection, Packaging Inspection, Assembly Verification |
| Companies Covered | Cognex Corporation, Keyence Corporation, Teledyne Technologies, Basler AG, Omron Corporation, National Instruments Corporation, Zebra Technologies, Datalogic S.p.A, Teledyne DALSA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Multi Camera Vision Inspection Systems Market Trends and Innovations
Inspection architectures are fragmenting into two competing design philosophies: centralized server farms processing high-resolution streams versus distributed edge inference on smart camera arrays. This technical divergence is reshaping vendor R&D priorities and buyer procurement criteria across the continent.
Deep learning defect classification is hybridizing traditional computer vision pipelines with neural network inference layers. Semiconductor fabricators in California and Texas are adopting these architectures for die-level crack detection at wafer throughput speeds. The technology is compressing the competitive gap between specialized machine vision vendors and general-purpose industrial AI platforms.
The EPA's industrial emissions frameworks are indirectly mandating tighter first-pass inspection accuracy to minimize rework waste and scrap generation. Pharmaceutical packaging lines in New Jersey and Illinois face heightened scrutiny on dimensional tolerances for blister packs and label alignment. Manufacturers are responding with redundant camera arrays and statistical process control integration.
Buyer procurement patterns are consolidating around application engineering intensity rather than hardware specifications alone. Electronics clusters in Guadalajara and Silicon Valley now demand same-week technical support availability as a contractual precondition. This behavioral shift favors vendors with regional service footprints over price-competitive offshore alternatives.
North America Multi Camera Vision Inspection Systems Market Segmentation
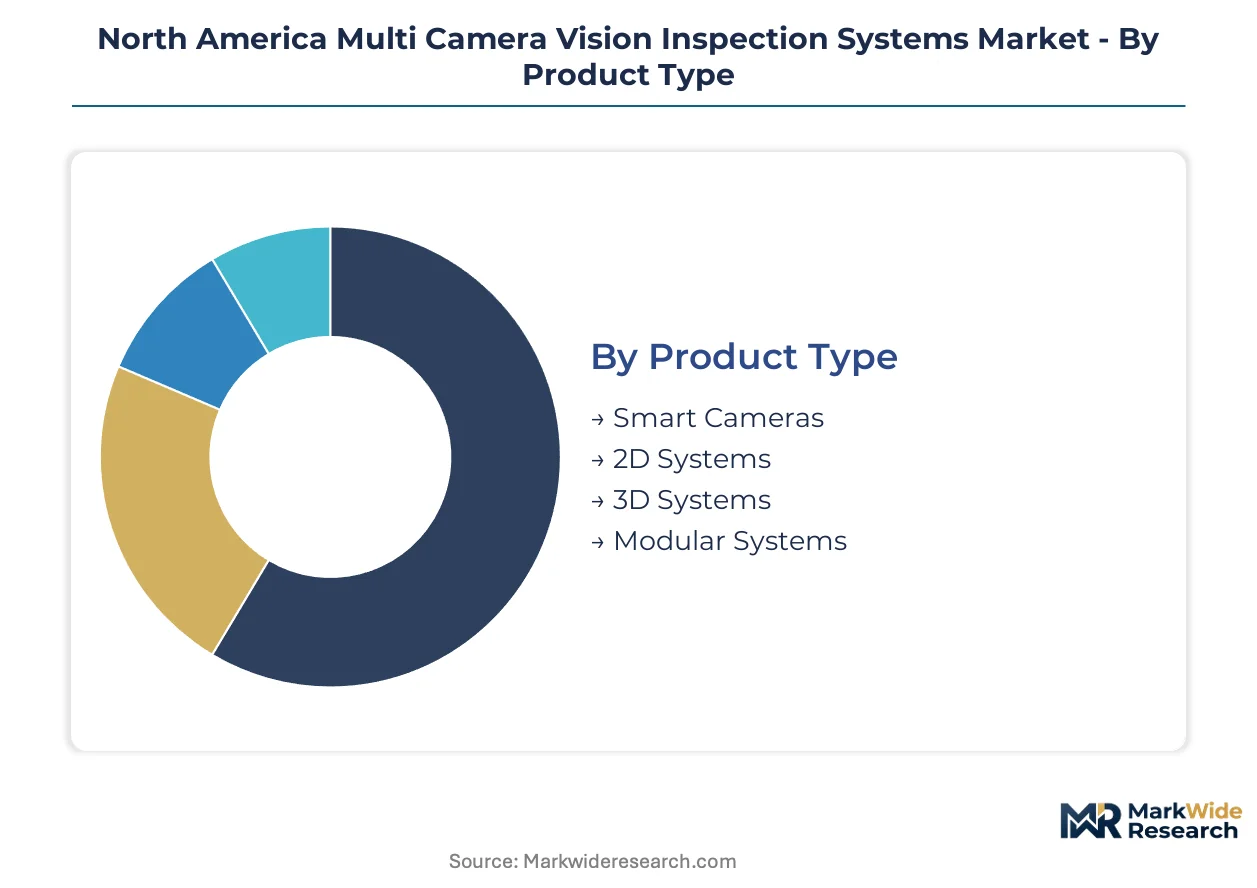
Multi camera vision inspection systems fragment across four critical dimensions that determine procurement priorities and vendor positioning. Product type governs capital deployment scale, while industry vertical dictates regulatory compliance intensity. Technology selection separates rule-based legacy installations from machine learning architectures, and application focus shapes integration complexity with existing production lines.
Product Type:
After-sales-service intensity varies dramatically across hardware tiers, with 3D volumetric stations demanding dedicated field engineering while smart cameras rely on remote diagnostics.
- 3D Systems:Volumetric inspection arrays employ synchronized stereo vision with sub-pixel calibration for depth-critical assemblies. EV battery module stacking in Michigan and Ohio requires real-time tolerance verification below 50 microns, driving premium positioning and extended warranty negotiations.
- Smart Cameras:Embedded processing units integrate lens, sensor, and inference engine in compact housings for high-volume deployments. Food and beverage packaging halls in Wisconsin and Pennsylvania prioritize these units for cost-sensitive label verification and fill-level checks.
- 2D Systems:Planar inspection configurations dominate legacy automotive paint and surface defect lines across Ontario assembly plants.
- Modular Systems:Reconfigurable camera arrays allow tier-one suppliers to adapt inspection stations across multiple vehicle platforms without complete replacement.
3D systems hold the largest share; momentum sits with smart cameras.
Industry Vertical:
Cost tier stratification separates pharmaceutical validation protocols from automotive throughput requirements, with electronics fabrication occupying a middle band of precision-versus-volume trade-offs.
- Automotive Manufacturing:NHTSA traceability mandates enforce component serialization with deterministic failure thresholds across powertrain and battery assembly. Michigan, Ohio, and Ontario facilities account for concentrated demand as domestic EV production scales.
- Pharmaceuticals:FDA quality system regulations require auditable inspection records with statistical process control integration. New Jersey and Illinois packaging lines face heightened dimensional scrutiny on blister packs and vial labeling.
- Electronics:Semiconductor fabricators in California and Texas deploy die-level crack detection at wafer throughput speeds.
- Food & Beverage:USDA and FDA dual oversight drives label alignment and contaminant detection across high-speed bottling operations.
Automotive manufacturing commands the largest installed base; pharmaceuticals is expanding most quickly.
Technology:
Application maturity separates proven image acquisition pipelines from emerging machine learning architectures that compress competitive differentiation.
- Machine Learning:Neural network inference layers hybridize with traditional computer vision for adaptive defect classification without explicit rule programming. California semiconductor fabricators and Michigan battery plants are displacing static algorithms with training pipelines that improve through production exposure.
- Image Processing:Established filtering, edge detection, and geometric analysis routines remain dominant in pharmaceutical packaging where deterministic thresholds satisfy FDA documentation requirements.
- Optical Character Recognition:Character decoding algorithms verify serialization codes and expiration dates at line speeds exceeding 500 units per minute.
- Image Acquisition:Sensor synchronization and lighting control foundations underpin all downstream analysis regardless of intelligence layer.
Image processing retains the largest share; machine learning is gaining share fastest.
Application:
Customer type bifurcation separates OEMs with embedded vision partnerships from contract manufacturers dependent on systems integrator channels.
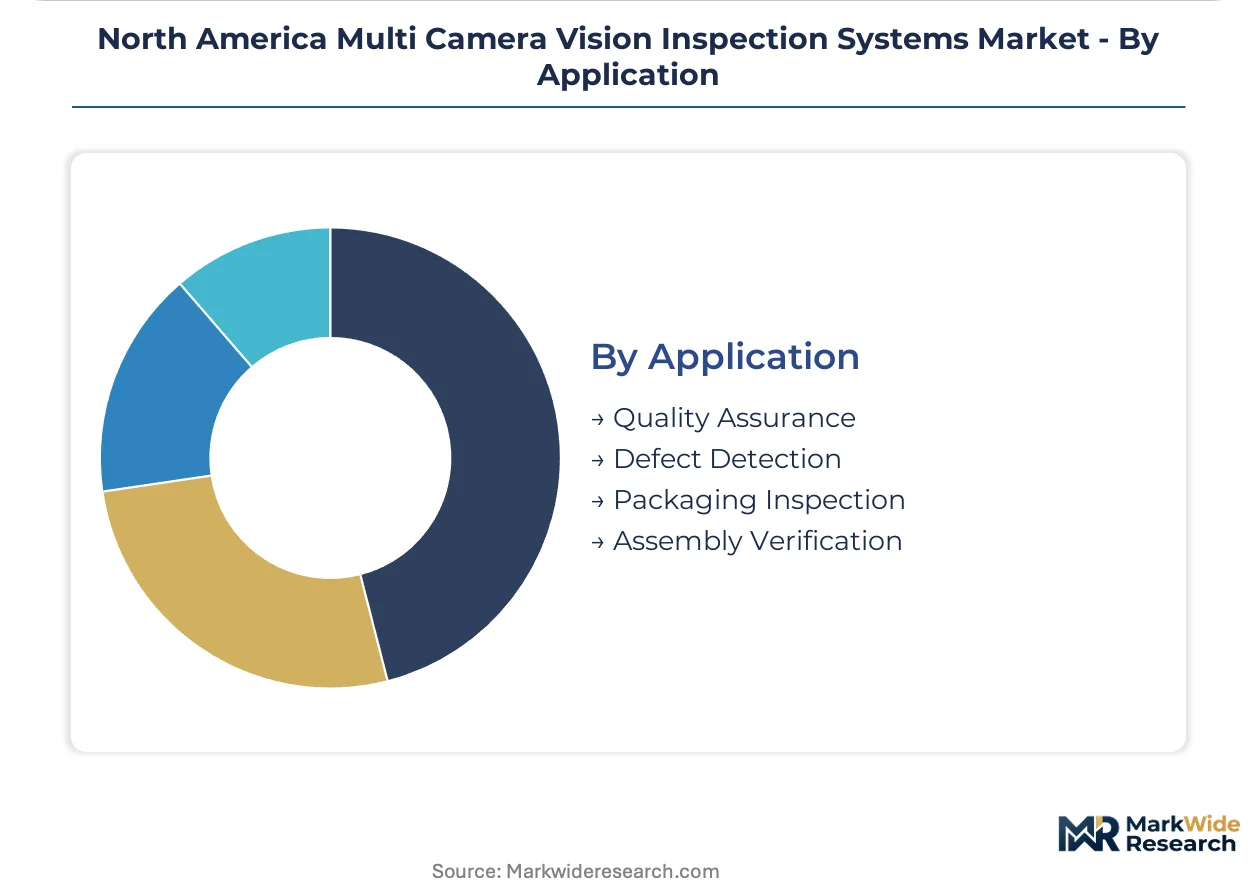
- Quality Assurance:Comprehensive inspection protocols span dimensional verification, surface analysis, and documentation generation for regulatory submission. Pharmaceutical manufacturers in New Jersey and Illinois treat these systems as quality system infrastructure rather than discretionary equipment.
- Defect Detection:Real-time flaw identification with immediate reject actuation minimizes downstream contamination in food processing and electronics assembly. Michigan automotive stamping operations deploy redundant camera arrays to prevent escaped defects from reaching welding stations.
- Packaging Inspection:Label alignment, print quality, and seal integrity verification operate at throughput speeds matching filling equipment.
- Assembly Verification:Presence-absence and correct-sequence confirmation ensures component completion before station handoff.
Quality assurance holds the largest share; assembly verification is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA traceability mandates and FDA quality system updates are reshaping inspection infrastructure investments across North America. Federal regulatory pressure combines with state-level manufacturing incentives to concentrate demand in specific industrial corridors. The analysis examines three national markets where multi-camera vision deployment patterns diverge by end-use vertical and supply chain maturity.
United States
Michigan and Ohio automotive clusters drive EV battery assembly verification demand with sub-50-micron tolerance requirements. NHTSA component serialization rules force tier-one suppliers to upgrade legacy 2D lines for complete production genealogy capture. California and Texas semiconductor fabricators deploy die-level crack detection at wafer throughput speeds using machine learning hybrid architectures.
Canada
Ontario's expanding generic drug manufacturing base remains underpenetrated by 3D inspection relative to US automotive clusters. Health Canada pharmaceutical quality guidelines align with FDA audit trail requirements, accelerating system replacement timelines in Toronto-area packaging facilities. The Great Lakes industrial corridor spanning Ontario, Michigan, and Ohio concentrates cross-border supply chain integration for automotive vision deployment.
Mexico
Nuevo León and Bajío Region electronics assembly plants serve as nearshore alternatives to Asian supply chains for US OEMs. Mexican automotive component exports to Michigan and Ohio require NHTSA-compliant inspection documentation at origin. Guadalajara electronics clusters demand same-week technical support availability as a contractual precondition, favoring vendors with regional service footprints.
North America Multi Camera Vision Inspection Systems Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Specialized machine vision vendors compete against diversified industrial automation conglomerates and emerging AI-native platforms. The competitive landscape fragments across embedded vision partnerships, application engineering intensity, and high-resolution optical specialization. Dominant competitive moves include direct OEM collaboration channels that bypass traditional systems integrators and strategic R&D investments in edge inference chip integration.
Within the specialized vision tier, Cognex Corporation, Keyence Corporation, and Teledyne Technologies occupy positions defined by regional service density and optical engineering depth. Cognex leverages its North American manufacturing footprint to sustain same-week delivery commitments for automotive clients in Michigan and Ohio. Keyence anchors its position through intensive application engineering support at major electronics clusters. Teledyne competes via specialized high-resolution arrays for pharmaceutical packaging lines in New Jersey and Illinois. These three represent the archetype spectrum from embedded vision partnership models to high-precision optical specialization.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| Teledyne Technologies |
| Basler AG |
| Omron Corporation |
| National Instruments Corporation |
| Zebra Technologies |
| Datalogic S.p.A |
| Teledyne DALSA |
| Others |
Pricing and Supply Chain Analysis
The Great Lakes industrial corridor spanning Ontario, Michigan, and Ohio concentrates multi-camera vision system manufacturing capacity, granting regional OEMs significant leverage over pricing negotiations with tier-two component suppliers. This geographic clustering of automotive and pharmaceutical demand creates asymmetric power dynamics where buyers extract volume discounts while specialized optics vendors maintain premium positioning through technical differentiation.
Pricing Analysis
Certification level creates the primary spread between FDA-grade pharmaceutical validation systems and standard industrial inspection arrays. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales service intensity, with 3D volumetric stations commanding extended field engineering bundles. Cost compression in the smart camera tier intensifies as semiconductor fabricators integrate inference chips directly into sensor modules. Contract manufacturers in Guadalajara exhibit highest price sensitivity, while Michigan automotive OEMs prioritize same-week delivery reliability over unit cost.
Supply Chain Analysis
Export control restrictions on high-resolution sensor arrays and specialized optical components limit flows from Japanese and German suppliers to North American integrators. Component sourcing draws from concentrated sensor fabrication in Japan, precision optics manufacturing in Germany, and edge inference chip production in Taiwan. Single-source vulnerability pervades the sub-pixel calibration software layer, where proprietary stacks tether buyers to specific vendor ecosystems. Distribution runs through direct OEM partnerships that displace traditional systems integrator channels across automotive and electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Michigan and Ohio automotive OEMs consolidate embedded vision partnerships, squeezing margin capture from mid-tier systems integrators. This consolidation forces vendors to choose between scale commitments through direct collaboration or niche specialization in regulatory-intensive pharmaceutical validation.
For Market Incumbents: Harden defensive moats by deepening backward integration into edge inference chip design and expanding application engineering density in the Canadian pharmaceutical corridor. Machine learning-native platforms threaten rule-based algorithm revenue streams; incumbents must accelerate on-camera inference deployment to prevent displacement. Certification investment in FDA-grade validation protocols preserves premium positioning against cost-competitive challengers.
For New Entrants and Emerging Players: Ontario's underpenetrated generic drug manufacturing base offers accessible white space relative to saturated Michigan automotive clusters. New entrants should target mid-tier contract manufacturers frozen at legacy 2D capability levels by capital intensity barriers, offering modular upgrade paths rather than greenfield 3D displacement. A machine learning-first go-to-market angle, emphasizing adaptive defect classification without explicit rule programming, differentiates against entrenched image processing incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because NHTSA and FDA mandates perpetuate replacement cycles regardless of macroeconomic pressure. Acquisition targets should display vertical integration into optical component sourcing or captive software stacks that lock in recurring service revenue. The signal to watch is EPA enforcement intensity on industrial emissions, which accelerates first-pass accuracy investments and expands addressable market for premium inspection arrays.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Inference Chip Integration | On-camera neural processing eliminates server dependency for Michigan battery plant real-time verification. |
| Direct OEM Partnership Channel | Embedded vision collaborations with automotive manufacturers bypass traditional integrator markups entirely. |
| Application Engineering Expansion | Same-week technical support availability in Guadalajara electronics clusters satisfies contractual preconditions. |
| Modular System Architecture | Reconfigurable arrays allow tier-one suppliers to adapt stations across multiple vehicle platforms. |
| Machine Learning Pipeline Development | Adaptive defect classification displaces static algorithms in California semiconductor wafer inspection. |
Research Methodology
A standing panel of automotive platform engineers, pharmaceutical quality directors, semiconductor fabrication managers, and vision systems procurement leads provided ongoing calibration across the study period. Primary interviews with tier-one supplier technical teams and OEM embedded vision program offices combined with secondary validation from NHTSA regulatory filings, FDA quality system guidance documents, SEC equipment vendor disclosures, and automotive production databases. Bottom-up segmentation modeling triangulated against top-down industry association estimates to constrain variance.
Scenario bracketing anchored projections across base, accelerated, and constrained regulatory enforcement cases without specifying discrete year markers. Segmentation dimensions modeled include product type hierarchy, industry vertical compliance intensity, technology architecture maturity, and application integration complexity. CAGRs derived from fitted growth curves applied to validated installed base estimates, with EV battery assembly verification throughput and pharmaceutical serialization mandate timelines as primary demand inputs across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-native platform entrants or accelerated EPA emissions enforcement would shift outcomes. Material shifts in NHTSA traceability implementation timelines or FDA quality system audit intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Europe Industrial Computed Tomography Market
Imaging
Whole Slide Imaging Systems Market
Imaging
Global Computed Radiography Market
Imaging
SDI Camera Market
Imaging
Handheld Retinal Scanners Market
Imaging
Global Digital Binoculars Market
Imaging
Camera Technology Market
Imaging
Low-Light Imaging Market
Imaging
Chemical Imaging Systems Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Digital Camera Market
Imaging
US Near Infrared Imaging Market
Imaging
Chemiluminescence Imaging Market
Imaging
Photoconductor Drums Market
Imaging
Automotive 3D Imaging Market
Imaging
Photography Ring Flash Market