
 Weatherproof Camera Market | 2026-2036
Weatherproof Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Weatherproof Camera Market Outlook
Online retail is reshaping how weatherproof cameras reach end users, with direct-to-consumer platforms and specialized e-commerce marketplaces displacing traditional distributor networks. FLIR Systems, Inc. leverages its thermal imaging heritage to dominate defense and industrial segments with hardened sensor packages. Panasonic i-PRO Sensing Solutions Co., Ltd. anchors professional surveillance channels through integrated video management platforms. Bosch Sicherheitssysteme GmbH competes on manufacturing scale, sustaining cost advantages across European and North American project deployments.
A weatherproof camera encloses optical and electronic components within sealed housings rated to IP66, IP67, or IP68 ingress protection standards, with operating temperature ranges typically spanning -40°C to 60°C and corrosion-resistant alloys or polycarbonate construction; these devices capture continuous or triggered imagery in rain, dust, salt spray, and extreme thermal conditions for security monitoring, wildlife observation, and industrial inspection. Wireless technology leads product development cycles as cellular and mesh networking protocols displace coaxial cabling in remote installations. Surveillance cameras command the largest revenue pool among product types, though action cameras represent the fastest-expanding segment as content creators and outdoor enthusiasts demand professional-grade durability.
FCC certification governs wireless transmission protocols for US-deployed units, while CE marking and RoHS compliance govern European market access with restricted substance thresholds and electromagnetic compatibility testing. The EU AI Act introduces new conformity requirements for cameras incorporating facial recognition or behavioral analytics, reshaping product roadmaps for algorithm-enabled devices. Stakeholders must monitor evolving cybersecurity mandates for connected imaging devices, as NIST frameworks and national critical infrastructure standards harden data protection requirements across government and utility procurement channels.
Market Dynamics
Wireless protocol migration and hardened edge-computing architectures are compressing installation timelines while expanding addressable use cases beyond traditional surveillance into predictive maintenance and environmental monitoring.
Growth Catalysts
- EU AI Act compliance:Mandatory conformity assessments for facial recognition-enabled cameras are accelerating procurement of certified hardware among European municipal security departments ahead of enforcement deadlines.
- Cellular mesh networking:Low-power wide-area protocols eliminate trenching and coaxial runs, enabling rapid deployment across remote utility substations and agricultural perimeters previously unreachable by cabled infrastructure.
- Federal infrastructure spending:US Department of Transportation bridge and tunnel rehabilitation programs specify weather-resistant video inspection systems for structural health monitoring.
Market Restraints
- Semiconductor supply concentration:Specialized image sensor foundry capacity clusters in Taiwan and South Korea, exposing procurement pipelines to geopolitical disruption and allocation rationing.
- REACH substance restrictions:European chemicals regulation limits specific flame retardants and stabilizers used in polycarbonate housings, forcing reformulation cycles that extend qualification timelines.
- Optical glass thermal limitations:Standard borosilicate lenses experience focal drift below -30°C, constraining reliable operation in Arctic and high-altitude installations without costly exotic material substitutions.
Strategic Opportunities
- India smart city mandates:Ministry of Housing and Urban Affairs funding for Safe City projects creates procurement pipelines for IP-rated surveillance across tier-2 municipal corporations with limited incumbent vendor relationships.
- On-device AI inference:Convergence of neural processing units with thermal sensors enables real-time anomaly detection at the edge, reducing bandwidth costs for oil and gas pipeline operators.
- Direct-to-installer platforms:Specialized e-commerce marketplaces bypass traditional distributor markups, capturing margin from electrical contractors and systems integrators in fragmented European markets.
Industry Challenges
- NIST cybersecurity framework alignment:Federal and utility procurement channels now mandate encrypted firmware and secure boot protocols, requiring engineering resources that strain mid-tier hardware vendors.
- Multi-protocol integration complexity:ONVIF, RTSP, and proprietary cloud APIs demand specialized software engineering talent scarce among traditional metal-bending enclosure manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weatherproof Camera Market |
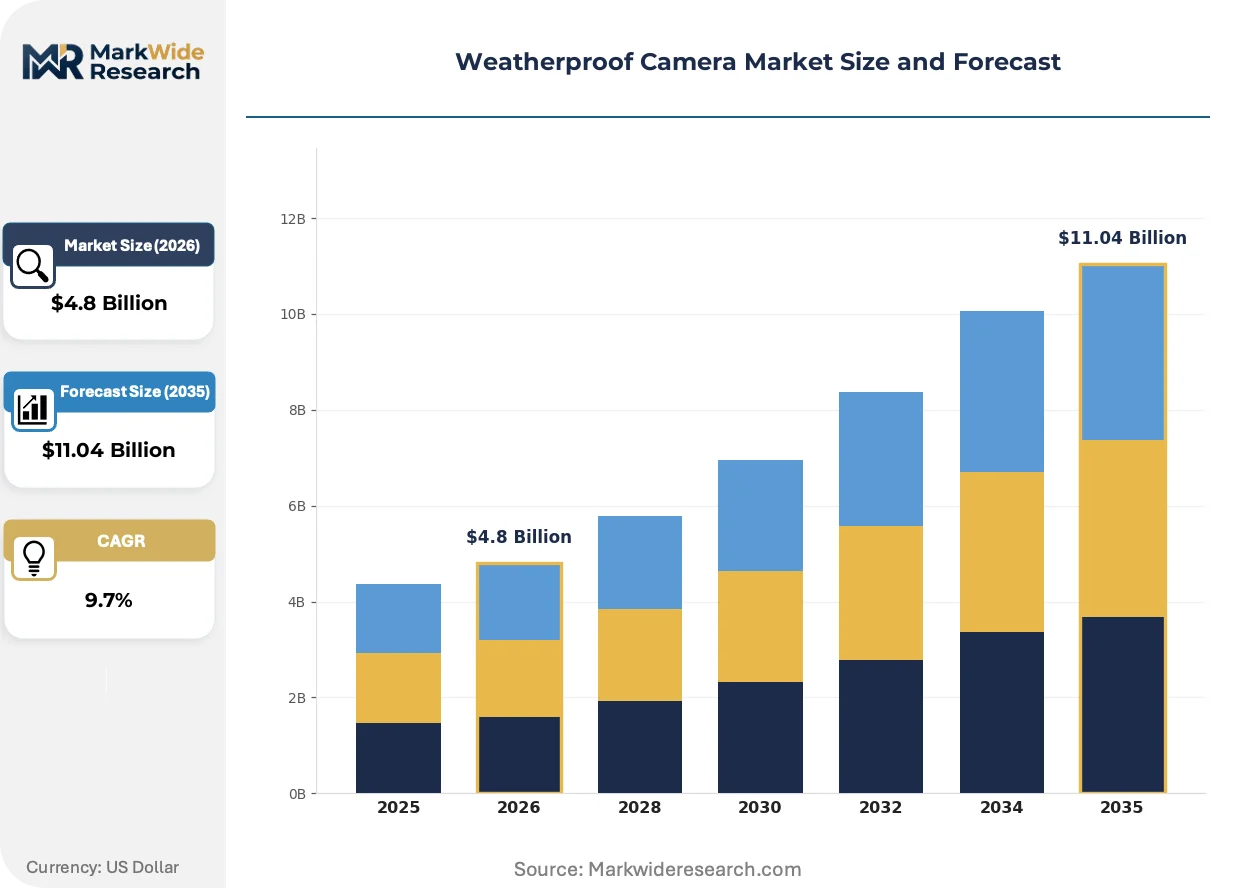
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Action Cameras, Outdoor Cameras, Surveillance Cameras, Trail Cameras Technology: Digital, Analog, Hybrid, Wireless End User: Residential, Commercial, Military, Industrial Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Wholesale |
| Companies Covered | Arlo, Honeywell International Inc., FLIR Systems, Inc., Vicon Motion Systems Ltd, Bosch Sicherheitssysteme GmbH, Panasonic i-PRO Sensing Solutions Co., Ltd., Pelco Corporations, Canon, GoPro, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weatherproof Camera Market Strategic Shifts
Edge-native processing architectures and solid-state thermal management are eliminating mechanical failure modes while enabling continuous operation in previously inaccessible environments. These shifts compress total cost of ownership curves and expand serviceable addressable markets.
Silicon-carbide power management integrated circuits now regulate voltage and thermal loads within camera housings without electrolytic capacitors. Solar-powered traffic monitoring deployments in Arizona and Nevada are adopting these packages for decade-long maintenance-free operation. This semiconductor transition is rendering obsolete the five-year replacement cycles typical of aluminum-electrolytic-based outdoor electronics.
EU Ecodesign for Energy-related Products Directive imposes standby power limits and efficiency tiers on networked imaging equipment sold in member states. Manufacturers must redesign power supplies and sleep-state logic to meet tiered consumption thresholds. Professional surveillance channels face the steepest compliance costs, while consumer action camera segments absorb redesign expenses through volume amortization.
Content creator demand for broadcast-grade durability is collapsing the traditional boundary between professional surveillance and action camera procurement. YouTube production houses and documentary crews now specify IP67-rated units with interchangeable lenses, bypassing traditional security integrators. This behavioral shift concentrates in North American and Western European outdoor recreation corridors where influencer-driven equipment choices accelerate product category convergence.
Weatherproof Camera Market Segmentation
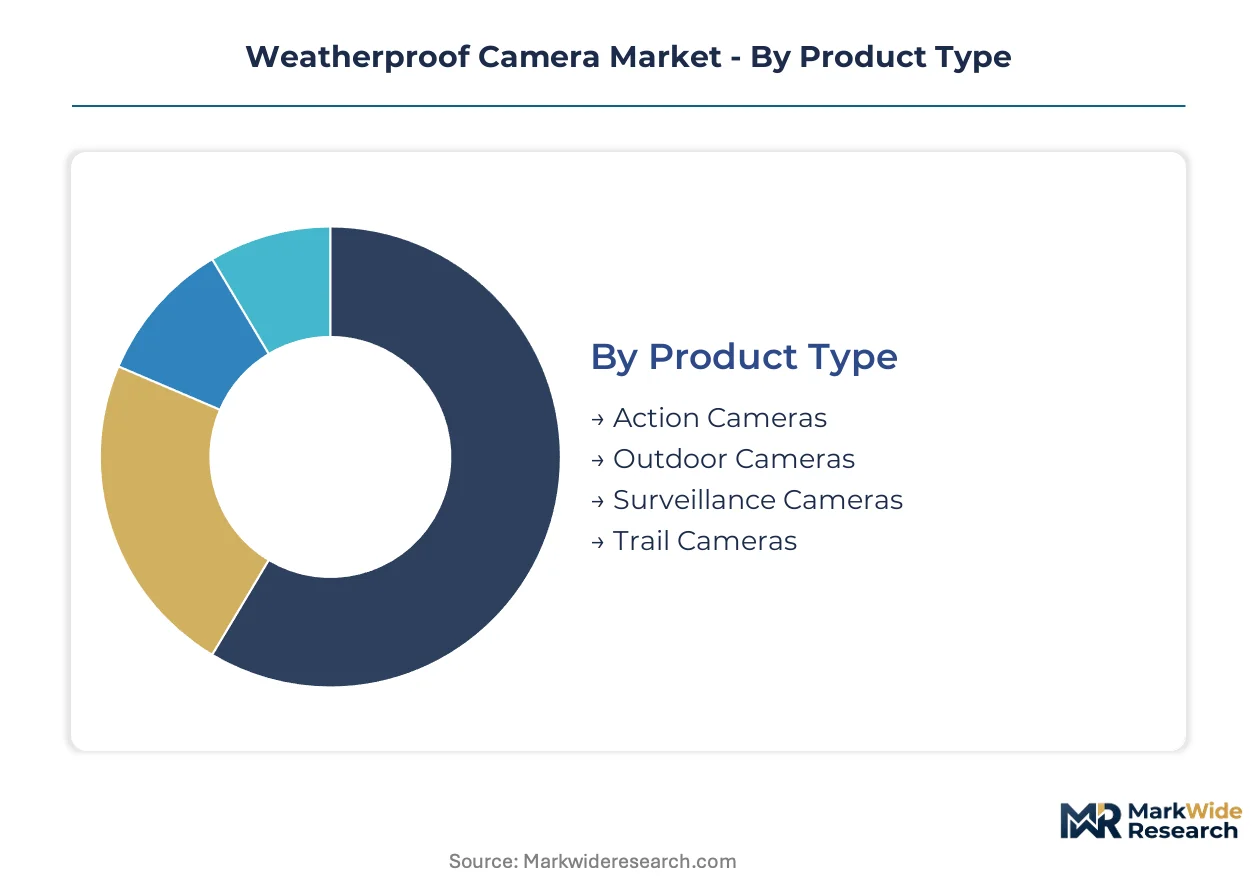
Weatherproof camera procurement patterns diverge sharply across use cases, with defense agencies prioritizing thermal resilience while content creators drive volume in action-oriented form factors. Understanding these segment boundaries clarifies where engineering investments and channel strategies concentrate.
Product Type:
Physical form factor and environmental sealing specifications determine installation feasibility and replacement cycles across deployment environments.
- Surveillance Cameras:Fixed-mount housings with IP66-IP68 ratings and integrated heater elements sustain continuous operation in perimeter security applications. Municipal smart city deployments in the United States and utility substation monitoring specify these units for decade-long service intervals.
- Action Cameras:Compact, shock-resistant enclosures with interchangeable lens mounts attract professional content creators requiring broadcast-grade durability in remote locations. YouTube production houses and documentary crews in North American outdoor recreation corridors now specify these units, bypassing traditional security integrators entirely.
- Outdoor Cameras:General-purpose weather-sealed designs serve wildlife observation and recreational monitoring with moderate ingress protection tiers.
- Trail Cameras:Battery-optimized, motion-triggered units with camouflage housings target hunting and ecological research applications requiring extended unattended operation.
Surveillance cameras command the established base. The steepest expansion runs through action cameras.
Technology:
Signal processing architecture shapes power consumption, installation complexity, and integration compatibility with existing infrastructure.
- Wireless:Cellular mesh and low-power wide-area protocols eliminate trenching requirements, enabling rapid deployment across remote agricultural perimeters and utility substations previously unreachable by cabled infrastructure. FCC certification governs transmission protocols for US-deployed units.
- Digital:IP-based streaming with ONVIF compliance integrates with enterprise video management platforms. Professional surveillance channels in European Union member states face steep compliance costs under Ecodesign for Energy-related Products Directive efficiency tiers.
- Analog:Coaxial-based transmission persists in legacy infrastructure upgrades where complete system replacement is cost-prohibitive.
- Hybrid:Dual-path architectures bridge analog legacy and digital migration paths for phased facility upgrades.
Wireless platforms are climbing the fastest as cellular infrastructure densifies. Analog retains residual share in retrofit-heavy industrial corridors.
End User:
Procurement authority and specification authority sit with distinct stakeholder types across residential, institutional, and government contexts.
- Military:Ruggedized imaging equipment with hardened sensor packages supports perimeter security and reconnaissance missions. Procurement specifications mandate encrypted firmware and secure boot protocols aligned with NIST cybersecurity frameworks.
- Industrial:Predictive maintenance and pipeline monitoring applications demand edge-native processing with neural processing units for real-time anomaly detection. Oil and gas operators specify these units to reduce bandwidth costs in remote installations.
- Commercial:Retail, hospitality, and corporate security departments prioritize integrated video management platforms with behavioral analytics capabilities.
- Residential:Consumer-grade units with simplified installation protocols serve home security and wildlife observation through direct-to-consumer channels.
Military and industrial segments anchor premium pricing. Commercial channels absorb the highest unit volumes through project deployment scale.
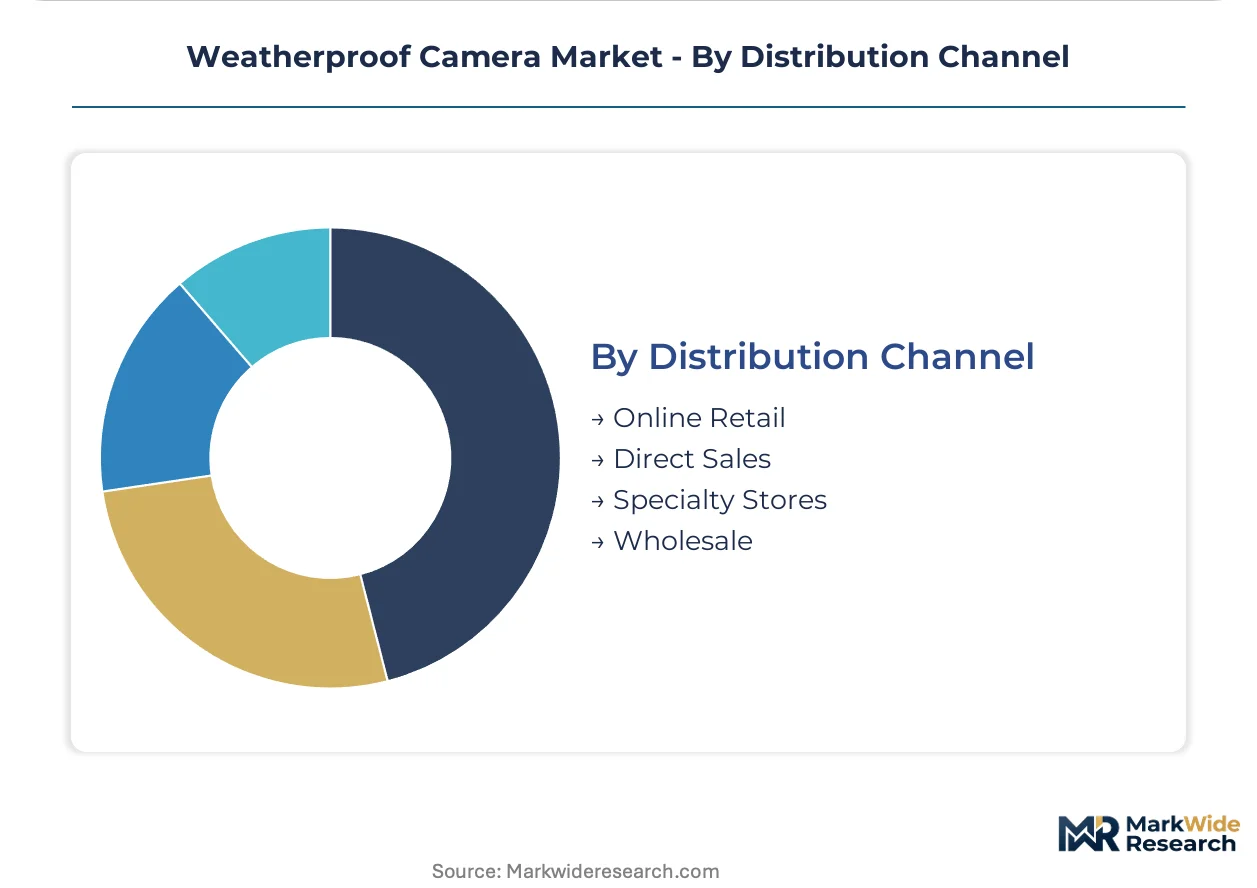
Distribution Channel:
Channel structure determines margin capture, technical support obligations, and customer relationship ownership.
- Online Retail:Direct-to-consumer platforms and specialized e-commerce marketplaces displace traditional distributor networks, capturing margin from electrical contractors and systems integrators. Fragmented European markets show particular susceptibility to this displacement.
- Direct Sales:Manufacturer-led engagement with municipal security departments and defense agencies supports complex specification and compliance documentation requirements.
- Specialty Stores:Regional security equipment dealers provide local installation support and maintenance services for mid-market commercial accounts.
- Wholesale:Distributor networks retain relevance in large-scale project deployments requiring inventory staging and credit terms.
Online retail is expanding most quickly in consumer and prosumer tiers. Direct sales defend position in defense and critical infrastructure procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC certification governs wireless transmission protocols for US-deployed units, anchoring the regulatory framework in the largest national market for weather-resistant surveillance systems.
United States
Federal infrastructure spending through Department of Transportation bridge and tunnel rehabilitation programs specifies weather-resistant video inspection systems for structural health monitoring. NIST cybersecurity frameworks mandate encrypted firmware and secure boot protocols for federal and utility procurement channels. Municipal smart city deployments in Arizona and Nevada accelerate adoption of solar-powered traffic monitoring systems.
Germany
Industrial predictive maintenance applications in the Ruhr industrial corridor and Bavarian manufacturing zones drive demand for edge-native processing cameras with neural processing units. EU AI Act conformity assessments for facial recognition-enabled cameras accelerate procurement among municipal security departments ahead of enforcement deadlines. Stuttgart and Munich anchor precision engineering clusters developing solid-state thermal management solutions.
China
Dual carbon goals under MIIT directives accelerate solar-powered remote monitoring installations across western provinces and agricultural perimeters. GB standards govern ingress protection ratings and electromagnetic compatibility for domestic and export-bound equipment. Shenzhen and Dongguan manufacturing clusters concentrate polycarbonate housing production and semiconductor packaging capacity.
India
Ministry of Housing and Urban Affairs funding for Safe City projects creates procurement pipelines for IP-rated surveillance across tier-2 municipal corporations with limited incumbent vendor relationships. BIS certification requirements for electronic goods tighten quality thresholds for imported and domestically manufactured units. Karnataka and Telangana smart city deployments in Bangalore and Hyderabad lead technical specification adoption.
Japan
METI efficiency standards and JIS ingress protection certifications shape product development for industrial inspection and wildlife observation applications. Edge-computing architectures for predictive maintenance gain traction among automotive and electronics manufacturers in the Chubu and Kansai industrial belts. Nagoya and Osaka manufacturing clusters specialize in precision optical glass and thermal-resistant lens assemblies.
Weatherproof Camera Market Competitive Environment
Defense-heritage thermal specialists and integrated surveillance platform providers split the market along application-specific vectors. The vendor base concentrates around three strategic archetypes: sensor-technology originators with military pedigree, diversified electronics conglomerates with video management integration capabilities, and action-camera pure-plays leveraging content creator demand. Competitive moves center on wireless protocol certification acceleration and direct-to-installer channel bypass strategies.
Within the defense-heritage tier, FLIR Systems, Inc. and Vicon Motion Systems Ltd exemplify thermal imaging specialization translated into ruggedized commercial applications. Panasonic i-PRO Sensing Solutions Co., Ltd. occupies the integrated platform position, representing the diversified electronics conglomerate archetype with end-to-end video management capabilities. Bosch Sicherheitssysteme GmbH anchors the European manufacturing scale vector, while GoPro, Inc. sits within the content creator-driven action camera segment that is collapsing traditional procurement boundaries.
| Leading Market Players |
|---|
| Arlo |
| Honeywell International Inc. |
| FLIR Systems, Inc. |
| Vicon Motion Systems Ltd |
| Bosch Sicherheitssysteme GmbH |
| Panasonic i-PRO Sensing Solutions Co., Ltd. |
| Pelco Corporations |
| Canon |
| GoPro, Inc. |
| Others |
Value Chain & Pricing Dynamics
Shenzhen and Dongguan manufacturing clusters concentrate polycarbonate housing production and semiconductor packaging capacity, granting dominant suppliers leverage over unit economics and forcing downstream buyers into long-term offtake arrangements to secure allocation.
Pricing Analysis
Price spreads between US and European procurement channels reflect certification burden differentials rather than component costs. Three-tier pricing structure across premium, standard, and economy levels separates NIST-compliant federal units from municipal-grade hardware and consumer action cameras. Cost compression in the standard tier is intensifying because REACH reformulation cycles extend qualification timelines. Municipal security departments exhibit highest price sensitivity; defense agencies absorb premium tiers without volume negotiation.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Jabil, and Pegatron holding dedicated outdoor electronics lines across Shenzhen, Dongguan, and Penang facilities. Image sensor foundry capacity clusters in Taiwan and South Korea; polycarbonate resins and optical glass feed from Japan and Germany. Single-source vulnerability in specialized thermal sensor foundries exposes pipelines to geopolitical disruption. Distribution runs through authorized integrator networks for defense and critical infrastructure, direct-to-installer platforms for commercial channels, and e-commerce marketplaces for consumer tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Weatherproof camera procurement is shifting from hardware transactional models toward platform-economics structures where video management software ecosystems and ONVIF interoperability determine vendor lock-in and lifetime value capture.
For Market Incumbents: Pre-empt displacement by direct-to-installer platforms through captive channel investments in tier-2 European markets and tier-2 Indian municipal corporations. Secure exclusive supplier status under US Department of Transportation bridge rehabilitation programs before competitive certification cycles complete. Backward integration into solid-state thermal management components reduces dependency on Japanese optical glass suppliers facing Arctic performance limitations. For New Entrants and Emerging Players: Tier-2 Indian municipal corporations with Safe City mandates and limited incumbent relationships offer the most penetrable white-space target for IP-rated surveillance hardware. Documentary production houses and YouTube creator studios in North American outdoor recreation corridors represent fastest-growing action camera demand with minimal brand loyalty. Pursue direct-to-installer e-commerce positioning to bypass established distributor markups and capture electrical contractor procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platform providers with video management software subscriptions and cloud storage tiers rather than hardware pure-plays. Long-term viability over the coming decade favors vendors with neural processing unit integration for edge-native AI inference and established FCC certification pipelines. Monitor cellular mesh networking protocol adoption rates among utility substation operators as inflection indicator for wireless platform displacement of cabled infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native AI Integration | Neural processing unit deployment enables real-time anomaly detection for oil and gas pipeline operators without bandwidth costs. |
| Direct-to-Installer Platform Launch | Specialized e-commerce marketplaces capture margin from electrical contractors in fragmented European procurement channels. |
| NIST Cybersecurity Certification | Encrypted firmware and secure boot protocols unlock federal and utility procurement channels with compliance mandates. |
| Solid-State Thermal Management | Silicon-carbide power management eliminates electrolytic capacitors, enabling decade-long maintenance-free solar deployments. |
| EU AI Act Conformity Acceleration | Mandatory assessments for facial recognition-enabled cameras create first-mover advantage among European municipal security departments. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs records, SEC filings from surveillance technology vendors, FCC equipment authorization databases, and EU Ecodesign directive implementation reports. Primary interviews engaged product managers at thermal imaging specialists, procurement officers at municipal security departments, systems integrators in European commercial channels, and engineering directors at polycarbonate housing manufacturers. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions across the analysis window.
Forecast inputs incorporate technology migration curves for wireless protocol adoption, regulatory compliance timeline acceleration, and channel structure displacement rates. Modeled dimensions span product type, signal processing architecture, end-user vertical, and distribution channel, with additional weighting for certification tier and geographic procurement authority. CAGRs derive from segment-level growth differentials applied across the projection horizon, with specific adjustment for semiconductor foundry capacity constraints and REACH substance restriction implementation phases.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese platform providers or subsidy-backed domestic manufacturers in India would shift outcomes beyond modeled ranges. Quarterly review of cellular infrastructure densification rates, BIS certification backlog timelines, and NIST framework adoption curves among federal procurement officers is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Asia Pacific IP Camera Market
Imaging
Uncooled Infrared Camera Market
Imaging
Ent Cameras Market
Imaging
Semiconductor Microscopes Market
Imaging
PET Scanners Market
Imaging
LCD Digital Microscope Market
Imaging
Webcam Market
Imaging
Global Backscatter X-Ray Devices Market
Imaging
Image Intensifier Market
Imaging
APAC Image Sensors Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
Infrared Imaging Market
Imaging
Digital Camera Market
Imaging
X-Ray Microscopes Market
Imaging
CMOS X-Ray Detectors Market
Imaging
Gige Camera Market