
 Ultra-Wide Field Imaging Device Market | 2026-2036
Ultra-Wide Field Imaging Device Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Wide Field Imaging Device Market Analytics
Buyer concentration among hospital networks is hardening across ophthalmology service lines. Optos leverages its installed base in academic medical centers to sustain recurring service revenue. Heidelberg Engineering anchors European demand through specialized diabetic retinopathy protocols. Carl Zeiss Meditec AG competes on integrated workflow connectivity with surgical suites.
Ultra-wide field imaging devices capture retinal images spanning up to 200 degrees in a single scan using scanning laser ophthalmoscopy or multi-spectral detection arrays, enabling peripheral lesion visualization that standard fundus cameras miss. Desktop systems dominate current revenue as hospital capital budgets favor permanent installation reliability, while handheld devices represent the fastest-expanding segment through point-of-care screening programs in underserved regions. Optical coherence tomography technology leads margin pools due to combined structural and angiographic imaging capabilities.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations extend development timelines for new entrants. ISO 13485 quality management standards govern manufacturing consistency across export markets. Stakeholders must monitor reimbursement code valuations for remote diagnostic interpretations.
Market Dynamics
Hospital network consolidation is compressing vendor negotiation cycles and favoring suppliers with integrated service ecosystems over standalone device manufacturers.
Growth Catalysts
- Aging demographics:Japan, Germany, and the United States face acute diabetic retinopathy and age-related macular degeneration burdens that mandate systematic screening programs.
- EU MDR harmonization:Streamlined technical documentation pathways accelerate cross-border market access for compliant manufacturers.
- Point-of-care expansion:Handheld ultra-wide field devices penetrate rural screening networks where permanent installation remains economically unviable.
Market Restraints
- Optical component concentration:Precision lens and laser source supply clusters in German and Japanese specialty manufacturers create input vulnerability.
- FDA 510(k) timeline friction:Substantial equivalence determinations for novel detection algorithms extend clearance durations unpredictably.
- Optical coherence tomography substitution:Combined structural-angiographic systems capture overlapping diagnostic use cases in academic settings.
Strategic Opportunities
- India rural health mission:National screening mandates for preventable blindness create procurement volume for portable imaging units.
- Telemedicine reimbursement codes:Remote diagnostic interpretation policies in select US states enable service-based revenue models.
- AI-assisted detection convergence:Automated lesion classification algorithms integrate with hardware platforms to reduce specialist interpretation burden.
Industry Challenges
- ISO 13485 implementation:Quality management system certification demands 12-18 month preparation cycles for emerging manufacturers.
- Legacy PACS integration:Hospital IT infrastructure heterogeneity complicates seamless image workflow connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Wide Field Imaging Device Market |
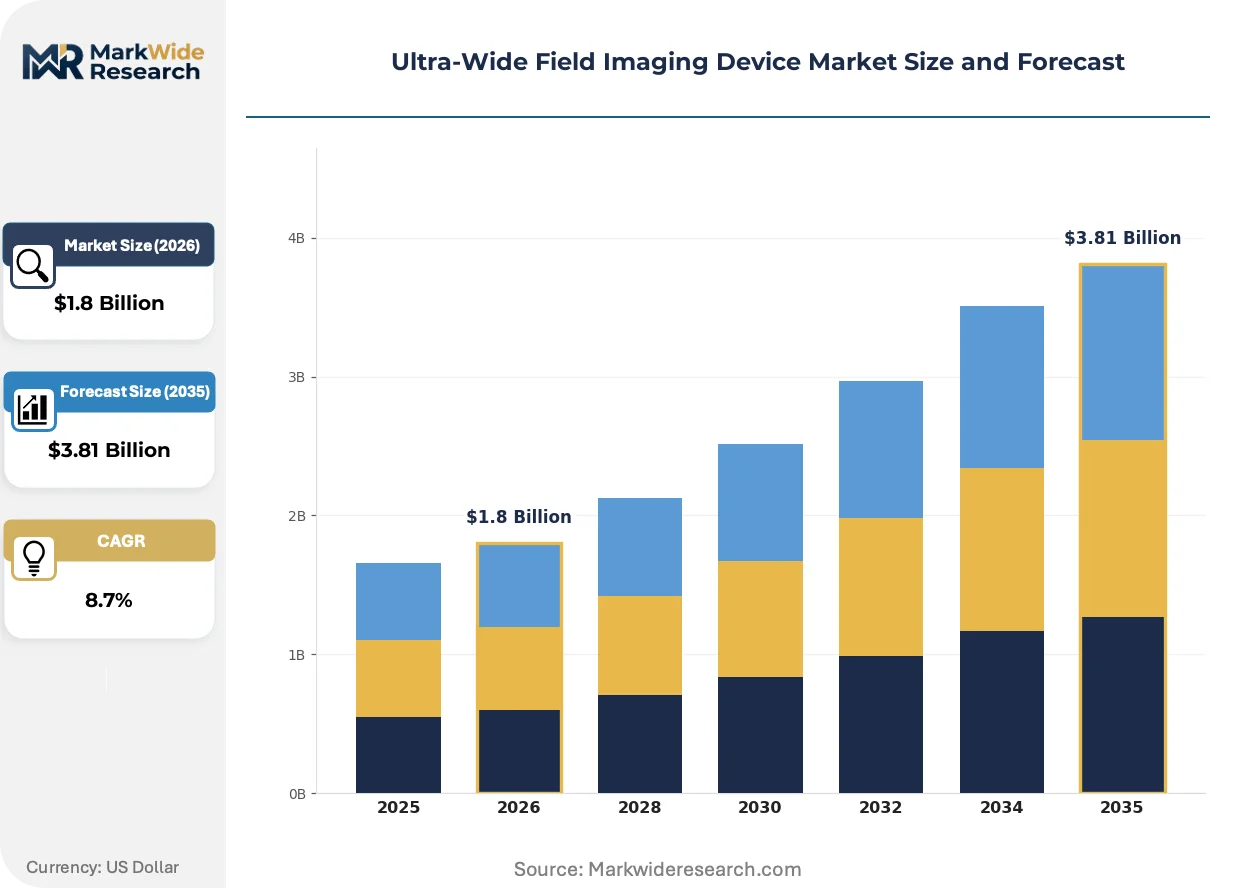
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Desktop Systems, Mobile Units, Fixed Systems Technology: Optical Coherence Tomography, Retinal Fundus Photography, Fluorescence Imaging, Multi-Spectral Imaging End User: Ophthalmology Clinics, Hospitals, Research Institutions, Diagnostic Labs Application: Retinal Screening, Disease Diagnosis, Surgical Guidance, Research Studies |
| Companies Covered | Optos, Carl Zeiss Meditec AG, Heidelberg Engineering, Centervue S.P.A., Clarity Medical Systems, Visunex Medical Systems, Topcon Healthcare, Zeiss Group, Nidek Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Wide Field Imaging Device Market Evolving Landscape
Multi-spectral detection arrays and artificial intelligence classification tools are reconfiguring competitive differentiation beyond raw image resolution metrics.
Scanning laser ophthalmoscopy platforms with integrated fluorescein angiography capability is expanding into comprehensive diabetic retinopathy management protocols. Community health systems in the United States adopt these systems to consolidate screening and referral workflows. The technology compresses capital equipment footprints while preserving diagnostic yield.
EU MDR technical documentation requirements for clinical evidence substantiation intensify post-market surveillance obligations. Manufacturers must maintain systematic safety and performance data collection across deployed installed bases. Class IIa device reclassification affects software-enabled diagnostic platforms most acutely.
Service contract unbundling separates preventive maintenance from software upgrade entitlements. Hospital procurement officers negotiate component pricing transparency that legacy bundled agreements obscured. This behavioral shift concentrates in German hospital networks with centralized ophthalmology service line management.
Ultra-Wide Field Imaging Device Market Segmentation
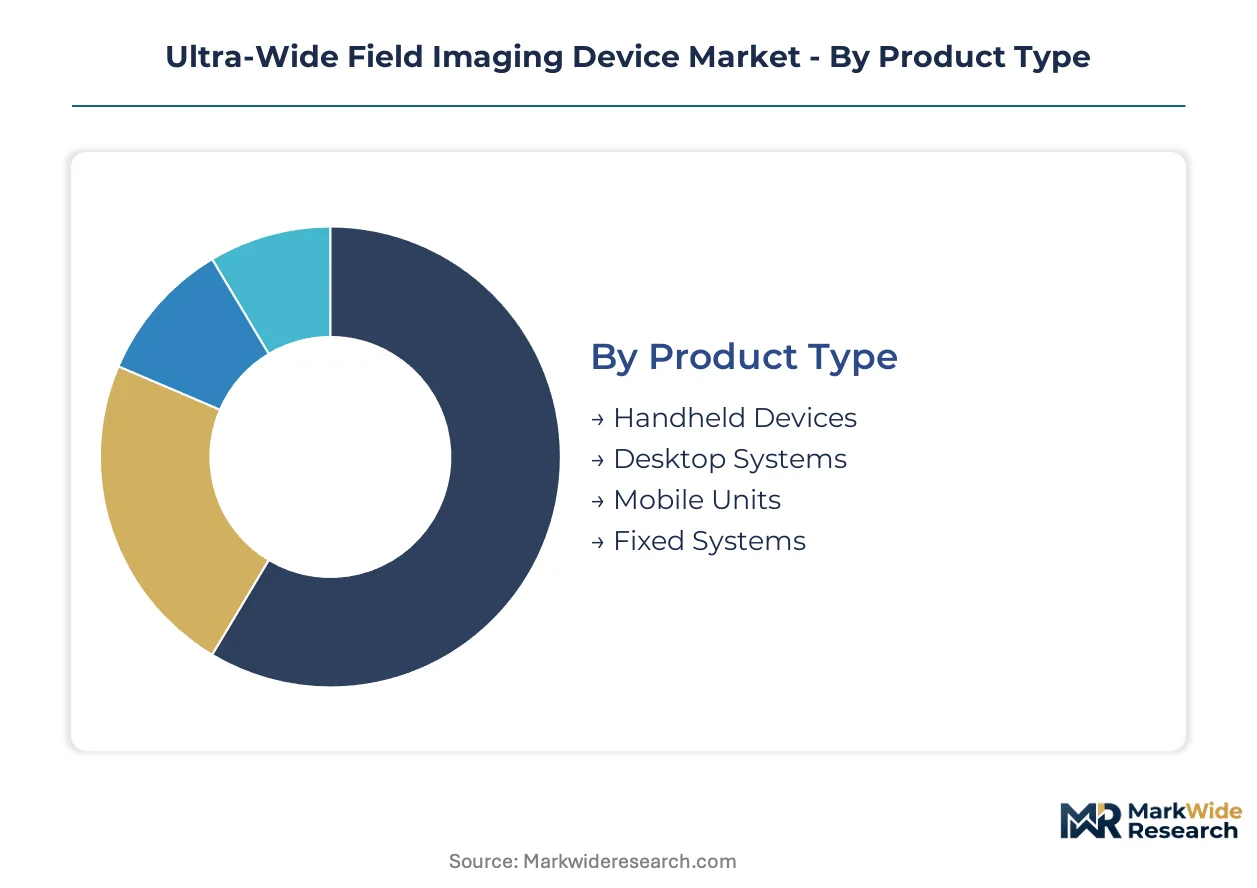
Ultra-wide field imaging devices serve distinct clinical workflows requiring hardware configurations ranging from portable screening tools to integrated surgical platforms. Procurement decisions hinge on capital budget cycles, patient throughput requirements, and connectivity demands within existing hospital IT infrastructure.
Product Type:
Standardization dominates permanent installations while customization pressures concentrate in portable screening programs requiring battery autonomy and ruggedized housing.
- Desktop Systems:Stationary units with integrated patient positioning systems and high-resolution scanning laser ophthalmoscopy engines. Hospital capital budgets in the United States and Germany favor these configurations for permanent ophthalmology suite installation where reliability and throughput volume justify upfront expenditure.
- Handheld Devices:Battery-powered units weighing under 2 kilograms with simplified operation protocols for non-specialist operators. Rural health missions in India and community screening programs across Japan deploy these most aggressively where infrastructure constraints prohibit fixed installation.
- Mobile Units:Cart-mounted systems with transportable power supplies for multi-department deployment within hospital networks.
- Fixed Systems:Permanent room installations with integrated fluorescein angiography capabilities and automated patient workflow management.
Most installed capacity flows through Desktop Systems. Expansion is steepest in Handheld Devices.
Technology:
Margin pools concentrate in multi-modal platforms while single-purpose systems face substitution pressure from combined diagnostic workflows.
- Optical Coherence Tomography:Interferometric depth-resolved imaging capturing retinal cross-sections with micrometer precision. Academic medical centers in Japan and the United States demand these systems for combined structural and angiographic assessment in diabetic retinopathy protocols.
- Multi-Spectral Imaging:Discrete wavelength detection arrays isolating specific chromophore absorption signatures for enhanced lesion contrast. Research institutions in Germany prioritize these configurations for longitudinal disease progression studies requiring standardized imaging biomarkers.
- Retinal Fundus Photography:Conventional visible-spectrum imaging with wide-angle lens attachments for documentation and screening.
- Fluorescence Imaging:Excitation-emission detection systems for dynamic vascular perfusion assessment following intravenous contrast administration.
Revenue concentration sits with Optical Coherence Tomography. Multi-Spectral Imaging is gaining share fastest among emerging purchase categories.
End User:
Procurement authority is consolidating within hospital network central purchasing while independent clinics retain decision autonomy for specialized equipment.
- Hospitals:Integrated health systems with centralized ophthalmology service lines managing high-volume screening and surgical referral pathways. Consolidated procurement in German hospital networks and US academic medical centers drives multi-unit purchasing agreements with preventive maintenance bundling.
- Ophthalmology Clinics:Independent specialty practices with focused diagnostic workflows and direct patient revenue models. These facilities in Japan and select US metropolitan areas prioritize compact footprints and rapid image acquisition cycles to maximize chair time utilization.
- Research Institutions:University-affiliated laboratories requiring calibrated imaging protocols and data export compatibility for multi-center trials.
- Diagnostic Labs:Centralized reading centers processing remote screening captures with specialist interpretation services.
Volume leadership belongs to Hospitals. Ophthalmology Clinics show the steepest expansion trajectory among decentralized care models.
Application:
Reimbursement code valuations differentiate screening from diagnostic interpretation, shaping hardware configuration requirements and software feature prioritization.
- Retinal Screening:Systematic image capture protocols for asymptomatic population surveillance with automated quality assessment. National blindness prevention programs in India and Japan mandate these workflows for diabetic and age-related disease detection at scale.
- Disease Diagnosis:Definitive characterization of pathological findings with multi-modal image correlation and progression tracking. Specialist practices in Germany and the United States require these capabilities for treatment planning in macular degeneration and retinal vascular disorders.
- Surgical Guidance:Real-time or preoperative imaging for procedural planning and intraoperative navigation.
- Research Studies:Standardized image acquisition for clinical trial endpoints and biomarker validation.
Installed base utilization concentrates in Retinal Screening. Disease Diagnosis commands the highest per-procedure reimbursement and fastest feature upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ophthalmology specialist density in Japan, Germany, and the United States anchors device deployment. Academic medical centers in these markets train the retinal surgeons who operate screening programs and drive procurement specifications.
United States
Hospital network consolidation concentrates purchasing authority within integrated delivery systems managing diabetic retinopathy screening at scale. FDA 510(k) clearance pathways shape product development timelines for algorithm-enabled diagnostic platforms. The Boston-Cambridge corridor hosts retinal imaging research clusters advancing multi-spectral detection protocols.
Germany
Centralized ophthalmology service line management within hospital networks drives multi-unit procurement agreements. EU MDR technical documentation obligations extend post-market surveillance requirements for software-enabled devices. The Heidelberg-Mannheim medical technology cluster anchors specialized diabetic retinopathy protocol development.
Japan
Aging demographics generate acute age-related macular degeneration screening demand mandating systematic population surveillance. PMDA regulatory frameworks govern software-as-medical-device classifications for AI-assisted detection algorithms. The Tokyo-Osaka corridor concentrates academic medical center installations with combined structural-angiographic imaging requirements.
India
National blindness prevention programs create procurement volume for portable screening units in rural health missions. CDSCO medical device registration requirements govern import and distribution pathways for foreign manufacturers. The Maharashtra-Gujarat pharmaceutical corridor hosts distribution networks reaching tier-two cities with mobile diagnostic deployments.
United Kingdom
National Health Service diabetic eye screening programs standardize imaging protocols across regional commissioning groups. MHRA conformity assessment procedures align with EU MDR technical documentation for market access continuity. The London-Oxford-Cambridge golden triangle concentrates research institutions validating longitudinal imaging biomarkers.
Ultra-Wide Field Imaging Device Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the technology spectrum. The vendor base organizes into three tiers: integrated optical systems houses, dedicated ophthalmology device manufacturers, and emerging portable imaging specialists. Strategic moves concentrate on service contract unbundling and AI-assisted detection algorithm integration. Geographic expansion into India's rural health missions and telemedicine reimbursement capture in select US states represent dominant competitive vectors.
Among diversified optical systems houses, Carl Zeiss Meditec AG and Zeiss Group occupy positions spanning microscopy, surgical visualization, and diagnostic imaging. Heidelberg Engineering exemplifies the European specialist archetype with concentrated retinal imaging protocol development. Optos represents the installed-base defender model leveraging academic medical center relationships for recurring service revenue. These three anchors illustrate how competitive positioning diverges between workflow integration depth and screening program specialization.
| Leading Market Players |
|---|
| Optos |
| Carl Zeiss Meditec AG |
| Heidelberg Engineering |
| Centervue S.P.A. |
| Clarity Medical Systems |
| Visunex Medical Systems |
| Topcon Healthcare |
| Zeiss Group |
| Nidek Co. |
| Others |
Value Network & Pricing Analysis
Optical engineering talent concentration in southern Germany and the Boston corridor feeds labor-cost differentials that widen pricing-tier spreads between premium multi-modal systems and economy screening units. Hospital procurement officers exploit this spread during consolidated vendor negotiations.
Pricing Analysis
Bundled preventive maintenance agreements are unbundling from software upgrade entitlements across German hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multi-spectral platforms from CE-marked screening-only configurations. Pricing pressure stems from optical coherence tomography systems capturing overlapping diagnostic workflows. Community health systems in the United States show highest price sensitivity; academic medical centers in Japan demonstrate lowest.
Supply Chain Analysis
ISO 13485 certification gating filters component suppliers before they reach device assembly tiers. Precision lens manufacturing concentrates in Germany and Japan; laser source production clusters in Japanese specialty houses. German and Japanese optical component dependencies create single-source vulnerability for scanning laser ophthalmoscopy engines. Distribution runs through hospital network central purchasing with multi-unit procurement agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ultra-wide field imaging hinges on AI-assisted detection software commanding premium pricing while handheld hardware costs compress through Indian manufacturing partnerships.
For Market Incumbents: Acquire AI-assisted detection algorithm portfolios to defend against optical coherence tomography substitution. Hospital network consolidation demands integrated workflow connectivity investments. Carl Zeiss Meditec AG and Heidelberg Engineering anchor positions through surgical suite integration and specialized diabetic retinopathy protocols respectively. For New Entrants and Emerging Players: Launch via portable screening unit distribution partnerships targeting India's rural health mission procurement volumes. National blindness prevention programs mandate systematic diabetic retinopathy screening at scale. Telemedicine reimbursement code capture in select US states enables service-based revenue models alongside hardware sales. For Investors and Strategic Acquirers: Valuations sit cheapest among emerging portable imaging specialists lacking installed base service revenue. Long-term viability favors vendors with FDA 510(k) clearance pathways and EU MDR technical documentation capabilities. Watch for PMDA software-as-medical-device classification shifts as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways accelerate algorithm-enabled diagnostic platform commercialization in US hospital networks. |
| CE Marking Pathway | EU MDR technical documentation obligations govern cross-border market access for software-enabled devices. |
| Hospital System Partnership | Consolidated procurement in German networks favors suppliers with integrated service ecosystems. |
| Software Companion Development | AI-assisted lesion classification reduces specialist interpretation burden in Japanese screening programs. |
| Reimbursement Strategy | Remote diagnostic interpretation policies in select US states enable service-based revenue capture. |
Research Methodology
Direct dialogue with retinal surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement code valuations. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against hospital installation records.
Bottom-up modeling segmented volume and value across product type, technology, end user, and application dimensions. CAGRs derived from regression analysis of historical procurement patterns and demographic screening mandate trajectories. Forecast inputs incorporated PMDA software-as-medical-device classification timelines and India rural health mission procurement schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA 510(k) timeline friction or optical component supply disruption. A model refresh is warranted upon material change in telemedicine reimbursement code valuations or EU MDR Class IIa reclassification enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Uncooled Infrared Camera Market
Imaging
Global Label-Free Array Systems Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
Global Document Scanner Market
Imaging
Global Broadcast Cameras Market
Imaging
AI-Based Fever Detection Camera Market
Imaging
X Ray Tubes Market
Imaging
Computer Aided Detection Market
Imaging
Global Image Processing Systems Market
Imaging
Micro Computed Tomography Market
Imaging
Camera with Flip Screen Market
Imaging
Photo Kiosk Market
Imaging
Pico Projector Market
Imaging
Semiconductor Microscopes Market
Imaging
Japan Digital X-Ray Market
Imaging
Document Imaging Market