
 Light Field Market | 2026-2036
Light Field Market Size, Share, and Industry Trends Forecast 2026-2036
Light Field Market Analysis
Healthcare visualization is decoupling from conventional two-dimensional displays as surgical planning and radiology departments demand volumetric depth cues without head-mounted hardware. NVIDIA Corporation leverages its GPU compute architecture to render real-time light field datasets for medical and entertainment pipelines. Sony Corporation anchors the professional camera segment through specialized sensor arrays designed for multi-view capture. Raytrix GmbH specializes in microlens array manufacturing for industrial metrology and research microscopy.
Light field technology captures both the intensity and directional vector of light rays through arrays of micro-lenses or multi-camera matrices, enabling post-capture refocusing and depth extraction from a single exposure. The hardware generates data volumes orders of magnitude larger than conventional imaging, requiring specialized compression and processing architectures. Display Systems command the largest product type category as holographic panels move from laboratory prototypes toward commercial deployment in automotive dashboards and surgical suites. Software represents the fastest-expanding segment as real-time rendering engines and light field codecs mature for streaming applications. Healthcare and Automotive verticals show the steepest adoption curves among industry applications, driven respectively by surgical precision requirements and heads-up display safety mandates.
The EU AI Act and FDA device classification frameworks are converging on algorithmic accountability standards for computational imaging used in diagnostic and autonomous vehicle contexts. CE marking under the MDR and REACH compliance for optical component materials shape product design cycles and market access timelines for European and North American suppliers. Stakeholders must monitor evolving interoperability standards between light field capture hardware and existing medical imaging archives as regulatory bodies finalize data format requirements for clinical acceptance.
Market Dynamics
Computational imaging pipelines are absorbing GPU architectures originally designed for gaming workloads, compressing hardware refresh cycles across medical and automotive display deployments.
Growth Catalysts
- Surgical visualization mandates:North American hospital systems are retrofitting operating theaters with volumetric displays to reduce cognitive load during minimally invasive procedures. FDA 510(k) pathways for holographic surgical aids are clarifying commercialization timelines.
- EU AI Act transparency requirements:Algorithmic accountability standards for diagnostic imaging are accelerating vendor investment in explainable light field rendering engines. CE marking under MDR is becoming a competitive differentiator for European suppliers.
- Automotive HUD safety regulations:Germany's KBA and NHTSA are tightening heads-up display field-of-view standards. Light field panels eliminate vergence-accommodation conflict, satisfying emerging safety mandates for autonomous vehicle interfaces.
Market Restraints
- Specialized sensor cost structure:Multi-view camera arrays require customized CMOS sensors with microlens overlay fabrication. Wafer-level optics manufacturing concentrates in Taiwan and South Korea, exposing buyers to foundry allocation volatility.
- Data bandwidth limitations:Single light field captures generate terabyte-scale raw datasets. Existing medical imaging archive infrastructure lacks native support for directional light ray storage, forcing costly middleware development.
- Display panel yield constraints:Holographic panel production requires sub-micron alignment of spatial light modulators. Manufacturing defects in diffractive optical elements render entire substrates non-functional, elevating unit economics.
Strategic Opportunities
- Underpenetrated industrial metrology:Japan's precision manufacturing sector shows minimal light field adoption for defect inspection. METI quality standard revisions may accelerate replacement of stereo vision systems in automotive component verification.
- Streaming codec maturation:Light field compression algorithms are approaching bandwidth parity with conventional video. Content delivery networks can now trial volumetric sports broadcasts without dedicated fiber infrastructure.
- Convergence with neural rendering:Differentiable light field synthesis is unifying capture hardware requirements with generative AI pipelines. Startups are emerging at the intersection of radiance field methods and real-time display hardware.
Industry Challenges
- Computational optics talent scarcity:Wave optics simulation and Fourier optics expertise resides primarily in academic laboratories. Industrial employers compete for PhD-level specialists capable of optimizing microlens array designs.
- Legacy PACS integration friction:Hospital radiology departments require bidirectional translation between DICOM archives and proprietary light field formats. Vendor-neutral interoperability standards remain under development by IEC technical committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Field Market |
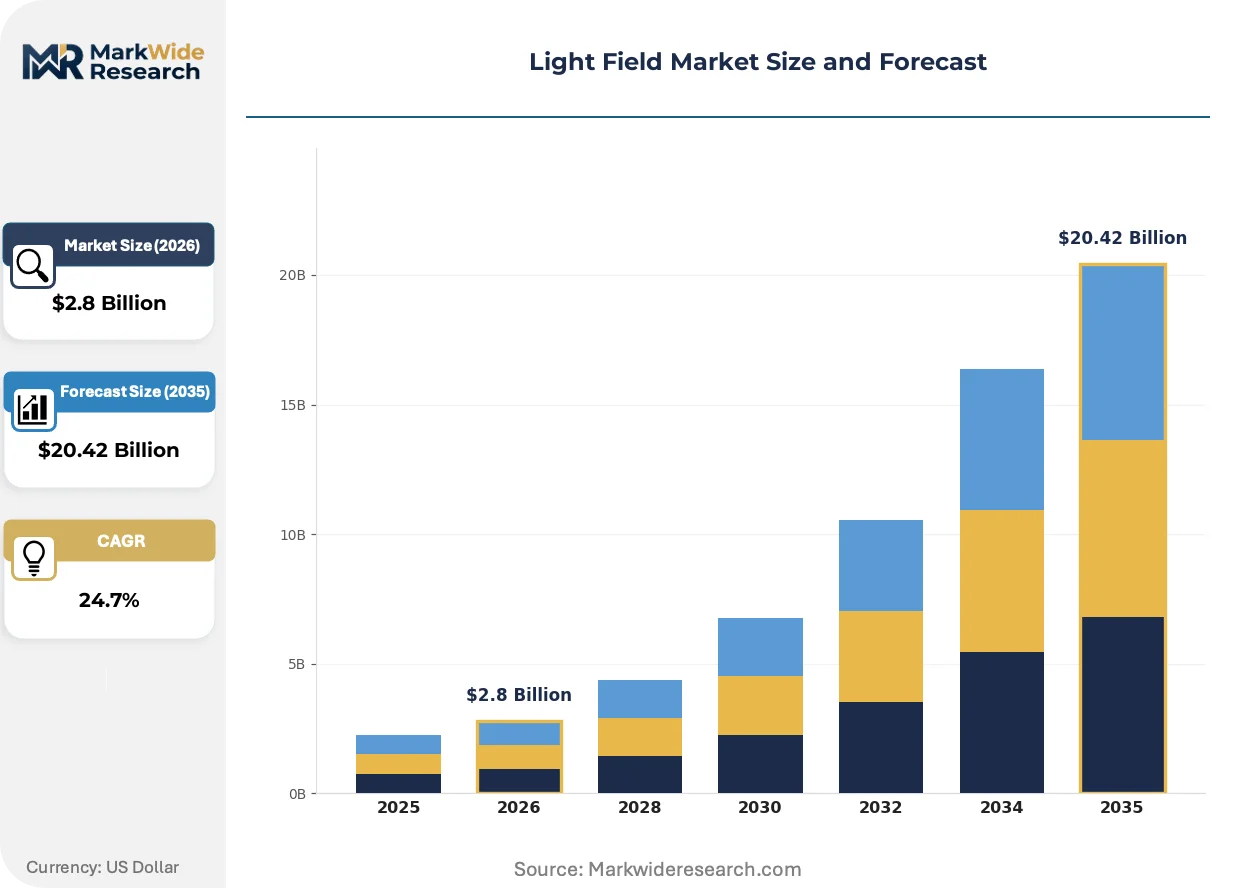
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Systems, Lenses, Cameras, Software Industry Vertical: Entertainment, Healthcare, Automotive, Education End User: Filmmakers, Clinicians, Designers, Researchers Technology: Computer Vision, Augmented Reality, Virtual Reality, Light Field Capture |
| Companies Covered | Light Field Lab, Inc., Raytrix GmbH, Avegant Corporation, NVIDIA Corporation, Sony Corporation, Google LLC, Leia Inc., OTOY Inc., FoVI 3D, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Field Market Emerging Trajectories
Real-time rendering architectures are collapsing the latency gap between capture and display, enabling interactive volumetric interfaces previously confined to offline post-production pipelines.
Neural light field compression is unifying previously separate encoding stages for depth estimation, view synthesis, and compression into single differentiable pipelines. Medical imaging equipment manufacturers are adopting these architectures to stream surgical navigation data within hospital network bandwidth constraints. The technology is unifying hardware requirements across diagnostic and interventional applications, reducing the need for dedicated post-processing workstations.
EU AI Act algorithmic transparency mandates are forcing computational imaging vendors to document training data provenance and inference decision boundaries. Light field depth extraction algorithms used in autonomous vehicle perception now require auditable documentation of edge-case handling. Automotive Tier-1 suppliers in Germany are restructuring software development workflows to satisfy conformity assessment body requirements before 2026 enforcement deadlines.
Hospital procurement committees are bundling light field display acquisitions with long-term service agreements covering calibration and software maintenance. Traditional capital equipment purchasing is giving way to subscription models that include codec updates and regulatory compliance patches. This shift is most visible in United States academic medical centers negotiating enterprise-wide visualization platform contracts.
Light Field Market Segmentation
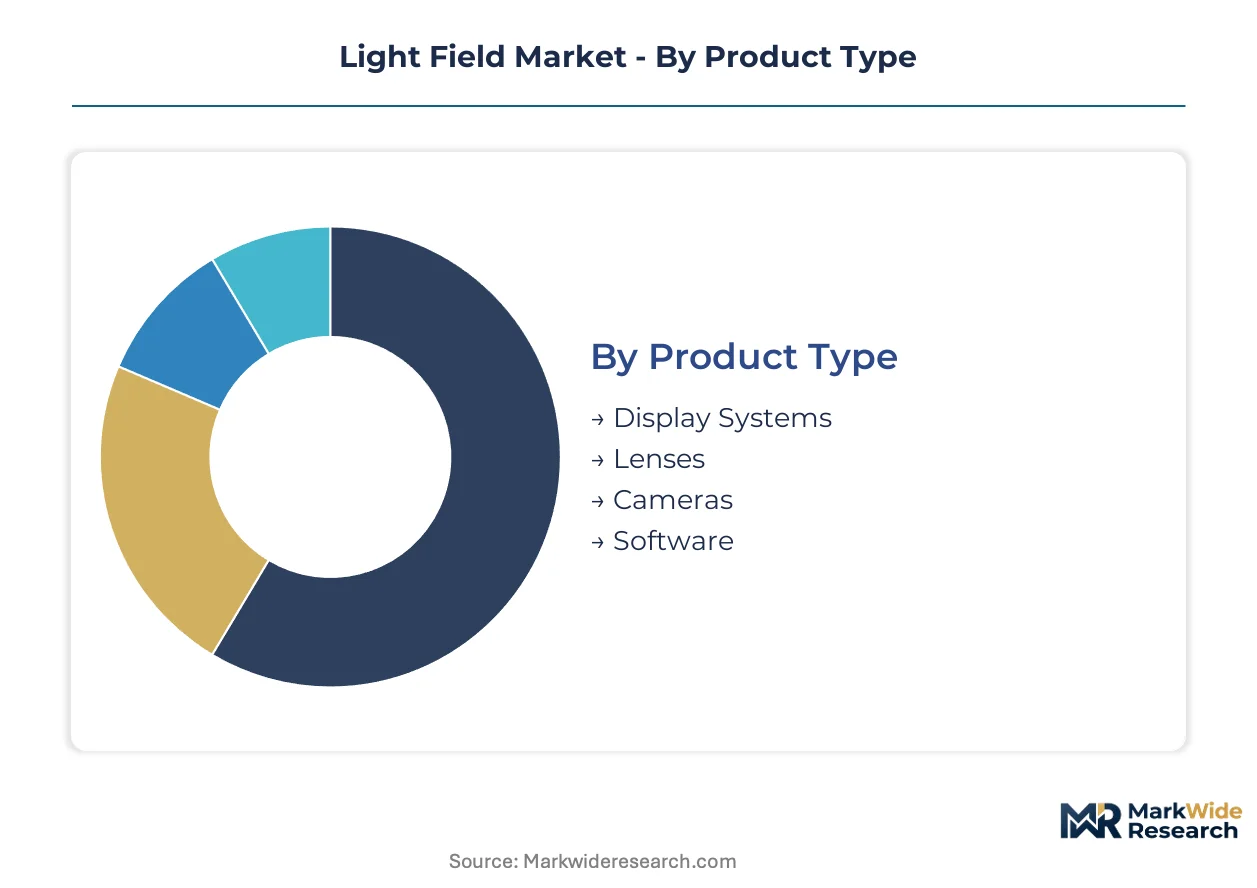
Light field technology spans heterogeneous hardware and software layers, each with distinct technical requirements and commercial maturity. Segmentation reveals where capital deployment concentrates and which application layers command premium pricing.
Product Type:
Microlens arrays and spatial light modulators define the technical frontier, with manufacturing precision determining performance tiers.
- Display Systems:Holographic panels integrate spatial light modulators with diffractive optical elements to render volumetric imagery without headsets. Hospital surgical suites in the United States and automotive design studios in Germany account for the bulk of current procurement, driven by FDA 510(k) pathway clarity and KBA safety mandates for heads-up interfaces.
- Software:Real-time rendering engines and neural compression codecs process terabyte-scale raw captures into streamable formats. Content delivery networks trial volumetric sports broadcasts as bandwidth efficiency approaches parity with conventional video, compressing codec development cycles.
- Cameras:Multi-sensor arrays with microlens overlays capture directional light vectors for post-capture refocusing.
- Lenses:Wafer-level microlens fabrication enables compact form factors for mobile and embedded applications.
Display Systems lead on scale; Software leads on momentum.
Industry Vertical:
Regulatory pressure and safety mandates are reshaping procurement priorities across end-use sectors.
- Healthcare:Surgical visualization and radiology departments demand volumetric depth cues without cognitive load from head-mounted hardware. North American academic medical centers negotiate enterprise platform contracts bundling hardware with calibration and compliance services.
- Automotive:Light field panels eliminate vergence-accommodation conflict in heads-up displays, satisfying emerging field-of-view standards from Germany's KBA and the United States NHTSA for autonomous vehicle interfaces.
- Entertainment:Professional capture systems serve volumetric video production for immersive media pipelines.
- Education:Research institutions deploy light field microscopy for biological specimen analysis and materials science.
Healthcare captures the premium pricing tier; Automotive climbs the fastest.
End User:
Technical sophistication and integration requirements fragment the customer base across specialist workflows.
- Clinicians:Surgeons and radiologists require FDA-cleared devices with DICOM interoperability for seamless archive integration. Vendor-neutral standards under IEC technical committee development remain incomplete, forcing costly middleware investment.
- Filmmakers:Volumetric capture for virtual production demands real-time preview and post-capture refocusing flexibility.
- Designers:Automotive and industrial designers prototype holographic interfaces using light field visualization.
- Researchers:Academic laboratories advance computational optics algorithms and Fourier optics simulation for next-generation microlens architectures.
Clinicians dominate current revenue; Researchers anchor the innovation pipeline.
Technology:
Capture and rendering architectures are converging as neural methods unify previously separate processing stages.
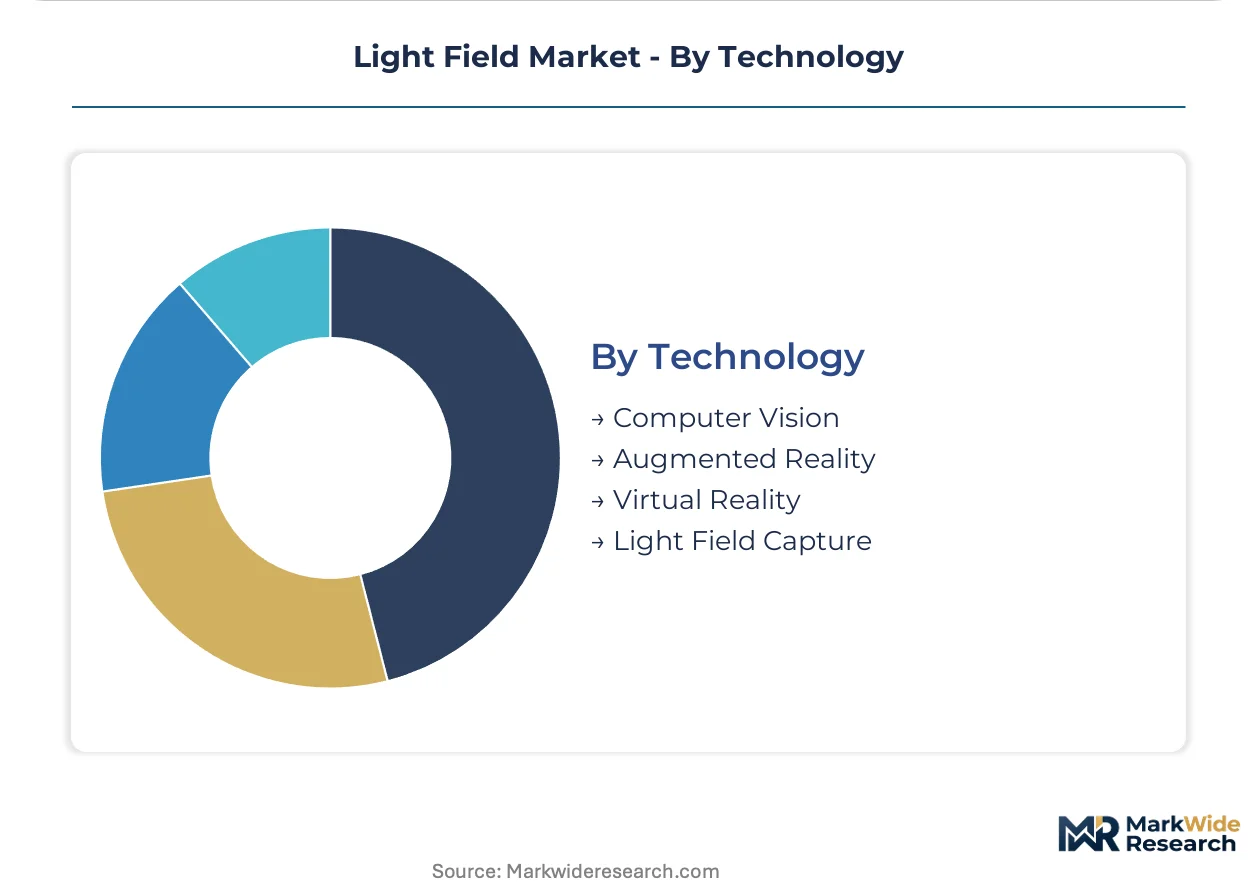
- Light Field Capture:Arrays of micro-lenses or multi-camera matrices record intensity and directional vector simultaneously. EU AI Act transparency requirements now mandate auditable documentation of depth extraction algorithms used in diagnostic and autonomous vehicle perception contexts.
- Computer Vision:Depth estimation and view synthesis algorithms process raw captures for target applications.
- Augmented Reality:Light field displays enable glasses-free volumetric overlay for industrial and medical guidance.
- Virtual Reality:Volumetric video capture feeds immersive environments with six-degrees-of-freedom navigation.
Light Field Capture anchors hardware investment; Computer Vision expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial optics cluster around Jena and Munich anchors the light field value chain, with precision manufacturing heritage translating into wafer-level microlens fabrication dominance. Regulatory momentum and automotive safety mandates are redrawing procurement priorities across key national markets.
United States
FDA 510(k) pathway clarity is accelerating hospital surgical suite retrofits with holographic visualization systems. Academic medical centers in Boston and the Research Triangle negotiate enterprise platform contracts bundling hardware with calibration services. NHTSA heads-up display field-of-view standards are tightening procurement specifications for autonomous vehicle interfaces.
Germany
KBA safety mandates for automotive HUDs are eliminating vergence-accommodation conflict through light field panel adoption. EU AI Act algorithmic transparency requirements force restructuring of software development workflows ahead of 2026 enforcement deadlines. The Jena-Munich optics corridor concentrates microlens array manufacturing for industrial metrology and research microscopy.
Japan
METI quality standard revisions may accelerate replacement of stereo vision systems in automotive component verification. Precision manufacturing sectors in Nagoya and Osaka show minimal current light field adoption for defect inspection. PMDA regulatory frameworks are adapting to computational imaging device classifications for diagnostic applications.
South Korea
Wafer-level optics foundries in Suwon and Pyeongtaek face allocation volatility as multi-view camera array demand surges. MFDS medical device approval pathways are clarifying for holographic surgical aids. Display panel manufacturers in Gyeonggi Province are piloting spatial light modulator production for automotive dashboard integration.
China
MIIT standards development for volumetric display interfaces is advancing alongside dual carbon goals for manufacturing efficiency. NMPA regulatory harmonization with international frameworks is streamlining import pathways for computational imaging equipment. Shenzhen and Shanghai hardware clusters are absorbing GPU architectures for real-time light field rendering pipelines.
Light Field Market Vendor Landscape
Strategic partnerships dominate the current landscape as vendors bridge hardware-software gaps in computational imaging pipelines. The vendor base stratifies across integrated platform providers, specialized component fabricators, and rendering engine developers. Three archetypes define positioning: GPU compute architects, microlens array specialists, and holographic display integrators. Technology licensing and vertical integration into wafer-level optics represent the primary competitive vectors reshaping supply relationships.
Among GPU compute architects, NVIDIA Corporation exemplifies the platform-tier position, while Sony Corporation anchors the professional capture segment through sensor array specialization. Raytrix GmbH occupies the component-specialist tier with microlens manufacturing expertise concentrated in the German optics corridor. These three represent distinct strategic postures: horizontal platform leverage, vertical integration into imaging hardware, and deep specialization in optical subsystems.
| Leading Market Players |
|---|
| Light Field Lab, Inc. |
| Raytrix GmbH |
| Avegant Corporation |
| NVIDIA Corporation |
| Sony Corporation |
| Google LLC |
| Leia Inc. |
| OTOY Inc. |
| FoVI 3D, Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up display panel specialists have consolidated spatial light modulator manufacturing in Germany and South Korea, tightening pricing discipline through captive wafer-level optics capacity while forcing mid-tier buyers into longer-term service bundling.
Pricing Analysis
Distributor margins for holographic display systems compress at 15-20 points as direct-to-OEM channels expand for automotive Tier-1 contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared surgical suites from research laboratory configurations and educational deployments. Pricing pressure stems from foundry allocation volatility for customized CMOS sensors with microlens overlays. Hospital procurement committees show lowest price sensitivity due to bundled calibration and compliance service requirements, while academic research institutions negotiate aggressively on per-unit hardware costs.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korean wafer-level optics foundries that fabricate microlens arrays for multi-view camera modules. Raw material dependencies include specialized glass substrates, photoresist materials for diffractive optical elements, and high-purity silicon for spatial light modulators. Tariff exposure runs through semiconductor equipment import restrictions affecting EU and North American display integrators. Distribution runs through specialized medical device distributors in the United States and direct OEM relationships in Germany's automotive corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Light Field Market compounds steadily as regulatory mandates for surgical visualization and automotive safety interfaces institutionalize volumetric display procurement across healthcare and mobility sectors.
For Market Incumbents: Deepen backward integration into wafer-level microlens fabrication to secure foundry allocation against emerging GPU-architecture competitors. Fortify FDA 510(k) pathway expertise as EU AI Act transparency requirements raise compliance barriers for rendering engine documentation. Control channel relationships with academic medical centers through enterprise platform contracts bundling hardware with codec updates. For New Entrants and Emerging Players: Launch via software-only neural compression codecs targeting content delivery networks trialing volumetric sports broadcasts without dedicated fiber infrastructure. Exploit underpenetrated industrial metrology in Japan's precision manufacturing sector as METI quality standard revisions accelerate stereo vision replacement. Pursue research institution partnerships for Fourier optics talent acquisition and algorithm credibility building. For Investors and Strategic Acquirers: Valuations sit cheapest among component-specialist microlens array fabricators with captive German optics corridor manufacturing and established CE marking under MDR. Long-term viability favors platforms with regulatory compliance infrastructure spanning FDA and EU AI Act enforcement horizons. Watch IEC technical committee progress on DICOM interoperability standards as the signal for hospital procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies rendering engines with medical imaging archives under FDA 510(k) compliance pathways. |
| Strategic Partnership | Secures wafer-level optics allocation from Taiwan and South Korean foundries for automotive HUD production. |
| Acquisition of Specialist Firm | Absorbs Fourier optics PhD talent pools concentrated in Jena and Munich research laboratories. |
| Geographic Expansion | Establishes CE marking infrastructure ahead of EU AI Act algorithmic transparency enforcement deadlines. |
| Product Launch | Introduces neural light field compression achieving bandwidth parity with conventional video for CDN trials. |
Methodological Framework
Multiple input streams — primary interviews with hospital procurement committees, automotive Tier-1 supplier engineers, and computational optics researchers; secondary validation against FDA 510(k) filings, EU MDR CE marking databases, and NHTSA regulatory dockets; and customs data on wafer-level optics trade flows — were reconciled through bottom-up and top-down triangulation. Conversations with GPO contracts managers and biomedical engineers at academic medical centers in Boston and the Research Triangle informed surgical visualization demand assumptions. SEC filings from GPU compute architects and patent filings from microlens array specialists provided technology roadmap validation.
Data-stream reconciliation anchored volume and value outputs across product type, industry vertical, end user archetype, and technology architecture dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EU AI Act compliance timeline assumptions, KBA automotive HUD safety mandate implementation pacing, and hospital capital equipment refresh cycle patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry allocation disruptions or IEC interoperability standard delays. Projections reflect documented assumptions regarding regulatory enforcement pacing and technology maturation curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Cell Imagers Market
Imaging
Ingaas Image Sensor Market
Imaging
Multi Camera System Market
Imaging
Global Ingaas Camera Market
Imaging
Low-Light Imaging Market
Imaging
Multimodal Imaging Market
Imaging
Machine Vision System Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Global CMOS Image Sensors Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Uncooled Infrared Camera Market
Imaging
Photoacoustic Imaging Market
Imaging
Automotive Compact Camera Module Market
Imaging
Asia-Pacific Hyperspectral Imaging Systems Market
Imaging
Underwater Camera Market