
 Asia-Pacific Image Recognition Market | 2026-2036
Asia-Pacific Image Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Image Recognition Market Outlook
Buyer concentration in Asia-Pacific retail is hardening as multinational chains consolidate technology procurement across regional banners. NEC Corporation leverages its longstanding government relationships in Japan to sustain dominance in public-sector facial recognition deployments. SenseTime Group Limited anchors its position through deep learning specialization for surveillance and retail analytics across Greater China. Microsoft Corporation competes by extending cloud-based computer vision APIs to enterprises seeking rapid deployment without heavy infrastructure investment.
Asia-Pacific image recognition encompasses computational systems that identify, classify, and interpret visual data through algorithmic processing of pixel arrays, typically operating at inference latencies below 100 milliseconds for real-time applications. These systems serve industrial automation, security screening, diagnostic assistance, and consumer device authentication by converting optical inputs into structured, actionable metadata. Deep learning architectures now lead technology adoption as convolutional neural networks deliver superior accuracy in object detection and medical imaging interpretation compared to classical image processing methods. Edge computing deployment is gaining structural momentum as manufacturers and security operators prioritize low-latency inference and data sovereignty compliance over centralized cloud architectures.
Japan's METI enforces AI utilization guidelines that mandate transparency in biometric inference, while China's SAMR and MIIT jointly oversee algorithm recommendation and data security provisions for commercial image recognition services. India's draft Digital Personal Data Protection rules impose consent requirements on facial recognition deployments, complicating rollout timelines for technology vendors. Stakeholders must monitor divergent national AI governance trajectories to anticipate compliance costs and localization obligations that will reshape competitive access across the region.
Market Dynamics
Edge computing architectures are displacing centralized cloud inference across Asia-Pacific manufacturing and security deployments, driven by data sovereignty mandates and sub-50-millisecond latency requirements for real-time biometric authentication.
Growth Catalysts
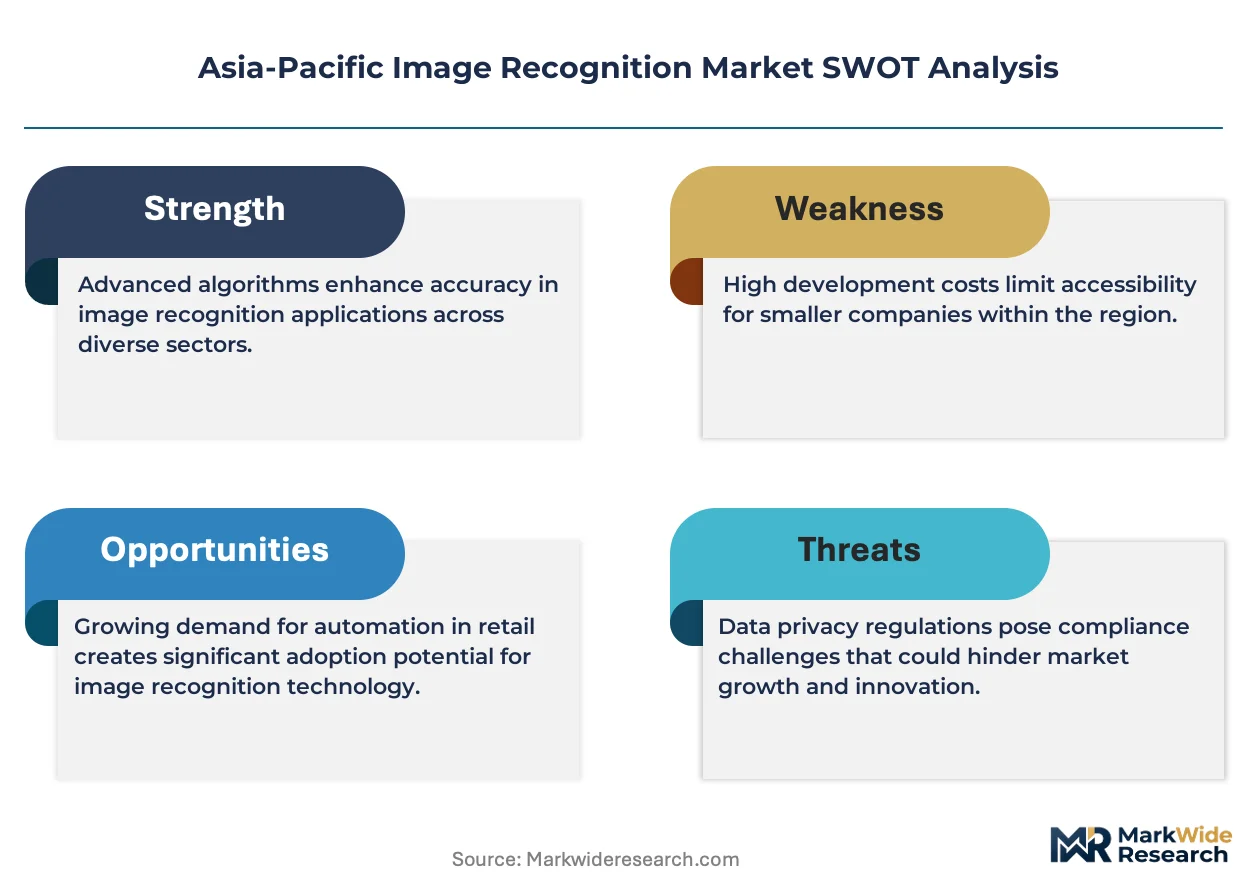
- Smart city infrastructure mandates:China's eastern seaboard municipalities sustain large-scale procurement of computer vision systems for traffic management and public safety monitoring.
- MIIT cybersecurity standards:Compliance requirements for biometric data handling are accelerating enterprise investment in localized, auditable image recognition infrastructure.
- Retail loss prevention automation:Southeast Asian department chains deploy facial analytics to shrinkage reduction programs, creating sustained demand for real-time customer behavior interpretation.
Market Restraints
- GPU supply concentration:Inference accelerator procurement depends on Taiwan-based foundry capacity, exposing deployment timelines to geopolitical supply disruptions.
- Biometric data localization:China's data security provisions and India's draft consent requirements impose architectural constraints that fragment cross-border solution scalability.
- Classical image processing substitution:Rule-based computer vision retains cost advantages in low-complexity industrial inspection, limiting deep learning penetration in price-sensitive segments.
Strategic Opportunities
- Indonesian retail modernization:Underpenetrated traditional trade sectors present white space for cloud-based computer vision APIs requiring minimal infrastructure investment.
- Medical imaging convergence:Fusion of convolutional neural networks with radiological workflows creates expansion paths in diagnostic assistance across Japan's aging hospital networks.
- PLI scheme alignment:India's production-linked incentives for electronics manufacturing attract component localization that reduces landed cost for domestic image recognition vendors.
Industry Challenges
- Deep learning engineering scarcity:Shortage of specialists capable of optimizing neural network architectures for edge deployment constraints compresses vendor delivery timelines.
- Multi-jurisdiction compliance synchronization:Divergent AI governance trajectories across China, Japan, and India force product architecture fragmentation that elevates development overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Image Recognition Market |
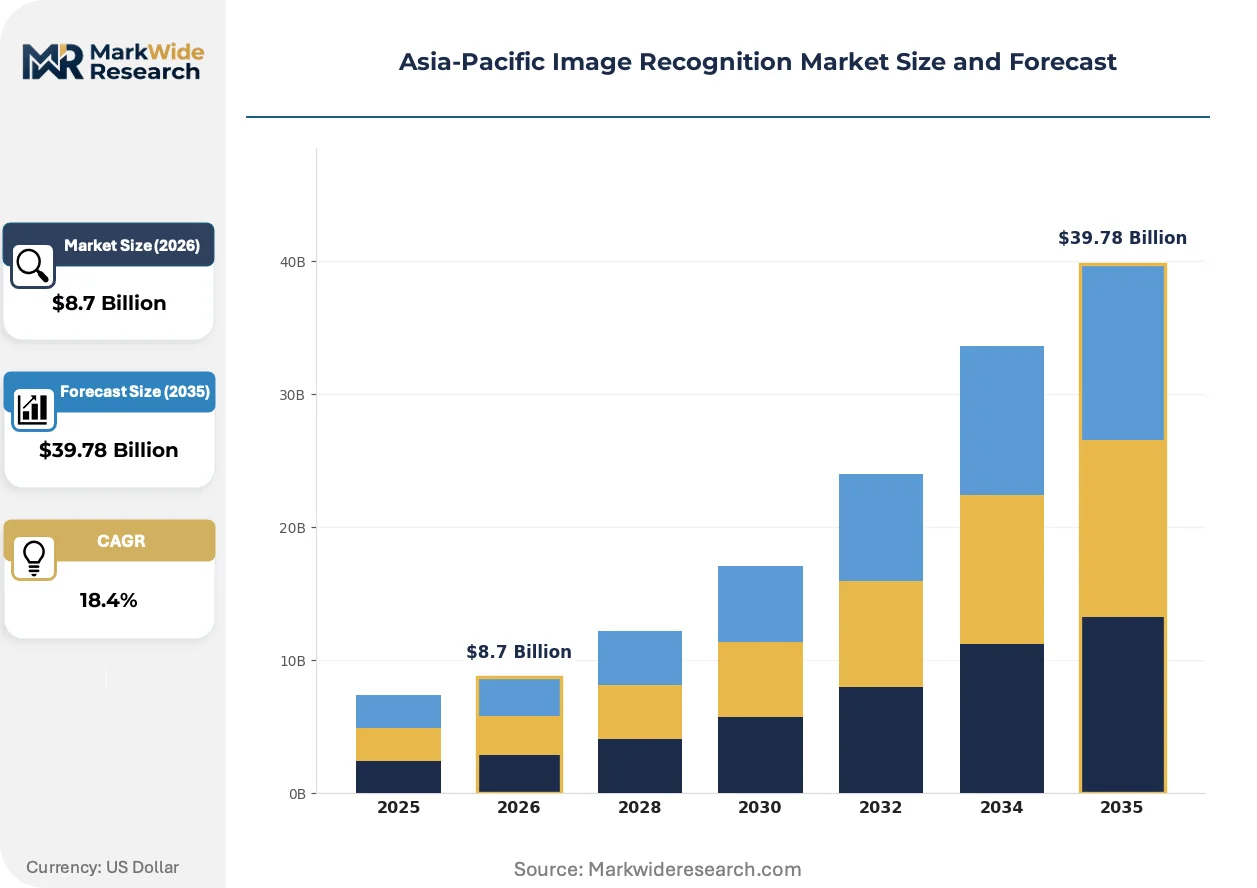
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Facial Recognition, Object Detection, Retail Analytics, Medical Imaging Technology: Machine Learning, Deep Learning, Neural Networks, Image Processing End User: Healthcare, Retail, Automotive, Security Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | NEC Corporation, SenseTime Group Limited, Megvii Technology Limited, Google LLC, Apple Inc., Microsoft Corporation, Amazon, Hitachi Ltd, Qualcomm Technologies Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Image Recognition Market Strategic Shifts
Transformer-based vision architectures are displacing convolutional dominance in production environments, while regulatory fragmentation forces modular compliance engineering. Procurement patterns favor inference-optimized hardware over general-purpose cloud credits.
Vision transformers are expanding into production-grade object detection by capturing long-range spatial dependencies that convolutional layers miss. Japanese automotive suppliers adopt these architectures for quality inspection at throughput rates exceeding 200 frames per second. The technology is expanding into medical imaging workflows where diagnostic accuracy gains justify computational overhead increases.
METI AI governance guidelines mandate transparency documentation for biometric inference systems deployed in commercial settings. Japanese enterprises must maintain algorithmic decision logs subject to third-party audit, elevating compliance engineering to core product development. Healthcare and financial services verticals face the steepest documentation burdens as they process sensitive personal imagery.
Subscription-based API consumption is displacing perpetual license models among mid-market retailers seeking to avoid infrastructure capitalization. Cloud-native computer vision services from hyperscale providers capture this demand through metered inference pricing. Southeast Asian e-commerce platforms represent the most aggressive adopters, prioritizing rapid feature deployment over solution ownership.
Asia-Pacific Image Recognition Market Segmentation
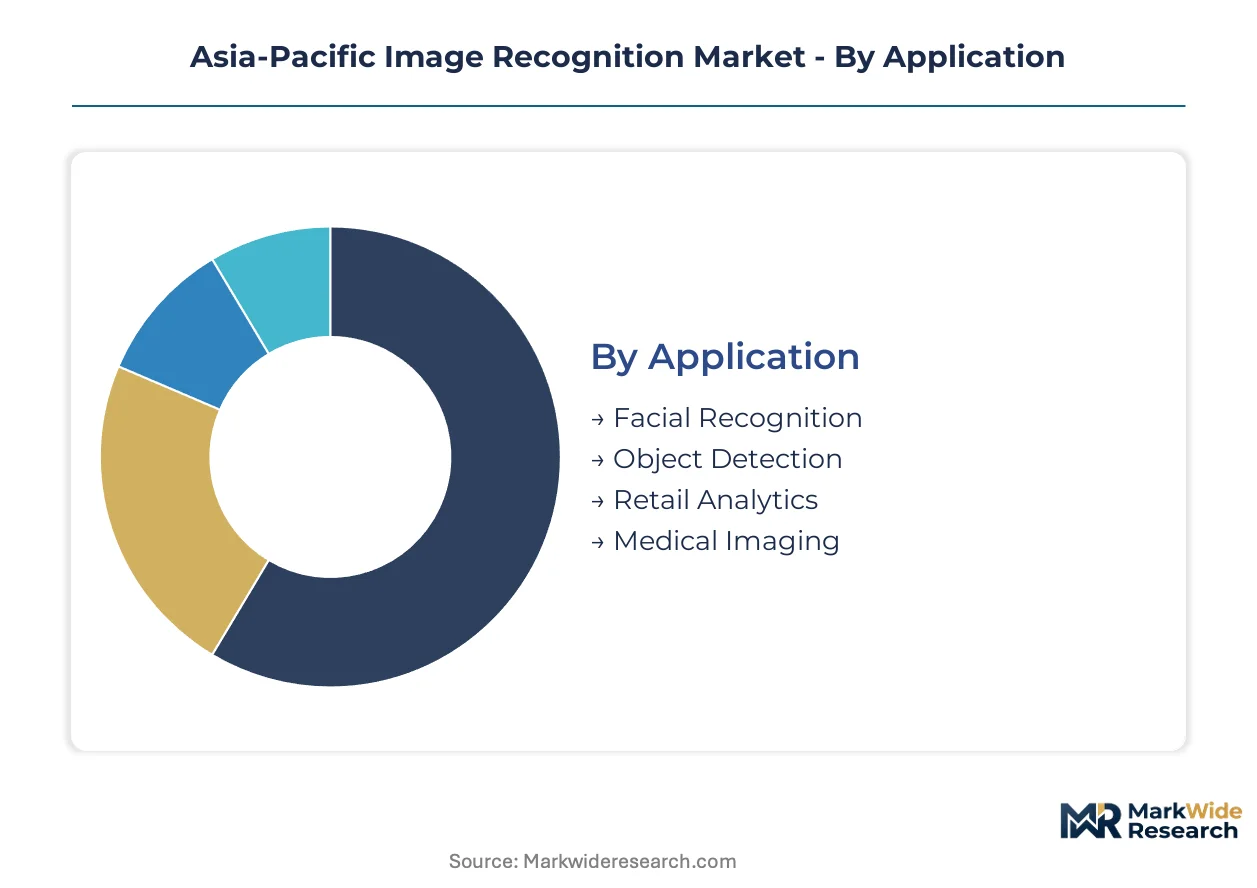
Segmentation across Asia-Pacific image recognition reveals divergent technology adoption curves between integrated edge deployments and centralized cloud architectures. Procurement patterns split sharply between latency-sensitive biometric authentication and batch-processed analytics workloads.
Application:
Standalone facial recognition systems dominate public-sector procurement, while embedded retail analytics modules integrate into broader enterprise software stacks.
- Facial Recognition:Real-time biometric authentication systems process pixel arrays through convolutional neural networks at sub-100-millisecond latency. Chinese municipal governments in Shanghai and Shenzhen sustain large-scale procurement for public safety infrastructure, constrained by MIIT data localization mandates that require on-device inference.
- Object Detection:Manufacturing quality inspection systems identify surface defects and dimensional anomalies through edge-deployed vision transformers. Japanese automotive suppliers in Toyota City and Yokohama adopt these architectures at throughput rates exceeding 200 frames per second, driven by zero-defect quality protocols.
- Retail Analytics:Customer behavior interpretation for loss prevention and merchandising optimization.
- Medical Imaging:Diagnostic assistance workflows fusing convolutional neural networks with radiological PACS systems.
Facial recognition leads volumes today; retail analytics is gaining share fastest.
Technology:
Cost structures stratify between capital-intensive deep learning infrastructure and lighter rule-based image processing for price-sensitive industrial segments.
- Deep Learning:Multi-layer neural architectures automatically extract hierarchical features from raw pixel data without manual feature engineering. Convolutional neural networks anchor production deployments across China's eastern seaboard smart city infrastructure, where accuracy requirements exceed 99% for biometric authentication.
- Machine Learning:Classical supervised learning with engineered features for constrained computational environments.
- Neural Networks:Feedforward and recurrent architectures for pattern recognition in sequential visual data.
- Image Processing:Rule-based algorithms using edge detection, thresholding, and morphological operations for low-complexity inspection tasks.
Deep learning commands premium pricing today; machine learning retains cost-sensitive volume.
End User:
Customer maturity varies between regulated healthcare procurement and fragmented retail technology adoption across Southeast Asian markets.
- Healthcare:Diagnostic imaging systems for radiological interpretation and pathology screening. Japanese hospital networks in Tokyo and Osaka deploy convolutional neural networks for oncology screening, facing METI-mandated algorithmic transparency documentation burdens.
- Security:Biometric access control and surveillance analytics for critical infrastructure protection.
- Retail:Customer analytics and loss prevention across department chains and e-commerce platforms.
- Automotive:In-cabin monitoring and advanced driver-assistance vision systems.
Security leads procurement volumes today; healthcare shows steepest expansion trajectory.
Deployment:
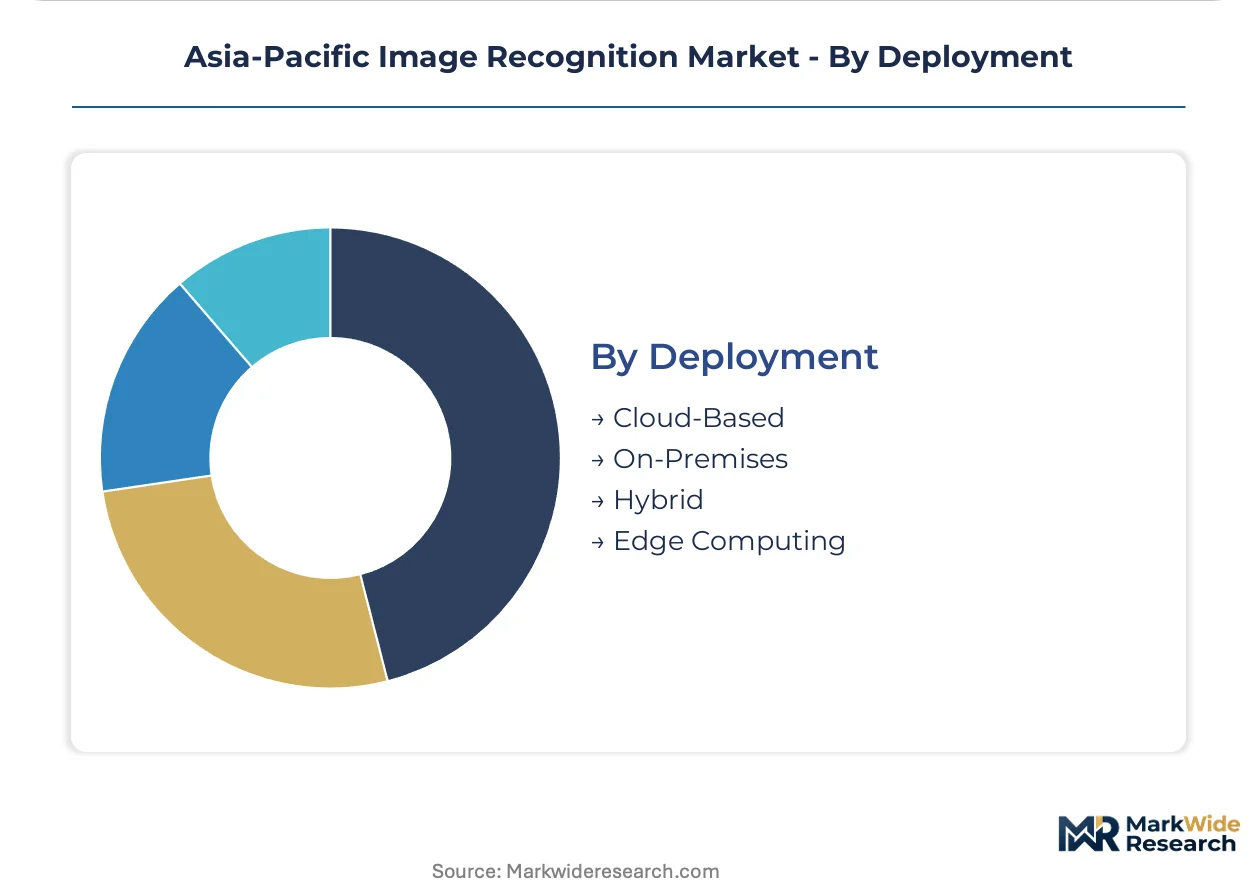
Infrastructure decisions hinge on data sovereignty requirements and latency thresholds that fragment solution architectures across national boundaries.
- Edge Computing:Distributed inference on localized hardware eliminating round-trip cloud latency. Manufacturing and security operators across Japan and South Korea prioritize sub-50-millisecond response times for real-time biometric authentication, bypassing cross-border data transfer restrictions.
- Cloud-Based:Centralized GPU clusters for batch analytics and model training workloads.
- On-Premises:Private data center deployments for regulated industries with strict data handling requirements.
- Hybrid:Orchestrated workloads splitting training to cloud and inference to edge endpoints.
Cloud-based deployments retain largest installed base today; edge computing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China outspends Japan on smart city computer vision infrastructure by a wide margin, yet Japanese manufacturers lead in edge-deployed quality inspection throughput. India's regulatory fragmentation complicates vendor entry despite its scale potential.
China
Shanghai and Shenzhen municipalities sustain large-scale procurement of facial recognition systems for traffic management and public safety monitoring. MIIT cybersecurity standards mandate localized data handling that accelerates investment in on-device inference architectures. The Yangtze River Delta cluster anchors production of inference-optimized hardware for domestic deployment.
Japan
Automotive suppliers in Toyota City and Yokohama adopt vision transformer architectures for zero-defect quality protocols at throughput rates exceeding 200 frames per second. METI AI governance guidelines enforce algorithmic transparency documentation for biometric inference systems. Tokyo and Osaka hospital networks deploy convolutional neural networks for oncology screening under steep compliance burdens.
India
Southeast Asian department chains source customer analytics modules from Indian software vendors seeking to avoid infrastructure capitalization. The draft Digital Personal Data Protection rules impose consent requirements that fragment cross-border solution scalability. Karnataka and Telangana electronics manufacturing clusters attract PLI scheme investment that reduces landed costs for domestic image recognition vendors.
South Korea
Security operators prioritize sub-50-millisecond response times for real-time biometric authentication, bypassing cross-border data transfer restrictions through edge computing deployment. The Seoul Capital Area concentrates demand for manufacturing quality inspection systems. Busan-Ulsan industrial corridors integrate computer vision into automotive and shipbuilding workflows.
Indonesia
Underpenetrated traditional trade sectors present white space for cloud-based computer vision APIs requiring minimal infrastructure investment. E-commerce platforms in Jakarta and Surabaya prioritize rapid feature deployment over solution ownership through subscription-based API consumption. The central government's retail modernization programs create procurement channels for foreign technology vendors.
Asia-Pacific Image Recognition Market Competitive Environment
Japanese producers anchor the public-sector tier through longstanding government relationships; Chinese specialists hold the surveillance and retail analytics segments through deep learning specialization. The vendor base splits between integrated conglomerates with cross-industry portfolios and focused neural architecture engineering shops. Three archetypes dominate: cloud hyperscalers offering metered inference APIs, edge hardware-software integrators, and government-contracting incumbents. Capacity localization and algorithmic transparency documentation represent the dominant competitive moves.
Within the government-contracting tier, NEC Corporation exemplifies the integrated conglomerate archetype through its public-sector positioning. SenseTime Group Limited and Megvii Technology Limited occupy positions as Chinese specialists in deep learning for surveillance and retail analytics. Microsoft Corporation sits within the cloud hyperscaler tier, extending computer vision APIs to enterprises seeking rapid deployment without heavy infrastructure investment.
| Leading Market Players |
|---|
| NEC Corporation |
| SenseTime Group Limited |
| Megvii Technology Limited |
| Google LLC |
| Apple Inc. |
| Microsoft Corporation |
| Amazon |
| Hitachi Ltd |
| Qualcomm Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Performance-tier bifurcation between sub-50-millisecond edge inference systems and centralized cloud APIs manifests in divergent pricing architectures and supply chain configurations across the Asia-Pacific image recognition landscape. Premium edge deployments command hardware-integrated pricing with Taiwan-sourced GPU accelerators, while metered API consumption models flatten upfront costs for Southeast Asian retail adopters seeking rapid deployment without infrastructure capitalization.
Pricing Analysis
Capacity additions in China's Yangtze River Delta GPU packaging facilities are reshaping price floors for inference-optimized hardware. Three-tier pricing structure across premium edge appliances, standard cloud API bundles, and economy-tier rule-based processing dominates procurement patterns. Cost compression in the economy tier intensifies because classical image processing retains viability for low-complexity industrial inspection. Mid-market retailers exhibit highest price sensitivity, while Japanese automotive suppliers under zero-defect protocols demonstrate lowest elasticity.
Supply Chain Analysis
GPU accelerator supply rests on Taiwan-based foundry capacity, Japanese specialty chemical producers for photoresist, and South Korean memory component manufacturers. Raw material dependencies include advanced silicon wafers, high-bandwidth memory modules, and precision optical sensors. Single-source vulnerability around Taiwan semiconductor fabrication exposes deployment timelines to geopolitical disruption. Distribution runs through direct OEM relationships for edge hardware and hyperscale cloud marketplaces for API consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in Asia-Pacific image recognition hinge on algorithmic efficiency gains that reduce per-inference compute costs and premium-tier shifts toward compliance-integrated solutions. Edge deployment specialization and modular transparency engineering represent the dominant value-capture mechanisms.
For Market Incumbents: Deepen government contracting relationships in Japan and China to defend against cloud hyperscaler encroachment. Invest in algorithmic transparency documentation capabilities to meet METI audit requirements. Prioritize backward integration into GPU packaging partnerships with Taiwan foundries to secure accelerator supply. For New Entrants and Emerging Players: Capture Indonesian retail modernization white space through cloud-native API offerings requiring minimal infrastructure investment. Target underpenetrated traditional trade sectors in Surabaya and Jakarta with subscription-based customer analytics modules. Lead with rapid feature deployment velocity rather than solution ownership positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where engineering scarcity intersects with multi-jurisdiction compliance fragmentation. Long-term viability favors acquirers of edge-optimized neural architecture specialists with established government relationships. Watch MIIT data localization enforcement intensity as inflection indicator for infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Hardware-Software Integration | Sub-50-millisecond inference meets MIIT data sovereignty mandates in Chinese smart city deployments. |
| Algorithmic Transparency Engineering | METI audit documentation capabilities differentiate vendors in Japanese healthcare and financial services procurement. |
| Vision Transformer Architecture Migration | Japanese automotive suppliers adopt 200+ frames-per-second quality inspection exceeding convolutional network throughput. |
| Cloud API Platform Expansion | Metered inference pricing captures Southeast Asian mid-market retailers avoiding infrastructure capitalization. |
| GPU Supply Partnership Localization | Taiwan foundry relationships reduce landed cost exposure and accelerate deployment timelines. |
Study Parameters
Bottom-up deployment modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with smart city procurement officers, automotive quality engineering directors, retail technology leads, and cloud platform architects combined with secondary validation against MIIT cybersecurity filings, METI AI governance documentation, hyperscaler capex disclosures, and Taiwan semiconductor trade data. Triangulation between end-use demand signals and component supply constraints ensures cross-verified market sizing.
Historical trendline analysis across technology adoption curves, regulatory implementation timelines, and infrastructure investment patterns informs projection frameworks. Segmentation dimensions span deployment architecture, application vertical, technology tier, and national regulatory cluster. CAGRs derive from fitted growth curves adjusted for compliance friction coefficients and supply constraint elasticities. Edge computing penetration rates and cloud API consumption velocity serve as primary forecast inputs.
GPU supply disruption, regulatory enforcement divergence, and classical processing substitution are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding localization mandate implementation pacing and foundry capacity expansion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global 3D Imaging Market
Imaging
Middle East and Africa IP Camera Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
TDI Camera Market
Imaging
India CCTV Camera Market
Imaging
PET Scanners Market
Imaging
Global Flow Imaging Microscopy/Dynamic Image Analysis Market
Imaging
Camera Stabilizer Market
Imaging
Micro Computed Tomography Market
Imaging
CCD Image Sensors Market
Imaging
Photoacoustic Tomography Market
Imaging
Digital Image Processing Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Sub-Micrometer Computed Tomography Market
Imaging
Ultra-Wide Field Imaging Device Market
Imaging
Global 3D Camera Market