
 Middle East and Africa Outdoor LED Lighting Market | 2026-2036
Middle East and Africa Outdoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Outdoor LED Lighting Market Insights
Modular luminaire-plus-control bundling is pivoting how municipal buyers evaluate procurement, shifting total-cost-of-ownership calculations toward lifecycle metrics rather than upfront capex. Signify leverages its Interact platform to anchor smart-city deployments across Gulf markets. Osram GmbH competes through deep specialization in high-efficacy chip architectures for extreme-climate operation. BEKA Schréder dominates retrofit-led tenders across South African metros with locally configured heat-dissipation engineering.
Middle East and Africa outdoor LED lighting comprises solid-state semiconductor fixtures emitting directional visible light for exterior illumination, typically operating at correlated color temperatures between 2700K and 6500K with system efficacies exceeding 130 lumens per watt, engineered for thermal management in ambient conditions reaching 55°C. Street lights lead volume deployment as highway and arterial road electrification absorbs the largest share of public-sector energy efficiency budgets. Smart lighting control technology captures the fastest expansion trajectory as remote monitoring and adaptive dimming protocols migrate from pilot installations to standard municipal specifications.
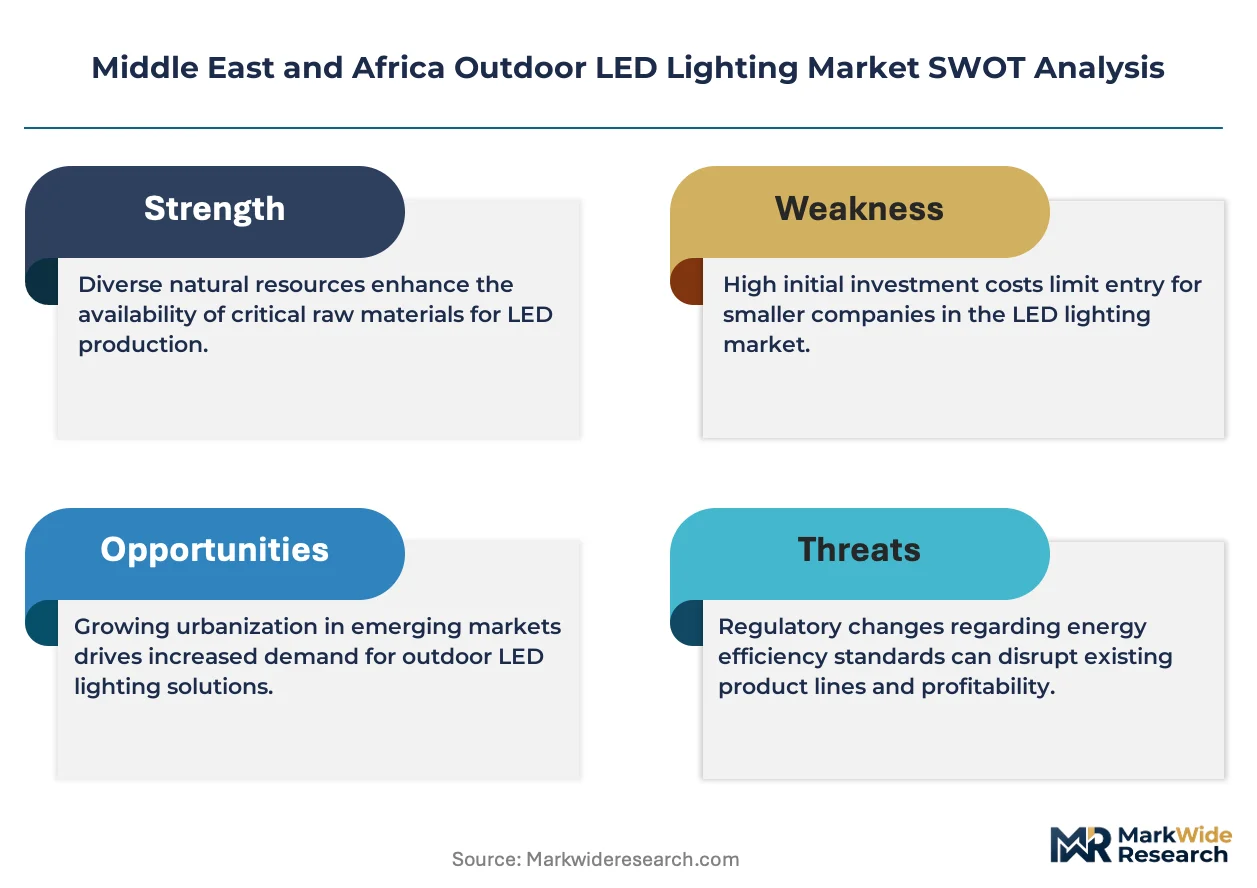
Regional energy regulators in Saudi Arabia, the UAE, and South Africa enforce minimum efficacy thresholds and local content requirements that filter market access for imported fixtures. SFDA technical conformity pathways and SASO energy performance labeling shape product certification timelines for manufacturers serving Gulf markets. Stakeholders must monitor how evolving smart-grid interoperability standards and carbon-accounting disclosures recalibrate procurement scoring weights in upcoming national infrastructure plans.
Market Dynamics
Municipal procurement offices across Gulf Cooperation Council states now bundle luminaire hardware with centralized control platforms, compressing vendor selection criteria from upfront capex to fifteen-year lifecycle cost modeling. This shift privileges suppliers with integrated software stacks over pure-play fixture manufacturers.
Growth Catalysts
- SASO energy performance labeling:Saudi Arabia's mandatory efficacy thresholds for imported luminaires filter low-performance competitors from tender participation, accelerating replacement cycles in Riyadh and Jeddah municipal fleets.
- Smart-city platform migration:Urban operating systems in Dubai and Abu Dhabi require interoperable lighting nodes as edge-computing infrastructure, pulling demand toward connected LED architectures with embedded sensors.
- Heat-dissipation engineering:Advances in thermal interface materials enable sustained lumen maintenance above 55°C ambient conditions, unlocking deployment in Saudi Arabia's interior desert corridors previously restricted to metal halide.
Market Restraints
- Driver IC supply concentration:Power semiconductor fabrication for LED drivers concentrates in East Asian foundries, exposing MEA project timelines to shipping volatility and tariff exposure at Gulf ports.
- SFDA technical conformity timelines:Saudi Arabia's certification pathway for electromagnetic compatibility testing extends product registration by four to six months, freezing inventory deployment for European and Asian manufacturers.
- Copper and aluminum price volatility:Housing and heat-sink raw material costs swing with London Metal Exchange benchmarks, compressing margin buffers for fixed-price municipal tenders common in South African metros.
Strategic Opportunities
- Nigeria's unpenetrated federal highway network:West Africa's largest economy maintains minimal LED conversion across its 35,000-kilometer arterial road system, presenting first-mover advantage for vendors with local assembly partnerships.
- Adaptive dimming protocol convergence:Integration of DALI-2 wireless with cellular IoT backhaul creates bundled service revenue streams beyond hardware sale, capturing recurring municipal budget allocations in UAE emirates.
- Egypt's sovereign LED manufacturing incentives:New industrial zone tax holidays in the Suez Canal Economic Zone attract component localization for re-export to Sub-Saharan African markets with weaker technical regulatory capacity.
Industry Challenges
- Embedded firmware cybersecurity certification:Gulf Cooperation Council municipalities now require IEC 62443 conformity for networked lighting controls, extending engineering validation cycles and demanding scarce industrial cybersecurity auditing capacity.
- Legacy sodium vapor base compatibility:Retrofit projects in South African townships must accommodate irregular pole spacing and degraded electrical infrastructure, complicating photometric design and installation labor estimation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Outdoor LED Lighting Market |
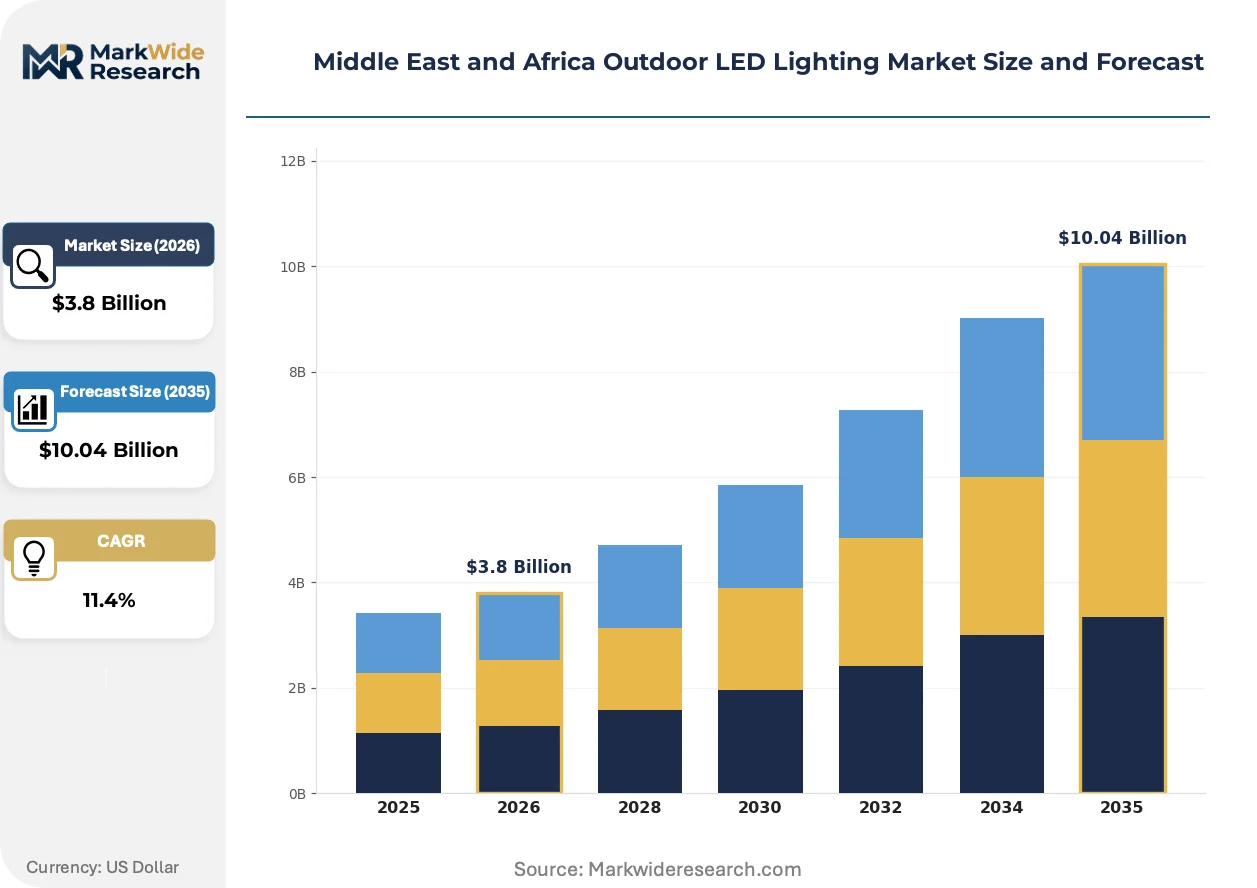
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Flood Lights, High Bay Lights, Decorative Lights Installation Type: New Installation, Retrofitting, Renovation, Temporary Installation End User: Municipalities, Commercial, Industrial, Residential Control Technology: Smart Lighting, Remote Monitoring, Dimming Control, Traditional Lighting |
| Companies Covered | Signify (Philips Lighting), Osram GmbH, Acuity Brands, Inc., Hubbell Incorporated, Zumtobel Group, Eaton Corporation plc, Fagerhult Group, BEKA Schréder, Al Nasser Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Outdoor LED Lighting Market Trends and Innovations
Product specification authority is migrating from electrical contractors to municipal IT departments as lighting infrastructure becomes a data collection layer. This reclassification alters vendor qualification criteria and contract structures.
Li-Fi optical wireless communication embedded in street luminaires is rewriting last-mile connectivity economics for dense urban corridors. Dubai's Roads and Transport Authority pilots this architecture for traffic signal synchronization without spectrum licensing fees. The technology is compressing the addressable market for separate small-cell 5G deployments in downtown districts.
SASO's 2024 update to technical regulation for lighting products introduced mandatory flicker metrics and unified glare rating thresholds. Fixture manufacturers serving Saudi Arabia must redesign optical systems and resubmit test reports, delaying new product introductions by two quarters. High-bay industrial applications face the steepest compliance cost due to lumen density requirements.
Municipal buyers in Abu Dhabi and Johannesburg now unbundle installation from supply contracts, awarding maintenance and control platform subscriptions to separate specialist integrators. This fragmentation favors pure-play software vendors over traditional luminaire houses. The shift is most visible in smart-city precinct developments where twenty-year service-level agreements replace conventional warranty terms.
Middle East and Africa Outdoor LED Lighting Market Segmentation
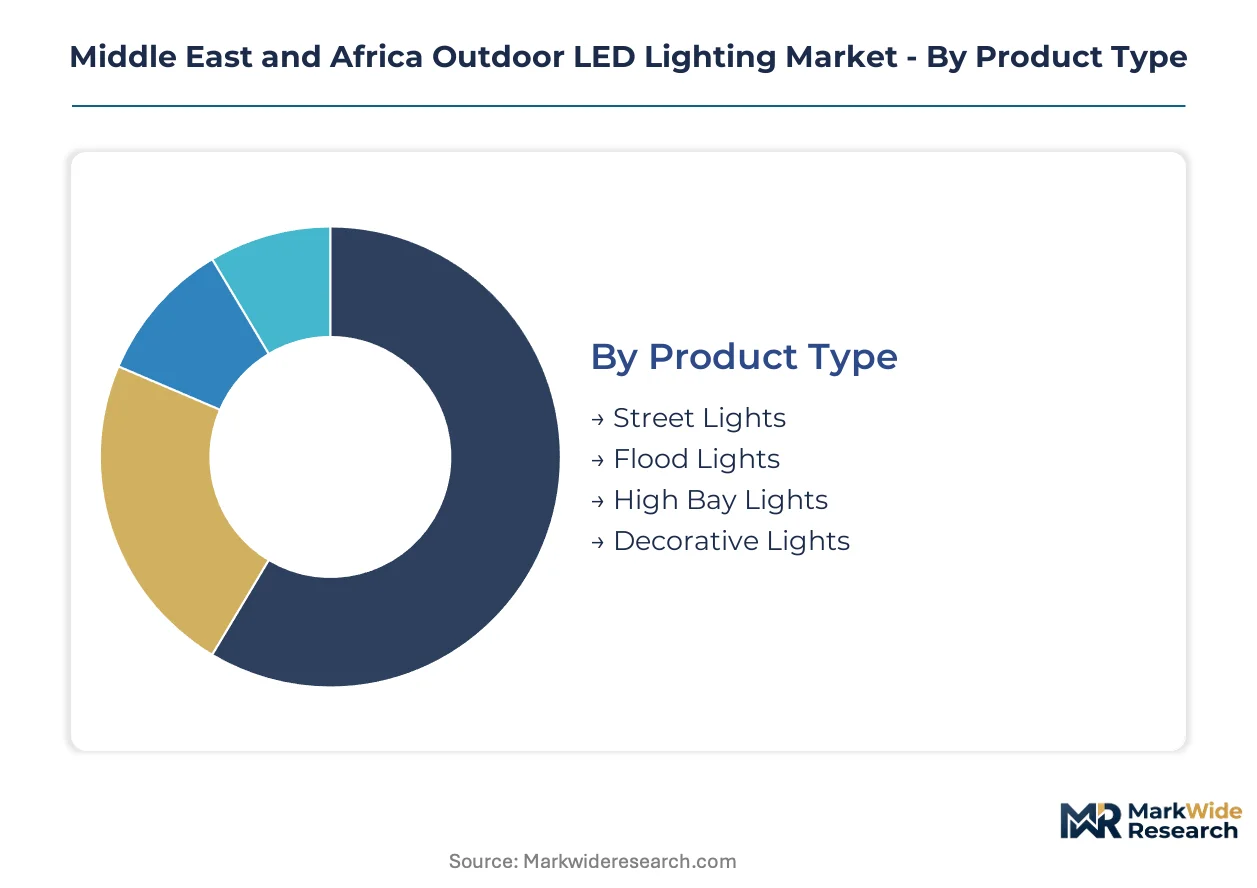
Procurement patterns across Middle East and Africa outdoor LED lighting diverge sharply by installation context and buyer sophistication. Municipal specifications now bundle hardware with control platforms, collapsing traditional product boundaries into integrated system sales.
Product Type:
Supply concentration for thermal management components favors vendors with in-house heat-sink fabrication serving extreme-climate corridors.
- Street Lights:Directional luminaires operating at 130+ lumens per watt with die-cast aluminum housings engineered for 55°C ambient operation. Saudi Arabia's SASO efficacy mandates and South Africa's retrofit-led municipal tenders absorb the dominant share of regional production capacity.
- Flood Lights:Asymmetric beam distribution fixtures for perimeter security and sports venue illumination. UAE commercial developments and Qatar infrastructure projects concentrate demand for high-lumen packages with marine-grade finish specifications.
- High Bay Lights:Industrial-grade fixtures with high-temperature LED arrays for warehousing and logistics facilities. Egypt's Suez Canal Economic Zone manufacturing incentives attract assembly localization for Sub-Saharan re-export.
- Decorative Lights:Ornamental post-top and bollard luminaires for urban beautification programs. Dubai and Abu Dhabi smart-city precincts specify DALI-2 wireless compatibility as standard.
Street lights absorb the bulk of installed capacity; smart-compatible flood lights are expanding most quickly.
Installation Type:
Cost tier stratification separates turnkey project awards from component-only supply, with financing availability determining buyer access to each tier.
- New Installation:Greenfield deployments on expanded road networks and master-planned urban districts. Saudi Arabia's Neom and Red Sea Project developments specify connected LED nodes as edge-computing infrastructure from initial commissioning.
- Retrofitting:LED replacement of legacy sodium vapor and metal halide fixtures on existing poles. South African metros dominate this segment due to constrained capital budgets favoring partial upgrade cycles over full replacement.
- Renovation:Comprehensive electrical infrastructure rebuilds accommodating altered pole spacing and upgraded supply capacity. Nigerian federal highway programs require renovation-grade solutions for degraded distribution networks.
- Temporary Installation:Rapid-deployment solar-hybrid luminaires for construction sites and emergency response. UAE event infrastructure and humanitarian corridor lighting in East Africa drive intermittent demand.
Retrofitting commands the largest project pipeline; new installation contracts carry the steepest margin premiums.
End User:
Volume concentration in municipal procurement compresses pricing for standardized specifications while commercial buyers absorb customization premiums.
- Municipalities:Public-sector street and highway lighting authorities with fifteen-year lifecycle cost evaluation criteria. Gulf Cooperation Council urban operating systems now require IEC 62443 cybersecurity conformity for networked controls.
- Commercial:Retail, hospitality, and office campus developers specifying aesthetic and brand-aligned illumination. Johannesburg and Cape Town private sector projects unbundle installation from supply, favoring specialist integrators.
- Industrial:Mining, petrochemical, and logistics facility operators demanding explosion-proof and high-vibration tolerance. Saudi Arabia's interior industrial cities specify thermal interface material upgrades for sustained lumen maintenance.
- Residential:Gated community and villa compound developers in UAE and Saudi Arabia. This segment trails in connected lighting adoption due to fragmented homeowner association decision structures.
Municipalities absorb the bulk of installed capacity; industrial end users are climbing the fastest on mining corridor electrification.
Control Technology:
Margin distribution concentrates in software-layer subscriptions as hardware commoditization accelerates across basic illumination functions.
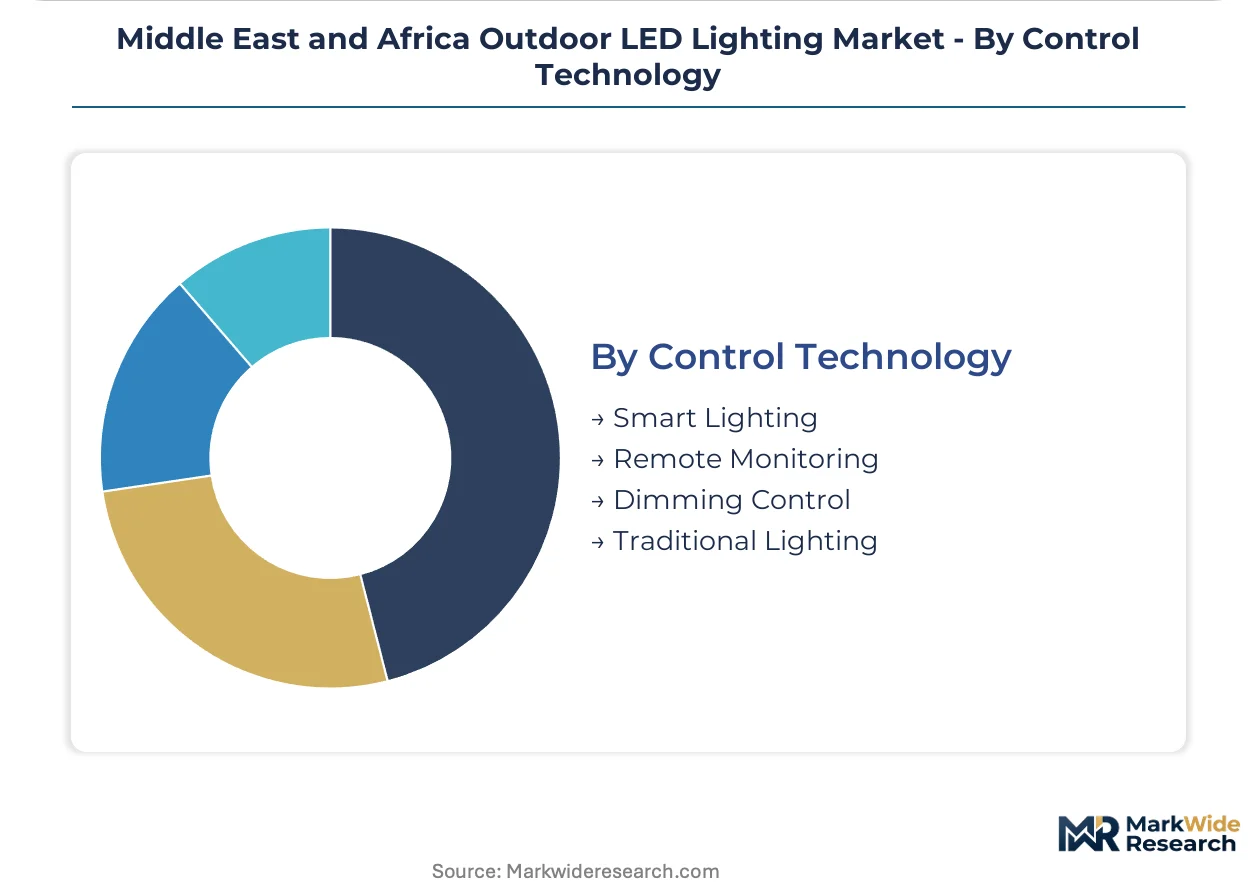
- Smart Lighting:Networked luminaires with embedded sensors and cellular IoT backhaul for adaptive operation. Dubai's Roads and Transport Authority pilots Li-Fi optical wireless for traffic synchronization without spectrum licensing.
- Remote Monitoring:Cloud-based asset management platforms with predictive maintenance algorithms. Abu Dhabi municipal contracts now award twenty-year service-level agreements separate from hardware supply.
- Dimming Control:DALI-2 and 0-10V protocols for scheduled lumen reduction during off-peak hours. South African load-shedding response programs mandate dimming compatibility for grid stability participation.
- Traditional Lighting:Standalone fixtures without network connectivity or adaptive functionality. This segment persists in Nigerian and Kenyan markets with weaker technical regulatory capacity and constrained IT infrastructure.
Traditional lighting retains the largest installed base; smart lighting architectures gain share fastest on Gulf smart-city platform migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption of outdoor LED lighting across the Middle East and Africa substantially exceeds regional manufacturing capacity, with Gulf Cooperation Council states importing finished luminaires from European and East Asian suppliers while Egypt and South Africa anchor limited local assembly operations. This production deficit shapes procurement timelines and compliance strategies throughout the analysis window.
Saudi Arabia
Riyadh and Jeddah municipal fleets drive replacement cycles for legacy sodium vapor infrastructure, with SASO energy performance labeling filtering low-efficacy competitors from tender participation. The Saudi Standards, Metrology and Quality Organization mandates minimum lumen-per-watt thresholds and electromagnetic compatibility certification that extends product registration timelines. NEOM and the Red Sea Project developments in the northwest specify connected LED nodes as edge-computing infrastructure from initial commissioning.
United Arab Emirates
Dubai's Roads and Transport Authority pilots Li-Fi optical wireless embedded in street luminaires for traffic signal synchronization without spectrum licensing fees. MOHAP technical conformity pathways govern product registration for Abu Dhabi and Dubai municipal contracts, with twenty-year service-level agreements now replacing conventional warranty terms. Abu Dhabi smart-city precincts unbundle installation from supply contracts, awarding maintenance subscriptions to specialist integrators.
South Africa
Johannesburg, Cape Town, and Durban metros dominate retrofit-led procurement due to constrained capital budgets favoring partial upgrade cycles over full replacement. The South African Bureau of Standards enforces efficacy and safety labeling that shapes import flows from European and Chinese suppliers. BEKA Schréder anchors locally configured heat-dissipation engineering for township retrofits accommodating irregular pole spacing and degraded electrical infrastructure.
Egypt
The Suez Canal Economic Zone manufacturing incentives attract component localization for re-export to Sub-Saharan African markets with weaker technical regulatory capacity. Cairo and Alexandria municipal authorities specify mid-tier efficacy packages for arterial road electrification. New industrial zone tax holidays target LED driver and thermal management component assembly, positioning Egypt as a supply hub for Nigerian and Kenyan procurement offices.
Nigeria
Lagos and Abuja federal highway programs present first-mover advantage for vendors with local assembly partnerships across the 35,000-kilometer arterial road system. The country's national standards body maintains minimal mandatory efficacy enforcement, preserving demand for traditional non-connected fixtures. Port Harcourt and Kano industrial clusters absorb high-bay LED deployment for warehousing and logistics facilities with limited smart-control integration.
Middle East and Africa Outdoor LED Lighting Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, with the vendor base stratifying between integrated platform providers and component-centric fabricators. Market structure concentrates in three archetypes: multinational lighting groups with software-layer subscriptions, regional specialists with climate-adapted thermal engineering, and emerging local assemblers serving price-sensitive tenders. Competitive moves center on strategic partnerships for control platform integration and backward integration into driver IC sourcing to mitigate supply volatility.
Among European-headquartered lighting groups, Signify and Osram GmbH occupy positions anchoring premium-tier municipal specifications across Gulf markets, with Signify representing the integrated platform archetype through its Interact smart-city deployments and Osram exemplifying deep specialization in high-efficacy chip architectures. BEKA Schréder sits within the regional specialist tier, with its South African base supporting locally configured engineering for extreme-climate operation and retrofit-led tender participation.
| Leading Market Players |
|---|
| Signify (Philips Lighting) |
| Osram GmbH |
| Acuity Brands, Inc. |
| Hubbell Incorporated |
| Zumtobel Group |
| Eaton Corporation plc |
| Fagerhult Group |
| BEKA Schréder |
| Al Nasser Group |
| Others |
Pricing and Supply Chain Analysis
Modular luminaire-plus-control bundling simultaneously compresses hardware margins and concentrates procurement leverage among platform-integrated vendors, reshaping cost economics across Gulf municipal tenders and South African retrofit programs. This structural shift privileges suppliers with captive software stacks while exposing pure-play fixture manufacturers to margin erosion in standardized specifications.
Pricing Analysis
Margin tightening in mid-tier municipal contracts reflects SASO efficacy mandates and lifecycle cost evaluation criteria compressing upfront hardware premiums. Three-tier pricing structure across premium smart-city platforms, standard connected fixtures, and economy non-networked luminaires separates vendors by certification depth and control integration. Cost-down pressure on economy tiers accelerates because Nigerian and Kenyan procurement offices prioritize lowest first-cost over operational efficiency. Commercial developers in Dubai and Johannesburg absorb the least price sensitivity, valuing aesthetic customization and twenty-year service-level agreements.
Supply Chain Analysis
Freight cost volatility from East Asian semiconductor foundries to Gulf ports exposes MEA project timelines to shipping rate swings and tariff uncertainty at Jebel Ali and Dammam terminals. Driver IC fabrication concentrates in Taiwan, South Korea, and China, while die-cast aluminum housing production draws from Chinese and Turkish metalworking clusters. Single-source vulnerability in power semiconductor supply feeds from concentrated East Asian foundry capacity. Distribution runs through Dubai-based trading houses for Gulf markets and Johannesburg logistics hubs for Sub-Saharan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform-integrated vendors as SASO cybersecurity mandates and smart-city interoperability requirements force smaller fixture specialists into subordinate supplier roles.
For Market Incumbents: Acquire embedded firmware engineering teams to satisfy IEC 62443 certification requirements now mandatory across Abu Dhabi and Riyadh municipal specifications. Defensive positioning demands backward integration into driver IC sourcing to mitigate Taiwan foundry concentration risk, alongside capacity expansion in Egypt's Suez Canal Economic Zone to capture Sub-Saharan re-export flows. For New Entrants and Emerging Players: Nigerian federal highway authorities present the most penetrable buyer archetype, with 35,000 kilometers of arterial roads maintaining minimal LED conversion and weak efficacy enforcement. Local assembly partnerships in Lagos or Port Harcourt unlock access to renovation-grade tenders addressing degraded electrical infrastructure. A go-to-market angle emphasizing solar-hybrid rapid deployment for construction and emergency response segments bypasses entrenched municipal procurement relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking smart-city platform capabilities. Long-term viability hinges on software-layer recurring revenue rather than hardware commoditization. Acquisition target archetypes include regional thermal engineering specialists with climate-adapted heat-dissipation IP. The signal to watch is DALI-2 wireless protocol adoption rates across UAE emirate procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Signify's Interact deployments across Gulf markets demonstrate control-layer margin capture. |
| Backward Integration | Captive driver IC sourcing insulates against East Asian foundry volatility and tariff exposure. |
| Geographic Expansion | Egyptian industrial zone localization positions vendors for Nigerian and Kenyan procurement access. |
| Certification Investment | IEC 62443 cybersecurity conformity unlocks Abu Dhabi twenty-year service-level agreement awards. |
| Joint Venture | Local assembly partnerships in Lagos bypass import logistics constraints for West African highway programs. |
Research Methodology
Multi-period observation of municipal tender awards, efficacy mandate implementation timelines, and smart-city platform procurement specifications anchored the trend analysis, supplemented by interviews with municipal lighting procurement officers, thermal engineering specialists at regional fixture manufacturers, smart-city platform integrators, and EPC contractors active in Gulf infrastructure developments. Secondary validation drew from SASO technical regulations, MOHAP conformity pathways, South African Bureau of Standards labeling requirements, customs import data for luminaire shipments through Dubai and Johannesburg ports, and municipal budget disclosures across Riyadh, Dubai, and Johannesburg. Bottom-up project pipeline tracking triangulated against top-down energy efficiency program targets.
Input-output matrices modeled luminaire deployment volumes against correlated color temperature specifications, control technology penetration rates, and installation type splits across new construction, retrofit, and renovation categories. Segmentation dimensions included product type, installation context, end-user sophistication tier, and control architecture complexity. CAGRs derived from logistic diffusion curves fitted to smart-city platform adoption patterns and regulatory mandate phase-in schedules. Industry-specific forecast inputs incorporated thermal interface material cost trajectories and LED efficacy improvement curves.
Revisions become necessary when Gulf Cooperation Council cybersecurity standards tighten beyond current IEC 62443 baselines, when East Asian semiconductor supply disruptions extend procurement timelines, or when copper and aluminum price volatility shifts municipal tender evaluation criteria. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Mexico LED Lighting Market
LED
Dot-Matrix LED Displays Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
China LED Market
LED
Europe Outdoor LED Lighting Market
LED
LED Tube Market
LED
Gan Substrate Market
LED
France Outdoor LED Lighting Market
LED
LED High Bay Drivers Market
LED
Thailand LED Market
LED
GCC LED Lighting Market
LED
UK Indoor LED Lighting Market
LED
Brazil LED Market
LED
Smart LED Indoor Signage Market
LED
LED Lighting Market
LED
Bluetooth LED Bulb Market