
 Global Thermal Imager Market | 2026-2036
Global Thermal Imager Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermal Imager Market Outlook
China's domestic sensor foundry expansion is reshaping component economics for the thermal imager industry. FLIR Systems leverages vertical integration across detector design and camera assembly to sustain margin control in defense contracts. Leonardo anchors European supply through its Naples-based electro-optics campus, while Hangzhou Hikvision Digital Technology dominates commercial volume with integrated security platform distribution.
A thermal imager converts infrared radiation emitted by objects into visible images through focal plane arrays operating across spectral bands from 7-14 micrometers. Uncooled vanadium oxide microbolometers now achieve thermal sensitivities below 50 millikelvin, enabling predictive maintenance in electrical substations and process plants. Handheld devices lead commercial penetration due to portability demands in building inspection and electrical maintenance workflows, while dual-sensor architectures are gaining fastest in surveillance applications where visible-infrared fusion reduces false alarms. Fixed installations retain premium pricing in oil and gas flare monitoring and perimeter security.
FDA 510(k) clearance requirements govern medical thermal imaging devices in the United States, while EU AI Act provisions are beginning to classify autonomous thermal analytics systems in surveillance contexts. REACH restrictions on lead-based solder materials are forcing detector packaging redesigns across European supply chains. Stakeholders must weigh uncooled versus cooled detector commitments against evolving export control classifications under Wassenaar Arrangement updates.
Market Dynamics
Uncooled microbolometer sensor technology is compressing cost structures across commercial thermal imaging applications, enabling volume deployment in building inspection and predictive maintenance workflows previously served by premium cooled detector systems.
Growth Catalysts
- EU AI Act surveillance classification:Autonomous thermal analytics systems face new compliance tiers in European security deployments, accelerating demand for certified edge-processing modules that meet algorithmic transparency requirements.
- Electrical substation predictive maintenance:Utility operators in the United States deploy vanadium oxide microbolometer arrays to detect thermal anomalies in transmission infrastructure before failure events occur.
- Wassenaar Arrangement export control updates:Evolving dual-use classifications for focal plane arrays are concentrating advanced detector production in domestic foundries across NATO member states.
Market Restraints
- Indium antimonide and mercury cadmium telluride input volatility:Cooled detector fabrication depends on scarce semiconductor materials subject to supply concentration in Chinese refining operations.
- REACH lead-free solder mandates:European detector packaging redesigns impose qualification delays and yield losses during transition to compliant interconnect materials.
- Visible-light camera fusion substitution:Low-light CMOS sensors with near-infrared sensitivity capture marginal thermal imaging applications in cost-constrained security installations.
Strategic Opportunities
- India industrial safety mandate expansion:Factory inspection regulations under the Directorate General Factory Advice and Labour Institutes are creating first-time thermal imager demand in process manufacturing.
- Medical thermography FDA 510(k) pathway:Subcutaneous vascular mapping and fever screening applications await streamlined clearance protocols for software-enhanced thermal diagnostic devices.
- Drone-mounted inspection services:Agricultural and photovoltaic survey operators in Brazil adopt thermal payload rental models rather than capital equipment ownership.
Industry Challenges
- Microbolometer design engineering scarcity:Foundry-level MEMS fabrication expertise concentrates in defense-aerospace supply chains, constraining commercial product development pipelines.
- Multi-spectral calibration complexity:Visible-infrared fusion architectures require algorithmic alignment across disparate sensor modalities, extending integration timelines for surveillance system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermal Imager Market |
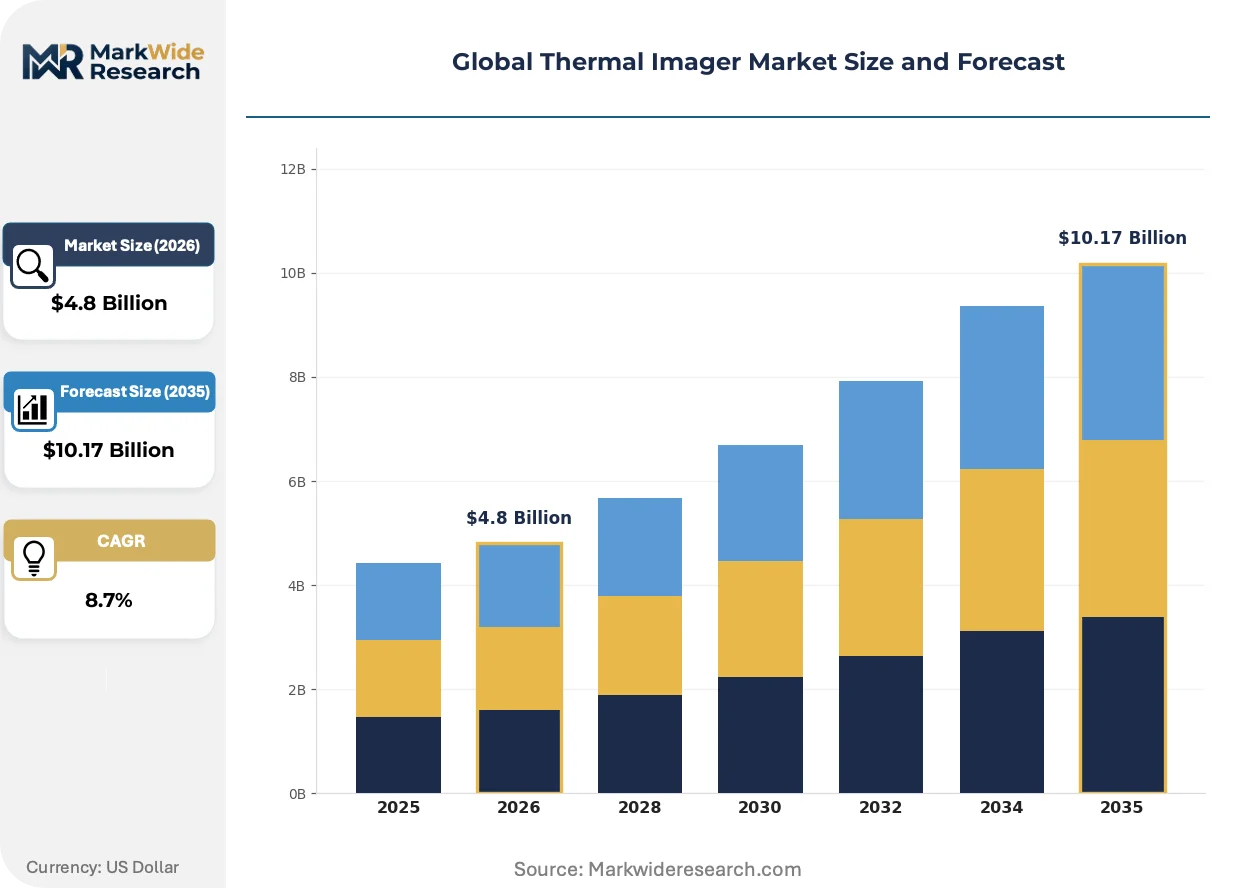
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fixed, Mounted, Portable Technology: Infrared, Long-Wave, Short-Wave, Dual-Sensor Application: Building Inspection, Electrical Maintenance, Surveillance, Fire Detection End User: Construction, Oil & Gas, Manufacturing, Law Enforcement |
| Companies Covered | FLIR Systems, Leonardo, Teledyne FLIR, Hangzhou Hikvision Digital Technology, Fluke Corporation, L3Harris Technologies, BAE Systems, Testo, RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermal Imager Market Strategic Shifts
Sensor fusion architectures and edge AI processing are redefining thermal imaging value propositions, shifting competitive advantage from raw detector performance to integrated analytics and workflow automation.
Vanadium oxide microbolometer arrays with sub-50 millikelvin noise-equivalent temperature difference are digitizing predictive maintenance protocols in electrical utilities and process plants. Maintenance teams at American transmission operators and German chemical complexes adopt handheld platforms that auto-flag thermal anomalies without specialist interpretation. The technology is digitizing inspection documentation, compressing decision cycles from days to hours and displacing scheduled manual rounds with condition-triggered interventions.
REACH restrictions on lead-based solder materials are forcing detector packaging redesigns across European supply chains. German and Italian electro-optics manufacturers face qualification delays and yield compression during transition to compliant interconnect materials. Medical device and industrial safety segments in the European Union absorb extended certification timelines as packaging suppliers recertify thermal cycling reliability under new metallurgy constraints.
Equipment-as-a-service models are penetrating commercial thermal imaging distribution in North American building inspection and electrical contracting verticals. Independent service providers and regional distributors displace traditional capital sales with monthly subscription tiers that bundle hardware, calibration, and cloud analytics access. The shift concentrates most visibly in California and Texas metropolitan markets where contractor labor mobility favors operational expenditure over balance-sheet equipment ownership.
Global Thermal Imager Market Segmentation
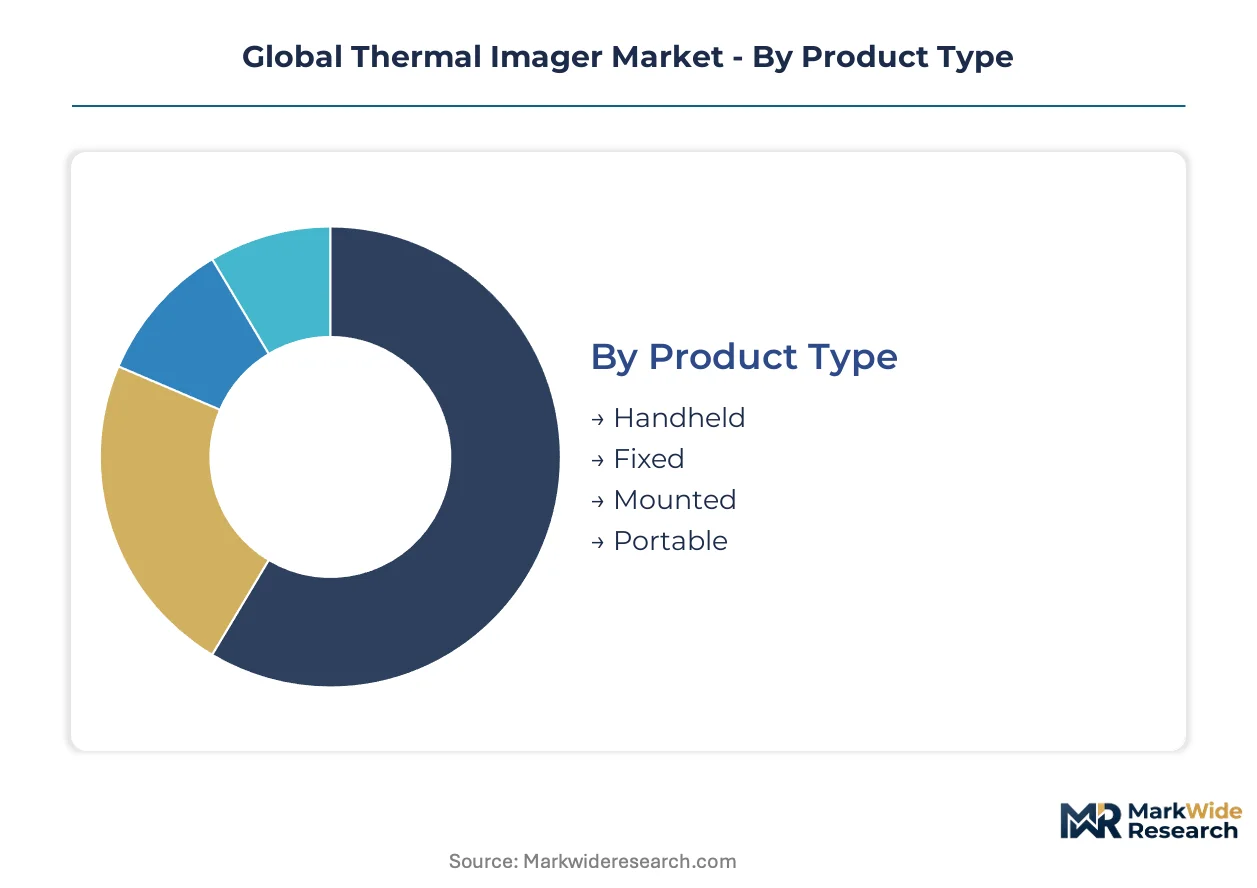
Thermal imager procurement cycles vary dramatically across form factors and use cases, from rapid replacement schedules in handheld electrical maintenance to decade-long deployments in fixed perimeter security. Understanding these velocity differentials helps suppliers align inventory, service contracts, and R&D roadmaps to actual consumption patterns rather than aggregated demand signals.
Product Type:
Handheld units turn over fastest at 2-3 year cycles driven by field damage and battery degradation, while fixed installations persist 10-15 years with only detector upgrades.
- Handheld:Vanadium oxide microbolometer cores power pistol-grip and smartphone-attachment formats weighing under 500 grams. Electrical contractors in Texas and California metro markets favor these for rapid thermal anomaly documentation during residential and commercial energy audits. The segment absorbs the highest absolute unit volumes but also experiences the steepest price erosion as Chinese sensor foundries commoditize 320x240 resolution arrays.
- Fixed:Gimbal-mounted and mast-mounted installations with sealed environmental housings dominate oil and gas flare monitoring and critical infrastructure perimeter defense. German chemical complexes along the Rhine corridor and Saudi Aramco processing facilities deploy these for continuous 24/7 thermal surveillance with integrated pan-tilt-zoom actuators. Procurement cycles extend to 10-15 years with mid-life detector refresh programs.
- Mounted:Vehicle-dashboard and helmet-rail configurations serve military dismounted soldier modernization kits and first responder thermal navigation. NATO member states drive specification requirements through defense procurement offices.
- Portable:Briefcase-sized systems with tripod mounting options bridge handheld convenience and fixed-installation stability for building thermography consultants. These units see seasonal demand spikes aligned with energy efficiency rebate program windows in the United States and European Union.
Handheld devices anchor the volume base while dual-sensor mounted configurations gain share at the steepest rate in defense and public safety procurement.
Technology:
Cost tiering separates mature uncooled microbolometer architectures from premium cooled indium antimonide and mercury cadmium telluride systems serving military and scientific applications.
- Infrared:Broad-spectrum thermal detection spanning 7-14 micrometers constitutes the commercial mainstream. Uncooled vanadium oxide and amorphous silicon microbolometers from Chinese and American foundries saturate building inspection and electrical maintenance markets. REACH lead-free solder mandates force European packaging redesigns that temporarily compress margins.
- Long-Wave:Atmospheric transmission optimization at 8-12 micrometers enables extended-range surveillance in humid climates. Brazilian agricultural operators deploy long-wave drone payloads for irrigation system leak detection across soybean and sugarcane estates.
- Short-Wave:Silicon-based detector sensitivity at 0.9-1.7 micrometers serves high-temperature process monitoring above 300°C where mid-wave and long-wave sensors saturate. Steel mills in India and glass manufacturing facilities in Italy specify short-wave systems for furnace and molten material inspection.
- Dual-Sensor:Visible-infrared fusion architectures combine thermal cores with low-light CMOS imagers for reduced false-alarm rates in security analytics. EU AI Act algorithmic transparency requirements are accelerating demand for certified edge-processing modules in this segment.
Infrared technology commands the installed base while dual-sensor architectures expand most quickly in surveillance and defense applications.
Application:
Customer workflow integration depth varies from standalone thermal documentation to embedded predictive maintenance systems triggering automated work orders.
- Building Inspection:Energy audit and moisture intrusion detection drive residential and commercial construction verticals. American utility rebate programs in California, New York, and Massachusetts subsidize thermal imaging assessments for building envelope verification.
- Electrical Maintenance:Substation transformer and switchgear thermal anomaly detection prevents catastrophic failures in transmission networks. FERC reporting requirements and utility insurance mandates in the United States accelerate deployment of vanadium oxide microbolometer arrays with auto-flag analytics.
- Surveillance:Perimeter security and border monitoring applications demand continuous operation with video analytics integration. German federal police and Italian port authorities specify dual-sensor systems with AI-powered threat classification.
- Fire Detection:Forest fire early warning and industrial facility hot spot monitoring leverage thermal sensitivity below 50 millikelvin. Australian rural fire services and Canadian provincial forest management agencies deploy fixed-mount systems with satellite telemetry backhaul.
Electrical maintenance anchors revenue stability while fire detection climbs the fastest on climate adaptation infrastructure spending.
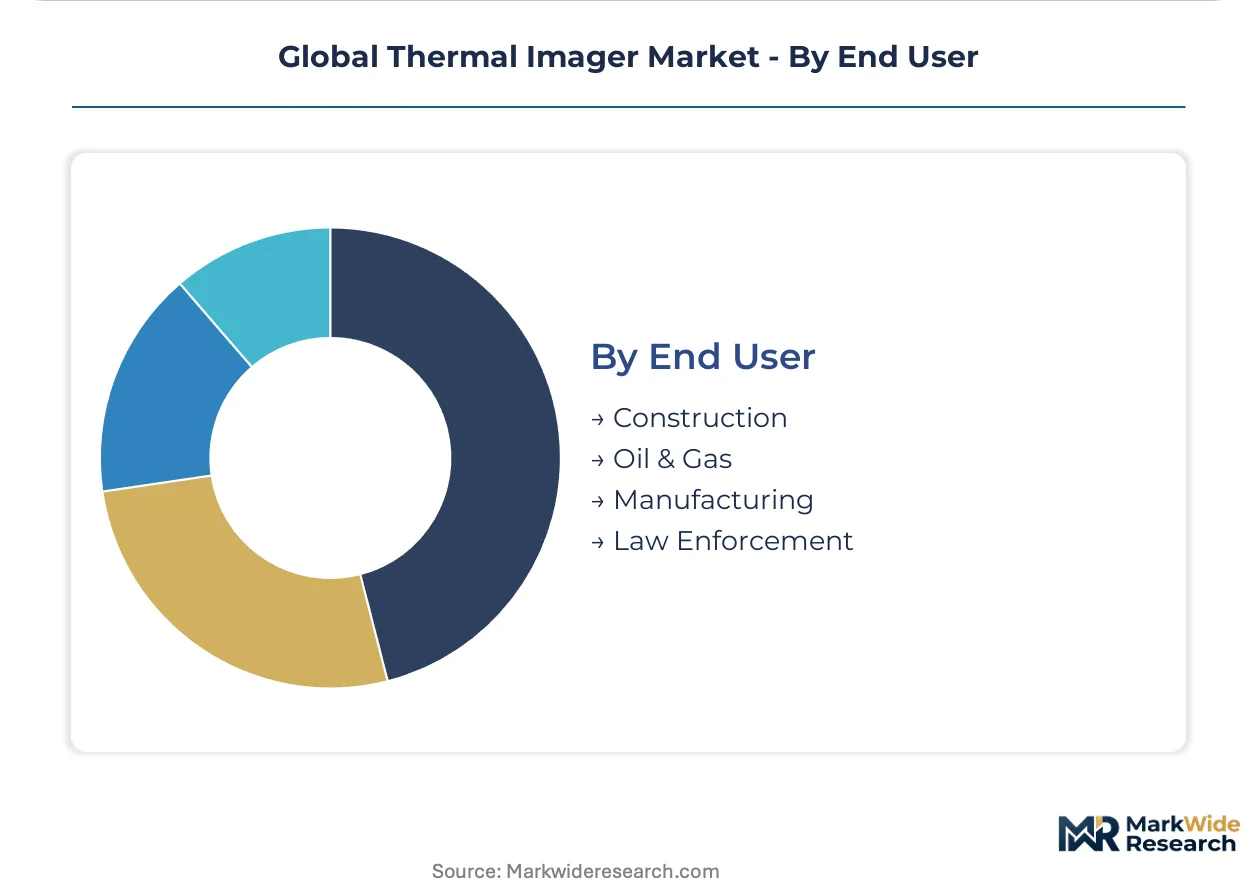
End User:
Procurement sophistication ranges from price-sensitive trade contractors to specification-driven defense procurement offices with multi-year qualification protocols.
- Construction:General contractors and specialized energy auditors purchase handheld units through distributor and equipment-as-a-service channels. Equipment-as-a-service subscription models concentrate in North American metropolitan markets where contractor labor mobility favors operational expenditure structures.
- Oil & Gas:Upstream exploration, midstream pipeline monitoring, and downstream refining operations specify explosion-protected fixed installations. Saudi Aramco, ADNOC, and American supermajors drive demand for continuous flare monitoring and leak detection systems.
- Manufacturing:Process plant predictive maintenance and quality control integration serve automotive, electronics, and food processing facilities. German automotive OEMs and Japanese electronics assemblers embed thermal inspection stations directly into production lines.
- Law Enforcement:Tactical operations, search and rescue, and perimeter surveillance drive mounted and handheld procurement. FBI, DEA, and major metropolitan police departments in the United States specify ruggedized systems with encrypted video output.
Manufacturing provides the most predictable replacement demand while law enforcement exhibits the steepest expansion trajectory on public safety modernization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese sensor foundries now supply the majority of microbolometer cores, while NATO defense procurement concentrates advanced cooled detector production in domestic facilities across member states.
United States
FERC reporting requirements and utility insurance mandates accelerate vanadium oxide microbolometer deployment across transmission networks. The IRA subsidizes thermal inspection equipment for grid modernization projects. Texas and California metropolitan markets concentrate equipment-as-a-service subscription models among electrical contractors.
Germany
REACH lead-free solder mandates force detector packaging redesigns across electro-optics supply chains. The EU AI Act algorithmic transparency requirements accelerate certified edge-processing module demand for surveillance applications. Chemical complexes along the Rhine corridor deploy fixed-mount systems for continuous thermal monitoring.
China
Domestic sensor foundry expansion reshapes component economics for uncooled microbolometer production. MIIT industrial safety standards mandate thermal inspection protocols in process manufacturing facilities. Hangzhou anchors commercial volume production through integrated security platform distribution networks.
India
Factory inspection regulations under the Directorate General Factory Advice and Labour Institutes create first-time thermal imager demand in process manufacturing. BIS certification requirements govern import and domestic production standards. Steel mills in Maharashtra and glass manufacturing in Gujarat specify short-wave systems for high-temperature monitoring.
Brazil
Agricultural and photovoltaic survey operators adopt thermal payload rental models rather than capital equipment ownership. ANVISA medical device regulations govern clinical thermography applications. Soybean and sugarcane estates deploy long-wave drone payloads for irrigation system leak detection.
Global Thermal Imager Market Competitive Environment
Defense-electronics conglomerates and commercial security platforms split the market into distinct procurement ecosystems. The vendor base organizes around three strategic archetypes: vertically integrated detector-to-camera assemblers, platform-integrated security distributors, and specialized test-and-measurement suppliers. Capacity expansion in Chinese sensor foundries and strategic partnerships for multi-spectral fusion algorithms represent the dominant competitive moves reshaping positioning.
Within the defense-aerospace tier, FLIR Systems and L3Harris Technologies occupy positions defined by captive detector design and NATO procurement relationships. Hangzhou Hikvision Digital Technology exemplifies the platform-integrated archetype, leveraging security ecosystem distribution for commercial volume penetration. Leonardo anchors European supply through its electro-optics campus, representing the regional defense-specialist model.
| Leading Market Players |
|---|
| FLIR Systems |
| Leonardo |
| Teledyne FLIR |
| Hangzhou Hikvision Digital Technology |
| Fluke Corporation |
| L3Harris Technologies |
| BAE Systems |
| Testo |
| RTX Corporation |
| Others |
Value Chain & Pricing Dynamics
Chinese sensor foundry concentration for vanadium oxide microbolometer wafers concentrates margin capture in the detector tier, while downstream camera assemblers compete on bundled analytics and service contracts. Cost compression from uncooled technology commoditization is shifting pricing power toward software-enhanced workflow solutions.
Pricing Analysis
REACH lead-free solder mandates dictate the pricing tier structure across European supply chains, forcing detector packaging redesigns that compress margins in mid-market segments. Three-tier pricing structure across premium, standard, and economy levels separates military-grade cooled systems with ITAR restrictions from commercial uncooled handhelds and entry-level smartphone attachments. Price differentiation rests on certification grade and volume scale, with FDA 510(k) cleared medical devices commanding substantial premiums over industrial inspection units. Cost compression in the 320x240 resolution tier is intensifying because Chinese foundries are flooding commercial channels with commodity microbolometer cores. Electrical contractors in North American metropolitan markets exhibit highest price sensitivity, while defense procurement offices demonstrate lowest sensitivity due to multi-year qualification protocols and performance specifications.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for focal plane array sourcing. Manufacturing concentrates in China for uncooled microbolometer wafers, the United States for cooled indium antimonide and mercury cadmium telluride detectors, and Germany for precision electro-optics assembly. Raw material dependencies draw from indium and tellurium refining operations, germanium substrates for long-wave optics, and lead-free solder alloys for European packaging compliance. Single-source vulnerability in Chinese rare earth processing creates strategic inventory requirements among NATO defense contractors. Distribution runs through platform-integrated security distributors for commercial volume, specialized test-and-measurement channels for industrial maintenance, and defense procurement offices for military systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermal imager market is experiencing high-growth disruption as uncooled microbolometer technology collapses cost barriers and EU AI Act surveillance classifications create new compliance-driven demand tiers.
For Market Incumbents: Build algorithmic transparency certification as a moat against commoditization pressure from Chinese sensor foundries. Deepen backward integration into edge-processing module design to capture AI Act compliance premiums in European surveillance deployments. Expand captive supply of vanadium oxide microbolometer cores through foundry partnerships in Taiwan and South Korea to reduce single-source exposure. Invest in multi-spectral calibration expertise as a defensive capability against low-light CMOS substitution in cost-constrained security installations. For New Entrants and Emerging Players: Establish a beachhead in Indian process manufacturing safety compliance, where Directorate General Factory Advice and Labour Institutes regulations are creating first-time thermal imager demand with limited incumbent presence. Target equipment-as-a-service subscription models in North American electrical contracting verticals, where contractor labor mobility favors operational expenditure structures over capital ownership. Pursue drone-mounted inspection service partnerships in Brazilian agricultural markets rather than competing on hardware sales alone. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed defense-electronics platforms that acquired thermal imaging divisions during prior consolidation waves. Five-to-ten year viability favors suppliers with captive detector design capabilities and NATO procurement relationships over pure-play commercial assemblers. Watch for Wassenaar Arrangement focal plane array reclassifications as a signal for domestic foundry investment inflection. Monitor FDA 510(k) clearance velocity for software-enhanced thermal diagnostic devices as an indicator of medical segment expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Spectral Sensor Fusion Development | EU AI Act algorithmic transparency requirements accelerate certified edge-processing module demand. |
| Equipment-as-a-Service Model Expansion | North American electrical contractors favor operational expenditure over balance-sheet equipment ownership. |
| Domestic Foundry Capacity Investment | Wassenaar Arrangement updates concentrate advanced detector production in NATO member states. |
| Medical Device Regulatory Pathway Navigation | FDA 510(k) streamlined clearance protocols await software-enhanced thermal diagnostic submissions. |
| Drone Payload Rental Platform Launch | Brazilian agricultural operators adopt thermal inspection services rather than capital equipment purchase. |
Study Parameters
Operator-level perspectives from utility maintenance directors, defense procurement officers, building inspection contractors, and electro-optics manufacturing engineers anchored the qualitative base for this study. Primary interviews with thermal imaging system integrators and distribution channel partners combined with secondary validation from SEC 10-K filings, FERC infrastructure spending disclosures, EU AI Act regulatory texts, and customs trade data. Bottom-up unit economics modeling triangulated against top-down market sizing from industrial safety mandate expansion trajectories.
Scenario-bracketing around Wassenaar Arrangement reclassification timing and REACH packaging transition delays bounded the forecast range across the analysis window. Segmentation dimensions modeled include product form factor, detector technology tier, application workflow integration depth, and end-user procurement sophistication. CAGRs derived from installed base turnover rates, replacement cycle compression, and greenfield penetration in industrial safety compliance markets. Forecast inputs incorporated vanadium oxide microbolometer cost curves and EU AI Act certification timeline assumptions.
Sensitivities concentrate around export control reclassifications, rare earth supply disruptions, and medical device regulatory pathway acceleration. Forecasts reflect documented assumptions on technology substitution rates and procurement budget allocation shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Phosphor Plate Scanners Market
Imaging
Handheld Retinal Scanners Market
Imaging
Digitizer Market
Imaging
North America Image Sensors Market
Imaging
Electron Microscopy Market
Imaging
On-Chip Color Filters Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
Global Ingaas Camera Market
Imaging
Global Optical Preclinical Imaging Market
Imaging
Latin America IP Camera Market
Imaging
Digital Imaging Market
Imaging
Industrial Computed Tomography Market
Imaging
Image Signal Processor and Vision Processor Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Wide Field Imaging Devices Market
Imaging
Automotive 3D Imaging Market