
 Lane Departure Warning (LDW) Market | 2026-2036
Lane Departure Warning (LDW) Market Size, Share, and Industry Trends Forecast 2026-2036
Lane Departure Warning (LDW) Market Foresight
Multi-source procurement for image sensors and edge-computing chipsets is broadening as Tier-1 suppliers diversify beyond single foundry relationships. Robert Bosch GmbH leverages in-house semiconductor capabilities to sustain vertical control over camera module production. Continental AG anchors its European supply position through dedicated manufacturing lines in Germany and Romania. Denso Corporation competes primarily across Asian OEM channels with specialized thermal-resistant sensor packaging for high-temperature engine-bay installations.
Lane Departure Warning (LDW) constitutes an active safety system that uses forward-facing cameras, typically operating at 30-60 frames per second with 1.2-2.0 megapixel resolution, to detect painted lane markings and trigger audible, haptic, or visual alerts when unintended drift occurs. The technology's primary commercial purpose is to reduce run-off-road and sideswipe collisions by intervening before the vehicle crosses lane boundaries. Camera-Based systems dominate current installations due to mature supply chains and declining CMOS sensor costs, while LIDAR-Based functionality represents the fastest-growing segment as automakers pursue redundancy for Level 3+ autonomy. Warning Alert functionality remains the largest revenue pool, though Lane Keep Assist commands premium pricing through its integration with electric power steering actuators.
The US NHTSA mandates electronic stability control and is advancing rulemaking for automatic emergency braking and lane-keeping on heavy trucks, directly expanding addressable fleet demand. European type-approval under UN ECE R79 governs Lane Keep Assist Systems performance thresholds, while the EU Green Deal's safety component provisions accelerate LDW fitment across new vehicle categories. Stakeholders must monitor whether NHTSA extends LDW mandates to passenger vehicles and how OEMs reconcile divergent US and European calibration standards for lane-marking recognition algorithms.
Market Dynamics
Camera-to-LIDAR sensor fusion is compressing the technology roadmap for heavy commercial vehicles, forcing Tier-1 suppliers to recalibrate R&D allocation between cost-optimized single-sensor systems and redundant multi-modal architectures demanded by emerging Level 3 autonomy standards.
Growth Catalysts
- UN ECE R79 type-approval:European mandates for Lane Keep Assist performance thresholds are compelling OEMs to standardize LDW fitment across passenger and commercial vehicle portfolios, expanding baseline addressable volume.
- Commercial fleet operators:North American heavy truck carriers are accelerating procurement ahead of anticipated NHTSA rulemaking for automatic emergency braking and lane-keeping systems, front-loading installation cycles.
- CMOS sensor cost curves:Declining unit economics for 2.0+ megapixel image sensors are enabling camera-based LDW penetration into economy vehicle segments previously served by ultrasonic-only parking assistance.
Market Restraints
- Semiconductor foundry concentration:Edge-computing chipsets for real-time lane detection rely on TSMC and Samsung advanced node capacity, creating allocation vulnerability during automotive demand surges.
- LIDAR component costs:Solid-state LIDAR modules for redundancy-compliant systems remain 8-12x the cost of camera-only alternatives, constraining adoption outside premium passenger segments.
- Algorithm calibration divergence:NHTSA and UN ECE maintain incompatible lane-marking recognition standards, forcing suppliers to maintain dual software branches and validation protocols.
Strategic Opportunities
- Aftermarket retrofit channels:Independent service garages in Germany and California are installing camera-based LDW kits on legacy commercial fleets to preempt regulatory compliance deadlines.
- EU Green Deal safety provisions:Extended vehicle category coverage under revised General Safety Regulation is creating first-fitment obligations for vans, buses, and specialty vehicles previously exempt.
- Thermal-resistant packaging:Convergence of LDW cameras with engine-bay proximity sensing for predictive maintenance is opening adjacent revenue pools in powertrain monitoring applications.
Industry Challenges
- Embedded vision engineering talent:Shortage of specialists in convolutional neural network optimization for automotive edge devices is extending development timelines for next-generation recognition algorithms.
- Functional safety certification:ISO 26262 ASIL-B compliance for camera-based LDW requires 18-24 month validation cycles, compressing product refresh windows against faster-moving consumer electronics sensor generations.
- Legacy fleet integration:Retrofitting CAN bus architecture compatibility into pre-2018 commercial vehicles demands custom harness engineering that erodes aftermarket margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lane Departure Warning (LDW) Market |
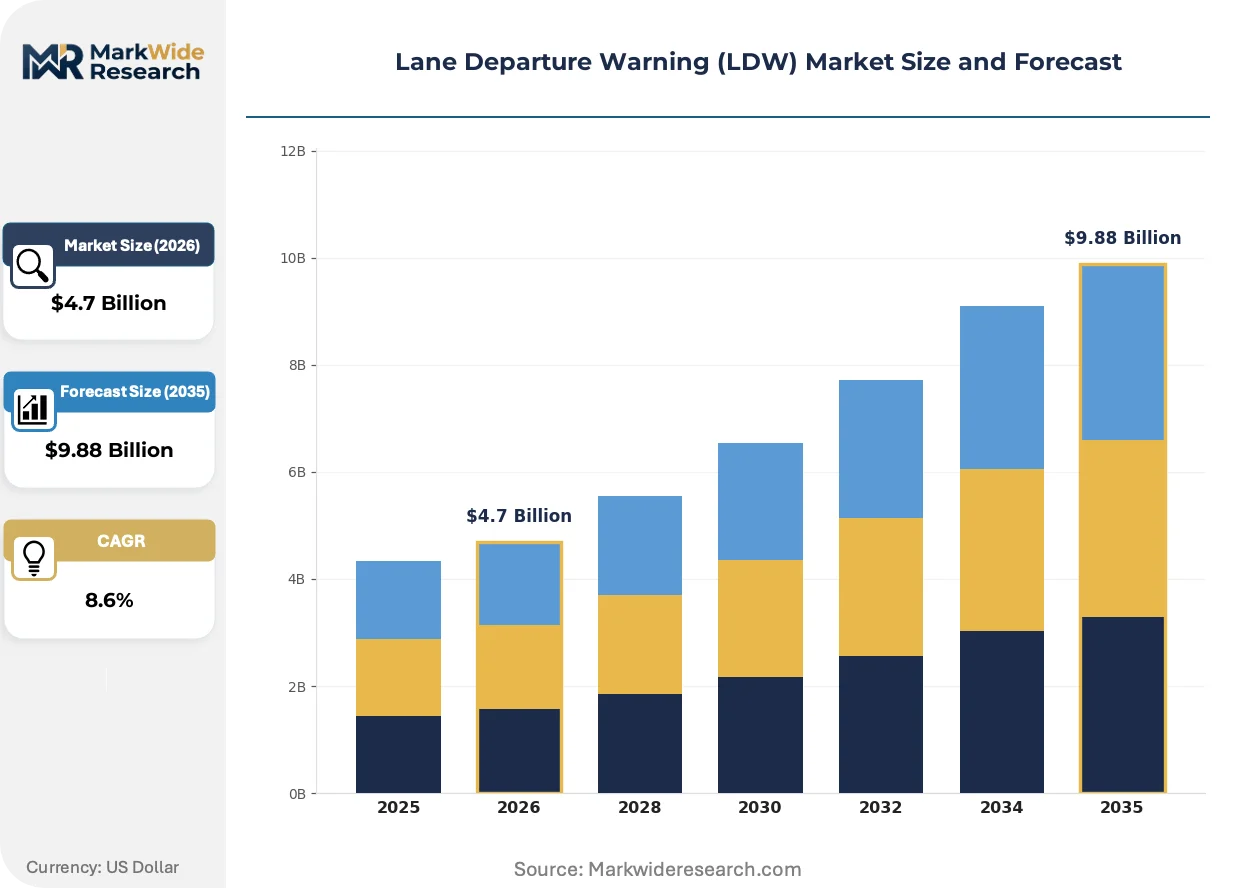
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Passenger Cars, Commercial Vehicles, Heavy Trucks, SUVs Technology: Camera-Based, Radar-Based, LIDAR-Based, Ultrasonic End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Functionality: Warning Alert, Automatic Steering, Lane Keep Assist, Driver Monitoring |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Valeo, Mobileye, Magna International, ZF Friedrichshafen AG, Aptiv, Autoliv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lane Departure Warning (LDW) Market Shifts & Advancements
Multi-modal sensor fusion is collapsing the traditional boundary between warning-only and assist-capable systems, compressing supplier differentiation strategies around software-defined functionality rather than hardware tiering.
Convolutional neural networks optimized for lane-edge detection are automating the transition from rule-based image processing to learned feature recognition, enabling sub-100 millisecond drift prediction. European OEMs are deploying these architectures across mid-range passenger vehicles previously limited to basic threshold alerts. The technology is automating the reduction of false-positive triggers in degraded lane-marking conditions, compressing warranty exposure for alert fatigue complaints.
NHTSA's pending heavy truck ADAS mandate is accelerating pre-compliance engineering cycles among US commercial vehicle manufacturers. The rulemaking's performance thresholds are forcing recalibration of camera mounting angles and detection ranges for articulated vehicle geometries. Fleet operators in Texas and Michigan are responding by specifying integrated LDW-LKA bundles rather than standalone warning systems to simplify future retrofit avoidance.
Fleet procurement departments are consolidating supplier relationships around full-stack ADAS providers capable of unified lane-keeping, emergency braking, and blind-spot coverage. Large North American for-hire carriers are displacing fragmented single-function vendors with multi-system contracts tied to total cost of ownership guarantees. This concentration is most visible among temperature-controlled logistics operators in the US Southeast, where insurance premium reductions for comprehensive ADAS fitment are driving specification standardization across tractor-trailer combinations.
Lane Departure Warning (LDW) Market Segmentation
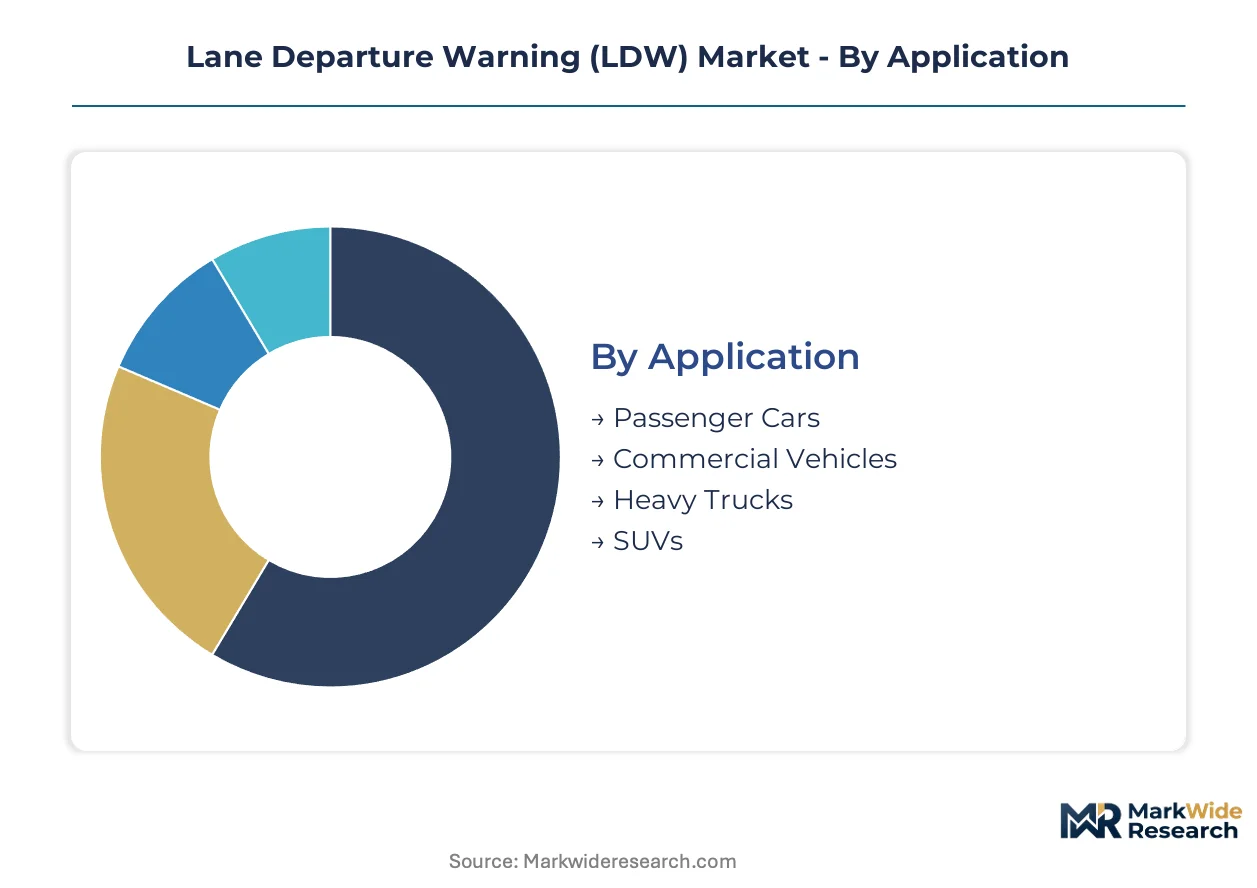
Lane Departure Warning technology fragments across hardware architectures, vehicle platforms, and procurement channels. Each segmentation dimension reveals distinct margin structures and competitive dynamics that shape supplier strategy and OEM sourcing decisions.
Application:
Customization intensity spans from standardized passenger car modules to heavy truck systems requiring bespoke calibration for articulated geometries.
- Passenger Cars:High-volume camera modules with 1.2-2.0 megapixel resolution dominate this segment. CMOS sensor cost compression is enabling fitment into economy vehicle trims previously limited to ultrasonic parking assistance.
- Commercial Vehicles:Fleet procurement in Texas and Michigan is consolidating around integrated LDW-LKA bundles rather than standalone warning systems to preempt NHTSA heavy truck mandates.
- Heavy Trucks:Articulated vehicle geometries demand recalibrated camera mounting angles and extended detection ranges. US for-hire carriers are front-loading installation cycles ahead of anticipated rulemaking.
- SUVs:Higher ride heights require adjusted lane-marking recognition algorithms to maintain detection accuracy across varied road crown angles.
Leading the category by volume: Passenger Cars. Growing fastest: Heavy Trucks.
Technology:
Cost tiers separate mature single-sensor systems from redundant multi-modal architectures demanded by Level 3 autonomy standards.
- Camera-Based:Forward-facing systems operating at 30-60 frames per second anchor current installations. Mature supply chains and declining sensor costs sustain penetration into mid-range vehicle segments.
- LIDAR-Based:Solid-state modules provide redundancy for Level 3+ autonomy but remain constrained by 8-12x cost premiums versus camera alternatives. Premium passenger segments absorb these economics.
- Radar-Based:All-weather performance advantages position this technology for heavy commercial applications where lane detection must persist through precipitation and debris.
- Ultrasonic:Limited to low-speed parking assistance applications; insufficient range and resolution for highway-speed lane departure detection.
Volume concentration: Camera-Based. Steepest expansion trajectory: LIDAR-Based.
End User:
Procurement authority distributes across vehicle manufacturing stages, with aftermarket channels gaining traction for regulatory pre-compliance.
- OEMs:German manufacturers anchor European specification-setting through integrated camera-based lane monitoring systems. In-house semiconductor capabilities at major suppliers sustain vertical control over module production.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG compete through dedicated manufacturing lines in Germany and Romania. Denso Corporation specializes in thermal-resistant sensor packaging for Asian OEM channels.
- Aftermarket Providers:Independent service garages in Germany and California are retrofitting legacy commercial fleets to meet impending compliance deadlines.
- Fleet Operators:Large North American temperature-controlled logistics operators are standardizing comprehensive ADAS fitment across tractor-trailer combinations to capture insurance premium reductions.
Procurement volume leader: OEMs. Channel expanding most quickly: Fleet Operators.
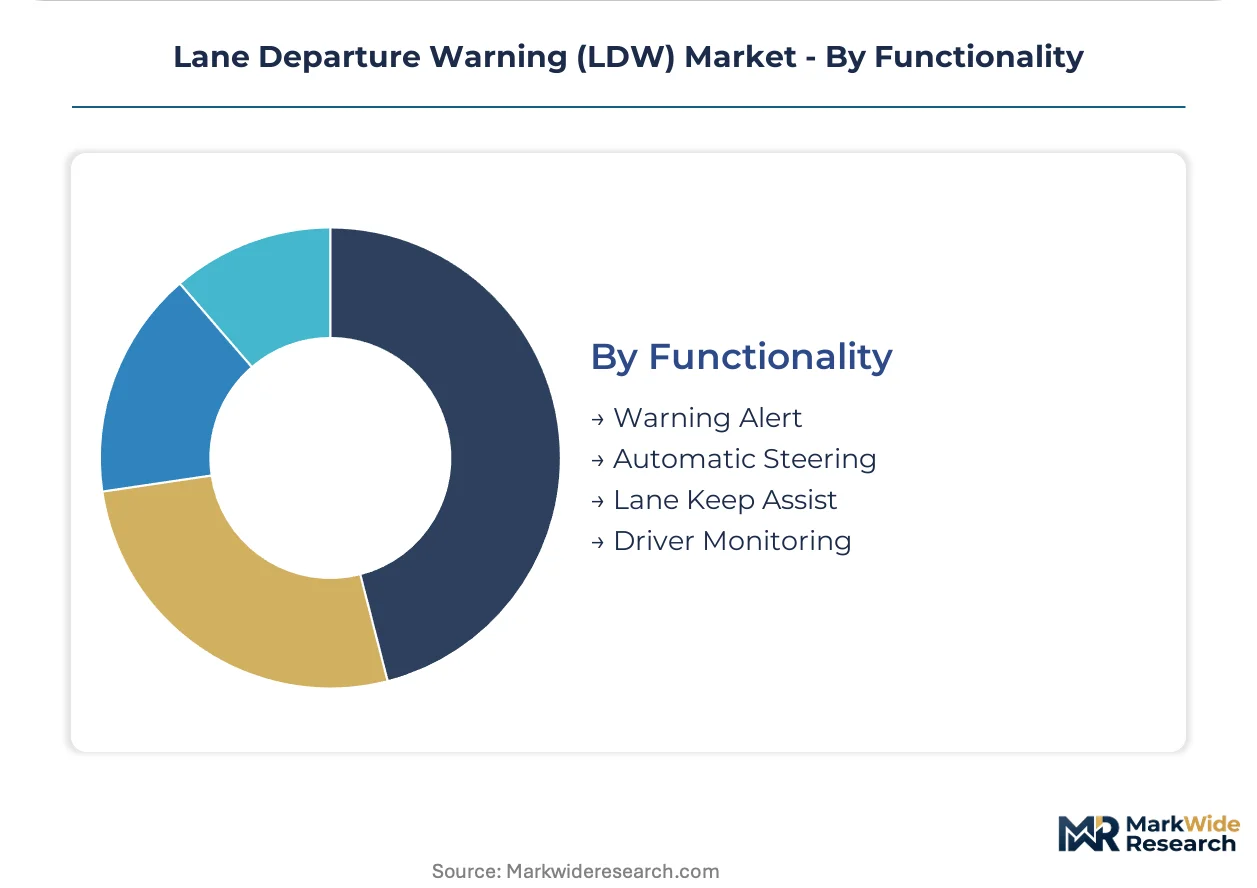
Functionality:
Margin structures stratify between warning-only systems and assist-capable platforms requiring electric power steering integration.
- Warning Alert:Audible, haptic, or visual triggers when unintended drift occurs constitute the largest revenue pool. Sub-100 millisecond drift prediction is automating false-positive reduction through convolutional neural networks.
- Lane Keep Assist:Electric power steering actuator integration commands premium pricing. UN ECE R79 type-approval performance thresholds are compelling standardization across European OEM portfolios.
- Automatic Steering:Higher autonomy levels demand redundant sensor fusion and ASIL-B functional safety certification with 18-24 month validation cycles.
- Driver Monitoring:Convergence with cabin-facing cameras creates adjacent revenue in drowsiness detection and hands-off-wheel enforcement.
Revenue concentration: Warning Alert. Premium expansion: Lane Keep Assist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer production in Germany and South Korea anchors the semiconductor feedstock chain for LDW camera modules and edge-computing chipsets. These material origins shape regional manufacturing footprints and procurement patterns across automotive electronics.
United States
Fleet operators in Texas and Michigan are front-loading LDW-LKA bundle installations ahead of NHTSA's pending heavy truck mandate. The regulator's rulemaking for automatic emergency braking and lane-keeping systems is compressing procurement timelines. Detroit's automotive engineering corridor concentrates Tier-1 supplier R&D for articulated vehicle camera calibration.
Germany
OEM integration of camera-based lane monitoring systems in Stuttgart and Munich anchors European specification-setting for LDW performance thresholds. UN ECE R79 type-approval mandates are compelling standardization across passenger and commercial vehicle portfolios. Continental AG's dedicated manufacturing lines in Lower Saxony and Romania sustain regional supply dominance.
Japan
Denso Corporation's thermal-resistant sensor packaging captures Asian OEM channels requiring high-temperature engine-bay installations. METI's vehicle safety technology roadmaps are accelerating LDW fitment into kei-car and compact vehicle segments. Nagoya's automotive supplier cluster concentrates specialized packaging R&D for extreme thermal environments.
China
Domestic CMOS sensor cost compression is enabling camera-based LDW penetration into economy vehicle segments previously served by ultrasonic-only systems. MIIT's intelligent connected vehicle standards are mandating lane-keeping functionality in new energy vehicle categories. Yangtze River Delta electronics manufacturing clusters are scaling module assembly for both domestic OEMs and export markets.
South Korea
Samsung's advanced node foundry capacity supplies edge-computing chipsets for real-time lane detection algorithms. MFDS automotive safety guidelines are aligning with UN ECE frameworks to accelerate LDW adoption in domestic heavy commercial vehicles. Seoul's semiconductor design corridor concentrates convolutional neural network optimization talent for next-generation recognition systems.
Lane Departure Warning (LDW) Market Competitive Landscape
Global majors compete with regional champions across technology integration depth and regulatory compliance speed. The market structures around three tiers: full-stack ADAS providers with captive semiconductor capabilities, specialized camera module fabricators, and software-defined functionality specialists. Consolidation pressure is intensifying as fleet procurement departments demand unified lane-keeping, emergency braking, and blind-spot coverage from single-source contracts. Dominant competitive moves include backward integration into image sensor production and strategic partnerships for LIDAR sensor fusion architectures.
Within the full-stack provider tier, Robert Bosch GmbH and Continental AG exemplify European-based manufacturers with in-house semiconductor capabilities and dedicated regional production lines. Denso Corporation occupies a position representing Asian-channel specialists with differentiated thermal packaging expertise. These three anchors illustrate the geographic segmentation of competitive advantage: German engineering depth in camera module vertical control, Japanese specialization in extreme-environment durability, and the scale economics of multi-modal sensor fusion development.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Valeo |
| Mobileye |
| Magna International |
| ZF Friedrichshafen AG |
| Aptiv |
| Autoliv |
| Others |
Supply & Pricing Matrix
Embedded vision engineering specialists in South Korea and Germany command compensation premiums that widen pricing spreads between premium LIDAR-fusion systems and economy camera-only tiers. Labor-cost differentials in convolutional neural network optimization directly feed into margin structures across warning-alert and lane-keep-assist functionality bundles.
Pricing Analysis
Warranty and over-the-air update bundling separates premium LDW-LKA integrated systems from unbundled warning-only modules sold through aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 26262 ASIL-B certification status and electric power steering integration depth. Cost compression in 2.0+ megapixel CMOS sensors is intensifying price erosion in camera-only tiers. Fleet operators in Texas and Michigan exhibit lowest price sensitivity due to insurance premium reduction capture, while independent service garages in California face acute margin pressure on retrofit installations.
Supply Chain Analysis
Edge-computing chipset supply rests on TSMC and Samsung advanced node foundry capacity in Taiwan and South Korea. CMOS image sensors, solid-state LIDAR modules, and thermal-resistant sensor packaging constitute critical input dependencies. Single-source vulnerability in automotive-grade semiconductor allocation during demand surges presents structural supply risk. Distribution runs through Tier-1 supplier direct OEM contracts, with aftermarket channels gaining share in Germany and California for regulatory pre-compliance retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced node foundry capacity constraints in Taiwan and South Korea prop pricing power for semiconductor-integrated LDW module suppliers. Supply scarcity in automotive-grade edge-computing chipsets sustains margin premiums across the analysis window.
For Market Incumbents: Hedge against LIDAR cost curve compression by securing multi-year foundry allocation agreements for 2.0+ megapixel image sensor production. Deepen backward integration into in-house semiconductor capabilities to defend against emerging Chinese CMOS sensor producers. Prioritize ASIL-B certification investment to maintain pricing tier separation from economy camera-only competitors.
For New Entrants and Emerging Players: Begin with thermal-resistant sensor packaging specialization for high-temperature engine-bay proximity applications adjacent to core LDW functionality. Target aftermarket retrofit channels in California and Germany where regulatory pre-compliance deadlines compress procurement timelines. Pursue fleet operator direct contracting with total cost of ownership guarantee structures to bypass entrenched Tier-1 supplier relationships.
For Investors and Strategic Acquirers: The window for entry favors specialists in convolutional neural network optimization for automotive edge devices with captive foundry relationships. Long-term viability centers on software-defined functionality differentiation rather than hardware tiering. Watch NHTSA rulemaking extension to passenger vehicles as inflection signal for addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modal Sensor Fusion Development | Redundant LIDAR-camera architectures satisfy Level 3 autonomy mandates from UN ECE R79. |
| Foundry Allocation Securement | Long-term TSMC and Samsung capacity contracts insulate against automotive demand surge volatility. |
| Aftermarket Retrofit Channel Expansion | Independent garage networks in Germany and California capture regulatory pre-compliance procurement. |
| ASIL-B Certification Acceleration | ISO 26262 compliance compresses product refresh windows against consumer electronics sensor generations. |
| Fleet Operator Direct Contracting | Total cost of ownership guarantees displace fragmented single-function vendor relationships. |
Research Methodology
Independent corroboration across Tier-1 supplier procurement executives, OEM platform engineering directors, aftermarket distributor operations heads, and fleet ADAS specification managers underwrites the qualitative findings. Primary interviews with embedded vision engineering specialists and thermal packaging R&D directors combined with secondary validation from NHTSA rulemaking dockets, UN ECE R79 type-approval records, and IHS Markit vehicle production databases. Bottom-up module shipment analysis and top-down ADAS content-per-vehicle estimates triangulate volume figures.
Rate-of-change decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions structures the analytical framework. CAGRs derive from segment-level shipment trajectories weighted by average selling price evolution throughout the forecast period. Convolutional neural network deployment timelines and NHTSA mandate implementation assumptions constitute automotive-specific forecast inputs.
Underlying measurement precision varies by segment; passenger car and heavy truck volume estimates carry tighter precision than emerging SUV and specialty vehicle categories. Forecasts reflect documented assumptions on CMOS sensor cost compression curves and foundry capacity expansion timelines. NHTSA rulemaking acceleration, EU Green Deal safety provision extensions, and LIDAR module cost breakthroughs warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Automotive Mirror Replacement System Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Germany Airbag Systems Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Automotive TPMS Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market
Automotive Safety and Security Systems
Two Wheeler Anti-Lock Braking System Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market