
 Car Camera Cleaning Systems Market | 2026-2036
Car Camera Cleaning Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Car Camera Cleaning Systems Market Analytics
Multi-source procurement for nozzle assemblies and pump modules is expanding as tier-one suppliers diversify beyond captive electronics houses. Bosch Group leverages its mechatronics heritage to sustain integrated camera-washer units for premium OEM programs. Continental AG anchors European factory-fit volumes through direct relationships with Stuttgart and Munich-based vehicle manufacturers. Magna International competes on North American assembly-plant proximity, controlling logistics costs for just-in-time delivery to Detroit and Ontario production lines.
Car camera cleaning systems employ precision-machined micro-nozzles, typically 0.3-0.8 mm in diameter, to deliver calibrated fluid bursts or directed air streams across optical surfaces without residue streaking; these assemblies integrate with ADAS controller area network buses to trigger cleaning cycles when image-quality algorithms detect occlusion. The primary commercial purpose is maintaining sensor fidelity for lane-keeping, surround-view, and automated parking functions under road-spray, dust, and winter-salt conditions. Automatic Systems lead factory-installed volumes given OEM liability exposure for ADAS downtime, while Liquid Dispensing technology dominates margin pools due to heated-fluid variants commanding premium positioning in cold-climate specifications. Aftermarket Products show structural growth from fleet-operator retrofit programs seeking to extend vehicle service life without full platform replacement.
NHTSA Federal Motor Vehicle Safety Standards and EU General Safety Regulation mandate rear-view and surround-camera visibility, directly embedding cleaning-system compliance into type-approval pathways for new vehicle categories. ISO 26262 functional-safety requirements for ADAS components further constrain supplier qualification, raising barriers for uncertified entrants. ECE R46 and R79 revisions across European member states synchronize camera-maintenance obligations with automated steering approvals. Stakeholders must monitor divergent homologation timelines between NHTSA rulemaking and EU delegated acts to align product-development cycles with enforcement windows.
Market Dynamics
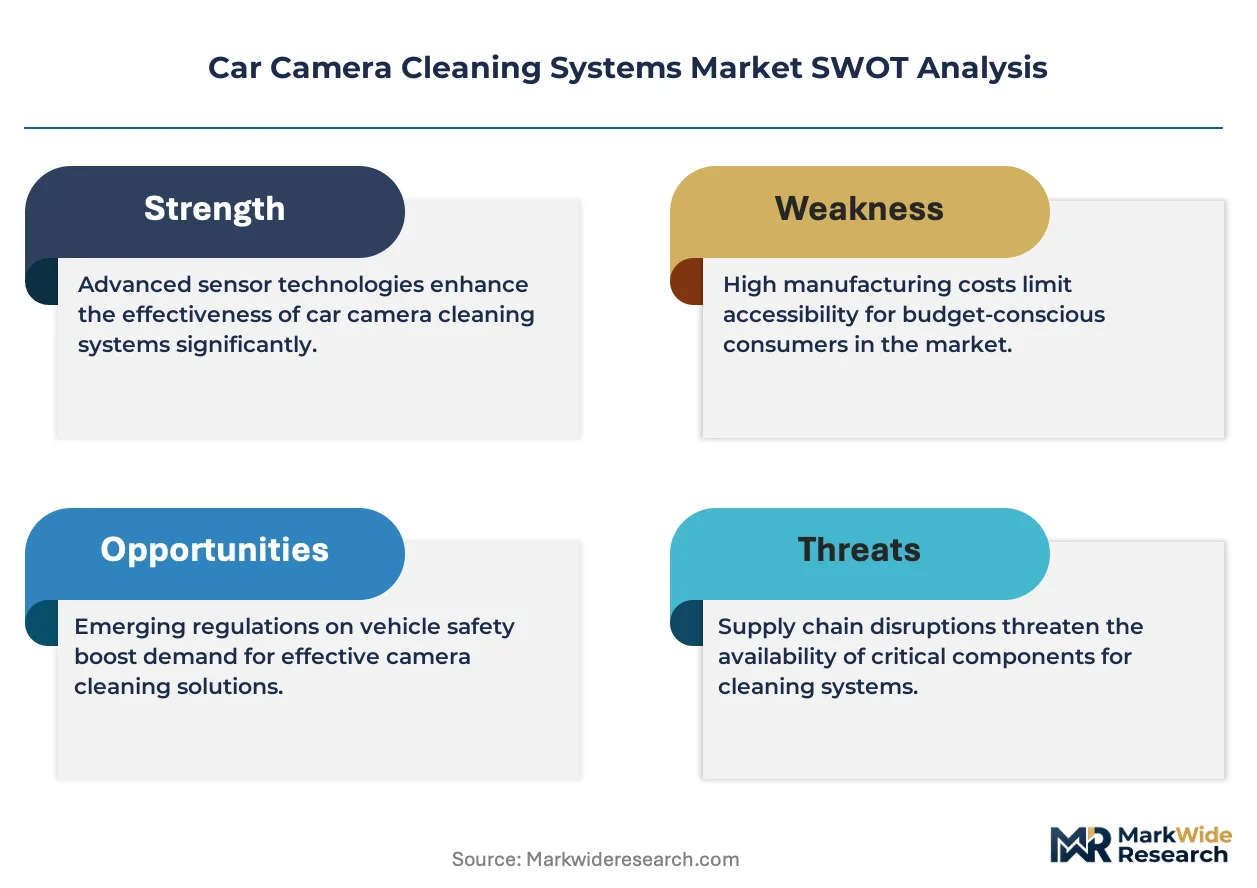
The collision between NHTSA camera-visibility mandates and ISO 26262 functional-safety certification is compressing supplier qualification timelines while concentrating procurement among mechatronics-integrated tier-ones.
Growth Catalysts
- ADAS sensor proliferation:Lane-keeping and automated parking functions now require surround-view camera arrays, each demanding dedicated cleaning circuits to maintain optical clarity under road-spray conditions.
- ECE R46 revisions:European member states synchronize camera-maintenance obligations with automated steering approvals, embedding cleaning-system compliance into type-approval pathways.
- Heated-fluid variants:Cold-climate specifications command premium positioning as fleet operators in Nordic markets and alpine corridors specify winter-grade camera washers to prevent ice occlusion.
Market Restraints
- Pump module supply concentration:Captive electronics houses in Germany and Japan control precision-machined micro-nozzle supply, exposing tier-one integrators to single-source vulnerability.
- ISO 26262 certification burden:Functional-safety documentation requirements for ADAS components raise barriers for uncertified entrants, constraining price competition.
- Silicone fluid cost volatility:Specialized low-residue cleaning formulations face input price pressure from semiconductor-grade chemical supply chains.
Strategic Opportunities
- Autonomous vehicle retrofit programs:Fleet operators in California and Arizona seek camera-cleaning upgrades for existing platforms without full vehicle replacement.
- Air-blast convergence with ultrasonic drying:Hybrid cleaning architectures combine directed air streams with piezoelectric moisture removal for residue-free performance.
- EU Green Deal chemical compliance:Biodegradable fluid formulations qualify for sustainability-linked procurement criteria in Stuttgart and Munich-based OEM programs.
Industry Challenges
- Mechatronics talent scarcity:Cross-functional engineers capable of integrating fluid dynamics, CAN bus architecture, and ADAS controller logic command premium compensation.
- Homologation timeline divergence:NHTSA rulemaking cycles and EU delegated acts release on different schedules, forcing parallel product-development tracks.
- Legacy washer reservoir integration:Existing vehicle architectures require physical redesign to accommodate dedicated camera-cleaning fluid circuits separate from windshield systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Camera Cleaning Systems Market |
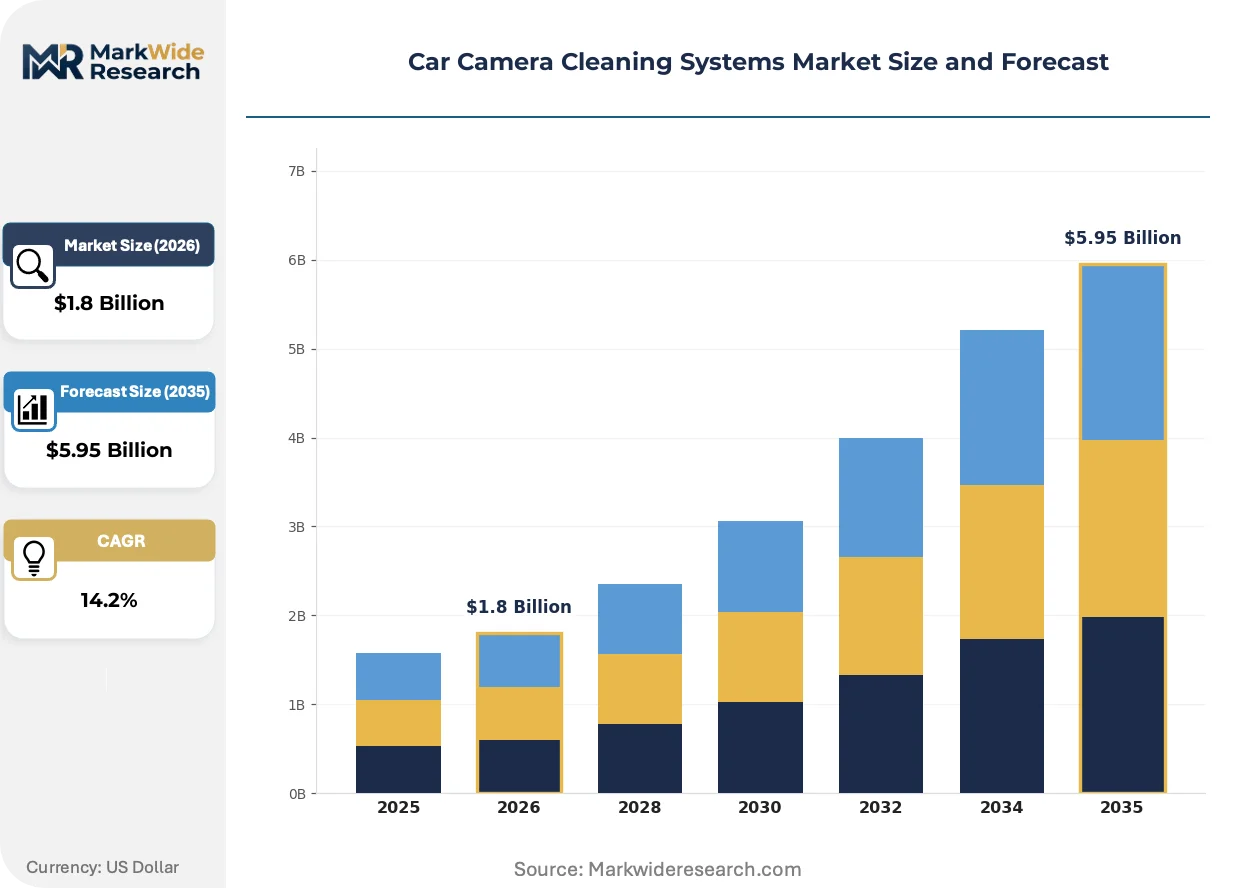
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Systems, Manual Kits, OEM Solutions, Aftermarket Products Technology: Ultrasonic Cleaning, Compressed Air, Brush Mechanism, Liquid Dispensing End User: Automotive Manufacturers, Fleet Operators, Vehicle Dealerships, Independent Service Providers Installation: Factory-Installed, DIY Kits, Retrofit Options, Professional Installation |
| Companies Covered | Bosch Group, Magna International Inc., Continental AG, dlhBOWLES, Ficosa International SA, Valeo SA, HELLA GmbH & Co. KGaA, Panasonic Corporation, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Camera Cleaning Systems Market Evolving Landscape
Active sensor maintenance is transitioning from passive bolt-on hardware to intelligent, algorithm-triggered systems that preserve ADAS uptime under dynamic contamination loads.
Piezoelectric micro-pump architectures are rewriting fluid delivery economics in camera cleaning. These solid-state devices eliminate reciprocating seals and enable precise burst calibration down to microliter volumes. Tier-one suppliers in Germany adopt them for premium OEM programs. The technology is compressing maintenance intervals while enabling heated-fluid integration without thermal losses in traditional pump housings.
EU General Safety Regulation mandates now extend to surround-camera visibility, binding cleaning-system performance to automated vehicle approvals. This regulatory architecture forces suppliers to document failure-mode probabilities under salt-spray and dust-loading test protocols. Aftermarket retrofit providers face exclusion from type-approved vehicle categories unless they achieve equivalent certification.
Fleet procurement departments now specify outcome-based camera-uptime guarantees rather than component-level hardware purchases. Logistics operators in North America negotiate penalty clauses for ADAS downtime attributable to optical occlusion. This contractual shift transfers performance risk from vehicle operators to cleaning-system integrators, compressing margin structures while demanding predictive maintenance telemetry.
Car Camera Cleaning Systems Market Segmentation
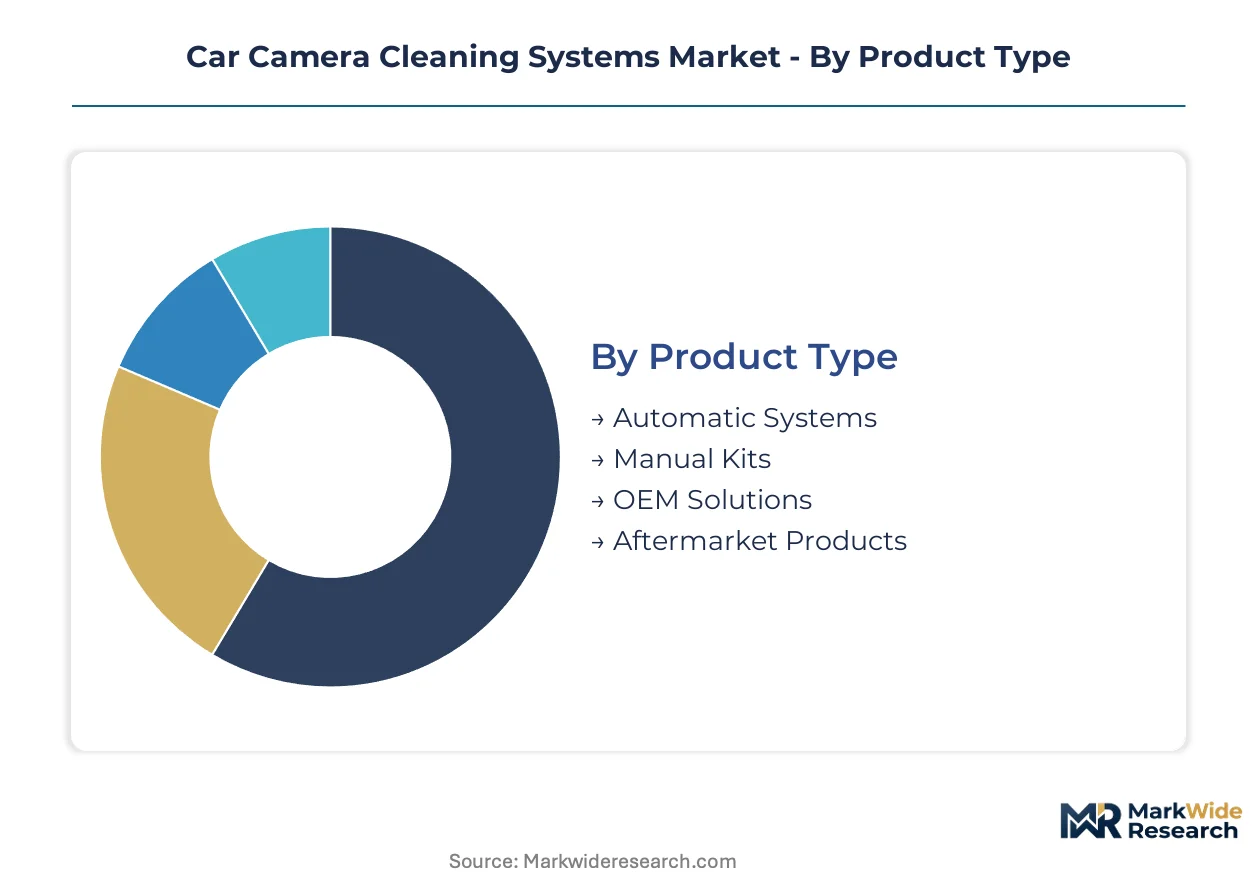
Camera cleaning systems fragment across four intersecting dimensions that determine procurement pathways, certification requirements, and margin structures. Product type and technology choices lock in supplier relationships for vehicle platform lifecycles. End-user concentration and installation modality dictate whether volumes flow through OEM type-approval channels or aftermarket retrofit programs.
Product Type:
Supply concentration in mechatronics-integrated systems is compressing procurement timelines as tier-one suppliers consolidate factory-fit volumes.
- Automatic Systems:Self-triggering assemblies integrate with ADAS controller area network buses to execute cleaning cycles when image-quality algorithms detect occlusion. Demand concentrates in Germany's automotive engineering corridor where Stuttgart and Munich-based OEMs specify heated-fluid variants for cold-climate ADAS reliability. ISO 26262 functional-safety certification requirements constrain supplier qualification to established mechatronics houses.
- Aftermarket Products:Retrofit programs for fleet operators in California and Arizona drive structural growth as logistics departments seek camera-uptime guarantees without full platform replacement. ECE R46 compliance documentation requirements exclude uncertified providers from type-approved vehicle categories.
- Manual Kits:Consumer-grade spray assemblies for enthusiast vehicle owners.
- OEM Solutions:Direct supplier programs with captive design integration.
Today's leader: Automatic Systems. Tomorrow's challenger: Aftermarket Products.
Technology:
Cost tiers separate precision-machined micro-nozzle architectures from compressed-air alternatives with divergent fluid economics and maintenance intervals.
- Liquid Dispensing:Calibrated fluid bursts through 0.3-0.8 mm diameter micro-nozzles deliver residue-free optical maintenance. Heated-fluid variants command premium positioning in Nordic markets and alpine corridors where winter-grade specifications prevent ice occlusion. Silicone-based low-residue formulations face input price pressure from semiconductor-grade chemical supply chains.
- Ultrasonic Cleaning:Piezoelectric micro-pump architectures eliminate reciprocating seals and enable microliter-volume burst calibration. Tier-one suppliers in Germany adopt these solid-state devices for premium OEM programs, compressing maintenance intervals while integrating thermal management without housing losses.
- Compressed Air:Directed air-stream systems for dust-heavy operating environments.
- Brush Mechanism:Mechanical-contact cleaning for heavy-contamination scenarios.
Today's leader: Liquid Dispensing. Tomorrow's challenger: Ultrasonic Cleaning.
End User:
Customer type determines contract structure, with fleet procurement departments now negotiating outcome-based uptime guarantees rather than component purchases.
- Fleet Operators:Logistics operators in North America specify penalty clauses for ADAS downtime attributable to optical occlusion. This contractual shift transfers performance risk to cleaning-system integrators, compressing margin structures while demanding predictive maintenance telemetry. Retrofit programs in Arizona and California extend vehicle service life without platform replacement.
- Automotive Manufacturers:Factory-fit volumes anchor revenue concentration through direct relationships with assembly-plant procurement departments. NHTSA camera-visibility mandates embed cleaning-system compliance into type-approval pathways, exposing OEMs to liability for ADAS downtime.
- Vehicle Dealerships:Service-bay installation of OEM-specified upgrade packages.
- Independent Service Providers:Uncertified aftermarket installation outside type-approval channels.
Today's leader: Automotive Manufacturers. Tomorrow's challenger: Fleet Operators.
Installation:
Volume distribution reflects the collision between legacy vehicle architectures and dedicated camera-cleaning fluid circuits requiring physical redesign.
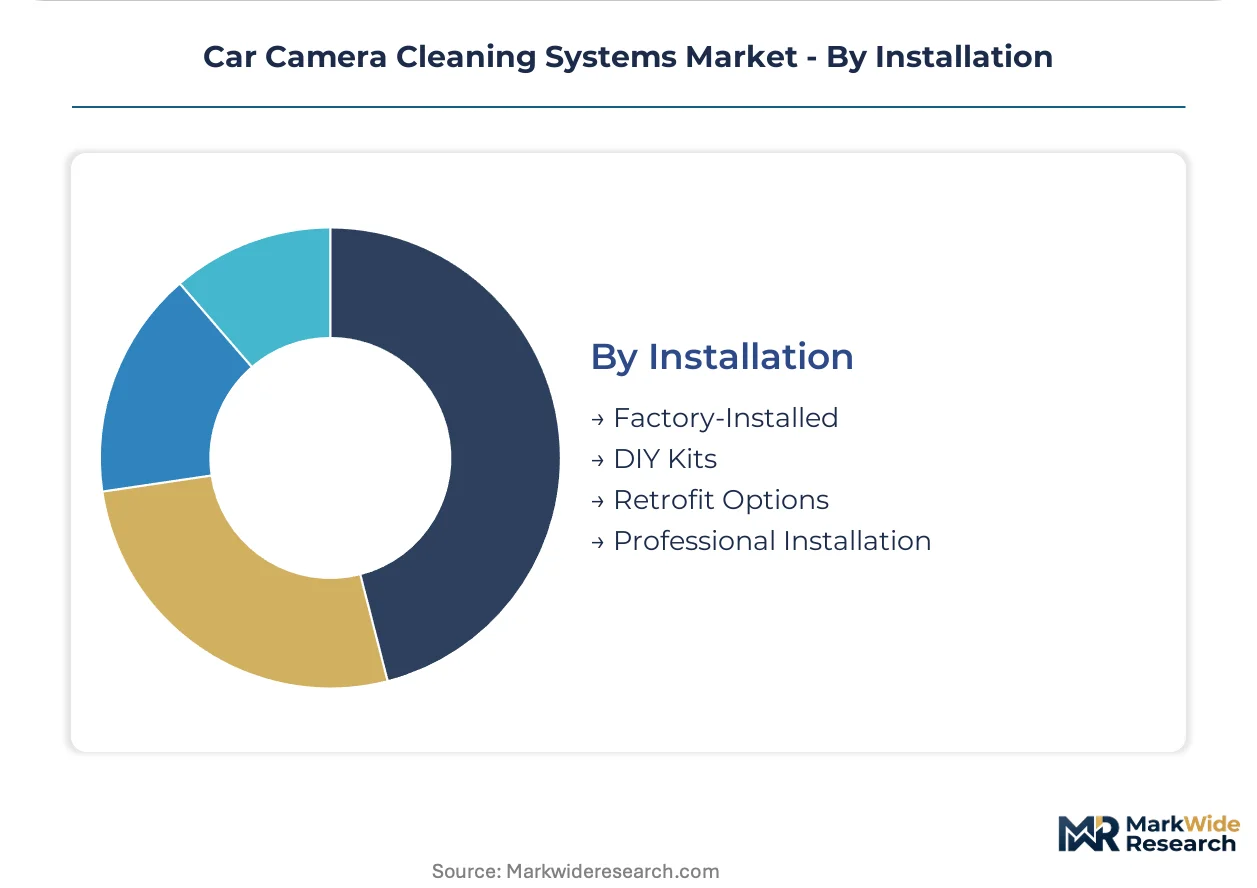
- Factory-Installed:Integrated at assembly-plant origin with dedicated reservoir circuits separate from windshield systems. Magna International controls logistics costs through North American assembly-plant proximity for just-in-time delivery to Detroit and Ontario production lines. Bosch Group sustains premium OEM programs through mechatronics heritage.
- Retrofit Options:Aftermarket programs for existing platforms face legacy washer reservoir integration challenges. Fleet operators in California and Arizona drive demand for camera-cleaning upgrades without full vehicle replacement, though physical redesign constraints limit addressable vehicle populations.
- DIY Kits:Consumer self-installation with simplified fluid routing.
- Professional Installation:Certified service-bay fitting with warranty coverage.
Today's leader: Factory-Installed. Tomorrow's challenger: Retrofit Options.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping supplier footprints as tier-one integrators migrate production toward jurisdictions with streamlined ADAS component homologation. Cost-of-compliance gaps between NHTSA-driven North American certification and EU delegated-act pathways concentrate investment in dual-standard manufacturing nodes.
United States
NHTSA Federal Motor Vehicle Safety Standards mandate rear-view and surround-camera visibility for new vehicle categories, embedding cleaning-system compliance into type-approval pathways. Fleet operators in California and Arizona negotiate penalty clauses for ADAS downtime, transferring performance risk to system integrators. Detroit and Ontario production lines anchor North American assembly-plant procurement volumes through just-in-time delivery relationships.
Germany
Stuttgart and Munich-based OEMs specify heated-fluid variants for cold-climate ADAS reliability, commanding premium positioning in Nordic and alpine export markets. ECE R46 and R79 revisions synchronize camera-maintenance obligations with automated steering approvals across European member states. The automotive engineering corridor concentrates mechatronics-integrated tier-one supplier relationships for factory-fit volumes.
Japan
METI industrial policy supports precision-machined micro-nozzle supply chains for domestic and export ADAS programs. Captive electronics houses control pump module production, exposing tier-one integrators to single-source vulnerability in semiconductor-grade chemical formulations. Toyota City and Nagoya industrial clusters anchor domestic procurement relationships with integrated camera-washer specifications.
China
MIIT GB standards for intelligent vehicle sensors incorporate camera-visibility maintenance requirements into domestic type-approval frameworks. Yangtze River Delta manufacturing nodes scale production for both domestic OEM programs and export retrofit markets. Dual carbon goals pressure suppliers toward biodegradable fluid formulations in sustainability-linked procurement criteria.
South Korea
MFDS-aligned vehicle safety regulations adopt camera-visibility mandates following EU and US precedent, compressing supplier qualification timelines. Seoul Capital Area electronics houses supply piezoelectric micro-pump architectures for premium OEM programs. Hyundai-Kia supplier parks in Busan-Ulsan anchor dedicated camera-cleaning circuit integration for surround-view ADAS arrays.
Car Camera Cleaning Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ultrasonic and air-blast cleaning architectures as differentiation vectors. The supplier base concentrates among mechatronics-integrated tier-ones with ISO 26262 functional-safety certification, compressing procurement timelines while excluding uncertified entrants. Three archetypes dominate: diversified automotive suppliers leveraging fluid-systems heritage, electronics specialists migrating from sensor manufacturing, and regional fabricators serving aftermarket retrofit channels. Competitive moves center on backward integration into precision-machined nozzle supply and geographic expansion toward autonomous vehicle testing corridors.
Within the diversified automotive supplier tier, Bosch Group and Continental AG exemplify integrated camera-washer program execution, while Magna International anchors North American assembly-plant proximity strategies. These entities represent the mechatronics-integrated archetype that dominates factory-fit volumes through direct OEM relationships and captive design integration capabilities.
| Leading Market Players |
|---|
| Bosch Group |
| Magna International Inc. |
| Continental AG |
| dlhBOWLES |
| Ficosa International SA |
| Valeo SA |
| HELLA GmbH & Co. KGaA |
| Panasonic Corporation |
| Denso Corporation |
| Others |
Value Network & Pricing Analysis
ISO 26262 certification-grade divergence separates premium mechatronics-integrated systems from commodity nozzle assemblies, compressing margins at the standard tier while concentrating pricing power among qualified tier-one suppliers in Germany and Japan. This bifurcation manifests in divergent procurement pathways: certified integrators command long-term OEM contracts with penalty-clause pricing, while uncertified entrants compete on spot-market fluid-component sales with minimal technical support bundling.
Pricing Analysis
Direct-to-OEM channel discounts dominate factory-fit volumes, with tier-one suppliers negotiating multi-year framework agreements that embed ADAS uptime guarantees as performance-adjusted pricing clauses. Three-tier pricing structure across premium heated-fluid, standard ambient, and economy aftermarket levels differentiates based on ISO 26262 certification tier and thermal management integration. Cost compression in standard-tier pump modules intensifies because silicone fluid input prices track semiconductor-grade chemical volatility. Fleet procurement departments exhibit lowest price sensitivity due to penalty-clause risk transfer, while independent service providers face acute margin pressure from uncertified competition.
Supply Chain Analysis
Freight cost optimization anchors Magna International's North American assembly-plant proximity strategy, controlling just-in-time delivery expenses to Detroit and Ontario production corridors. Precision-machined micro-nozzle supply concentrates in Germany, Japan, and South Korea, with piezoelectric micro-pump architectures drawing from Seoul Capital Area electronics houses. Single-source vulnerability in semiconductor-grade silicone formulations exposes tier-one integrators to chemical supply chain disruptions. Distribution runs through captive OEM supplier parks and certified aftermarket retrofit channels with ECE R46 documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Car Camera Cleaning Systems Market functions as a stable compounder anchored by NHTSA and EU regulatory mandates that embed cleaning-system compliance into irreversible type-approval pathways. This regulatory lock-in generates predictable replacement demand across vehicle platform lifecycles.
For Market Incumbents: Acquire precision-machined micro-nozzle production capabilities to eliminate single-source exposure from Japanese and German captive electronics houses. Backward integration into heated-fluid formulation chemistry defends margin position against silicone cost volatility. ISO 26262 certification investment creates barrier against ultrasonic cleaning technology substitutes from emerging Korean suppliers.
For New Entrants and Emerging Players: Launch via fleet-operator retrofit programs in California and Arizona, where penalty-clause risk transfer creates demand for outcome-based uptime guarantees without OEM type-approval barriers. Target uncertified aftermarket channels for manual kit distribution while piezoelectric micro-pump patents expire. White-space penetration concentrates in biodegradable fluid formulations qualifying for EU Green Deal procurement criteria.
For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics talent scarcity intersects with ISO 26262 certification bottlenecks, favoring acquisition of mid-tier German engineering houses with established OEM relationships. Long-term viability frames this as a regulatory-capture play with embedded ADAS sensor proliferation ensuring sustained demand. Watch NHTSA rulemaking acceleration as inflection signal for North American contract repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nozzle Manufacturing | Eliminates single-source dependency on German and Japanese captive electronics suppliers. |
| Heated-Fluid Thermal Management Patent Filing | Secures premium positioning in Nordic and alpine cold-climate OEM specifications. |
| Fleet Retrofit Program Partnership | Captures California and Arizona logistics operator demand without type-approval delays. |
| Biodegradable Formulation Certification | Qualifies for EU Green Deal sustainability-linked procurement in Stuttgart and Munich programs. |
| Piezoelectric Micro-Pump Platform Development | Displaces reciprocating seal architectures with solid-state maintenance compression. |
Research Methodology
Multiple input streams — primary interviews with tier-one supplier procurement officers, OEM platform engineers, and aftermarket distribution heads; secondary validation through vehicle production databases, NHTSA rulemaking dockets, and ECE regulatory filings; and customs trade data for fluid component flows — were reconciled through bottom-up and top-down triangulation. Stakeholder roles spanned ADAS integration specialists at Stuttgart and Munich-based OEMs, fleet operations managers in Arizona and California logistics corridors, and technical directors at mechatronics-integrated tier-one suppliers.
Historical volume trajectories were cross-referenced against panel input from procurement executives to establish baseline penetration rates across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user contract structure, and installation modality, with additional granularity on heated-fluid versus ambient specifications. CAGRs were derived from regression analysis of ADAS sensor array proliferation rates against regulatory enforcement windows, incorporating fleet-operator retrofit demand curves and OEM platform lifecycle replacement patterns.
Several conditions sit outside the modeled scope, including potential NHTSA rulemaking delays, EU delegated-act revision timelines, and breakthrough displacement of liquid dispensing by ultrasonic or air-blast architectures. Forecasts reflect assumptions about regulatory enforcement consistency and ADAS sensor proliferation continuity. Stakeholders should weight assumptions against their own operating context regarding certification investment capacity and geographic procurement concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Advanced Suspension Control System Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Global Automotive Seat Belt Reminder Market
Automotive Safety and Security Systems
Automotive Airbag Inflator Market
Automotive Safety and Security Systems
Driver Drowsiness Monitoring System Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Panoramic Reverse Systems Market
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market