
 North America Airbag Systems Market | 2026-2036
North America Airbag Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Airbag Systems Market Analytics
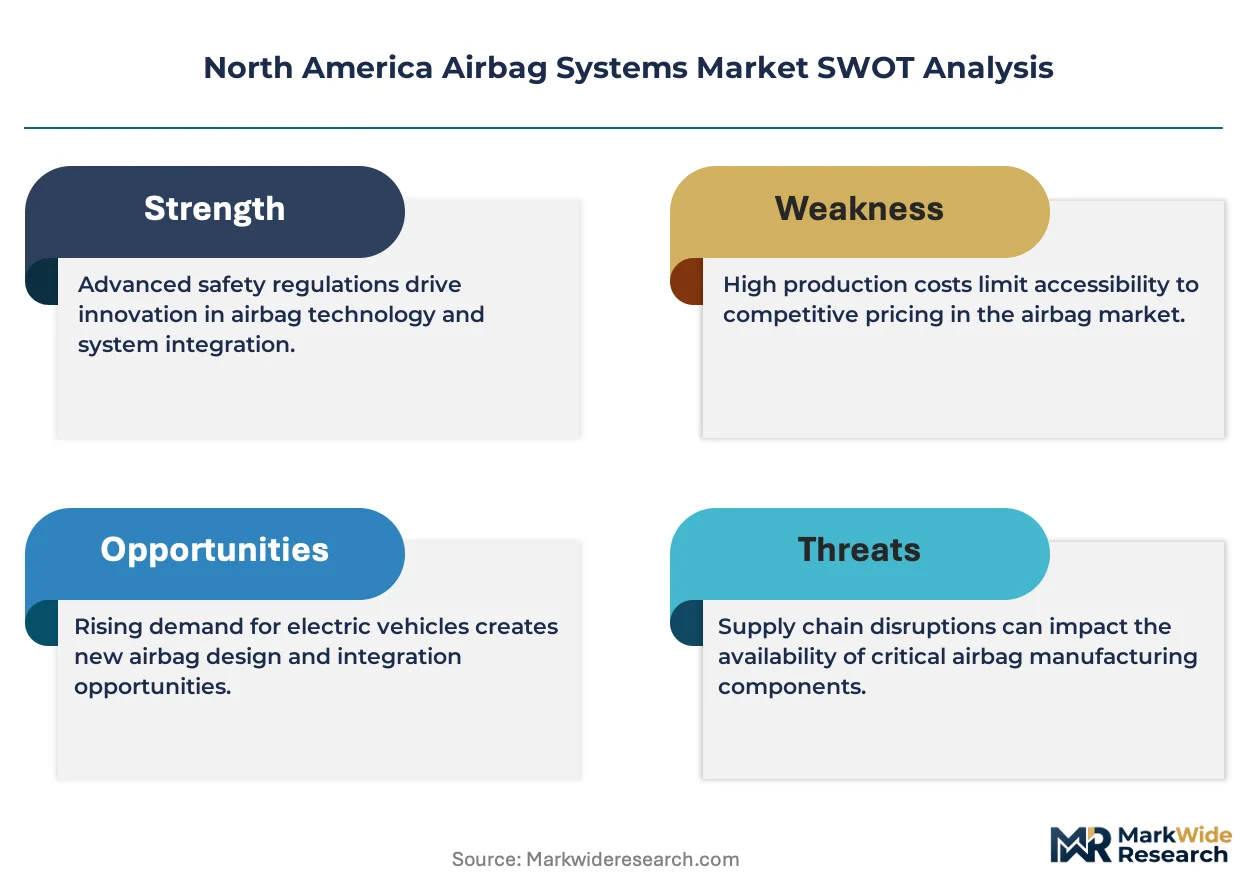
The capability gap between integrated inflator manufacturers and pure-play module assemblers is collapsing as Tier-1 suppliers absorb pyrotechnic production in-house. Autoliv Inc. leverages captive inflator capacity across its North American plant network to lock in OEM contracts. ZF Friedrichshafen AG anchors its regional position through sensor-to-deployment integration, while Joyson Safety Systems competes aggressively on cost in the aftermarket channel.
North America airbag systems are occupant-restraint assemblies comprising fabric cushions, gas generators, and electronic deployment controllers designed to inflate within milliseconds of crash detection via accelerometer and pressure sensor inputs. Frontal airbags dominate installed value but face margin compression as designs standardize across vehicle classes; curtain airbags represent the fastest-growing product category as rollover protection mandates expand to light trucks and crossovers. Pyrotechnic systems retain technological leadership in inflator performance, though electronic control units capture expanding value as algorithm sophistication differentiates Tier-1 supplier offerings.
NHTSA Federal Motor Vehicle Safety Standards, Transport Canada CMVSS regulations, and Mexico's NOM-194-SCFI-2015 framework collectively mandate multi-point airbag coverage, forcing module standardization across trilateral production platforms. The U.S. IRA's domestic content incentives for automotive components further reshape sourcing geography, pressuring suppliers to requalify supply chains within USMCA territory. Stakeholders must monitor how NHTSA's anticipated updates to side-pole crash test protocols will redirect R&D spending toward advanced curtain and center-console airbag architectures.
Market Dynamics
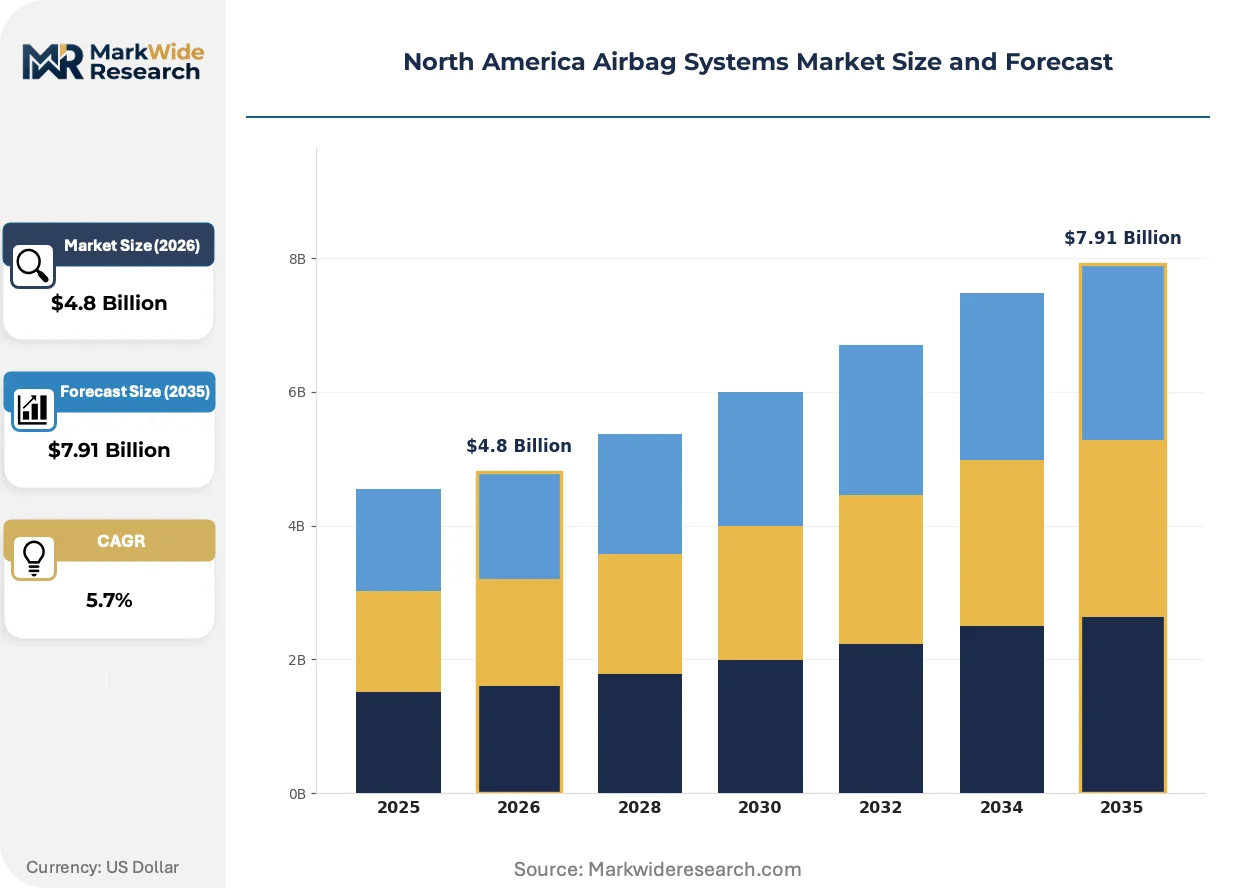
The North America airbag systems market is being reshaped by NHTSA's expanding side-impact and rollover mandates, which force module redesigns across light truck and SUV platforms while compressing supplier margins through standardized architectures.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 214:Mandates advanced side-impact protection for all light vehicles, driving curtain airbag penetration into mid-size pickup and crossover segments.
- Pyrotechnic inflator miniaturization:Reduced generator size enables multi-chamber knee and center-console bags without packaging penalties, opening new interior real estate for safety integration.
- Mexico's vehicle assembly corridor:Concentrated OEM capacity expansion south of the U.S. border generates localized module demand and supplier co-location incentives.
Market Restraints
- Sodium azide supply concentration:Pyrotechnic precursor sourcing clusters with three Asian chemical processors, exposing inflator manufacturers to input volatility and qualification delays.
- USMCA rules-of-origin complexity:Domestic content thresholds for IRA automotive incentives force supply chain requalification costs onto Tier-1 assemblers already operating on thin margins.
- Alternative restraint systems:Autonomous emergency braking and structural crumple zone advances reduce per-crash airbag deployment frequency in premium vehicle segments.
Strategic Opportunities
- Canada's CMVSS update cycle:Anticipated alignment with U.S. side-pole protocols creates first-mover advantage for suppliers with pre-certified curtain architectures.
- Algorithm-driven occupant classification:Machine learning integration with seat-mounted pressure sensors enables adaptive deployment force, differentiating Tier-1 ECU offerings.
- Independent repair channel consolidation:Post-collision module replacement demand concentrates in collision repair networks seeking certified aftermarket sourcing partnerships.
Industry Challenges
- Pyrotechnic engineer scarcity:Specialized gas generator chemistry expertise pools at legacy defense contractors, constraining inflator R&D staffing for automotive suppliers.
- Multi-protocol validation timelines:Simultaneous NHTSA, Transport Canada, and NOM-194 homologation stretches testing capacity and delays platform launches.
- Legacy sensor integration:New center-console airbag architectures must interface with decade-old accelerometer harnesses without full electrical system redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Airbag Systems Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frontal Airbags, Side Airbags, Curtain Airbags, Knee Airbags Technology: Pyrotechnic Systems, Electronic Control Units, Inflatable Seat Belts, Sensor Technology End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Vehicle Assemblers Installation: Integrated Installation, Retrofit Solutions, Modular Systems, Semi-Independent Systems |
| Companies Covered | Autoliv Inc., Continental AG, Denso Corporation, Robert Bosch GmbH, Hyundai Mobis, Toyoda Gosei Co., Ltd., ZF Friedrichshafen AG, Joyson Safety Systems, Key Safety Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Airbag Systems Market Evolving Landscape
Sensor-to-deployment integration is compressing the traditional Tier-2 to Tier-1 value chain, while software-defined restraint algorithms create new differentiation vectors beyond hardware specifications.
Hybrid gas generators combining stored compressed gas with pyrotechnic augmentation are displacing pure pyrotechnic inflators in curtain applications, offering tunable pressure curves for variable occupant positions. Ford and General Motors have qualified dual-stage hybrid units for 2026 light truck platforms. The technology is displacing conventional azide-based generators in rollover-critical segments where extended bag retention matters.
NHTSA's anticipated side-pole crash test protocol revision will mandate coverage for far-side occupants, forcing center-console airbag architectures into standard equipment status. The rulemaking compresses development timelines for module suppliers already committed to 2027 platform launches. Curtain and tubular center-bag designs dominate engineering resources as OEMs pre-position for compliance.
Fleet buyers now specify total cost of ownership metrics including post-collision module replacement rates and sensor calibration complexity, shifting procurement criteria beyond unit price. Large rental and commercial operators weight warranty claim history more heavily than brand heritage. This behavioral pivot concentrates volume with suppliers offering modular, field-replaceable ECU designs.
North America Airbag Systems Market Segmentation
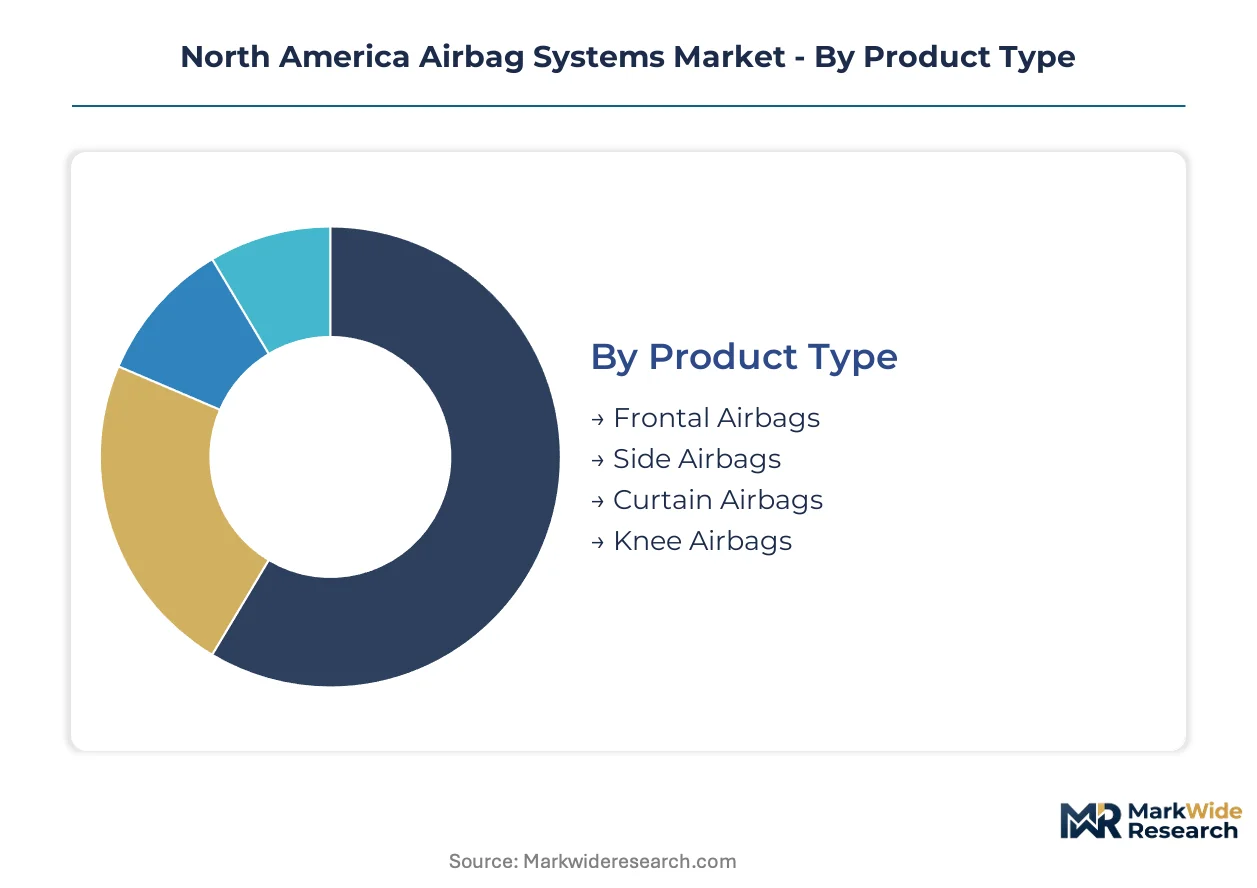
Airbag system procurement diverges sharply across installation contexts and buyer types, with OEM integration timelines and aftermarket replacement cycles creating distinct margin profiles. Technology selection increasingly hinges on sensor-to-deployment latency rather than raw inflator performance, reshaping supplier competitive position across every segment tier.
Product Type:
Substitution pressure from structural reinforcement materials and active restraint systems weighs most heavily on frontal architectures, while rollover mandates protect curtain segment expansion.
- Frontal Airbags:Dual-stage pyrotechnic cushions deploy from steering wheel and passenger dashboard housings. Demand concentrates in full-size pickup platforms where NHTSA compliance baselines sustain volume, though margin compression intensifies as designs commoditize across Detroit Three production lines.
- Curtain Airbags:Tubular or chambered designs extend along roof rails to cover side-window apertures during rollover events. Light truck and crossover assembly in Mexico's Bajío corridor drives procurement concentration as OEMs pre-position for expanded rollover protection mandates.
- Side Airbags:Seat-mounted or door-panel units address lateral impact forces.
- Knee Airbags:Lower-dashboard modules protect femur and patella displacement.
Frontal Airbags retains volume leadership; Curtain Airbags holds the steepest expansion curve.
Technology:
Cost tier stratification separates proven pyrotechnic platforms from emerging electronic architectures that command premium positioning through algorithmic differentiation.
- Pyrotechnic Systems:Azide or non-azide gas generators remain the dominant propellant chemistry for instantaneous cushion inflation. Sourcing concentrates with suppliers maintaining captive chemical processing capacity, as sodium azide precursor availability constrains new market entrants.
- Electronic Control Units:Microcontroller-based deployment logic processes accelerometer and pressure sensor inputs to determine inflation timing and force. Detroit Three procurement specifications now prioritize machine learning-enabled occupant classification, concentrating demand with Tier-1 suppliers offering software-defined restraint architectures.
- Inflatable Seat Belts:Webbing-integrated airbag cushions distribute crash loads across torso surfaces.
- Sensor Technology:Accelerometer, pressure, and radar inputs feed deployment decision trees.
Pyrotechnic Systems dominates unit shipment scale; Electronic Control Units captures the fastest margin expansion.
End User:
Application context separates vehicle assembler procurement—governed by platform lifecycle planning—from aftermarket replacement demand triggered by collision events.
- OEMs:Original equipment manufacturers specify module architectures during vehicle development programs spanning 48-60 month cycles. Ford, General Motors, and Stellantis procurement teams in Michigan and Ontario concentrate design-in authority, with Mexico assembly expansion shifting volume commitments southward.
- Tier-1 Manufacturers:Autoliv, ZF, and Joyson Safety Systems integrate inflator production with module assembly to defend contract renewals. Their captive manufacturing networks across the USMCA zone position them for IRA domestic content compliance.
- Aftermarket Suppliers:Post-collision replacement module distributors serve independent repair channels.
- Vehicle Assemblers:Contract manufacturers and niche EV producers source pre-certified architectures.
OEMs command the largest absolute procurement value; Tier-1 Manufacturers face the most intense consolidation pressure.
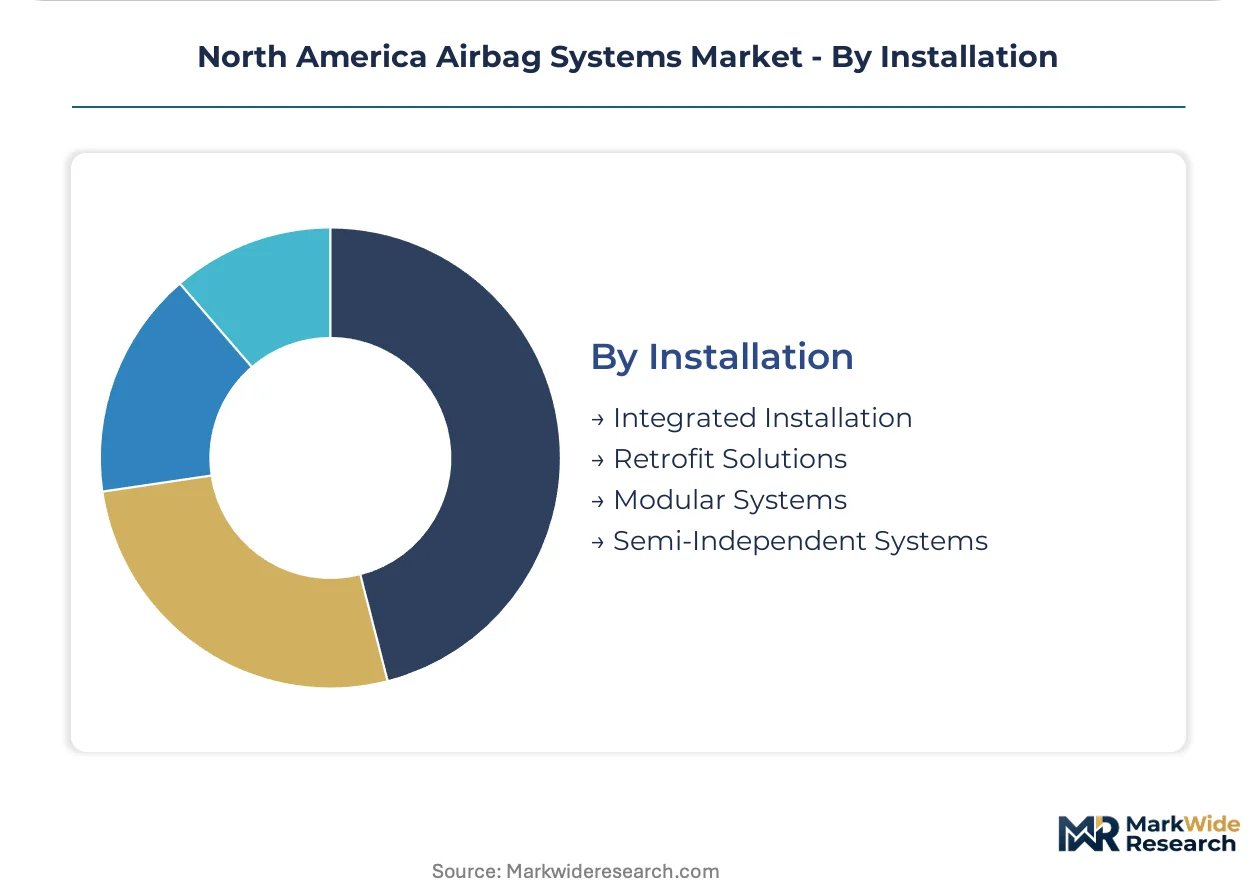
Installation:
Supply concentration among integrated platform specialists constrains retrofit penetration, as factory-calibrated sensor networks resist field modification.
- Integrated Installation:Factory-designed airbag modules embed within steering columns, dashboards, and pillar trim during vehicle assembly. This channel captures nearly all NHTSA-compliant deployment, as post-assembly modification voids homologation certification.
- Modular Systems:Standardized ECU-inflator-cushion configurations enable supplier interchangeability across multiple OEM platforms. The approach concentrates procurement with Tier-1 assemblers offering cross-platform validation packages, reducing OEM qualification overhead.
- Retrofit Solutions:Aftermarket add-on restraint systems serve specialty vehicle and commercial retrofit applications.
- Semi-Independent Systems:Partially integrated architectures separate sensor input from deployment logic.
Integrated Installation maintains absolute volume dominance; Modular Systems shows the strongest share gain trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands pricing leverage through Detroit Three procurement authority, while Mexico captures volume expansion through assembly corridor investments. Canada occupies a mid-tier position shaped by CMVSS regulatory alignment and Tier-1 supplier concentration in Southern Ontario.
United States
NHTSA Federal Motor Vehicle Safety Standard 214 drives curtain airbag adoption across light truck and crossover segments. The IRA's domestic content incentives pressure suppliers to requalify supply chains within USMCA territory. Michigan and Ohio house the Detroit Three's engineering centers where platform development decisions concentrate procurement authority.
Mexico
OEM capacity expansion in the Bajío corridor generates localized module demand for export-oriented assembly. NOM-194-SCFI-2015 mandates multi-point airbag coverage equivalent to U.S. standards. Querétaro and Guanajuato cluster Tier-1 supplier facilities serving both domestic assembly and U.S. border logistics.
Canada
Transport Canada CMVSS regulations anticipate alignment with anticipated NHTSA side-pole protocols. Southern Ontario's Windsor-Toronto corridor anchors module assembly operations serving cross-border Detroit Three platforms. The region's supplier base faces margin pressure from USMCA rules-of-origin compliance costs.
North America Airbag Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated inflator manufacturers defend contract renewals through captive pyrotechnic capacity, while pure-play module assemblers compete on price in standardized segments. Three archetypes dominate: full-system integrators with sensor-to-deployment capabilities, regional cost competitors leveraging Mexico manufacturing, and aftermarket specialists serving collision repair channels. M&A activity concentrates among Tier-1 suppliers absorbing inflator production in-house, while strategic partnerships proliferate around algorithm development for occupant classification systems.
Among Sweden-based safety system specialists, Autoliv Inc. exemplifies the integrated archetype through its captive manufacturing network across the USMCA zone. Germany's ZF Friedrichshafen AG and China's Joyson Safety Systems occupy distinct competitive positions, with the former anchoring sensor-to-deployment integration and the latter representing cost-focused competition in aftermarket channels. These three companies illustrate the capability divergence between technology-differentiated and price-driven market approaches.
| Leading Market Players |
|---|
| Autoliv Inc. |
| Continental AG |
| Denso Corporation |
| Robert Bosch GmbH |
| Hyundai Mobis |
| Toyoda Gosei Co., Ltd. |
| ZF Friedrichshafen AG |
| Joyson Safety Systems |
| Key Safety Systems |
| Others |
Value Network & Pricing Analysis
Ninety-day sodium azide precursor lead times concentrate pricing power with Asian chemical processors, compressing margins for North American inflator manufacturers while forcing Tier-1 suppliers to absorb inventory carrying costs or renegotiate OEM contract terms.
Pricing Analysis
Configured-to-order curtain airbag architectures command 15-25% premiums over standardized frontal modules due to NHTSA side-pole compliance complexity and vehicle-specific roof-rail integration requirements. Three-tier pricing structure across premium algorithm-driven ECUs, standard pyrotechnic platforms, and economy aftermarket replacements stratifies procurement across Detroit Three, Mexico assembly, and independent repair channels. Cost compression in standardized frontal architectures intensifies as module designs commoditize across light truck platforms, while fleet buyers exhibit lowest price sensitivity for adaptive deployment systems with machine learning-enabled occupant classification.
Supply Chain Analysis
Strategic stockpiling of sodium azide precursors dominates Tier-1 inventory strategy given single-source vulnerability to Asian chemical processor qualification delays, while just-in-time sensor component flows from Mexico maquiladoras sustain assembly line continuity. Pyrotechnic chemical processing concentrates in China, Japan, and South Korea; module assembly clusters in Michigan, Ontario, and Mexico's Bajío corridor. Supply chain risk centers on tariff exposure from USMCA rules-of-origin compliance for IRA domestic content thresholds. Distribution runs through captive Tier-1 logistics networks serving OEM assembly plants with sequenced module delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as NHTSA's anticipated side-pole protocol bifurcation splits procurement between legacy frontal architectures and advanced curtain-center-console systems, opening niches for specialized algorithm developers and hybrid inflator specialists.
For Market Incumbents: Shield contract renewals by absorbing pyrotechnic production in-house through backward integration into gas generator chemistry, eliminating sodium azide supply concentration risk. Lock in OEM platform engineering relationships before 2027 model-year commitments solidify, as NHTSA rulemaking compresses development timelines for compliant architectures.
For New Entrants and Emerging Players: Lead with algorithm-driven occupant classification systems that differentiate through machine learning integration with seat-mounted pressure sensors, targeting the penetrable aftermarket channel where collision repair networks seek certified replacement module partnerships with modular ECU designs.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense contractors holding specialized pyrotechnic engineering expertise pools, as automotive Tier-1 suppliers face acute staffing constraints for gas generator R&D. Long-term viability hinges on sensor-to-deployment integration capabilities; monitor NHTSA side-pole protocol publication as inflection indicator for curtain architecture demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrotechnic Chemistry | Eliminates sodium azide supply concentration and secures captive inflator capacity for OEM contract defense. |
| Algorithm Development Partnership | Machine learning-enabled occupant classification differentiates Tier-1 ECU offerings beyond hardware specifications. |
| Mexico Manufacturing Footprint Expansion | Positions suppliers for IRA domestic content compliance and Detroit Three assembly corridor growth. |
| Aftermarket Channel Certification Program | Captures post-collision replacement demand from consolidated collision repair networks seeking modular sourcing. |
| Hybrid Inflator Platform Launch | Ford and General Motors qualification of dual-stage units for 2026 light truck platforms validates technology displacement. |
Research Methodology
Initial hypotheses were tested against primary input from Tier-1 supplier procurement executives, OEM platform engineering directors, aftermarket distribution channel managers, and pyrotechnic R&D specialists, then refined through secondary validation against NHTSA Federal Motor Vehicle Safety Standard filings, Transport Canada CMVSS regulatory updates, vehicle production databases, and SEC 10-K disclosures from listed safety system suppliers. Bottom-up module shipment estimates triangulated with top-down OEM platform content analysis.
Variance decomposition across the projection horizon isolates volume drivers by vehicle class, propulsion architecture, airbag content per vehicle, and regional production cluster. CAGRs derive from segmented growth rate aggregation incorporating NHTSA mandate implementation timelines, Mexico assembly capacity expansion schedules, and technology substitution curves for hybrid versus pyrotechnic inflators.
Forecasts assume regulatory continuity in NHTSA, Transport Canada CMVSS, and Mexico NOM-194 regimes; material policy shifts would require re-modeling deployment timing assumptions. Revision becomes warranted when sodium azide supply disruptions or USMCA rules-of-origin enforcement changes cross thresholds affecting Tier-1 supplier qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Video Event Data Recorder Market
Automotive Safety and Security Systems
South Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Global Car Radar Detectors Market
Automotive Safety and Security Systems
Panoramic Reverse Systems Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market