
 United States Automotive Parts Die Casting Market | 2026-2036
United States Automotive Parts Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automotive Parts Die Casting Market Analytics
Lightweighting pressure across powertrain architectures is tilting die casting toward high-pressure aluminum processes capable of thin-wall, complex geometries. Ryobi Die Casting (USA), Inc. leverages its thermal management expertise to anchor supply relationships with domestic EV programs. Dynacast International sustains technology leadership through multi-slide zinc and aluminum platforms that reduce secondary machining. Pace Industries competes on geographic density, operating a network of regional plants that positions it close to Midwest OEM assembly footprints.
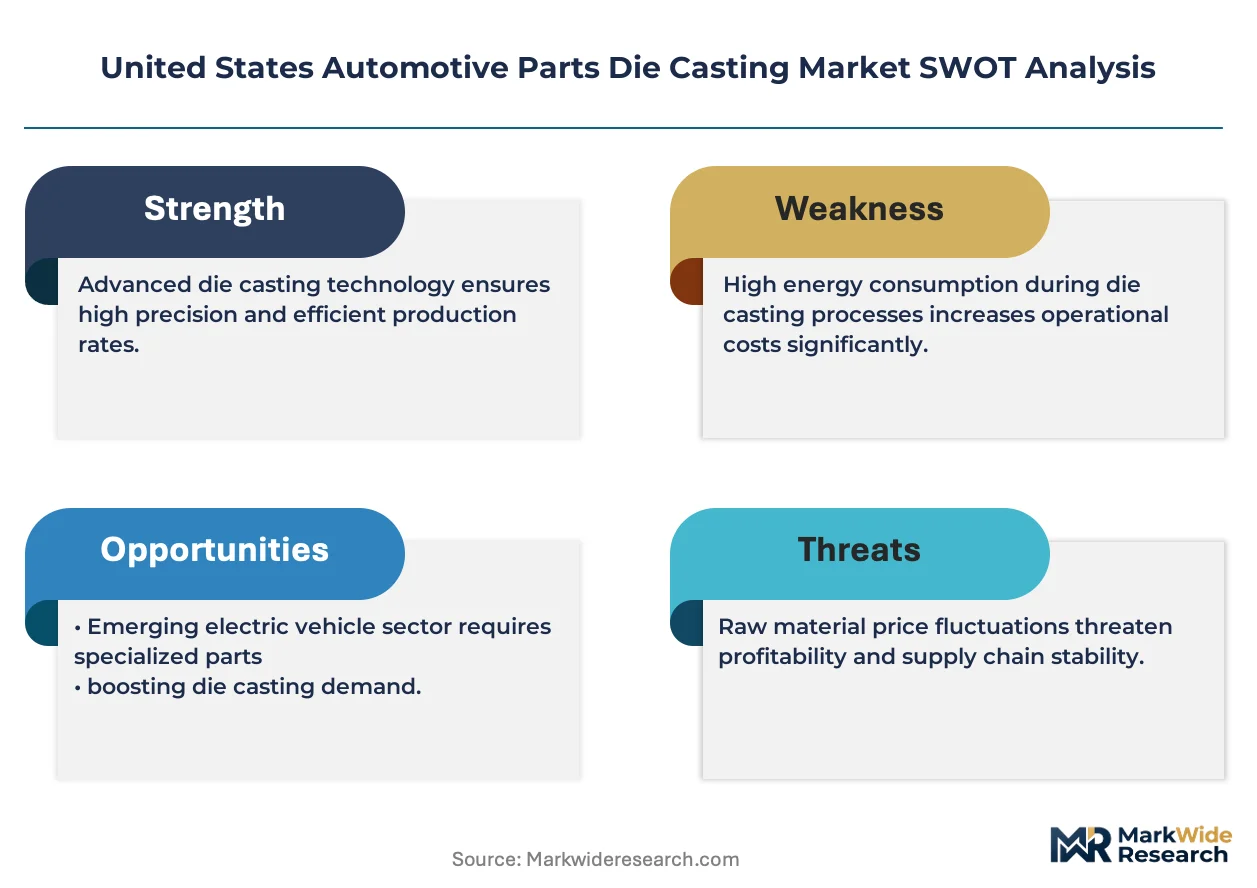
Automotive parts die casting employs molten metal injection into hardened steel dies under pressures exceeding 1,000 psi to produce near-net-shape components with dimensional tolerances of ±0.1 mm, serving primarily as a weight-reduction and cost-consolidation method for powertrain and structural assemblies. Aluminum transmission components and engine blocks occupy mature, high-volume positions where margin pools have compressed amid commodity metal volatility, while structural parts represent the fastest-growing category as OEMs consolidate multi-piece weldments into single die-castings for body-in-white applications. Zinc die castings retain durable positions in smaller mechanical and decorative assemblies where corrosion resistance and surface finish requirements limit material substitution.
NHTSA Corporate Average Fuel Economy standards, EPA greenhouse gas regulations, and OSHA foundry safety mandates collectively shape product specifications, capital allocation, and facility compliance burdens across the domestic supply base. The Inflation Reduction Act's domestic content provisions for clean vehicle tax credits are redirecting sourcing decisions toward US-based die casting capacity. Stakeholders must monitor how NHTSA's forthcoming light-duty vehicle rulemakings recalibrate weight targets and whether EPA tailpipe standards accelerate aluminum intensity per vehicle beyond current program assumptions.
Market Dynamics
Electric vehicle powertrain architectures are forcing a fundamental reconstitution of die casting demand toward large-format aluminum structural castings that consolidate multi-piece assemblies into single near-net-shape components. This shift from internal combustion engine blocks and transmission housings toward battery enclosures and motor housings is redrawing capacity allocation across the domestic supply base.
Growth Catalysts
- NHTSA fuel economy standards:Corporate Average Fuel Economy mandates compel OEMs to substitute aluminum for steel across powertrain and structural applications, pulling die casting volume into lightweighting programs.
- Great Lakes manufacturing corridor:Concentrated Tier-1 supplier clusters near Detroit and Cleveland assembly operations reduce logistics costs and enable just-in-sequence delivery for high-volume programs.
- High-pressure aluminum processes:Thin-wall, complex geometry capabilities meet EV thermal management requirements for motor enclosures and battery housings.
Market Restraints
- Primary aluminum price volatility:London Metal Exchange pricing swings compress margin pools for fixed-price OEM contracts, exposing converters to raw material risk.
- Tooling lead times:Hardened steel die fabrication cycles of 16-24 weeks constrain program launch velocity for new EV platforms.
- OSHA foundry safety mandates:Silica exposure limits and molten metal handling protocols elevate compliance burdens and capital requirements for facility upgrades.
Strategic Opportunities
- Inflation Reduction Act domestic content provisions:Clean vehicle tax credit eligibility requirements redirect sourcing decisions toward US-based die casting capacity expansion.
- Body-in-white structural consolidation:Multi-piece weldment replacement with single die-castings opens new margin pools beyond traditional powertrain applications.
- Indiana and Ohio corridor expansion:Underutilized industrial real estate in secondary Midwest markets offers cost-advantaged greenfield development for EV-dedicated facilities.
Industry Challenges
- Tooling engineer scarcity:Retirement-driven attrition in die design and CNC programming functions constrains new program ramp rates.
- EPA emissions compliance timelines:Accelerated tailpipe standard implementation compresses product development cycles for casting process qualification.
- Legacy equipment integration:Retrofitting conventional high-pressure cells for large-format structural casting geometries requires substantial capital reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automotive Parts Die Casting Market |
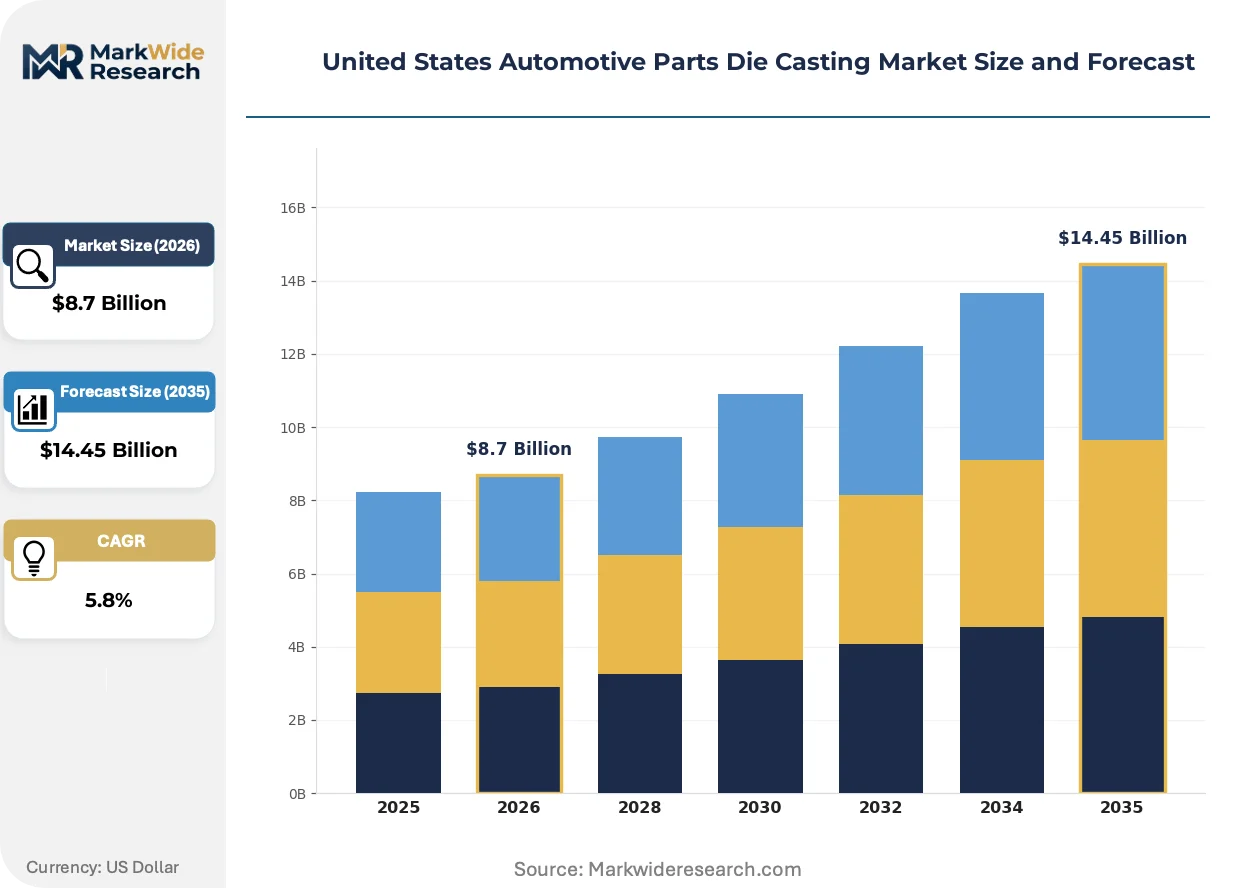
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmission Components, Engine Blocks, Wheels, Structural Parts Material: Aluminum, Zinc, Magnesium, Copper End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Thermal Casting, Cold Chamber, Hot Chamber, Continuous Casting |
| Companies Covered | American Precision Die Casting, IQ Enterprises, Ryobi Die Casting (USA), Inc., Dynacast International, Amsted Industries, Pace Industries, Madison-Kipp Corporation, Erie Bronze and Aluminum Co., KenWalt Die Casting, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automotive Parts Die Casting Market Evolving Landscape
Process convergence between traditional high-pressure die casting and emerging large-format structural techniques is fragmenting established equipment supplier relationships. OEMs now specify hybrid production lines capable of both legacy powertrain components and next-generation battery enclosures.
Large-format aluminum structural casting is hybridizing conventional high-pressure and low-pressure process boundaries to produce single-piece body-in-white components exceeding one meter in dimension. Ford and General Motors EV programs are adopting these techniques for rear underbody assemblies, collapsing multi-stamp welding operations. The technology is hybridizing supplier capabilities, forcing Tier-1 converters to retool for geometric complexity and alloy thermal management previously outside their scope.
NHTSA's forthcoming light-duty vehicle rulemakings are recalibrating weight reduction targets that cascade through material specification committees at domestic OEMs. The regulatory pressure intensifies aluminum intensity per vehicle beyond current program assumptions, particularly for pickup truck and SUV segments where mass reduction yields disproportionate fuel economy gains. EPA tailpipe standards operating in parallel are compressing development timelines for casting suppliers to qualify new alloy formulations.
Buyer concentration among Detroit Three OEMs and emerging EV pure-plays is consolidating procurement leverage into fewer sourcing decision-makers. Long-term supply agreements now specify volume commitments indexed to platform production rather than component-level call-offs, transferring demand risk upstream to converters. This pattern is most pronounced in Michigan and Ohio, where assembly plant proximity determines supplier selection criteria more than unit cost differentials alone.
United States Automotive Parts Die Casting Market Segmentation
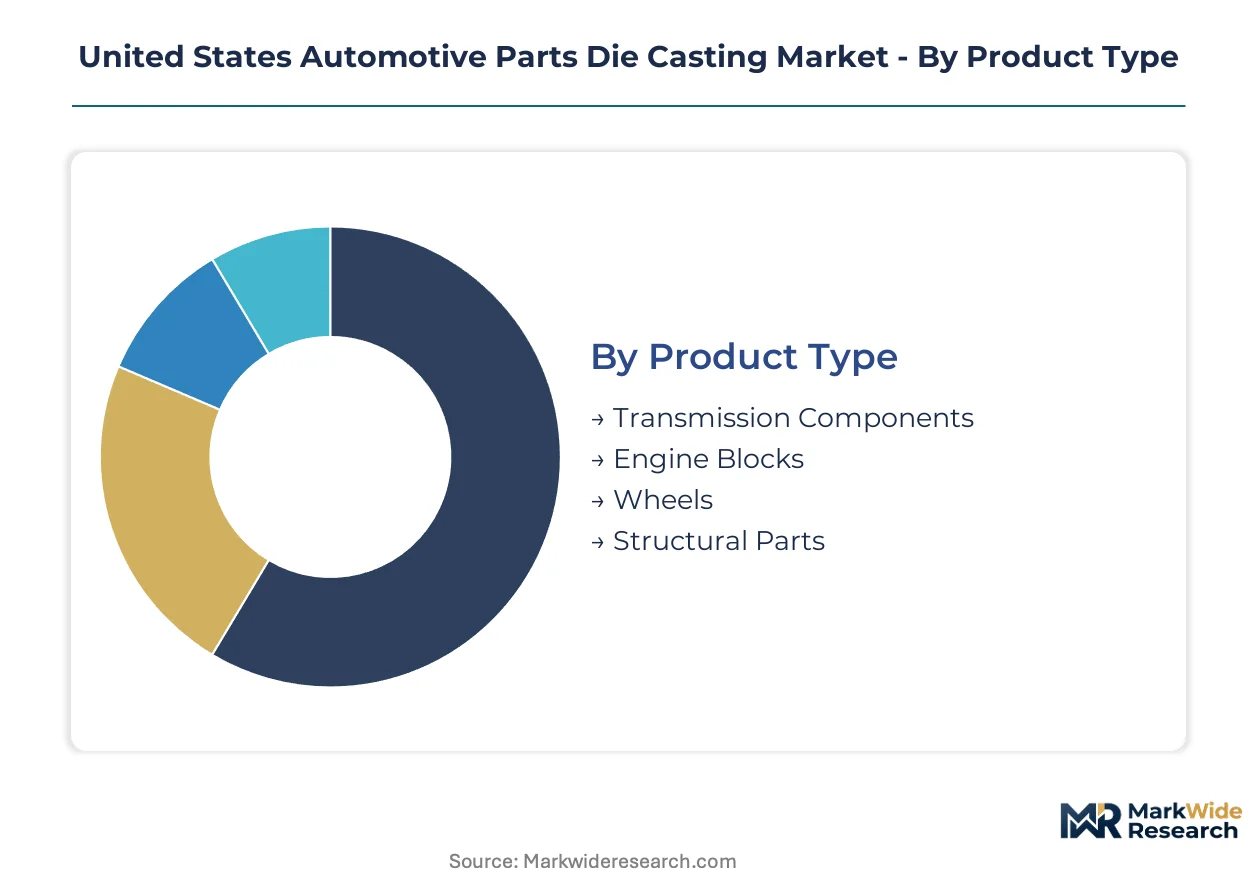
Die casting segmentation in the US automotive sector reflects divergent service intensity, tooling amortization cycles, and alloy specification requirements across powertrain, structural, and aftermarket applications. Understanding these fault lines exposes where margin pools concentrate and where capital deployment faces the longest payback periods.
Product Type:
After-sales service intensity varies sharply across product categories, with structural parts demanding minimal post-installation support while transmission components require extensive warranty and replacement part provisioning.
- Transmission Components:High-pressure aluminum housings and valve bodies operate under cyclic thermal stress and fluid pressure loads. Demand clusters around Detroit Three powertrain operations in Michigan and Ohio, where NHTSA fuel economy standards accelerate multi-speed automatic and dual-clutch transmission adoption. Tooling refresh cycles run 8-12 years, locking suppliers into long-term platform commitments.
- Engine Blocks:Conventional high-pressure die castings face displacement pressure from EV powertrain elimination, though hybrid architectures sustain demand for compact gasoline and range-extender blocks. Foundries serving Indiana and Ohio engine plants confront margin compression from aluminum price volatility indexed to London Metal Exchange fluctuations.
- Wheels:Cosmetic and load-bearing aluminum castings serve both OEM fitment and aftermarket replacement channels with distinct finishing requirements.
- Structural Parts:Large-format battery enclosures and motor housings consolidate multi-piece assemblies into single near-net-shape components exceeding one meter in dimension.
Transmission Components holds the largest share; momentum sits with Structural Parts.
Material:
Cost tier stratification separates commodity aluminum from premium magnesium and copper alloys, with zinc occupying an intermediate position balancing corrosion resistance against density limitations.
- Aluminum:Dominates powertrain and structural applications through silicon-copper alloy formulations optimized for fluidity and tensile strength. EPA emissions compliance timelines accelerate substitution for steel in body-in-white assemblies across Michigan, Ohio, and Indiana manufacturing corridors.
- Zinc:Retains durable positions in smaller mechanical and decorative assemblies where surface finish quality and corrosion resistance limit material substitution. Smaller die casting houses in secondary Midwest markets exploit zinc's lower melting point to reduce energy costs and extend die life.
- Magnesium:Ultra-lightweight applications in seat frames and steering column components face supply chain concentration risks from limited domestic smelting capacity.
- Copper:High-conductivity castings serve electrical motor components and busbar connections in EV powertrains with demanding thermal management specifications.
Aluminum dominates volume; copper and magnesium are climbing fastest on EV thermal management requirements.
End User:
Customer type determines contract structure, with OEMs and vehicle assemblers extracting volume commitments while aftermarket providers and Tier-1 suppliers absorb demand volatility.
- OEMs:Detroit Three and emerging EV pure-plays consolidate procurement leverage into platform-level agreements spanning 5-7 year horizons. Domestic content provisions in the Inflation Reduction Act redirect sourcing decisions toward US-based die casting capacity expansion.
- Aftermarket Providers:Fragmented demand across collision repair and wear-part replacement channels requires flexible production scheduling and reduced minimum order quantities. Distributors in the Great Lakes corridor maintain regional inventory positions to serve independent repair networks.
- Tier-1 Suppliers:Intermediate converters face margin pressure from both raw material volatility and OEM price-down schedules.
- Vehicle Assemblers:Final assembly operations in Detroit, Cleveland, and Chicago metropolitan areas prioritize just-in-sequence delivery proximity over unit cost minimization.
OEMs command the largest procurement volume; aftermarket channels offer the most resilient demand through economic cycles.
Technology:
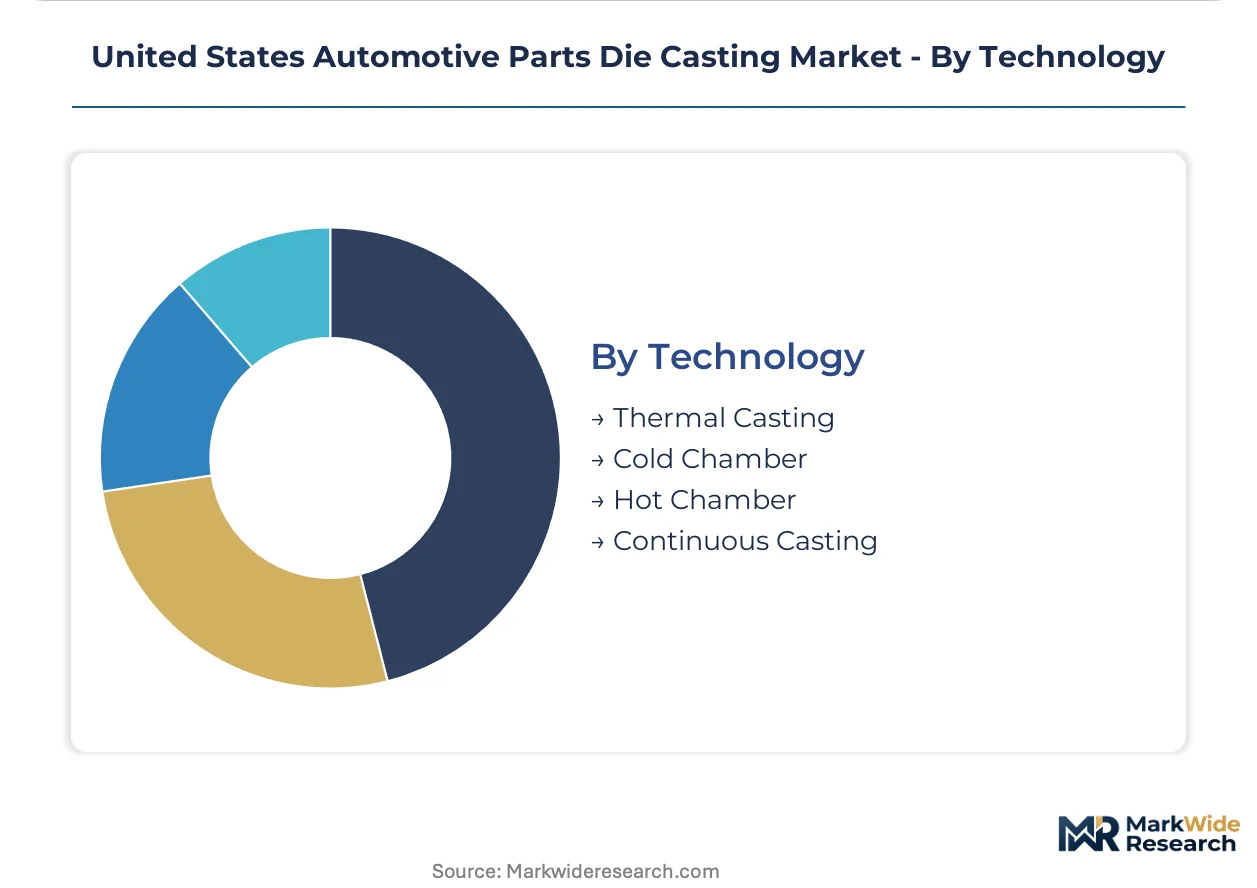
Process maturity creates a technology ladder, with thermal casting and cold chamber methods serving high-volume production while hot chamber and continuous casting address specialized geometries and alloy limitations.
- Thermal Casting:Advanced temperature control systems enable thin-wall aluminum geometries for battery enclosures and motor housings. Ford and General Motors EV programs specify these capabilities for rear underbody structural consolidation.
- Cold Chamber:Conventional high-pressure aluminum die casting dominates transmission and engine applications with established tooling supply chains and qualified alloy formulations.
- Hot Chamber:Zinc-focused methods exploit faster cycle times and reduced thermal shock on dies for smaller mechanical components.
- Continuous Casting:Semi-finished ingot and billet production feeds downstream machining operations rather than near-net-shape component fabrication.
Cold Chamber retains the largest installed base; Thermal Casting is expanding most quickly on large-format structural demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian aluminum smelters feed raw material southward to Michigan and Ohio die casters, while Mexican assembly plants pull finished components into NAFTA-integrated supply chains. This tri-national trade corridor concentrates die casting demand around Detroit, Cleveland, and Monterrey manufacturing nodes.
Michigan
Detroit Three powertrain operations consume high-pressure aluminum transmission housings and engine blocks at scale. NHTSA Corporate Average Fuel Economy standards accelerate material substitution from steel to aluminum across Warren and Flint assembly plants. Tier-1 supplier clusters in Sterling Heights and Grand Rapids enable just-in-sequence delivery for high-volume programs.
Ohio
GM and Ford EV platform launches in Lordstown and Avon Lake redirect die casting demand toward battery enclosures and motor housings. EPA greenhouse gas regulations compress product development timelines for casting process qualification. Cleveland-area foundries retool for large-format structural geometries exceeding one meter in dimension.
Indiana
Hybrid transmission and range-extender engine production in Kokomo and Lafayette sustains demand for conventional aluminum castings amid EV transition. OSHA foundry safety mandates elevate compliance burdens for silica exposure limits at Elkhart County facilities. Secondary Midwest markets offer underutilized industrial real estate for greenfield EV-dedicated capacity.
Illinois
Chicago metropolitan assembly operations prioritize supplier proximity over unit cost minimization for just-in-sequence delivery. Inflation Reduction Act domestic content provisions redirect sourcing decisions toward US-based capacity expansion. Rockford and Decatur machining corridors feed semi-finished castings into downstream powertrain component fabrication.
United States Automotive Parts Die Casting Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates procurement leverage among Detroit Three OEMs and emerging EV pure-plays. The vendor base organizes into three strategic archetypes: thermal management specialists anchoring EV powertrain relationships, multi-slide technology leaders reducing secondary machining requirements, and geographically dense regional networks positioning close to Midwest assembly footprints. Dominant competitive moves include capacity reconfiguration for large-format structural casting and backward integration into alloy formulation capabilities.
Among US-based die casting specialists, Ryobi Die Casting (USA), Inc. and Dynacast International occupy positions exemplifying divergent technology vectors, while Pace Industries represents geographic density strategies. These entities anchor competitive dynamics without exhausting the full vendor landscape.
| Leading Market Players |
|---|
| American Precision Die Casting |
| IQ Enterprises |
| Ryobi Die Casting (USA), Inc. |
| Dynacast International |
| Amsted Industries |
| Pace Industries |
| Madison-Kipp Corporation |
| Erie Bronze and Aluminum Co. |
| KenWalt Die Casting |
| Others |
Value Network & Pricing Analysis
Underutilized capacity across Indiana and Ohio secondary markets is compressing pricing power for conventional high-pressure aluminum castings while tightening availability for large-format structural geometries. This utilization asymmetry shapes supplier behavior toward selective capacity investment and tiered customer prioritization.
Pricing Analysis
The technology-generation pricing gap separates legacy cold-chamber aluminum processes from emerging thermal casting platforms capable of one-meter-plus structural dimensions. Three-tier pricing structure across premium thermal-casting, standard cold-chamber, and economy zinc platforms reflects differentiation by geometric complexity and alloy thermal management specifications. Pricing pressure stems from London Metal Exchange aluminum volatility indexed to fixed-price OEM contracts. Aftermarket distributors exhibit highest price sensitivity due to fragmented demand and inventory carrying costs, while Detroit Three OEMs prioritize just-in-sequence delivery proximity over unit cost minimization.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates raw material cost planning for Great Lakes corridor die casters drawing primary aluminum from Quebec smelters. The supply chain rests on Canadian ingot, Mexican assembly plant demand, and domestic tooling fabrication concentrated in Michigan and Ohio machine shops. Single-source vulnerability concentrates in hardened steel die supply from specialized tool-and-die shops facing retirement-driven engineer attrition. Distribution runs through Tier-1 supplier hubs in Sterling Heights and Grand Rapids enabling just-in-sequence delivery to Detroit assembly operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Detroit Three OEMs and emerging EV pure-plays, consolidating procurement leverage into platform-level agreements that transfer demand risk upstream to converters.
For Market Incumbents: Entrench thermal management capabilities for EV battery enclosures and motor housings as the primary defensive position against new large-format structural casting specialists. Secure backward integration into silicon-copper alloy formulation to reduce London Metal Exchange price exposure. Add capacity in Indiana and Ohio secondary markets where underutilized industrial real estate offers cost-advantaged greenfield development for EV-dedicated facilities. For New Entrants and Emerging Players: Pursue aftermarket transmission component channels where tooling refresh cycles and warranty service requirements create durable revenue streams outside OEM price-down schedules. Target Ohio EV platform launches in Lordstown and Avon Lake where incumbent retooling lags create temporary supply gaps. Lead with rapid die fabrication capabilities compressing the 16-24 week tooling cycle to accelerate program launch velocity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Tier-1 suppliers with long-term platform agreements spanning 5-7 year horizons and indexed volume commitments. Long-term viability centers on structural casting capability hybridization enabling both legacy powertrain and next-generation battery enclosure production. Acquisition target archetype: regional die casters with geographic density in the Great Lakes corridor and underutilized capacity for thermal casting retooling. Monitor NHTSA light-duty vehicle rulemakings as the signal for aluminum intensity inflection beyond current program assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Large-Format Structural Casting Capacity | Ford and General Motors EV programs specify one-meter-plus rear underbody assemblies collapsing multi-stamp welding operations. |
| Alloy Formulation Backward Integration | In-house silicon-copper development reduces London Metal Exchange volatility exposure for fixed-price OEM contracts. |
| Thermal Management Process Qualification | Advanced temperature control systems meet EPA-compressed development timelines for EV battery enclosure adoption. |
| Great Lakes Corridor Geographic Expansion | Indiana and Ohio secondary markets offer underutilized industrial real estate for EV-dedicated greenfield facilities. |
| Die Fabrication Cycle Compression | Rapid tooling capabilities address 16-24 week lead time constraints constraining new EV platform launch velocity. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and foundry operations managers; and secondary validation through NHTSA rulemaking dockets, EPA emissions compliance filings, vehicle production databases, and SEC disclosures from aluminum processors. Primary interviews explored capacity allocation decisions, tooling investment timelines, and alloy specification trends. Secondary sources captured regulatory trajectory, production volume assumptions, and raw material price movements. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, and regional production cluster across the analysis window. The analytical framework models aluminum intensity per vehicle indexed to NHTSA Corporate Average Fuel Economy standards and EPA tailpipe compliance timelines. CAGRs derive from segment-level volume projections weighted by alloy specification and process technology mix. Industry-specific inputs include EV platform launch schedules and Inflation Reduction Act domestic content eligibility thresholds.
Macroeconomic conditions sit as an overlay; deviation in primary aluminum prices, interest rate environments affecting capital equipment investment, or trade policy shifts between NAFTA partners would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation pace and OEM platform adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
Russia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Automotive Winches System (AWS) Market
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
Motor Bearings Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Japan Automotive Hydraulic Actuators Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Brake Lathe Machine Market