
 Automotive Seat Belt Pretensioner Market | 2026-2036
Automotive Seat Belt Pretensioner Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seat Belt Pretensioner Market Intelligence
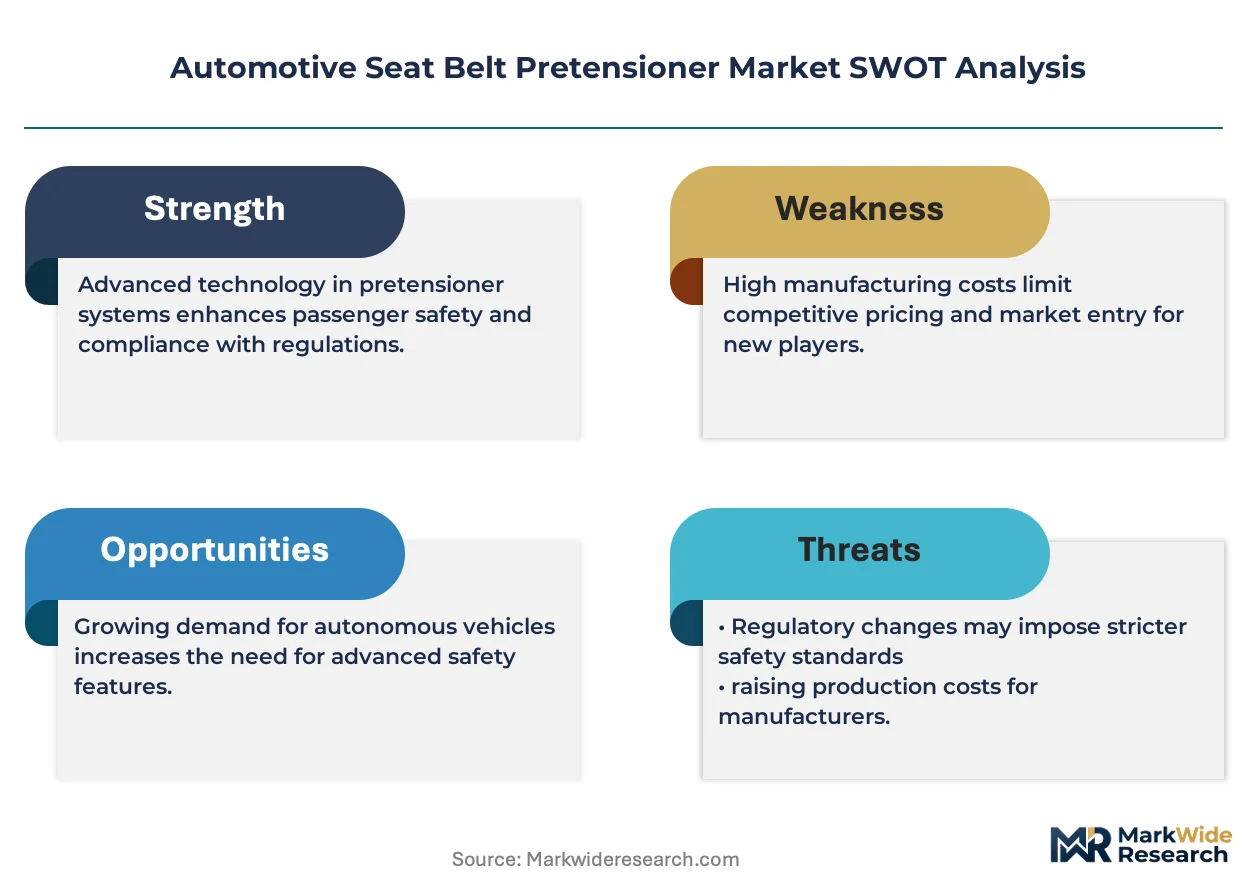
The shift from purely mechanical or pyrotechnic triggers to electronically controlled systems integrated with vehicle sensor suites is tilting the design of seat belt pretensioners. Autoliv Inc. leverages its scale in passive safety systems to offer integrated solutions. ZF Friedrichshafen AG competes by embedding advanced pretensioner logic within its broader active and passive safety electronics portfolio. Tokai Rika Co. Ltd specializes in electromechanical components for Japanese automakers.
An automotive seat belt pretensioner is a safety device that tightens a seat belt to restrain an occupant securely during a collision. Pyrotechnic versions use a gas charge to retract the belt spool, while electric pretensioners use a motor, enabling reversible activation. Pyrotechnic pretensioners continue to dominate the market due to cost-effectiveness, but electric pretensioners represent the fastest-growing product type. The OEM segment constitutes the primary end-user channel, with devices factory-installed in passenger vehicles and light commercial vehicles.
Vehicle safety mandates from the US National Highway Traffic Safety Administration (NHTSA) and test protocols from Euro NCAP set stringent performance criteria for pretensioner activation speed and force. Concurrently, evolving GB standards in China and the introduction of Bharat NCAP in India are expanding the mandatory fitment of these devices in new vehicles. The central challenge for component manufacturers is allocating R&D capital between cost-optimized pyrotechnic systems and feature-rich, reversible electric pretensioners.
Market Dynamics
The market's core tension revolves around dual development paths. Manufacturers must simultaneously invest in cost-optimizing mature pyrotechnic pretensioners for mass-market vehicles while also funding the R&D for advanced, reversible electric systems integrated with ADAS sensor suites.
Growth Catalysts
- New Safety Mandates:The introduction of Bharat NCAP in India and evolving GB standards in China expand the mandatory fitment of pretensioners in mass-market vehicles.
- ADAS Integration:Advanced driver-assistance systems require reversible electric pretensioners for predictive activation, linking pretensioner demand to the adoption of active safety features.
- SUV Segment Demand:Strong consumer preference for SUVs, which feature higher safety content, increases the per-vehicle installation rate and sophistication of pretensioners.
Market Restraints
- Input Material Volatility:Reliance on specialized gas generants for pyrotechnic devices exposes manufacturers to cost fluctuations and supply chain vulnerabilities for these niche chemicals.
- Electric System Cost:The high unit cost of electric pretensioners limits their adoption in cost-sensitive vehicle platforms, slowing the transition away from pyrotechnic systems.
- OEM Channel Dependency:The market is dependent on new vehicle production cycles, as pretensioners are factory-installed, single-use devices with a negligible aftermarket.
Strategic Opportunities
- Light Commercial Vehicles:Expanding safety regulations for LCVs in markets like Mexico and Eastern Europe creates an opportunity to increase fitment in this underpenetrated category.
- Autonomous Driving Applications:Reversible electric pretensioners can reposition occupants in autonomous vehicles, creating a new use case beyond traditional crash scenarios.
- Software-Defined Control:The shift to centralized vehicle architectures enables selling pretensioner control logic as a software feature within a safety domain controller.
Industry Challenges
- Dual-Technology Investment:Manufacturers must allocate capital to both legacy pyrotechnic lines and new electric systems, stretching R&D budgets and engineering resources.
- Complex System Integration:Ensuring reliable communication between pretensioner control units and the expanding suite of ADAS sensors presents a significant software integration challenge.
- Lengthy Validation Cycles:New pretensioner designs require extensive testing to meet strict criteria from bodies like Euro NCAP and NHTSA, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seat Belt Pretensioner Market |
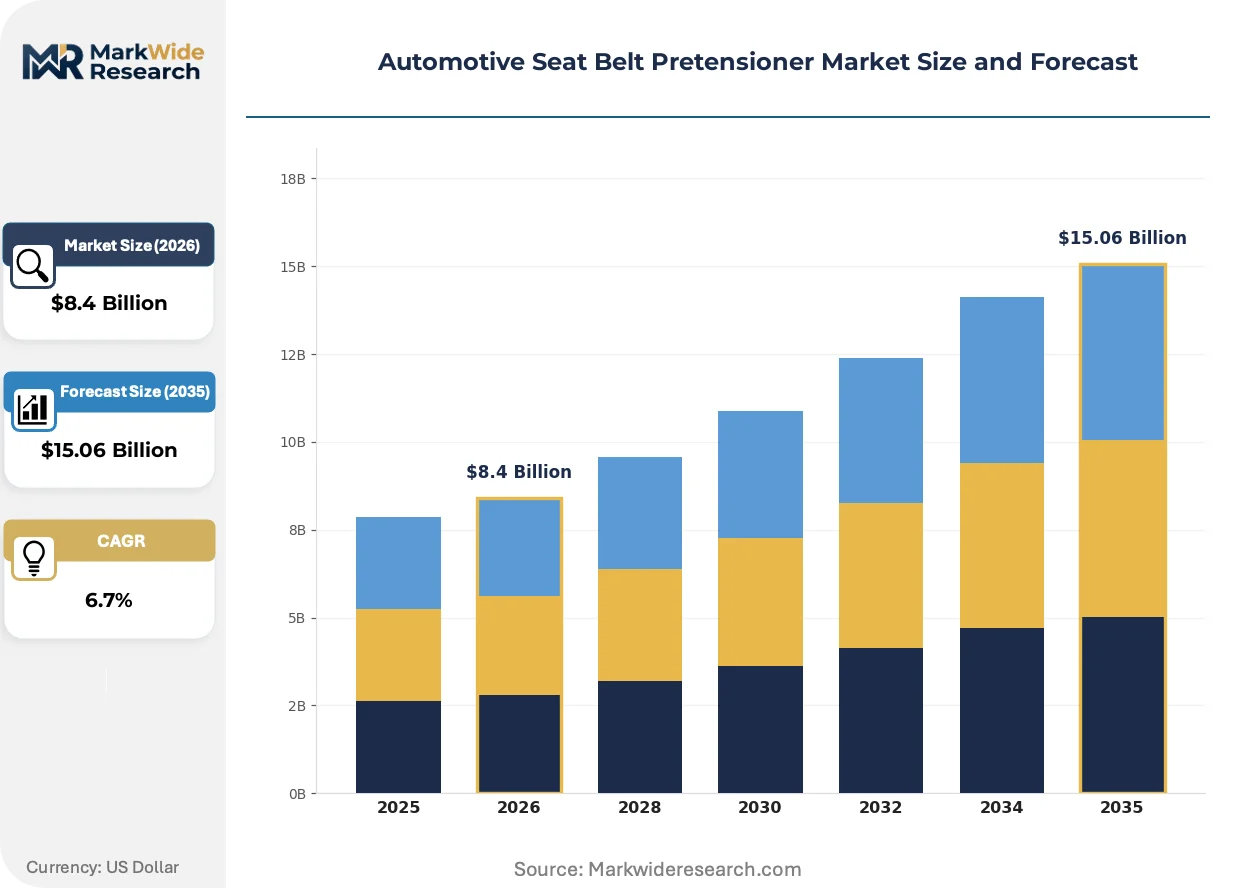
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pyrotechnic Pretensioner, Mechanical Pretensioner, Electric Pretensioner, Hydro-Mechanical Pretensioner Vehicle Type: Passenger Vehicles, Light Commercial Vehicles, Heavy Trucks, Buses Application: Driver Seat, Front Passenger Seat, Rear Seat, Child Safety Seat End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Safety Equipment Makers |
| Companies Covered | Autoliv Inc., Joyson Safety Systems, ZF Friedrichshafen AG, Tokai Rika Co. Ltd, Iron Force Industrial Co. Ltd, Continental AG, Hyundai Mobis Co. Ltd, ITW Automotive Products GmbH, Special Devices Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seat Belt Pretensioner Market Strategic Shifts & Innovations
A fundamental shift from standalone safety components to integrated nodes within a vehicle's electronic nervous system is the defining theme. This transition prioritizes software-defined functionality and data exchange with other vehicle systems, particularly advanced driver-assistance systems.
Reversible electric pretensioners use a small motor to tighten the belt, allowing for repeated, non-destructive activation. Automakers are adopting these systems in premium vehicles equipped with pre-crash sensing capabilities. This technology is collapsing the distinction between active and passive safety by enabling pre-emptive restraint before an impact occurs.
The latest Euro NCAP test protocols award higher scores for vehicles with advanced occupant protection systems that react to a wider range of crash scenarios. This incentivizes automakers to install more sophisticated pretensioners, including electric versions, across more of their model lineups. The mid-size and compact vehicle segments are most affected, accelerating technology adoption beyond luxury models.
Automakers are increasingly bundling advanced safety features into tiered packages as optional add-ons or standard equipment on higher trims. This moves pretensioner technology from a baseline commodity to a feature differentiator tied to ADAS packages. This trend is most visible in the North American and European markets for new passenger cars.
Automotive Seat Belt Pretensioner Market Segmentation
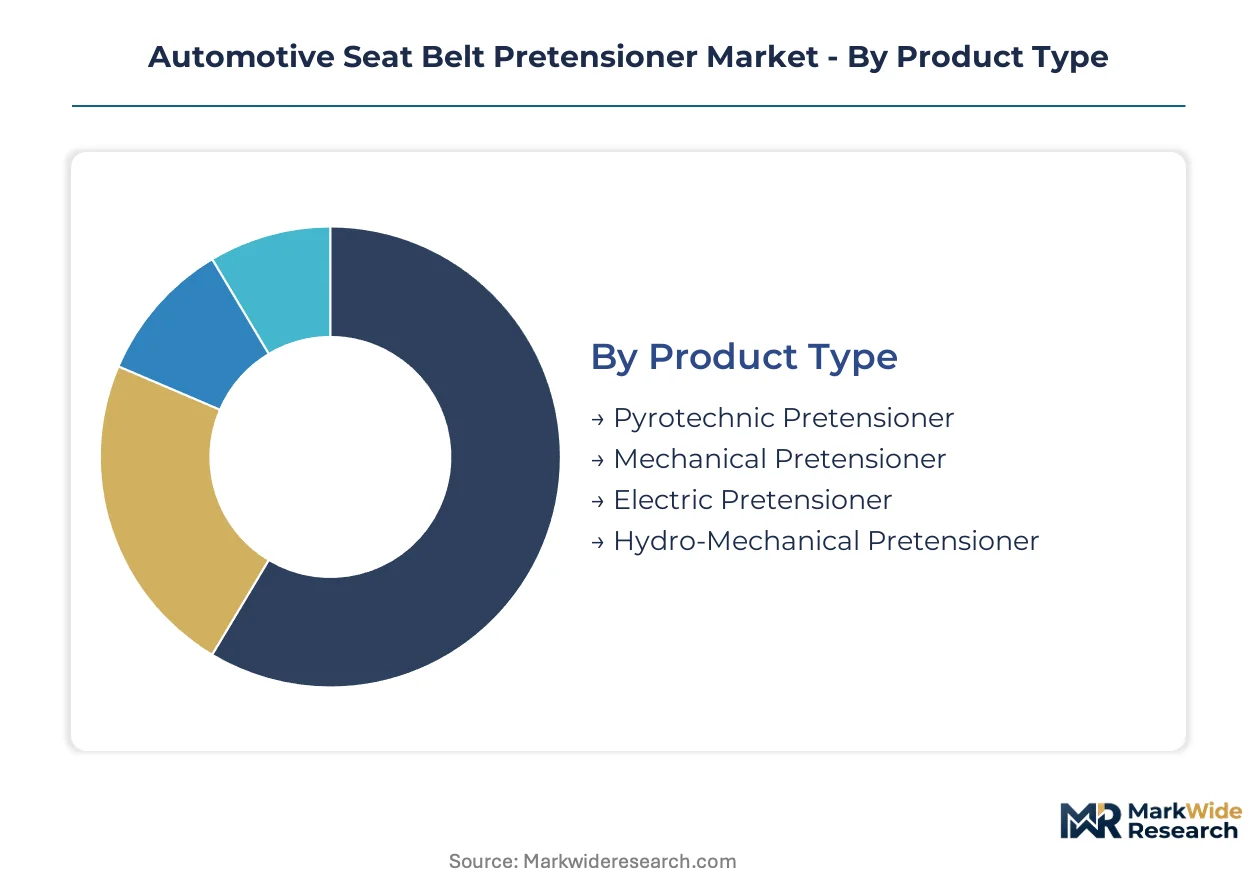
The Automotive Seat Belt Pretensioner Market segments reflect distinct technological maturity levels and adoption cycles across various vehicle types and end-user channels. Understanding these segments helps manufacturers allocate development resources and target specific market opportunities.
Product Type:
Product type segmentation reveals the varied development timelines for pretensioner technologies, from mature mechanical systems to rapidly evolving electric variants.
- Pyrotechnic Pretensioner:These devices utilize a small gas charge to rapidly retract the seat belt webbing during a collision, providing immediate occupant restraint. Demand for these cost-effective systems concentrates in mass-market passenger vehicles and light commercial vehicles, particularly in emerging economies due to their proven reliability and lower unit cost.
- Electric Pretensioner:Electric pretensioners employ an electric motor to tighten the seat belt, offering reversible activation and precise control. This technology is increasingly adopted in premium passenger vehicles and SUVs, where integration with advanced driver-assistance systems (ADAS) allows for pre-emptive restraint based on pre-crash sensor data.
- Mechanical Pretensioner:Mechanical pretensioners rely on mechanical linkages and springs, often triggered by deceleration sensors, to tighten the seat belt. These systems are older technology, primarily found in some entry-level vehicles or as supplementary devices.
- Hydro-Mechanical Pretensioner:Hydro-mechanical systems combine hydraulic pressure with mechanical components for seat belt retraction, offering a balance of speed and force. These are less common than pyrotechnic or electric types, finding niche applications.
Pyrotechnic Pretensioner dominates the installed base. Electric Pretensioner is where expansion concentrates.
Vehicle Type:
Vehicle type segmentation highlights the differing safety requirements and volume potential across automotive categories, influencing pretensioner design and fitment rates.
- Passenger Vehicles:This segment includes sedans, hatchbacks, and SUVs, which represent the largest volume for pretensioner installation due to stringent safety regulations and high production numbers. Strong consumer preference for SUVs, which often feature higher safety content, drives increased per-vehicle installation rates.
- Light Commercial Vehicles:LCVs, such as vans and pickup trucks, are experiencing expanding safety regulations, particularly in markets like Mexico and Eastern Europe. This creates a significant opportunity for increased pretensioner fitment as manufacturers seek to meet evolving compliance standards.
- Heavy Trucks:Heavy trucks incorporate pretensioners to enhance driver and passenger safety, particularly given the higher kinetic energy involved in potential collisions. Fitment is standard in many regions, driven by occupational safety mandates.
- Buses:Buses include city buses, coaches, and school buses, where pretensioners are critical for occupant protection, especially for drivers and front-row passengers. Safety standards for buses are evolving globally to improve overall crashworthiness.
Passenger Vehicles drive the largest volumes. Light Commercial Vehicles are gaining share fastest.
Application:
Application segmentation illustrates the critical safety hierarchy within a vehicle, with front-row occupants typically receiving the most advanced restraint systems.
- Driver Seat:The driver seat consistently features pretensioners as a primary safety measure, mandated by virtually all global safety regulations. This application requires robust and reliable systems to protect the vehicle operator during impact scenarios.
- Front Passenger Seat:Pretensioners for the front passenger seat are standard in most modern vehicles, mirroring the safety provisions for the driver. Evolving safety standards, like those from Euro NCAP, incentivize sophisticated systems for all front-row occupants.
- Rear Seat:Rear seat pretensioner fitment is becoming more common, particularly in premium vehicles and as optional safety packages. This trend responds to increasing consumer demand for comprehensive occupant protection.
- Child Safety Seat:While child safety seats have their own restraint mechanisms, vehicle-integrated pretensioners can enhance their effectiveness by reducing slack in the vehicle's seat belt system, improving overall child occupant protection.
Driver Seat applications are foundational. Rear Seat applications are seeing the steepest expansion trajectory.
End User:
End-user segmentation clarifies the primary channels through which pretensioners reach the market, heavily skewed towards factory installation in new vehicles.
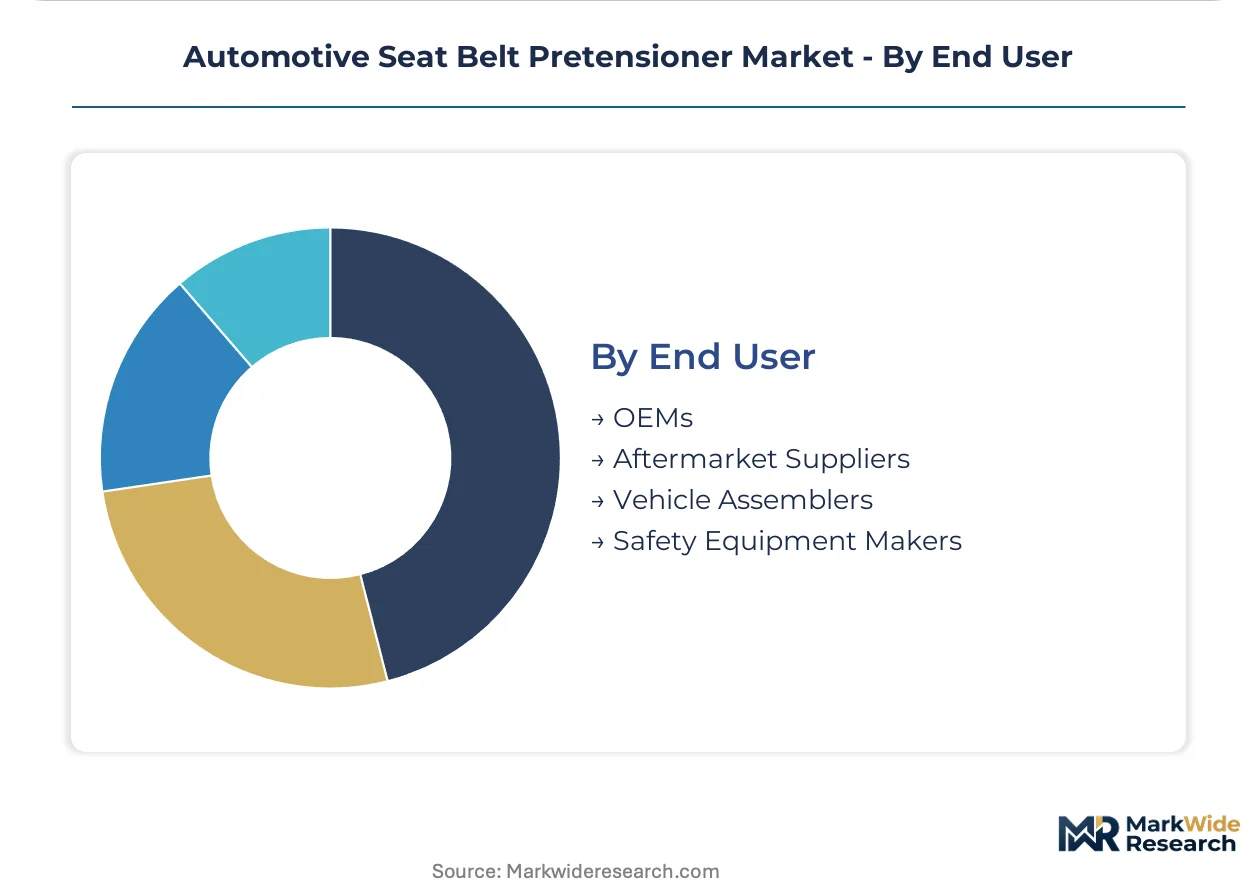
- OEMs:Original Equipment Manufacturers constitute the primary end-user channel, integrating pretensioners directly into new passenger vehicles and light commercial vehicles during the assembly process. This segment is characterized by long design cycles and high volume contracts.
- Vehicle Assemblers:Vehicle assemblers, often distinct from the brand-owning OEMs, procure pretensioners for integration into vehicles produced at their plants. Demand is concentrating in new vehicle assembly plants across Mexico, India, and parts of Eastern Europe.
- Aftermarket Suppliers:Aftermarket suppliers provide replacement pretensioners, primarily for vehicles involved in collisions where the original pretensioner has deployed. This segment represents a smaller portion of the market due to the single-use nature of most pretensioners.
- Safety Equipment Makers:Safety equipment makers specialize in producing various automotive safety components, including pretensioners, which they then supply to OEMs and vehicle assemblers. These firms focus on advanced research and development for next-generation systems.
OEMs represent the largest procurement channel. Vehicle Assemblers are the focus of new supply chain development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive seat belt pretensioners concentrates in vehicle assembly plants across key manufacturing hubs. OEMs and vehicle assemblers in these regions represent the primary procurement channel for these essential safety components. This concentration reflects the globalized nature of automotive production and safety technology adoption.
Mexico
Expanding light commercial vehicle (LCV) safety regulations and growing automotive production drive demand in Mexico. The country's evolving safety standards for new vehicles are increasing mandatory fitment rates for pretensioners. Automotive assembly corridors in states like Nuevo León and Guanajuato are rapidly increasing pretensioner installation in locally produced vehicles.
India
The introduction of Bharat NCAP and rising passenger vehicle sales are significant demand drivers in India. Bharat NCAP expands mandatory fitment of advanced safety devices, including pretensioners, in new vehicles. Vehicle manufacturing clusters in Pune and Chennai are seeing increased procurement for both pyrotechnic and electric pretensioner systems.
Germany
Premium vehicle production and the integration of advanced driver-assistance systems (ADAS) for electric pretensioners define the German market. Euro NCAP test protocols incentivize sophisticated pretensioner systems in new vehicle models across all segments. Automotive R&D centers in Stuttgart and Munich focus on integrating advanced pretensioner logic into broader safety electronics portfolios.
China
Evolving GB standards and rapid growth in the SUV segment underpin China's pretensioner market expansion. Evolving GB standards are expanding mandatory fitment requirements across various vehicle types, including mass-market models. Major automotive production bases in the Yangtze River Delta and Pearl River Delta are driving high-volume pretensioner procurement for domestic and export vehicles.
United States
Strong consumer preference for SUVs and stringent NHTSA safety mandates shape the market in the United States. The US National Highway Traffic Safety Administration (NHTSA) sets stringent performance criteria for occupant restraint systems. Automotive manufacturing hubs in Michigan and the Southeast are integrating advanced pretensioner technology into new vehicle platforms, particularly for larger vehicles.
Automotive Seat Belt Pretensioner Market Key Industry Players
Channel-controlling players compete with product-specialist players in the automotive seat belt pretensioner market, creating a tiered competitive environment. The market structure features large, integrated safety system providers alongside focused component manufacturers specializing in electromechanical solutions. These integrated providers often leverage their extensive safety portfolios to offer comprehensive solutions to global OEMs. Competitive moves include strategic partnerships for ADAS integration, continuous R&D investment in electric pretensioner technologies, and geographic expansion into emerging automotive production hubs.
Specialists in passive safety systems include Autoliv Inc., which leverages its scale to deliver integrated solutions across vehicle platforms, particularly in pyrotechnic and early-generation electric pretensioners. ZF Friedrichshafen AG, a German-based company, occupies a position as a broad active and passive safety electronics provider, embedding advanced pretensioner logic within its wider portfolio for premium vehicle segments. Tokai Rika Co. Ltd, a Japanese company, exemplifies a focus on electromechanical components, primarily serving Asian automakers with cost-effective and reliable solutions. These players collectively anchor the market's innovation trajectory and supply chain dynamics, influencing technology adoption rates globally.
| Leading Market Players |
|---|
| Autoliv Inc. |
| Joyson Safety Systems |
| ZF Friedrichshafen AG |
| Tokai Rika Co. Ltd |
| Iron Force Industrial Co. Ltd |
| Continental AG |
| Hyundai Mobis Co. Ltd |
| ITW Automotive Products GmbH |
| Special Devices Inc. |
| Others |
Cost & Logistics Intelligence
Automotive assembly corridors in Mexico, particularly in Nuevo León and Guanajuato, exert significant influence on pretensioner pricing, reflecting their high-volume procurement capacity and regional supply chain integration. This concentration of manufacturing capacity drives competitive pricing dynamics for both pyrotechnic and electric systems. The globalized nature of vehicle production means pricing strategies must adapt to regional cost structures and safety mandates.
Pricing Analysis
Cost-plus contracts, often indexed to raw material prices for specialized gas generants and steel, dominate pretensioner procurement. Price differentiation stems from certification level (e.g., Euro NCAP compliance) and volume scale for large OEM orders. Pricing pressure stems from automaker demands for cost-optimized pyrotechnic systems, particularly for mass-market vehicles. OEMs in emerging markets like India exhibit the highest price sensitivity, balancing safety mandates with vehicle affordability.
Supply Chain Analysis
Upstream feedstock for pyrotechnic pretensioners, especially specialized gas generants, originates primarily from chemical producers in China and Germany. Automotive component supply concentrates in Germany, Japan, and parts of Eastern Europe for electric systems. Single-source vulnerability for niche chemicals represents a structural supply chain risk. Distribution runs through Tier 1 automotive suppliers directly to vehicle assembly plants globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the shift towards software-defined vehicle architectures creating niches for specialized control logic and advanced electric systems. Automakers increasingly seek tailored pretensioner solutions for diverse vehicle platforms and safety feature bundles.
For Market Incumbents: Harden core pyrotechnic pretensioner lines through backward integration into critical gas generant production to mitigate input material volatility. Expand electric pretensioner R&D, focusing on seamless integration with ADAS sensor suites to counter new entrant specialization. Leverage existing OEM relationships to offer bundled safety system packages. This strategy defends against margin pressure from cost-sensitive vehicle platforms.
For New Entrants and Emerging Players: Establish a beachhead in software-defined control logic for electric pretensioners, targeting autonomous driving applications. Focus on reversible electric systems that offer predictive activation capabilities, appealing to premium vehicle segments. The light commercial vehicle (LCV) segment in Mexico offers a penetrable market due to expanding safety regulations. Go-to-market via strategic partnerships with ADAS platform providers.
For Investors and Strategic Acquirers: Long-term, this sits as a technology integration play because advanced safety systems are becoming increasingly software-defined and interconnected. Target acquisition archetypes include specialized software firms developing pretensioner control algorithms or electromechanical component innovators. A signal to watch is the increasing standardization of vehicle communication protocols for safety domain controllers. This indicates readiness for advanced, integrated restraint solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Control Investment | Enables predictive activation logic integration with ADAS for premium vehicles. |
| Geographic Manufacturing Footprint | Supports localized supply for vehicle assembly plants in India and Mexico. |
| Electric Pretensioner R&D | Accelerates transition from pyrotechnic systems in response to Euro NCAP incentives. |
| Supply Chain Diversification | Reduces reliance on single-source suppliers for niche gas generants. |
| ADAS Platform Partnership | Facilitates seamless integration of reversible pretensioners into advanced safety suites. |
Research Approach
A spread of perspectives from OEM procurement managers, Tier 1 safety system engineers, automotive R&D directors, and regulatory compliance specialists converged on the working assumptions. Primary interviews were validated against secondary sources including NHTSA crash data, Euro NCAP test protocols, and vehicle production statistics. This approach allowed for bottom-up data aggregation and top-down market sizing triangulation.
The demand-supply balance for pretensioners was modeled across the analysis window, considering vehicle production forecasts and safety mandate evolution. Segmentation dimensions included product type, vehicle type, application, and OEM integration level. Compound annual growth rates were derived from historical trends and projected technological adoption curves. Key inputs included ADAS fitment rates and regional regulatory timelines.
Macroeconomic conditions sit as an overlay; deviation in global vehicle production or consumer spending would shift the trajectory. Forecasts reflect documented assumptions regarding safety regulation enforcement and technological advancements. Cross-checking against vehicle safety component market benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Automotive Friction Brake System Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Europe Adaptive Steering Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Whiplash Protection System Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Global Highway Driving Assist Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Automotive Radar Applications Market
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Brazil Airbag Systems Market