
 Global Motorcycle Carbon Ceramic Brake Rotors Market | 2026-2036
Global Motorcycle Carbon Ceramic Brake Rotors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Motorcycle Carbon Ceramic Brake Rotors Market Outlook
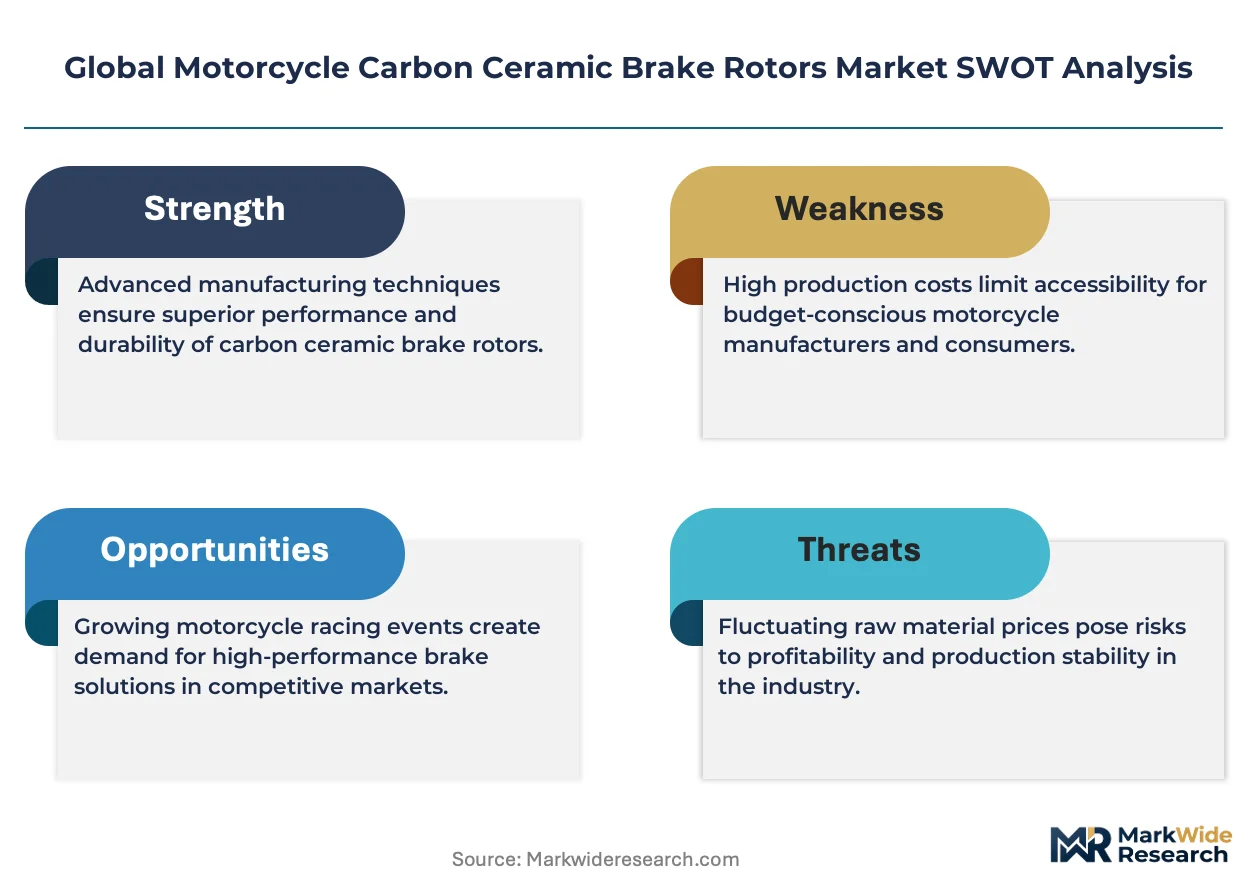
Aftermarket distribution for premium brake components is tilting toward specialized motorsport retailers and direct-to-builder channels. Brembo leverages vertical integration across carbon fiber weaving and ceramic matrix infiltration to sustain margin control. SGL Carbon anchors supply through captive production of carbon-ceramic preforms, while AP Racing competes via racing-focused product specialization.
Motorcycle carbon ceramic brake rotors consist of a silicon carbide-reinforced ceramic matrix composite, typically manufactured through chemical vapor infiltration or liquid silicon infiltration processes, delivering operating temperatures exceeding 1,000°C with minimal thermal fade. High-performance rotors and racing rotors dominate margin pools due to low-volume, high-specification production economics. Street motorcycle applications lead volume absorption, though racing motorcycles command premium positioning through technology transfer from motorsport validation programs.
EMA's MDR framework and REACH substance restrictions shape material composition standards for friction components sold across Europe, while Japan's METI enforces JIS standards on aftermarket brake system imports. The US NHTSA maintains FMVSS compliance thresholds for original equipment brake assemblies. Stakeholders must monitor regulatory divergence between ceramic matrix composite certification pathways and emerging electronic braking system integration mandates.
Market Dynamics
Thermal management requirements in superbike and hypersport segments are intensifying procurement specifications for carbon ceramic brake rotors, while EU F-Gas Regulation and REACH compliance frameworks tighten material composition standards across European supply chains.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on fluorinated greenhouse gases are accelerating substitution toward ceramic matrix composites in high-performance braking systems across German and Italian manufacturing corridors.
- Silicon carbide infiltration:Advances in liquid silicon infiltration processes are reducing production cycle times and improving yield rates for complex rotor geometries demanded by racing validation programs.
- Emilia-Romagna motorsports cluster:Concentrated demand from Italy's precision engineering hub is creating localized economies of scale for specialized carbon-ceramic preform suppliers serving OEM and aftermarket channels.
Market Restraints
- Carbon fiber precursor costs:Volatility in polyacrylonitrile pricing and limited weaving capacity constrains margin expansion for rotor manufacturers dependent on third-party preform supply.
- REACH substance restrictions:ECHA's evolving candidate list for Substances of Very High Concern creates compliance uncertainty for friction material formulations and ceramic matrix binders.
- Cast iron substitution:Conventional cast iron rotors retain cost advantage in street motorcycle volume segments, limiting carbon ceramic penetration below 600cc displacement categories.
Strategic Opportunities
- Japan's precision manufacturing corridor:Underdeveloped aftermarket distribution for premium brake components in METI-regulated markets offers channel expansion potential for specialized motorsport retailers.
- Electronic braking integration:Convergence of carbon ceramic thermal performance with ABS and cornering-ABS systems creates specification pull from hypersport OEMs integrating Bosch and Continental braking electronics.
- Direct-to-builder channels:Custom motorcycle builders and track-day specialists are bypassing traditional distribution tiers, enabling margin capture for manufacturers with configurators and technical support infrastructure.
Industry Challenges
- Chemical vapor infiltration expertise:Scarce technician pools for CVI reactor operation and process control limit capacity scaling at specialized ceramic matrix composite facilities.
- EMA MDR certification timelines:Extended conformity assessment procedures for friction components under the EU Medical Device Regulation framework create launch delays for racing-derived street applications.
- Legacy system integration:Retrofit compatibility with existing master cylinder calibrations and ABS modulation profiles complicates aftermarket product development for multi-brand motorcycle portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Motorcycle Carbon Ceramic Brake Rotors Market |
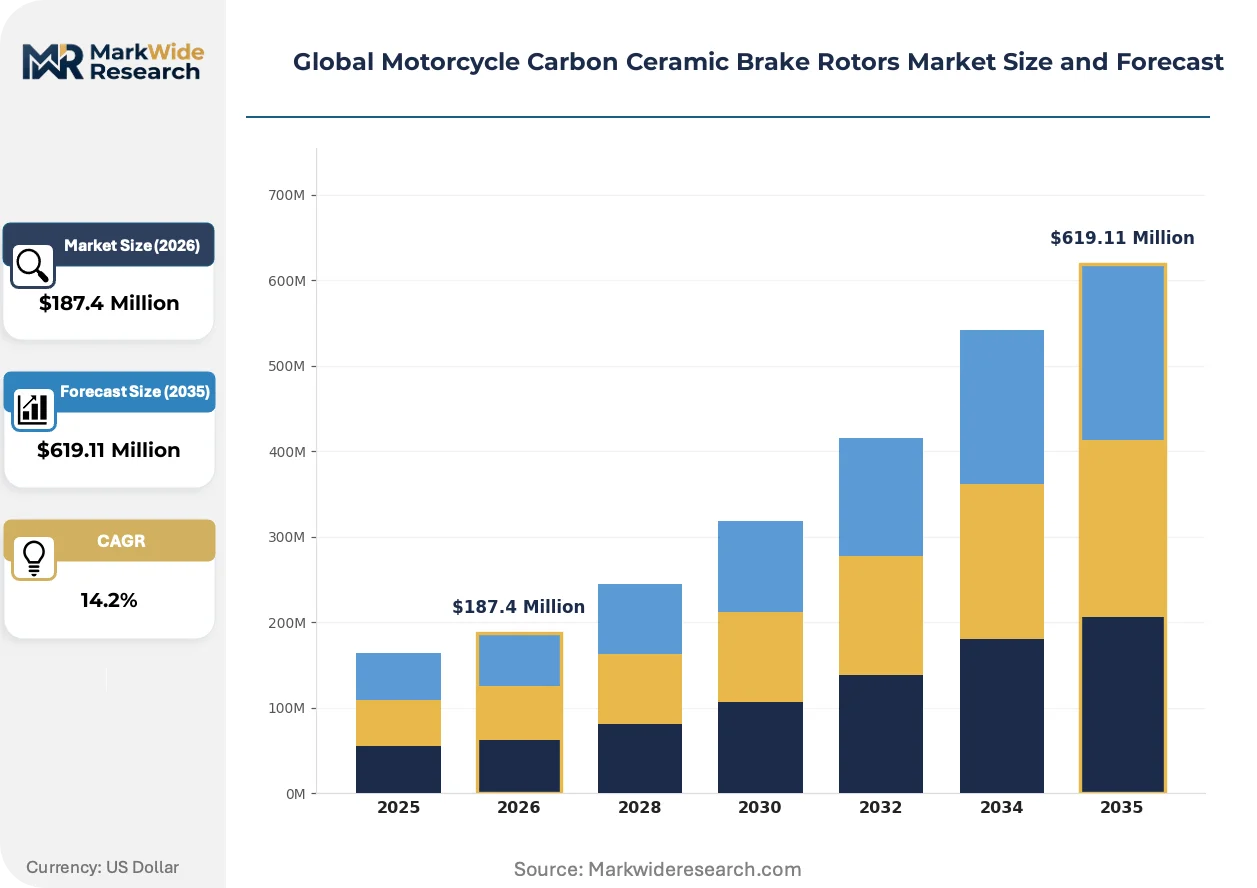
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Rotors, High-Performance Rotors, Racing Rotors, OEM Rotors End User: Motorcycle Manufacturers, Aftermarket Retailers, Racing Teams, Individual Consumers Application: Street Motorcycles, Off-Road Motorcycles, Racing Motorcycles, Touring Motorcycles Technology: Disc Brake Technology, Integrated Braking Systems, Electronic Braking Systems, Conventional Brake Systems |
| Companies Covered | Brembo, LEMYTH, BrakeTech, AP Racing, SGL Carbon, EBC Brakes, Performance Friction, Rotora, Surface Transforms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Motorcycle Carbon Ceramic Brake Rotors Market Strategic Shifts
Manufacturing process intensification and regulatory material restrictions are compressing traditional supply chain configurations while opening asymmetric advantages for vertically integrated producers with captive carbon fiber and ceramic infiltration capabilities.
Short-fiber chopped carbon preforms reinforced with silicon carbide matrices are collapsing cost structures for mid-performance street applications that previously required continuous fiber architectures. Japanese and German OEMs are adopting these materials for 600-1000cc sportbike platforms where thermal duty cycles approach racing thresholds. The technology is collapsing the historical price gap between cast iron and carbon ceramic solutions in premium street segments.
REACH substance restrictions on hexavalent chromium and certain phenolic resin precursors are forcing reformulation of ceramic matrix binders and friction surface coatings. ECHA's 2023-2024 updates to the Authorization List are compelling Italian and German suppliers to qualify alternative high-temperature polymers. Racing rotor manufacturers with established motorsport validation programs are leveraging existing test data to accelerate compliance certification for street-legal product lines.
Specialized motorsport retailers are displacing traditional aftermarket distributors as the primary procurement channel for premium brake components in enthusiast segments. Track-day operators and racing schools in Germany, Italy, and Japan are consolidating purchase volumes through direct manufacturer relationships. This channel compression is most visible in Japan's Kanto and Kansai manufacturing belts where METI-registered importers face margin pressure from parallel direct sourcing.
Global Motorcycle Carbon Ceramic Brake Rotors Market Segmentation
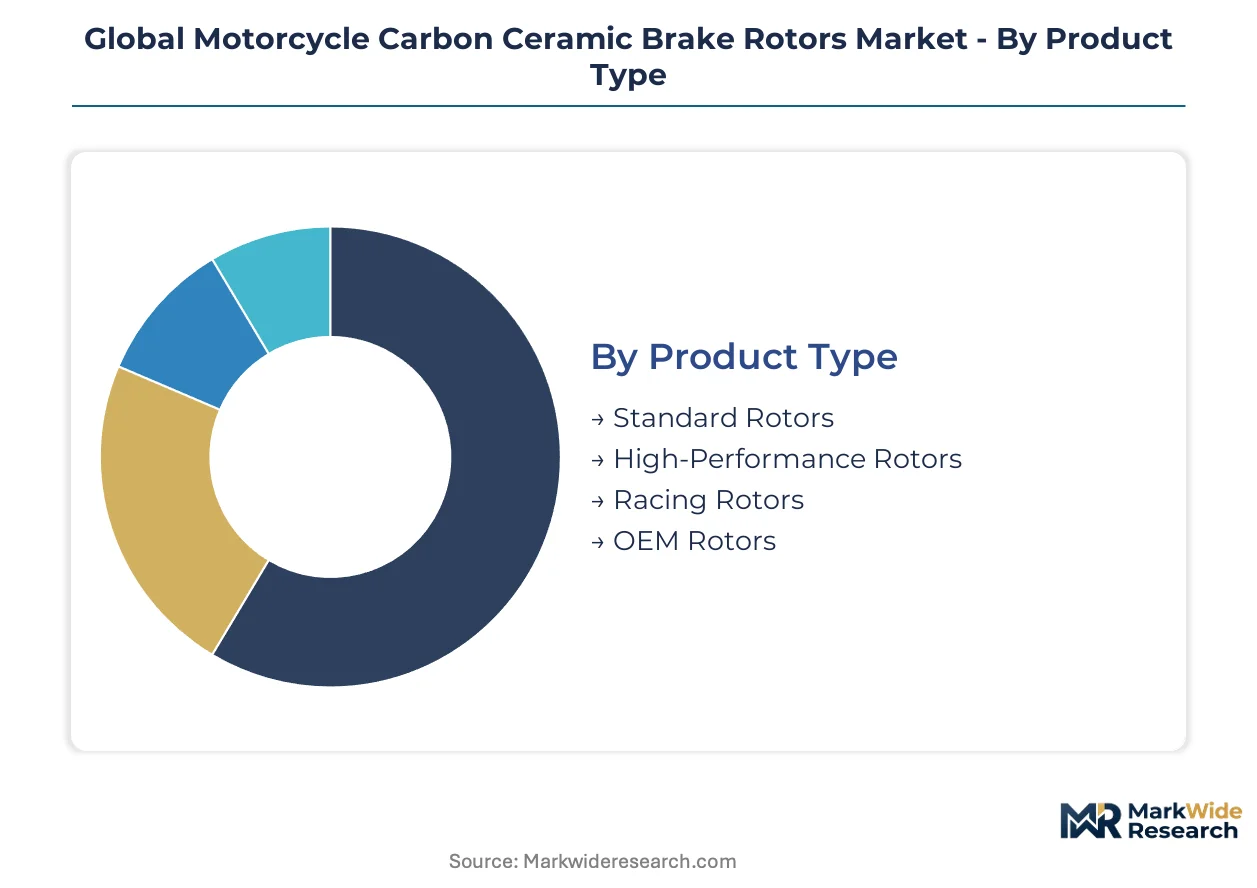
Carbon ceramic brake rotor markets fragment across performance tiers and procurement channels, with thermal duty cycles and certification requirements determining margin architecture. Segmentation reveals where silicon carbide matrix economics concentrate versus where cast iron substitution still dominates.
Product Type:
Mature racing derivatives now penetrate street-legal platforms, while emerging short-fiber preform technologies collapse cost structures in volume segments.
- Racing Rotors:Continuous carbon fiber architectures with liquid silicon infiltration withstand sustained temperatures exceeding 1,000°C. Emilia-Romagna motorsports clusters in Italy and Japan's Kanto precision corridor absorb the bulk of FIM-sanctioned procurement, driven by WSBK and MotoGP validation requirements.
- High-Performance Rotors:Hybrid preform designs bridge motorsport thermal capacity with street-legal compliance. German and Italian superbike OEMs specify these for 1000cc hypersport platforms where cornering-ABS integration demands predictable friction coefficients across temperature ranges.
- Standard Rotors:Chopped short-fiber silicon carbide composites serve premium street motorcycles in 600-1000cc displacement categories.
- OEM Rotors:Captive supply agreements with Brembo and SGL Carbon dominate procurement for factory-fit superbike assemblies.
Racing rotors handle the majority of throughput; high-performance rotors are gaining share fastest as thermal management requirements intensify in street-legal superbike platforms.
End User:
Channel structure varies sharply by certification burden, with direct procurement displacing traditional distribution where technical specification complexity rises.
- Racing Teams:FIM-homologated squads and national championship entrants purchase through technical partnership frameworks with preform suppliers. These relationships bypass distributor markups and embed telemetry-based wear monitoring.
- Motorcycle Manufacturers:BMW Motorrad, Ducati, and Kawasaki integrate carbon ceramic rotors into flagship hypersport and superbike platforms, sourcing through multi-year supply agreements with vertically integrated ceramic matrix composite producers.
- Aftermarket Retailers:Specialized motorsport retailers in Germany, Italy, and Japan consolidate enthusiast demand from track-day operators.
- Individual Consumers:Custom builders and high-mileage touring riders purchase through direct-to-builder configurators with technical support infrastructure.
Motorcycle manufacturers absorb the dominant procurement volume; racing teams are expanding most quickly as national championship grids proliferate across Europe and Asia-Pacific.
Application:
Street-legal thermal duty cycles increasingly approximate racing thresholds, blurring traditional application boundaries.
- Street Motorcycles:600-1000cc sportbike platforms in Germany and Italy now specify carbon ceramic rotors where cornering-ABS and electronic braking integration demands thermal stability. Short-fiber preform cost reductions are accelerating penetration in this segment.
- Racing Motorcycles:MotoGP, WSBK, and national superbike championships mandate carbon ceramic solutions for sustained high-speed braking zones. Validation data from these programs cascades into street-legal product development timelines.
- Touring Motorcycles:Heavyweight GT platforms with integrated luggage and passenger loads require fade-resistant braking for alpine and coastal mountain routes.
- Off-Road Motorcycles:Enduro and motocross applications remain limited by impact damage susceptibility and cost constraints relative to cast iron alternatives.
Street motorcycles command the largest installed base; racing motorcycles show the steepest expansion trajectory as homologation requirements tighten across FIM-sanctioned series.
Technology:
Electronic braking convergence is reshaping specification requirements for thermal management components.
- Electronic Braking Systems:Bosch and Continental cornering-ABS modules require predictable friction coefficients across temperature ranges that carbon ceramic matrices deliver. German and Japanese OEMs specify these for flagship hypersport platforms.
- Integrated Braking Systems:Linked front-rear actuation demands matched thermal expansion characteristics across rotor pairs, favoring ceramic matrix consistency over cast iron variability.
- Disc Brake Technology:Conventional hydraulic actuation remains standard across mid-displacement street motorcycles.
- Conventional Brake Systems:Cable-actuated drums and discs persist in emerging market volume segments below 400cc displacement.
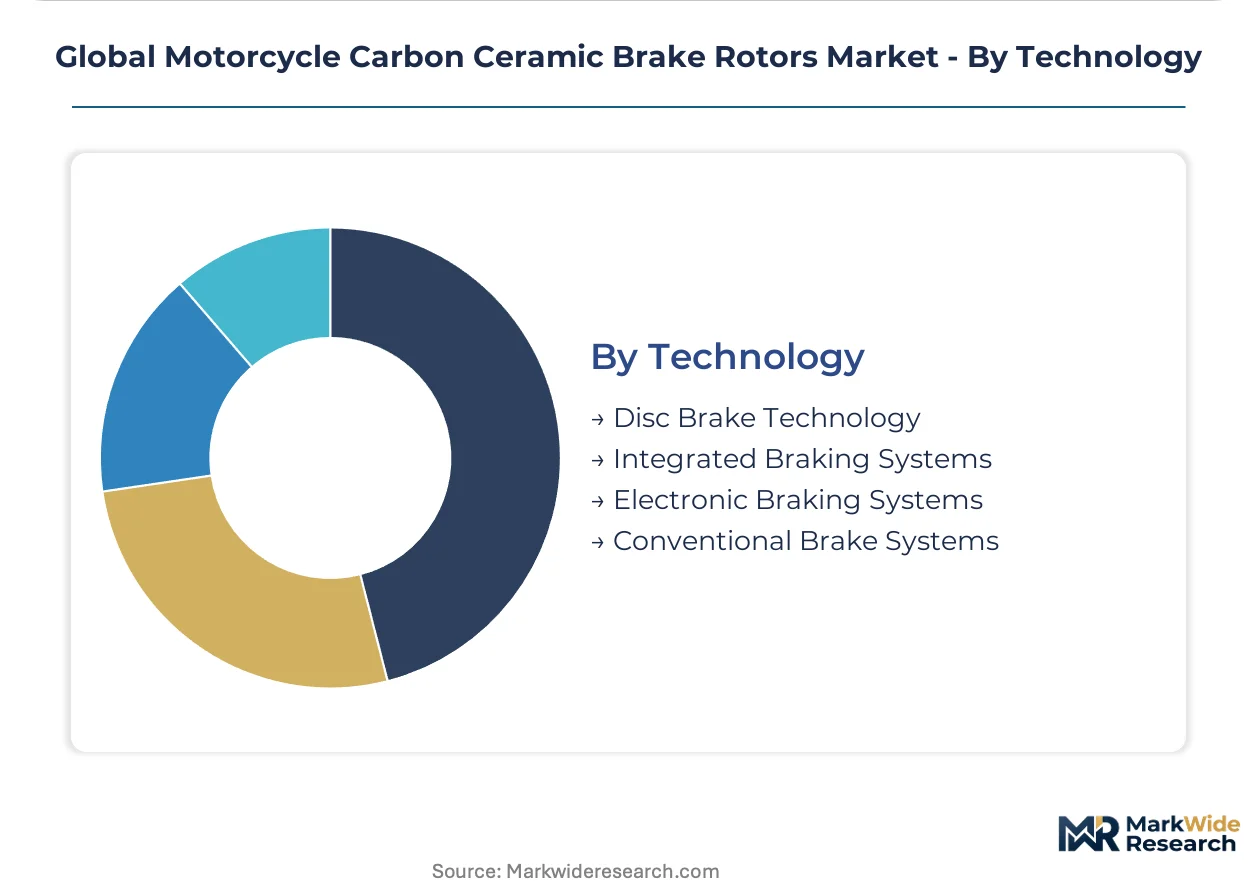
Disc brake technology maintains the broadest installed footprint; electronic braking systems are climbing fastest as OEMs integrate advanced rider assistance across premium model lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for carbon ceramic brake rotors through its precision manufacturing corridor, while Japan's METI-regulated aftermarket channels compress margins for equivalent specifications. This asymmetry reflects divergent distribution structures and regulatory enforcement intensity across the two manufacturing hubs.
Germany
BMW Motorrad and KTM anchor OEM demand for hypersport braking systems in the Bavarian manufacturing belt. The KBA enforces stringent type-approval protocols for friction components entering the German market. Stuttgart's automotive supplier cluster hosts specialized ceramic matrix composite facilities serving both motorcycle and motorsport applications.
Italy
Ducati and MV Agusta drive procurement specifications through the Emilia-Romagna motorsports cluster. REACH substance restrictions from ECHA compel reformulation of ceramic matrix binders for EU market access. Bologna's precision engineering corridor concentrates preform suppliers and brake system integrators within a 50-kilometer radius.
Japan
Kawasaki and Yamaha integrate carbon ceramic rotors into flagship superbike platforms manufactured in the Kanto precision corridor. METI's JIS standards create compliance barriers for aftermarket imports from European suppliers. The Kansai manufacturing belt hosts specialized distributors serving track-day operators and racing schools.
United States
Harley-Davidson and Indian Motorcycle explore carbon ceramic applications for heavyweight touring platforms. The NHTSA maintains FMVSS compliance thresholds for original equipment brake assemblies. California's aftermarket enthusiast market absorbs premium brake components through specialized motorsport retailers bypassing traditional distribution tiers.
United Kingdom
Triumph Motorcycles sources carbon ceramic rotors for limited-edition hypersport models. The UK's post-Brexit regulatory divergence from EU REACH creates dual certification burdens for friction material suppliers. The Midlands automotive cluster hosts testing facilities validating motorsport-derived brake technologies for street-legal conversion.
Global Motorcycle Carbon Ceramic Brake Rotors Market Competitive Environment
Vertically integrated ceramic matrix composite producers and specialized racing component fabricators split the market along the OEM-versus-aftermarket divide. Concentration is moderate, with three to five suppliers capturing the majority of high-performance procurement volumes. Two strategic archetypes dominate: captive preform manufacturers with in-house carbon fiber weaving, and racing-focused specialists leveraging motorsport validation data. Capacity expansion in silicon carbide infiltration and direct-to-builder channel development represent the primary competitive vectors.
Among European-based suppliers, Brembo and SGL Carbon occupy positions reflecting contrasting integration strategies, while AP Racing exemplifies the racing-specialist archetype. Brembo represents the vertically integrated model with captive control over carbon fiber preform production. SGL Carbon anchors supply through its composite materials heritage. AP Racing sits within the motorsport-validation tier, deriving specification authority from FIM-sanctioned racing programs.
| Leading Market Players |
|---|
| Brembo |
| LEMYTH |
| BrakeTech |
| AP Racing |
| SGL Carbon |
| EBC Brakes |
| Performance Friction |
| Rotora |
| Surface Transforms |
| Others |
Value Chain & Pricing Dynamics
Italy's Emilia-Romagna preform suppliers concentrate margin capture in racing rotor tiers where FIM-homologated specifications command configured-to-order premiums. Polyacrylonitrile fiber weaving capacity constraints in Germany and Japan feed downstream pricing power to vertically integrated ceramic matrix composite producers.
Pricing Analysis
Configured-to-order racing rotors carry 40-60% premiums over standard high-performance street variants due to continuous fiber architectures and liquid silicon infiltration cycle times. Price differentiation hinges on FIM certification tier and thermal duty cycle rating, with Bosch-integrated cornering-ABS specifications commanding additional markups. Cost compression in short-fiber preform tiers is intensifying because Japanese OEMs are qualifying chopped carbon architectures for 600-1000cc sportbike platforms. Individual consumers and custom builders show highest price sensitivity, while factory superbike procurement teams prioritize thermal stability over unit cost.
Supply Chain Analysis
Polyacrylonitrile precursor supply draws from Germany, Japan, and the United States, with carbon fiber weaving concentrated in Stuttgart's automotive supplier cluster and Italy's Bologna precision corridor. Raw material dependencies center on silicon carbide powder, phenolic resin precursors, and high-purity liquid silicon. Single-source vulnerability in chemical vapor infiltration reactor equipment creates capacity bottlenecks for specialized ceramic matrix facilities. Distribution runs through direct manufacturer relationships with BMW Motorrad and Ducati OEM procurement teams, supplemented by specialized motorsport retailers serving track-day operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetry-based wear monitoring and predictive replacement subscriptions are expanding faster than hardware sales as racing teams and track-day operators adopt outcome-based service models.
For Market Incumbents: Harden captive control over carbon fiber preform production to defend margin pools against emerging short-fiber preform specialists from Japan's Kanto corridor. Invest in REACH-compliant ceramic matrix binder reformulation ahead of ECHA's 2023-2024 Authorization List updates to preempt compliance-driven procurement switches. For New Entrants and Emerging Players: Pursue aftermarket distribution gaps in Japan's METI-regulated Kansai belt where parallel direct sourcing is displacing traditional importer margins. Target track-day operators and racing schools with technical partnership frameworks that bundle rotor supply with telemetry-based wear monitoring services. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive brake specialists seeking motorcycle portfolio diversification. Five-to-ten year viability hinges on electronic braking integration mandates spreading from German hypersport OEMs to mid-displacement platforms. Watch for Bosch and Continental cornering-ABS specification pull as the inflection signal for ceramic matrix composite demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Vapor Infiltration Capacity Expansion | Addresses technician scarcity constraining specialized ceramic matrix composite facilities in Stuttgart and Bologna corridors. |
| Backward Integration into Carbon Fiber Weaving | Mirrors Brembo's captive preform model to secure margin control against polyacrylonitrile price volatility. |
| Direct-to-Builder Configurator Launch | Captures enthusiast demand bypassing traditional aftermarket distribution tiers in California and Japan's Kanto belt. |
| REACH-Compliant Binder Reformulation | Accelerates street-legal certification for racing-derived product lines ahead of ECHA substance restrictions. |
| Telemetry Partnership with Track-Day Operators | Creates recurring revenue layer through predictive replacement subscriptions tied to wear monitoring data. |
Study Parameters
A standing panel of brake system procurement managers at German and Italian superbike OEMs, ceramic matrix composite plant engineers in Stuttgart and Bologna, and FIM technical directors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from KBA type-approval databases, METI JIS standard filings, and ECHA REACH candidate list updates. Bottom-up rotor shipment tallies by displacement category and top-down OEM procurement spend estimates were triangulated to converge on market sizing.
Scenario-bracketing around EU F-Gas Regulation enforcement intensity and silicon carbide infiltration yield improvement curves bounded the projection range across the analysis window. Segmentation dimensions modeled include rotor performance tier, end-user procurement channel, application thermal duty cycle, and electronic braking integration specification. CAGRs were derived from installed base growth rates and content-per-vehicle assumptions for cornering-ABS penetration in hypersport platforms. Forecast inputs incorporated polyacrylonitrile fiber capacity expansion timelines and FIM homologation requirement evolution.
Sensitivities concentrate around ECHA substance restriction timing, chemical vapor infiltration technician availability, and cornering-ABS mandate spread to mid-displacement categories. Forecasts reflect documented assumptions on OEM platform lifecycle cadence and racing championship grid growth. Cross-checking against NHTSA FMVSS compliance filing trends and METI aftermarket import registration data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
North America Automotive Airfilters Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
Autocatalyst Market
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
Insert Drive for Torque Wrench Market
Automotive Parts
Brazil Automotive Airfilters Market
Automotive Parts
Global EV Speed Reducer Market
Automotive Parts
Brazil Automotive Parts Magnesium Die Casting Market
Automotive Parts
Cabin Air Filter Housing Replacement Parts Market
Automotive Parts
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
Automotive Electric Vacuum Pump Market