
 Side Guard Door Beam Market | 2026-2036
Side Guard Door Beam Market Size, Share, and Industry Trends Forecast 2026-2036
Side Guard Door Beam Market Analysis
China is narrowing the gap in hot-stamped door beam capacity through dedicated lines serving domestic OEM platforms. Gestamp sustains integrated roll-forming and hot-stamping operations across multiple continents. Kirchhoff Automotive GmbH anchors European supply relationships with German and French OEMs. Benteler Automotive competes on tube-hydroforming expertise for structural hollow sections.
A side guard door beam is a structural reinforcement member installed within vehicle doors, typically fabricated from ultra-high-strength steel, aluminum extrusions, or fiber-reinforced composites, designed to absorb and distribute lateral impact energy during side collisions. The component must achieve specified intrusion resistance metrics while minimizing mass contribution to the door assembly. Steel retains dominance in mass-market passenger vehicles where cost sensitivity governs platform decisions, while aluminum captures share in premium SUVs and electric vehicle architectures where every kilogram of mass reduction extends range. Composite segments remain nascent but occupy strategic positions in motorsport-derived and limited-production applications where tooling amortization tolerates higher per-unit material costs.
NHTSA Federal Motor Vehicle Safety Standard 214 governs side-impact protection in the United States, mandating specific intrusion limits that directly determine beam section modulus requirements. Euro NCAP and the EU General Safety Regulation progressively tighten side-pole and mobile-deformable-barrier test protocols, compelling redesign cycles among European OEMs. ECE R95 harmonization efforts across UN member states create compliance complexity for suppliers serving multiple export markets. Stakeholders must monitor evolving battery-electric vehicle platform architectures, as skateboard chassis designs redistribute side-impact loads and may obsolete conventional door beam mounting strategies.
Market Dynamics
Automakers' mass-reduction mandates for battery-electric platforms are compressing legacy steel door beam architectures while forcing aluminum and composite substitution decisions at the program engineering stage.
Growth Catalysts
- Euro NCAP side-pole protocols:The 2026 test revision tightens intrusion limits, compelling OEMs to upgrade beam section modulus across European vehicle programs.
- Aluminum extrusion adoption:Premium SUV and electric vehicle architectures specify aluminum door beams to offset battery pack mass and extend driving range.
- Hot-stamping capacity expansion:China is installing dedicated press-hardening lines to serve domestic OEM platforms with ultra-high-strength steel solutions.
Market Restraints
- Aluminum price volatility:LME aluminum fluctuations compress supplier margins and destabilize long-term OEM supply agreements.
- Tooling amortization burden:Composite door beams require multi-cavity molds with 6-figure tooling costs that limit adoption to low-volume premium applications.
- ECE R95 harmonization friction:Divergent UN member state interpretations of side-impact certification create compliance redundancy for export-market suppliers.
Strategic Opportunities
- Skateboard chassis integration:Battery-electric platform side-impact load redistribution creates demand for novel door beam mounting geometries and attachment strategies.
- India passenger vehicle safety upgrade:Bharat NCAP implementation and mandatory side-impact testing open procurement opportunities for crash-rated beam suppliers.
- Continuous fiber thermoplastic composites:Automated fiber placement advances are narrowing the cost gap with metals for mid-volume electric vehicle programs.
Industry Challenges
- Hot-stamping process engineering talent:The shortage of press-hardening specialists constrains capacity ramp rates at new production facilities.
- Multi-material joining certification:OEM weld-bond specifications for steel-aluminum door assemblies extend validation timelines by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Side Guard Door Beam Market |
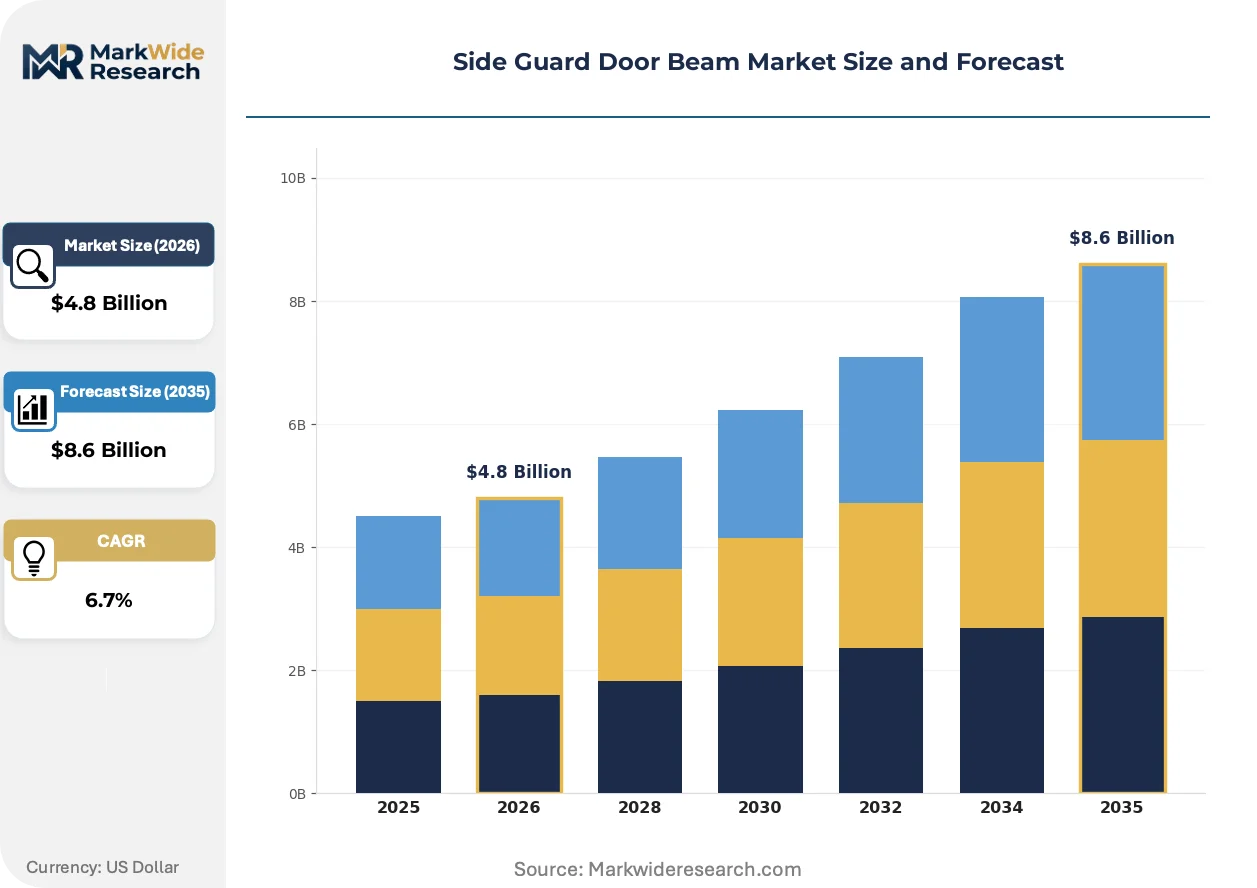
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Composite, Plastic Application: Passenger Vehicles, Commercial Trucks, SUVs, Minivans Manufacturing Stage: Forging, Stamping, Molding, Extrusion End User: OEMs, Aftermarket Suppliers, Automotive Manufacturers, Fleet Operators |
| Companies Covered | KVA Stainless, Kirchhoff Automotive GmbH, GNS America, IFB Automotive Pvt. Ltd, Founder Land, H-One Co. Ltd, Gestamp, Shiloh Industries, Benteler Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Side Guard Door Beam Market Emerging Trajectories
Digital engineering workflows and regulatory test protocol evolution are compressing traditional door beam development cycles while enabling topology-optimized designs previously uneconomical at production scale.
Generative design software coupled with additive manufacturing validation is digitizing door beam development from concept to production tooling release. BMW and Volkswagen engineering teams deploy topology optimization to minimize mass while maintaining NHTSA Federal Motor Vehicle Safety Standard 214 intrusion resistance. The technology is digitizing supplier-OEM collaboration models by collapsing iterative prototype cycles from months to weeks.
EU General Safety Regulation mandates for enhanced side-impact protection are forcing material specification upgrades across mid-range vehicle segments. The regulation eliminates cost-driven steel retention in C-segment platforms where aluminum substitution was previously deferred. French and German OEMs are accelerating hot-stamped ultra-high-strength steel adoption to meet 2026 compliance deadlines without radical architecture changes.
Direct OEM engagement with tier-two material converters is fragmenting traditional tier-one supplier relationships in door beam procurement. Tier-one integrators now compete with steel mills and aluminum extruders for platform engineering access and specification influence. This pattern concentrates in Germany where BMW and Volkswagen maintain active body-in-white engineering programs with multi-tier supplier involvement.
Side Guard Door Beam Market Segmentation
Door beam procurement cycles vary dramatically by material and manufacturing process, with some segments turning over on 3-year platform cycles while others persist across vehicle generations. Understanding these velocity differentials helps suppliers align capacity investments with actual replacement demand rather than static fleet size.
Product Type:
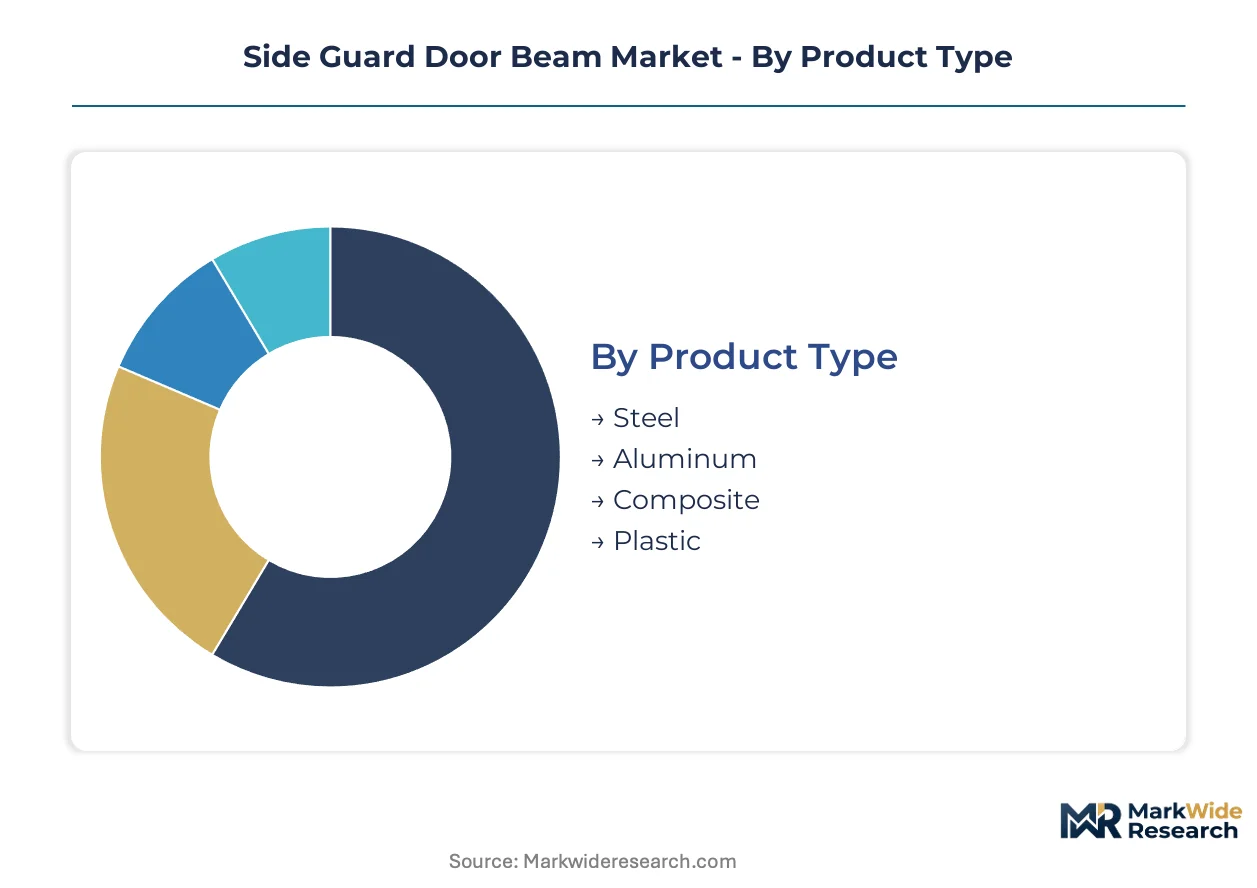
Steel door beams refresh slowest due to amortized tooling and conservative OEM validation timelines, while composite segments exhibit the most rapid specification churn as thermoplastic formulations mature.
- Steel:Ultra-high-strength boron steel grades dominate through hot-stamping and roll-forming processes, achieving intrusion resistance at the lowest per-unit cost. BMW and Volkswagen anchor demand in Germany, where Euro NCAP 2026 compliance deadlines are forcing section modulus upgrades across C-segment and above platforms without full aluminum conversion.
- Aluminum:6xxx-series extrusions and 7xxx-series hollow sections capture specification in electric vehicle architectures where battery pack mass creates urgent offset requirements. Premium SUV platforms specify aluminum door beams to extend driving range, with Chinese OEMs narrowing the capacity gap through dedicated press-hardening and extrusion investments.
- Composite:Continuous fiber thermoplastic solutions occupy motorsport-derived and limited-production applications where tooling amortization tolerates six-figure mold costs.
- Plastic:Short-fiber reinforced polymers serve secondary energy absorption roles in cost-constrained emerging market platforms where metallic primary beams are supplemented rather than replaced.
Steel dominates installed base. Aluminum is where expansion concentrates.
Application:
Passenger vehicle platforms generate the highest beam volumes but compress margins through consolidated procurement, while commercial truck applications sustain longer production runs with less frequent redesign.
- Passenger Vehicles:C-segment and D-segment sedans specify steel door beams as standard equipment, with aluminum penetration climbing fastest in electric vehicle derivatives where range anxiety dictates mass reduction. NHTSA Federal Motor Vehicle Safety Standard 214 governs intrusion limits for US-market programs.
- SUVs:Higher beltlines and larger door apertures demand enhanced section modulus, with premium architectures specifying aluminum extrusions to manage center-of-gravity implications of battery-electric powertrains.
- Commercial Trucks:Cab-over and conventional truck designs prioritize durability over mass reduction, with steel retention near-universal and replacement cycles tied to chassis longevity rather than styling refreshes.
- Minivans:Sliding door architectures complicate beam mounting geometries, with integrated rail-and-beam assemblies specified by Stellantis and Toyota for North American family vehicle platforms.
Passenger vehicles generate absolute volume. SUVs are climbing the fastest in specification value per vehicle.
Manufacturing Stage:
Forging and stamping processes concentrate in established supplier footprints with amortized capital, while extrusion capacity is expanding fastest to serve aluminum-intensive platform architectures.
- Hot Stamping:Press-hardening of boron steel blanks achieves tensile strengths exceeding 1500 MPa, with Gestamp and Kirchhoff Automotive GmbH sustaining integrated operations across multiple continents.
- Roll Forming:Continuous bending operations produce variable-section steel beams with tailored stiffness distribution, dominating high-volume European and Chinese passenger vehicle programs.
- Extrusion:Direct and indirect aluminum extrusion creates hollow sections with complex internal ribs, with capacity expansion concentrated in China to serve domestic OEM platforms.
- Molding:Compression and injection molding of thermoplastic composites remains constrained by cycle times and fiber orientation control, limiting adoption to low-volume specialty applications.
Stamping dominates current throughput. Extrusion is where capacity investment concentrates.
End User:
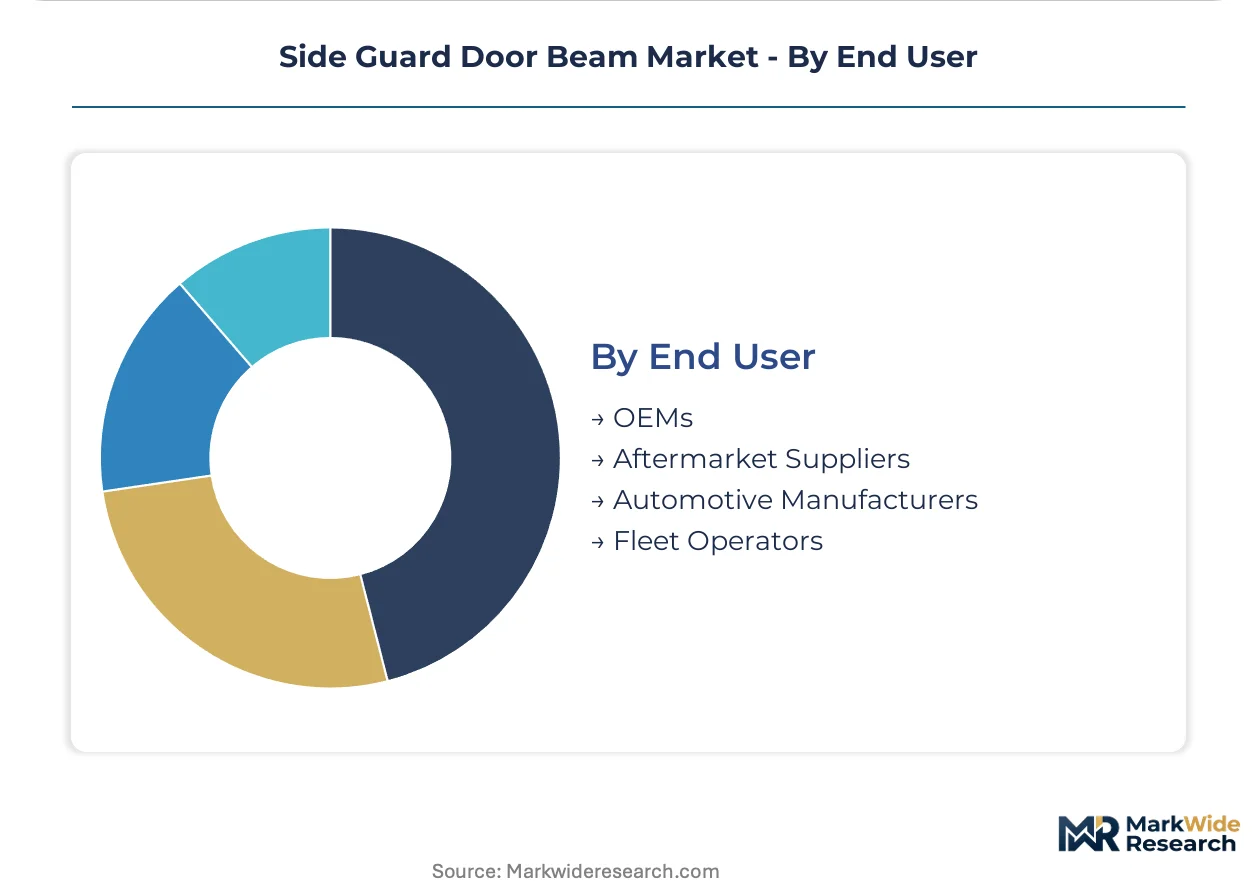
OEM direct procurement is fragmenting traditional tier-one relationships as automakers engage material converters earlier in platform development, while aftermarket demand remains negligible due to crashworthiness liability.
- OEMs:BMW and Volkswagen maintain active body-in-white engineering programs with multi-tier supplier involvement, specifying door beams at the platform architecture stage to optimize side-impact load paths.
- Automotive Manufacturers:Full-line producers consolidate beam procurement across vehicle families, leveraging volume to compress steel pricing while accepting aluminum premiums for electric vehicle derivatives.
- Fleet Operators:Commercial and rental fleet purchasers prioritize repair cost minimization, indirectly reinforcing steel specification through insurance and residual value calculations.
- Aftermarket Suppliers:Crash-rated beam replacement is essentially nonexistent due to liability exposure and the integral nature of door beam mounting in modern unibody structures.
OEMs dominate specification authority. Automotive manufacturers are where procurement consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA Federal Motor Vehicle Safety Standard 214 governs side-impact protection in the United States, anchoring regulatory stringency that shapes beam specifications across North American platforms. This framework cascades through export markets and influences material selection thresholds worldwide.
United States
Detroit Three automakers specify ultra-high-strength steel door beams for high-volume truck and SUV platforms, balancing intrusion resistance against mass targets. NHTSA compliance deadlines compress redesign cycles for 2026 model year refreshes. Manufacturing clusters concentrate in Michigan and Ohio, where integrated stamping operations serve just-in-sequence assembly requirements.
Germany
BMW and Volkswagen anchor advanced body-in-white engineering programs that specify aluminum extrusions for premium electric vehicle architectures. Euro NCAP 2026 side-pole protocol revisions tighten intrusion limits, forcing section modulus upgrades across C-segment and above platforms. Engineering activity concentrates in Munich and Wolfsburg, where multi-tier supplier involvement shapes platform decisions.
China
Domestic OEMs install dedicated hot-stamping lines to serve battery-electric vehicle platforms with press-hardened steel solutions. MIIT fuel consumption and new energy vehicle mandates accelerate mass-reduction procurement. Capacity expansion clusters in Shanghai and Guangzhou, where dedicated lines narrow the technology gap with European suppliers.
Japan
Toyota and Honda integrate door beam specifications at the platform architecture stage to optimize side-impact load paths for hybrid and electric powertrains. METI carbon neutrality roadmaps reinforce lightweighting priorities across vehicle segments. Production engineering concentrates in Aichi and Tochigi prefectures, where close supplier proximity enables rapid prototype iteration.
India
Bharat NCAP implementation and mandatory side-impact testing open procurement opportunities for crash-rated beam suppliers serving Maruti Suzuki and Hyundai Motor India. BIS automotive safety standards alignment with UN regulations creates compliance clarity for export-oriented suppliers. Manufacturing investment concentrates in Tamil Nadu and Haryana, where OEM assembly expansion drives tier-one localization.
Side Guard Door Beam Market Vendor Landscape
Capability concentration sits with integrated metallurgical specialists; scale advantage sits with high-volume stamping houses serving consolidated OEM procurement. The supplier base organizes around three strategic archetypes: hot-stamping specialists with press-hardening expertise, aluminum extruders capturing electric vehicle platform share, and roll-forming houses dominating cost-sensitive passenger vehicle programs. Competitive moves center on capacity expansion in China and strategic partnerships for skateboard chassis integration.
Among European-anchored engineering groups, Kirchhoff Automotive GmbH exemplifies the integrated metallurgical archetype with sustained multi-continent operations, while Benteler Automotive occupies a position within tube-hydroforming expertise for structural hollow sections. Gestamp represents the hot-stamping scale tier with integrated roll-forming and press-hardening capabilities across multiple continents. These three anchors illustrate how geographic footprint and process specialization stratify competitive positioning.
| Leading Market Players |
|---|
| KVA Stainless |
| Kirchhoff Automotive GmbH |
| GNS America |
| IFB Automotive Pvt. Ltd |
| Founder Land |
| H-One Co. Ltd |
| Gestamp |
| Shiloh Industries |
| Benteler Automotive |
| Others |
Supply Flow & Price Mechanics
LME aluminum volatility compresses supplier margins and destabilizes long-term OEM supply agreements, determining both pricing tier spreads and supply chain shape across steel-aluminum-composite procurement decisions. This commodity exposure forces tier-one integrators to absorb cost swings in contract structures while OEMs segment specifications by mass-reduction urgency.
Pricing Analysis
Chinese hot-stamped steel beams trade at a discount to German-engineered aluminum extrusions, reflecting capacity concentration and process maturity differentials. Three-tier pricing structure across premium aluminum, standard hot-stamped steel, and economy roll-formed grades segments the market by section modulus performance and certification tier. Pricing pressure stems from battery-electric platform mass mandates forcing aluminum substitution despite higher unit costs. Fleet operators and emerging-market OEMs exhibit highest price sensitivity, while premium electric vehicle programs prioritize intrusion resistance over procurement cost.
Supply Chain Analysis
Extended payment terms from BMW and Volkswagen engineering programs strain working capital for tier-two aluminum extruders serving German body-in-white programs. Supply concentrates in Germany for hot-stamping expertise, China for press-hardening capacity expansion, and Mexico for North American just-in-sequence delivery. Raw material dependencies center on boron steel blanks, 6xxx-series aluminum billet, and continuous fiber thermoplastic prepregs. Single-source vulnerability runs through Gestamp's integrated roll-forming operations for European C-segment platforms. Distribution runs through captive tier-one supplier networks with direct OEM platform engineering access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive lightweighting cycles position this market for recovery as battery-electric platform volumes inflect and Euro NCAP compliance deadlines force specification upgrades across European vehicle programs.
For Market Incumbents: Harden press-hardening process engineering capabilities against Chinese capacity expansion by securing captive boron steel supply agreements and embedding platform engineers within BMW and Volkswagen development teams. Deepen backward integration into aluminum billet casting to offset LME volatility exposure and defend margin position against emerging extrusion specialists. For New Entrants and Emerging Players: Pursue Bharat NCAP-driven procurement opportunities in India where Maruti Suzuki and Hyundai Motor India lack established hot-stamping supplier relationships. Target skateboard chassis integration programs for battery-electric platforms where novel door beam mounting geometries create specification white space absent entrenched incumbent relationships. For Investors and Strategic Acquirers: Euro NCAP 2026 side-pole protocol revision reshapes the acquisition landscape by forcing section modulus upgrades across C-segment and above platforms without full architecture redesigns. Long-term viability centers on suppliers with demonstrated NHTSA Federal Motor Vehicle Safety Standard 214 certification history and active OEM platform engineering engagement. Monitor MIIT fuel consumption mandate enforcement in China as the signal indicating domestic OEM aluminum substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Stamping Capacity Expansion | Secures ultra-high-strength steel supply for Euro NCAP 2026 compliance deadlines. |
| Aluminum Extrusion Backward Integration | Captures billet cost control for battery-electric platform mass-reduction mandates. |
| Skateboard Chassis Partnership | Redesigns door beam mounting for battery-electric load path redistribution. |
| Bharat NCAP Certification Investment | Opens procurement access to Maruti Suzuki and Hyundai Motor India platforms. |
| Continuous Fiber Thermoplastic Scale-Up | Narrows cost gap with metals for mid-volume electric vehicle programs. |
Methodological Framework
Desk research of NHTSA Federal Motor Vehicle Safety Standard 214 compliance filings, Euro NCAP test protocol documentation, and MIIT new energy vehicle production databases preceded structured interviews with OEM platform engineers, tier-one supplier procurement leads, hot-stamping process specialists, and aluminum extrusion operations managers. Secondary validation drew from IHS Markit vehicle production data, customs trade records for boron steel and aluminum billet flows, and SEC filings of listed automotive suppliers. Bottom-up beam content-per-vehicle estimates triangulated against top-down OEM procurement consolidation patterns.
Assumptions held fixed include NHTSA and Euro NCAP regulatory stringency trajectories, battery-electric platform architecture migration rates, and aluminum-steel relative price ratios. The analytical framework modeled demand across material type, vehicle class, propulsion architecture, and regional production cluster throughout the forecast period. CAGRs derived from segment-specific replacement cycle velocities and platform engineering timelines. Industry-specific inputs included door beam mass-per-vehicle specifications, press-hardening line capacity utilization rates, and OEM body-in-white engineering program cadence.
Sensitivities concentrate around LME aluminum price volatility, Euro NCAP protocol revision implementation timing, and Chinese domestic OEM platform standardization decisions. Forecasts reflect assumptions regarding regulatory compliance deadlines and battery-electric vehicle adoption curves without incorporating potential trade policy disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Front Collision Warning Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Two Wheeler Anti-Lock Braking System Market
Automotive Safety and Security Systems
Germany Airbag Systems Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Global Automotive Seat Belt Reminder Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Automotive Intelligent Headlight System Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Automotive Radar Applications Market
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Airbag Market