
 Global Automotive Electronic Stability Control Systems Market | 2026-2036
Global Automotive Electronic Stability Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Electronic Stability Control Systems Market Intelligence
The United States' Federal Motor Vehicle Safety Standard No. 126, mandating ESC on all new passenger vehicles, is realigning the cost-of-entry calculus for automakers. Robert Bosch GmbH leverages its extensive R&D in sensor fusion and software algorithms to maintain a leadership position. Continental AG competes on the strength of its integrated safety systems, combining ESC with other active safety features. ZF Friedrichshafen AG specializes in advanced chassis control systems for both passenger and commercial vehicles.
Automotive Electronic Stability Control is a computerized technology that improves a vehicle's stability by detecting and minimizing skids. The system operates by comparing the driver's steering input with the vehicle's actual direction, using individual wheel braking to correct oversteer or understeer. Within the technology segment, yaw rate sensors and wheel speed sensors are fundamental components for all system tiers. The application landscape shows passenger vehicles as the dominant segment, while adoption in commercial trucks is growing due to new safety regulations.
Compliance with standards from bodies like the United States' NHTSA and adherence to the EU's General Safety Regulation are non-negotiable for market access. In China, GB standards dictate the performance requirements for all ESC systems sold domestically. Future development hinges on integrating ESC functions seamlessly into the centralized domain controllers required for higher levels of automated driving.
Market Dynamics
The global expansion of mandatory vehicle safety regulations represents the central force shaping the market. Rules like the United States' FMVSS No. 126 and the EU's General Safety Regulation make Electronic Stability Control a non-negotiable, baseline technology for market access.
Growth Catalysts
- Regulatory Mandates:The enforcement of stringent vehicle safety standards by bodies like the NHTSA in the United States and similar regulations in the European Union makes ESC a standard feature on all new passenger cars, creating a stable demand floor.
- ADAS Integration:ESC serves as a foundational technology for more complex Advanced Driver-Assistance Systems (ADAS), including autonomous emergency braking and adaptive cruise control, linking its growth directly to the adoption of higher-level automation.
- Emerging Market Safety Upgrades:Rapidly motorizing economies, particularly China and India, are continuously elevating their domestic vehicle safety standards, such as China's GB standards, compelling automakers to equip vehicles with ESC to meet local requirements.
Market Restraints
- Cost Pressure in Economy Vehicles:Integrating ESC systems into budget-conscious, high-volume vehicle segments adds to the bill of materials, challenging automakers to absorb costs without impacting the final vehicle price in competitive markets.
- Sensor Supply Chain Concentration:The market's reliance on a limited number of specialized suppliers for critical components like yaw rate and steering angle sensors creates vulnerability to supply disruptions and pricing power concentration.
- Software Validation Complexity:The development and rigorous testing of control algorithms to ensure reliable performance across diverse vehicle platforms and driving conditions require significant R&D investment and long validation cycles.
Strategic Opportunities
- Commercial Vehicle Penetration:The market for ESC in heavy-duty trucks and buses remains underpenetrated, presenting a significant growth avenue as new safety regulations for commercial fleets are introduced in North America and Europe.
- Software-Defined ESC:Transitioning ESC from hardware-centric modules to software functions within centralized vehicle computers allows for over-the-air updates, performance tuning, and integration with electric vehicle powertrain management systems.
- Aftermarket Systems:There is an opportunity to develop and certify aftermarket ESC kits for installation in older vehicle models in developing regions where safety regulations are not retroactive, addressing a latent safety demand.
Industry Challenges
- System Interoperability:Ensuring seamless functional communication between ESC components and other vehicle control systems, such as electric power steering and brake-by-wire systems often sourced from different vendors, poses a significant integration challenge.
- Functional Safety Certification:The process of achieving and maintaining compliance with the ISO 26262 functional safety standard for all electronic hardware and software components is resource-intensive and adds considerable time to product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Electronic Stability Control Systems Market |
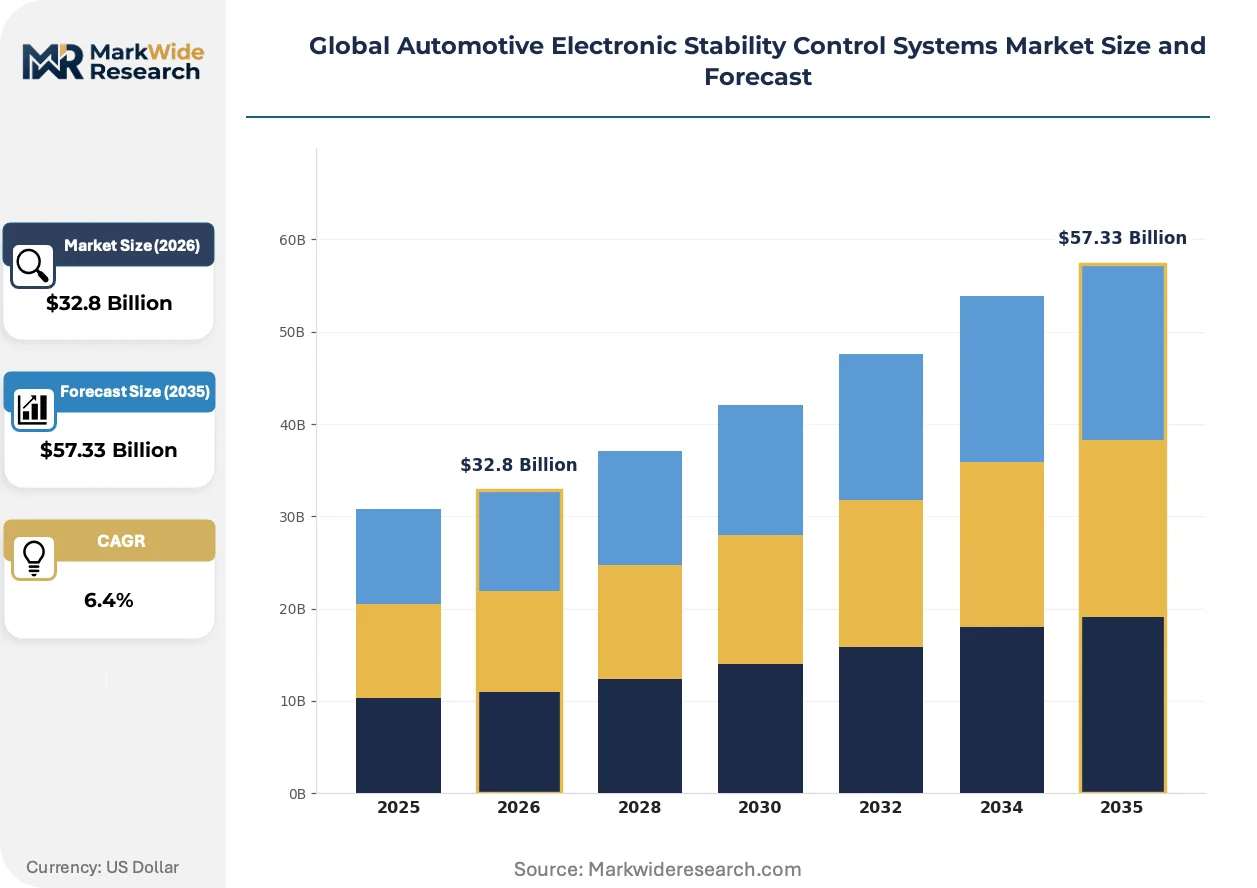
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic ESC, Electric ESC, Combined ESC, Brake-based ESC, Adaptive ESC Technology: Gyroscopic Sensors, Accelerometers, Yaw Rate Sensors, Steering Angle Sensors, Wheel Speed Sensors Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Off-road Vehicles, Emergency Vehicles End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers, Parts Distributors |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Denso Corporation, Hyundai Mobis, Mando Corporation, Autoliv Inc., Knorr-Bremse AG, Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Electronic Stability Control Systems Market Strategic Shifts & Innovations
The evolution of Electronic Stability Control is defined by its transition from a standalone reactive safety system to a proactive, integrated element of overall vehicle motion control. This shift is driven by software advancements and the architectural needs of automated driving.
Sensor fusion technology combines data streams from yaw rate sensors, wheel speed sensors, and accelerometers to create a precise model of vehicle behavior. Automakers are rapidly adopting this approach across all passenger vehicle segments to improve system accuracy and responsiveness. This technology is integrating formerly discrete safety functions into unified domain controllers, enabling more holistic control over braking, steering, and powertrain for advanced driver-assistance features.
The European Union's General Safety Regulation is compelling automakers to include a wider array of active safety technologies as standard equipment. This rule effectively makes advanced, sensor-rich ESC a baseline requirement for market access, accelerating the obsolescence of more basic systems. The passenger vehicle segment is most directly impacted, with suppliers focusing R&D on systems that meet these enhanced performance criteria for features like lane-keeping assist.
Automaker sourcing behavior is changing, with a clear preference for suppliers who can provide integrated chassis control software solutions rather than just hardware components. This pivot disrupts the traditional tiered supplier model, favoring partners with deep expertise in control algorithms and functional safety software compliant with ISO 26262. This demand is most pronounced in the electric vehicle sector, where ESC software is critical for managing torque vectoring and regenerative braking.
Global Automotive Electronic Stability Control Systems Market Segmentation
Segmentation analysis within the Global Automotive Electronic Stability Control Systems Market reveals crucial insights into technology adoption, application diversity, and the evolving dynamics of the supply chain. Understanding these distinct segments helps stakeholders identify areas of concentrated demand and emerging growth opportunities.
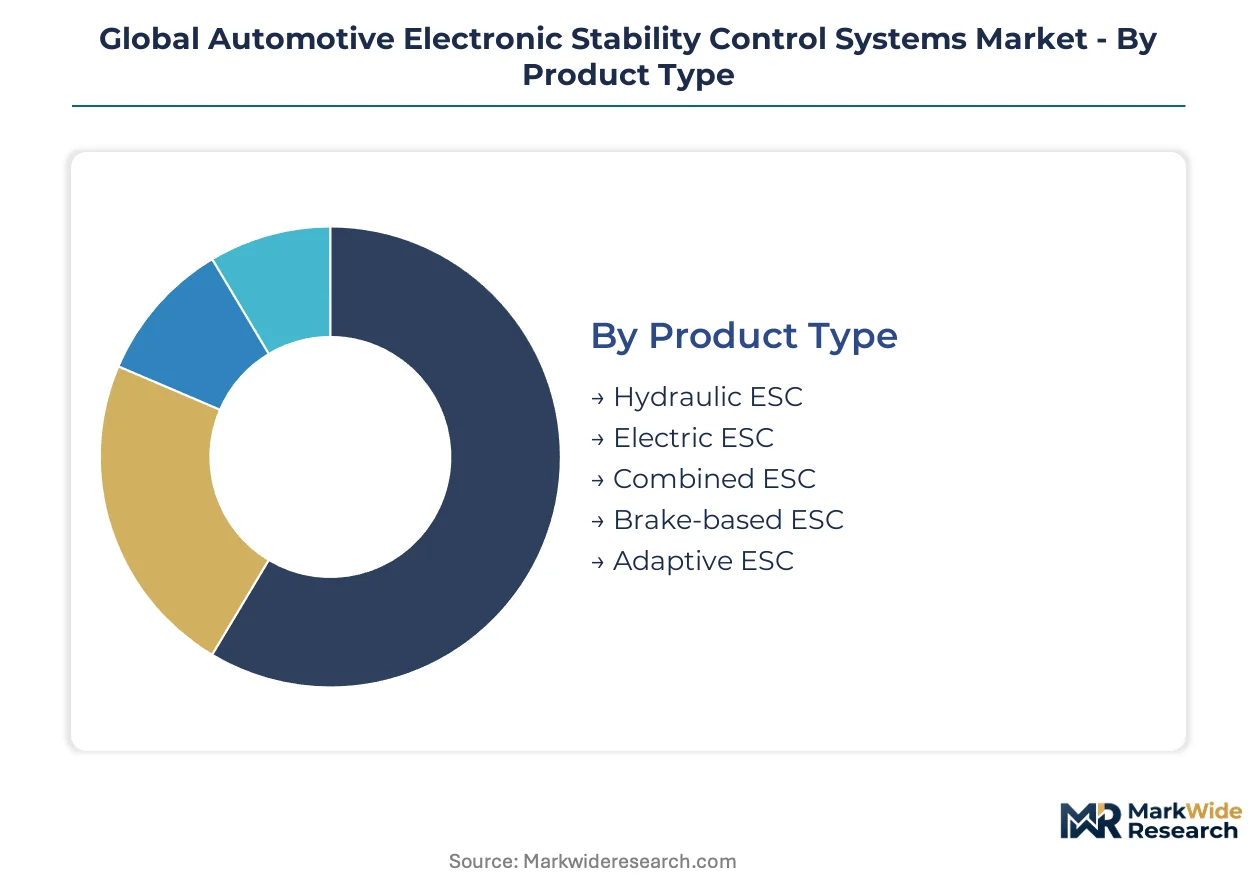
Product Type:
The supply chain for Electronic Stability Control systems exhibits concentration across distinct product types, influencing manufacturing scale and component sourcing strategies for automakers.
- Electric ESC:Utilizes electric motors and actuators for braking and steering adjustments, offering faster response times and higher integration with electric vehicle powertrains. Demand for this type is concentrating in passenger vehicles in Europe, driven by ADAS adoption.
- Adaptive ESC:Continuously adjusts stability parameters based on real-time road conditions and driver behavior, employing sophisticated algorithms and sensor fusion. Luxury passenger vehicles in Germany increasingly adopt Adaptive ESC for enhanced performance and safety.
- Hydraulic ESC:Employs hydraulic pressure to modulate individual wheel brakes for stability control and is a mature technology.
- Combined ESC:Integrates both hydraulic and electric components to achieve hybrid system performance.
- Brake-based ESC:Relies primarily on selective braking to correct vehicle instability, often found in simpler systems.
Today's leader: Hydraulic ESC. Tomorrow's challenger: Adaptive ESC.
Technology:
Different ESC technologies cater to specific application requirements, impacting system complexity, data fusion capabilities, and overall vehicle performance.
- Yaw Rate Sensors:Measures the vehicle's angular velocity around its vertical axis, providing critical data for detecting oversteer or understeer conditions. Passenger vehicles globally require these sensors as a core component for ESC functionality due to safety mandates.
- Wheel Speed Sensors:Monitors the rotational speed of each wheel, essential for calculating slip and informing brake intervention decisions. Commercial trucks in North America are increasingly integrating these sensors for enhanced ESC performance under new safety regulations.
- Gyroscopic Sensors:Detects changes in vehicle orientation and angular velocity, contributing to precise stability calculations.
- Accelerometers:Measures linear acceleration along multiple axes, informing the overall vehicle motion model.
- Steering Angle Sensors:Determines the driver's intended direction, comparing it with the vehicle's actual movement for control input.
Wheel Speed Sensors represent the fastest-growing component segment due to their universal application in safety systems.
Application:
Volume dynamics across applications dictate the scale of ESC system deployment and influence manufacturing priorities for system suppliers.
- Passenger Vehicles:Integrates ESC as a standard safety feature, often linked with advanced driver-assistance systems like autonomous emergency braking. Regulatory mandates in the United States and the European Union ensure universal adoption across new car models.
- Commercial Trucks:Implements robust ESC systems designed to handle heavier loads and greater inertia, improving stability during challenging maneuvers. New safety regulations in Europe are driving increased penetration of ESC systems in heavy-duty commercial fleets.
- Two-Wheelers:Incorporates specialized ESC variants to enhance stability and prevent skidding in motorcycles, particularly in high-performance models.
- Off-road Vehicles:Utilizes tailored ESC calibrations for traction control and stability on uneven terrain, adapting to varied driving conditions.
- Emergency Vehicles:Equips specialized vehicles with enhanced ESC for high-speed stability and maneuverability during critical operations.
Passenger Vehicles exhibit market maturity, while Commercial Trucks are expanding most quickly.
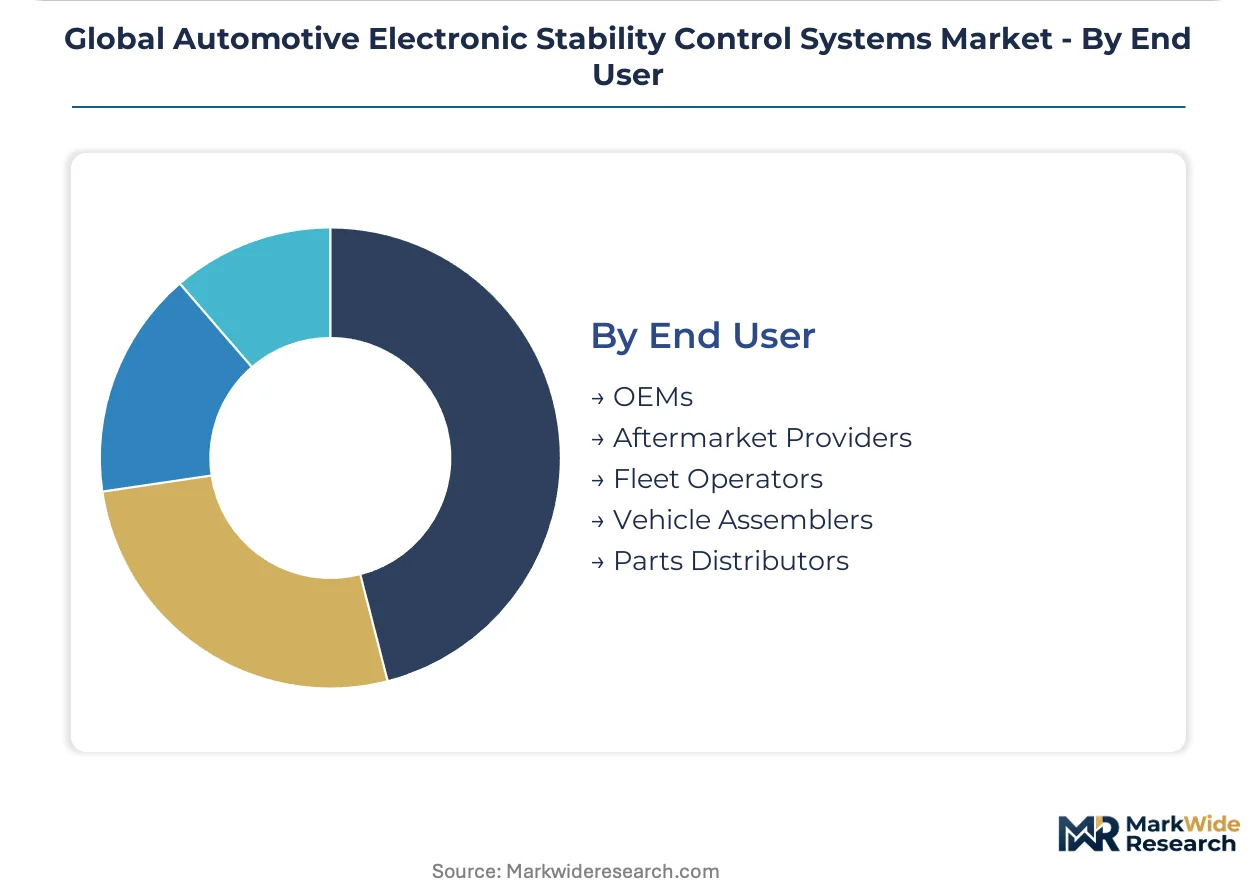
End User:
Different customer types exhibit distinct procurement patterns and integration requirements for ESC systems, shaping market access strategies.
- OEMs:Integrate ESC systems directly into vehicle designs during the manufacturing process, ensuring seamless hardware and software compatibility. Global automakers prioritize suppliers offering integrated chassis control software solutions compliant with ISO 26262 for new vehicle platforms.
- Aftermarket Providers:Supply ESC kits and components for installation in existing vehicles, often targeting older models lacking factory-installed systems. Developing regions like India present opportunities for aftermarket ESC kits to meet latent safety demands in older vehicle fleets.
- Fleet Operators:Procure ESC-equipped vehicles to enhance safety, reduce accident rates, and improve operational efficiency across their commercial fleets.
- Vehicle Assemblers:Integrate ESC modules as part of the final assembly process for various vehicle types, ensuring system functionality.
- Parts Distributors:Manage the supply chain for ESC components, serving both OEM production lines and aftermarket repair channels.
OEMs drive the highest volume, while Aftermarket Providers offer higher margin potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive electronic stability control systems market scaled significantly in Germany, driven by early technological advancements from key automotive suppliers. This foundational development established a global benchmark for vehicle safety technologies. Early integration into luxury vehicle segments propelled initial market expansion.
United States
The United States market exhibits consistent demand for ESC systems, propelled by the country's stringent safety regulations. Federal Motor Vehicle Safety Standard No. 126 mandates ESC on all new passenger vehicles, ensuring broad market penetration. Detroit serves as a major hub for vehicle integration, where automakers collaborate on advanced safety system development.
Germany
German automotive manufacturers prioritize advanced ESC solutions, aligning with the European Union's General Safety Regulation which drives demand for sophisticated active safety features. The German Federal Motor Transport Authority (KBA) oversees compliance, fostering a competitive environment for innovation. Stuttgart and Wolfsburg are central to automotive R&D and manufacturing, impacting ESC system design.
China
China's rapidly expanding automotive sector and continuous upgrades to domestic safety standards drive significant ESC adoption. The GB standards elevate performance requirements for all ESC systems sold domestically. Shanghai and Guangzhou host significant automotive production, where local and international manufacturers integrate these systems into new models.
India
India's growing vehicle parc requires enhanced safety features, leading to increased ESC penetration in new vehicle sales. The country's regulatory bodies are continuously elevating vehicle safety standards, making ESC a more common feature. Pune and Chennai are emerging manufacturing clusters, attracting investment in safety component production for the domestic market.
Japan
Japanese automakers focus on high-quality ESC systems, ensuring compliance with JIS standards for vehicle safety and performance. The Ministry of Economy, Trade and Industry (METI) supports technological advancements in automotive components. Toyota City and Hiroshima are key automotive production regions, driving demand for reliable and integrated ESC solutions.
Global Automotive Electronic Stability Control Systems Market Key Industry Players
The competitive structure tilts toward integrated automotive technology providers, reflecting the complex nature of ESC systems. The market features a blend of large, diversified Tier 1 suppliers and specialized component manufacturers. Strategic archetypes include comprehensive system integrators, sensor technology specialists, and software algorithm developers focusing on advanced control systems. Dominant competitive moves involve strategic partnerships for ADAS integration and significant R&D investment in functional safety software to meet evolving regulatory standards.
Within the comprehensive system integrator archetype, Robert Bosch GmbH and Continental AG represent established German suppliers with extensive R&D in sensor fusion and integrated safety systems. ZF Friedrichshafen AG also occupies a position as a major German player, specializing in advanced chassis control systems for both passenger and commercial vehicles. These entities anchor the market through extensive R&D capabilities, broad product portfolios, and strong compliance with global safety regulations. Their deep expertise in control algorithms and functional safety software is critical for next-generation ESC systems.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Hyundai Mobis |
| Mando Corporation |
| Autoliv Inc. |
| Knorr-Bremse AG |
| Aisin Corporation |
| Others |
Cost & Logistics Intelligence
Highly skilled software engineers in Germany and Japan influence the premium pricing of advanced Electronic Stability Control (ESC) systems, creating distinct pricing tiers based on algorithmic sophistication and functional safety compliance. This labor-cost differential translates into higher costs for systems requiring extensive R&D in control algorithms and sensor fusion.
Pricing Analysis
Contract-based long-term offtake agreements characterize the dominant pricing model for Electronic Stability Control systems supplied to original equipment manufacturers. Price differentiation stems from ISO 26262 functional safety certification levels and the degree of integration with advanced driver-assistance systems. Pricing pressure stems from the high-volume economy vehicle segments, where automakers seek to absorb system costs without impacting final vehicle prices. OEMs producing budget-conscious vehicles exhibit the highest price sensitivity, while luxury vehicle manufacturers prioritize performance over cost.
Supply Chain Analysis
Dual-sourcing requirements for critical components like yaw rate and steering angle sensors are becoming standard practice, driven by OEM efforts to mitigate supply chain risks. The supply chain for specialized sensors concentrates in Germany, Japan, and South Korea, while volume manufacturing of control units often occurs in China. Critical dependencies include microcontrollers and MEMS (Micro-Electro-Mechanical Systems) sensors. Single-source vulnerability for highly specialized sensor components represents a structural risk. Distribution runs through direct sales channels to OEMs and a network of parts distributors for the aftermarket segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a clear margin-expansion story, driven by the increasing integration of Electronic Stability Control into advanced driver-assistance systems. This shift allows for premium pricing on sophisticated, software-defined solutions.
For Market Incumbents:Lock in long-term supply agreements for software-defined ESC systems, leveraging deep OEM relationships and functional safety expertise. Consolidate R&D efforts on sensor fusion and centralized domain controllers to counter the threat from specialized software startups. Invest heavily in ISO 26262 certification processes to maintain a competitive edge and meet evolving regulatory requirements. Expand market share in commercial vehicle segments, which remain underpenetrated.
For New Entrants and Emerging Players:Begin with niche applications or specific geographic regions where regulatory mandates are nascent or evolving, presenting white-space opportunities. Target the commercial vehicle segment in North America with cost-effective, regulation-compliant ESC solutions, as this market is expanding quickly. Develop specialized software algorithms for torque vectoring in electric vehicles, offering a distinct go-to-market angle. Focus on modular, easily integratable solutions for smaller OEMs.
For Investors and Strategic Acquirers:Automotive Tier 1 suppliers are the most active acquirers in this space, seeking to bolster their software and sensor fusion capabilities. The market demonstrates long-term viability as ESC remains foundational for higher levels of automated driving over the next decade. Target specialized software algorithm developers or sensor technology firms with strong intellectual property in functional safety. The signal to watch is increased M&A activity involving companies focused on centralized vehicle architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization for ESC Modules | Reduces development costs and accelerates time-to-market for new vehicle models across diverse OEM platforms. |
| Investment in Software-Defined Vehicle Architecture | Enables over-the-air updates and unlocks new revenue streams through subscription-based safety features for automakers. |
| Strategic Partnerships for ADAS Integration | Combines ESC capabilities with advanced driver-assistance systems, offering comprehensive safety solutions to OEMs. |
| Expansion into Commercial Vehicle ESC Systems | Capitalizes on new safety regulations and addresses the underpenetrated market for heavy-duty trucks and buses. |
| Deepening Functional Safety Certification Expertise | Ensures compliance with stringent ISO 26262 standards, critical for market access and competitive differentiation. |
Research Approach
Direct dialogue with OEM platform engineers, Tier 1 R&D directors, regulatory affairs specialists, and sensor manufacturers provided qualitative insights and validated quantitative data. This primary research was combined with extensive secondary validation from public sources. Bottom-up and top-down triangulation ensured robust market sizing and accurate forecasting across all segments.
The analytical framework produced granular market projections across the analysis window, modeling various segmentation dimensions including product type, technology, application, end-user, and vehicle class. Compound annual growth rates were derived from a comprehensive analysis of historical trends, regulatory impacts, and technological adoption curves. Key industry-specific forecast inputs included new vehicle production forecasts and regional safety mandate timelines.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts or rapid shifts in autonomous driving adoption that could fundamentally alter market dynamics. Forecasts reflect assumptions documented through expert consensus and historical patterns. Deviation in global semiconductor supply chain stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Automotive Airbag Inflator Market
Automotive Safety and Security Systems
Brake Override System Market
Automotive Safety and Security Systems
Driver Alert System Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
South Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Automotive Shielding Market
Automotive Safety and Security Systems
Global Electronic Brake Force Distribution System Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market