
 Automotive Brake Shims Market | 2026-2036
Automotive Brake Shims Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Shims Market Analysis
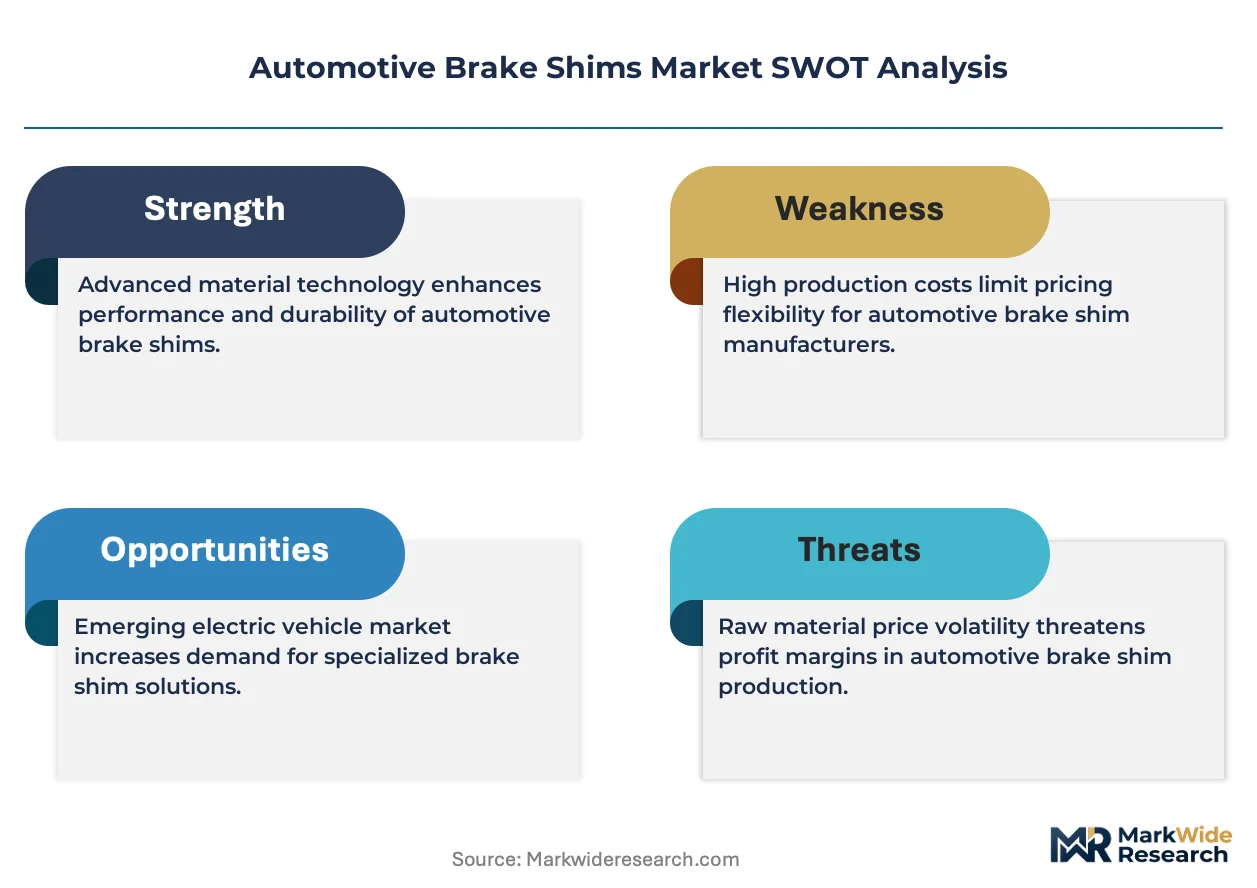
The gap between premium NVH-optimized brake shims and commodity stamped-metal alternatives is repositioning supplier economics across the value chain. Robert Bosch GmbH leverages integrated brake system design to bundle shim specifications with caliper platforms, sustaining captive demand from German OEMs. Nisshinbo Holdings Inc. anchors its position through rubber-composite laminate expertise, while Meneta Group competes on cold-rolled steel precision for European heavy-duty installations.
Automotive brake shims are thin, engineered layers—typically 0.5 mm to 2.0 mm thick—installed between brake pads and caliper pistons to dampen vibration, prevent squeal, and ensure uniform pressure distribution; they are manufactured through cold rolling, adhesive bonding, or multi-layer vulcanization depending on material class. Composite shims lead value contribution due to polymer-metal hybrid construction that meets stringent NVH targets without adding rotational mass. Metal shims remain volume-dominant in aftermarket channels where cost sensitivity favors single-layer stainless or galvanized steel configurations.
Federal-Mogul Co. and ZF Friedrichshafen AG navigate divergent compliance burdens: the former addresses EPA particulate standards indirectly through friction-system integration, while the latter aligns with EU REACH restrictions on rubber adhesive chemistries. China's SAMR enforces GB/T 17469 brake performance protocols that now incorporate shim adhesion durability under thermal cycling. Stakeholders must weigh material certification costs against OEM qualification timelines as regulation tightens on both sides of the Atlantic.
Market Dynamics
OEMs are consolidating shim specifications around integrated brake platform architectures, compressing supplier qualification timelines while elevating material certification burdens. This structural shift favors compounders with captive polymer-metal lamination capabilities over discrete metal stampers.
Growth Catalysts
- NVH Mandates:China's MIIT has tightened GB/T 17469 protocols to incorporate shim adhesion durability under thermal cycling, forcing domestic upgrades.
- Aftermarket Prioritization:Vehicle owners in Germany now specify noise-dampening composite shims during routine brake servicing, elevating replacement-grade material specifications.
- Precision Engineering:Cold-rolled steel shims with sub-10-micron thickness tolerance are penetrating premium passenger car platforms sourced from Stuttgart and Munich.
Market Restraints
- Rubber Adhesive Chemistry Constraints:EU REACH restrictions on aromatic solvent-based bonding agents are forcing reformulation of multi-layer vulcanization processes.
- Stainless Steel Input Volatility:Cold-rolled strip prices fluctuate with nickel exchange dynamics, compressing margin buffers for single-layer metal shim producers.
- Substitution Pressure:Integral piston insulator designs in electric vehicle brake calipers are displacing discrete shim layers in certain low-torque applications.
Strategic Opportunities
- India Aftermarket Expansion:BIS certification alignment with ECE R90 friction standards is opening formal channels for noise-optimized shim imports.
- Dual Carbon Policy Tailwind:China's MEE enforcement of carbon intensity benchmarks is accelerating domestic demand for lightweight polymer-metal hybrids that reduce unsprung mass.
- Digital Distribution Channels:Specialized B2B platforms for brake component procurement are fragmenting traditional aftermarket wholesale hierarchies in North America.
Industry Challenges
- Polymer-Metal Interface Expertise Gap:Formulation chemists capable of optimizing damping coefficients across -40°C to 300°C operational windows command scarcity premiums.
- OEM Qualification Timelines:Brake platform validation cycles now stretch 36-48 months, freezing supplier switching costs and locking out new compounders.
- Legacy Caliper Integration Complexity:Retrofitting composite shims into existing floating caliper architectures without piston stack height modification requires custom spacer engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Shims Market |
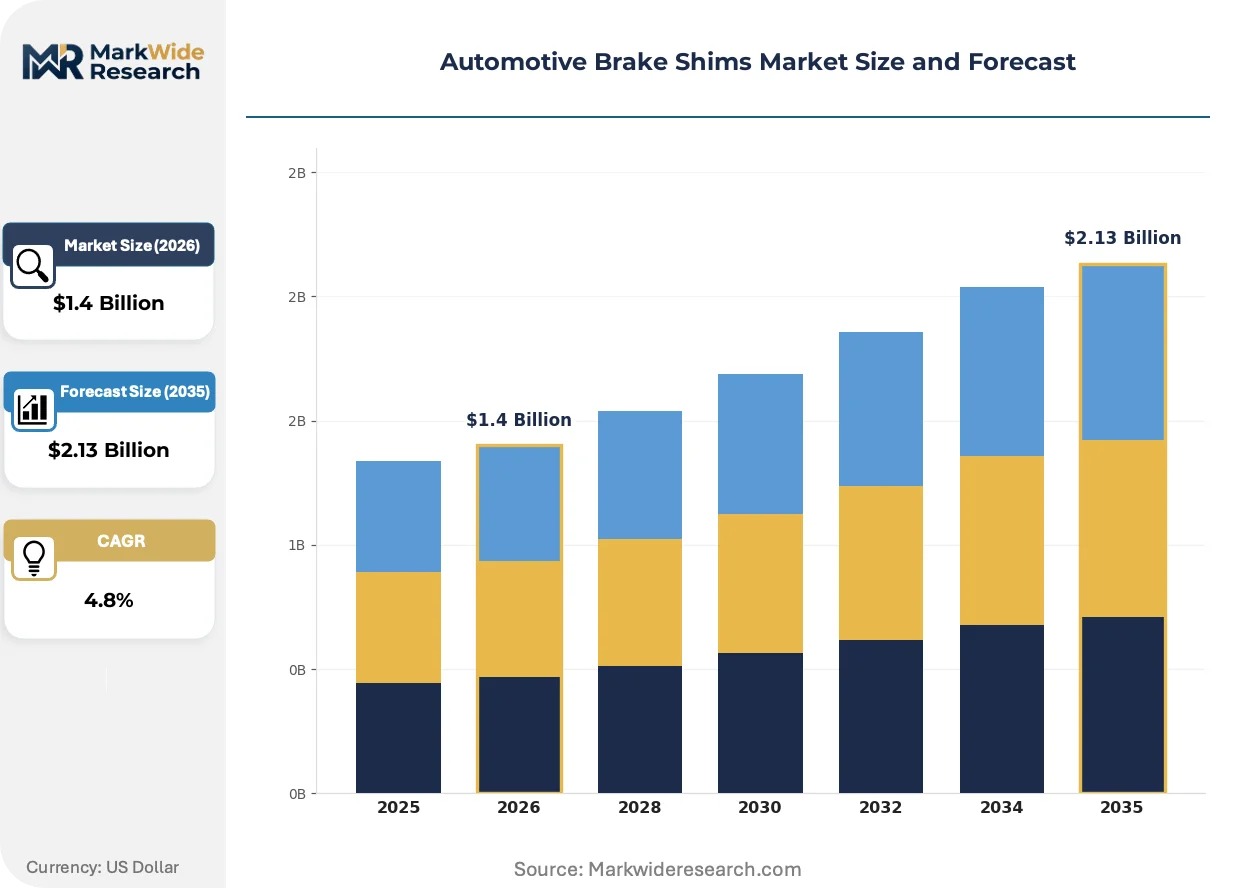
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, Rubber, Composite, Ceramic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Cars, Commercial Vehicles, Buses, Light Trucks Installation Type: On-Road, Off-Road, Racing, Heavy-Duty |
| Companies Covered | Federal-Mogul Co., Nisshinbo Holdings Inc., Robert Bosch GmbH, Valeo S.A., ZF Friedrichshafen AG, Brembo S.p.A., Trelleborg Group, Meneta Group, Akebono Brake Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Shims Market Emerging Trajectories
Material science advances are collapsing the functional boundary between noise-dampening layers and thermal management interfaces. Brake shim architectures now integrate sensors and active damping elements previously housed in separate subsystems.
Rubber-ferroelastic composite formulations are converging with embedded piezoelectric sensor arrays to enable real-time squeal prediction. Tier 1 brake system integrators in Germany are piloting these smart shim configurations for premium electric vehicle platforms. The convergence is compressing the traditional separation between passive NVH hardware and active brake control modules.
China's SAMR enforcement of updated GB standards for brake system performance is mandating adhesion retention testing after 500 thermal cycles. Domestic suppliers must now certify polymer-metal bonds under combined salt spray and shear load protocols. The regulatory compression is accelerating laboratory accreditation investments among mid-tier compounders in Jiangsu and Zhejiang provinces.
Fleet operators and independent service chains are unbundling shim selection from pad-replacement bundles, creating specification transparency previously obscured by integrated kit pricing. This behavioral shift is most visible in the United States, where commercial vehicle maintenance contracts now itemize NVH-grade tiers separately from friction material grades. Distributors are responding with open-specification catalog interfaces that expose damping coefficient data previously restricted to OEM technical bulletins.
Automotive Brake Shims Market Segmentation
Brake shim segmentation reveals how certification burdens concentrate in polymer-metal interfaces while metal-only configurations face lighter approval pathways. Understanding these tiered compliance loads helps suppliers prioritize R&D spend and qualification timelines.
Product Type:
GB/T 17469 thermal cycling protocols impose the heaviest certification loads on rubber-composite laminates, while single-layer metal shims navigate lighter adhesion-testing requirements under REACH and EPA frameworks.
- Metal:Cold-rolled stainless or galvanized steel configurations dominate aftermarket channels where cost sensitivity overrides NVH optimization. German heavy-duty fleet operators specify these for drum brake retrofits where vibration tolerance is higher. Leading the category by volume: Metal. Growing fastest: Composite.
- Rubber:Vulcanized nitrile or EPDM layers bonded to steel substrates deliver targeted damping coefficients for passenger car disc brakes. EU REACH aromatic solvent restrictions are forcing reformulation of adhesive chemistries in Stuttgart supplier parks.
- Composite:Polymer-metal hybrid laminates integrate viscoelastic cores between steel facings to meet sub-60 dB squeal targets without rotational mass penalties. China's MIIT carbon intensity benchmarks accelerate domestic procurement from Jiangsu compounders.
- Ceramic:Alumina-silicate formulations serve extreme thermal environments in racing and heavy-duty descents. KBA in Stuttgart mandates separate friction-system validation for these specialty configurations.
Composite configurations command premium positioning through GB standard compliance, while metal retains aftermarket dominance via stripped certification requirements.
End User:
OEM qualification timelines now stretch 36-48 months, freezing supplier switching costs and locking specification control with incumbent compounders.
- OEMs:Integrated brake platform architectures bundle shim specifications with caliper designs, sustaining captive demand through system-level validation. German premium passenger car assemblers in Munich and Stuttgart source precision-engineered composites with sub-10-micron thickness tolerance.
- Aftermarket Providers:Independent distributors and service chains unbundle shim selection from pad-replacement kits, creating specification transparency previously obscured by integrated pricing. US commercial vehicle maintenance contracts now itemize NVH-grade tiers separately from friction material grades.
- Vehicle Assemblers:Contract manufacturers without captive brake system design rely on Tier-1 integrators to specify shim grades, compressing direct procurement leverage.
- Tier-1 Suppliers:Bosch and ZF Friedrichshafen AG consolidate multi-source shim inputs under unified platform validation, elevating material certification burdens for sub-tier compounders.
Tier-1 integrators concentrate specification authority, while aftermarket channels fragment through digital procurement platforms.
Application:
Passenger car platforms absorb the steepest NVH compliance investment, while commercial vehicle applications tolerate higher damping thresholds in exchange for durability.
- Passenger Cars:Premium electric vehicle architectures in Germany pilot smart shim configurations with embedded piezoelectric sensor arrays for real-time squeal prediction. These platforms demand the most stringent GB/T 17469 adhesion retention certification.
- Commercial Vehicles:Fleet operators prioritize thermal fatigue resistance over acoustic performance, favoring stainless steel configurations with simplified REACH documentation.
- Buses:Urban transit specifications in China emphasize lightweight polymer-metal hybrids to reduce unsprung mass under MEE carbon intensity enforcement.
- Light Trucks:North American service chains specify mid-grade composites for pickup brake servicing, balancing NVH improvement against cost sensitivity in independent repair channels.
Passenger car applications absorb the majority of R&D investment, while commercial vehicle procurement emphasizes input cost stability over performance tiering.
Installation Type:
Racing and heavy-duty segments isolate extreme thermal cycling requirements, while on-road installations face the broadest regulatory overlap across jurisdictions.
- On-Road:Standard passenger and commercial vehicle installations must satisfy simultaneous GB, REACH, and EPA compliance, creating the most complex certification matrices for multi-layer vulcanization processes.
- Off-Road:Construction and agricultural equipment tolerates higher squeal thresholds, permitting simplified metal shim configurations with reduced polymer content.
- Racing:Track-specific ceramic and carbon-composite shims operate beyond standard thermal cycling protocols, requiring separate validation from Germany's KBA for motorsport exemption categories.
- Heavy-Duty:Descent braking on mountain corridors demands alumina-silicate or specialized steel grades with enhanced heat sink properties, sourced through dedicated supplier relationships outside standard automotive channels.
On-road installations concentrate regulatory complexity, while racing and heavy-duty segments isolate specialized thermal performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors precision brake shim procurement for German premium OEMs, while regulatory divergence across major automotive clusters reshapes supplier qualification burdens and material certification investments.
United States
Commercial vehicle fleet operators now itemize NVH-grade shim tiers separately from friction materials in maintenance contracts. EPA particulate standards indirectly shape friction-system integration requirements for domestic suppliers. Detroit-based distributors deploy digital B2B platforms that fragment traditional aftermarket wholesale hierarchies.
Germany
Munich and Stuttgart assemblers source cold-rolled steel shims with sub-10-micron thickness tolerance for premium passenger car platforms. KBA mandates separate friction-system validation for specialty ceramic configurations in motorsport applications. ZF Friedrichshafen and Robert Bosch consolidate multi-source inputs under unified platform validation.
China
Jiangsu and Zhejiang compounders accelerate laboratory accreditation investments to meet SAMR-enforced GB/T 17469 protocols. MIIT carbon intensity benchmarks drive domestic procurement of lightweight polymer-metal hybrids. The country's national automotive regulator now mandates adhesion retention testing after 500 thermal cycles.
Japan
Meti-aligned JIS standards govern rubber-ferroelastic composite formulations for disc brake applications. Nagoya-area suppliers pilot embedded piezoelectric sensor arrays for real-time squeal prediction in electric vehicle platforms. Akebono Brake Industry anchors domestic OEM supply relationships through captive polymer-metal lamination capabilities.
India
BIS certification alignment with ECE R90 friction standards opens formal channels for noise-optimized shim imports. Vehicle owners in Delhi-NCR and Maharashtra prioritize NVH reduction during routine brake servicing. Domestic aftermarket distributors expand procurement of composite configurations previously restricted to OEM technical bulletins.
Automotive Brake Shims Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the brake shim value chain. Integrated brake system manufacturers sustain captive demand through bundled platform specifications, while discrete compounders fight for sub-tier qualification slots. Three archetypes dominate: polymer-metal laminate specialists, precision cold-rolled steel stampers, and full-system integrators with captive shim design. Consolidation pressure favors compounders with in-house vulcanization capabilities, while metal-only stampers face margin compression from stainless input volatility.
Within the full-system integrator tier, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify platform-level specification control that locks sub-tier compounders into extended validation cycles. Nisshinbo Holdings Inc. occupies a position among Japanese laminate specialists with rubber-composite expertise. These three entities represent divergent strategic positions: German system integration, Japanese material science depth, and the competitive pressure facing mid-tier metal stampers without captive polymer capabilities.
| Leading Market Players |
|---|
| Federal-Mogul Co. |
| Nisshinbo Holdings Inc. |
| Robert Bosch GmbH |
| Valeo S.A. |
| ZF Friedrichshafen AG |
| Brembo S.p.A. |
| Trelleborg Group |
| Meneta Group |
| Akebono Brake Industry Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
China's MIIT carbon intensity benchmarks gate qualified supply for premium-tier polymer-metal hybrid shims, restricting certification-ready compounders to Jiangsu and Zhejiang provinces while elevating pricing power among accredited domestic producers serving OEM procurement channels.
Pricing Analysis
Value-based pricing anchored to NVH performance outcomes separates composite laminates from commodity metal alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects GB/T 17469 certification grade and thermal cycling durability. Cost compression in single-layer stainless configurations is intensifying because nickel exchange volatility squeezes margin buffers for discrete stampers. Aftermarket distributors exhibit highest price sensitivity, while German premium OEMs absorb premium tiers for platform-integrated specifications.
Supply Chain Analysis
Cold-rolled steel strip supply rests on German precision mills and Chinese integrated producers, with rubber-ferroelastic compounds drawing from Japanese specialty chemical houses. Viscoelastic core materials, adhesive bonding agents, and piezoelectric sensor arrays constitute critical input dependencies. Single-source vulnerability concentrates in EU REACH-compliant aromatic solvent alternatives, forcing reformulation timelines. Distribution runs through Tier 1 brake system integrators bundling shim specifications with caliper platforms, supplemented by digital B2B platforms fragmenting North American aftermarket wholesale hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart shim architectures with embedded sensor arrays are displacing passive damping layers, compressing the traditional separation between NVH hardware and active brake control modules in a technology-transition phase.
For Market Incumbents: Anticipate displacement pressure from integral piston insulator designs in electric vehicle calipers by deepening captive polymer-metal lamination capabilities and accelerating GB/T 17469 laboratory accreditation investments in Jiangsu province. Lock specification control through 36-48 month platform validation cycles with Stuttgart and Munich assemblers. For New Entrants and Emerging Players: Enter via India's BIS-certified aftermarket channels where ECE R90 alignment opens formal import pathways for noise-optimized composites previously restricted to OEM technical bulletins. Target Delhi-NCR and Maharashtra service chains with unbundled shim selection from pad-replacement bundles, leveraging digital procurement platforms to bypass traditional wholesale hierarchies. For Investors and Strategic Acquirers: Tier 1 brake integrators consolidating multi-source inputs under unified platform validation is the leading indicator that captive lamination capabilities will command scarcity premiums over discrete metal stampers. Prioritize compounders with in-house vulcanization expertise and SAMR-accredited testing infrastructure across the medium-term horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive viscoelastic formulation control secures GB/T 17469 adhesion retention certification for Jiangsu compounders. |
| Platform Standardization with Smart Shim Architectures | Embedded piezoelectric sensor convergence with brake control modules locks German OEM specification authority. |
| Long-term Supply Agreement with Stainless Steel Mills | Fixed-price cold-rolled strip contracts insulate margin buffers against nickel exchange volatility for European stampers. |
| Geographic Manufacturing Footprint in Zhejiang Province | Proximity to SAMR accreditation laboratories accelerates thermal cycling certification timelines for domestic market access. |
| Joint Venture with Aftermarket Digital Platforms | Direct B2B channel partnerships fragment traditional wholesale hierarchies and expose damping coefficient data transparency. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations with bottom-up and top-down triangulation. SAMR enforcement protocols, MIIT carbon intensity benchmarks, KBA friction-system validations, and EPA particulate standards supplied regulatory cross-referencing. Vehicle production databases, IHS Markit registration data, and brake component customs classifications furnished volume calibration.
Granularity-level modeling distinguished polymer-metal hybrid, rubber-composite, metal-only, and ceramic configurations across passenger car, commercial vehicle, bus, and light truck applications. Propulsion architecture, content per vehicle, OEM tier positioning, and regional production clusters shaped segmentation dimensions. CAGRs derived from installed base attrition rates, NVH mandate adoption curves, and aftermarket replacement frequency patterns across the projection horizon. Thermal cycling durability standards and REACH aromatic solvent restrictions informed material transition assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EV brake architecture shifts or nickel price spike scenarios. Forecasts reflect documented assumptions regarding platform validation cycle durations and regulatory enforcement intensity. A small set of triggers—MIIT carbon benchmark tightening, integral piston insulator penetration rates, and BIS-ECE R90 harmonization progress—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Argentina Automotive Engine Oils Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
Philippines Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Seat Track Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Engine Piston Ring Set Market
Automotive Parts
Canada Automotive Actuators Market
Automotive Parts
Road Marking Machine Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
North America Ceramic Ball Bearings Market
Automotive Parts
Rammer Market