
 Automotive Spacer Ring Market | 2026-2036
Automotive Spacer Ring Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Spacer Ring Market Outlook
Aftermarket service revenue is reconfiguring margin pools away from pure component sales toward integrated module supply and refurbishment programs. Schaeffler AG leverages its bearing and precision component heritage to dominate spacer ring supply for transmission and engine architectures. SKF Group anchors its position through R&D intensity in polymer-composite formulations that reduce weight without sacrificing dimensional stability. Dana Incorporated competes aggressively in North American commercial vehicle spacer ring applications, sustaining volume through long-term platform contracts with domestic OEMs.
Automotive spacer rings are precision-machined or molded annular components, typically manufactured from hardened steel alloys, engineered thermoplastics, or fiber-reinforced composites, with tolerances often held within micrometers to ensure proper axial positioning and load distribution in rotating assemblies. These components primarily maintain critical clearances between bearing races, gear sets, and shaft interfaces across powertrain and chassis systems. Metal spacer rings retain the largest share of current OEM demand due to proven performance under high thermal and mechanical stress, though composite spacer rings represent the fastest-expanding category as electrified platforms prioritize mass reduction. Application demand clusters heavily in transmission units, where multi-speed gearboxes and e-axle designs require complex stacked spacer configurations, while brake system spacer rings occupy a mature, price-sensitive segment with thinner margin pools.
The EPA enforces material content and recyclability standards that shape composite spacer ring formulation choices for vehicles sold in the United States. REACH and the EU Green Deal impose substance restrictions and carbon footprint disclosure requirements that European suppliers must navigate for market access. China's MIIT and GB standards govern dimensional precision and material certification for domestic automotive component production. Stakeholders must monitor evolving battery-electric platform architectures, as thermal management module designs will determine whether spacer rings retain their current form factors or fragment into application-specific geometries.
Market Dynamics
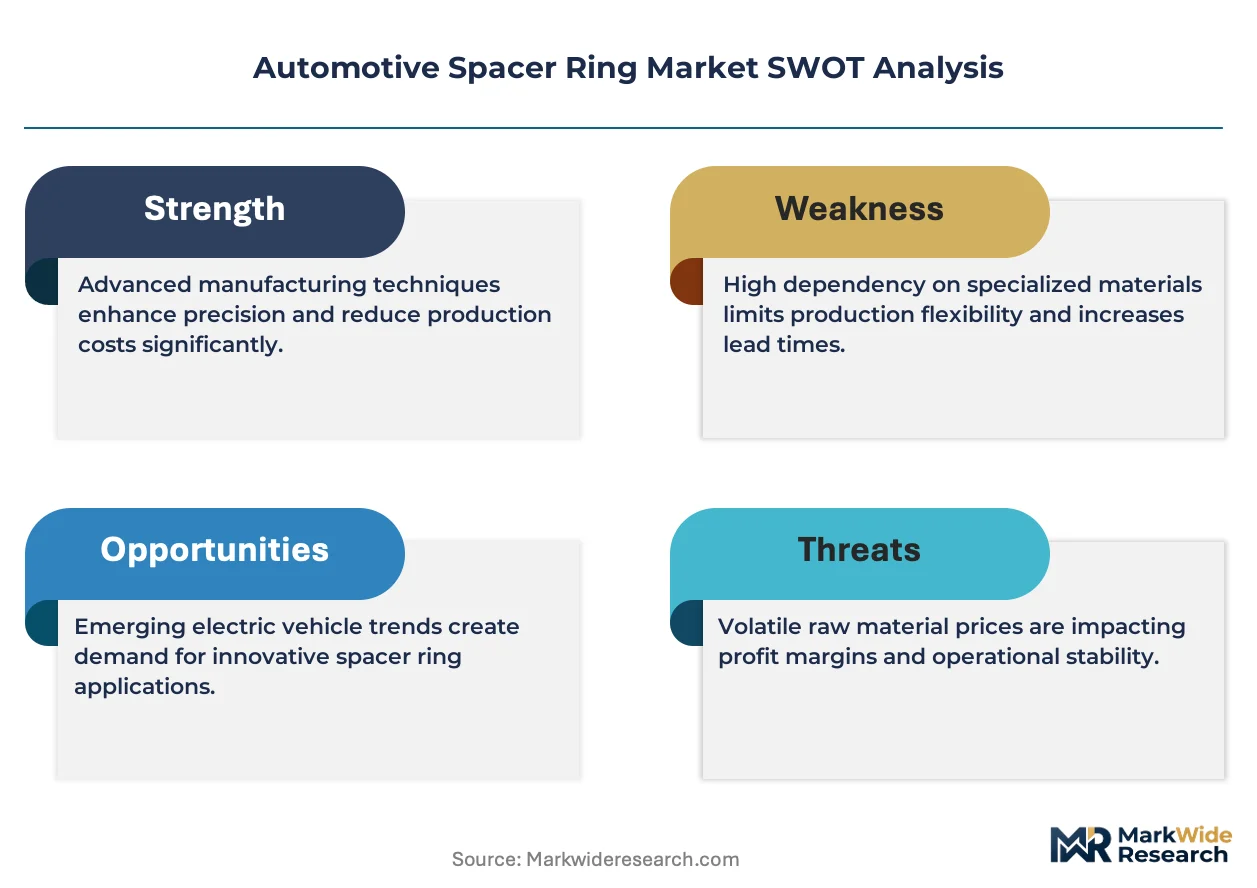
Electrification of powertrain architectures is fundamentally restructuring spacer ring demand, as thermal management module redesigns and e-axle integration eliminate traditional transmission stack configurations while creating novel clearance-control requirements in battery housing assemblies.
Growth Catalysts
- NEV Mandates:China's MIIT enforcement of new energy vehicle production quotas compels automakers to engineer lightweight spacer solutions for electric drivetrain thermal modules.
- REACH Substance Restrictions:European ECHA regulations on hazardous material content accelerate composite formulation R&D among Tier-1 suppliers serving premium drivetrain applications.
- Multi-Speed E-Axle Proliferation:Complex gearboxes in electrified platforms require precision-stacked spacer configurations for bearing race positioning and load distribution.
Market Restraints
- Steel Price Volatility:Hardened alloy steel input costs fluctuate with energy-intensive smelting operations, compressing margins on conventional metal spacer ring production.
- German Supply Concentration:Tier-1 production gravity in Baden-Württemberg and Bavaria creates geographic vulnerability to regional energy cost spikes and logistics disruptions.
- Dimensional Precision Limits:Fiber-reinforced composites face tolerance-holding constraints below 10 micrometers, restricting deployment in ultra-precision bearing applications.
Strategic Opportunities
- Indian NEV Supply Localization:PLI scheme incentives for domestic automotive component manufacturing open captive demand from Tata Motors and Mahindra electric platforms.
- Refurbishment Program Integration:Aftermarket service bundling of spacer ring replacement within transmission overhaul modules captures lifetime value from commercial vehicle fleets.
- Polymer-Composite Convergence:Hybrid material systems combining engineered thermoplastics with selective metal reinforcement enable weight reduction without full performance trade-offs.
Industry Challenges
- Micro-Machining Talent Scarcity:Tooling engineers capable of holding sub-10-micrometer tolerances in composite materials remain concentrated among German and Japanese precision component specialists.
- GB Standard Certification Timelines:China's MIIT material certification protocols for domestic automotive production extend product qualification cycles by 8-14 months for foreign suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Spacer Ring Market |
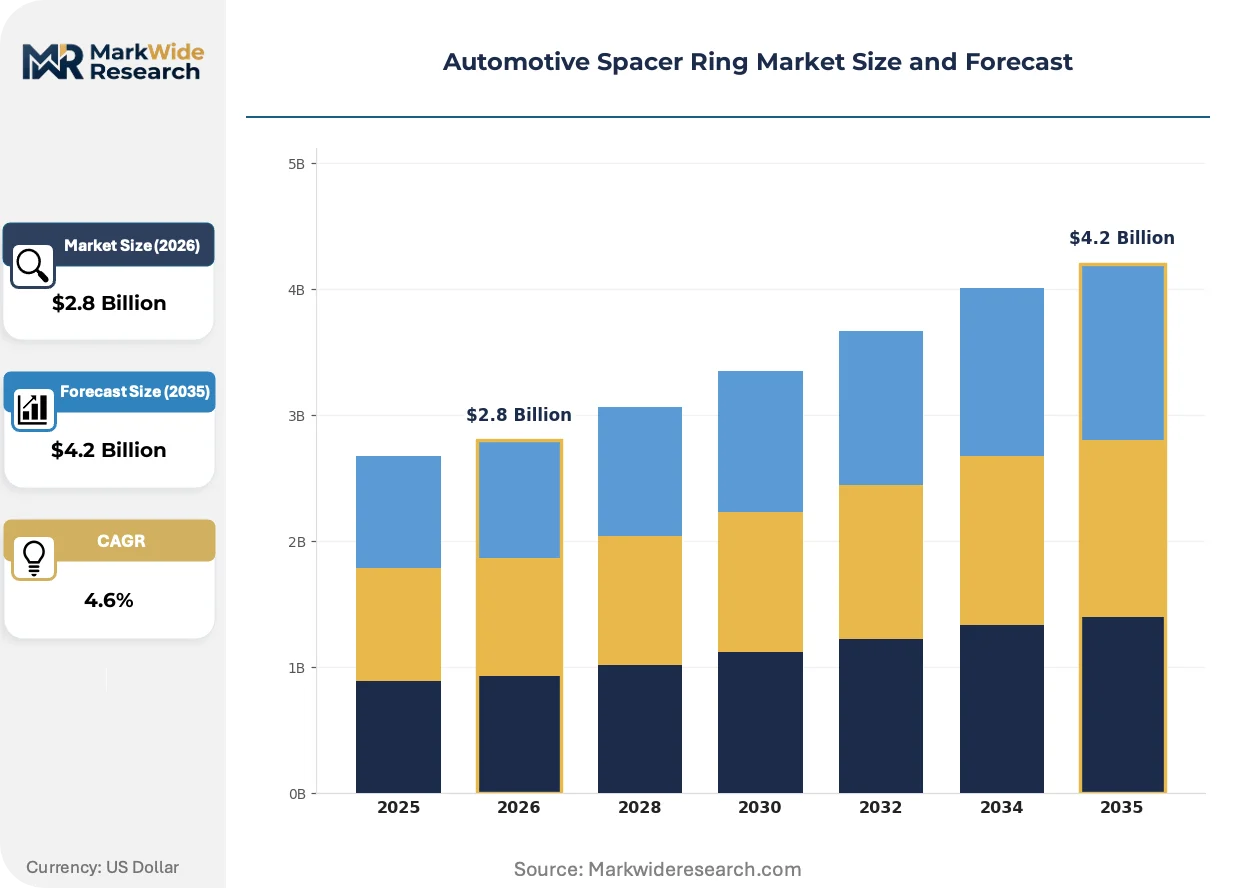
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Spacer Rings, Plastic Spacer Rings, Composite Spacer Rings, Rubber Spacer Rings Application: Engine Components, Suspension Systems, Transmission Units, Brake Systems End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Size: Small, Medium, Large, Custom |
| Companies Covered | Schaeffler AG, SKF Group, Dana Incorporated, NTN Corporation, ZF Friedrichshafen AG, Continental AG, BorgWarner Inc., Magna International Inc., JTEKT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Spacer Ring Market Strategic Shifts
Material science breakthroughs and regulatory disclosure mandates are converging to transform how spacer rings are specified, validated, and procured across automotive supply chains.
Manufacturing methodology is migrating from conventional subtractive machining toward hybrid additive-subtractive processes. Selective laser sintering of polymer-matrix composites enables internal lattice structures that reduce mass while maintaining compressive strength. BMW and Volkswagen Group powertrain divisions are piloting these geometries for e-axle thermal management modules. The shift is compressing lead times for prototype iterations from weeks to days.
REACH carbon footprint disclosure requirements under the EU Green Deal are forcing formulation transparency across composite supply chains. European Tier-1 suppliers must now document embodied emissions from raw polymer through finished component. This regulatory pressure is favoring suppliers with captive recycling streams and bio-based feedstock integration. German automotive manufacturers are tightening supplier qualification criteria accordingly.
Integrated module procurement is displacing discrete component purchasing for transmission and e-axle assemblies. OEM engineering teams now specify spacer rings as bundled subsystems rather than standalone parts, requiring suppliers to assume design responsibility for stacked configurations. This pattern concentrates purchasing power with platform-level Tier-1 integrators. The restructuring is most pronounced in North American commercial vehicle contracts.
Automotive Spacer Ring Market Segmentation
Spacer ring procurement cycles vary dramatically across material classes and application tiers, with brake system replacements turning over in months while transmission stack configurations persist across entire vehicle lifecycles. Understanding these velocity differentials helps suppliers align inventory positioning with actual consumption patterns rather than aggregated demand signals.
Product Type:
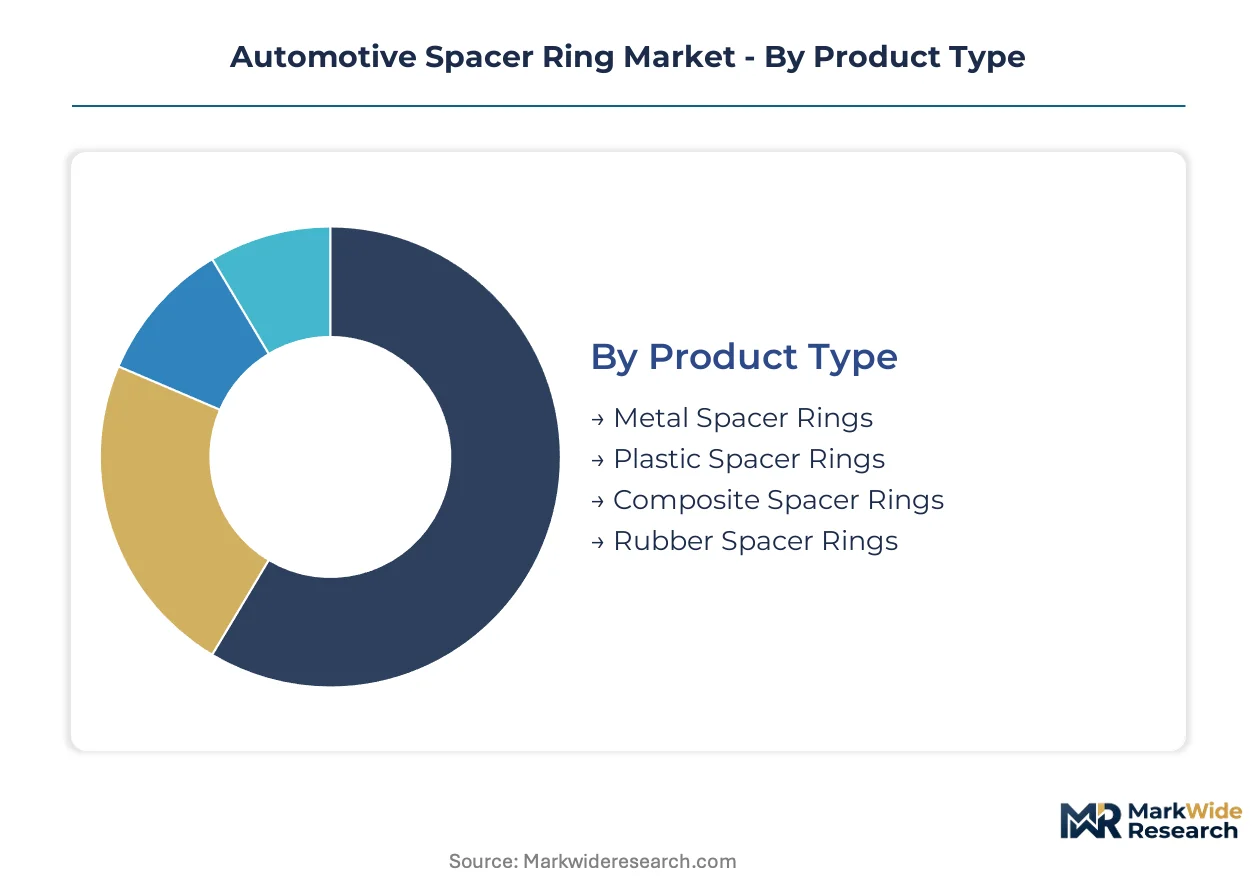
Metal spacer rings turn inventory slowest due to multi-year durability in powertrain assemblies, while rubber variants in chassis applications require most frequent replenishment. Composite formulations occupy the middle ground as electrified platforms accelerate their specification rates.
- Metal Spacer Rings:Hardened steel and alloy formulations dominate transmission bearing races and engine crankshaft assemblies where thermal loads exceed polymer tolerance thresholds. Demand concentrates in Germany's precision manufacturing corridor, where Schaeffler AG and SKF Group anchor supply for BMW and Volkswagen Group powertrain divisions. REACH substance disclosure requirements are forcing alloy composition transparency that extends qualification timelines.
- Composite Spacer Rings:Fiber-reinforced polymer matrices combine glass or carbon fiber with engineered thermoplastics to achieve 30-50% mass reduction versus steel equivalents. China's MIIT NEV mandates are accelerating specification for electric drivetrain thermal modules, though sub-10-micrometer tolerance constraints limit deployment in ultra-precision bearing applications. The category is expanding most quickly as battery-electric platforms proliferate.
- Plastic Spacer Rings:Injection-molded engineered thermoplastics serve cost-sensitive brake and chassis applications where mechanical loads remain moderate.
- Rubber Spacer Rings:Elastomer formulations absorb vibration and accommodate thermal expansion in suspension bushing assemblies with shortest replacement cycles.
Metal spacer rings dominate installed base across internal combustion powertrains. Composite spacer rings are where expansion concentrates as electrification reconfigures thermal management architectures.
Application:
Cost tier stratification separates premium drivetrain applications from commodity brake and chassis segments, with transmission units commanding highest per-unit value and brake systems operating on thinnest margins.
- Transmission Units:Multi-speed gearboxes and emerging e-axle designs demand complex stacked spacer configurations for bearing race positioning, thrust washer separation, and gear mesh clearance control. Precision requirements reach sub-10 micrometers in premium German and Japanese automated manual transmissions. Integrated module procurement trends are bundling spacer rings with bearing assemblies rather than discrete component sourcing.
- Engine Components:Crankshaft thrust bearings, camshaft timing systems, and turbocharger assemblies require hardened steel spacers resisting thermal cycling and mechanical fatigue. North American commercial vehicle platforms sustain volume through long-term supply contracts with domestic OEMs.
- Suspension Systems:Chassis geometry control and shock absorber mounting employ rubber and polymer spacers in high-volume, price-competitive specifications.
- Brake Systems:Caliper piston sealing and pad retention spacers represent mature demand with minimal technology differentiation and compressed supplier margins.
Transmission applications concentrate value capture and R&D investment. Brake system supply is where price pressure intensifies and supplier consolidation accelerates.
End User:
Customer type determines technical engagement depth, with Tier-1 integrators assuming stacked configuration design responsibility while aftermarket providers compete on availability and interchangeability.
- Tier-1 Suppliers:Platform-level integrators such as Dana Incorporated and Schaeffler AG now specify spacer ring subsystems rather than discrete components, concentrating purchasing power and design authority. These suppliers maintain captive machining capabilities and polymer formulation expertise to serve OEM transmission and e-axle programs.
- OEMs:Direct procurement persists for high-volume engine and brake applications where in-house powertrain engineering teams retain component-level specification authority, particularly among Japanese and Korean manufacturers.
- Aftermarket Providers:Independent distributors and service chains capture replacement demand through refurbishment program integration and commercial fleet overhaul bundling.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders source standard spacer configurations through distributor channels rather than direct Tier-1 relationships.
Tier-1 suppliers dominate design-in influence for emerging electrified platforms. Aftermarket channels are where lifetime value capture shifts as commercial vehicle fleets extend service intervals.
Size:
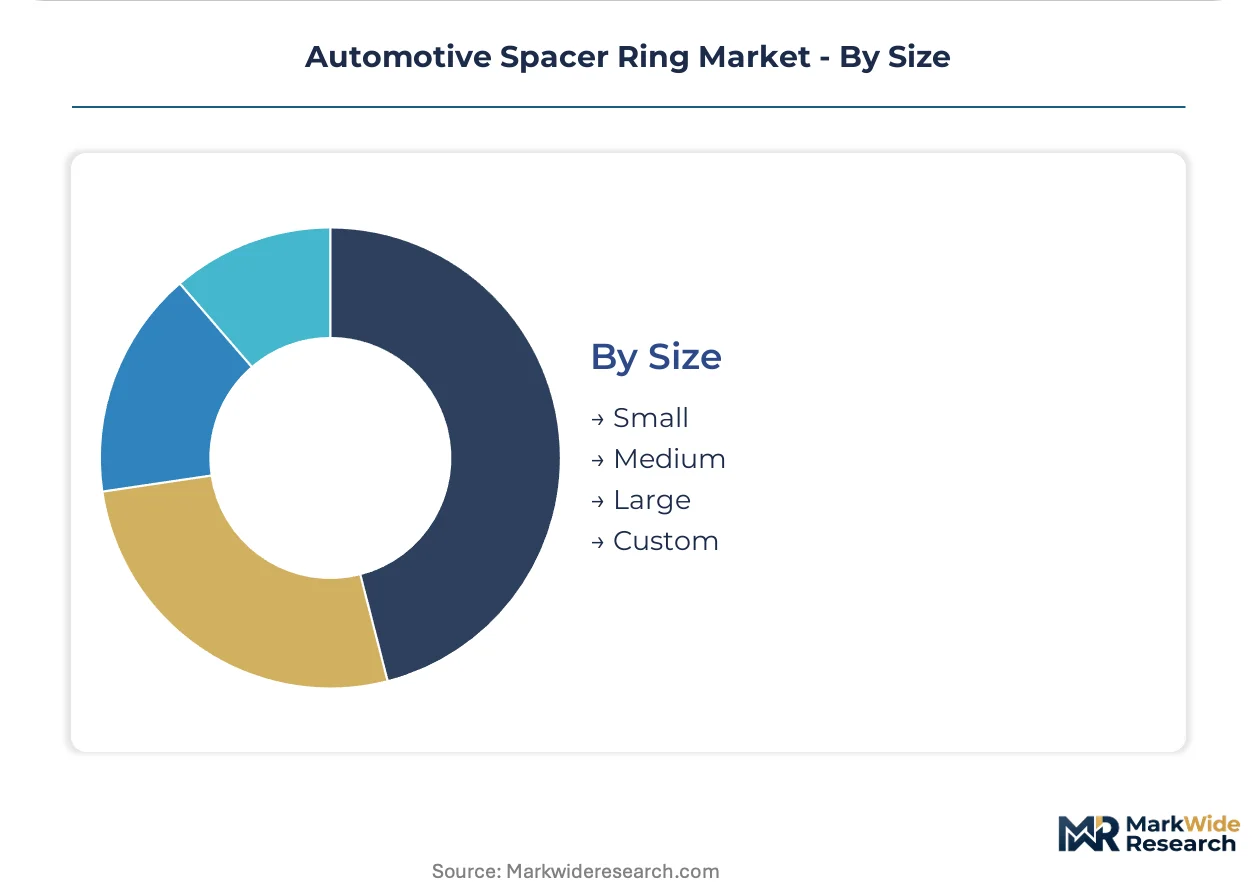
Volume concentration sits with medium and small formats standardized across passenger vehicle platforms, while custom geometries command premium positioning in commercial vehicle and performance applications.
- Medium:Standardized dimensions for passenger vehicle transmission and engine applications enable economies of scale across multiple OEM platforms. Baden-Württemberg machining clusters specialize in medium-format precision production.
- Small:Compact spacers for turbocharger assemblies, fuel injection systems, and electrified auxiliary drives match the miniaturization trajectory of powertrain components.
- Large:Heavy-duty commercial vehicle and off-highway equipment applications require thicker cross-sections and larger diameters with extended lead times.
- Custom:Motorsport, aerospace-derived automotive, and prototype electrified platforms demand application-specific geometries with prototype-to-production transition services.
Medium formats anchor production scale across standardized passenger vehicle programs. Custom specifications are where margin expansion potential concentrates for suppliers with hybrid additive-subtractive manufacturing capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major automotive manufacturing zones. Germany prioritizes sub-10-micrometer precision for transmission stacks, while China emphasizes lightweight composite formulations for NEV thermal modules, and the United States sustains volume through commercial vehicle platform contracts.
Germany
Precision transmission and e-axle assembly demand anchors spacer ring consumption in Baden-Württemberg and Bavaria. REACH substance restrictions under ECHA jurisdiction force alloy composition transparency that extends Tier-1 supplier qualification timelines. Stuttgart's machining clusters specialize in hardened steel configurations for BMW and Volkswagen Group powertrain divisions.
China
MIIT enforcement of NEV production quotas compels automakers to engineer composite spacer solutions for electric drivetrain thermal management. GB standards govern dimensional precision and material certification for domestic automotive component production. Yangtze River Delta manufacturing corridors concentrate polymer-formulation R&D for battery housing clearance-control applications.
United States
North American commercial vehicle platforms sustain metal spacer ring volume through long-term supply contracts with domestic OEMs. EPA material content and recyclability standards shape composite formulation choices for vehicles sold in the United States. Michigan and Ohio industrial corridors anchor production for heavy-duty transmission and engine crankshaft assemblies.
Japan
Automated manual transmission precision requirements reach sub-10 micrometers in premium Japanese powertrain architectures. METI industrial policy supports advanced materials R&D for electrified platform thermal management. Nagoya's Chubu region concentrates precision component specialists with captive micro-machining capabilities.
India
PLI scheme incentives for domestic automotive component manufacturing open captive demand from Tata Motors and Mahindra electric platforms. BIS certification protocols govern dimensional standards for spacer ring production serving domestic OEMs. Maharashtra and Gujarat industrial corridors attract Tier-1 supplier localization for emerging NEV supply chains.
Automotive Spacer Ring Market Competitive Environment
Capability concentration sits with precision machining specialists; scale advantage sits with diversified automotive component conglomerates. The vendor base organizes into three tiers: integrated platform-level suppliers assuming stacked configuration design responsibility, discrete component manufacturers serving cost-sensitive brake and chassis segments, and hybrid material specialists bridging metal-composite convergence. Consolidation pressures intensify as OEM procurement shifts toward bundled subsystem sourcing. Two dominant competitive moves define current positioning: backward integration into captive polymer formulation capabilities, and strategic partnerships with additive manufacturing technology providers.
Among German-based precision component specialists, Schaeffler AG exemplifies the integrated platform-tier archetype through its bearing and precision component heritage. SKF Group occupies a position within the hybrid materials vector, anchoring R&D intensity in polymer-composite formulations. Dana Incorporated represents the scale-driven North American commercial vehicle end, sustaining volume through long-term platform contracts.
| Leading Market Players |
|---|
| Schaeffler AG |
| SKF Group |
| Dana Incorporated |
| NTN Corporation |
| ZF Friedrichshafen AG |
| Continental AG |
| BorgWarner Inc. |
| Magna International Inc. |
| JTEKT Corporation |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg's precision machining clusters concentrate hardened steel spacer ring capacity for BMW and Volkswagen Group powertrain divisions, translating geographic supply dominance into pricing power for sub-10-micrometer tolerance specifications. China's Yangtze River Delta polymer-formulation corridors compete on composite cost structures, fragmenting pricing authority across material classes and forcing Tier-1 suppliers to defend margin position through captive R&D rather than scale leverage alone.
Pricing Analysis
Long-term offtake agreements anchor pricing for transmission stack configurations serving German OEM powertrain divisions, while spot procurement governs brake system replacement demand. Price differentiation rests on REACH certification tiers and volume scale commitments, with premium drivetrain applications commanding substantial premiums over commodity chassis segments. Cost compression in plastic and rubber formulations is intensifying because Chinese NEV mandates accelerate specification of lightweight alternatives. Aftermarket distributors exhibit highest price sensitivity, whereas Tier-1 integrators prioritize dimensional stability guarantees over unit cost minimization.
Supply Chain Analysis
Contract manufacturing concentration sits with Schaeffler AG and SKF Group captive facilities in Germany, supplemented by Dana Incorporated production corridors in Michigan and Ohio. Raw material flows draw from Swedish specialty steel producers, German polymer compounders, and Chinese carbon fiber suppliers. Single-source vulnerability concentrates in sub-10-micrometer micro-machining tooling engineered by Japanese and German precision specialists. Distribution runs through platform-level Tier-1 integrators bundling spacer rings within transmission and e-axle subsystems rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated module procurement trends, as OEM engineering teams delegate stacked spacer configuration design responsibility to platform-level Tier-1 suppliers and consolidate purchasing volumes accordingly.
For Market Incumbents: Build formulation expertise moats around polymer-composite convergence technologies that blend engineered thermoplastics with selective metal reinforcement. Deepen backward integration into captive polymer compounding capabilities to offset REACH carbon footprint disclosure requirements. Add precision machining capacity in India's Maharashtra and Gujarat corridors to capture PLI scheme localization demand from Tata Motors and Mahindra electric platforms before emerging competitors establish qualification relationships. For New Entrants and Emerging Players: India's NEV supply localization gap offers the most penetrable entry vector for composite spacer ring specialists seeking qualification with domestic OEMs. Target commercial vehicle aftermarket refurbishment programs in North America, where fleet overhaul bundling creates service revenue streams independent of OEM platform design-in cycles. Pursue joint development agreements with additive manufacturing technology providers to bypass micro-machining talent scarcity constraining incumbent composite tolerance capabilities. For Investors and Strategic Acquirers: Long-term, this sits as a materials-transition play because electrification reconfigures thermal management architectures and prioritizes mass reduction over legacy metal performance metrics. Acquisition targets should emphasize hybrid additive-subtractive manufacturing capabilities enabling rapid prototype-to-production transitions for custom e-axle geometries. Monitor MIIT GB standard certification timeline compression as an inflection signal indicating foreign supplier qualification barriers are easing.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer-Composite Formulation Investment | REACH carbon disclosure requirements favor suppliers with captive recycling streams and bio-based feedstock integration. |
| Hybrid Additive-Subtractive Manufacturing Scale-Up | BMW and Volkswagen Group powertrain divisions pilot lattice-structured geometries compressing prototype iterations from weeks to days. |
| Indian Manufacturing Footprint Establishment | PLI scheme incentives attract Tier-1 supplier localization for emerging Tata Motors and Mahindra electric platform supply chains. |
| Aftermarket Refurbishment Program Integration | Commercial fleet overhaul bundling captures lifetime value through transmission module replacement rather than discrete component sales. |
| MIIT GB Standard Certification Acceleration | Foreign suppliers reducing 8-14 month qualification cycles gain first-mover advantage in China's NEV thermal module procurement. |
Study Parameters
Cross-validation between OEM platform engineering interviews and Tier-1 supplier procurement disclosures anchors the qualitative findings. Primary fieldwork engaged powertrain division executives at BMW and Volkswagen Group, Schaeffler AG and Dana Incorporated procurement leads, aftermarket distributor operations heads, and precision machining tooling engineers. Secondary validation incorporated IHS Markit vehicle production databases, MIIT NEV mandate compliance filings, ECHA REACH substance restriction updates, and SEC 10-K component segment disclosures. Bottom-up unit consumption modeling triangulated against top-down OEM platform content-per-vehicle estimates.
Calibration against historical specification shifts in transmission and e-axle architectures refined elasticity assumptions across the projection horizon. Segmentation dimensions modeled include material class, application tier, end-user type, and regional production cluster. CAGRs derived from slope-intercept analysis of platform-level procurement volume trajectories, adjusted for electrification-driven thermal management module redesigns. Industry-specific forecast inputs encompassed battery-electric platform architecture roadmaps and composite tolerance-holding constraint resolution timelines.
Practitioners should monitor steel alloy price volatility, REACH substance restriction expansions, and MIIT certification protocol modifications for early signals requiring forecast revision. Quarterly review of Tier-1 integrated module procurement contract awards and additive manufacturing pilot program escalations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Differential System Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Automotive Mechanical Control Cable Market
Automotive Parts
Automotive Canister Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Engine Piston Ring Set Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Synchronous Timing Belts Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market