
 EV Reduction Gears Market | 2026-2036
EV Reduction Gears Market Size, Share, and Industry Trends Forecast 2026-2036
EV Reduction Gears Market Insights
The gap between premium precision-machined reduction gears and commodity-grade alternatives is shifting from a price spread into a capability divide. BorgWarner leverages its integrated e-axle platforms to control high-torque planetary systems for performance EVs. ZF competes through modular gear architectures that sustain manufacturing flexibility across passenger and commercial vehicle lines. GKN Automotive anchors its position in all-wheel-drive applications where torque-vectoring demands exceed standard gearbox tolerances.
EV reduction gears are precision torque-modifying transmissions that step down motor rotational speed while multiplying output torque, typically operating at input speeds exceeding 15,000 RPM with noise thresholds below 70 decibels to meet cabin comfort specifications. Planetary gear configurations dominate high-torque applications due to their coaxial packaging efficiency and load distribution across multiple planet gears. Bevel gear systems occupy niche positions in axle-mounted drivetrains where angular power transfer is required. Helical gears lead in noise-sensitive passenger vehicle segments where tooth engagement angle reduces acoustic signature below competing geometries.
EPA tailpipe regulations in the United States and EU Green Deal carbon-neutrality mandates are forcing gear manufacturers toward aluminum and composite material substitutions that reduce rotating mass. NHTSA safety standards and ECE homologation requirements shape tooth fatigue testing protocols that govern market access for imported gearsets. Stakeholders must monitor how China MIIT domestic content rules and evolving ISO gear-quality grades interact to reshape supplier qualification criteria across major EV manufacturing clusters.
Market Dynamics
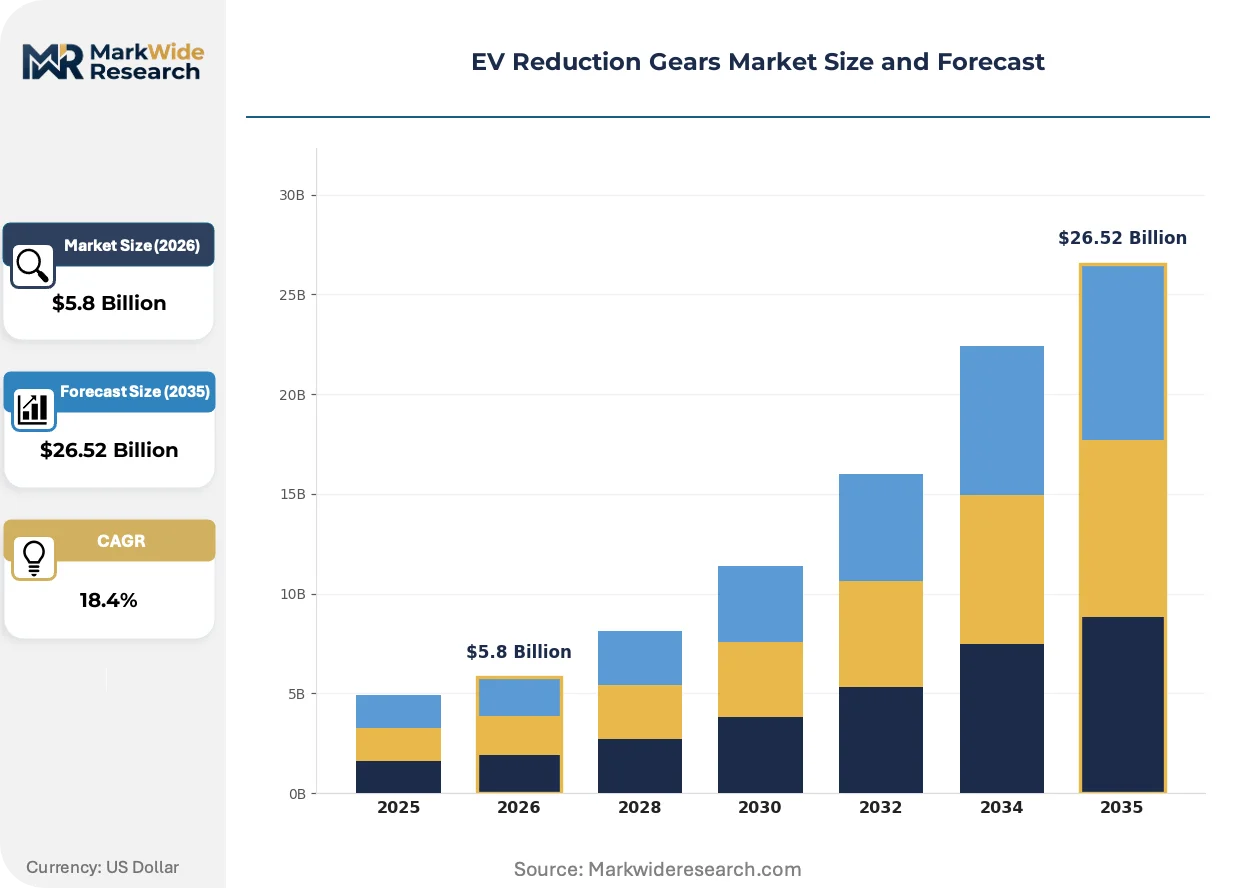
Passenger vehicle electrification is compressing powertrain development cycles, forcing gear manufacturers to synchronize precision-machining capacity with platform launches from domestic EV producers in China, Germany, and the United States. This acceleration is restructuring supplier qualification timelines and capital deployment patterns across the value chain.
Growth Catalysts
- EU Green Deal carbon-neutrality mandates:These frameworks are compelling automakers to source lighter aluminum and composite gearsets that reduce rotating mass and extend vehicle range.
- China MIIT domestic content rules:Local EV manufacturers are scaling in-house drivetrain platforms, creating captive demand for precision planetary systems within domestic supply chains.
- Helical gear tooth geometries:These configurations are penetrating noise-sensitive passenger segments where cabin comfort specifications demand acoustic signatures below 70 decibels.
Market Restraints
- Rare-earth magnet price volatility:Neodymium and dysprosium input costs for integrated e-motor-gear units fluctuate with Chinese export quotas, compressing margin predictability.
- Single-source precision grinding equipment:German and Japanese machine tool suppliers control 5-axis gear-hobbing capacity, creating chokepoints for tier-2 manufacturers scaling output.
- ISO 6336 tooth fatigue certification timelines:Extended validation protocols for high-RPM applications delay market entry for new gearset architectures by 18-24 months.
Strategic Opportunities
- Commercial vehicle electrification in India:BIS efficiency standards for electric buses and last-mile delivery fleets are opening demand for high-torque planetary reduction systems previously confined to passenger applications.
- Additive manufacturing convergence with topology optimization:Laser powder bed fusion is enabling lattice-structured gear carriers that reduce weight 30-40% versus conventional cast housings.
- US Inflation Reduction Act clean vehicle credits:Domestic assembly requirements are incentivizing North American gear production co-location with battery cell and e-axle manufacturing.
Industry Challenges
- Precision metrology skill scarcity:Gear noise-vibration-harshness (NVH) engineering and CMM programming expertise concentrates among aging specialists in Stuttgart, Wolfsburg, and Detroit metro areas.
- Legacy axle-gear integration complexity:Torque-vectoring all-wheel-drive architectures require sub-arc-minute backlash tolerances that strain conventional quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Reduction Gears Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $26.52 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Planetary Gears, Bevel Gears, Worm Gears, Helical Gears Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Industrial Vehicles Material: Steel, Aluminum, Composite Materials, Plastic Technology: Mechanical, Electromechanical, Hydraulic, Pneumatic |
| Companies Covered | BorgWarner, ZF, GKN Automotive, Bosch, HOTA Industrial, Schaeffler, Aichi Machine Industry, Magna International, Nidec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Reduction Gears Market Trends and Innovations
Digital thread integration across design, simulation, and production is collapsing development lead times for precision reduction systems. Gear manufacturers are reconfiguring capital allocation toward predictive quality systems and modular platform architectures.
AI-driven generative design software is automating tooth profile optimization for specific torque-speed operating maps. Tier-1 suppliers in Germany and Japan are deploying these tools to compress iteration cycles from months to weeks. The technology is automating the transition from empirical design rules toward physics-informed topology that minimizes contact stress while maximizing lubrication film thickness.
REACH substance restrictions on PFAS lubricants are forcing reformulation of gear oils for high-speed EV applications. ECHA evaluation of perfluorinated compounds is accelerating adoption of ionic liquid and polyalkylene glycol base stocks with comparable thermal stability. European gear manufacturers are qualifying these alternatives under ECE homologation protocols ahead of 2025 restriction deadlines.
Direct-to-platform procurement contracts are displacing traditional tier-n supplier hierarchies. Chinese EV producers are awarding multi-year gear supply agreements to machining specialists that co-locate with final assembly plants. This pattern is most visible in Hefei, Ningbo, and Xi'an manufacturing clusters where MIIT industrial policy incentivizes supply chain compression.
EV Reduction Gears Market Segmentation
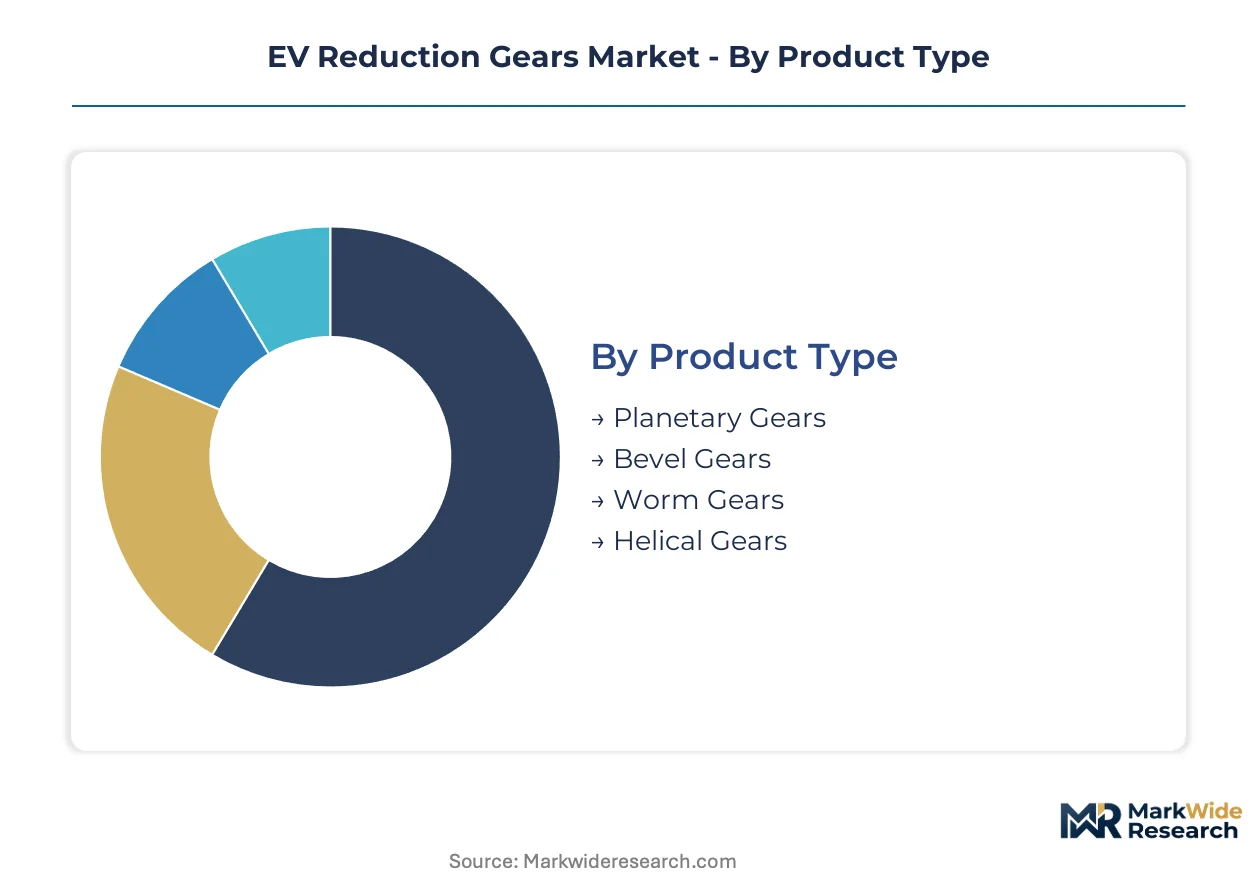
Precision reduction gear architectures fragment across torque-density requirements, acoustic thresholds, and integration depth with e-axle platforms. Segmentation reveals where standalone gearboxes persist versus fully embedded motor-gear units, shaping supplier qualification criteria and capital deployment patterns across the value chain.
Product Type:
Integration depth separates standalone reduction units from embedded motor-gear systems, with coaxial packaging demands driving divergence in manufacturing scale and precision requirements.
- Planetary Gears:Coaxial configurations distribute torque across multiple planet gears rotating within an annulus ring, enabling the highest torque-density packaging for performance EVs. Demand concentrates in China where domestic manufacturers scale in-house drivetrain platforms requiring high-RPM tolerance above 15,000 RPM.
- Helical Gears:Angled tooth engagement geometry reduces acoustic signature through progressive contact patterns, critical for cabin comfort specifications below 70 decibels. European passenger vehicle electrification under EU Green Deal mandates is accelerating adoption of noise-optimized tooth profiles.
- Bevel Gears:Conical tooth geometries enable angular power transfer in axle-mounted configurations where motor-gear alignment deviates from wheel axis.
- Worm Gears:Screw-and-wheel mechanisms provide high reduction ratios in self-locking configurations for limited-slip differential applications.
Planetary gears lead volumes today; helical configurations are gaining share fastest in premium passenger segments.
Application:
Vehicle electrification intensity varies sharply across duty cycles, with urban delivery patterns and highway cruising profiles imposing divergent thermal and fatigue requirements on gear systems.
- Passenger Vehicles:Noise-vibration-harshness specifications below 70 decibels dominate design priorities, with helical and planetary architectures competing on packaging efficiency. China MIIT domestic content rules are compressing supplier qualification timelines as local EV manufacturers scale production.
- Commercial Vehicles:High-torque planetary systems endure stop-start duty cycles and regenerative braking loads in electric buses and last-mile delivery fleets. India's BIS efficiency standards for electric buses are opening demand for gearsets previously confined to passenger applications.
- Two-Wheelers:Compact single-stage reduction units prioritize weight minimization and sealed-for-life lubrication in high-volume scooter and motorcycle platforms.
- Industrial Vehicles:Forklift and warehouse automation applications demand intermittent high-torque output with extended idle periods, stressing lubrication film stability.
Passenger vehicles anchor current demand; commercial vehicle electrification is climbing the fastest.
Material:
Rotating mass reduction directly extends vehicle range, compelling substitution away from conventional steel toward lighter alloys and engineered composites under tightening emissions frameworks.
- Steel:Carburized and through-hardened alloy grades maintain dominance in high-torque commercial applications where tooth bending fatigue resistance governs service life. EPA tailpipe regulations in the United States and EU Green Deal carbon-neutrality mandates are nonetheless forcing weight-conscious substitutions in passenger segments.
- Aluminum:Die-cast and forged aluminum alloys reduce rotating mass 40-60% versus steel equivalents, with silicon-modified grades improving wear resistance in planetary carriers. European gear manufacturers are qualifying aluminum architectures under ECE homologation protocols ahead of 2025 restriction deadlines.
- Composite Materials:Carbon-fiber-reinforced polymer gear carriers achieve 30-40% weight reduction through laser powder bed fusion topology optimization.
- Plastic:High-performance polyamide and PEEK formulations serve low-torque auxiliary drives where metal-to-metal contact is eliminated.
Steel retains volume leadership; aluminum alloys are expanding most quickly under range-extension imperatives.
Technology:
Actuation mechanisms differentiate between purely mechanical torque paths and integrated electromechanical systems where gear reduction couples directly with motor control electronics.
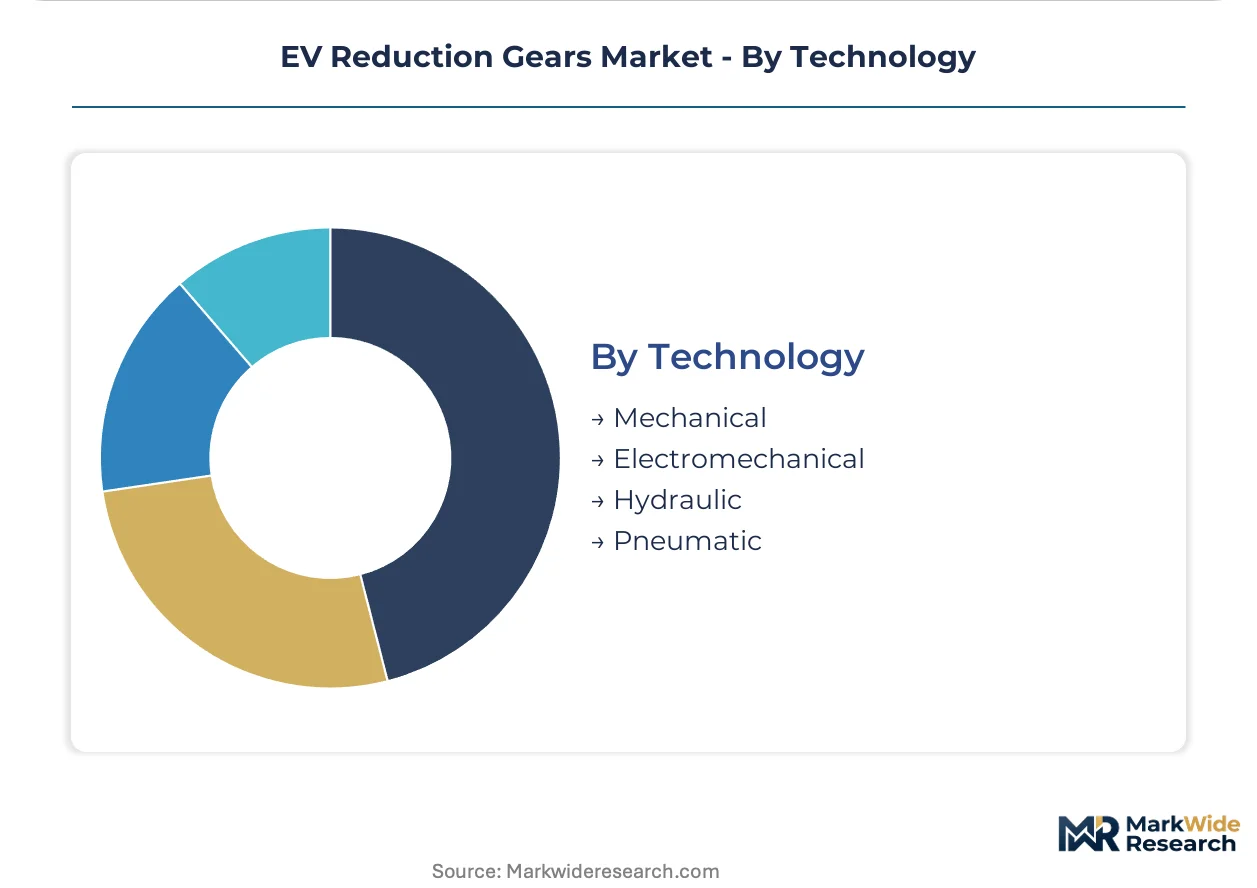
- Mechanical:Conventional gear meshes with fixed ratios dominate cost-sensitive applications where electronic control integration is deferred to downstream suppliers. German and Japanese machine tool suppliers control 5-axis gear-hobbing capacity for precision mechanical systems.
- Electromechanical:Integrated e-axle platforms combine motor, inverter, and reduction gear in sealed units, demanding sub-arc-minute backlash tolerances for torque-vectoring precision. ZF and BorgWarner compete through modular electromechanical architectures that sustain manufacturing flexibility across vehicle lines.
- Hydraulic:Fluid power transmission persists in heavy-duty off-highway applications where torque multiplication exceeds mechanical gear limits.
- Pneumatic:Compressed air actuation serves niche auxiliary systems in industrial vehicle braking and suspension mechanisms.
Mechanical systems dominate installed base; electromechanical integration is gaining share fastest as e-axle platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands manufacturing scale for EV reduction gears while Germany maintains precision-engineering dominance in high-torque planetary systems. Divergent regulatory frameworks and industrial policies are fragmenting competitive dynamics across major production clusters.
China
Domestic EV manufacturers are scaling in-house drivetrain platforms at unprecedented velocity, creating captive demand for high-RPM planetary systems. MIIT domestic content rules compress supplier qualification timelines and favor local machining specialists. Hefei, Ningbo, and Xi'an manufacturing clusters concentrate precision gear production alongside final assembly plants.
Germany
EU Green Deal carbon-neutrality mandates force aluminum and composite substitutions that reduce rotating mass. ECHA REACH frameworks govern PFAS lubricant phase-outs, accelerating ionic liquid reformulation. Stuttgart and Wolfsburg metro areas concentrate gear noise-vibration-harshness engineering expertise among aging specialist workforces.
United States
IRA clean vehicle credits incentivize North American gear production co-location with battery cell and e-axle manufacturing. EPA tailpipe regulations drive material lightweighting in passenger vehicle segments. Detroit metro area retains precision metrology and CMM programming capabilities despite workforce constraints.
Japan
METI industrial policy supports electromechanical integration for modular e-axle architectures serving export markets. JIS gear-quality grades interact with evolving ISO 6336 certification protocols. Nagoya and Tokyo manufacturing bases sustain 5-axis gear-hobbing capacity controlled by dominant machine tool suppliers.
India
BIS efficiency standards for electric buses and last-mile delivery fleets open demand for high-torque planetary systems. Commercial vehicle electrification intensifies stop-start duty cycle requirements. Gujarat and Maharashtra industrial corridors attract gear manufacturers serving domestic OEM platform launches.
EV Reduction Gears Market Competitive Landscape
Top-tier vendors anchor integrated e-axle platforms, while mid-tier machining specialists compete on co-location proximity and qualification speed. The vendor base stratifies between full-system integrators and component suppliers. Three archetypes dominate: precision planetary specialists, modular architecture providers, and captive in-house producers. M&A activity concentrates on electromechanical integration capabilities, while capacity expansion patterns track MIIT industrial zones and IRA incentive corridors.
Among German-based Tier-1 suppliers, ZF and Schaeffler exemplify modular gear architectures that sustain manufacturing flexibility across vehicle lines. BorgWarner occupies a position representing integrated e-axle platforms controlling high-torque planetary configurations. These three entities anchor competitive positioning where precision-machined reduction gears diverge from commodity-grade alternatives on capability rather than price.
| Leading Market Players |
|---|
| BorgWarner |
| ZF |
| GKN Automotive |
| Bosch |
| HOTA Industrial |
| Schaeffler |
| Aichi Machine Industry |
| Magna International |
| Nidec |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed machining specialists in China's Hefei and Ningbo industrial corridors anchor supply concentration for high-RPM planetary systems, translating captive procurement relationships into pricing discipline that resists spot-market volatility. This ownership pattern compresses supplier qualification timelines under MIIT domestic content rules while forcing European and North American buyers to absorb premium logistics costs for precision-ground gearsets outside domestic production clusters.
Pricing Analysis
Bundled electromechanical e-axle platforms command substantial premiums over standalone reduction units, with price differentiation resting on ISO 6336 tooth fatigue certification grades and after-sales service bundling. Three-tier pricing structure across precision-machined, modular-standard, and commodity-grade tiers stratifies the market. Cost compression in standard-grade helical configurations is intensifying because German and Japanese machine tool suppliers constrain 5-axis hobbing capacity. Fleet procurement officers at commercial vehicle OEMs exhibit highest price sensitivity, while performance EV platform engineers prioritize NVH specifications over unit economics.
Supply Chain Analysis
Reverse-logistics flows for remanufactured planetary carriers and refurbished precision grinding spindles are emerging from Stuttgart and Detroit metro service depots, extending component lifecycles amid scarce metrology expertise. Manufacturing concentration centers on China, Germany, and Japan for precision-machined gearsets. Raw material dependencies draw from neodymium and dysprosium rare-earth magnets, carburized alloy steel billets, and aluminum-silicon casting alloys. Single-source vulnerability in 5-axis gear-hobbing equipment creates structural chokepoints. Distribution runs through Tier-1 e-axle integrators directly to OEM platform engineering teams, bypassing traditional tier-n hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal carbon-neutrality mandates and EPA tailpipe regulations mechanically expand addressable demand for lightweight gear architectures. The regulatory intensity creates asymmetric returns for suppliers achieving certification ahead of restriction deadlines.
For Market Incumbents: Acquire precision metrology and CMM programming capabilities concentrated in Stuttgart and Wolfsburg to defend against Chinese captive producers scaling in-house drivetrain platforms. Deepen backward integration into aluminum-silicon alloy casting to secure rotating mass reduction supply under ECHA REACH material substitution timelines. Prioritize electromechanical integration R&D to maintain positioning as e-axle architectures displace standalone gearboxes. For New Entrants and Emerging Players: Direct-to-platform digital procurement channels serving Chinese EV manufacturers in Xi'an manufacturing clusters offer the most penetrable entry vector. Target commercial vehicle electrification in India under BIS efficiency standards for electric buses, where high-torque planetary demand exceeds established supplier coverage. Pursue additive manufacturing certification for topology-optimized gear carriers to bypass capital-intensive 5-axis hobbing equipment constraints. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier machining specialists with co-location proximity to MIIT industrial zones but lacking electromechanical integration capabilities. Long-term viability over the projection horizon favors targets achieving ISO 6336 certification ahead of 2025 ECHA restriction deadlines. Monitor PFAS lubricant reformulation progress as the signal indicating which European gear manufacturers will retain ECE homologation access.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical E-Axle Integration | Sealed motor-inverter-gear units command platform-standardization decisions at ZF and BorgWarner. |
| Aluminum Alloy Material Substitution | Die-cast silicon-modified grades reduce rotating mass 40-60% under EU Green Deal range mandates. |
| Precision Metrology Capability Acquisition | CMM programming expertise concentrates among aging specialists in Stuttgart and Detroit corridors. |
| Additive Manufacturing Certification | Laser powder bed fusion enables 30-40% weight reduction in lattice-structured gear carriers. |
| Co-Location with MIIT Industrial Zones | Hefei and Ningbo clusters compress supplier qualification timelines under domestic content rules. |
Research Methodology
Bottom-up EV platform production modeling reconciled against top-down precision machining capacity tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket service heads, and precision grinding equipment specialists combined with secondary validation from MIIT production disclosures, EPA regulatory filings, ECHA REACH substance evaluations, and IHS Markit vehicle registration databases. This dual-structure approach triangulates demand signals against supply-side constraints.
Historical trendline analysis of gear content per vehicle across passenger, commercial, and two-wheeler electrification pathways informed the projection framework. Segmentation dimensions modeled include gear architecture type, vehicle application, material grade tier, and technology integration depth, with regional production cluster dynamics as an automotive-specific overlay. CAGRs were derived from elasticity-adjusted penetration curves rather than linear extrapolation, incorporating rare-earth magnet price volatility and ISO 6336 certification timeline assumptions.
Machine tool capacity bottlenecks, PFAS lubricant restriction enforcement variance, and China MIIT domestic content rule calibration are the dominant revision risks to forecast outputs. Practitioners should monitor German and Japanese 5-axis gear-hobbing equipment lead times, ECHA evaluation timelines for perfluorinated compounds, and IRA clean vehicle credit domestic assembly requirement implementations for early signals of trajectory adjustment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
HCV Brake Components Market
Automotive Parts
Cabin Air Filter Housing Replacement Parts Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Automotive All Wheel Drive Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Automotive Fuel Supply System Market
Automotive Parts
Philippines Automotive Lubricants Market
Automotive Parts
Automotive Lubricants Market