
 Canada Automotive Actuators Market | 2026-2036
Canada Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive Actuators Market Outlook
Ontario's electric vehicle battery plant investments are rewriting component sourcing maps across the Canadian supplier base. Denso Corporation leverages its powertrain actuator expertise to secure Tier-1 contracts with domestic vehicle assemblers. Robert Bosch GmbH anchors its position through integrated mechatronic modules that combine motor control with position sensing. Continental AG competes on brake-system actuation, where electromechanical architectures displace legacy hydraulic designs in next-generation platforms.
Automotive actuators are electromechanical devices that convert electrical, hydraulic, or pneumatic energy into precise mechanical motion, typically achieving positioning accuracy within micrometers to millimeters depending on feedback architecture. Their primary purpose spans chassis control, thermal management, and powertrain optimization, with brushless DC motor variants now dominating electric vehicle applications for their efficiency and durability. Linear actuators lead product-type revenue pools, particularly in seat adjustment and closure systems where load-bearing precision commands premium pricing. Electric technology displaces hydraulic and pneumatic alternatives across power steering and brake systems, driven by vehicle electrification and the elimination of engine-driven pumps. OEMs capture the dominant end-user share, though aftermarket providers gain traction as actuator-equipped vehicles age out of warranty coverage.
Transport Canada enforces CMVSS crashworthiness standards that mandate redundant actuator performance in safety-critical brake and steering systems, while Environment Canada tailpipe regulations compel engine-control actuator precision to optimize combustion efficiency. Health Canada and PMRA jointly oversee material compliance for adhesives and coatings used in actuator housings, adding a chemical-safety layer to component qualification. Stakeholders must monitor how pending amendments to Canada's Motor Vehicle Safety Regulations reshape validation timelines for electromechanical braking actuators.
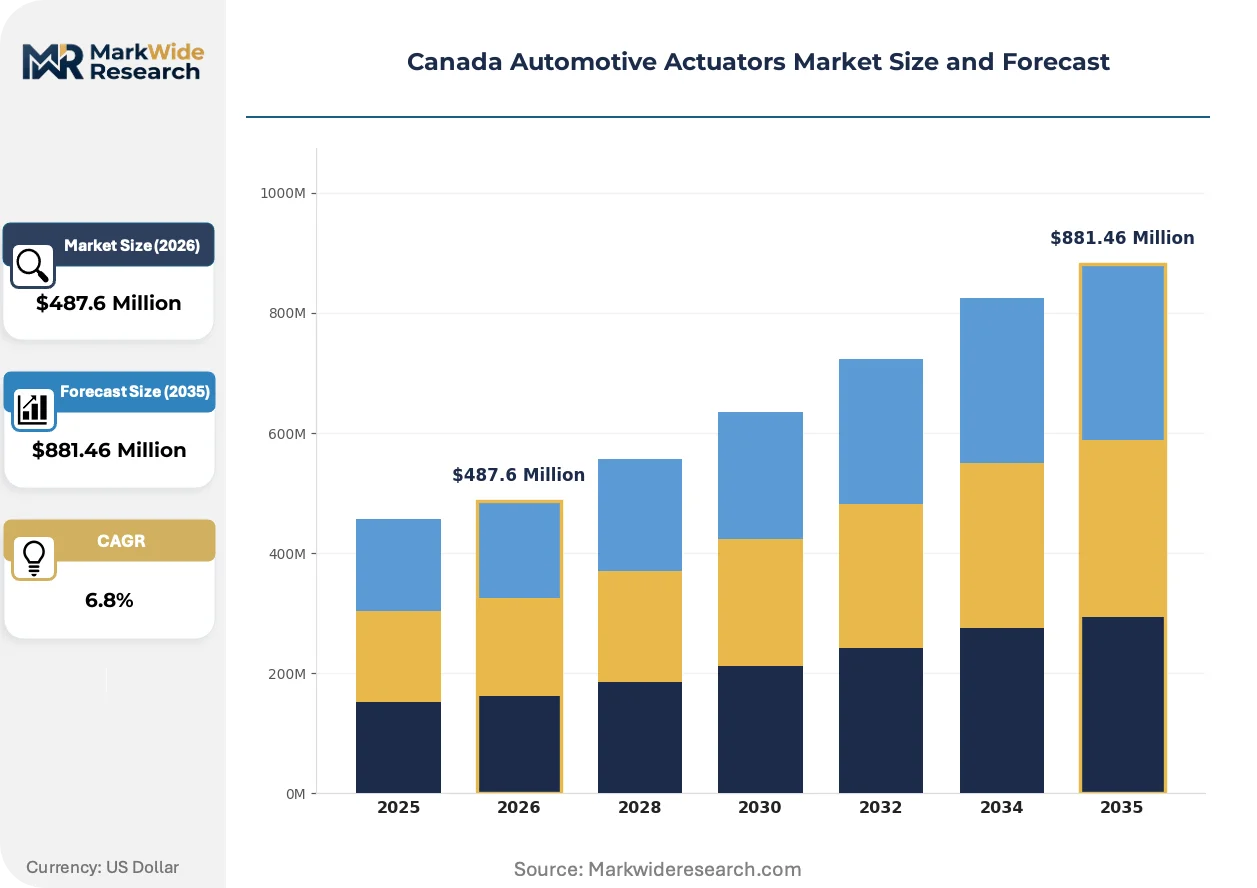
Market Dynamics
Canada's federal ZEV mandate and Ontario's battery plant investments are compressing supplier qualification timelines, forcing actuator manufacturers to accelerate electromechanical platform validation while maintaining CMVSS crashworthiness compliance.
Growth Catalysts
- Powertrain electrification mandates:Transport Canada's escalating tailpipe standards compel OEMs to replace engine-driven hydraulic pumps with high-efficiency electric actuators in steering and brake architectures.
- Windsor-Toronto corridor concentration:Stellantis, Ford, and GM assembly operations within this 300-kilometer zone create dense procurement pull for precision actuation systems with localized technical support.
- Light-duty truck electrification programs:Ontario provincial incentives for commercial fleet conversion generate sustained demand for heavy-load linear actuators in thermal management and closure systems.
Market Restraints
- Rare-earth magnet supply concentration:Brushless DC motor actuators depend on neodymium supply chains concentrated outside North America, exposing Tier-1 suppliers to input cost volatility and geopolitical friction.
- CMVSS validation burden:Transport Canada's redundant performance requirements for safety-critical brake actuators extend development cycles and escalate qualification costs for electromechanical platforms.
- Hydraulic system installed base:Legacy hydraulic actuation in commercial vehicle fleets creates substitution resistance, slowing electric actuator penetration in heavy-duty segments despite efficiency advantages.
Strategic Opportunities
- Quebec charging infrastructure buildout:Provincial electrification targets for transport refrigeration create demand for specialized thermal management actuators in commercial cold-chain vehicles.
- Health Canada material compliance services:PMRA adhesive and coating regulations position domestic testing laboratories to capture value-added certification revenue from foreign actuator manufacturers entering the Canadian market.
- Western Canada resource extraction electrification:Alberta and Saskatchewan mining fleet decarbonization programs open demand for ruggedized actuators in off-highway electric powertrains.
Industry Challenges
- Mechatronics engineering talent scarcity:The convergence of motor control, position sensing, and embedded software in integrated actuator modules outpaces Canadian university program output, compressing hiring pipelines for OEM technical centers in Oakville and Windsor.
- Dual certification complexity:Simultaneous CMVSS validation and US FMVSS alignment for cross-border supply contracts fragments engineering resources and extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive Actuators Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Solenoid Actuators, Piezoelectric Actuators Technology: Electric, Hydraulic, Pneumatic, Mechanical End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Power Steering, Seat Adjustment, Engine Control, Brake Systems |
| Companies Covered | Denso Corporation, Nidec Corporation, Johnson Electric Holdings Limited, Aptiv PLC, Continental AG, BorgWarner Inc., Robert Bosch GmbH, Stoneridge Inc., Mitsubishi Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive Actuators Market Strategic Shifts
Electromechanical architectures are collapsing legacy hydraulic and pneumatic paradigms across Canadian vehicle platforms, while regulatory pressure tightens material compliance and safety validation protocols.
Integrated mechatronic modules that combine brushless DC motors with Hall-effect position sensing are collapsing the historical separation between motion generation and feedback control. OEM procurement teams in Ontario now specify these unified packages for electric power steering and brake-by-wire systems, compressing supplier tier structures from three layers to two. The structural consequence is margin pressure on standalone motor manufacturers unable to deliver closed-loop positioning capability.
Health Canada and PMRA joint oversight of adhesives and coatings used in actuator housings is tightening material qualification requirements beyond mechanical performance metrics. Manufacturers must now submit chemical safety dossiers alongside traditional durability test data, extending validation timelines by four to six months. Brake-system suppliers face the steepest compliance burden, as housing materials in electromechanical calipers must satisfy both crashworthiness and environmental release standards.
Stellantis and Ford technical centers in Windsor and Oakville are consolidating actuator procurement under single-source mechatronic platform contracts, displacing the historical multi-vendor model. Tier-1 suppliers must now deliver integrated thermal, chassis, and powertrain actuation from unified engineering teams rather than product-specific divisions. This concentration is most visible in Ontario, where assembly plant proximity enables just-in-sequence delivery of complete actuator subsystems.
Canada Automotive Actuators Market Segmentation
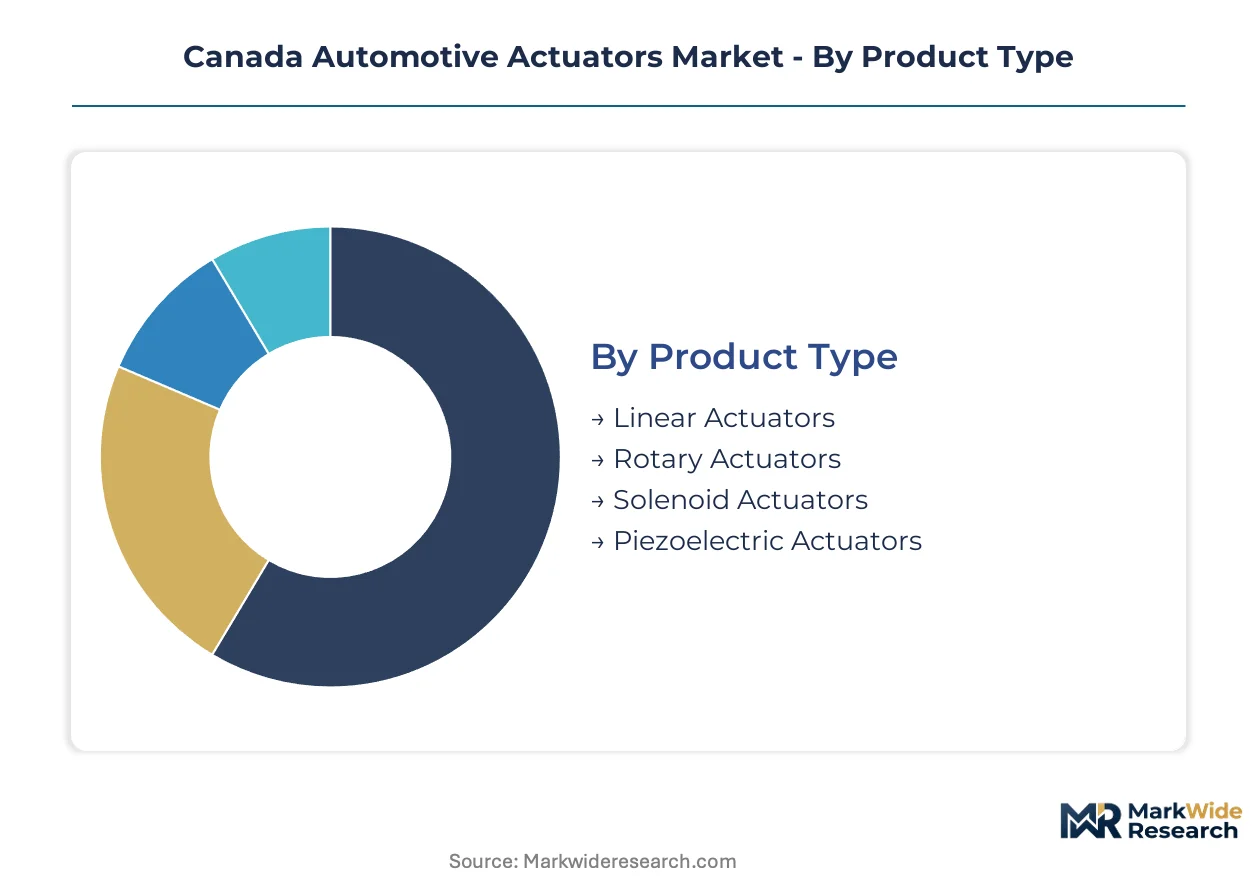
Actuator segmentation in Canada reveals divergent service intensity profiles across product architectures. Linear and rotary variants demand specialized calibration infrastructure that concentrates aftermarket revenue in Ontario's Windsor-Toronto corridor.
Product Type:
After-sales-service intensity varies sharply by motion mechanism, with precision feedback systems requiring dedicated diagnostic equipment.
- Linear Actuators:These devices convert rotational motion into precise linear displacement through ball-screw or belt-drive mechanisms. Demand concentrates in seat adjustment and closure systems across Stellantis and Ford light-duty truck platforms, where load-bearing precision commands premium replacement part pricing. Linear actuators hold the largest share; momentum sits with piezoelectric variants.
- Rotary Actuators:Torque-generating units that deliver angular positioning through harmonic drive or direct-drive motor architectures. Procurement pulls from GM's Oshawa assembly operations for chassis stabilization and active aerodynamic systems, driven by federal ZEV mandate compliance timelines.
- Solenoid Actuators:Electromagnetic switching devices providing rapid on-off actuation for transmission control and fuel injection systems.
- Piezoelectric Actuators:Ceramic-stack precision positioners enabling nanometer-scale motion control in fuel injection and optical headlamp alignment.
Linear architectures dominate replacement revenue pools; piezoelectric systems are climbing the fastest on precision electrification demand.
Technology:
Cost tier stratification separates premium electric platforms from legacy hydraulic maintenance streams.
- Electric:Brushless DC motor systems with integrated power electronics and position feedback. Windsor-Toronto corridor OEMs specify these for brake-by-wire and steer-by-wire architectures, displacing engine-driven pumps under Transport Canada tailpipe regulations.
- Hydraulic:Fluid-power actuation using pressurized oil circuits for high-force applications. Installed base concentration in Alberta commercial fleets creates sustained aftermarket demand despite efficiency disadvantages.
- Pneumatic:Compressed-air systems for low-cost, high-speed motion in legacy commercial vehicle suspension.
- Mechanical:Linkage and cam-driven actuation without external power sources, surviving in entry-level seat adjustment.
Electric platforms capture the margin premium; hydraulic systems retain the installed-base revenue base.
End User:
Customer type determines validation burden and pricing power, with OEMs demanding integrated subsystem accountability.
- OEMs:Original equipment manufacturers specifying complete mechatronic modules for platform integration. Ford and Stellantis technical centers in Oakville consolidate procurement under single-source contracts, compressing supplier margins while extending warranty liability.
- Aftermarket Providers:Independent distributors and service chains addressing out-of-warranty vehicle populations. Quebec's commercial fleet density supports specialized thermal management actuator rebuild services.
- Tier-1 Suppliers:Subsystem integrators delivering actuator assemblies to vehicle assemblers.
- Vehicle Assemblers:Final-stage manufacturers incorporating actuators into complete vehicle platforms.
OEMs dominate procurement volume; aftermarket providers are gaining share fastest as ZEV-equipped vehicles age.
Application:
Application maturity dictates supplier qualification timelines, with safety-critical systems facing extended CMVSS validation.
- Power Steering:Electric power steering actuators replacing hydraulic racks with column-mounted or rack-drive motor systems. Ontario battery plant investments accelerate electromechanical platform adoption across light-duty truck electrification programs.
- Seat Adjustment:Multi-axis linear actuators enabling memory positioning and massage functions. Premium SUV production at Oakville assembly generates concentrated demand for high-load precision mechanisms.
- Engine Control:Throttle body, variable valve timing, and EGR actuators optimizing combustion efficiency.
- Brake Systems:Electromechanical caliper and park-brake actuators replacing hydraulic circuits. Transport Canada redundant performance requirements extend development cycles for brake-by-wire suppliers.
Seat adjustment holds the largest share; brake systems are expanding most quickly on safety electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian actuator manufacturing clusters around the Windsor-Toronto corridor, where Stellantis, Ford, and GM assembly operations generate concentrated procurement pull. Provincial electrification mandates and federal ZEV targets are redrawing supplier qualification requirements across sub-regional markets.
Ontario
Stellantis and Ford technical centers in Windsor and Oakville consolidate procurement under single-source mechatronic contracts, compressing supplier tiers. Transport Canada CMVSS crashworthiness standards mandate redundant actuator performance in brake and steering systems. The Windsor-Toronto corridor anchors North American light-duty truck electrification programs, with battery plant investments accelerating OEM demand for precision actuation.
Quebec
Provincial charging infrastructure buildout for transport refrigeration generates specialized thermal management actuator demand in commercial cold-chain vehicles. Health Canada and PMRA joint oversight of adhesives and coatings extends validation timelines for actuator housing materials. Montreal-based testing laboratories capture certification revenue from foreign manufacturers entering the Canadian market.
Alberta
Mining fleet decarbonization programs create demand for ruggedized actuators in off-highway electric powertrains. Federal tailpipe regulations compel gradual displacement of hydraulic systems in resource extraction equipment. Calgary and Edmonton serve as procurement hubs for western Canada commercial fleet conversion initiatives.
British Columbia
Port of Vancouver electrification and zero-emission mandates for drayage trucks accelerate electromechanical brake and steering actuator adoption. Provincial zero-emission vehicle standards align with federal ZEV mandates, forcing component redesigns. Vancouver's clean technology cluster supports actuator validation for Pacific Northwest cross-border supply contracts.
Canada Automotive Actuators Market Competitive Environment
Integrated mechatronics specialists and standalone motor manufacturers split the market along capability boundaries. Tier-1 suppliers with closed-loop positioning expertise capture consolidated platform contracts from Windsor-Toronto corridor OEMs. Three archetypes dominate: Japanese diversified industrials with powertrain actuator heritage, German mechatronics integrators, and North American automotive-focused component suppliers. Competitive moves center on electromechanical platform validation acceleration and cross-border CMVSS-FMVSS dual certification alignment.
Within the diversified industrial tier, Denso Corporation and Nidec Corporation represent Japanese powertrain actuator expertise anchored in global automotive supply chains. Robert Bosch GmbH exemplifies the German mechatronics integrator archetype, occupying a position where motor control and position sensing capabilities converge. Continental AG sits within the brake-system specialization segment, reflecting electromechanical displacement of hydraulic architectures in safety-critical applications.
| Leading Market Players |
|---|
| Denso Corporation |
| Nidec Corporation |
| Johnson Electric Holdings Limited |
| Aptiv PLC |
| Continental AG |
| BorgWarner Inc. |
| Robert Bosch GmbH |
| Stoneridge Inc. |
| Mitsubishi Electric |
| Others |
Value Chain & Pricing Dynamics
The Windsor-Toronto corridor concentrates electromechanical actuator manufacturing capacity, compressing supplier margins while amplifying procurement leverage for Stellantis, Ford, and GM technical centers. Input cost volatility in rare-earth magnet supply chains feeds downstream pricing pressure across brushless DC motor architectures.
Pricing Analysis
Transport Canada CMVSS crashworthiness standards dictate the pricing tier structure for safety-critical brake and steering actuators, separating validated electromechanical platforms from unqualified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from OEM procurement teams. Pricing pressure stems from neodymium supply chain concentration outside North America, squeezing margins on brushless DC motor variants. Tier-1 suppliers with integrated mechatronic capabilities command least price sensitivity; standalone motor manufacturers face acute buyer leverage.
Supply Chain Analysis
Export controls on rare-earth processing technology limit North American magnet supply autonomy, tethering Canadian actuator manufacturers to concentrated overseas feedstock. China, Japan, and South Korea anchor global neodymium magnet production, with brushless DC motors and Hall-effect sensors drawing from these concentrated sources. Single-source vulnerability in rare-earth supply creates structural exposure to geopolitical friction and input cost spikes. Distribution runs through just-in-sequence delivery networks serving the Windsor-Toronto assembly corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where consolidated mechatronic procurement contracts are displacing multi-vendor sourcing models. Interoperability between motor control and position sensing modules is collapsing supplier tier structures from three layers to two.
For Market Incumbents: Harden defensive positions through backward integration into rare-earth magnet supply chains and accelerated CMVSS-FMVSS dual certification alignment. Capture stranded engineering talent in Windsor and Oakville technical centers before competitors consolidate recruitment pipelines. Prioritize single-source platform contracts with Stellantis and Ford to lock out emerging mechatronics specialists.
For New Entrants and Emerging Players: Western Canada mining fleet decarbonization represents the most penetrable white-space target, with Alberta and Saskatchewan procurement hubs underserved by established Ontario suppliers. Quebec transport refrigeration electrification offers secondary entry through specialized thermal management actuators. Lead with Health Canada PMRA material compliance services to capture certification revenue from foreign manufacturers entering the Canadian market.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because single-source mechatronic platform contracts are compressing viable supplier count to integrated specialists with closed-loop positioning expertise. Target acquisition archetypes: mid-cap Canadian actuator manufacturers with CMVSS validation history and Windsor-Toronto corridor proximity. Monitor Transport Canada Motor Vehicle Safety Regulations amendments as the critical inflection signal for electromechanical brake actuator validation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Stellantis and Ford consolidate procurement under unified mechatronic subsystem contracts. |
| Battery Supply Agreement | Ontario cell manufacturing investments accelerate electromechanical actuator content per vehicle. |
| Software-Defined Vehicle Investment | Embedded motor control and position sensing integration enables brake-by-wire architectures. |
| Geographic Manufacturing Footprint | Windsor-Toronto corridor proximity enables just-in-sequence delivery to assembly plants. |
| Charging Infrastructure Partnership | Quebec electrification targets create demand for thermal management actuators in commercial fleets. |
Study Parameters
Initial hypotheses were tested against primary input from Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and Health Canada regulatory affairs specialists and refined through secondary validation. Primary fieldwork combined structured interviews with Windsor-Torridor technical center personnel and Quebec commercial fleet operators. Secondary sources encompassed Transport Canada CMVSS documentation, Environment Canada tailpipe regulation filings, vehicle production databases, and IHS Markit registration data. Bottom-up segment sizing triangulated against top-down market value estimates.
Demand-supply balance modeling across the projection horizon captured powertrain electrification mandate impacts and rare-earth magnet supply constraints. Segmentation dimensions included product type, technology architecture, end-user category, and application safety criticality. CAGRs derived from regression analysis of historical procurement patterns and forward policy trajectory. Industry-specific inputs incorporated ZEV mandate compliance timelines and CMVSS validation burden estimates for electromechanical brake systems.
Practitioners should monitor rare-earth export control escalations, Transport Canada regulatory amendments, and OEM platform consolidation announcements for early signals of forecast deviation. Forecasts reflect documented assumptions regarding neodymium supply chain stability and Windsor-Toronto corridor assembly output. Material shifts in federal ZEV mandate stringency or CMVSS electromechanical brake validation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Crank Trigger System Market
Automotive Parts
North America Automotive AHSS Market
Automotive Parts
Automatic Gearbox Valves Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Russia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
US Automotive Airfilters Market
Automotive Parts
Automotive Timing Chain Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market