
 Automotive Grease Market | 2026-2036
Automotive Grease Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Grease Market Analysis
Electric vehicle assembly lines are broadening the end-use vertical mix for automotive grease, as battery thermal management systems and e-axle bearings require specialty lubricants distinct from internal combustion formulations. Shell plc leverages its global blending infrastructure to supply OEM-certified products across multiple continents. Fuchs Petrolub SE specializes in high-performance polyurea greases for precision bearing applications. Sinopec anchors supply security across Asia through integrated base oil and additive manufacturing.
Automotive grease comprises a semi-solid lubricant formulated from a base oil, thickener—typically lithium complex, calcium sulfonate, or polyurea—and performance additives, designed to reduce friction and prevent wear in components operating under high load and temperature. Its primary commercial purpose centers on extending service intervals and protecting wheel bearings, chassis joints, and engine ancillaries from corrosion and mechanical failure. Lithium grease occupies the largest volume share due to its versatility and cost efficiency across temperature ranges. Polyurea grease represents the fastest-expanding category, driven by extended-life specifications in sealed-for-life electric motor bearings and wheel hub units. Chassis applications retain stable demand from commercial fleet operators prioritizing preventive maintenance schedules.
The US EPA regulates base oil recycling and waste grease disposal under RCRA hazardous waste protocols, while EU REACH mandates disclosure of heavy-metal content and additive chemistry in lubricant formulations. China's SAMR enforces GB standards on grease oxidation stability and drop point specifications for domestic automotive supply chains. India's BIS certification requirements for automotive lubricants are tightening import quality gates. Stakeholders must monitor evolving OEM grease-fill specifications for electric axle assemblies and position formulation portfolios around thermal conductivity and dielectric compatibility requirements.
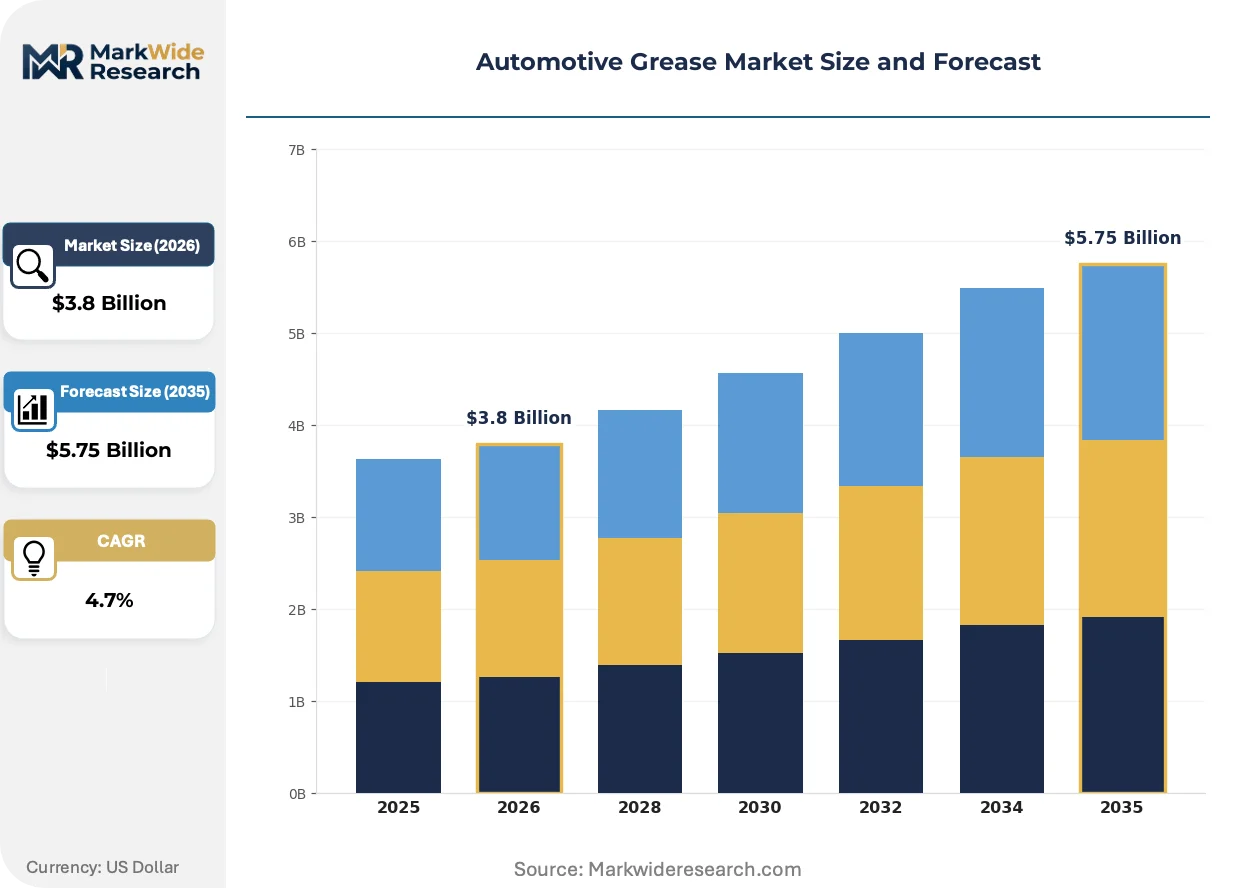
Market Dynamics
Electric vehicle powertrain architectures are fragmenting lubricant specifications, as thermal management systems and e-axle bearings demand greases with dielectric compatibility and conductivity profiles absent from internal combustion engine formulations.
Growth Catalysts
- EU REACH heavy-metal disclosure mandates:Formulators investing in clean-label additive packages capture OEM certification advantages across German and French automotive supply chains.
- India's commercial fleet density:Preventive maintenance protocols at Mumbai and Delhi servicing hubs sustain chassis grease consumption despite electrification headwinds elsewhere.
- Polyurea thickener chemistry:Extended-life specifications for sealed-for-life wheel hub units and electric motor bearings are accelerating specification upgrades from lithium complex alternatives.
Market Restraints
- Lithium hydroxide feedstock volatility:Battery sector competition for lithium salts compresses grease thickener margins and strains multi-year supply contracts.
- Base oil blending concentration:Integrated refiners in the US Gulf Coast and Rotterdam harbor control 60% of Group II/III supply, creating procurement bottlenecks for independent blenders.
- Dielectric property thresholds:E-axle thermal interface materials must simultaneously conduct heat and insulate electrically, a formulation boundary that eliminates conventional mineral-oil bases.
Strategic Opportunities
- Brazil's ANVISA import pathways:Localized blending investments bypass tariff barriers on finished lubricants while serving Mercosur fleet operators.
- China GB standard convergence:SAMR-mandated oxidation stability testing creates first-mover advantages for additive suppliers with pre-certified packages.
- Direct-to-fleet digital channels:Telematics-integrated inventory replenishment bypasses traditional distributor markups for commercial vehicle operators.
Industry Challenges
- Tribochemistry specialization gap:Formulators lack sufficient personnel trained in electric powertrain contact mechanics and thermal-electric coupling behavior.
- OEM grease-fill validation timelines:New e-axle specifications require 18-24 month qualification cycles that delay portfolio monetization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Grease Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Grease, Calcium Grease, Polyurea Grease, Silicone Grease Application: Wheel Bearings, Chassis, Engine Components, Electrical Systems End User: Automotive OEMs, Aftermarket Providers, Service Stations, Fleet Operators Packaging Type: Tubs, Cartridges, Drums, Sachets |
| Companies Covered | Shell plc, ExxonMobil Corporation, Sinopec, Fuchs Petrolub SE, TotalEnergies SE, Chevron Corporation, BP plc, PetroChina, Lukoil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Grease Market Emerging Trajectories
Formulation science is pivoting toward thermal-electric multifunctionality, while regulatory disclosure requirements and procurement digitization are compressing traditional specification and distribution architectures.
Synthetic ester base stocks with tailored viscosity-temperature profiles are modularizing grease platform development. Tier-1 suppliers serving German and Japanese OEMs adopt these stocks to reduce SKU proliferation across climate zones. The technology is modularizing how blenders configure regional product lines from centralized masterbatch systems.
China's SAMR enforcement of GB/T 7324 oxidation stability protocols is disqualifying import-dependent distributors. Domestic blenders with in-house testing laboratories capture specification-setting roles previously held by multinational technical service teams. Heavy-duty commercial chassis applications face the steepest compliance recertification burden.
Telematics-enabled consumption tracking is unbundling after-sales service contracts from lubricant supply agreements. Fleet operators in India's western corridor now procure grease through usage-based subscriptions rather than periodic bulk orders. This pattern is most visible among temperature-controlled logistics providers managing hub-and-spoke distribution networks.
Automotive Grease Market Segmentation
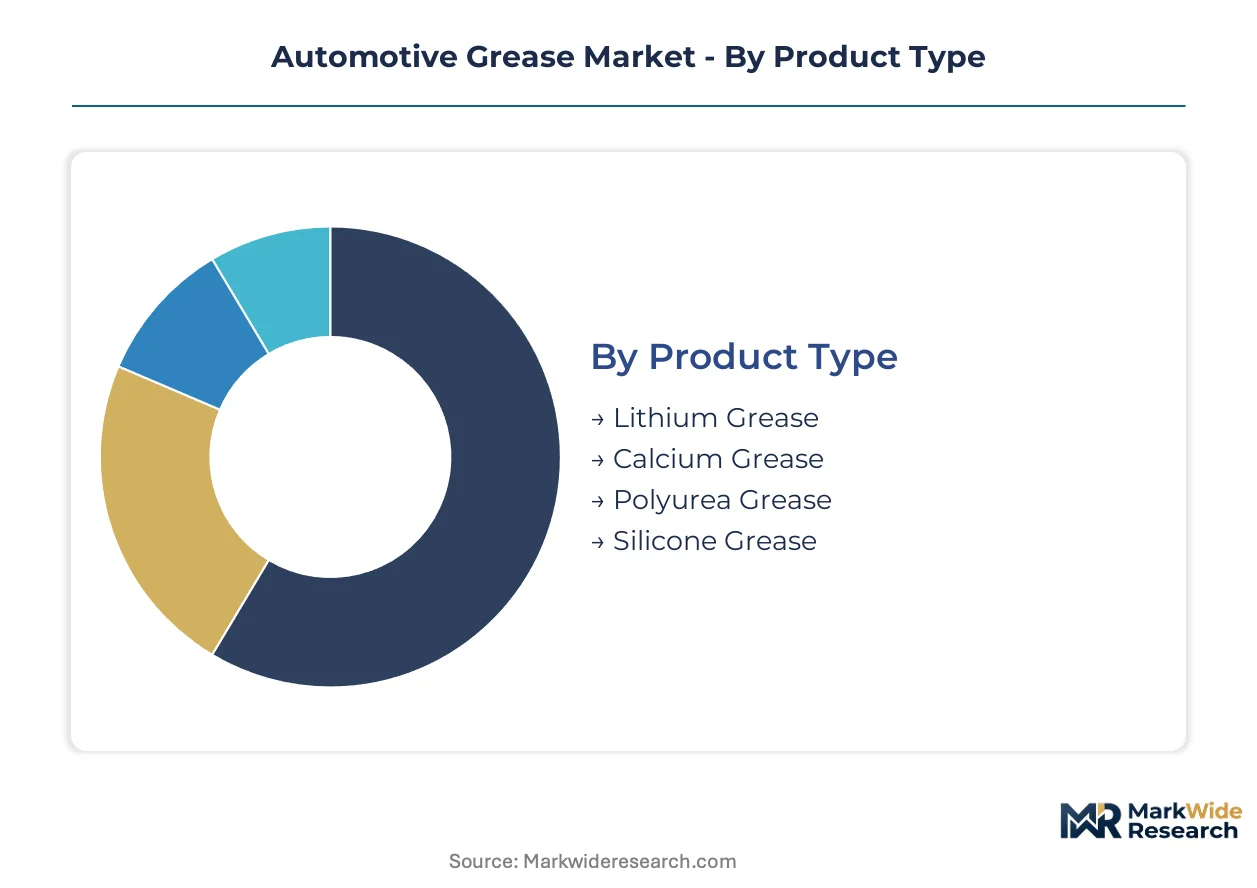
Automotive grease segmentation reflects divergent capital requirements across formulation chemistry, application engineering, and distribution infrastructure. Understanding these investment thresholds clarifies where integrated manufacturers hold structural advantages over specialized blenders.
Product Type:
Capital intensity peaks in synthetic thickener synthesis and additive compounding capabilities, with integrated producers capturing margin through backward control of lithium hydroxide and polyurea precursor supply.
- Lithium Grease:Formulated from lithium soap thickeners suspended in mineral or synthetic base oils, this category delivers multi-purpose performance across temperature ranges from -30°C to 150°C. Demand concentrates in India's commercial vehicle aftermarket and Germany's precision manufacturing corridor, where cost efficiency outweighs extended-life specifications. Most installed capacity flows through Lithium Grease. Expansion is steepest in Polyurea Grease.
- Polyurea Grease:Built on diurea thickener chemistry with exceptional oxidative stability and low noise characteristics, this segment commands premium positioning for sealed-for-life electric motor bearings and wheel hub units. Japanese and Korean OEMs specify these formulations for EV powertrain components requiring 10-year service intervals without relubrication.
- Calcium Grease:Water-resistant formulations with calcium sulfonate thickeners serve marine-adjacent automotive applications and chassis components exposed to washdown environments.
- Silicone Grease:Inert fluorosilicone or dimethyl silicone bases handle extreme temperature swings in electrical connector sealing and brake system lubrication.
Capacity utilization rates diverge sharply: lithium lines run continuously across regional blending networks, while polyurea batches require dedicated clean-room compounding infrastructure with 40% longer campaign changeovers.
Application:
Application-driven segmentation tracks divergent specification complexity, with electrical system formulations demanding entirely new testing protocols compared to legacy mechanical lubrication.
- Wheel Bearings:Hub unit assemblies specify NLGI Grade 2 greases with controlled oil separation and bearing noise ratings, with polyurea chemistry displacing lithium complex in premium platforms. German and Japanese OEMs mandate 300,000-kilometer life validation for sealed units.
- Electrical Systems:Battery thermal interface materials and e-axle bearings require dielectric strength above 15 kV/mm combined with thermal conductivity exceeding 0.8 W/mK, eliminating conventional mineral oil bases and demanding synthetic ester or PFPE formulations. Volume concentrates in China's EV manufacturing clusters around Shanghai and Shenzhen.
- Chassis:Steering linkages, suspension joints, and fifth wheels consume lithium-based greases through high-frequency relubrication intervals, with Indian fleet operators representing the most price-sensitive demand pool.
- Engine Components:Ancillary bearings and starter motor lubrication face gradual volume pressure as belt-driven accessories electrify, though commercial vehicle applications sustain baseline consumption.
Specification velocity varies: wheel bearing formulations stabilize over 5-year platform cycles, while electrical system requirements shift within 18-month product generations.
End User:
Customer type segmentation reveals procurement power concentration, with fleet operators consolidating volumes through telematics-integrated supply contracts that bypass traditional distributor networks.
- Fleet Operators:Temperature-controlled logistics providers and long-haul trucking networks in India's western corridor adopt usage-based grease subscriptions tied to telematics consumption tracking, compressing working capital requirements and shifting inventory risk upstream.
- Automotive OEMs:Powertrain and chassis engineering teams specify factory-fill greases through 5-7 year platform agreements with technical service support requirements, locking blenders into dedicated laboratory capacity and field engineering coverage.
- Aftermarket Providers:Distributors and parts retailers stock multi-purpose lithium greases across climate zones, with inventory turns fastest in high-temperature markets.
- Service Stations:Quick-lube and maintenance bays consume cartridges and mini-tubs for chassis lubrication services, with volume per outlet declining as sealed-for-life components proliferate.
Margin structure inverts across the value chain: OEM contracts sacrifice 15-20 points of gross margin for volume security and specification influence, while fleet direct channels recover distributor discounts through operational efficiency.
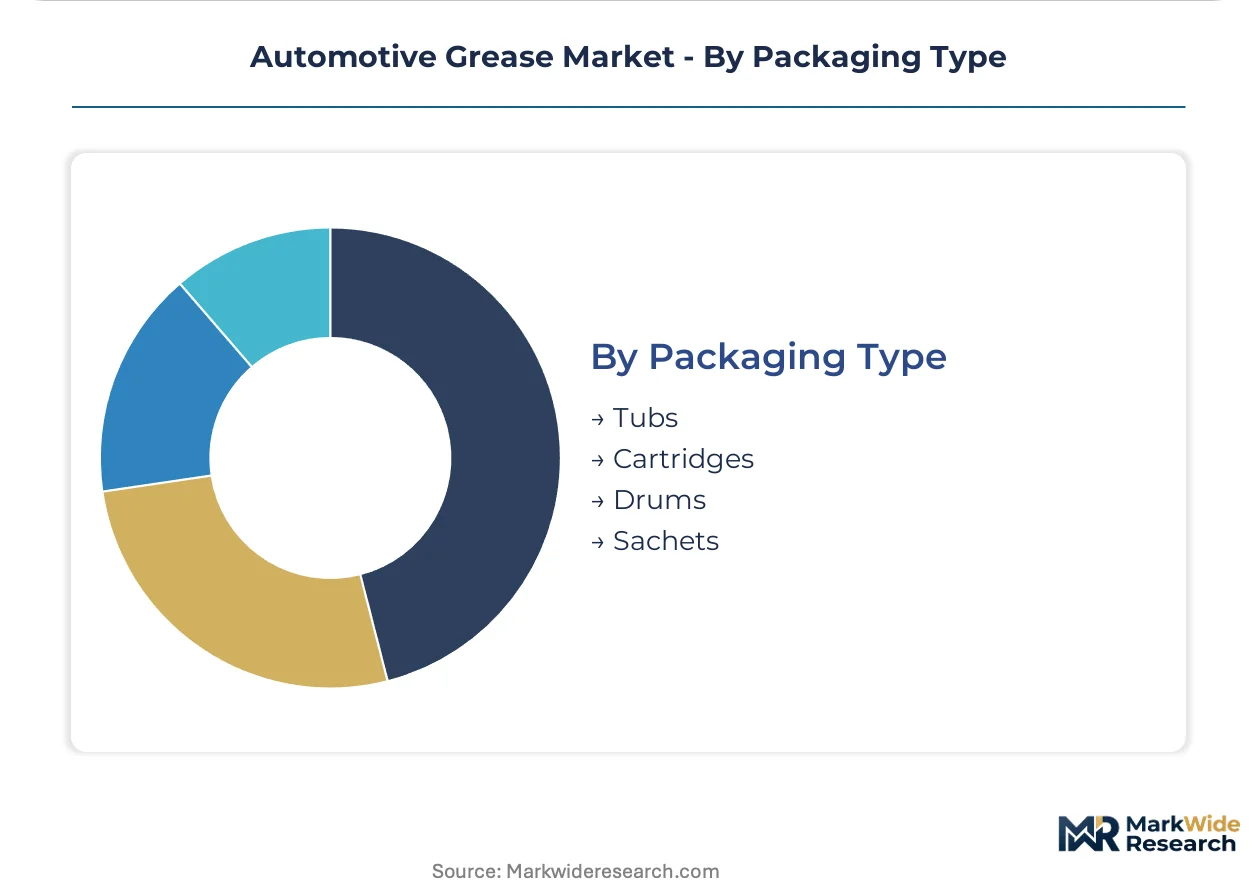
Packaging Type:
Packaging segmentation reflects logistics economics and application method constraints, with drum-to-cartridge conversion rates indicating automation penetration in assembly plants versus maintenance bays.
- Drums:180-kilogram steel containers supply high-volume OEM fill stations and centralized fleet maintenance depots, with returnable drum programs reducing per-kilogram packaging cost.
- Cartridges:400-gram grease gun tubes dominate aftermarket chassis service and wheel bearing repackaging, with single-use format eliminating contamination risk.
- Tubs:500-gram to 5-kilogram plastic containers serve small fleet workshops and agricultural equipment maintenance.
- Sachets:Single-application foil packets support field service operations and emergency repair kits.
Packaging mix shifts toward cartridges in markets with high labor costs and automated lubrication systems, while drum share holds in emerging markets with manual application methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing corridor anchors the most concentrated demand for high-specification automotive grease formulations, with industrial clusters in Stuttgart and Munich driving specification standards for sealed-for-life bearing applications across European supply chains.
Germany
EU REACH heavy-metal disclosure mandates reshape formulation requirements for suppliers serving BMW and Mercedes-Benz assembly networks. The country's Federal Environment Agency enforces strict additive chemistry documentation thresholds. Stuttgart's automotive engineering cluster demands polyurea greases validated for 300,000-kilometer wheel hub service intervals.
China
Shanghai and Shenzhen EV manufacturing clusters generate specialized demand for dielectric-compatible thermal interface materials. SAMR enforces GB/T 7324 oxidation stability protocols that disqualify import-dependent distributors. Domestic blenders with in-house testing laboratories capture specification-setting roles previously held by multinational technical service teams.
India
Mumbai and Delhi commercial fleet servicing networks sustain chassis grease consumption through preventive maintenance protocols. BIS certification requirements for automotive lubricants tighten import quality gates and favor domestic formulation capabilities. The western corridor's temperature-controlled logistics providers adopt telematics-integrated grease subscriptions.
United States
Gulf Coast integrated refiners control Group II/III base oil supply, creating procurement bottlenecks for independent blenders. EPA RCRA hazardous waste protocols govern base oil recycling and waste grease disposal. Detroit's automotive engineering centers specify factory-fill formulations through multi-year platform agreements.
Brazil
Mercosur fleet operators in São Paulo and Rio de Janeiro drive aftermarket chassis lubrication demand. ANVISA import pathways create tariff barriers on finished lubricants that favor localized blending investments. Domestic formulators serving commercial vehicle operators bypass distributor markups through direct procurement channels.
Automotive Grease Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated refiners extend blending infrastructure to capture EV-specific formulation demand. The vendor base organizes around three structural tiers: multinational oil majors with captive base oil supply, regional specialists with thickener chemistry expertise, and national champions serving protected domestic markets. Strategic archetypes include backward-integrated refiners controlling lithium hydroxide feedstock and additive houses with pre-certified clean-label packages. Geographic expansion and portfolio diversification toward dielectric-compatible formulations represent the dominant competitive moves.
Among integrated oil majors, Shell plc and ExxonMobil Corporation exemplify scale-driven positions anchored by global blending networks and OEM certification relationships. Fuchs Petrolub SE occupies a specialist tier focused on high-performance polyurea chemistry for precision bearing applications. Sinopec represents the national champion archetype with integrated base oil and additive manufacturing securing supply security across Asian automotive supply chains.
| Leading Market Players |
|---|
| Shell plc |
| ExxonMobil Corporation |
| Sinopec |
| Fuchs Petrolub SE |
| TotalEnergies SE |
| Chevron Corporation |
| BP plc |
| PetroChina |
| Lukoil |
| Others |
Supply Flow & Price Mechanics
Specialized tribochemistry expertise concentrated in Stuttgart's automotive engineering cluster and Singapore's lubricant R&D hubs generates labor-cost differentials that widen pricing-tier spreads between commodity lithium formulations and certified polyurea products. Formulators in lower-cost blending centers compete on standard chassis greases while German and Japanese technical centers command premiums for sealed-for-life electric motor bearing specifications.
Pricing Analysis
Input-cost pass-through from lithium hydroxide and Group II/III base oil volatility shapes contract structures across the market. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified polyurea grades from fleet-specified lithium complex and generic calcium formulations. Cost compression in economy-tier chassis products is intensifying because Indian aftermarket distributors consolidate volumes through telematics-integrated procurement. Fleet operators in Mumbai and Delhi represent the most price-sensitive segment, while German OEM engineering teams absorb premiums for 300,000-kilometer validated wheel hub specifications.
Supply Chain Analysis
Returnable drum programs and waste grease collection networks create reverse-logistics value recovery for base oil re-refiners serving US Gulf Coast and Rotterdam harbor clusters. Manufacturing concentrates in Germany, China, and the United States, with integrated refiners controlling captive Group II/III supply. Formulation draws from lithium hydroxide, polyurea precursor chemicals, and synthetic ester base stocks as primary inputs. Single-source vulnerability in lithium salt supply creates structural risk as battery sector competition strains multi-year contracts. Distribution runs through regional blending terminals serving OEM fill stations and fleet maintenance depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH heavy-metal disclosure mandates operate as a regulatory compounder, accelerating specification upgrades and clean-label additive investments across German and French automotive supply chains.
For Market Incumbents: Extend polyurea thickener capacity in Stuttgart and Shanghai to capture sealed-for-life electric motor bearing demand before qualification cycles close to new entrants. Deepen backward integration into lithium hydroxide feedstock to defend margin position against battery sector competition. Prioritize SAMR pre-certification for GB/T 7324 oxidation stability protocols to secure specification-setting roles in China's EV manufacturing clusters. For New Entrants and Emerging Players: The price-point gap between premium polyurea OEM specifications and economy lithium chassis products creates entry space for mid-tier synthetic ester formulations targeting Indian fleet operators. Brazil's ANVISA tariff barriers on finished lubricants present the most penetrable geography for localized blending investments serving Mercosur commercial vehicle networks. Deploy direct-to-fleet digital channels with telematics-integrated inventory replenishment to bypass entrenched distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic Chinese blenders with in-house GB standard testing laboratories and backward-integrated base oil supply. Long-term viability centers on dielectric-compatible formulation capabilities for e-axle thermal interface materials. Watch OEM grease-fill validation timeline compression as the inflection signal indicating qualification backlog clearance and portfolio monetization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Hydroxide | Captive thickener supply secures margin against battery sector demand competition. |
| GB Standard Pre-Certification Investment | SAMR-mandated testing creates first-mover advantage in China's domestic supply chains. |
| Polyurea Clean-Label Additive Development | REACH-compliant packages capture OEM certification advantages across German networks. |
| Telematics-Integrated Fleet Channels | Usage-based subscriptions bypass distributor markups in India's western corridor. |
| Dielectric Thermal Interface Formulation | Synthetic ester platforms address e-axle conductivity and heat dissipation requirements. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, fleet operations managers, and lubricant formulator R&D directors combined with secondary validation from customs trade data, SEC filings of integrated oil majors, vehicle production databases, and national lubricant standards documentation. Triangulation across stakeholder inputs and published supply chain disclosures ensures segment-level consistency.
Historical trendline analysis of grease consumption per vehicle class and commercial fleet density established baseline trajectories across the projection horizon. Segmentation modeling incorporated product type chemistry, application engineering requirements, end-user procurement behavior, and regional regulatory frameworks. CAGRs derived from volume elasticity to vehicle production forecasts and electrification penetration curves. Industry-specific inputs included OEM grease-fill specifications per powertrain architecture and fleet telematics adoption rates for inventory management.
Caveats apply where lithium hydroxide feedstock diversion to battery manufacturing, accelerated EV platform standardization, or regulatory timeline shifts could materially shift the outlook. Forecasts reflect modeling assumptions about qualification cycle durations and specification stability. Practitioners should monitor OEM e-axle thermal interface material validation progress and SAMR enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Air Lift Jack Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Automotive Suspension System Market
Automotive Parts
Insert Drive for Torque Wrench Market
Automotive Parts
Automotive Forging Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Global Automotive Damper Market
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
Russia Automotive Airfilters Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
Egypt Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
India Automotive Hydraulic Actuators Market