
 Argentina Automotive Engine Oils Market | 2026-2036
Argentina Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Automotive Engine Oils Market Outlook
Aftermarket service revenue is reshaping profit pools as workshops capture value beyond the initial product sale. YPF leverages its integrated fuel-station network to dominate last-mile distribution across Argentine provinces. ExxonMobil anchors premium synthetic positioning through technical service partnerships with fleet operators. Royal Dutch Shell Plc competes on formulation innovation tailored to South American driving conditions.
Automotive engine oils are lubricating fluids formulated from base oils and additive packages that reduce friction, dissipate heat, and prevent wear in internal combustion engines, typically specified by viscosity grades such as SAE 5W-30 or 15W-40 and performance levels like API SP or ACEA C3. Their primary purpose is to protect engine components under thermal stress and extend operational life between drain intervals. Synthetic formulations command expanding share as OEM fill specifications tighten, while conventional lubricants retain volume in older vehicle parc segments. Among end users, heavy-duty trucks generate the most intensive consumption per unit due to extended operating hours and severe-duty cycles.
Argentina's national industrial technology institute INTA sets lubricant quality benchmarks, while the Secretariat of Energy monitors fuel-economy claims tied to engine oil performance. Compliance with these frameworks determines product registration and market access for both domestic blenders and importers. Stakeholders must track how impending sulfur-content rules and used-oil recovery mandates alter formulation costs and reverse-logistics obligations.
Market Dynamics
Argentina's automotive engine oils sector is restructuring around the tightening nexus between INTA emissions standards and the operational demands of modernizing heavy-duty fleets. The commercial transport sector's upgrade cycle is compressing drain intervals and elevating specification requirements across Buenos Aires province and interior corridors.
Growth Catalysts
- INTA Emissions Compliance:Argentina's national industrial technology institute is mandating formulation upgrades that reduce sulfur content and improve thermal stability. Blenders are reformulating base stock portfolios to meet these benchmarks.
- Heavy-Duty Fleet Modernization:Commercial transport operators are retiring older trucks and specifying synthetic lubricants compatible with exhaust aftertreatment systems. This segment generates the highest per-unit consumption intensity.
- Buenos Aires Service Infrastructure:Vehicle density in the capital province concentrates demand and enables rapid technical service response. Workshop networks here capture aftermarket value beyond product sales.
Market Restraints
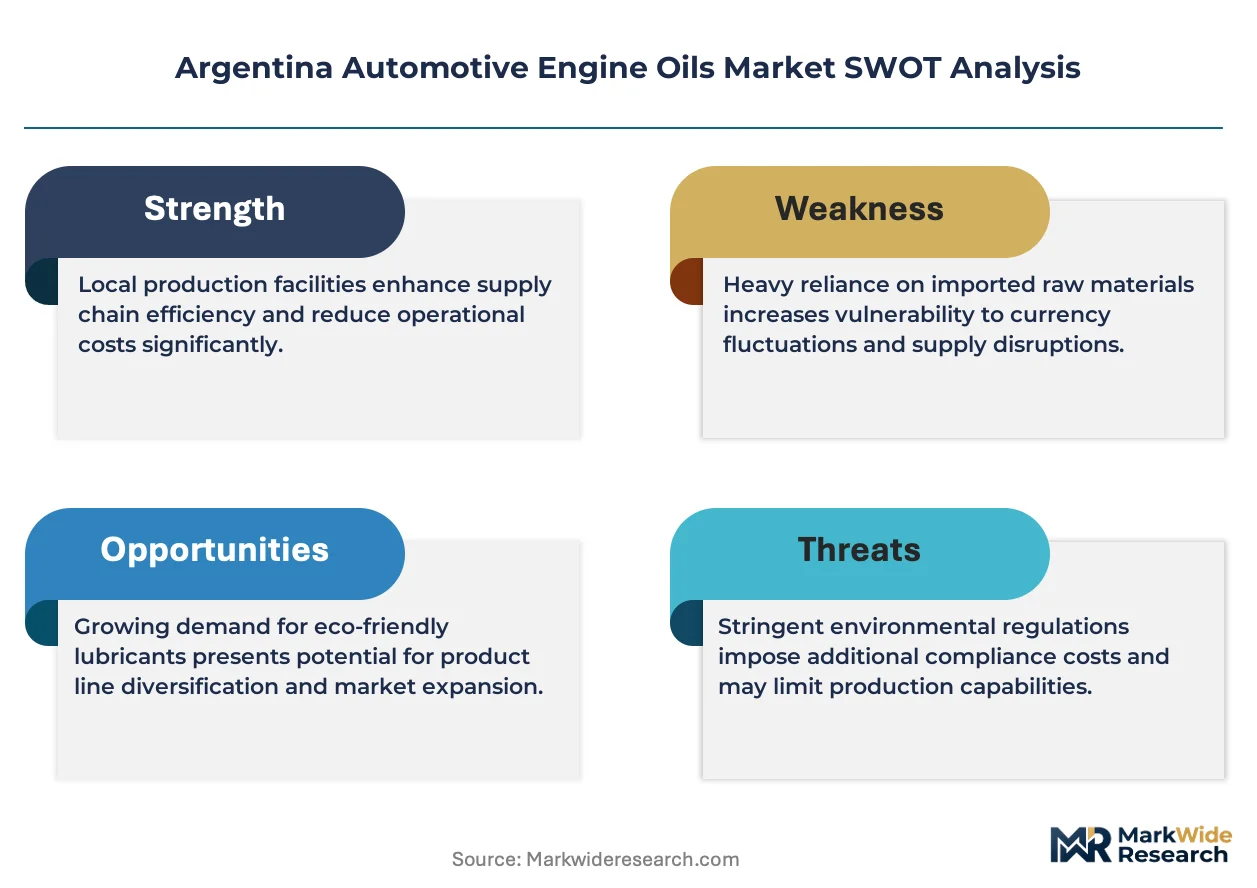
- Base Oil Import Dependency:Argentina lacks domestic Group II/III base oil production capacity. Formulators rely on seaborne supply from US Gulf Coast refiners, exposing margins to freight volatility and currency fluctuation.
- Used Oil Recovery Mandates:Pending regulations will impose reverse-logistics obligations on blenders and distributors. Collection infrastructure in Patagonian provinces remains underdeveloped, threatening compliance cost escalation.
- Conventional Lubricant Inertia:Older vehicle parc segments in interior provinces resist specification upgrades. Price-sensitive owner-operators extend drain intervals beyond OEM recommendations, compressing synthetic penetration rates.
Strategic Opportunities
- Córdoba Industrial Corridor:Manufacturing concentration in this central province creates captive fleet demand for bulk lubricant supply. Direct technical service partnerships with logistics operators bypass traditional distribution markups.
- Synthetic-Blend Tier Positioning:Mid-tier formulations bridge the gap between premium synthetics and mineral oils. This segment captures fleet managers seeking emissions compliance without full synthetic cost structures.
- Fuel-Station Network Integration:National oil companies with retail presence can embed lubricant sales into existing fleet card programs. Last-mile delivery density in Mendoza and Santa Fe provinces enables rapid replenishment cycles.
Industry Challenges
- Formulation Chemist Shortage:Argentina's technical education pipeline produces insufficient lubricant engineers. Blenders compete for talent with petrochemical and agrochemical sectors offering superior compensation packages.
- INTA Certification Timeline Compression:New product registration requires extended laboratory validation. Accelerated specification cycles strain R&D budgets and delay revenue recognition for reformulated grades.
- Legacy Workshop Equipment Compatibility:Interior province service bays lack bulk synthetic handling systems. Capital investment requirements for tankage and dispensing infrastructure slow premium product penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Automotive Engine Oils Market |
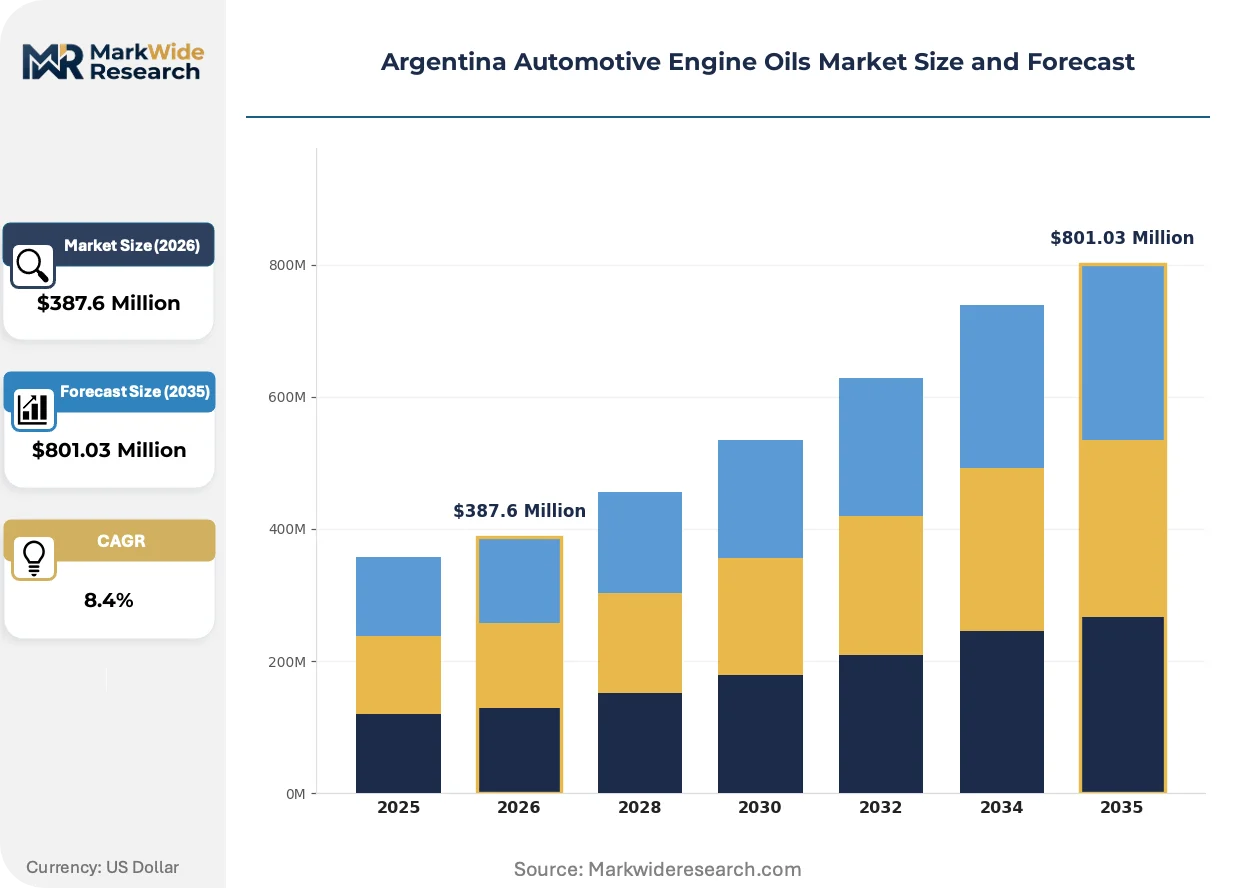
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Conventional, Semi-Synthetic, High Mileage End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Service Type: Oil Change, Oil Filter Replacement, Engine Flush, Regular Maintenance Distribution Channel: Online Retailers, Auto Parts Stores, Service Stations, Direct Sales |
| Companies Covered | Royal Dutch Shell Plc, Chevron Corporation, YPF, Gulf Oil International, Petrobras, BP Plc (Castrol), TotalEnergies, Petronas Lubricants International, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Automotive Engine Oils Market Strategic Shifts
Formulation science and distribution architecture are converging to redefine value capture in Argentina's lubricant sector. Three developments are compressing traditional competitive boundaries and elevating technical service as a differentiation lever.
Digital oil analysis platforms are virtualizing the traditional drain interval decision. Fleet operators in Buenos Aires province now transmit used oil samples to remote laboratories for wear metal and viscosity degradation assessment. This capability extends service intervals for low-stress applications while flagging premature degradation in severe-duty cycles. The technology is virtualizing the role of the service advisor, compressing face-to-face technical consultation into algorithmic recommendation engines.
INTA is tightening sulfur content thresholds for heavy-duty diesel engine oils under its evolving emissions framework. The regulation is forcing reformulation toward lower SAPS (sulfated ash, phosphorus, sulfur) additive packages that protect exhaust aftertreatment hardware. Heavy-duty fleet operators are responding by consolidating procurement around suppliers with verified INTA registration and documented field performance in Argentine operating conditions.
Workshop networks in Córdoba and Rosario are unbundling lubricant sales from mechanical service billing. Fleet managers now negotiate fluid supply contracts separately from maintenance labor, enabling direct price comparison across blender brands. This transparency is compressing distributor margins and rewarding suppliers with technical service capabilities that justify premium positioning through documented fuel economy or component life extension claims.
Argentina Automotive Engine Oils Market Segmentation
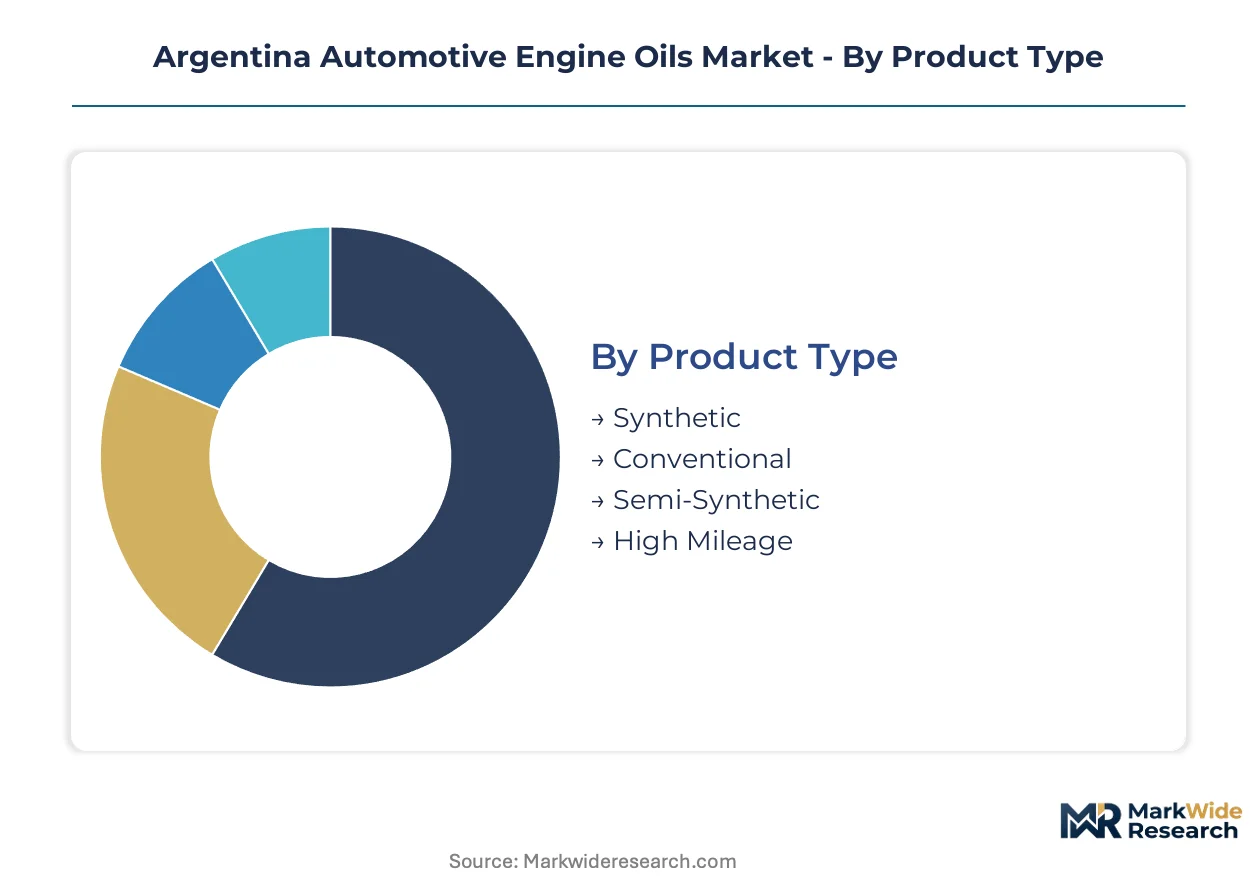
Segmentation in Argentina's automotive engine oils market reveals how formulation chemistry, vehicle duty cycles, and service infrastructure interact to create distinct profit pools. Understanding these divides exposes where specification upgrades concentrate and where conventional lubricants retain volume.
Product Type:
Cost tier stratification determines margin structure and procurement behavior across fleet and retail channels.
- Synthetic:Formulated from Group III/IV base stocks with engineered additive packages delivering extended drain intervals and thermal stability under severe duty. Demand concentrates among Buenos Aires fleet operators modernizing trucks for INTA emissions compliance, where exhaust aftertreatment protection justifies premium positioning.
- Conventional:Refined mineral base oils with standard additive treatments meeting API SN/SP minimums for everyday passenger vehicle protection. Older vehicle parc segments in interior provinces resist specification upgrades, extending drain intervals beyond OEM recommendations and compressing synthetic penetration rates.
- Semi-Synthetic:Blended formulations combining mineral and synthetic base stocks to balance performance uplift against cost sensitivity.
- High Mileage:Viscosity-enhanced grades with seal conditioners targeting vehicles exceeding 120,000 kilometers.
Synthetic lubricants command the established base in revenue terms. The steepest expansion runs through semi-synthetic formulations bridging premium and economy tiers.
End User:
Application intensity varies dramatically by operating hours, load severity, and emissions hardware sensitivity.
- Heavy-Duty Trucks:Diesel engines operating 16-20 hours daily under full load generate the highest per-unit consumption intensity. Fleet procurement in Córdoba and Rosario corridors specifies low-SAPS formulations protecting SCR and DPF systems mandated under tightening INTA standards.
- Commercial Vehicles:Light trucks and vans with moderate duty cycles require 10W-40 or 15W-40 grades balancing urban stop-start wear against highway fuel economy. Workshop networks in Mendoza province capture aftermarket value through bundled fluid and labor contracts.
- Passenger Vehicles:Private automobiles with intermittent use patterns favor 5W-30 and 0W-20 grades specified by OEM fill recommendations.
- Motorcycles:Small-displacement engines with shared sump designs demand JASO MA2-certified formulations preventing clutch slippage.
Heavy-duty trucks command the established base in volume consumption. The steepest expansion runs through commercial vehicles as logistics fleets expand across Santa Fe and Entre Ríos provinces.
Service Type:
Customer type divides between transactional oil changes and comprehensive maintenance relationships.
- Oil Change:Standalone fluid replacement services with 30-45 minute turnaround dominate quick-lube bays and fuel-station workshops. Buenos Aires density enables rapid replenishment cycles through YPF's integrated retail network.
- Regular Maintenance:Scheduled service packages bundling lubricant, filters, inspections, and component replacement. Fleet managers in Córdoba industrial corridor negotiate multi-year technical service partnerships capturing lifecycle value.
- Oil Filter Replacement:Concurrent filter swap services preventing contamination of fresh charge.
- Engine Flush:Chemical cleaning procedures removing sludge deposits prior to specification upgrades.
Standalone oil changes command the established base in transaction volume. The steepest expansion runs through bundled regular maintenance as fleet procurement consolidates around lifecycle cost management.
Distribution Channel:
Supply concentration shapes last-mile economics and technical service attachment rates.
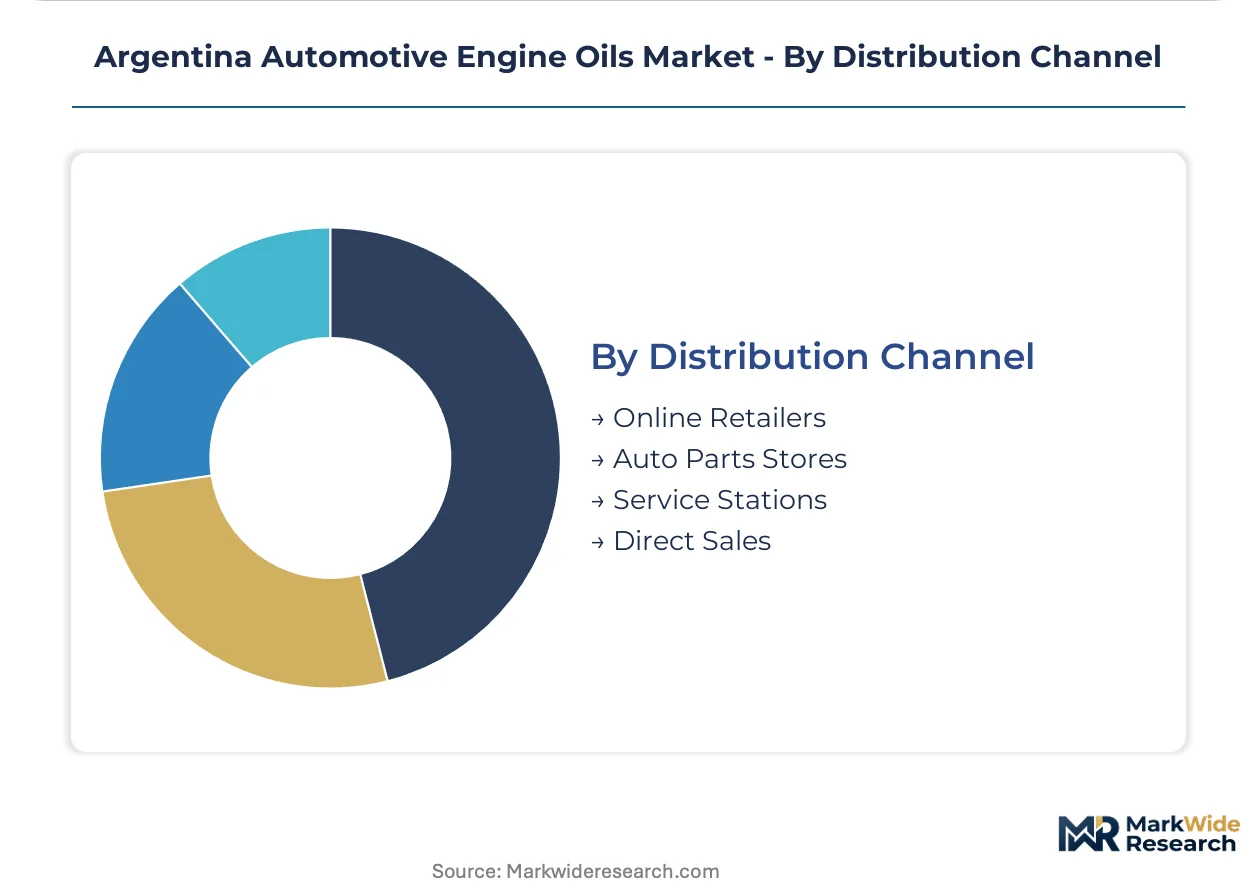
- Service Stations:YPF's 1,600+ retail sites dominate lubricant availability across Argentine provinces, embedding oil sales into fleet card programs and enabling emergency replenishment on major transport corridors.
- Auto Parts Stores:Independent and chain retailers serving DIY enthusiasts and small workshops in secondary cities. Patagonian provinces rely on this channel where integrated fuel networks have sparse coverage.
- Direct Sales:Blender-to-fleet contracts bypassing distributor markups through bulk tankage installations at logistics hubs.
- Online Retailers:E-commerce platforms with 48-72 hour delivery windows capturing price-sensitive consumers in Buenos Aires metropolitan area.
Service stations command the established base in geographic reach. The steepest expansion runs through direct sales as heavy-duty fleets consolidate procurement around technical service partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Argentine provinces diverge sharply between Buenos Aires province's intensive fleet operations and interior regions where older vehicle parcs sustain conventional lubricant demand. This geographic split shapes formulation requirements, distribution economics, and regulatory compliance burdens.
Buenos Aires Province
Heavy-duty fleet operators in this province generate the highest per-unit lubricant consumption intensity through 16-20 hour daily duty cycles. INTA emissions compliance mandates are accelerating specification upgrades toward low-SAPS formulations protecting SCR and DPF systems. The Greater Buenos Aires corridor concentrates technical service infrastructure and rapid replenishment networks.
Córdoba Province
Manufacturing logistics fleets in this central province create captive demand for bulk synthetic supply contracts. The Secretariat of Energy monitors fuel-economy claims tied to engine oil performance in this industrial corridor. Direct blender-to-fleet partnerships in Córdoba city bypass traditional distribution markups through on-site tankage installations.
Santa Fe Province
Rosario's workshop networks are unbundling lubricant sales from mechanical service billing, enabling direct price comparison across blender brands. INTA certification timelines compress product registration cycles for reformulated grades entering this market. Fleet procurement consolidation here rewards suppliers with documented fuel economy validation capabilities.
Mendoza Province
Wine industry logistics and cross-border trucking sustain commercial vehicle lubricant demand in this western province. Fuel-station network integration enables rapid replenishment cycles through fleet card programs. Service infrastructure gaps in outlying valleys slow premium synthetic penetration compared to coastal provinces.
Patagonian Provinces
Sparse population density and underdeveloped used-oil recovery infrastructure threaten compliance cost escalation for blenders serving this southern region. Auto parts stores dominate distribution where integrated fuel networks have limited coverage. Extended drain interval practices among price-sensitive owner-operators compress synthetic adoption rates.
Argentina Automotive Engine Oils Market Competitive Environment
Capability concentration sits with international formulators possessing INTA-registered laboratories and field validation protocols; scale advantage sits with national oil companies leveraging retail fuel networks for last-mile distribution. The market structures around three tiers: global majors with synthetic portfolios, regional Latin American blenders, and domestic distributors serving interior provinces. Consolidation pressure runs through technical service partnerships and direct fleet procurement contracts.
Among global integrated majors, Royal Dutch Shell Plc and ExxonMobil Corporation exemplify formulation-led positioning through severe-duty validation programs. YPF anchors domestic scale advantages through its 1,600-plus retail site network embedding lubricant sales into fleet card infrastructure. These three entities represent distinct competitive archetypes: international technical service depth, integrated fuel-lubricant distribution density, and hybrid national champion positioning.
| Leading Market Players |
|---|
| Royal Dutch Shell Plc |
| Chevron Corporation |
| YPF |
| Gulf Oil International |
| Petrobras |
| BP Plc (Castrol) |
| TotalEnergies |
| Petronas Lubricants International |
| ExxonMobil Corporation |
| Others |
Value Chain & Pricing Dynamics
Freight volatility on seaborne Group II/III base oil shipments from the US Gulf Coast compresses margin structures across all pricing tiers while simultaneously forcing blenders toward longer-term supply contracts that lock in volume commitments. This dual pressure widens spreads between premium synthetic formulations and economy mineral grades as currency fluctuation risk gets priced into spot procurement.
Pricing Analysis
Contract structures favor multi-year offtake agreements between major blenders and fleet operators seeking INTA-compliant formulation stability, while spot transactions dominate the fragmented workshop segment. Price differentiation hinges on certification tier—INTA-registered products command measurable premiums over unregistered imports—and volume scale, with bulk tankage installations attracting double-digit discounts per liter. Pricing pressure stems from synthetic base stock cost escalation as Argentine peso depreciation amplifies import exposure. Owner-operators in interior provinces exhibit highest price sensitivity, extending drain intervals to defer purchases, whereas Buenos Aires fleet managers prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Extended payment terms from blenders to distributors—stretching to 90 days in some interior provinces—reflect working capital strain as import costs rise. Geographic supply concentration centers on the US Gulf Coast for Group II/III base stocks, with additive packages sourced from Singapore and European specialty chemical hubs. Raw material dependencies include polyalphaolefin base fluids, detergent-dispersant additive systems, and viscosity index improvers. Single-source vulnerability runs through the Houston-Argentine shipping lane, where port congestion or canal delays cascade through blender inventory cycles. Distribution runs through YPF's integrated fuel-station network for last-mile density, supplemented by direct bulk delivery to Córdoba and Rosario logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's automotive engine oils market functions as a regulatory-moat business where INTA certification timelines and laboratory validation requirements erect barriers that favor incumbents with established technical infrastructure. Network effects concentrate among blenders possessing field-performance documentation in Argentine operating conditions.
For Market Incumbents: Build switching-cost moats by embedding digital oil analysis platforms into fleet management systems, creating data dependencies that resist supplier churn. Deepen backward integration into additive blending capabilities to offset import cost volatility, particularly for low-SAPS formulations protecting exhaust aftertreatment hardware. Defend against regional Latin American blenders by accelerating INTA registration for reformulated grades before specification cycles compress further. For New Entrants and Emerging Players: Build out white-space positions in the Córdoba industrial corridor's direct technical service partnerships, where incumbent coverage remains thinner than Buenos Aires. Target Patagonian provinces' auto parts store channel as the most penetrable distribution gap, leveraging 48-72 hour delivery commitments to offset sparse fuel-station network density. Establish go-to-market credibility through documented fuel economy validation under Secretariat of Energy monitoring protocols. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors technical-service-anchored blenders over pure distribution plays. Long-term viability across the analysis window hinges on R&D capabilities that compress INTA certification timelines and field validation infrastructure. Acquisition targets should demonstrate established low-SAPS formulation portfolios and direct fleet relationships in the heavy-duty segment. The signal to watch is INTA's sulfur-content rule implementation pace, which would accelerate procurement consolidation around registered suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Blending | Captures margin currently lost to Singapore and European specialty chemical suppliers. |
| Digital Oil Analysis Platform Deployment | Virtualizes drain interval decisions and creates proprietary data assets locking in fleet relationships. |
| Direct Fleet Technical Service Partnerships | Bypasses distributor markups in Córdoba and Rosario corridors where procurement consolidates. |
| Low-SAPS Formulation R&D Acceleration | Anticipates INTA emissions tightening protecting SCR and DPF hardware in modernizing truck fleets. |
| Patagonian Collection Infrastructure Buildout | Preempts compliance cost escalation from pending used-oil recovery mandates in underdeveloped southern provinces. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with lubricant blenders, fleet procurement managers, and workshop network operators across Buenos Aires, Córdoba, and Santa Fe provinces; and secondary validation through INTA product registration databases, Secretariat of Energy fuel-economy claim filings, and Argentine customs records tracking base oil import volumes. Bottom-up triangulation across fleet consumption intensity metrics and top-down reconciliation against blender revenue disclosures anchored volume estimates.
Forecast inputs incorporated formulation chemistry evolution, vehicle parc age distribution, and INTA regulatory trajectory across the projection horizon. Segmentation dimensions modeled include product type tier, end-user duty cycle intensity, service relationship depth, and distribution channel concentration. CAGRs were derived from trend extrapolation of fleet modernization rates and specification upgrade elasticity, cross-referenced against peso-denominated pricing elasticity observed in prior regulatory transitions.
Stress conditions across base oil import cost volatility, INTA certification timeline compression, and used-oil recovery mandate implementation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fleet turnover rates and synthetic penetration elasticity. Macroeconomic deviation, regulatory acceleration, or technological substitution in electrification would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Philippines Passenger Vehicles Lubricants Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Automotive Air Compressor Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
Tow Bar Market
Automotive Parts
India Automotive Parts Magnesium Die Casting Market
Automotive Parts
Mobile Diesel Heaters Market
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Passenger Car Accessories Market