
 Latin America Electric Power Steering Market | 2026-2036
Latin America Electric Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Electric Power Steering Market Foresight
Project finance tied to automotive supplier parks is reconfiguring competitive entry in the Latin America Electric Power Steering Market. ZF Friedrichshafen AG leverages its manufacturing footprint near Mexican assembly corridors to serve cross-border OEM demand. Robert Bosch GmbH anchors regional R&D operations in São Paulo, sustaining technology transfer from European parent operations. JTEKT Corporation specializes in column-assist configurations for compact passenger vehicles that dominate Brazilian production lines.
Electric power steering replaces hydraulic pump-driven systems with brushless motor actuators mounted directly to the steering rack or column, eliminating parasitic engine load and improving fuel economy by four to six percent. The primary commercial purpose centers on enabling advanced driver assistance features through precise torque control and lane-keeping feedback. Rack-assist systems command the dominant share of OEM installations across Latin American assembly plants due to superior road-feel calibration for varied terrain. Column-assist configurations occupy the entry-level passenger car segment where cost sensitivity overrides performance demands. Integrated modules are gaining traction among premium SUVs assembled in Mexico for export markets.
Brazil's ANFAVEA safety protocols and Mexico's NOM-194 vehicle standards mandate electronic stability compatibility, effectively requiring EPS architecture in new platform designs. Argentina's national automotive regulator enforces progressive steering assistance requirements that align with Mercosur technical harmonization. Colombia's Ministry of Transport has adopted UN ECE steering safety regulations that favor electronically controlled systems over hydraulic alternatives. Stakeholders must monitor how Mercosur-EU trade negotiations reshape local content rules for steering system components.
Market Dynamics
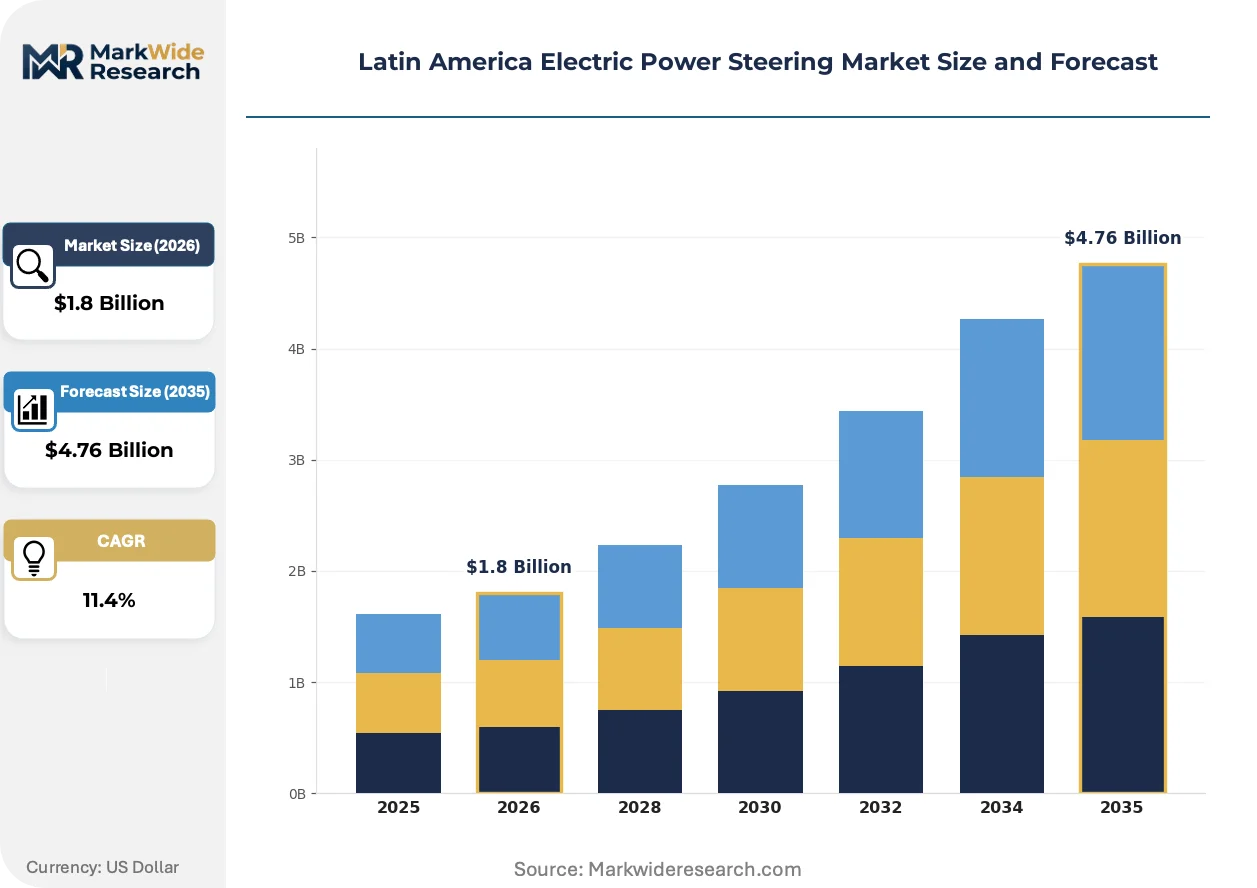
Light commercial vehicle fleets across Brazil are accelerating adoption of rack-assist electric power steering systems as OEMs pursue aggressive fuel efficiency targets under ANFAVEA protocols. This technology shift is compressing hydraulic system demand while reconfiguring supplier relationships around integrated module production.
Growth Catalysts
- ANFAVEA Safety Protocols:Brazil's automotive manufacturer association mandates electronic stability compatibility, effectively requiring EPS architecture in all new platform designs for passenger and commercial vehicles.
- Brushless Motor Actuators:These components eliminate parasitic engine load and deliver four to six percent fuel economy improvement, creating measurable operating cost reductions for fleet operators.
- US-Mexico Supply Chain Proximity:Mexican assembly corridors attract integrated EPS module investments to serve cross-border OEM demand with reduced logistics friction.
Market Restraints
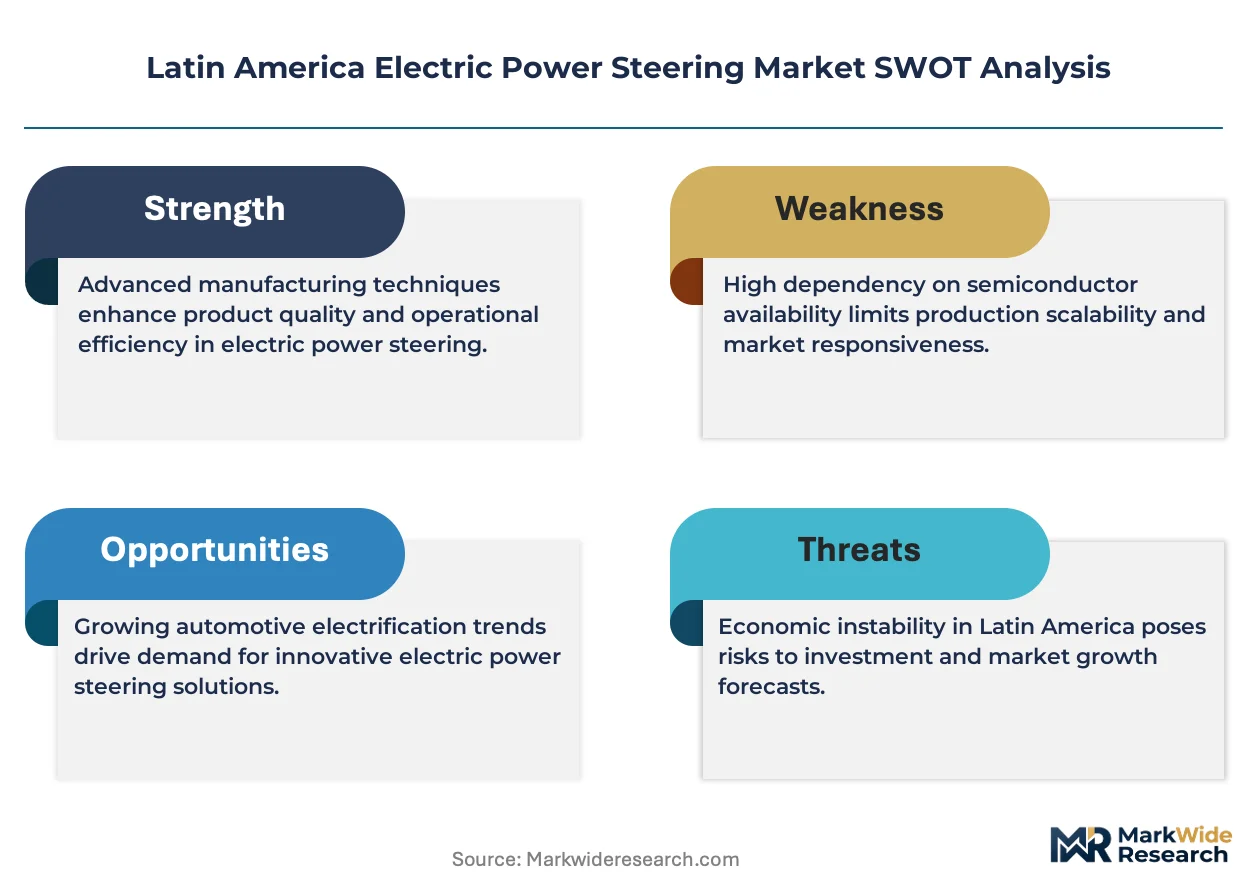
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings in Chinese processing centers create input cost instability for brushless motor production.
- Steering System Supplier Concentration:Tier 1 module assembly concentrates among three European-Japanese conglomerates, limiting pricing leverage for Latin American OEMs.
- Legacy Hydraulic Infrastructure:Existing service networks and technician training investments in hydraulic systems create switching friction for aftermarket conversion.
Strategic Opportunities
- Argentina's Progressive Mandates:The national automotive regulator enforces escalating steering assistance requirements that align with Mercosur technical harmonization, opening new vehicle categories.
- ADAS Convergence:Integration of lane-keeping assistance with torque-controlled steering creates premium pricing potential for SUVs assembled in Mexican export corridors.
- Column-Assist Segment White Space:Entry-level passenger vehicles in Brazil remain underpenetrated by electronic systems relative to rack-assist configurations.
Industry Challenges
- Embedded Software Certification:Functional safety validation under ISO 26262 extends development timelines by eight to fourteen months for new platform launches.
- Cross-Border Talent Mobility:Electromechanical calibration engineers with road-feel tuning expertise concentrate in São Paulo and Mexico City, creating recruitment bottlenecks for secondary facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Electric Power Steering Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Assist, Rack Assist, Pump Assist, Integrated End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Electric, Hybrid, Hydraulic, Electro-Hydraulic Vehicle Type: Passenger Cars, Commercial Vehicles, SUVs, Trucks |
| Companies Covered | Robert Bosch GmbH, ZF Friedrichshafen AG, JTEKT Corporation, Nexteer Automotive, NSK Ltd., Nidec Corporation, Mitsuba Corporation, Hitachi Astemo, LG Innotek, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Electric Power Steering Market Shifts & Advancements
Steering system architectures are converging with autonomous drive platforms, forcing suppliers to redesign torque control algorithms for machine-directed inputs rather than human feedback loops. This shift is compressing development cycles and elevating software competency above mechanical engineering heritage.
Rack-assist EPS configurations are migrating from premium vehicle applications into mid-size pickup trucks and light commercial vans across Brazilian assembly plants. Volkswagen and Fiat Chrysler production lines in São Bernardo do Campo now specify these systems for one-ton payload categories previously served by hydraulic pumps. The technology is migrating from performance-oriented segments into cost-sensitive fleet procurement, forcing suppliers to compress module pricing while maintaining durability standards for varied terrain.
Colombia's Ministry of Transport has adopted UN ECE steering safety regulations that favor electronically controlled systems over hydraulic alternatives. This regulatory alignment with European technical standards accelerates platform commonality for multinational OEMs operating across Andean markets. Light commercial vehicle assemblers in Bogotá industrial corridors must now certify EPS compatibility to access domestic fleet sales channels.
Fleet procurement managers are consolidating supplier relationships around full-lifecycle service agreements rather than component-only transactions. Brazilian rental and logistics operators now demand predictive maintenance telemetry embedded within steering control modules. This behavioral shift is most visible in São Paulo state, where telematics-integrated EPS contracts have displaced conventional warranty-plus-spares purchasing for vehicles above three-ton gross weight.
Latin America Electric Power Steering Market Segmentation
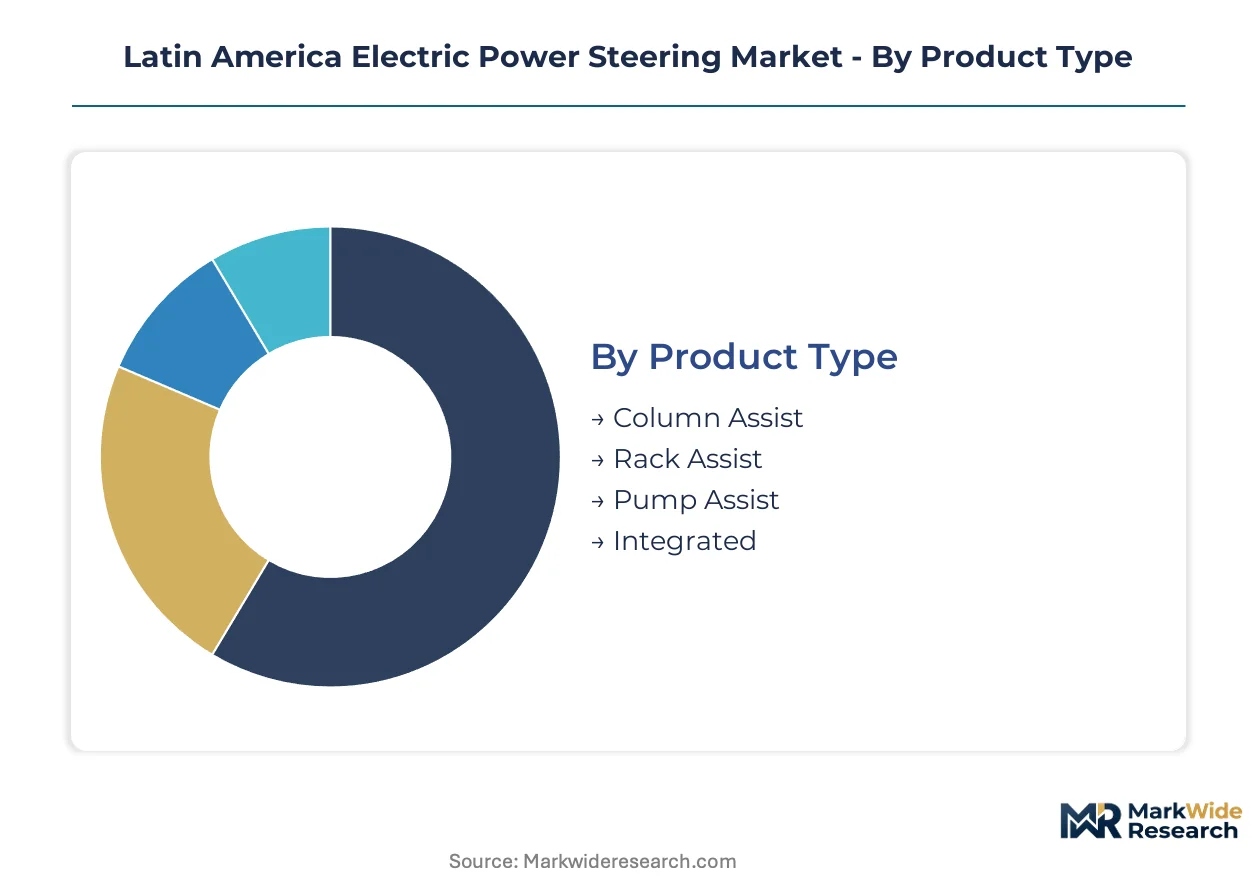
Electric power steering architectures diverge sharply in replacement cycles and margin profiles across Latin American assembly corridors. Procurement patterns for rack-assist systems in Brazilian commercial fleets compress refresh timelines versus column-assist configurations serving entry-level passenger segments.
Product Type:
Cycle times vary from eighteen months for integrated modules to seven years for hydraulic conversion kits, creating distinct inventory and service strategies for each configuration.
- Rack Assist:Brushless motor actuators mount directly to the steering rack, delivering precise torque control for lane-keeping assistance. Brazilian light commercial vehicle fleets specify these systems under ANFAVEA fuel efficiency mandates, displacing hydraulic pumps in one-ton payload categories.
- Column Assist:Compact motor units integrate above the steering column, reducing per-unit cost by eliminating rack-mounted hardware. Entry-level passenger vehicles produced in São Bernardo do Campo favor this configuration where cost sensitivity overrides performance demands.
- Pump Assist:Electromechanical pumps replace engine-driven hydraulic units in legacy platform retrofits.
- Integrated:Full module assemblies combine motor, controller, and sensor arrays for premium SUV exports from Mexican assembly corridors.
Rack-assist configurations anchor the volume base while integrated modules gain share at the steepest rate.
End User:
Margin structures compress from OEM direct procurement to fragmented aftermarket channels, with Tier-1 suppliers capturing intermediate value through module assembly.
- OEMs:Volkswagen and Fiat Chrysler specify EPS architectures at platform design stage, locking in multi-year supply agreements with integrated module producers. Mexican assembly corridors serving US export demand concentrate procurement among three European-Japanese conglomerates.
- Tier-1 Suppliers:Module integrators source brushless motors, torque sensors, and control electronics from specialized component manufacturers. São Paulo-based operations sustain technology transfer from European parent companies while serving regional OEM demand.
- Aftermarket Providers:Hydraulic-to-electric conversion kits target legacy fleet vehicles outside warranty coverage.
- Vehicle Assemblers:Contract manufacturers in Colombian industrial corridors require EPS certification under UN ECE steering safety regulations.
OEM direct procurement anchors the volume base while aftermarket providers expand most quickly in secondary Brazilian states.
Technology:
Development timelines stretch longest for fully electric architectures requiring ISO 26262 functional safety validation, while electro-hydraulic hybrids offer faster certification paths.
- Electric:Brushless DC motors eliminate parasitic engine load entirely, delivering four to six percent fuel economy improvement. Argentine regulatory mandates under Mercosur harmonization accelerate platform adoption for new vehicle categories.
- Electro-Hydraulic:Combined architectures retain hydraulic backup for fail-safe operation in heavy commercial applications. Colombian Ministry of Transport regulations permit transitional certification for systems meeting UN ECE standards.
- Hybrid:Dual-mode systems switch between electric assist and hydraulic backup based on vehicle speed.
- Hydraulic:Legacy pump-driven systems persist in aftermarket service networks despite OEM phase-out.
Electric architectures anchor the volume base while electro-hydraulic systems climb the fastest in heavy commercial segments.
Vehicle Type:
Specification intensity scales from basic column-assist in compact passenger cars to redundant rack-assist in premium SUVs, with commercial vehicles occupying a mid-tier complexity band.
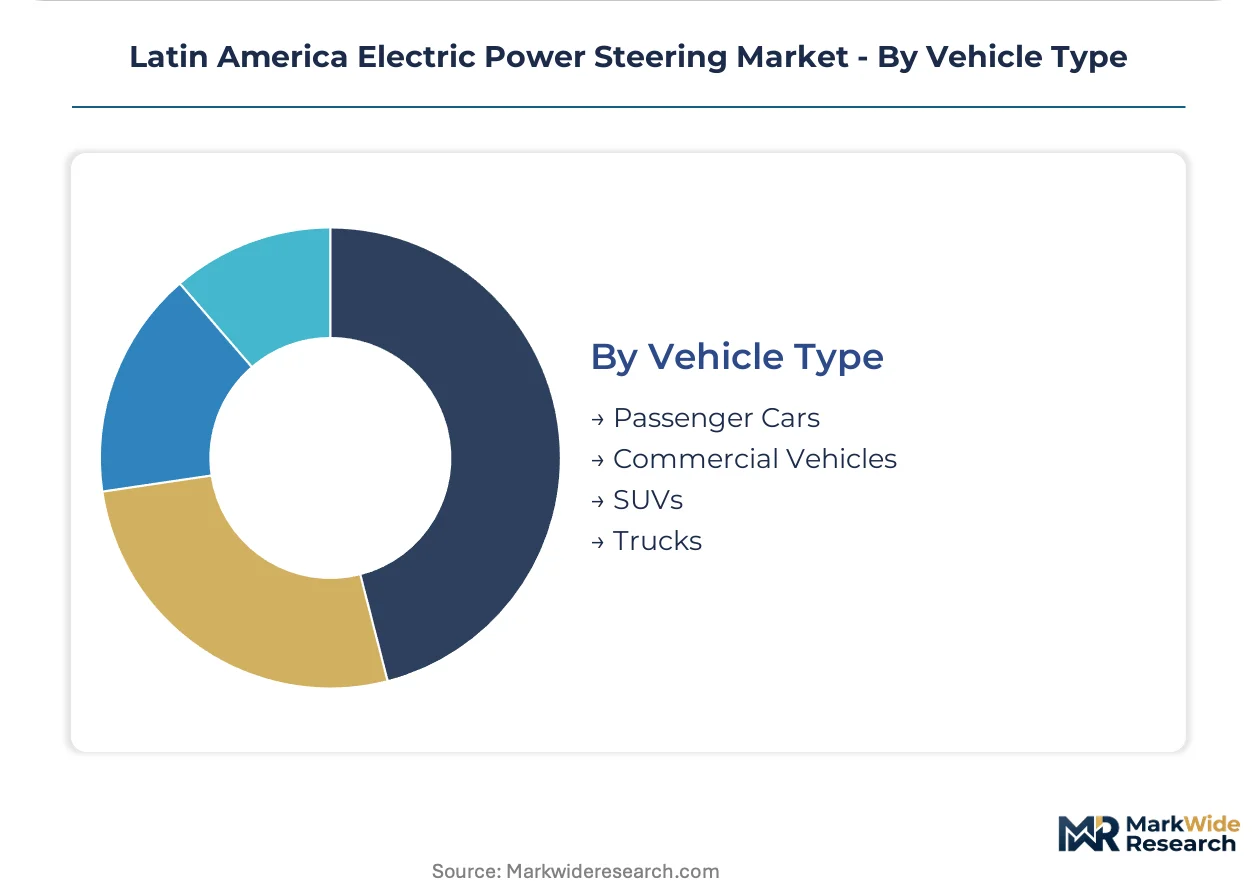
- Commercial Vehicles:Light vans and pickup trucks across Brazilian assembly plants specify rack-assist systems for payload ratings previously served by hydraulic pumps. ANFAVEA protocols mandate electronic stability compatibility, effectively requiring EPS architecture in new platform designs.
- SUVs:Premium exports from Mexican corridors integrate full ADAS-capable steering modules with predictive maintenance telemetry. Fleet procurement managers in São Paulo state demand telematics-integrated contracts for vehicles above three-ton gross weight.
- Passenger Cars:Entry-level Brazilian production favors cost-optimized column-assist configurations.
- Trucks:Heavy-duty categories retain electro-hydraulic architectures for steering load capacity.
Commercial vehicles anchor the volume base while SUVs gain share at the steepest rate in Mexican export corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing leverage through ANFAVEA-mandated platform conversions, while Argentine procurement absorbs cost premiums from import dependency and currency volatility.
Brazil
Light commercial vehicle fleets in São Bernardo do Campo drive rack-assist adoption for one-ton payload categories. ANFAVEA protocols mandate electronic stability compatibility in all new platform designs. Volkswagen and Fiat Chrysler production corridors specify EPS architectures previously served by hydraulic pumps.
Mexico
Cross-border OEM demand attracts integrated module investments to serve US export markets. NOM-194 vehicle standards enforce electronic stability requirements for domestic and export-bound platforms. Assembly corridors near Tijuana and Puebla concentrate procurement among European-Japanese conglomerates.
Argentina
The national automotive regulator enforces progressive steering assistance requirements for new vehicle categories. Mercosur technical harmonization aligns local mandates with Brazilian safety protocols. Córdoba industrial clusters face input cost pressure from rare earth magnet import dependencies.
Colombia
Bogotá-based assemblers adopt UN ECE steering safety regulations favoring electronically controlled systems. The Ministry of Transport mandates EPS certification for fleet sales channel access. Light commercial vehicle production in Andean industrial corridors accelerates platform commonality with European standards.
Chile
Mining fleet operators in Antofagasta and Santiago metropolitan areas specify telematics-integrated steering modules for heavy-duty applications. National transport safety codes progressively restrict hydraulic system certifications for commercial vehicles. Northern copper belt logistics corridors drive demand for predictive maintenance telemetry.
Latin America Electric Power Steering Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying brushless motors, torque sensors, and control electronics. The supplier base concentrates among three European-Japanese conglomerates with manufacturing footprints near Mexican assembly corridors and São Paulo R&D operations. Two strategic archetypes dominate: integrated module assemblers serving OEM direct procurement, and electromechanical component fabricators feeding Tier-1 supply chains. Competitive moves center on cross-border capacity alignment with OEM platform launches and embedded software competency acquisition for ADAS convergence.
Among the conglomerate-tier suppliers, ZF Friedrichshafen AG and Robert Bosch GmbH anchor European-origin platform integration, while JTEKT Corporation represents Japanese specialization in column-assist configurations. These three occupy positions spanning rack-assist dominance in Brazilian commercial fleets, integrated module production for Mexican export corridors, and cost-optimized architectures for entry-level passenger segments. Their collective footprint shapes procurement patterns across Mercosur and USMCA trade zones.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| JTEKT Corporation |
| Nexteer Automotive |
| NSK Ltd. |
| Nidec Corporation |
| Mitsuba Corporation |
| Hitachi Astemo |
| LG Innotek |
| Others |
Supply & Pricing Matrix
Monterrey-Querétaro freight corridors transmit rare earth magnet cost volatility directly into Brazilian assembly plant procurement, compressing margins for rack-assist module suppliers while amplifying price differentiation between integrated OEM contracts and fragmented aftermarket channels. This logistics-cost dynamic concentrates pricing power among three European-Japanese conglomerates that anchor cross-border supply networks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across Latin American assembly corridors. Price differentiation stratifies across volume scale and ADAS certification tier, with premium SUV exports from Mexican corridors commanding substantial premiums over entry-level column-assist configurations. Cost compression in the aftermarket tier is intensifying because hydraulic conversion kit providers compete on replacement cycle speed rather than technology content. Fleet procurement managers demonstrate highest price sensitivity, while premium SUV assemblers prioritize ADAS integration over per-unit cost.
Supply Chain Analysis
Extended payment terms from São Paulo-based R&D operations to Chinese rare earth processors stabilize working capital for brushless motor assembly. Supply concentrates in China for neodymium magnets, Japan for torque sensor fabrication, and Mexico for integrated module final assembly. Brushless DC motors, control electronics, and rack-mounted actuator hardware constitute critical input dependencies. Single-source vulnerability in Chinese rare earth processing creates structural exposure to export restriction risk. Distribution runs through Tier-1 module integrators serving OEM direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America Electric Power Steering Market represents an early-cycle expansion story as ANFAVEA-mandated platform conversions accelerate hydraulic displacement across Brazilian commercial fleets. Regulatory tailwinds in Argentina and Colombia extend this penetration runway through Mercosur and UN ECE alignment.
For Market Incumbents: Pre-empt margin erosion in rack-assist configurations by securing captive supply of rare earth magnets through backward integration into Chinese processing partnerships. Lock in multi-year platform engineering contracts with Volkswagen and Fiat Chrysler before electro-hydraulic hybrid architectures gain traction in heavy commercial segments. Defensive patent positioning around torque control algorithms for lane-keeping assistance blocks emerging software entrants. For New Entrants and Emerging Players: Pursue white-space opportunity in telematics-integrated steering modules for Brazilian rental and logistics operators above three-ton gross weight. Target column-assist configurations for entry-level passenger vehicles in São Bernardo de Campo where cost sensitivity overrides performance demands. Establish go-to-market presence through full-lifecycle service agreements rather than component-only transactions. For Investors and Strategic Acquirers: Electromechanical calibration specialists with road-feel tuning expertise represent the priority acquisition archetype as machine-directed steering algorithms displace human feedback loops. Long-term viability hinges on software competency acquisition outpacing mechanical engineering heritage. Watch for ADAS convergence inflection as lane-keeping assistance integration rates cross threshold penetration in Mexican export corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen and Fiat Chrysler lock in multi-year EPS supply agreements through shared architectures. |
| Battery Supply Agreement | Brushless motor producers secure rare earth magnet offtake from Chinese processing centers. |
| Software-Defined Vehicle Investment | Torque control algorithm development for machine-directed inputs compresses development cycles. |
| Geographic Manufacturing Footprint | ZF and Bosch anchor integrated module production near Tijuana-Puebla assembly corridors. |
| Charging Infrastructure Partnership | Predictive maintenance telemetry integration meets São Paulo fleet operator procurement demands. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and fleet maintenance directors anchored the qualitative base. Primary interview findings triangulated against vehicle production databases, IHS Markit registration data, ANFAVEA safety protocol filings, and SEC disclosures from automotive suppliers. Bottom-up segment sizing across product type, end user, technology, and vehicle type dimensions converged with top-down market validation.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing for rare earth price volatility and regulatory implementation timelines. Segmentation modeling captured rack-assist versus column-assist configurations, OEM versus aftermarket channels, electric versus electro-hydraulic architectures, and commercial vehicle versus passenger car applications. CAGRs derived from production volume trajectories and content-per-vehicle assumptions, with cross-validation against Mercosur trade flow data and USMCA automotive rules of origin.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Chinese export license policies, or Mercosur-EU local content negotiations would shift the trajectory. Forecasts assume documented regulatory implementation schedules and technology substitution curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Air Brake Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Automotive Hoses Market
Automotive Parts
Europe Ball Bearings Market
Automotive Parts
Wheel Arch Liner Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
Automotive Transmission Valve Spool Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market
Automotive Parts
High Level Brake Lamp Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Global Automotive Stampings Market