
 Automotive Steering Knuckle Market | 2026-2036
Automotive Steering Knuckle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Steering Knuckle Market Analysis
The capability gap between in-house forging capacity and outsourced machined-knuckle supply is collapsing as OEMs consolidate supplier bases. Thyssenkrupp AG leverages captive steel-forging assets to anchor long-term contracts with German premium automakers. Bosch Automotive Steering competes through integrated electromechanical steering systems that bundle knuckle-adjacent hardware. Dana Incorporated specializes in heavy-duty forged knuckles for North American commercial vehicle programs, sustaining pricing power in a volatile raw-material environment.
An automotive steering knuckle is the steering pivot component that connects the wheel hub to the suspension system, typically manufactured from forged or cast aluminum alloy with post-machining tolerances within 0.05 mm for kingpin bore alignment; its primary purpose is to transfer steering and braking loads while permitting controlled wheel articulation. Forged knuckles still dominate value capture in premium applications where fatigue resistance justifies higher unit costs, though cast aluminum variants are gaining share in mass-market electric vehicles where weight reduction directly extends range. Composite knuckles remain nascent but occupy strategic R&D budgets as OEMs pursue radical chassis mass targets. The end-user structure tilts toward Tier-1 Suppliers who consolidate knuckle procurement with adjacent control-arm and hub-bearing assemblies, compressing margin pools for standalone component specialists.
The EPA and NHTSA jointly enforce Corporate Average Fuel Economy standards that penalize vehicle weight, directly incentivizing aluminum and magnesium knuckle substitution across US light-truck platforms. The EU Green Deal and REACH chemical restrictions further constrain traditional steel-surface treatment processes, reshaping supplier qualification criteria for European OEM sourcing teams. Stakeholders must monitor how China's MIIT dual carbon goals redirect domestic foundry capacity toward electric vehicle chassis components, potentially rerouting export supply that Western Tier-1 suppliers have historically depended upon.
Market Dynamics
The transition from internal combustion to electric vehicle architectures is collapsing the traditional weight-bearing requirements that once favored forged steel knuckles, forcing a wholesale requalification of aluminum casting suppliers across OEM engineering departments.
Growth Catalysts
- EPA CAFE Standards:US fuel economy penalties on vehicle weight are accelerating aluminum knuckle adoption across light-truck platforms, particularly for full-size pickup programs where every kilogram saved translates to compliance credits.
- China MIIT Dual Carbon Goals:Domestic foundry capacity redirection toward electric vehicle chassis components is intensifying localized procurement of machined aluminum knuckles by BYD, NIO, and XPeng engineering teams.
- Suspension Module Integration:Tier-1 suppliers are bundling knuckles with control arms and hub bearings into pre-assembled corner modules, reducing OEM line-side complexity and expanding contract values for integrated system providers.
Market Restraints
- Primary Aluminum Price Volatility:London Metal Exchange aluminum price swings above fifteen percent annually are compressing margin buffers for cast knuckle specialists without long-term smelter contracts.
- European REACH Surface Treatment Restrictions:Hexavalent chromium bans and cadmium limitations are disqualifying traditional steel knuckle coating processes, forcing costly chemistry transitions for remaining forged product lines.
- Structural Fatigue Limitations:Cast aluminum microstructure porosity thresholds above 0.5 percent porosity by volume continue to exclude the material from heavy-duty commercial axle applications above 7.5 tonnes gross vehicle weight.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentive thresholds for advanced automotive parts are attracting aluminum knuckle machining investments to Tamil Nadu and Gujarat industrial corridors.
- Magnesium Alloy Substitution:AZ91D and AM60B magnesium grades are penetrating luxury electric sedan programs where radical chassis mass reduction targets justify the twenty-five percent cost premium over aluminum.
- Remanufacturing Channel Development:Independent aftermarket distributors are establishing certified knuckle refurbishment lines for collision repair, capturing margin pools that OEMs have historically ceded to scrap recyclers.
Industry Challenges
- CNC Machining Talent Scarcity:Kingpin bore finishing to 0.05 mm tolerance requires five-axis programming expertise that vocational pipelines in Germany, Japan, and the US are failing to replenish at replacement rates.
- Homologation Timeline Compression:EU Whole Vehicle Type Approval cycles for new suspension architectures have shortened from eighteen to twelve months, squeezing validation windows for knuckle design iterations.
- Legacy Steel-Forning Asset Stranding:Tier-1 suppliers with captive forge presses face write-down pressure as OEM technical specifications shift definitively toward cast aluminum for volume electric platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Steering Knuckle Market |
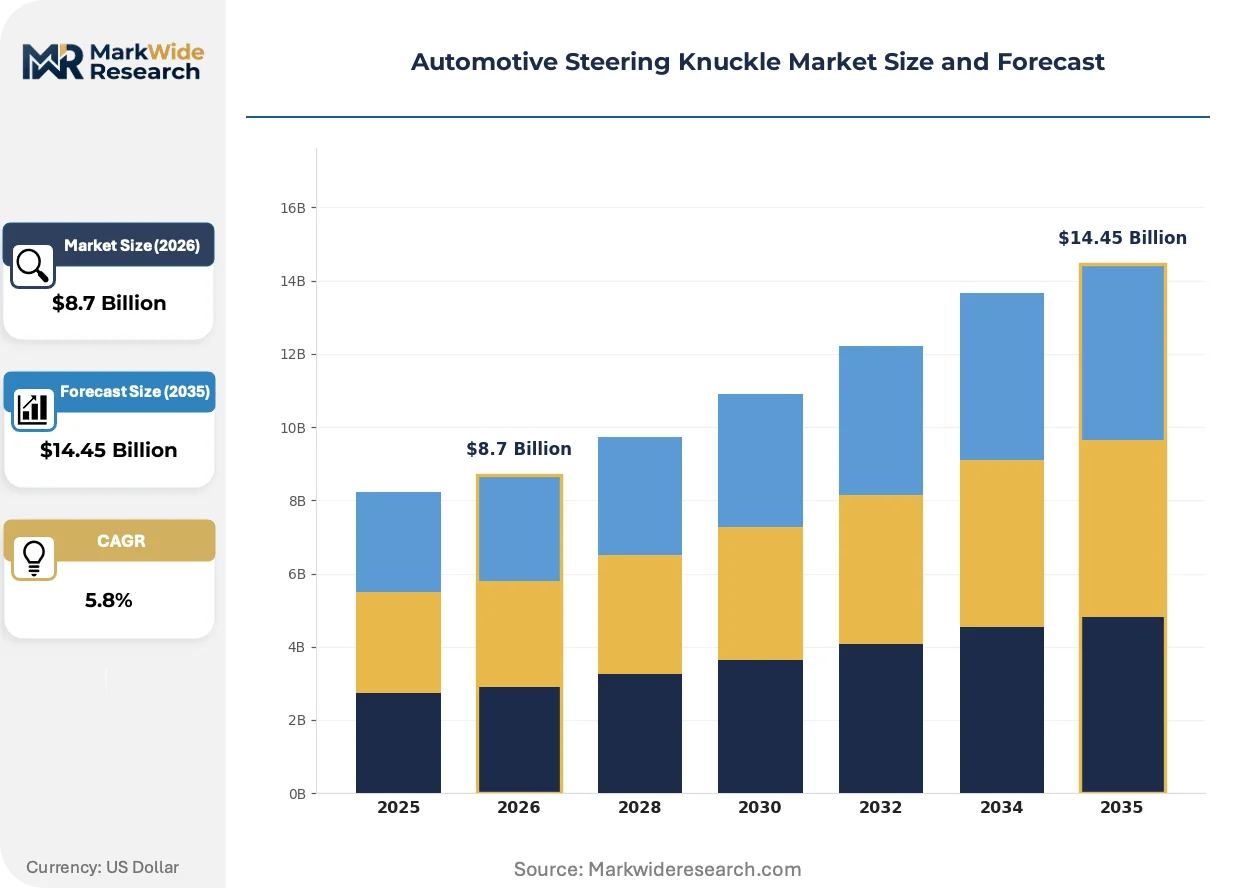
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forged Knuckle, Cast Knuckle, Machined Knuckle, Composite Knuckle Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Heavy-Duty Vehicles Material: Aluminum, Steel, Magnesium, Plastic End User: OEMs, Aftermarket, Tier-1 Suppliers, Distributors |
| Companies Covered | Benteler International AG, Bosch Automotive Steering, ZF Friedrichshafen AG, GKN Automotive Limited, Aisin Seiki Co., Ltd, Thyssenkrupp AG, Dana Incorporated, Continental AG, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Steering Knuckle Market Emerging Trajectories
Material science advances and regulatory weight mandates are converging to destabilize the forged-steel knuckle incumbent, creating openings for alternative manufacturing processes and integrated subsystem designs.
Aluminum high-pressure die casting with vacuum-assisted filling is fragmenting the traditional split between forged premium and cast economy knuckle tiers. Tesla's structural battery pack architecture and Rivian's skateboard platform are adopting these castings for both front and rear corners, collapsing the historical three-hundred-dollar unit cost gap with forged alternatives. The technology is fragmenting supplier tiering structures that once segregated by vehicle class.
EU Green Deal carbon border adjustment mechanisms are reshaping sourcing mathematics for European OEM procurement teams. Embedded emissions calculations now disadvantage Chinese-sourced primary aluminum against European recycled-content feedstock, redirecting contract awards toward hydro-powered smelters in Norway and Iceland. German premium automakers are responding with supplier sustainability scorecards that weight carbon intensity above landed unit cost.
Fleet operators and mobility-as-a-service providers are compressing knuckle replacement cycles through predictive wear monitoring. Uber and Lyft vehicle aggregators in California and Texas are negotiating lifetime-per-kilometer service contracts with Tier-1 suppliers, unbundling component procurement from traditional new-vehicle program economics. This behavior is most visible in high-utilization urban ride-hail fleets where annual mileage exceeds one hundred thousand kilometers per vehicle.
Automotive Steering Knuckle Market Segmentation
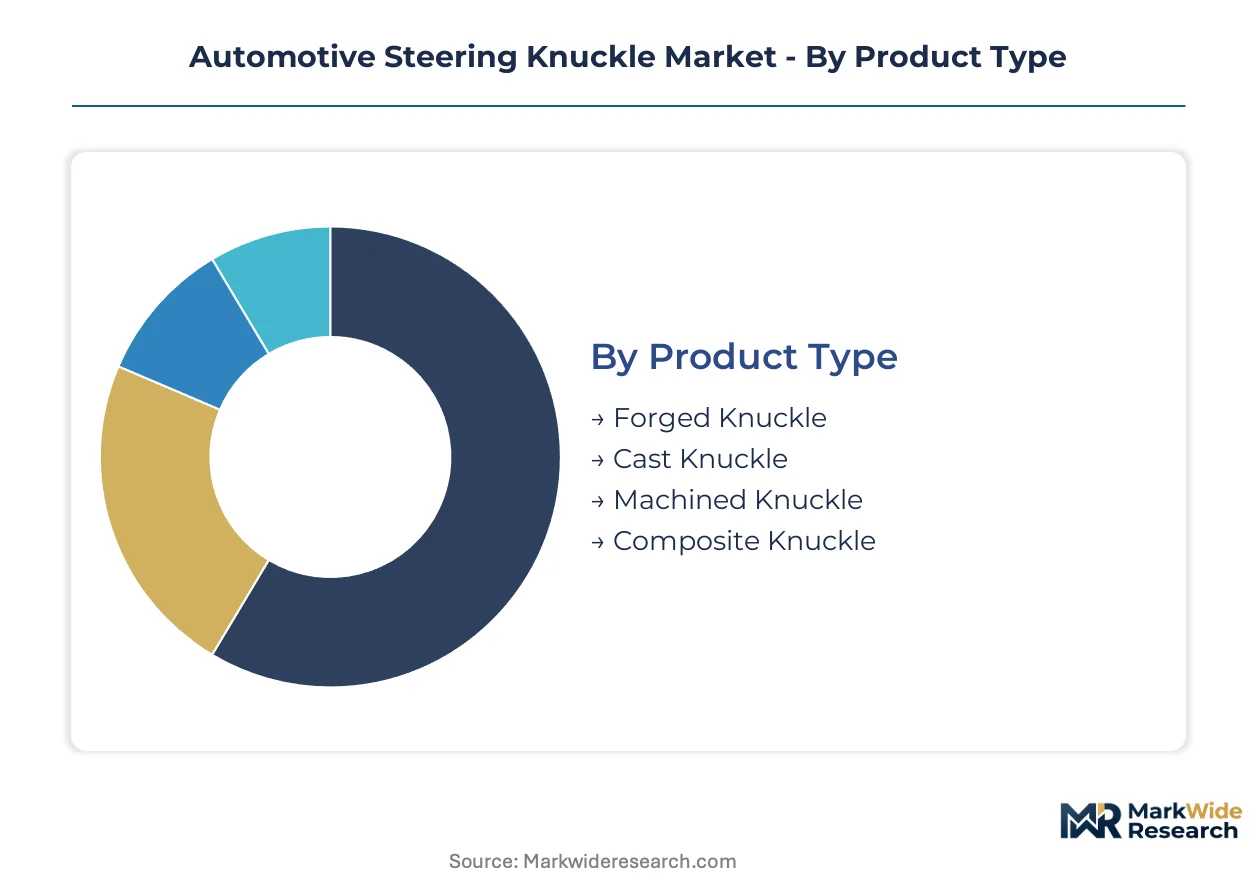
Segmentation in the automotive steering knuckle market tracks how material substitution and platform electrification are fragmenting traditional supply relationships. Procurement channels are diverging as OEMs consolidate around integrated corner modules while aftermarket distributors develop independent refurbishment capabilities.
Product Type:
Forged knuckles flow through premium OEM direct contracts and captive forge networks, while cast and machined variants increasingly reach assembly plants via Tier-1 system integrators bundling suspension modules.
- Forged Knuckle:Manufactured from closed-die steel forgings with grain flow optimized for fatigue resistance. Demand concentrates in German premium automaker programs and North American heavy-duty truck axles where load-bearing requirements exceed cast aluminum capabilities. EPA CAFE penalties on vehicle weight are compressing addressable volume despite superior mechanical properties.
- Cast Knuckle:Produced through high-pressure die casting with vacuum-assisted filling, typically from A356-T6 aluminum alloy. BYD and Tesla engineering teams are driving adoption across electric vehicle platforms where every kilogram of unsprung mass reduction extends range. China MIIT dual carbon goals are redirecting domestic foundry capacity toward this segment.
- Machined Knuckle:CNC-finished forgings or castings achieving kingpin bore tolerances within 0.05 mm. Tier-1 suppliers in Tamil Nadu and Gujarat industrial corridors are expanding machining capacity under India's PLI scheme for advanced automotive components.
- Composite Knuckle:Carbon-fiber-reinforced polymer prototypes under evaluation for radical chassis mass targets in luxury electric sedans. Strategic R&D budgets at BMW and Mercedes-Benz include validation programs for this material system.
Forged knuckles dominate installed base. Cast knuckles are where expansion concentrates.
Application:
Cost tier separation is pronounced: passenger vehicle programs absorb aluminum castings at volume scale while commercial and heavy-duty applications sustain steel forging premiums through performance requirements.
- Passenger Vehicles:The largest volume category encompassing sedans, crossovers, and light SUVs. NHTSA fuel economy standards and EU CO2 targets are accelerating aluminum substitution across this segment faster than engineering departments can requalify suppliers.
- Commercial Vehicles:Delivery vans, medium-duty trucks, and bus platforms with gross vehicle weights between 3.5 and 7.5 tonnes. Dana Incorporated maintains pricing power here through specialized forged knuckle designs resistant to cast aluminum porosity limitations.
- Off-Road Vehicles:Agricultural machinery, construction equipment, and mining trucks operating in high-impact environments. Surface treatment chemistry transitions under REACH restrictions are forcing supplier qualification changes for European OEM sourcing teams.
- Heavy-Duty Vehicles:Class 8 trucks and axle applications above 7.5 tonnes where cast aluminum microstructure porosity thresholds exclude the material. Bosch Automotive Steering bundles knuckle-adjacent hardware into electromechanical systems for this segment.
Passenger vehicles anchor volume procurement. Heavy-duty vehicles preserve forged steel margins.
Material:
Supply concentration varies sharply by feedstock: primary aluminum flows through London Metal Exchange pricing volatility while steel maintains captive forge integration and magnesium remains specialty-sourced.
- Aluminum:A356, A380, and Silafont-36 alloys processed through high-pressure die casting or low-pressure permanent mold casting. European OEM procurement teams are redirecting contract awards toward Norwegian and Icelandic hydro-powered smelters under EU carbon border adjustment mechanisms.
- Steel:Microalloyed forging grades with controlled sulfur content for machinability. Thyssenkrupp AG leverages captive steel-forging assets to anchor long-term contracts with German premium automakers resistant to material substitution.
- Magnesium:AZ91D and AM60B grades penetrating luxury electric sedan programs where radical chassis mass reduction justifies cost premiums. Volume constraints limit this material to platforms above fifty thousand dollars manufacturer suggested retail price.
- Plastic:Glass-reinforced nylon prototypes for non-structural knuckle shrouds and sensor housings. Functional steering load-bearing applications remain outside this material's capability envelope.
Steel maintains heavy-duty dominance. Aluminum is climbing the fastest across electrified platforms.
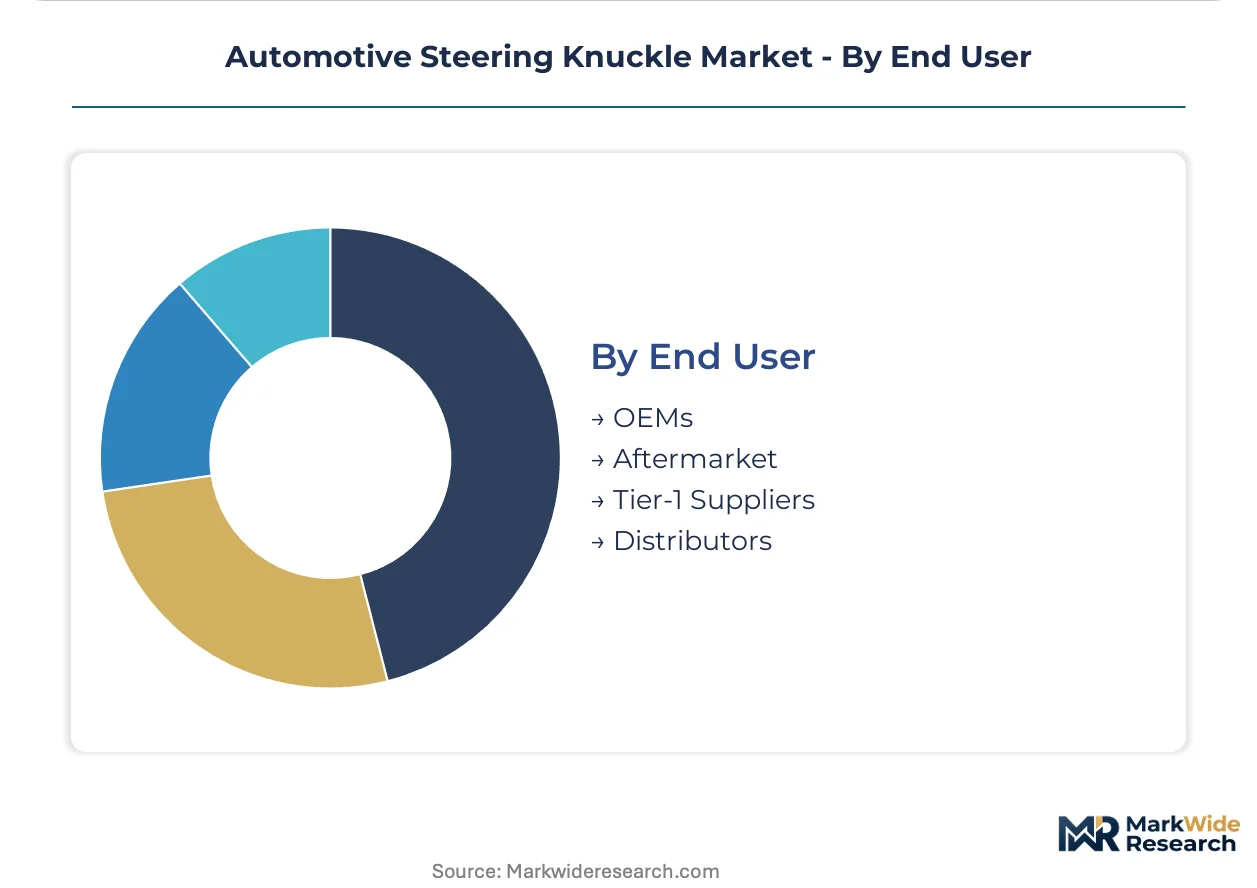
End User:
Customer type determines margin structure: OEMs extract volume discounts through consolidated corner-module procurement while aftermarket channels develop remanufacturing capabilities outside traditional new-vehicle economics.
- OEMs:Volkswagen Group, Toyota Motor Corporation, and Stellantis engineering teams specifying knuckles as part of integrated suspension architectures. Homologation timeline compression from eighteen to twelve months under EU Whole Vehicle Type Approval is squeezing design iteration windows.
- Aftermarket:Independent distributors and collision repair specialists developing certified knuckle refurbishment lines. Uber and Lyft fleet operators in California and Texas are negotiating lifetime-per-kilometer service contracts that unbundle component procurement from traditional program economics.
- Tier-1 Suppliers:Continental, ZF Friedrichshafen, and Mando Corporation consolidating knuckle procurement with control-arm and hub-bearing assemblies. This integration compresses margin pools for standalone component specialists.
- Distributors:Regional warehousing operations serving fragmented repair shop networks. CNC machining talent scarcity for kingpin bore finishing is limiting distributor expansion into in-house remanufacturing.
Tier-1 suppliers control new-vehicle flow. Aftermarket distributors are capturing collision-repair margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes knuckles at electric vehicle scale, while Germany preserves forged steel premiums for performance platforms and the United States splits demand between aluminum light-truck compliance and heavy-duty forging heritage.
China
BYD and NIO engineering teams are localizing machined aluminum knuckle procurement at unprecedented rates. MIIT dual carbon goals redirect foundry capacity from export castings toward domestic EV chassis components. Yangtze River Delta clusters around Shanghai and Ningbo now host the densest concentration of high-pressure die casting capacity serving OEM assembly plants.
Germany
Volkswagen Group and BMW engineering departments maintain forged steel specifications for M-series and RS performance variants despite aluminum encroachment on volume platforms. EU Green Deal carbon border adjustments penalize Chinese primary aluminum, redirecting contract awards toward Norwegian hydro-powered smelters. Baden-Württemberg's Stuttgart corridor anchors captive forging networks for premium automaker programs.
United States
Ford and General Motors light-truck platforms absorb aluminum knuckles to offset EPA CAFE weight penalties on full-size pickups. NHTSA enforcement of Corporate Average Fuel Economy standards intensifies material substitution pressure. Michigan's Detroit-to-Lansing corridor concentrates Tier-1 supplier engineering centers coordinating corner module integration.
India
Maruti Suzuki and Tata Motors procurement teams are qualifying domestic aluminum knuckle suppliers under accelerated timelines. PLI scheme production-linked incentives for advanced automotive components attract machining investments to Tamil Nadu and Gujarat industrial corridors. Chennai's Sriperumbudur belt now hosts expanding CNC finishing capacity for export-oriented Tier-1 contracts.
Japan
Toyota Motor Corporation and Honda engineering teams balance aluminum adoption with conservative fatigue validation protocols that slow supplier requalification. METI industrial policy supports domestic forging asset modernization rather than offshore casting migration. Aichi Prefecture's Toyota City cluster maintains integrated in-house forging capacity for hybrid platform knuckle supply.
Automotive Steering Knuckle Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in knuckle supply. Tier-1 system integrators consolidate procurement with adjacent suspension hardware, compressing margin pools for standalone component manufacturers. The market separates into three archetypes: captive forge operators with steel assets, aluminum casting specialists serving EV platforms, and integrated chassis module assemblers. Competitive moves center on corner module bundling contracts and sustainability scorecard positioning for European OEM procurement teams.
Within the integrated chassis systems tier, ZF Friedrichshafen AG and Continental AG exemplify the bundling strategy that knits knuckles into pre-assembled corner modules. Thyssenkrupp AG occupies a distinctive position among German-based fabricators with captive steel-forging heritage. Bosch Automotive Steering represents the electromechanical integration vector where knuckle-adjacent hardware converges with steering actuator systems. These three anchors illustrate how supplier tiering now stratifies by subsystem integration depth rather than component specialization alone.
| Leading Market Players |
|---|
| Benteler International AG |
| Bosch Automotive Steering |
| ZF Friedrichshafen AG |
| GKN Automotive Limited |
| Aisin Seiki Co., Ltd |
| Thyssenkrupp AG |
| Dana Incorporated |
| Continental AG |
| Magna International |
| Others |
Supply Flow & Price Mechanics
High-pressure die casting capacity utilization above eighty percent in Yangtze River Delta clusters compresses unit economics for aluminum knuckle suppliers while simultaneously elevating price floors for buyers locked out of long-term foundry contracts. This scale concentration lets integrated Tier-1 suppliers extract volume discounts that standalone machining specialists cannot match, bifurcating procurement economics across OEM direct contracts and fragmented aftermarket channels.
Pricing Analysis
After-sales service contracts and lifetime-per-kilometer agreements with fleet operators now capture more lifetime value than initial component sales, shifting revenue recognition toward recurring service streams. Three-tier pricing structure across premium forged steel, standard cast aluminum, and economy remanufactured tiers differentiates by fatigue certification grade and kingpin bore tolerance. Pricing pressure stems from London Metal Exchange aluminum volatility above fifteen percent annually, squeezing margin buffers for cast specialists without smelter hedging. Fleet operators and mobility aggregators exhibit highest price sensitivity, while German premium automakers accept steel forging premiums for performance variants.
Supply Chain Analysis
Strait of Malacca transit vulnerability for primary aluminum ingot from Australian and Indonesian smelters exposes Chinese foundry clusters to logistics disruption. Supply concentrates in China, Germany, and Mexico, with raw material dependencies on A356 aluminum alloy, microalloyed forging steel, and AZ91D magnesium grades. Single-source vulnerability in high-pressure die casting tooling from Japanese equipment makers elevates capex risk for new entrants. Distribution runs through Tier-1 system integrators bundling knuckles into pre-assembled corner modules, compressing direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent forged steel suppliers face substitution defense against aluminum casting encroachment on electric vehicle platforms, where every kilogram of unsprung mass reduction directly extends range and satisfies EPA CAFE compliance thresholds.
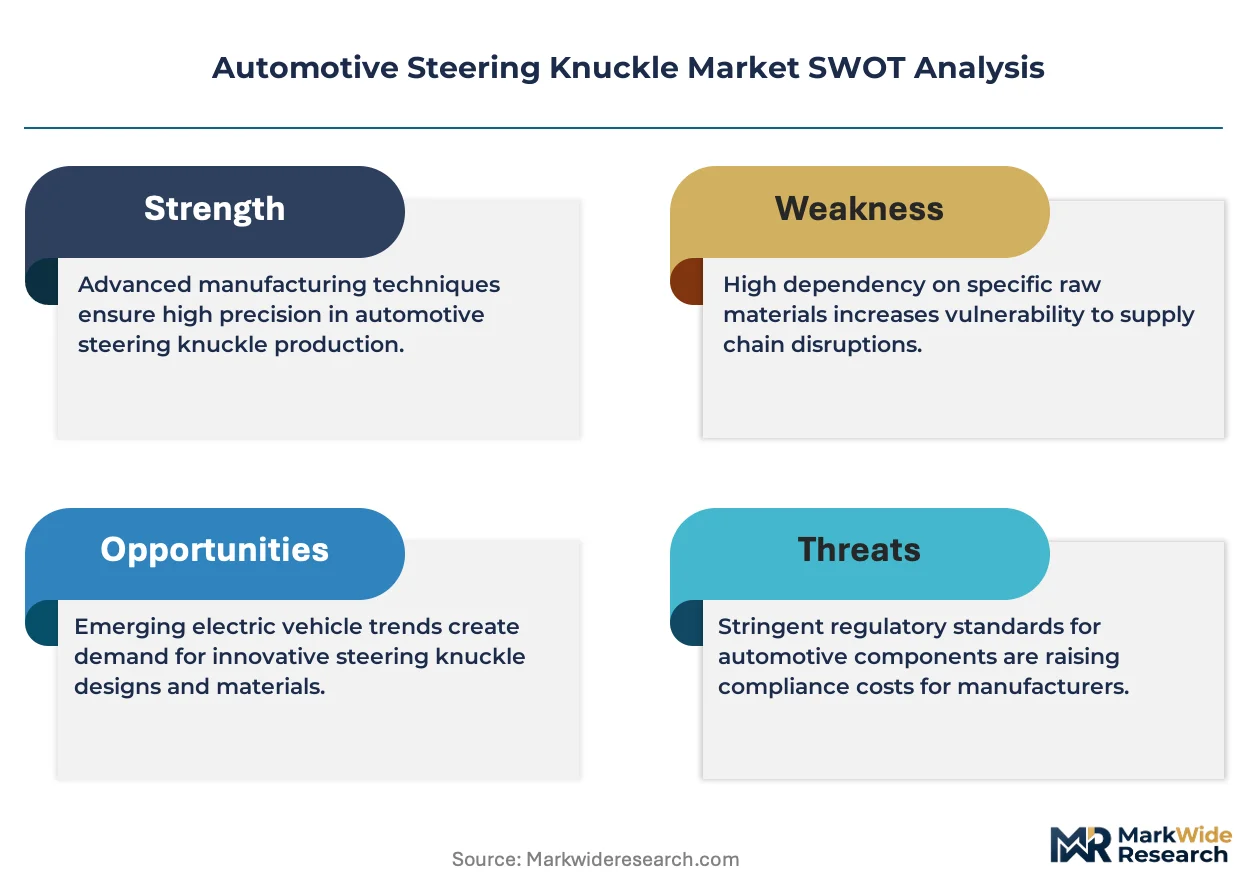
For Market Incumbents: Compound captive forging relationships with German premium automakers by embedding sustainability scorecards that weight carbon intensity above landed cost, while simultaneously acquiring CNC machining capacity in Tamil Nadu and Gujarat to offset aluminum casting share loss. Backward integration into closed-die forging assets and Norwegian hydro-powered aluminum sourcing defends margin position against Chinese foundry competition. For New Entrants and Emerging Players: Anchor in India's PLI scheme production-linked incentives for advanced automotive components, where Maruti Suzuki and Tata Motors procurement teams are accelerating domestic supplier qualification timelines. Target certified knuckle refurbishment for collision repair channels in California and Texas, where Uber and Lyft fleet operators negotiate lifetime-per-kilometer service contracts outside traditional OEM program economics. Lead with predictive wear monitoring technology to unbundle component procurement from new-vehicle sales cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aluminum casting specialists with vacuum-assisted die casting capabilities and established relationships with Tesla, BYD, and Rivian engineering teams. Long-term viability hinges on corner module integration depth rather than standalone component specialization, with acquisition value concentrating in Tier-1 suppliers bundling knuckles with control arms and hub bearings. Watch for MIIT dual carbon goal enforcement redirecting Chinese foundry capacity away from export markets as the inflection signal for Western supply shortage.| Strategic Initiative | Industry Significance |
|---|---|
| Corner Module Integration | Bundling knuckles with control arms and hub bearings reduces OEM line-side complexity and expands contract values for Continental and ZF Friedrichshafen. |
| Sustainability Scorecard Adoption | Volkswagen Group and BMW procurement teams now weight embedded carbon intensity above landed unit cost under EU Green Deal border adjustments. |
| Remanufacturing Channel Development | Independent aftermarket distributors capture collision-repair margin pools that OEMs historically ceded to scrap recyclers through certified refurbishment lines. |
| Magnesium Alloy Qualification | AZ91D and AM60B grades penetrate luxury electric sedan programs at BMW and Mercedes-Benz where radical chassis mass targets justify cost premiums. |
| PLI Scheme Capacity Expansion | Production-linked incentives in Tamil Nadu and Gujarat attract aluminum knuckle machining investments serving Maruti Suzuki and export Tier-1 contracts. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and CNC machining specialists converged on the working assumptions for material substitution timelines and supplier requalification windows. Primary interviews with foundry operations managers and suspension system architects combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA CAFE compliance filings, and EU ECHA REACH restriction notices. Bottom-up unit economics for forged versus cast knuckle production triangulated against top-down OEM procurement budget allocations.
Segmentation dimensions modeled across the analysis window encompass propulsion architecture, vehicle class, material grade tier, and regional production cluster. CAGRs were derived from production volume forecasts weighted by content-per-vehicle assumptions for aluminum versus steel knuckle penetration. Industry-specific inputs included London Metal Exchange aluminum price trajectories, MIIT dual carbon policy enforcement intensity, and NHTSA fuel economy standard penalty schedules.
Underlying assumptions cover sustained EPA CAFE enforcement and EU carbon border adjustment implementation, with deviation risk concentrated in primary aluminum price volatility and CNC machining talent scarcity for five-axis kingpin bore finishing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Automobile Muffler Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
Steel Cords for Radial Tyres Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Apron Bus Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Automotive Engine Cam Cover Market
Automotive Parts
Automotive Antifreeze Market