
 Latin America Automotive Parts Zinc Die Casting Market | 2026-2036
Latin America Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Automotive Parts Zinc Die Casting Market Foresight
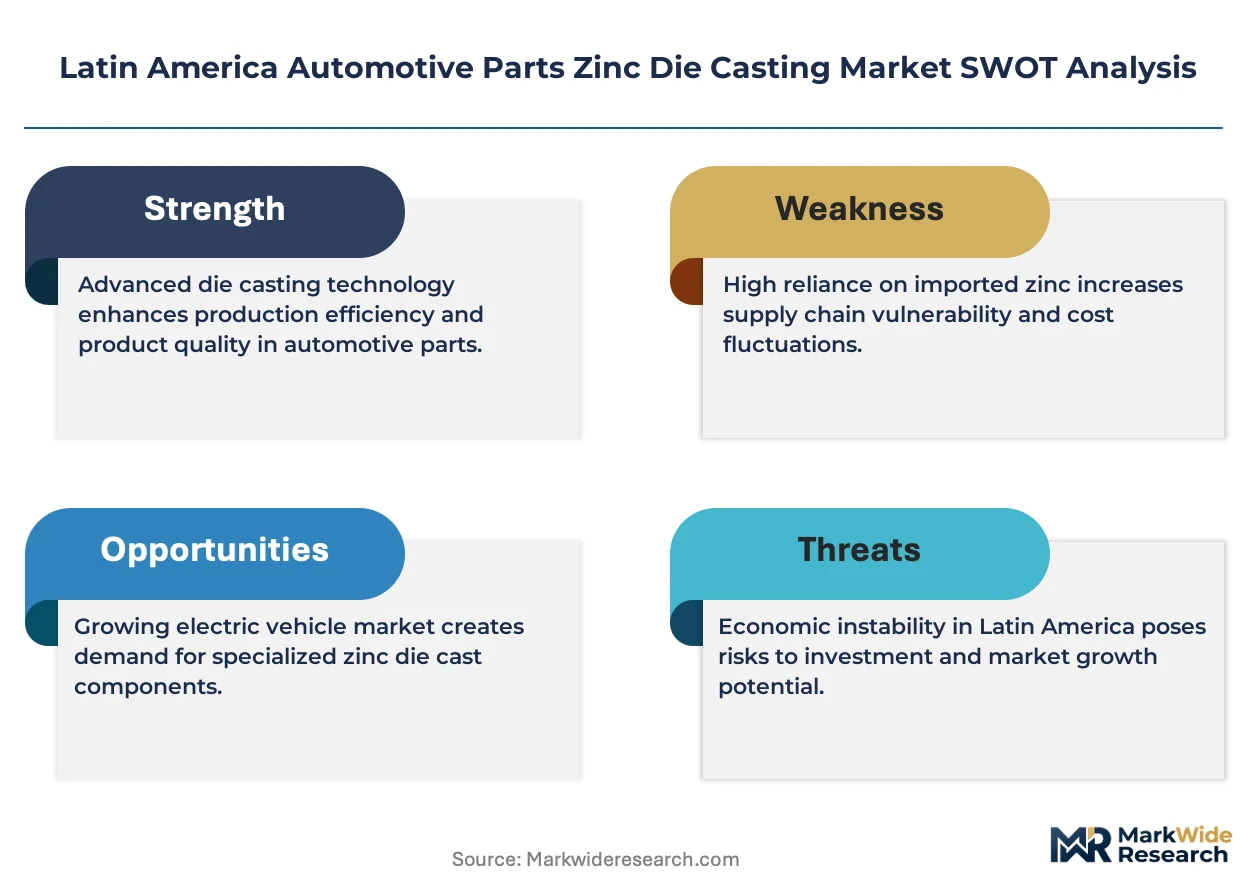
Mexico's PROSEC tariff program is consolidating zinc die casting demand around in-region supply chains. Dynacast leverages its multi-plant footprint across Mexico and Brazil to anchor OEM programs for transmission and chassis components. Sandhar Technologies Ltd sustains engineering partnerships with passenger vehicle assemblers in the Bajío corridor. Zinc Nacional dominates domestic zinc alloy supply, giving it backward integration advantages that competitors navigate around.
Latin America automotive parts zinc die casting involves injecting zinc alloys with aluminum, copper, and magnesium additions into hardened steel dies at pressures exceeding 1,000 bar, producing near-net-shape components with wall thicknesses down to 0.5 millimeters for corrosion-resistant automotive hardware. Engine components represent the most mature product category, with long-standing demand for valve covers and timing chain housings, while electrical parts capture expanding margin pools as EV architectures multiply grounding and connector applications. High-pressure die casting leads technology deployment for complex geometries, though gravity die casting retains share in lower-volume commercial vehicle and motorcycle segments where tooling amortization cycles extend.
Brazil's ANFAVEA emission protocols and Mexico's NOM environmental standards shape alloy composition requirements and foundry effluent controls across the region. INMETRO certification in Brazil and PROFECO oversight in Mexico further govern dimensional tolerances and consumer protection for aftermarket replacement parts. Stakeholders must monitor how PROSEC rule revisions and potential Mercosur-Pacific Alliance trade linkage talks redistribute casting demand across Mexican, Brazilian, and Argentine production nodes.
Market Dynamics
OEM lightweighting mandates for powertrain housings are compressing traditional steel and aluminum supply chains across Mexico and Brazil, forcing tier suppliers to retool for zinc alloy precision casting at sub-millimeter tolerances.
Growth Catalysts
- PROSEC tariff incentives:Mexico's Sectoral Promotion Programs eliminate import duties on zinc alloy inputs for automotive exporters, anchoring foundry investment in the Bajío corridor near Volkswagen and Nissan assembly plants.
- EV electrical architecture expansion:Grounding terminals and high-voltage connector housings for battery-electric platforms multiply zinc die casting applications beyond traditional engine hardware.
- High-pressure die casting maturation:Advanced multi-slide tooling achieves 0.5-millimeter wall thicknesses, opening transmission valve body and steering housing programs previously reserved for machined aluminum.
Market Restraints
- Zinc price volatility:London Metal Exchange zinc contract swings transmit directly to foundry margins, compressing profitability for operators without backward integration into alloy supply.
- Specialized tooling amortization:Hardened steel dies for complex geometries require 18-24 month payback cycles, deterring entry for low-volume commercial vehicle and motorcycle suppliers.
- Effluent compliance burden:Brazil's ANFAVEA emission protocols and Mexico's NOM environmental standards impose capital-intensive wastewater treatment and air filtration systems on foundry operations.
Strategic Opportunities
- Argentine production node development:Potential Mercosur-Pacific Alliance trade linkage talks could redistribute casting demand toward Córdoba's underutilized industrial parks, offering tariff-advantaged export positioning.
- Aftermarket replacement parts certification:INMETRO certification in Brazil and PROFECO oversight in Mexico create margin pools for dimensionally precise zinc castings in brake caliper brackets and door hinge assemblies.
- Thin-wall magnesium-zinc hybrid alloys:Convergence of magnesium creep resistance with zinc castability enables next-generation steering column brackets and seat recliner mechanisms.
Industry Challenges
- Multi-slide tooling technician scarcity:The Bajío corridor and São Paulo industrial belt compete for operators capable of programming and maintaining 1,000-bar injection systems with real-time porosity monitoring.
- PROSEC rule revision uncertainty:Pending Mexican tariff schedule updates threaten to reclassify zinc alloy import categories, freezing capital allocation decisions among tier-two foundries.
- Legacy ERP integration friction:Foundries modernizing toward Industry 4.0 traceability face data architecture conflicts with OEM purchasing systems requiring lot-level alloy chemistry documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Automotive Parts Zinc Die Casting Market |
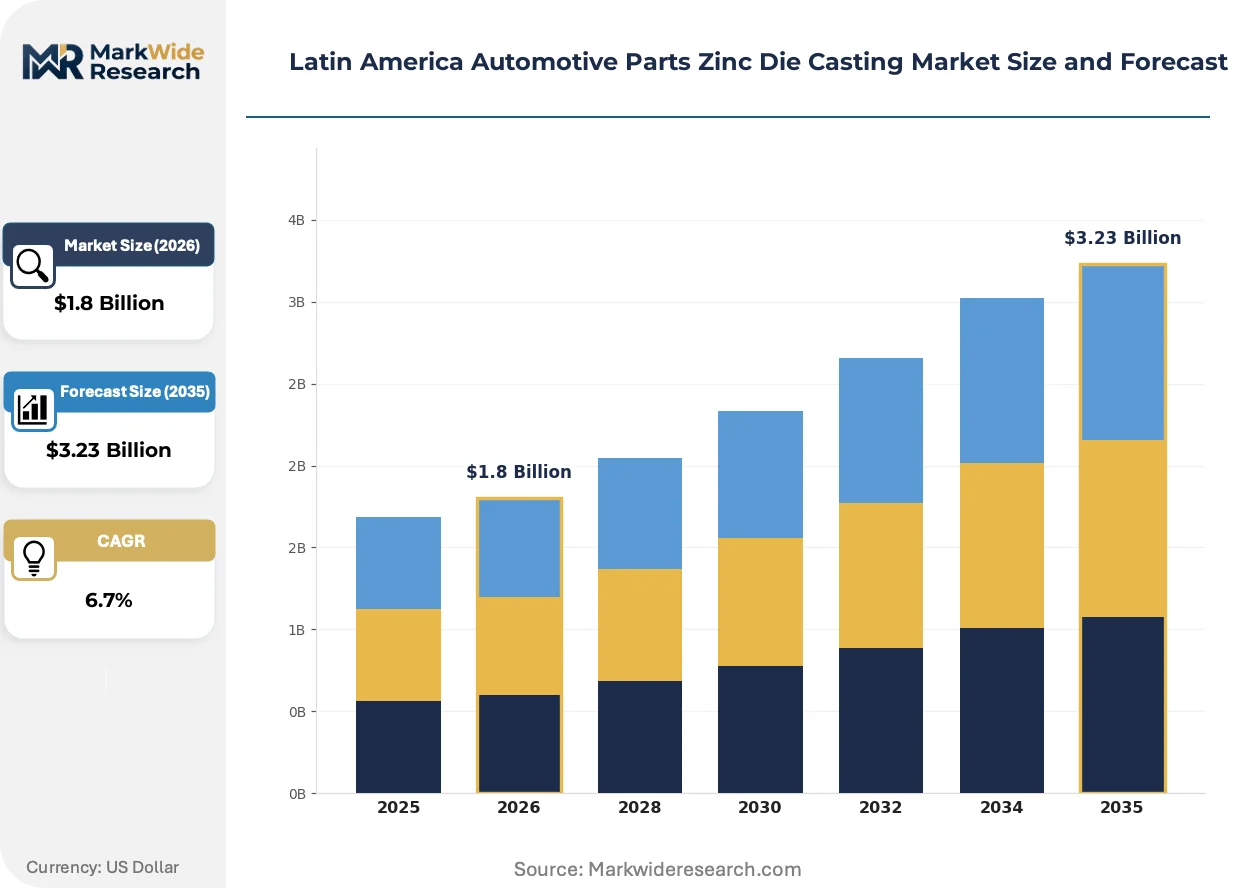
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Chassis Parts, Electrical Parts Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy Machinery End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: High-Pressure Die Casting, Low-Pressure Die Casting, Gravity Die Casting, Sand Casting |
| Companies Covered | Dynacast, Sandhar Technologies Ltd, Brillcast Manufacturing LLC, Pace Industries, Ashok Minda Group, Zinc Nacional, Kemlows Die Casting Products Ltd, Minda Corporation Limited, Empire Casting Co., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Automotive Parts Zinc Die Casting Market Shifts & Advancements
Process digitization and alloy formulation advances are compressing development cycles for precision automotive hardware, while regulatory tightening on emissions and dimensional tolerances reshapes competitive qualification requirements across Mexican and Brazilian supply bases.
Multi-slide zinc die casting technology is rewriting component consolidation possibilities for transmission and chassis modules. Tier-one suppliers in Guanajuato and São Paulo are adopting four-slide tooling configurations to cast integrated valve body housings with internal oil galleries previously assembled from three separate machined parts. The structural consequence is collapsing sub-supplier tiers as OEMs qualify single-source zinc castings for 150,000-unit annual programs.
Brazil's ANFAVEA emission protocols now mandate foundry-level reporting of volatile organic compound releases per ton of zinc alloy processed, with third-party audit requirements effective across all INMETRO-certified suppliers. Industrial consequence includes accelerated capital deployment toward thermal oxidizers and regenerative thermal oxidizer systems. The passenger vehicle segment is most affected, with Volkswagen do Brasil and Stellantis Betim plants now requiring ISO 14001 certification extension to tier-two zinc foundries as a condition of program award.
Consolidated procurement models are displacing fragmented multi-source purchasing for zinc die castings across the Bajío automotive corridor. Volkswagen de México and Nissan Aguascalientes have reduced their transmission housing supplier bases from four to two qualified foundries each, replacing competitive bidding with long-term alloy price hedging agreements. This concentration is most visible in Guanajuato state, where OEM engineering teams now embed resident quality engineers at sole-source zinc casting operations for real-time dimensional correction.
Latin America Automotive Parts Zinc Die Casting Market Segmentation
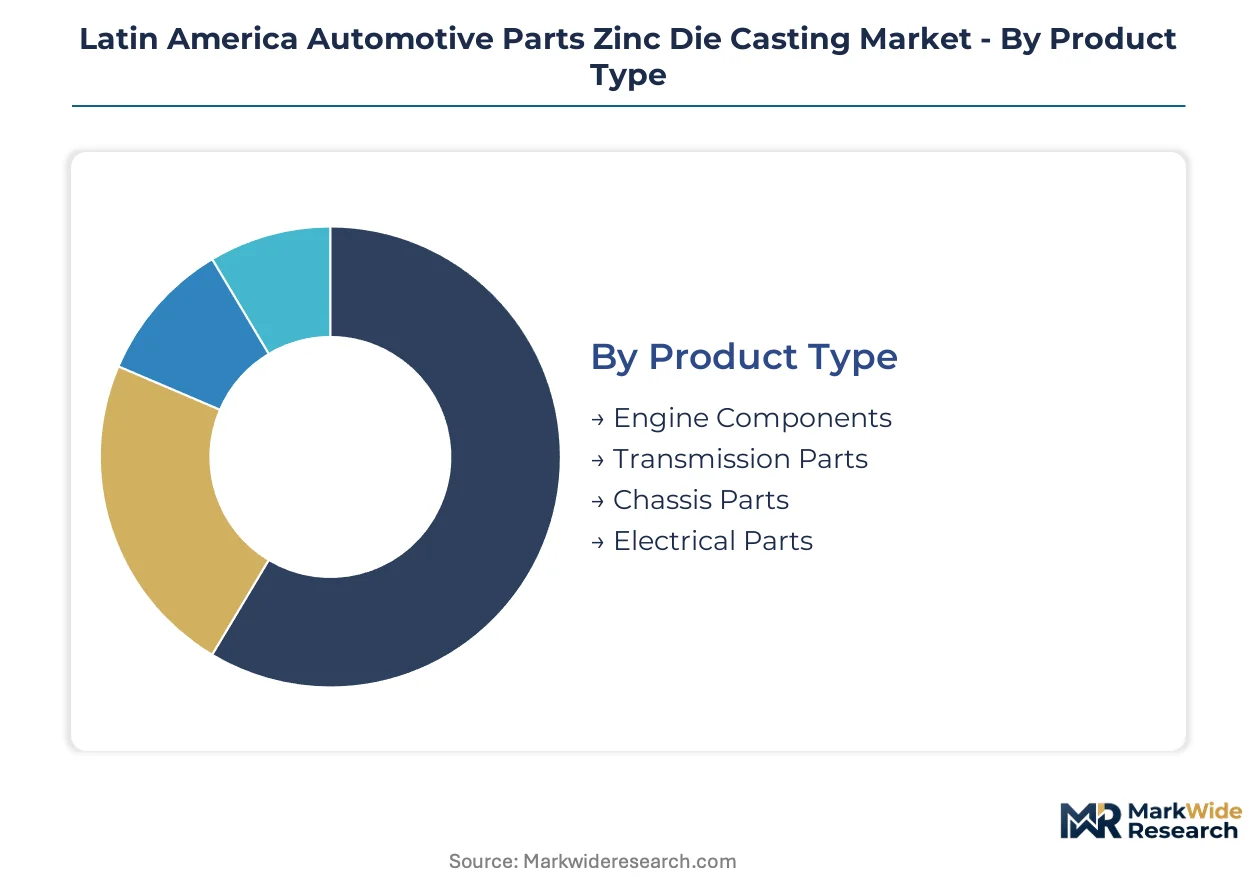
Zinc die casting procurement patterns diverge sharply across product categories, end-user sophistication, and process technology. Each segmentation axis reveals distinct margin structures and qualification barriers that shape competitive positioning in Mexico and Brazil.
Product Type:
Volume concentration and tooling amortization cycles separate buyers in this category, with OEMs prioritizing consolidated component sourcing against fragmented aftermarket procurement.
- Engine Components:Valve covers and timing chain housings constitute the most mature zinc die casting category, with standardized alloy compositions of ZAMAK 3 and ZAMAK 5 dominating. Demand concentrates in Volkswagen and Nissan powertrain programs across Guanajuato and Aguascalientes assembly corridors, where 150,000-unit annual volumes justify hardened steel die investments.
- Transmission Parts:Multi-slide tooling achieves integrated valve body housings with internal oil galleries at 0.5-millimeter wall thicknesses, collapsing three-part machined assemblies into single zinc castings. This segment captures expanding share as OEM lightweighting mandates compress traditional aluminum supply chains in São Paulo and Bajío industrial belts.
- Chassis Parts:Steering housings and suspension brackets require sub-millimeter tolerances for fatigue resistance.
- Electrical Parts:Grounding terminals and high-voltage connector housings for battery-electric platforms multiply zinc applications beyond legacy engine hardware.
Engine Components leads volumes today; Transmission Parts is gaining share fastest.
Application:
Production scale and regulatory stringency divide this category, with passenger vehicle OEMs imposing ISO 14001 certification extensions that commercial vehicle suppliers rarely match.
- Passenger Vehicles:Volkswagen do Brasil and Stellantis Betim plants mandate ANFAVEA emission protocol compliance across tier-two foundries, with thermal oxidizer investments required for program qualification. This segment commands premium pricing for INMETRO-certified dimensional precision in brake caliper brackets and door hinge assemblies.
- Commercial Vehicles:Lower-volume truck and bus programs extend tooling amortization cycles to 24-30 months, favoring gravity die casting over high-pressure systems. Demand clusters in Mercedes-Benz and Scania assembly networks across São Bernardo do Campo and Resende industrial zones.
- Motorcycles:Honda and Yamaha two-wheeler programs in Manaus Free Trade Zone favor simplified tooling configurations.
- Heavy Machinery:Caterpillar and Komatsu construction equipment sourcing tolerates broader dimensional tolerances for non-structural housings.
Passenger Vehicles dominates revenue; Commercial Vehicles offers the steepest expansion trajectory for specialized foundries.
End User:
Backward integration depth and lot-level traceability requirements distinguish procurement sophistication across this axis.
- OEMs:Volkswagen de México and Nissan Aguascalientes have consolidated transmission housing supplier bases from four to two qualified foundries each, replacing competitive bidding with long-term alloy price hedging agreements. Resident quality engineers embed at sole-source operations for real-time dimensional correction.
- Tier-1 Suppliers:Dynacast and Sandhar Technologies anchor multi-plant footprints across Mexico and Brazil to service OEM programs, leveraging engineering partnerships for transmission and chassis component qualification.
- Aftermarket Providers:PROFECO oversight in Mexico and INMETRO certification in Brazil create margin pools for replacement brake caliper brackets.
- Vehicle Assemblers:Final assembly plants in Córdoba and Buenos Aires source zinc castings through Mercosur trade linkages.
OEMs concentrate procurement volume; Tier-1 Suppliers capture margin expansion through engineering integration.
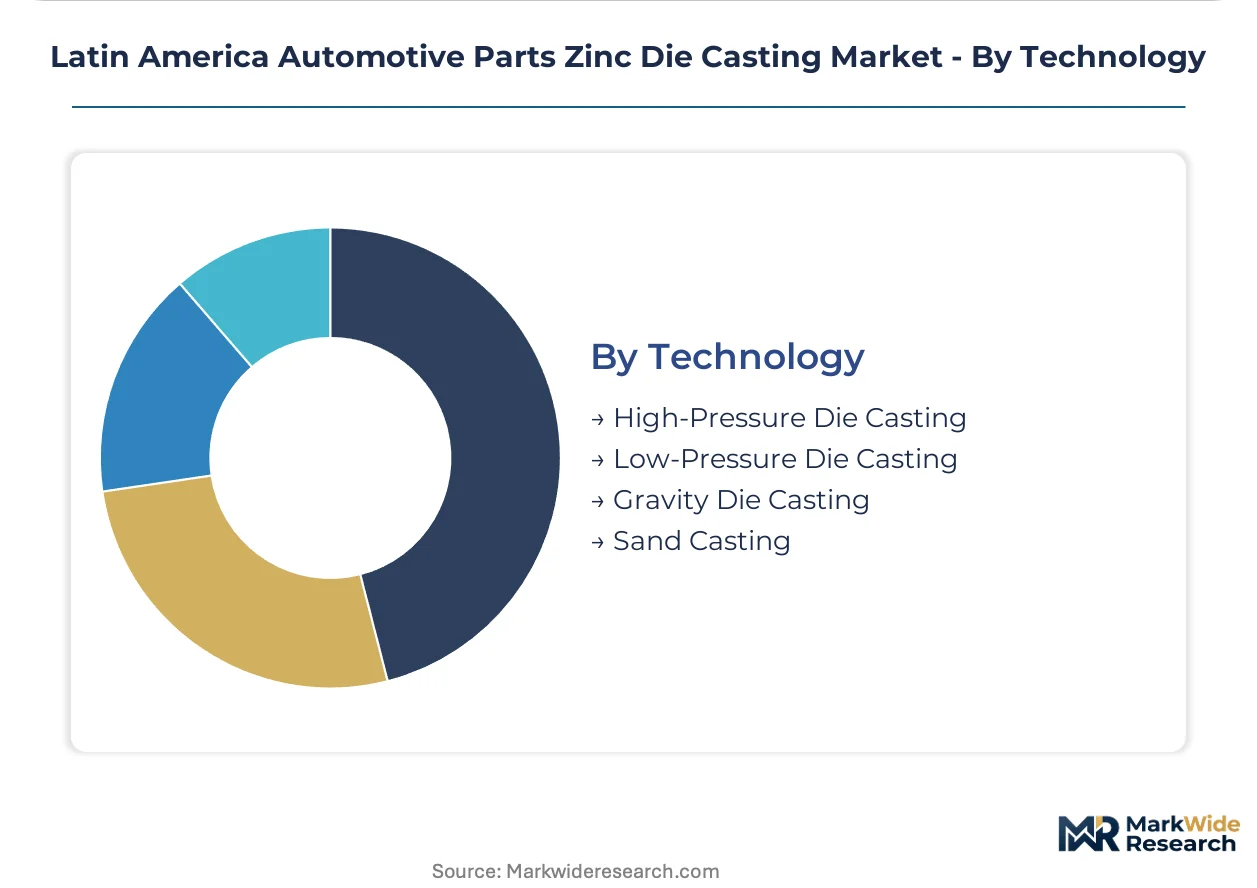
Technology:
Geometric complexity and production velocity determine process selection, with high-pressure systems commanding technician premiums that constrain supply.
- High-Pressure Die Casting:Four-slide tooling configurations achieve 1,000-bar injection pressures with real-time porosity monitoring, enabling integrated transmission valve bodies previously reserved for machined aluminum. The Bajío corridor and São Paulo industrial belt compete for scarce operators capable of programming these systems.
- Gravity Die Casting:Lower capital requirements and extended tooling life suit commercial vehicle and motorcycle segments where annual volumes fall below 50,000 units. Brazilian foundries in Minas Gerais retain significant share in this category.
- Low-Pressure Die Casting:Intermediate complexity applications in electrical connector housings.
- Sand Casting:Prototype development and heavy machinery non-structural components.
High-Pressure Die Casting anchors OEM qualification; Gravity Die Casting defends position in commercial vehicle niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zinc die casting for automotive components took root in Latin America during the 1960s as Volkswagen and Nissan established assembly operations in Mexico, creating demand for localized precision metal forming that previously traveled from European and Japanese supplier networks.
Mexico
Transmission housing programs for Volkswagen de México and Nissan Aguascalientes anchor demand volumes exceeding 150,000 units annually. PROSEC tariff elimination on zinc alloy inputs for automotive exporters concentrates foundry investment in the Bajío corridor. Guanajuato state hosts resident OEM quality engineers at sole-source casting operations for real-time dimensional correction.
Brazil
Stellantis Betim and Volkswagen do Brasil plants mandate ANFAVEA emission protocol compliance across tier-two foundries, requiring thermal oxidizer investments for program qualification. INMETRO certification governs dimensional precision in brake caliper brackets and door hinge assemblies. São Bernardo do Campo and Resende industrial zones cluster Mercedes-Benz and Scania commercial vehicle sourcing networks.
Argentina
Córdoba's underutilized industrial parks position for casting demand redistribution if Mercosur-Pacific Alliance trade linkage talks advance. Honda and Yamaha two-wheeler programs in the region favor simplified tooling configurations. The country's national automotive regulator oversees dimensional tolerance standards for aftermarket replacement parts distribution.
Chile
Mining equipment manufacturers including Caterpillar and Komatsu source non-structural zinc housings with broader dimensional tolerances. Copper mining operations in the Atacama region generate zinc alloy feedstock proximity advantages for specialized foundries. Santiago-based distributors coordinate Mercosur trade linkages for Brazilian and Argentine casting imports.
Latin America Automotive Parts Zinc Die Casting Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Latin American zinc die casting, with integrated alloy suppliers and multi-plant foundry operators commanding distinct strategic positions. The market structures around three tiers: backward-integrated zinc alloy producers, multi-plant precision foundries, and regional engineering specialists. Consolidation pressure intensifies as OEM procurement models shift from four-supplier bases to two-qualified-foundry arrangements. Dominant competitive moves include geographic footprint expansion across Mexican and Brazilian industrial corridors and long-term alloy price hedging agreements replacing spot purchasing.
Among multi-plant precision foundries, Dynacast anchors OEM programs through its footprint across Mexico and Brazil. Sandhar Technologies Ltd occupies a position within the engineering partnership tier, sustaining relationships with passenger vehicle assemblers. Zinc Nacional exemplifies the backward-integrated archetype, leveraging domestic zinc alloy supply advantages that competitors navigate around.
| Leading Market Players |
|---|
| Dynacast |
| Sandhar Technologies Ltd |
| Brillcast Manufacturing LLC |
| Pace Industries |
| Ashok Minda Group |
| Zinc Nacional |
| Kemlows Die Casting Products Ltd |
| Minda Corporation Limited |
| Empire Casting Co. |
| Others |
Supply & Pricing Matrix
Zinc alloy ingot costs cascade through three distinct pricing tiers as London Metal Exchange contract volatility transmits from Zinc Nacional's smelters to tier-two foundries without backward integration. OEMs in Guanajuato and São Paulo negotiate long-term hedging agreements that compress spot-market premiums for transmission housing programs, while aftermarket distributors absorb sharper margin compression on brake caliper brackets under PROFECO price oversight.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates INMETRO-certified OEM supply from uncertified aftermarket channels. Premium tier pricing commands alloy chemistry documentation and resident quality engineer embedding at sole-source operations. Standard tier pricing applies to tier-one supplier programs with annual volume commitments exceeding 50,000 units. Economy tier pricing dominates Manaus Free Trade Zone motorcycle component sourcing where simplified tooling tolerances apply. Pricing pressure stems from zinc price volatility transmitting directly to unhedged foundry margins. Aftermarket providers exhibit highest price sensitivity due to fragmented procurement and absence of long-term contract structures.
Supply Chain Analysis
Scrap zinc recovery flows from Brazilian automotive dismantlers back to Minas Gerais foundries, creating circular feedstock loops that reduce primary ingot dependence. Supply concentrates in Mexico, Brazil, and Argentina across the Bajío corridor, São Paulo industrial belt, and Córdoba industrial parks. Raw material dependencies center on zinc concentrate from Peruvian and Australian mining operations, alloy additives from Chilean copper smelters, and hardened steel die imports from German and Japanese toolmakers. Single-source vulnerability runs through zinc alloy supply where Zinc Nacional dominates domestic Mexican production. Distribution runs through OEM-embedded tier-one suppliers for high-volume programs, with aftermarket channels served by independent distributors under INMETRO and PROFECO certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America automotive parts zinc die casting operates as a stable compounder anchored by OEM lightweighting mandates that sustain transmission and chassis component demand across multi-year vehicle platform cycles.
For Market Incumbents: Deepen backward integration into zinc alloy supply or captive die-making capacity to defend margins against London Metal Exchange volatility. Consolidate supplier qualification positions as Volkswagen de México and Nissan Aguascalientes reduce approved foundry bases from four to two sources. Prioritize resident quality engineer relationships at sole-source operations to lock out challenger entry. ANFAVEA emission protocol tightening threatens capital-intensive thermal oxidizer investments that smaller competitors cannot absorb. For New Entrants and Emerging Players: The gap between INMETRO-certified premium pricing and uncertified economy tier pricing creates entry space for mid-market positioning. Target Argentine Córdoba industrial parks if Mercosur-Pacific Alliance trade linkage talks advance, offering tariff-advantaged export positioning to Brazilian OEMs. Pursue gravity die casting specialization in commercial vehicle and motorcycle segments where tooling amortization cycles deter high-pressure system incumbents. Lead with simplified certification pathways under Brazil's national automotive regulator standards. For Investors and Strategic Acquirers: Roll-up economics work for multi-plant precision foundries because OEM procurement consolidation from four-supplier to two-supplier bases creates scalable platform value. Five-to-ten year viability rests on transmission housing program renewal rates and EV electrical architecture expansion into grounding terminal applications. Acquire tier-one suppliers with embedded resident engineer relationships at Volkswagen and Nissan operations. Monitor PROSEC rule revision announcements for tariff category reclassification signals that would freeze capital allocation and compress valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Alloy Supply | Captive feedstock from Zinc Nacional competitors insulates margins against LME contract swings. |
| Multi-Slide Tooling Technician Training Programs | Bajío corridor and São Paulo industrial belt competition for 1,000-bar system operators intensifies. |
| Long-Term Alloy Price Hedging Agreements | OEMs at Volkswagen de México and Nissan Aguascalientes replace spot purchasing with contract structures. |
| Mercosur-Pacific Alliance Trade Positioning | Argentine Córdoba industrial parks gain tariff advantage if linkage talks advance. |
| INMETRO Certification Extension to Tier-Two Foundries | Volkswagen do Brasil and Stellantis Betim plants mandate compliance for program qualification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-one supplier procurement leads, foundry operations managers, and aftermarket distributors with secondary validation. Foundry capacity databases, vehicle production registries from IHS Markit, London Metal Exchange zinc contract archives, and ANFAVEA emission protocol filings anchored quantitative inputs. Bottom-up triangulation against top-down market sizing cross-validated segment-level estimates.
Segment-weighting approaches distributed volume and value across product type, application, end user, and technology dimensions throughout the forecast period. High-pressure die casting adoption curves, gravity die casting retention in commercial vehicle niches, and EV electrical architecture penetration rates informed analytical frameworks. CAGRs derived from production volume trajectories at Volkswagen, Nissan, Stellantis, and GM assembly plants across Mexican and Brazilian corridors.
Caveats apply where PROSEC rule revisions, Mercosur-Pacific Alliance trade linkage outcomes, or zinc price volatility spikes could materially shift the outlook. Forecasts reflect assumptions regarding OEM lightweighting mandate continuity and EV platform rollout schedules. Practitioners should monitor ANFAVEA protocol amendments and NOM environmental standard updates for early signals of regulatory cost compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
US Automotive Airfilters Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
Automobile Muffler Market
Automotive Parts
Automotive Crankcase Additives Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Wheel Arch Liner Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Automotive Washer System Market
Automotive Parts
Exhaust Hanger Material Market
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Bumper Beam Market