
 Canada Transit Buses Market | 2026-2036
Canada Transit Buses Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Transit Buses Market Insights
A widening capital-intensity divergence between full-system integrators and component suppliers is reorganizing competitive tiers in Canadian transit bus manufacturing. New Flyer Industries leverages its Winnipeg production footprint and in-house battery-electric platforms to anchor large-volume contracts with TransLink and the TTC. GreenPower Motor Company differentiates through purpose-built electric chassis designs that occupy the mid-size and shuttle niche for university and corporate campus operators.
Canada transit buses are heavy-duty road vehicles engineered for high-cycle urban passenger transport, typically configured with gross vehicle weights exceeding 12,000 kg, low-floor entry systems, and modular drivetrain architectures accommodating diesel, hybrid, compressed natural gas, or battery-electric propulsion. The battery electric type segment leads capital deployment as provinces phase out fossil-fuel procurement mandates, while the articulated size category captures premium unit economics on high-ridership corridors in Montreal and Calgary. Public transport authorities represent the dominant end-user channel, though private operators are gaining fleet-share through contracted service models in secondary Canadian cities.
Transport Canada administers the Motor Vehicle Safety Act and CMVSS standards governing bus structural integrity and crashworthiness, while provincial regulators such as Ontario's MTO and British Columbia's CVSE enforce emissions compliance and operational certification for intra-provincial routes. Health Canada and PMRA jointly oversee material safety in interior composites and fire-retardant specifications, creating multi-layer compliance burdens for imported chassis platforms. Stakeholders must monitor how forthcoming federal ZEV sales mandates interact with provincial electricity grid capacity commitments to determine viable deployment timelines for next-generation fleet electrification.
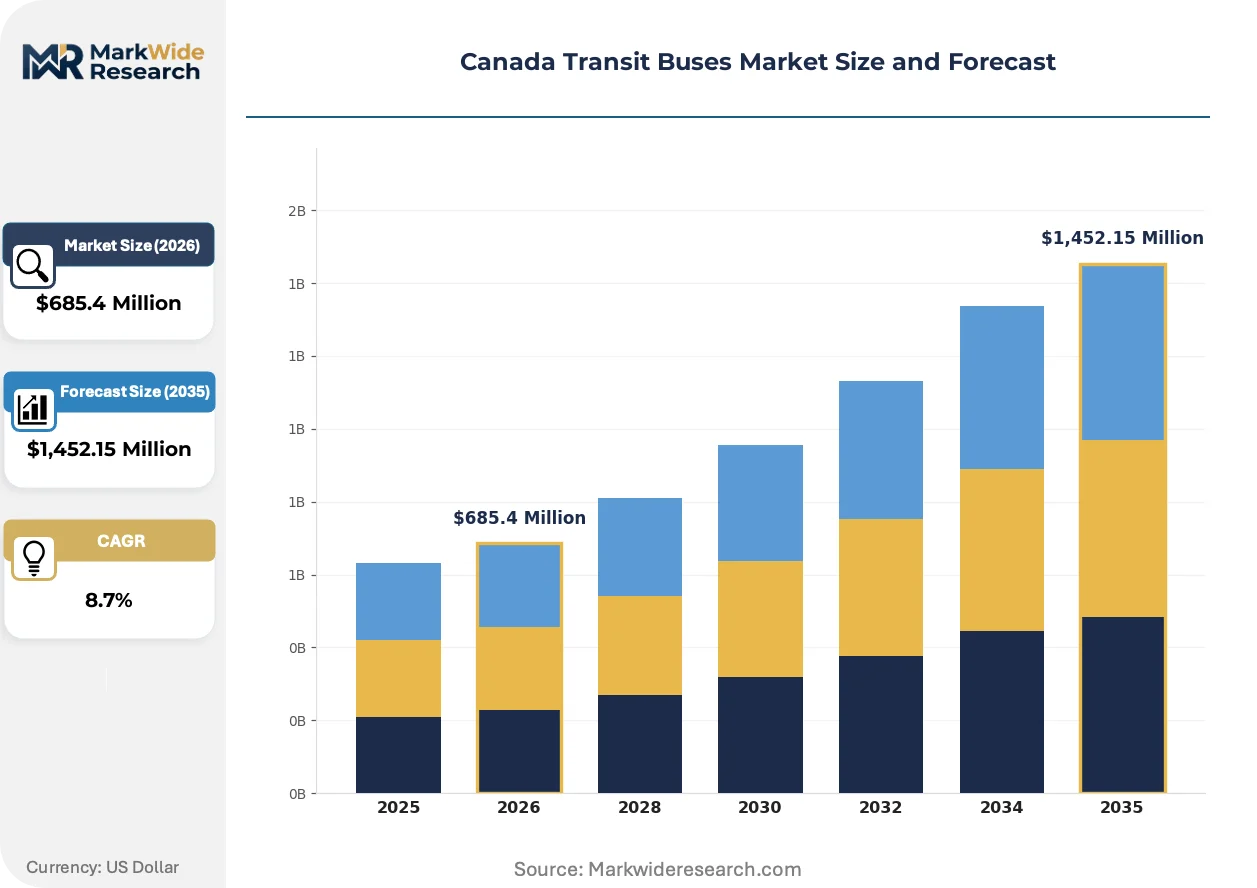
Market Dynamics
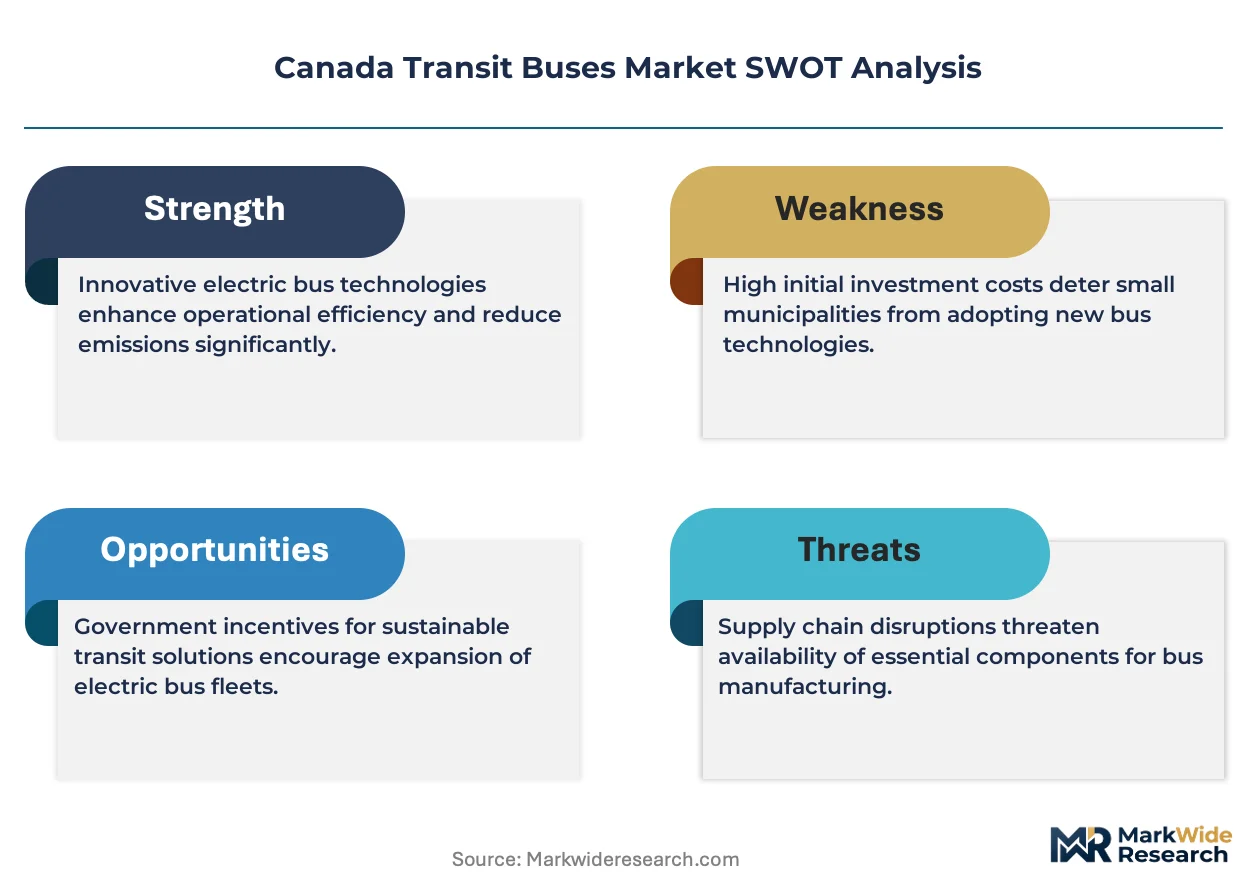
Federal zero-emission vehicle mandates are compressing procurement timelines across Canadian transit authorities, forcing rapid fleet turnover decisions before charging infrastructure and grid capacity fully mature. This regulatory acceleration is fragmenting traditional diesel-electric hybrid transition pathways that operators had planned through the late 2020s.
Growth Catalysts
- Federal ZEV Sales Mandate:Ottawa's regulated phase-out of fossil-fuel bus procurement creates binding demand floors for battery-electric platforms at TransLink, TTC, and STM.
- Grid Decarbonization:Ontario's nuclear baseload and British Columbia's hydroelectric surplus deliver carbon-free electrons that improve lifecycle emissions accounting for electric fleet operators.
- Campus Shuttle Electrification:University end-users in Waterloo and Burnaby are deploying mid-size electric shuttles to meet institutional carbon neutrality commitments ahead of municipal timelines.
Market Restraints
- Battery Cell Supply Concentration:Cathode active material refining concentrates in China, exposing Canadian integrators to tariff and logistics volatility for lithium-iron-phosphate packs.
- Charging Infrastructure Capex:Depot electrification requires substation upgrades and on-site energy storage that strain municipal capital budgets beyond vehicle acquisition costs.
- Winter Range Derating:Heating loads in prairie provinces reduce effective battery range by 25-40 percent, forcing larger pack configurations that increase curb weight and axle loading.
Strategic Opportunities
- Quebec Manufacturing Expansion:The province's lithium refining investments and skilled aerospace workforce create conditions for battery pack assembly and electric axle production serving eastern Canadian demand.
- Vehicle-to-Grid Integration:Bidirectional charging protocols enable transit depots to provide grid stabilization services, unlocking revenue streams through provincial utility demand-response programs.
- Indigenous Transit Partnerships:Federal infrastructure commitments to remote First Nations communities create demand for ruggedized electric shuttles with extended-range configurations and off-grid charging.
Industry Challenges
- High-Voltage Technician Scarcity:Fleet maintenance divisions lack certified personnel for 600V+ battery management system diagnostics and thermal runaway containment protocols.
- Multi-Agency Certification Coordination:Transport Canada CMVSS approval, provincial CVSE operational permits, and utility interconnection agreements create sequential bottlenecks that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Transit Buses Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Battery Electric, Diesel, Hybrid, CNG Size: Standard, Articulated, Double-Decker, Mini Bus End User: Public Transport Authorities, Private Operators, Universities, Corporate Fleets Features: Low Floor, Wi-Fi Enabled, Accessibility Options, Real-Time Tracking |
| Companies Covered | GreenPower Motor Company, Siemens, New Flyer Industries, PowerON Energy Solutions, ChargePoint, Nova Bus, ABB, The Mobility House, Cummins Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Transit Buses Market Trends and Innovations
Battery chemistry diversification and thermal management advances are altering competitive positioning among Canadian transit bus suppliers. Platform modularity now enables faster drivetrain swaps between routes with varying topography and climate exposure.
Solid-state battery prototyping is fragmenting technology roadmaps at Winnipeg and Vancouver manufacturing facilities. Transit authorities in Calgary and Edmonton are evaluating silicon-anode cells for improved energy density in articulated configurations. This chemistry transition is fragmenting supplier relationships as cell vendors compete for validation contracts with domestic integrators.
Health Canada and PMRA are tightening interior material emissions standards for flame-retardant composites in passenger compartments. Bus builders must reformulate seating and panel substrates to meet simultaneous fire safety and volatile organic compound thresholds. Ontario-based manufacturers are accelerating third-party certification timelines to secure 2027 fleet renewal awards.
Service contracting is displacing traditional capital procurement at secondary Canadian municipalities. Private operators in London, Halifax, and Saskatoon are assuming fleet ownership risk through availability-based agreements that bundle vehicles, charging infrastructure, and maintenance. This model transfers battery degradation exposure from public agencies to contractor balance sheets.
Canada Transit Buses Market Segmentation
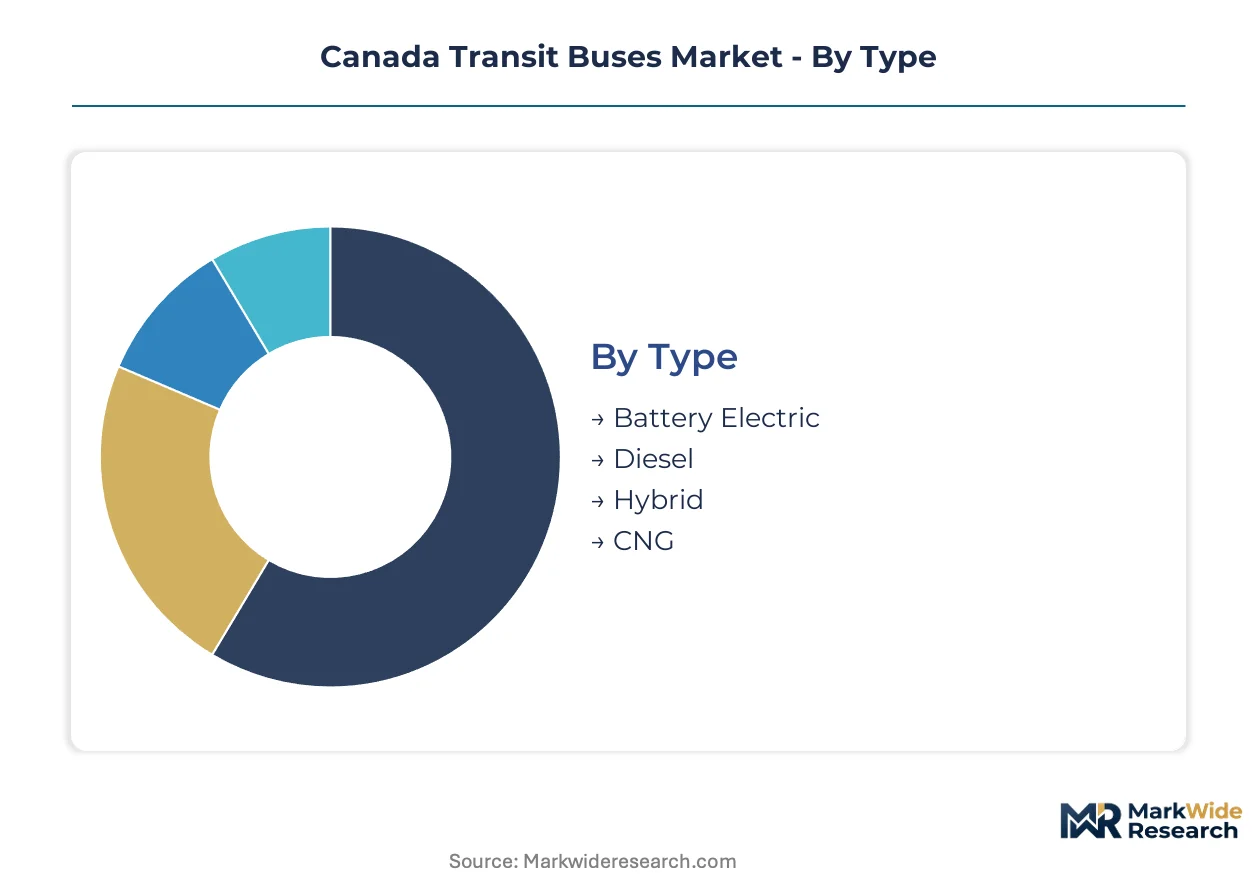
Segmentation in the Canada transit buses market reveals how procurement mandates and operational requirements reshape supplier priorities. Battery chemistry choices, vehicle dimensions, and end-use specifications determine contract eligibility for TransLink, TTC, and STM fleet renewals.
Type:
Battery electric configurations command the widest margin spreads as federal ZEV mandates eliminate fossil-fuel alternatives from public procurement pipelines.
- Battery Electric:Lithium-iron-phosphate and nickel-manganese-cobalt cell architectures power zero-emission platforms. TransLink and TTC deployments in Vancouver and Toronto concentrate demand as provincial grids decarbonize through Ontario nuclear baseload and British Columbia hydroelectric surplus.
- Diesel:Compression-ignition engines with selective catalytic reduction dominate existing fleet bases in prairie provinces. Calgary Transit and Edmonton ETS maintenance divisions preserve these vehicles through extended rebuild cycles while charging infrastructure matures.
- Hybrid:Diesel-electric parallel systems with regenerative braking capture transitional procurement in secondary municipalities. Saskatoon and London transit authorities deploy these where full electrification capex exceeds capital budgets.
- CNG:Compressed natural gas combustion suits regions with established fuelling infrastructure. Winnipeg and Ottawa fleets utilize these for emissions reduction where battery range limitations constrain route electrification.
The dominant share belongs to Battery Electric, while Hybrid is closing the gap fastest through transitional fleet strategies in mid-size cities.
Size:
Vehicle dimensions determine route eligibility and per-unit revenue recognition across Canadian transit authorities with varying ridership densities.
- Standard:Single-chassis 12-meter configurations with two or three axles form the procurement baseline. Montreal STM and Toronto TTC high-frequency corridors absorb volume production from Winnipeg and Quebec manufacturing facilities.
- Articulated:18-meter hinge-connected designs with third-axle load distribution maximize passenger throughput. Calgary and Vancouver B-Line rapid transit routes specify these for 200+ passenger capacity during peak periods.
- Double-Decker:Bi-level passenger compartments with low-floor entry modifications serve sightseeing and select commuter markets. Victoria and Niagara regional operators deploy these for tourism route differentiation.
- Mini Bus:Sub-9-meter cutaway chassis configurations with gross vehicle weights below 12,000 kg access restricted roadways. University of Waterloo and Simon Fraser University shuttle services concentrate demand for campus circulation.
Standard vehicles retain the largest installed base, though Articulated configurations are expanding most quickly through rapid transit corridor investments.
End User:
Ownership structures differentiate capital risk allocation between public agencies and private fleet operators across Canadian urban hierarchies.
- Public Transport Authorities:Crown corporations and municipal departments with regulated farebox recovery ratios. TransLink, STM, and TTC procurement offices issue multi-year fleet replacement tenders with domestic content requirements.
- Private Operators:Contracted service providers assuming vehicle ownership through availability-based agreements. Halifax Transit and London Transit Commission outsource routes to private fleet managers transferring battery degradation risk.
- Universities:Institutional procurement departments with carbon neutrality commitments preceding municipal timelines. University of British Columbia and McGill University sustainability offices specify mid-size electric shuttles for campus mobility.
- Corporate Fleets:Employer-sponsored employee transportation with dedicated route structures. Resource sector camps in Alberta and remote mining operations deploy ruggedized configurations for fly-in workforce logistics.
Public Transport Authorities control the dominant procurement volume, while Private Operators are gaining share fastest through service contracting displacement of direct capital purchase.
Features:
Specification tiers separate base compliance configurations from premium offerings commanding higher per-unit pricing.
- Low Floor:Kneeling suspension and ramp-equipped entry systems meeting Transport Canada accessibility mandates. All new procurements from TransLink and STM require full-floor wheelchair accommodation.
- Wi-Fi Enabled:Onboard cellular backhaul and passenger connectivity infrastructure. GO Transit commuter coaches and selected TTC express routes incorporate these as ridership retention tools.
- Accessibility Options:Audio-visual stop announcements, priority seating configurations, and tactile guidance systems. Ontario AODA and British Columbia accessibility regulations mandate these across all fleet replacements.
- Real-Time Tracking:GPS-based location transmission to passenger information systems and operational control centers. Calgary Transit and Edmonton ETS integrate these with open data APIs for third-party app developers.
Low Floor specifications represent universal procurement requirements, while Real-Time Tracking is climbing the fastest as open data mandates expand across provincial transit funding agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario commands premium pricing for battery-electric configurations while prairie provinces absorb higher total cost of ownership from winter range derating. This asymmetry concentrates manufacturing investment in Quebec and Ontario while service contracting expands in secondary markets.
Ontario
Toronto Transit Commission electrification mandates and GO Transit commuter rail integration drive fleet renewal volumes. Transport Canada CMVSS standards and Ontario MTO emissions enforcement create dual compliance layers for domestic assemblers. Windsor-Toronto corridor manufacturing facilities anchor New Flyer Industries and Nova Bus production for eastern Canadian demand.
Quebec
Montreal STM articulated bus procurement and provincial carbon reduction frameworks accelerate zero-emission deployment. Health Canada and PMRA interior material standards impose reformulation requirements on seating and panel suppliers. Quebec City and Saint-Eustache production sites leverage provincial lithium refining investments for battery pack assembly serving Maritime provinces.
British Columbia
TransLink rapid transit expansion and Vancouver B-Line corridor electrification concentrate demand for high-capacity configurations. British Columbia CVSE operational certification and provincial ZEV procurement mandates eliminate fossil-fuel alternatives from public tenders. Burnaby and Vancouver manufacturing facilities exploit hydroelectric grid surplus for favorable lifecycle emissions accounting.
Alberta
Calgary Transit and Edmonton ETS fleet managers preserve diesel-electric hybrid pathways where charging infrastructure capex exceeds capital budgets. Provincial utility demand-response programs and federal ZEV mandate timelines create procurement uncertainty. Calgary manufacturing partnerships evaluate silicon-anode validation for prairie winter range requirements.
Atlantic Canada
Halifax Transit service contracting models transfer battery degradation risk to private operators through availability-based agreements. Federal infrastructure commitments to remote First Nations communities generate demand for ruggedized extended-range shuttles. Moncton and Halifax procurement offices prioritize total cost of ownership over upfront capital expenditure in fleet decisions.
Canada Transit Buses Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Canadian transit bus manufacturing tier. Full-system integrators with in-house electric platforms capture large-volume contracts from TransLink and TTC, while component specialists and charging infrastructure providers fragment the upstream supply layer. Three archetypes dominate: domestic chassis assemblers with captive battery partnerships, purpose-built electric specialists occupying mid-size niches, and European multinationals leveraging global validation programs. Competitive moves concentrate on Quebec manufacturing expansion and vehicle-to-grid integration protocols.
Among domestic assemblers, New Flyer Industries and Nova Bus exemplify full-system integrators with established provincial procurement relationships. GreenPower Motor Company occupies the purpose-built electric specialist tier, representing mid-size and shuttle configuration providers targeting university and corporate campus operators. Siemens and ABB anchor the European multinational segment, leveraging global electrification portfolios for charging infrastructure and grid integration components.
| Leading Market Players |
|---|
| GreenPower Motor Company |
| Siemens |
| New Flyer Industries |
| PowerON Energy Solutions |
| ChargePoint |
| Nova Bus |
| ABB |
| The Mobility House |
| Cummins Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between TransLink and New Flyer Industries lock in battery-electric platform supply while anchoring unit price visibility across multi-year fleet renewal cycles. These arrangements transfer cell cost volatility from transit authorities to integrators through fixed-price chassis deliveries indexed to lithium-iron-phosphate cathode supply benchmarks.
Pricing Analysis
Configured-to-order pricing for articulated battery-electric configurations commands a substantial premium over standard 12-meter single-chassis procurement. Three-tier pricing structure across premium, standard, and economy levels segments by drivetrain complexity, with silicon-anode validation and vehicle-to-grid capability commanding top-tier positioning. Pricing pressure stems from cathode active material refining concentration in China exposing Canadian assemblers to tariff volatility. Private operators in secondary municipalities exhibit highest price sensitivity through total-cost-of-ownership evaluations, while TTC and STM procurement offices prioritize lifecycle emissions accounting over upfront capital expenditure.
Supply Chain Analysis
Extended lead times for lithium-iron-phosphate cell deliveries stretch 18-24 months from order placement to pack integration at Winnipeg and Quebec manufacturing facilities. Cathode active material refining concentrates in China, with South Korean and Japanese cell vendors supplying secondary volumes to Canadian integrators. Raw material dependencies span lithium carbonate from Chilean and Australian spodumene operations, nickel from Indonesian laterite projects, and copper busbar stock from domestic smelters. Single-source vulnerability in Chinese cathode processing exposes assemblers to export restriction risk. Distribution runs through provincial transit authority procurement offices with domestic content requirements favoring Quebec and Ontario manufacturing footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified high-voltage technician scarcity constrains fleet maintenance scaling across Canadian transit authorities, creating a capability bottleneck that threatens electrification timelines. This skills gap amplifies competitive advantage for integrators with captive service networks and training infrastructure.
For Market Incumbents: Fortify Quebec manufacturing capacity through lithium refining co-location and electric axle assembly investments. Secure provincial utility demand-response partnerships to embed vehicle-to-grid revenue streams that offset battery degradation cost exposure. Defend against purpose-built electric specialists by accelerating silicon-anode validation for prairie winter range requirements. For New Entrants and Emerging Players: Anchor in Indigenous transit partnerships for ruggedized extended-range shuttle configurations serving remote First Nations communities. Campus electrification at Waterloo and Burnaby universities offers the most penetrable white-space target with carbon neutrality commitments preceding municipal timelines. Pursue availability-based service contracting models that transfer battery degradation risk from public agencies to private balance sheets. For Investors and Strategic Acquirers: Capital is best deployed toward component specialists with captive battery management system IP and provincial utility interlock relationships. Long-term viability across the analysis window favors suppliers with backward integration into thermal management hardware and high-voltage safety certification infrastructure. Monitor federal ZEV mandate enforcement rigor as the primary inflection signal for procurement volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Quebec Manufacturing Expansion | Provincial lithium refining investments enable domestic cathode processing for eastern Canadian demand. |
| Vehicle-to-Grid Integration | Bidirectional charging protocols unlock revenue streams through British Columbia and Ontario utility demand-response programs. |
| Solid-State Battery Validation | Silicon-anode prototyping at Calgary and Edmonton facilities addresses prairie winter range derating challenges. |
| Indigenous Transit Partnerships | Federal infrastructure commitments create demand for ruggedized electric shuttles with off-grid charging configurations. |
| High-Voltage Technician Certification | Training infrastructure investments alleviate maintenance bottlenecks threatening fleet electrification timelines at TTC and TransLink. |
Research Methodology
Operator-level perspectives from transit authority fleet managers, provincial procurement officers, utility demand-response coordinators, and high-voltage maintenance technicians anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation against Transport Canada CMVSS filings, Ontario MTO emissions enforcement records, British Columbia CVSE operational certification databases, and provincial transit funding agreement disclosures. Bottom-up unit deployment estimates from TransLink, TTC, STM, and Calgary Transit procurement pipelines triangulated against top-down market sizing from federal ZEV mandate compliance schedules.
Sensitivity analysis around battery cell cost trajectories, charging infrastructure capex assumptions, and winter range derating coefficients shaped the forecast framework across the analysis window. Segmentation dimensions modeled include propulsion architecture, vehicle size category, end-user ownership structure, and provincial regulatory cluster. CAGRs derived from deployment pipeline aggregation weighted by fleet renewal timing and grid interconnection readiness. Industry-specific inputs incorporated Ontario nuclear baseload capacity expansion and British Columbia hydroelectric surplus availability for lifecycle emissions accounting.
Decision-makers should treat outputs as directional under assumptions of federal ZEV mandate enforcement continuity and provincial electricity grid capacity commitments; material deviation in either would warrant model refresh. Forecasts reflect these base conditions alongside cathode material supply stability and certified technician training program scaling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Trolley Bus Market
Buses
Airport Shuttle Bus Market
Buses
Bus Chassis Market
Buses
Electric Intercity Bus Market
Buses
Bus Flooring Market
Buses
Bus Bellows Market
Buses
Airport Bus Market
Buses
Luxury Bus Market
Buses
Bus Transmission System Market
Buses
Bus Rental Market
Buses
Africa Electric Bus Market
Buses
Solar Bus Market
Buses
Intercity Bus Travel Market
Buses
Global Bus Market
Buses
Canada School Bus Market
Buses
City Bus Low-Floor Axle Systems Market