
 UK Automotive Parts Aluminium Die Casting Market | 2026-2036
UK Automotive Parts Aluminium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
UK Automotive Parts Aluminium Die Casting Market Analytics
Competitive Dynamics
The capital-intensity divergence between high-pressure die casting specialists and general foundries is redrawing competitive boundaries across the UK supply base. Georg Fischer Limited leverages its Swiss-parented tooling expertise to sustain premium positioning in complex structural components. Haworth Castings Limited anchors its reputation on gravity and sand-casting flexibility for low-volume OEM programmes. Dynacast competes through its global hot-chamber technology platform, extending rapid-cycle production capabilities to UK-based tier-1 customers.
Technical Definition and Segment Structure
Automotive parts aluminium die casting is a metal-forming process wherein molten aluminium alloys—typically A380, A383, or AlSi10MgFe—are injected under high pressure into hardened steel moulds to produce near-net-shape components with wall thicknesses below 3mm. This process serves the primary industrial purpose of mass-producing lightweight, dimensionally precise parts that replace heavier ferrous castings or fabricated assemblies in vehicle architectures. Structural components dominate current output volumes, reflecting OEM demand for crash-worthy aluminium subframes and body-in-white elements, while electric vehicle applications represent the fastest-expanding segment as battery tray castings and motor housings absorb new capacity. Engine blocks retain mature, high-volume status but face long-term displacement as powertrain electrification accelerates.
Regulatory Environment and Outlook
The UK Department for Transport's zero-emission vehicle mandate and the EU-originated REACH regulation on chemical substances in manufacturing processes jointly shape product standards and market access for domestic die casters. BSI standards for aluminium alloy specifications and the Health and Safety Executive's control of substances hazardous to health regulations govern foundry operations and workplace exposure limits. Stakeholders must monitor how the UK's post-EU conformity assessment regime evolves, as divergent technical requirements from the EU CE marking framework could fragment certification costs for exporters serving continental OEM assembly plants.
Market Dynamics
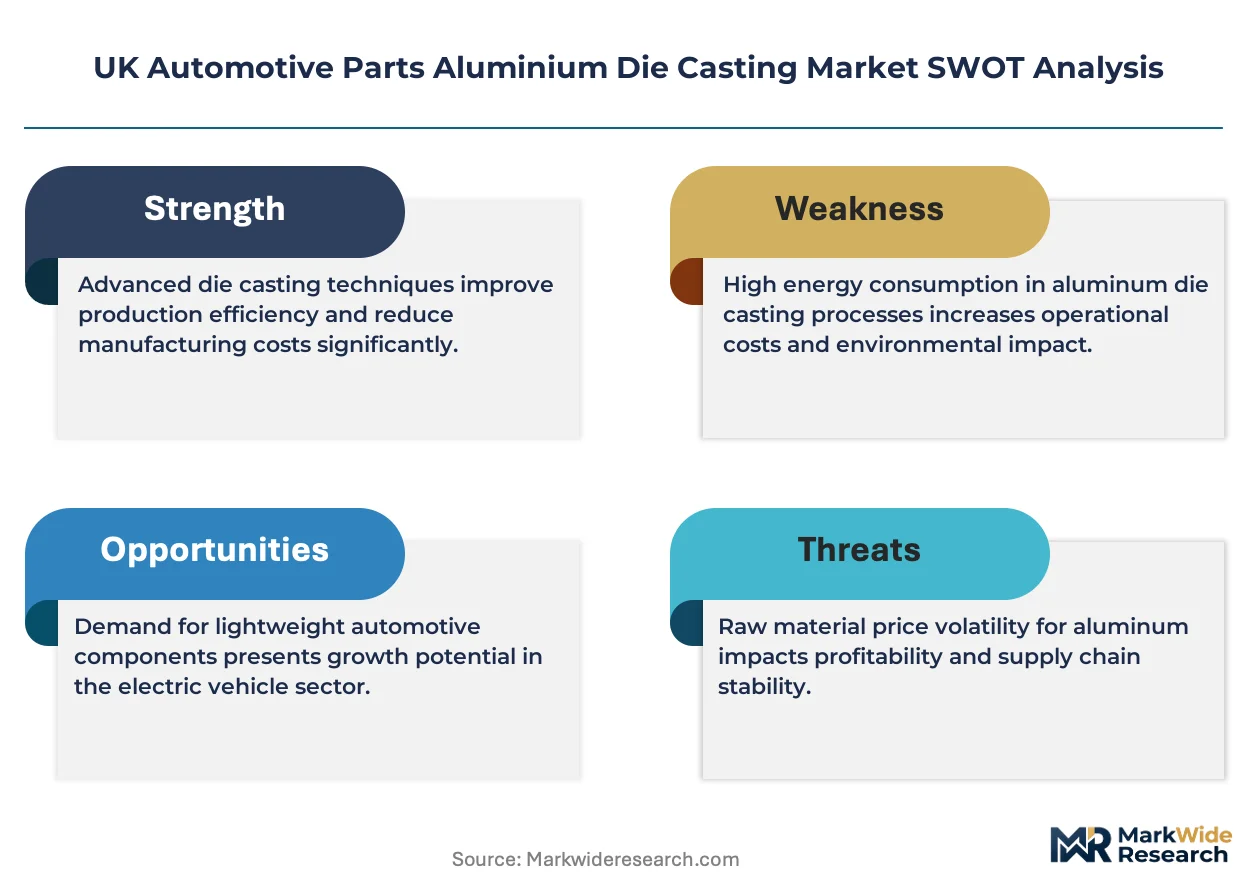
The UK's 2030 internal combustion engine sales ban is forcing die casting capacity toward battery enclosure and motor housing production, compressing the transition timeline for traditional engine block manufacturers.
Growth Catalysts
- Zero-Emission Vehicle Mandate:The UK Department for Transport's binding annual targets for ZEV sales create guaranteed offtake for aluminium battery tray castings through 2035.
- Powertrain Lightweighting:OEMs pursuing 15-20% mass reduction in electric vehicle architectures specify thin-wall aluminium motor housings over steel fabricated alternatives.
- West Midlands Cluster Density:Tier-1 supplier concentration around Birmingham and Coventry reduces logistics costs and enables just-in-sequence delivery to JLR and Nissan Sunderland.
Market Restraints
- Primary Aluminium Price Volatility:London Metal Exchange aluminium pricing swings compress foundry margins on fixed-price OEM contracts.
- Tooling Lead Times:Hardened steel die fabrication from specialist suppliers extends 18-24 weeks, constraining programme launch velocity.
- REACH Compliance Burden:ECHA chemical substance restrictions on process additives increase formulation costs and disqualify legacy foundry chemistry.
Strategic Opportunities
- Battery Enclosure Integration:Structural battery tray castings combining crash protection and thermal management open higher-value product tiers for HPDC specialists.
- Recycled Alloy Premium:Closed-loop aluminium scrap recovery from machining operations supports OEM carbon accounting and circularity commitments.
- Scotland Renewables Manufacturing:Emerging EV supply chain development around Glasgow creates geographic diversification beyond the West Midlands.
Industry Challenges
- Die Maintenance Skill Shortage:Experienced toolroom technicians capable of welding and refinishing thermal-fatigued die surfaces are retiring faster than apprentices replace them.
- Multi-Material Joining Complexity:Aluminium cast-to-steel body-in-white integration requires new adhesive and mechanical fastening process development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Automotive Parts Aluminium Die Casting Market |
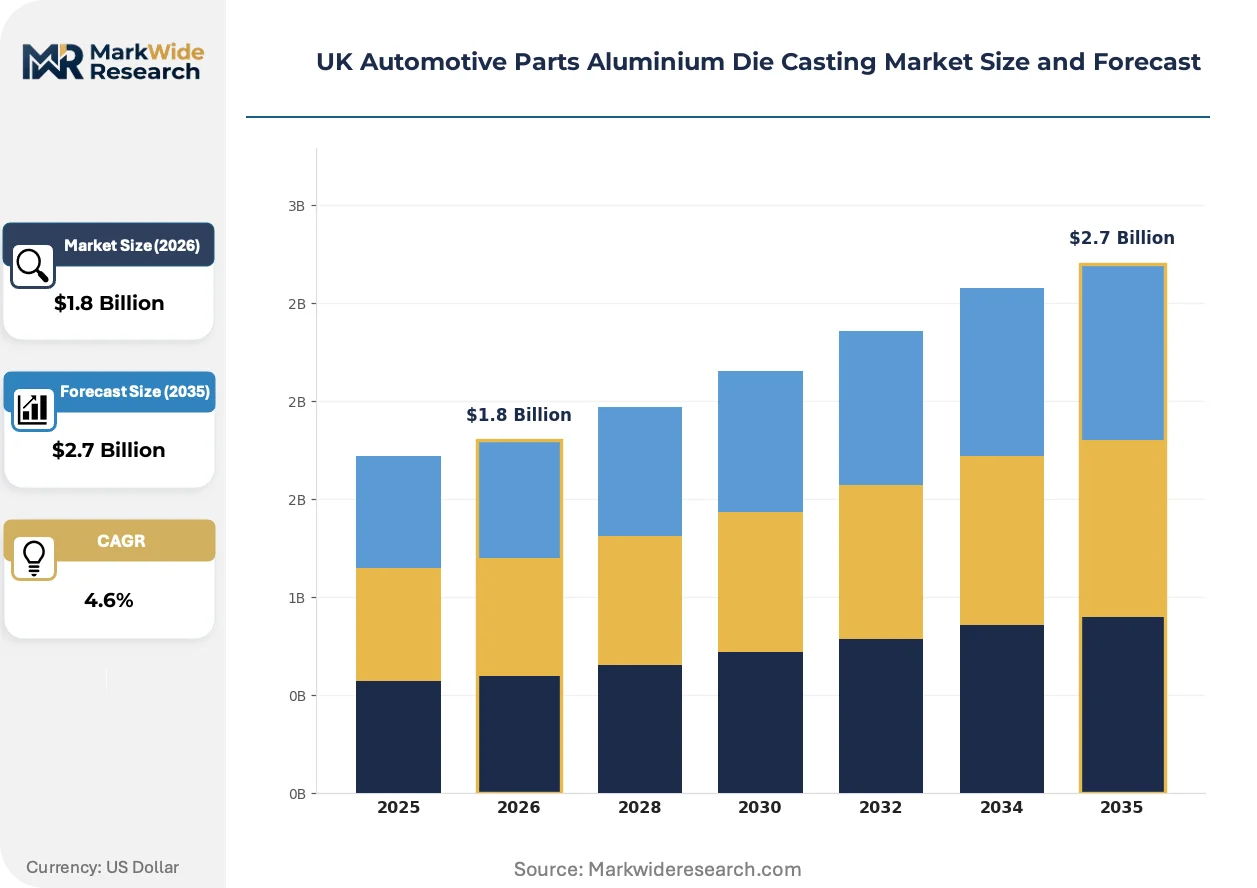
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Blocks, Transmission Housings, Structural Components, Chassis Parts Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Aftermarket Manufacturing Stage: Die Casting, Finishing, Machining, Assembly End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Georg Fischer Limited, Haworth Castings Limited, Amtek Group, Dynacast, BSC Die Casting & Finishing Ltd, Buvo Castings, Kemlows Diecasting Products Ltd, Harrison Castings Limited, Carlton Die Castings Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Automotive Parts Aluminium Die Casting Market Evolving Landscape
Process automation and alloy formulation advances are reshaping competitive capability requirements, while regulatory deadlines compress implementation windows across the UK supply base.
Large-structural high-pressure die casting is bifurcating the supplier base into two capability tiers. Giga-press technology enabling single-piece rear underbody castings above 6,000 tonnes clamping force demands capital commitments beyond mid-tier foundries. OEMs adopting Tesla-style megacasting architectures source from a shrinking pool of qualified suppliers, while generalists retreat to smaller powertrain components.
REACH chemical substance restrictions are tightening process chemistry standards. ECHA's 2023 update to restricted substance lists limits certain release agents and die lubricants, forcing reformulation of established foundry practices. Die casters serving continental OEM assembly plants face dual compliance overhead as UKCA marking divergence from CE frameworks proceeds.
Buyer consolidation among tier-1 systems integrators is compressing supplier negotiation leverage. Continental, Bosch, and Vitesco have reduced their UK aluminium die casting vendor panels by 30-40% since 2022, concentrating volume with remaining qualified sources. Long-term agreements now specify minimum recycled content thresholds and Scope 3 emissions reporting, raising qualification barriers for smaller foundries.
UK Automotive Parts Aluminium Die Casting Market Segmentation
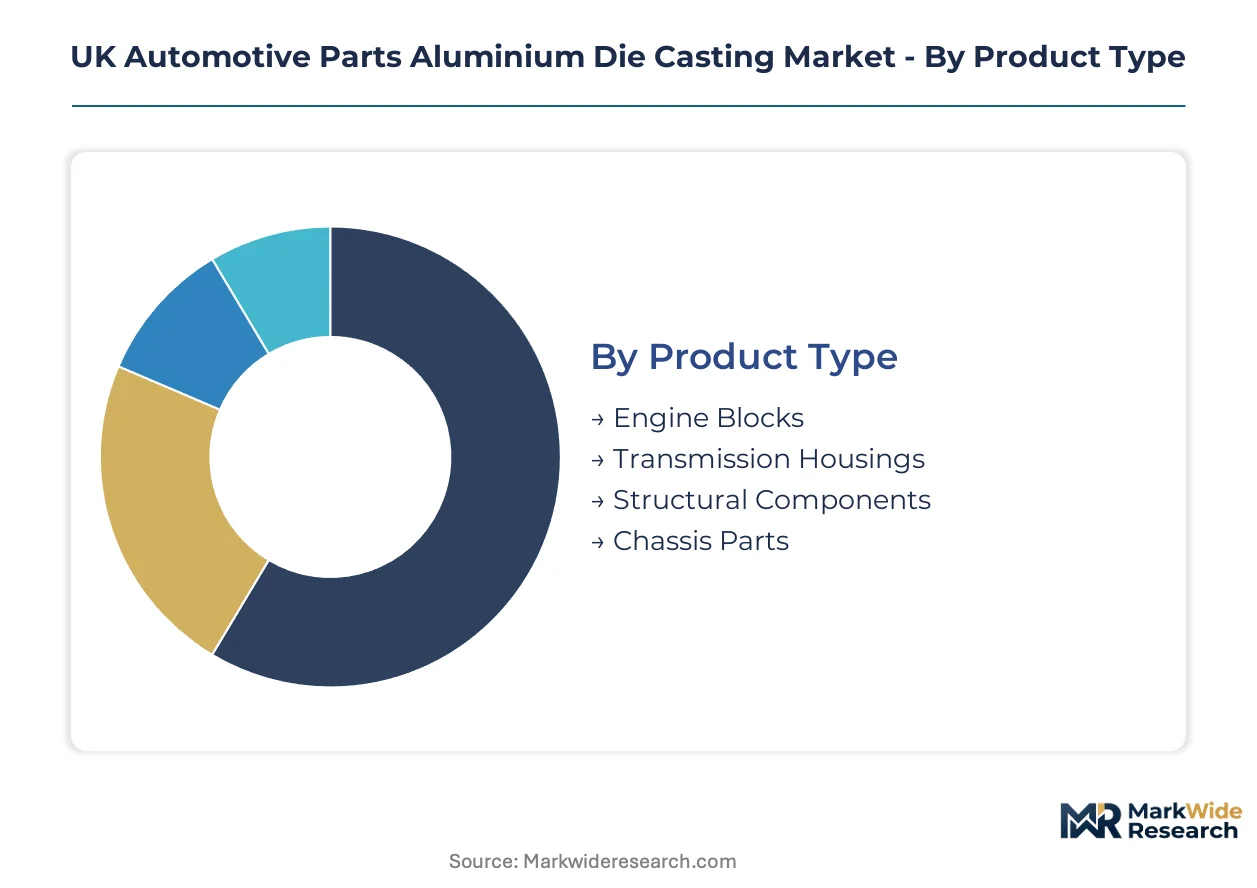
Die casting suppliers in the UK must align capacity investments with divergent segment trajectories. Product mix decisions determine exposure to ICE phase-out risks versus EV expansion rewards.
Product Type:
Structural components face the strongest substitution pressure from steel stampings and carbon fibre composites in premium vehicle architectures.
- Engine Blocks:High-pressure die cast A380 aluminium cylinders with integrated coolant jackets serve remaining ICE production at JLR and Nissan Sunderland. Demand concentrates in legacy SUV and light commercial vehicle programmes with extended production timelines.
- Transmission Housings:Complex multi-slide castings for dual-clutch and automatic transmissions retain volume through hybrid powertrain adaptation. West Midlands suppliers report sustained orders from tier-1 integrators serving European OEM assembly plants.
- Structural Components:Crash management systems and subframe castings.
- Chassis Parts:Steering knuckles and control arms.
Engine blocks retain volume leadership; structural components hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive OEM programmes from price-sensitive aftermarket replacement cycles.
- Electric Vehicles:Battery tray castings and motor housings in AlSi10MgFe alloys demand 6,000-tonne giga-press capabilities. Birmingham-based HPDC specialists are securing multi-year contracts with UK EV startups and continental battery manufacturers.
- Passenger Vehicles:Body-in-white and closure castings for mass-market OEMs.
- Commercial Vehicles:Heavy-duty transmission cases and axle housings.
- Aftermarket:Replacement engine components and crash repair parts.
Passenger vehicles retain volume leadership; electric vehicles hold the steepest expansion curve.
Manufacturing Stage:
Process maturity varies sharply across the value chain, with downstream stages offering margin protection against raw material volatility.
- Die Casting:Molten metal injection under 1,000-4,000 bar pressure forms near-net-shape components. Coventry suppliers dominate this stage through accumulated tooling expertise and thermal management know-how.
- Finishing:Shot blasting, deburring, and surface preparation.
- Machining:CNC finishing to tight tolerances.
- Assembly:Component integration and sub-system build.
Die casting retains volume leadership; machining holds the steepest expansion curve.
End User:
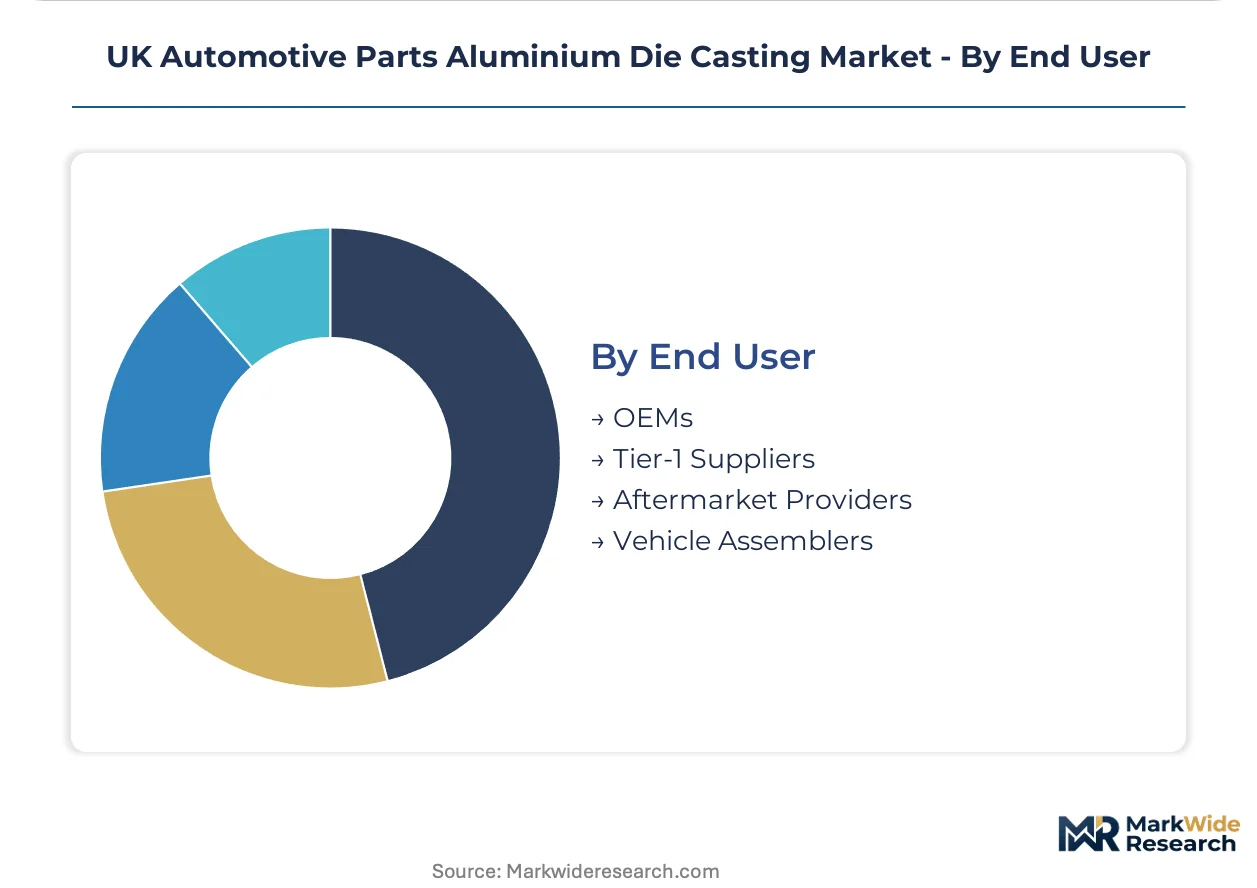
Customer concentration risk concentrates in tier-1 supplier panels, where buyer consolidation has reduced vendor counts by 30-40% since 2022.
- OEMs:JLR, Nissan, and BMW Mini specify direct-sourced structural castings for flagship platforms. Volume commitments span 5-7 year model cycles with stringent recycled content mandates.
- Tier-1 Suppliers:Continental, Bosch, and Vitesco aggregate die casting demand for powertrain and chassis systems.
- Aftermarket Providers:Independent distributors and repair networks.
- Vehicle Assemblers:Contract manufacturers and specialist builders.
Tier-1 suppliers retain volume leadership; OEMs hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the West Midlands automotive cluster while Scottish suppliers compete on renewable energy credentials. The geographic asymmetry reflects divergent infrastructure maturity and OEM proximity across UK sub-regions.
West Midlands
JLR's Castle Bromwich and Solihull plants anchor demand for structural battery tray castings and motor housings. The Health and Safety Executive's workplace exposure limits govern foundry operations across Birmingham and Coventry. Tier-1 supplier density around these cities enables just-in-sequence delivery to Nissan Sunderland and continental OEM assembly plants.
Scotland
Glasgow's emerging EV supply chain development attracts die casting investment linked to offshore wind manufacturing. The Scottish Government's manufacturing action plan funds industrial decarbonisation for foundries transitioning from ICE components. Suppliers in the Central Belt region leverage renewable electricity contracts to meet OEM Scope 3 emissions reporting requirements.
North East England
Nissan Sunderland's EV36Zero project sustains transmission housing demand through hybrid powertrain adaptation. The Department for Transport's zero-emission vehicle mandate binds regional suppliers to annual ZEV sales targets. Washington and Sunderland industrial parks concentrate machining and finishing capacity for exported powertrain systems.
South East England
BMW Mini's Oxford plant specifies direct-sourced structural castings with stringent recycled content mandates. REACH compliance burdens from ECHA chemical substance restrictions affect formulation costs for process additives. Milton Keynes and Oxfordshire supplier parks serve premium vehicle architectures with complex multi-slide casting requirements.
Wales
Residual engine block production for light commercial vehicles extends foundry utilisation in South Wales. The UK Department for Transport's 2030 ICE sales ban compresses transition timelines for traditional manufacturers. Deeside and Ebbw Vale industrial zones retain gravity and sand-casting flexibility for low-volume OEM programmes.
UK Automotive Parts Aluminium Die Casting Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UK supply base. High-pressure die casting specialists command premium positioning through giga-press capabilities above 6,000 tonnes clamping force, while general foundries compete on programme flexibility and lower capital intensity. The market structures around three archetypes: Swiss-parented tooling experts, UK heritage gravity casters, and global hot-chamber platform operators. Dominant competitive moves include capacity reallocation toward battery enclosure production and strategic partnerships with tier-1 systems integrators.
Within the premium-tier vector, Georg Fischer Limited occupies a position exemplifying Swiss-parented tooling expertise applied to complex structural components. Haworth Castings Limited and Dynacast represent contrasting archetypes—UK heritage flexibility versus global platform scale—each anchoring distinct competitive positions in the supplier hierarchy. These three entities collectively illustrate how capital-intensity divergence redraws competitive boundaries across the UK die casting base.
| Leading Market Players |
|---|
| Georg Fischer Limited |
| Haworth Castings Limited |
| Amtek Group |
| Dynacast |
| BSC Die Casting & Finishing Ltd |
| Buvo Castings |
| Kemlows Diecasting Products Ltd |
| Harrison Castings Limited |
| Carlton Die Castings Ltd |
| Others |
Value Network & Pricing Analysis
Giga-press capacity utilisation above 6,000 tonnes clamping force concentrates pricing power among Birmingham and Coventry specialists serving JLR and continental OEM assembly plants. This scale threshold stratifies the UK supply base between premium-tier structural component suppliers and general foundries competing on programme flexibility.
Pricing Analysis
The customization-premium spread separates configured-to-order battery tray castings from standard transmission housings. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with OEM direct-sourced structural components commanding 15-25% premiums over tier-1 aggregated supply. Cost compression in standard-grade engine blocks is intensifying because fixed-price contracts expose foundries to London Metal Exchange aluminium volatility. Aftermarket replacement parts exhibit highest price sensitivity; OEM direct programmes show lowest.
Supply Chain Analysis
Just-in-sequence delivery preferences dominate West Midlands OEM supply, contrasting with strategic stockpiling of primary aluminium ingot by foundries hedging against commodity swings. Raw material supply draws from Norway, Iceland, and UAE smelters for primary aluminium; secondary scrap feeds from UK machining operations. Single-source vulnerability concentrates in hardened steel die fabrication from specialist German and Italian tooling suppliers. Distribution runs through tier-1 systems integrator consolidation panels that have reduced vendor counts substantially since 2022.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK die casting sector faces high-growth disruption as the 2030 ICE sales ban forces capital reallocation toward giga-press battery enclosure capacity. This regulatory inflection compresses transition timelines and rewards early movers in EV structural casting qualifications.
For Market Incumbents: Shield core margins by securing long-term alloy supply agreements with Norwegian primary producers and accelerating closed-loop scrap recovery systems. The threat of tier-1 buyer consolidation demands backward integration into CNC machining to capture downstream value and meet OEM Scope 3 reporting requirements. For New Entrants and Emerging Players: Anchor in Scotland's emerging EV supply chain around Glasgow, where renewable electricity contracts attract OEM carbon accounting mandates. The most penetrable segment lies in secondary alloy processing for battery tray castings; target qualification partnerships with UK EV startups bypassing established tier-1 panels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among HPDC specialists with giga-press qualifications and multi-year OEM platform contracts. Long-term viability hinges on exposure to EV architecture share gains rather than residual ICE volume. Acquisition targets should display thermal management tooling expertise and REACH-compliant process chemistry. Watch for inflection when continental OEMs accelerate UK battery plant localisation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Giga-Press Capacity Installation | 6,000-tonne clamping force capability unlocks single-piece rear underbody casting contracts with JLR and continental EV platforms. |
| Closed-Loop Scrap Recovery | Machining swarf recapture supports OEM circularity commitments and insulates margin from primary aluminium price swings. |
| REACH Process Chemistry Reformulation | ECHA-compliant release agent substitution maintains continental market access amid UKCA-CE marking divergence risks. |
| Tier-1 Systems Integrator Partnership | Continental and Vitesco panel consolidation concentrates volume with qualified sources holding multi-year platform contracts. |
| Scotland Manufacturing Footprint | Glasgow renewable energy access attracts battery manufacturer co-location and diversifies geographic risk beyond West Midlands. |
Research Methodology
Operator-level perspectives from HPDC plant managers, tier-1 supplier procurement leads, OEM platform engineers, and aftermarket distribution heads anchored the qualitative base. Secondary validation drew from UK Department for Transport ZEV mandate filings, Health and Safety Executive foundry inspection records, ECHA restricted substance updates, and London Metal Exchange aluminium pricing archives. Bottom-up capacity assessments across West Midlands and Scottish production facilities triangulated against top-down OEM platform content estimates.
Sensitivity analysis tested forecast robustness across primary aluminium price bands, giga-press adoption rates, and ICE phase-out acceleration scenarios. Segmentation modeling spanned product type, propulsion architecture, manufacturing stage, and end-user tier across the projection horizon. CAGRs derived from installed capacity expansion timelines, OEM platform launch schedules, and alloy substitution elasticity in vehicle architectures. Industry-specific inputs included die maintenance technician availability indices and REACH compliance cost curves.
Decision-makers should treat outputs as directional under base assumptions of stable UK-EU trade arrangements and linear EV adoption curves; material deviation would warrant model refresh. Specific risk factors include abrupt ECHA substance restrictions disqualifying current process chemistry and continental OEM battery plant relocation decisions. Revision becomes warranted when primary aluminium price volatility crosses thresholds that trigger contract renegotiation clauses.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Electric Power Steering Market
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Japan Ball Bearing Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Cycloid Gear Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Global Fuel and Oil Filters Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Automotive Grease Market