
 Racing Motor Bike Seat Unit Market | 2026-2036
Racing Motor Bike Seat Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Racing Motor Bike Seat Unit Market Analytics
Italy is reshaping competitive dynamics in racing motorcycle seating as regional manufacturers expand carbon fiber molding capacity near Modena. Saddlemen leverages vertical integration into foam formulation and cover stitching to sustain margin control across North American distribution. LePera Seats anchors its position through deep specialization in Harley-Davidson performance platforms, while XPC Racing competes aggressively on weight reduction metrics for supersport applications.
A racing motor bike seat unit comprises a rigid base pan, energy-absorbing foam core, and weather-resistant cover assembly engineered to secure rider positioning during high-G cornering, braking, and acceleration events; units typically specify foam densities between 45-80 kg/m³ and incorporate anti-slip surfaces or heat-resistant materials to maintain tactile feedback across temperature extremes. Racing seat configurations currently dominate premium value pools as professional teams and track day enthusiasts prioritize mass reduction and biomechanical support over cost. Carbon fiber material adoption is accelerating fastest among performance-oriented segments, though leather coverings retain substantial share in cruiser and touring designs where tactile comfort outweighs gram-scale savings.
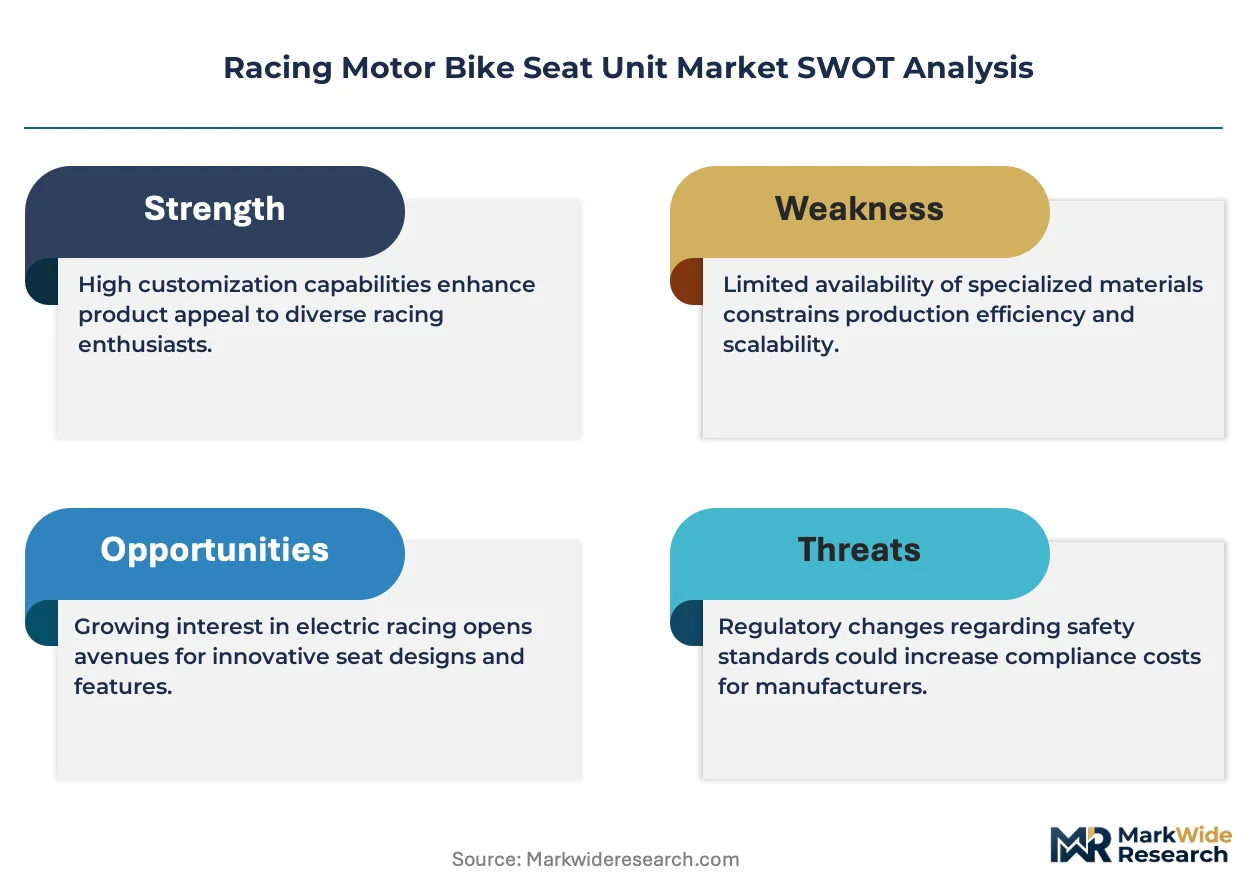
Federal Motor Vehicle Safety Standards administered by NHTSA govern structural integrity requirements for street-legal motorcycle seating sold in the United States, while EU type-approval frameworks under UNECE regulations establish harmonized crashworthiness and environmental durability criteria across member states. EPA compliance for foam blowing agents and REACH restrictions on certain chemical treatments in leather tanning processes are forcing material substitutions that elevate R&D overhead for seat unit producers. Stakeholders must monitor evolving e-mobility platform architectures, as electric racing motorcycles with fundamentally different weight distributions and thermal profiles will demand seat units with revised ergonomic geometries and cooling integration.
Market Dynamics
Carbon fiber composite adoption is compressing traditional manufacturing economics while EPA restrictions on foam blowing agents force material reformulation across the supply base. Track day participation growth is fragmenting demand between professional racing teams and amateur enthusiasts with divergent performance requirements.
Growth Catalysts
- REACH chemical compliance:European environmental frameworks are accelerating substitution toward bio-based polyurethane foams and water-based adhesives, creating first-mover advantages for compliant suppliers.
- Track day infrastructure expansion:Amateur racing circuits in Italy, Spain, and Germany are multiplying, generating aftermarket replacement cycles independent of OEM procurement.
- Carbon fiber molding automation:Resin transfer molding advances are reducing unit labor content and enabling mid-volume production runs previously uneconomical for composite seat pans.
Market Restraints
- Petrochemical input volatility:Polyol and isocyanate prices fluctuate with crude oil indices, compressing margin predictability for foam core producers without long-term supply contracts.
- Prepreg supply concentration:Aerospace-grade carbon fiber tow availability is dominated by Japanese and US suppliers, exposing racing seat manufacturers to allocation risk during capacity crunches.
- Leather tanning restrictions:Chrome VI limitations under REACH and state-level California Proposition 65 enforcement are eliminating traditional finishing processes for premium cover materials.
Strategic Opportunities
- Electric motorcycle thermal integration:Battery pack proximity in racing e-motorbikes is creating demand for seat units with embedded cooling channels and phase-change materials.
- Direct-to-rider digital channels:Configurator platforms allowing geometry customization and rapid fulfillment are capturing margin previously absorbed by distributor networks.
- Italian manufacturing cluster proximity:Dense supplier ecosystems near Modena and Bologna enable just-in-time carbon fiber layup and same-day cover stitching for premium orders.
Industry Challenges
- Composite technician scarcity:Hand layup and autoclave operation skills are concentrated among aging workforces in Emilia-Romagna, constraining output scaling.
- Homologation timeline compression:UNECE type-approval cycles for new foam formulations now exceed product development schedules for seasonal racing collections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Racing Motor Bike Seat Unit Market |
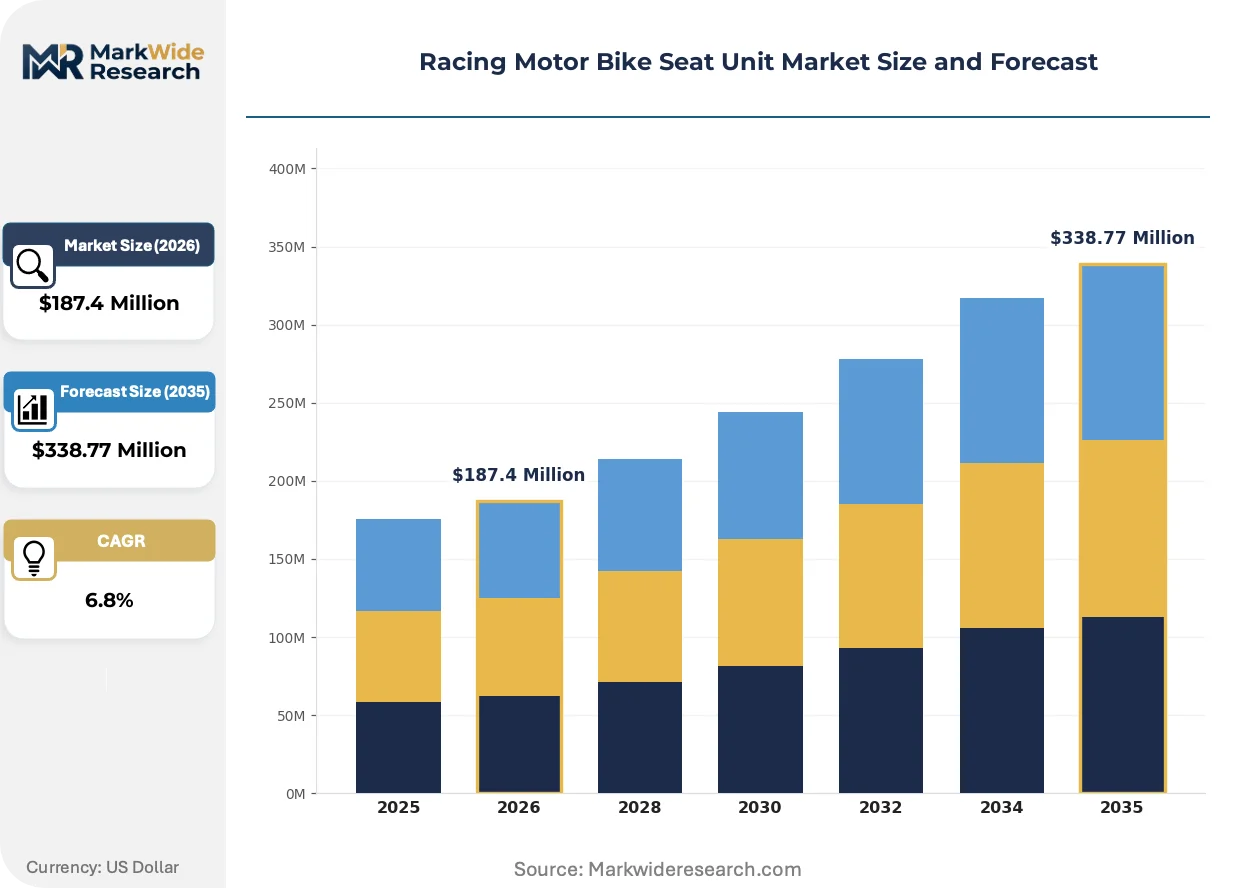
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Seat, Racing Seat, Custom Seat, Ergonomic Seat Material: Leather, Vinyl, Carbon Fiber, Foam Design: Sport, Adventure, Touring, Cruiser End User: Professional Racers, Casual Riders, Track Day Enthusiasts, Motorcycle Collectors |
| Companies Covered | Corbin Motorcycle Seats & Accessories, Saddlemen, Renazco Dual Sport Seats, LePera Seats, Mustang Seats, Sargent Cycle Products, XPC Racing, Motorsport Aftermarket Group, Danny Gray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Racing Motor Bike Seat Unit Market Evolving Landscape
Material science breakthroughs and regulatory chemistry restrictions are simultaneously enabling performance gains and forcing process reinvention across the value chain. Digital manufacturing tools are compressing the traditional design-to-track timeline.
Automated fiber placement for carbon fiber base pans is rendering obsolete hand-layup production for mid-volume racing applications. Supersport and Moto2 replica seat suppliers are adopting robotic tow placement to achieve ±0.1mm thickness tolerance and 15% weight reduction versus manual methods. This process consistency is rendering obsolete the batch-to-batch variability that previously required oversized safety margins in structural calculations.
EPA Significant New Alternatives Policy restrictions on hydrofluorocarbon blowing agents are mandating transition to hydro-olefin and water-blown foam systems. Formulation houses must recertify density and energy absorption specifications under revised chemistries, extending R&D cycles by 8-12 months. North American producers are responding fastest, leveraging prior automotive seating compliance investments to accelerate racing foam qualification.
Configurator-driven procurement is fragmenting traditional distributor relationships as track day enthusiasts specify custom geometries through manufacturer-direct portals. Amateur racing clubs in Germany and the UK are aggregating small-batch orders through digital platforms, bypassing wholesale channels that previously required minimum order quantities. This channel shift is most visible among supersport riders aged 25-40, who prioritize rapid turnaround over retail tactile evaluation.
Racing Motor Bike Seat Unit Market Segmentation
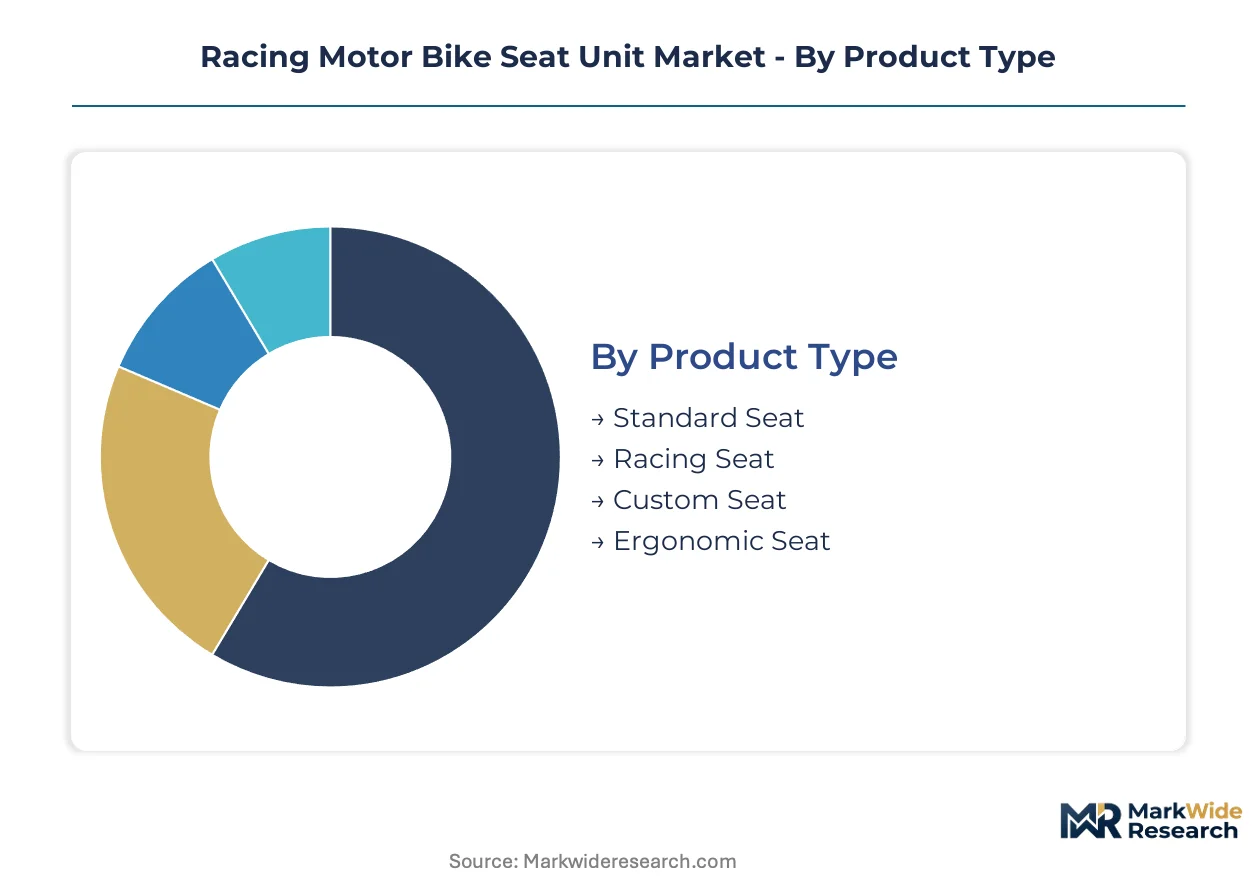
Racing motor bike seat unit demand fragments across performance tiers, material technologies, and rider experience levels. Segmentation reveals where margin pools concentrate and which specifications command premium positioning.
Product Type:
Use-case spectrum spans mass-market replacement through bespoke competition hardware.
- Racing Seat:Carbon fiber base pans with multi-density foam cores engineered for sub-1kg mass targets. MotoGP replica demand concentrates in Italy and Spain, where track day infrastructure expansion sustains premium aftermarket procurement independent of OEM cycles.
- Custom Seat:Configurator-driven geometry tailored to rider anthropometry and bike modifications. German and UK amateur racing clubs aggregate small-batch orders through direct-manufacturer portals, compressing traditional distributor margins.
- Standard Seat:OEM replacement units prioritizing cost efficiency over mass reduction.
- Ergonomic Seat:Biomechanically optimized pressure distribution for extended circuit sessions.
The dominant share belongs to Racing Seat, while Custom Seat is closing the gap fastest.
Material:
Cost tier stratification separates aerospace-grade composites from commodity synthetics.
- Carbon Fiber:Prepreg tow layup achieves ±0.1mm thickness tolerance and 15% weight reduction versus manual methods. Japanese and US aerospace-grade fiber suppliers dominate tow allocation, exposing manufacturers to capacity crunches during demand surges.
- Foam:Polyurethane cores with densities between 45-80 kg/m³ calibrated for energy absorption and tactile feedback. EPA Significant New Alternatives Policy restrictions on hydrofluorocarbon blowing agents force 8-12 month R&D recertification cycles for North American producers.
- Leather:Premium hide coverings with traditional tanning processes facing REACH chrome VI limitations.
- Vinyl:Weather-resistant synthetic covers for cost-sensitive replacement markets.
Carbon Fiber commands the premium tier, yet Foam maintains volume leadership across all price bands.
Design:
Application geometry dictates ergonomic priorities from tucked racing positions to upright touring postures.
- Sport:Aggressive forward cant with minimal padding to secure rider positioning during high-G cornering. Supersport platform demand clusters in Italian and Spanish markets where MotoGP heritage sustains premium specification tolerance.
- Cruiser:Low-slung profiles with plush foam prioritizing tactile comfort over gram-scale savings. Leather coverings retain substantial share where long-distance ergonomics outweigh mass reduction imperatives.
- Adventure:Dual-sport geometry accommodating standing and seated riding modes.
- Touring:Extended-range cushioning with integrated heating elements and weather sealing.
Sport design generates the highest per-unit margins, though Adventure configurations are expanding most quickly.
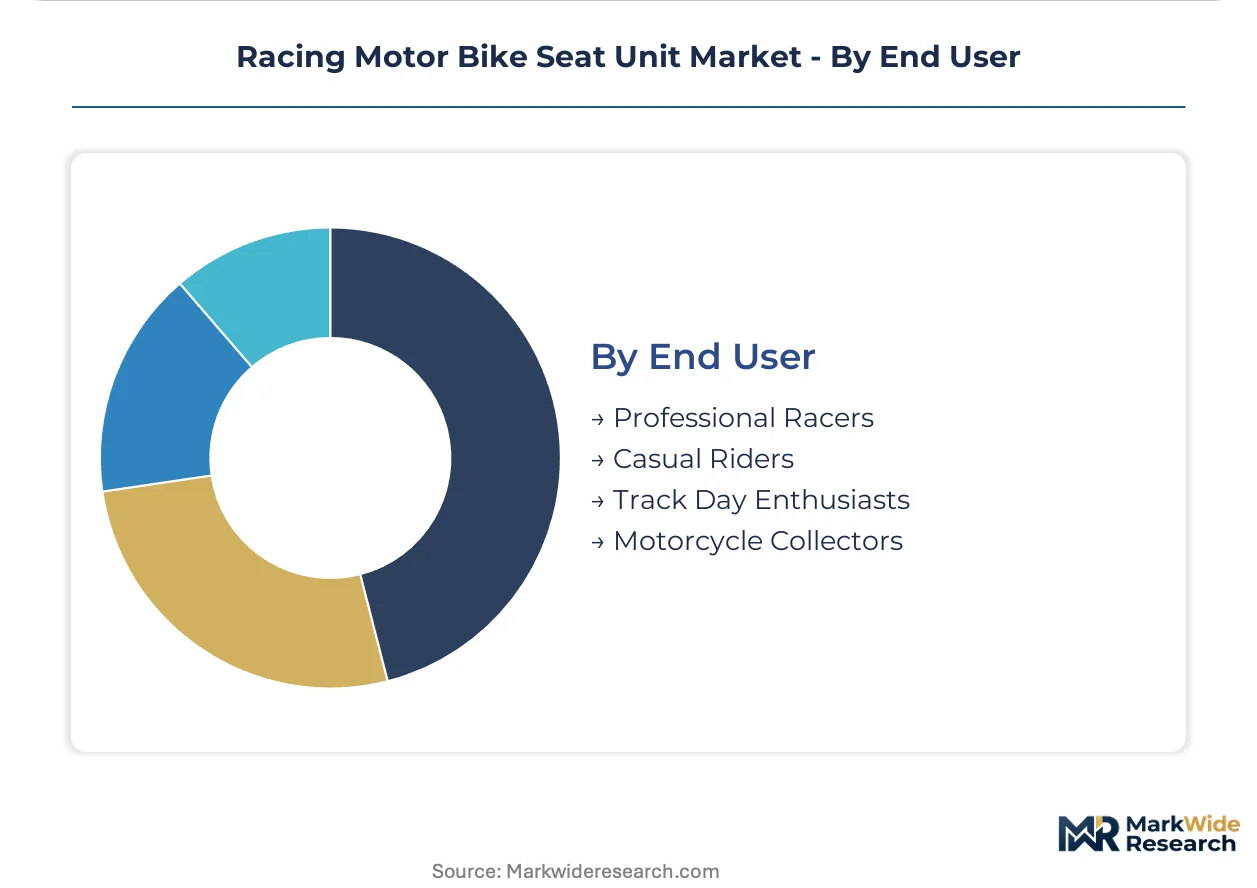
End User:
Customer type determines procurement channel, specification intensity, and replacement frequency.
- Track Day Enthusiasts:Amateur riders accessing commercial circuit infrastructure with personalized equipment requirements. Configurator platforms enabling geometry customization are capturing margin previously absorbed by wholesale networks.
- Professional Racers:Factory-supported teams with homologated specifications and seasonal development cycles. UNECE type-approval timelines for new foam formulations now exceed product development schedules, compressing competitive update windows.
- Casual Riders:Street-focused motorcyclists prioritizing comfort and durability over performance metrics.
- Motorcycle Collectors:Restoration specialists sourcing period-correct materials and stitching patterns.
Track Day Enthusiasts constitute the fastest-expanding segment, while Professional Racers anchor absolute value contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber prepreg supply concentrates among Japanese and US aerospace-grade fiber suppliers, exposing racing seat manufacturers to allocation risk during capacity crunches. Italian and German aftermarket distribution networks sustain premium procurement independent of OEM cycles, while US EPA restrictions on foam blowing agents accelerate North American material reformulation.
Italy
MotoGP heritage and dense aftermarket distribution networks sustain premium seat unit consumption in the Italian market. REACH chemical compliance frameworks under ECHA jurisdiction mandate bio-based polyurethane foam transitions, elevating R&D overhead for domestic producers. Manufacturing clusters near Modena and Bologna enable just-in-time carbon fiber layup and same-day cover stitching for premium orders.
Germany
Amateur racing circuit expansion generates aftermarket replacement cycles independent of OEM procurement in Germany. KBA homologation requirements govern street-legal motorcycle seating structural integrity alongside EU type-approval frameworks. Industrial concentration in Bavaria and Baden-Württemberg supports precision molding capabilities for mid-volume composite production runs.
United States
Track day infrastructure proliferation fragments demand between professional racing teams and amateur enthusiasts with divergent performance requirements. NHTSA-administered Federal Motor Vehicle Safety Standards govern structural integrity for street-legal motorcycle seating sold domestically. California Proposition 65 enforcement eliminates traditional chrome VI finishing processes for premium cover materials.
Japan
Aerospace-grade carbon fiber tow availability from domestic suppliers anchors composite seat pan production for Asia-Pacific racing applications. METI industrial standards and JIS certification requirements shape material specification protocols for export-oriented manufacturers. Manufacturing concentration in the Chubu region around Nagoya leverages automotive supply chain expertise for resin transfer molding automation.
United Kingdom
Amateur racing clubs aggregate small-batch orders through digital platforms, bypassing wholesale channels that previously required minimum order quantities. DVSA compliance with UNECE regulations establishes harmonized crashworthiness criteria for street-legal configurations. Motorsport engineering clusters in the Midlands sustain specialist composite fabrication capabilities for bespoke competition hardware.
Racing Motor Bike Seat Unit Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies across three tiers: premium carbon fiber houses with captive molding capacity, mid-market foam-and-cover assemblers sourcing base pans from third parties, and value-oriented replacement part distributors. Two strategic archetypes dominate: vertically integrated specialists controlling foam formulation through cover stitching, and weight-reduction-focused engineering houses competing on gram-scale metrics. Capacity expansion near Italian manufacturing clusters and direct-to-rider digital channel development represent the dominant competitive moves.
Among North American specialists, Saddlemen exemplifies backward integration into foam formulation and cover assembly, while LePera Seats anchors a position through deep platform specialization. XPC Racing occupies the aggressive weight-reduction vector for supersport applications. Corbin Motorcycle Seats & Accessories, Renazco Dual Sport Seats, and Motorsport Aftermarket Group represent the breadth of geographic and application coverage across the competitive set.
| Leading Market Players |
|---|
| Corbin Motorcycle Seats & Accessories |
| Saddlemen |
| Renazco Dual Sport Seats |
| LePera Seats |
| Mustang Seats |
| Sargent Cycle Products |
| XPC Racing |
| Motorsport Aftermarket Group |
| Danny Gray |
| Others |
Value Network & Pricing Analysis
Japanese and US aerospace-grade carbon fiber tow suppliers dominate upstream feedstock allocation, concentrating pricing power among seat unit manufacturers with long-term offtake agreements while fragmenting margin capture for second-tier assemblers sourcing base pans from third parties. REACH chemical compliance and EPA Significant New Alternatives Policy restrictions on foam blowing agents are elevating R&D overhead, compressing margin pools for producers without captive formulation capabilities.
Pricing Analysis
REACH and EPA Significant New Alternatives Policy restrictions dictate the pricing tier structure across the Racing Motor Bike Seat Unit Market, separating premium carbon fiber houses with captive molding capacity from mid-market foam-and-cover assemblers and value-oriented replacement part distributors. Price differentiation hinges on certification grade for UNECE type-approval compliance and vertical integration depth into foam formulation. Pricing pressure stems from petrochemical input volatility in polyol and isocyanate markets, with track day enthusiasts exhibiting highest price sensitivity versus professional racing teams prioritizing gram-scale performance.
Supply Chain Analysis
Aerospace-grade carbon fiber tow feeds from Japanese and US suppliers, with polyurethane foam systems and premium leather hides drawing from Italian, German, and domestic US tanning operations. Raw material dependencies center on prepreg tow allocation, bio-based polyol formulations, and REACH-compliant water-based adhesives. Single-source vulnerability in aerospace-grade fiber supply exposes manufacturers to allocation risk during capacity crunches. Distribution runs through Italian and German aftermarket networks alongside direct-to-rider digital configurator platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Racing Motor Bike Seat Unit Market operates as a defensive-moat arena where regulatory entrenchment through UNECE type-approval and REACH compliance creates sticky supplier relationships that resist displacement. Switching costs accumulate through homologated foam formulations and rider-specific geometry databases.
For Market Incumbents: Build regulatory entrenchment through accelerated bio-based foam certification under revised EPA Significant New Alternatives Policy timelines. Deepen backward integration into carbon fiber prepreg layup capacity near Modena manufacturing clusters to defend margin position against emerging automated fiber placement specialists. Threat of resin transfer molding automation displacing hand-layup premiums demands preemptive capacity investment. For New Entrants and Emerging Players: Establish a beachhead in direct-to-rider configurator channels serving German and UK amateur racing clubs aggregating small-batch custom orders. White-space concentrates in electric motorcycle thermal integration seat units with embedded cooling channels, where battery pack proximity creates specification gaps unaddressed by incumbent racing-focused portfolios. Go-to-market leverage rests on rapid geometry customization turnaround versus distributor minimum order quantities. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed foam formulation houses possessing automotive seating compliance infrastructure transferable to racing applications. Long-term viability across the analysis window favors suppliers with dual-use aerospace-automotive carbon fiber molding capabilities and captive Italian manufacturing cluster access. Signal to monitor: allocation priority shifts from Japanese tow suppliers toward domestic US prepreg capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Capacity | Robotic tow placement achieves ±0.1mm tolerance for MotoGP replica seat pans. |
| Bio-Based Foam Certification | REACH-compliant polyurethane transitions capture first-mover advantage in EU markets. |
| Direct-to-Rider Configurator Platform | Digital geometry customization bypasses wholesale minimum order requirements. |
| Thermal Integration R&D | Phase-change material embedding addresses electric motorcycle battery proximity cooling. |
| Italian Manufacturing Cluster Expansion | Same-day carbon fiber layup and cover stitching capability anchors premium fulfillment. |
Research Methodology
A spread of perspectives from racing team procurement managers, carbon fiber composite engineers, foam formulation chemists, and aftermarket distribution channel heads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through UNECE regulatory filings, EPA Significant New Alternatives Policy guidance documents, and ECHA REACH substance restriction updates. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators from motorcycle production databases and track day participation surveys.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation dimensions spanning product type, material technology, design geometry, and end-user experience tier. CAGRs derived from iterative reconciliation of unit shipment trajectories and value-per-unit expansion assumptions. Industry-specific forecast inputs incorporated resin transfer molding automation adoption curves and electric motorcycle platform thermal management specification evolution.
Macroeconomic conditions sit as an overlay; deviation in petrochemical input indices, aerospace fiber allocation priorities, or amateur racing circuit infrastructure investment would shift the trajectory. Forecasts reflect documented assumptions about regulatory timeline compression and composite technician workforce availability. Cross-checking against MotoGP team supplier disclosure patterns and aftermarket distributor inventory turnover benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Coupling Replacement Kit Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Tire Vulcanizer Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Harmonic Gearboxes Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Clutch Pedal Kit Market
Automotive Parts
Automotive Brake Actuator Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Canada Automotive Actuators Market
Automotive Parts
Air Suspension Systems Market
Automotive Parts
Automotive Slack Adjuster Market