
 Brazil E-Bike Market | 2026-2036
Brazil E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil E-Bike Market Outlook
Subscription-based fleet leasing is narrowing the capital barrier for last-mile logistics operators entering the Brazil e-bike space. Caloi anchors its position through deep manufacturing scale at its São Paulo facilities. Yamaha Motor do Brasil differentiates via integrated motor-drive systems developed for tropical humidity conditions. Sense Bike Indústria competes on price-accessible city models distributed through independent retailers across Minas Gerais and Paraná.
An e-bike combines a pedal-driven bicycle frame with an electric motor assist system, typically powered by a rechargeable lithium-ion battery pack with voltage ratings between 36V and 48V, designed to augment human propulsion for urban mobility, cargo transport, and recreational riding. City e-bikes dominate unit sales among commuters in dense metropolitan corridors, while cargo e-bikes capture expanding margin pools as Brazilian delivery platforms electrify their logistics networks. Lithium-ion battery configurations lead the technology mix due to energy density advantages, though lead acid retains residual share in entry-level price tiers sold through supermarket channels.
ANVISA enforces electrical safety certification for battery systems, while INMETRO mandates energy efficiency labeling that shapes import eligibility and consumer comparison. The Brazilian Traffic Code, administered by CONTRAN, classifies e-bike power thresholds and determines where models may operate legally. Stakeholders must monitor how municipal governments in Curitiba, Belo Horizonte, and Brasília structure dedicated cycling infrastructure, as lane availability directly conditions fleet deployment decisions by delivery operators and rental services.
Market Dynamics
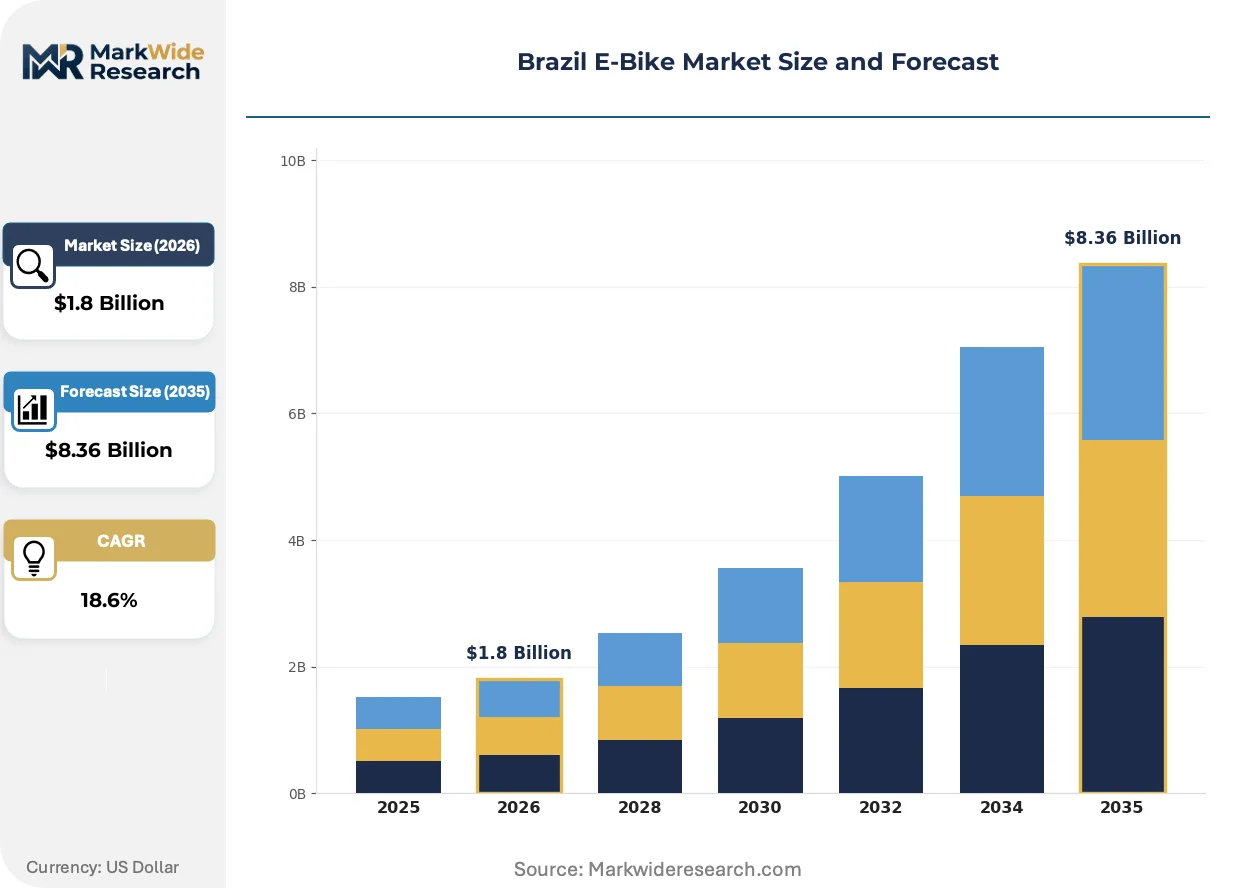
Delivery fleet electrification in São Paulo and Rio de Janeiro is compressing payback periods for commercial e-bike adoption, while ANVISA and INMETRO certification requirements reshape import economics and domestic manufacturing investment patterns.
Growth Catalysts
- Urban congestion pricing:Municipal traffic restrictions in southeastern Brazilian metros push logistics operators toward two-wheeled electric alternatives for last-mile fulfillment.
- ANVISA electrical safety certification:Mandatory battery system testing creates quality floor that weeds out low-grade imports and rewards compliant domestic assemblers.
- Lithium-ion energy density gains:Pack-level improvements extend daily range for cargo configurations without frame redesign, enabling heavier payload electrification.
Market Restraints
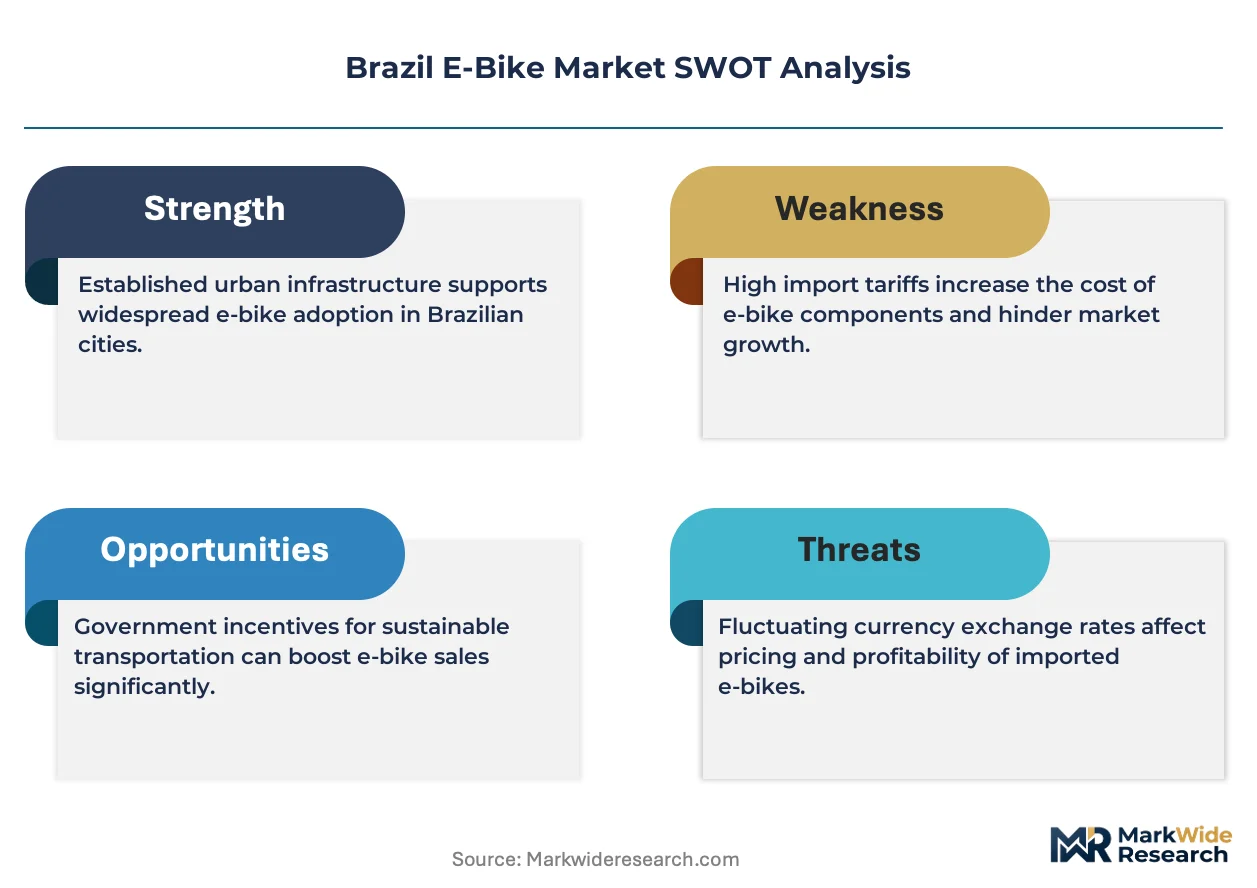
- Import duty volatility:Brazilian foreign trade tax fluctuations on Chinese battery cells compress margin predictability for assemblers dependent on overseas cell supply.
- INMETRO efficiency labeling delays:Extended certification timelines for new models slow product refresh cycles and trap capital in inventory awaiting approval.
- Lead-acid residual share:Supermarket-channel price competition from sealed lead-acid entry models caps premium positioning for lithium-based city bikes in price-sensitive segments.
Strategic Opportunities
- Minas Gerais retail network expansion:Independent dealer density in Belo Horizonte corridor remains below São Paulo saturation, creating first-mover shelf space for emerging brands.
- Curitiba cycling infrastructure mandates:Dedicated lane construction commitments reduce fleet risk perception and enable higher-utilization subscription pricing models.
- CONTRAN threshold harmonization:Potential federal reclassification of e-bike power limits would clarify operating permissions and unlock highway-adjacent commercial routes currently restricted.
Industry Challenges
- Battery thermal management engineering:Tropical humidity and temperature cycling stress pack longevity, requiring localized R&D capabilities most assemblers lack.
- INMETRO recertification for design changes:Component substitution triggers full retesting protocols that extend time-to-market and erode competitive responsiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil E-Bike Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Cargo E-Bikes, Foldable E-Bikes End User: Commuters, Recreational Users, Delivery Services, Tourists Battery Type: Lithium-Ion, Lead Acid, Nickel-Metal Hydride, Lithium Polymer Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Supermarkets |
| Companies Covered | Yadea, Decathlon, Caloi, Pon Bicycle Holding BV, Trek Bicycle Corporation, Sense Bike Indústria, Lev, Yamaha Motor do Brasil, VELA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil E-Bike Market Strategic Shifts
Fleet electrification economics, regulatory certification stringency, and procurement model restructuring are converging to reshape how e-bikes reach Brazilian commercial and consumer buyers.
Integrated motor-drive systems engineered for tropical humidity conditions are collapsing the reliability gap that previously favored conventional combustion motorcycles for delivery work. Logistics platforms operating in Rio de Janeiro and São Paulo are adopting these sealed-unit configurations at accelerating pace, compressing total cost of ownership calculations that previously excluded electric alternatives from high-utilization fleet planning.
ANVISA battery safety certification protocols now require thermal runaway containment documentation for all lithium-ion packs sold in Brazil. This regulatory tightening excludes uncertified Asian imports and redirects procurement toward INMETRO-registered domestic assemblers with testing capabilities. Commercial fleet buyers now prioritize certification status over upfront unit cost in vendor selection criteria.
Subscription-based fleet leasing is displacing direct purchase for last-mile operators in southeastern metros. Independent logistics contractors in Belo Horizonte and Curitiba are shifting capital expenditure to operating expense models that bundle maintenance and battery replacement. This behavioral pivot concentrates buyer power with leasing platforms and fragments direct manufacturer relationships.
Brazil E-Bike Market Segmentation
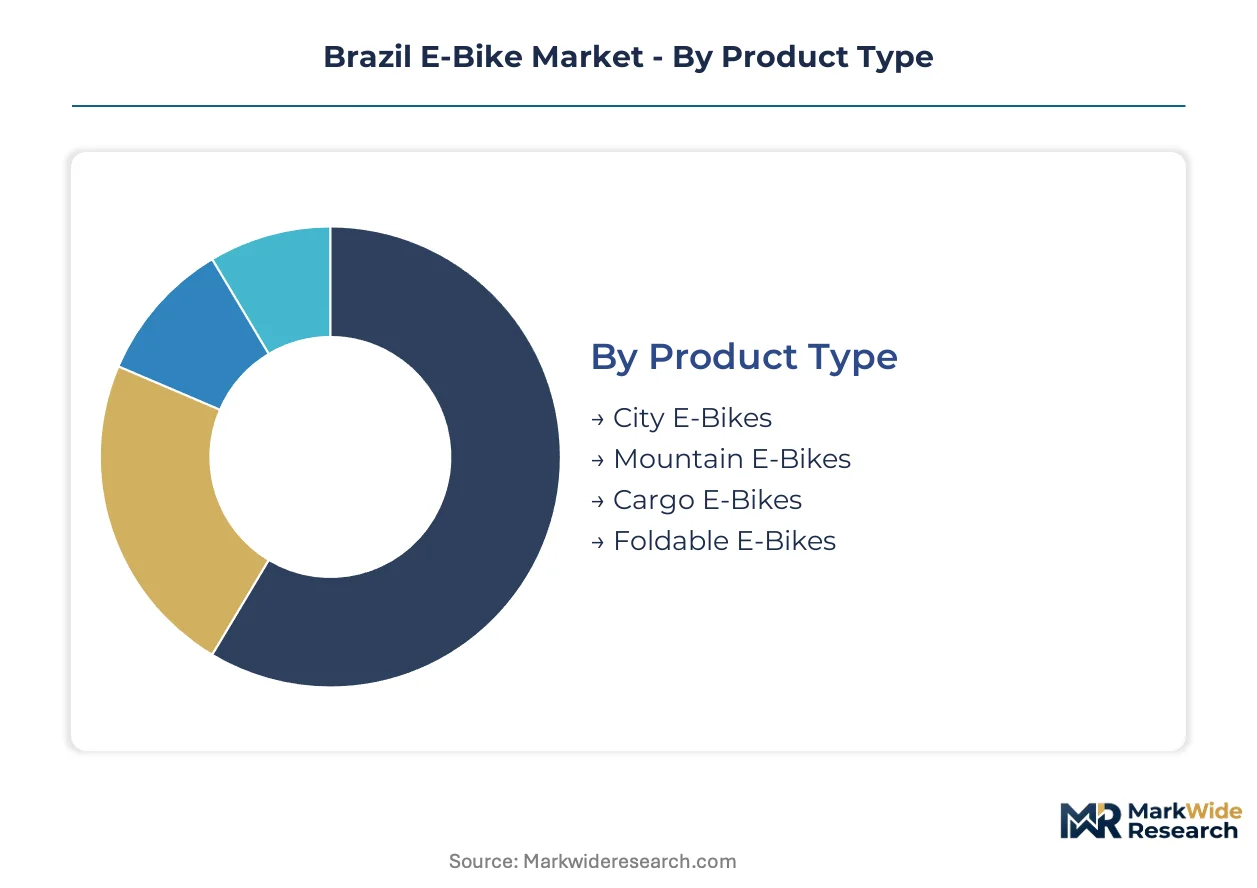
Segmentation in the Brazil e-bike market reveals how product specifications, user economics, and channel access intersect with regulatory constraints. Understanding these divides explains why lithium-ion city bikes dominate São Paulo commuter corridors while cargo configurations capture fleet procurement in delivery logistics.
Product Type:
Mature urban mobility formats anchor current volume, while emerging specialized configurations reshape commercial procurement patterns.
- City E-Bikes:Step-through frames with integrated battery housings and 250W-350W hub motors dominate daily commuter adoption in Belo Horizonte and Curitiba. Dense southeastern metro cycling infrastructure and CONTRAN power threshold compliance position these units as the default replacement for combustion motorcycles in last-mile logistics.
- Cargo E-Bikes:Extended wheelbase frames with dual-battery 48V systems and reinforced rear racks support 150kg+ payloads for São Paulo delivery fleet operators. Subscription leasing models from independent logistics contractors concentrate demand in refrigerated and parcel transport segments where daily utilization exceeds 12 hours.
- Mountain E-Bikes:Full-suspension frames with mid-drive torque sensors serve recreational trail networks in Minas Gerais and Santa Catarina.
- Foldable E-Bikes:Collapsible frame designs with reduced battery capacity target multimodal commuters in Rio de Janeiro's ferry-integrated transit corridors.
City e-bikes retain volume leadership; cargo e-bikes hold the steepest expansion curve.
End User:
Commercial operators now outpace individual consumers in procurement velocity, reversing historical purchase patterns.
- Commuters:Salaried professionals in São Paulo's expanded cycling lane network purchase mid-tier lithium-ion step-through models for 15-25km daily round trips. Fuel price volatility and municipal congestion restrictions in the southeastern corridor accelerate replacement of automobile-dependent commutes.
- Delivery Services:Platform logistics contractors and independent fleet operators in Rio de Janeiro electrify at scale through operating-expense leasing models. ANVISA-certified battery systems and INMETRO efficiency labels determine vendor eligibility, concentrating procurement with domestic assemblers capable of documentation compliance.
- Recreational Users:Weekend riders in Paraná and Minas Gerais trail networks purchase mid-drive mountain configurations seasonally.
- Tourists:Rental operators in coastal municipalities deploy entry-level hub-motor fleets for short-duration beach corridor access.
Delivery services command the fastest procurement volume growth; commuters maintain the largest installed base.
Battery Type:
Energy density advantages separate premium lithium chemistries from residual lead-acid share in price-sensitive channels.
- Lithium-Ion:18650 cylindrical cell configurations with 500+ cycle lifespans dominate certified e-bike sales through specialty retailers. ANVISA thermal runaway containment documentation requirements and INMETRO efficiency labeling redirect procurement toward registered domestic pack assemblers with testing laboratory partnerships.
- Lead Acid:Sealed AGM batteries in 36V configurations persist in supermarket-channel entry bikes below price thresholds where lithium-ion unit economics displace them. Residual share concentrates in one-time recreational purchasers without daily utilization requirements.
- Nickel-Metal Hydride:Intermediate energy density chemistry retains niche presence in legacy fleet replacements.
- Lithium Polymer:Pouch cell formats with flexible form factors enable frame-integrated battery housings in premium city and cargo designs.
Lithium-ion retains volume leadership; lithium polymer configurations gain share fastest in premium integrated designs.
Distribution Channel:
Channel selection determines certification visibility and after-sales service access for distinct buyer risk profiles.
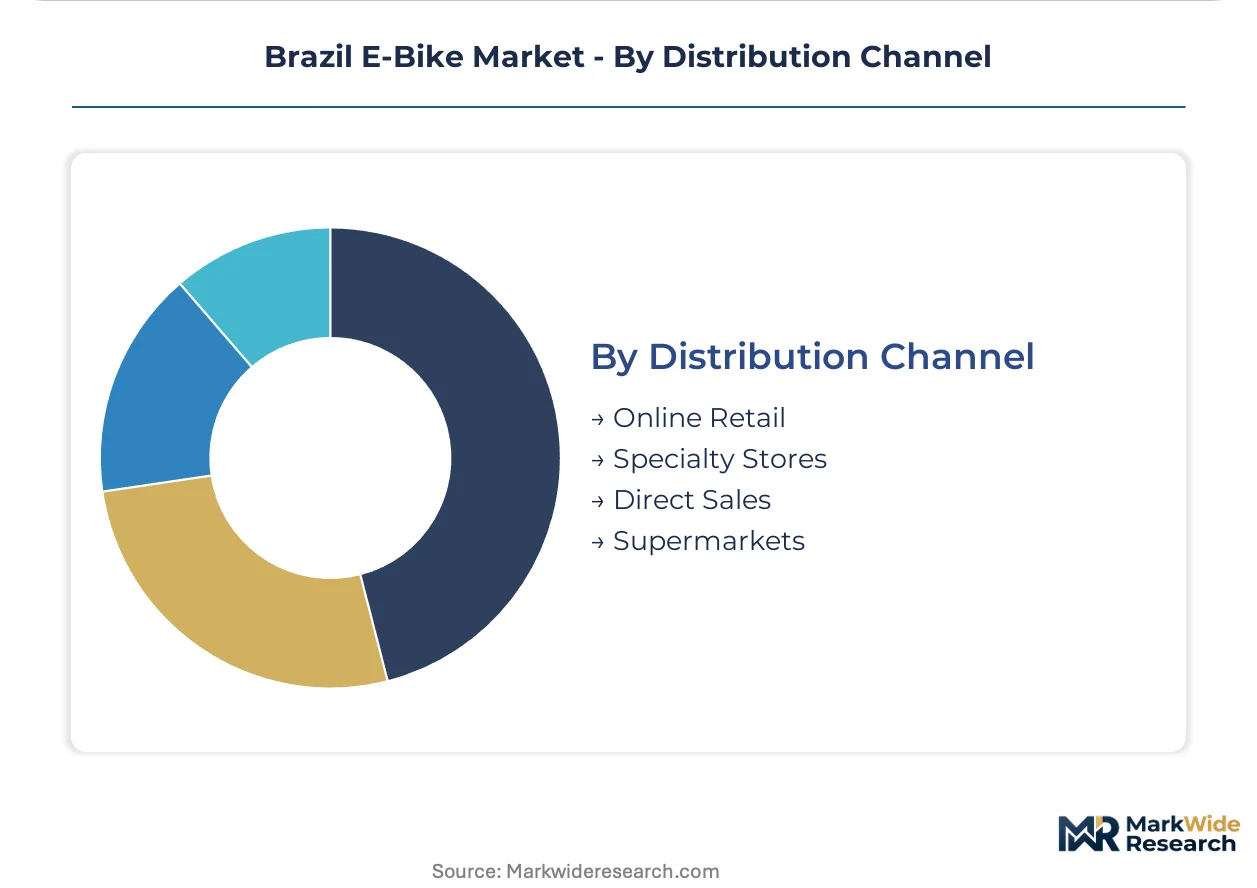
- Specialty Stores:Independent retailers in Belo Horizonte and Curitiba provide test-ride facilities, ANVISA certification verification, and battery replacement programs. Technical staff explain INMETRO efficiency labels and CONTRAN operating permissions, reducing purchase friction for first-time electric adopters.
- Online Retail:E-commerce platforms aggregate comparison tools for ANVISA-registered models, though import duty volatility on direct-ship battery cells creates delivery timeline uncertainty. Digital channels capture price-sensitive buyers in secondary cities with limited physical dealer presence.
- Direct Sales:Manufacturer-owned showrooms in São Paulo anchor brand positioning for premium motor-drive system configurations.
- Supermarkets:Mass merchandisers in Minas Gerais and Paraná move lead-acid entry bikes through seasonal promotional cycles.
Specialty stores retain volume leadership; online retail channels expand most quickly into underserved interior municipalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo commands premium pricing power over Belo Horizonte due to logistics density and fleet electrification urgency. Southeastern states concentrate procurement volume where urban congestion pricing and fuel volatility intersect.
São Paulo
Metropolitan congestion restrictions and delivery platform electrification mandates drive commercial fleet procurement. ANVISA battery safety certification requirements filter import eligibility toward registered domestic assemblers. The capital corridor anchors manufacturing scale at Caloi's São Paulo facilities while subscription leasing operators concentrate fleet deployment.
Minas Gerais
Independent retail network density in Belo Horizonte remains below southeastern saturation levels, creating shelf space opportunities for emerging brands. INMETRO efficiency labeling shapes consumer comparison and import economics for specialty store channels. Price-accessible city models distribute through regional dealer networks serving interior municipalities.
Rio de Janeiro
Delivery fleet operators electrify at scale through operating-expense models that bundle maintenance and battery replacement. CONTRAN power threshold classifications determine legal operating permissions for commercial routes. Coastal logistics corridors see refrigerated transport segments adopting dual-battery cargo configurations for high-utilization deployment.
Paraná
Curitiba's dedicated cycling infrastructure commitments reduce fleet risk perception and enable higher-utilization subscription pricing. Municipal lane construction programs condition deployment decisions by rental services and logistics contractors. Independent retailers across the state capture price-sensitive buyers migrating from supermarket-channel lead-acid entry models.
Rio Grande do Sul
Recreational trail networks in southern municipalities sustain seasonal demand for full-suspension configurations. Port access shapes import logistics for battery cell supply chains dependent on overseas sourcing. Regional assembly operations face margin compression from foreign trade tax volatility on Chinese lithium-ion components.
Brazil E-Bike Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in motor-drive and battery pack supply. The vendor base stratifies across three tiers: multinational assemblers with domestic manufacturing scale, regional specialists in tropical-condition engineering, and import-dependent distributors serving price-sensitive channels. Two strategic archetypes dominate: vertically integrated manufacturers controlling certification compliance, and fleet-leasing platforms aggregating buyer power. Competitive moves concentrate on ANVISA registration acquisition and INMETRO testing laboratory partnerships.
Among Asia-Pacific platform manufacturers, Yadea anchors the volume-driven import segment. European holding structures exemplify portfolio diversification across price tiers, with Pon Bicycle Holding BV occupying a position spanning premium to mass-market positioning. Domestic Brazilian specialists including Caloi and Sense Bike Indústria represent the compliance-forward archetype, leveraging localized assembly and certification capabilities to capture fleet procurement from delivery operators prioritizing ANVISA documentation over upfront unit cost.
| Leading Market Players |
|---|
| Yadea |
| Decathlon |
| Caloi |
| Pon Bicycle Holding BV |
| Trek Bicycle Corporation |
| Sense Bike Indústria |
| Lev |
| Yamaha Motor do Brasil |
| VELA |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure on Chinese lithium-ion battery cells compresses margin predictability for Brazilian assemblers while simultaneously widening the pricing gap between certified domestic builds and uncertified imports. This import duty volatility forces a supply chain structure anchored in Southeast Asian cell sourcing and São Paulo final assembly, with pricing tiers separating ANVISA-registered fleet configurations from supermarket-channel lead-acid entry models.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. ANVISA certification grade and INMETRO efficiency labeling drive price differentiation, with certified lithium-ion cargo configurations commanding substantial premiums over lead-acid supermarket alternatives. Cost compression in the entry tier intensifies because Chinese import competition and residual lead-acid share cap upward pricing mobility. Fleet leasing operators show least price sensitivity, prioritizing certification documentation and battery replacement guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between China and Brazil dominates supply chain risk calculations for cell-dependent assemblers. Manufacturing concentration centers on China, South Korea, and Japan for 18650 cylindrical cells, while Brazilian final assembly draws from Taiwanese BMS components and domestic frame fabrication. Single-source vulnerability in cathode active materials feeds from Chilean and Australian lithium concentrate. Distribution runs through specialty retailer networks in southeastern metros, with direct manufacturer relationships fragmenting as subscription platforms aggregate procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's e-bike market represents an early-cycle expansion story where fleet electrification mandates in São Paulo and Rio de Janeiro accelerate commercial penetration ahead of consumer adoption curves.
For Market Incumbents: Insulate certification moats by deepening INMETRO testing laboratory partnerships and accelerating ANVISA registration for next-generation thermal management systems. Capacity addition in Minas Gerais retail corridors counters emerging brand shelf space capture. Vertical integration into battery pack assembly reduces import duty exposure on finished cells.
For New Entrants and Emerging Players: Independent logistics contractors in Belo Horizonte and Curitiba represent the most penetrable entry point, with subscription-based fleet leasing creating operating-expense access without capital barrier confrontation. Price-accessible city models distributed through underserved interior dealer networks bypass São Paulo saturation. Direct sales partnerships with municipal cycling infrastructure programs unlock pilot fleet deployment.
For Investors and Strategic Acquirers: ANVISA battery safety protocol tightening reshapes the acquisition landscape toward domestic assemblers with registered testing capabilities and existing certification documentation. Long-term viability rests on regulatory compliance infrastructure rather than manufacturing scale alone. The signal to watch is CONTRAN power threshold reclassification, which would clarify highway-adjacent commercial permissions and expand addressable fleet routes.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Acquisition | Registered battery system documentation unlocks fleet procurement eligibility from delivery platforms prioritizing compliance. |
| INMETRO Testing Laboratory Partnership | Localized efficiency validation accelerates product refresh cycles and reduces capital trap in approval-awaiting inventory. |
| Subscription Fleet Leasing Platform Launch | Operating-expense models concentrate buyer power and fragment direct manufacturer relationships in last-mile logistics. |
| Tropical Humidity Motor-Drive Engineering | Sealed-unit configurations engineered for Rio de Janeiro conditions collapse reliability gaps versus combustion motorcycles. |
| Minas Gerais Retail Network Expansion | Independent dealer density below São Paulo saturation creates first-mover shelf space for emerging brand capture. |
Study Parameters
The analysis maps city e-bike, cargo e-bike, mountain e-bike, and foldable e-bike configurations, each validated through fleet procurement managers at delivery platforms, independent logistics contractors, specialty retailer owners, and INMETRO certification officers. Primary interviews combined with secondary validation from ANVISA registration databases, CONTRAN regulatory filings, customs import records, and municipal cycling infrastructure disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across the projection horizon.
Assumptions held fixed include ANVISA certification requirements and INMETRO efficiency labeling protocols, while tariff rates and lithium carbonate pricing varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, end user archetype, battery chemistry, and distribution channel, with additional industry-specific weighting for fleet leasing penetration rates. CAGRs derived from logistic curve fitting to historical adoption patterns and elasticity-adjusted response to fuel price volatility.
Practitioners should monitor foreign trade tax fluctuations on Chinese cells and CONTRAN regulatory revisions for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
Two Wheeler Fenders Market
Bikes and Motorcycles
Cruiser Bikes Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Bicycle Trip Market
Bikes and Motorcycles
Europe Motorcycle Market
Bikes and Motorcycles
Bike Kickstand Market
Bikes and Motorcycles
Switzerland E-Bike Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
Smart Electric Bikes Market
Bikes and Motorcycles
Child Bike Seats Market